
 Indonesia Waterproofing Solutions Market | 2026-2036
Indonesia Waterproofing Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Waterproofing Solutions Market Insights
Premium-grade membrane specification is bifurcating the Indonesia waterproofing solutions landscape as developers separate long-durability projects from cost-driven tenders. Sika AG leverages its polyurethane technology leadership to anchor specification conversations with tier-one contractors in Jakarta. PT Selaras Cipta Global competes on localized bituminous formulations and channel control across secondary cities. Soprema sustains its position through membrane specialization for infrastructure-grade waterproofing where warranty terms extend beyond standard commercial practice.
Indonesia waterproofing solutions encompass liquid-applied and sheet-based barrier systems formulated from bituminous compounds, polyurethane resins, cementitious blends, or silicone polymers to prevent moisture ingress in building envelopes and civil structures. These systems typically achieve elongation ratings exceeding 300% and hydrostatic resistance thresholds critical for tropical monsoon exposure, protecting structural integrity across commercial high-rises, industrial facilities, and transportation infrastructure. Liquid membrane leads product-type demand where complex geometries and detailing dominate, while sheet membrane retains margin concentration in infrastructure applications requiring factory-controlled thickness uniformity. Polyurethane technology captures the fastest specification growth among technology categories as contractors prioritize cold-applied installation speed over hot-melt bituminous methods in dense urban sites.
Indonesia's Ministry of Public Works and Housing sets national building envelope standards that directly shape waterproofing product certification requirements for commercial and infrastructure projects. BIS-equivalent local standards and ASEAN harmonization frameworks influence cross-border material approvals, creating compliance layers for imported membrane systems. Facility managers and property developers must monitor regulatory alignment between national codes and green building certification schemes as sustainability-linked procurement criteria expand across Indonesian construction tender protocols.
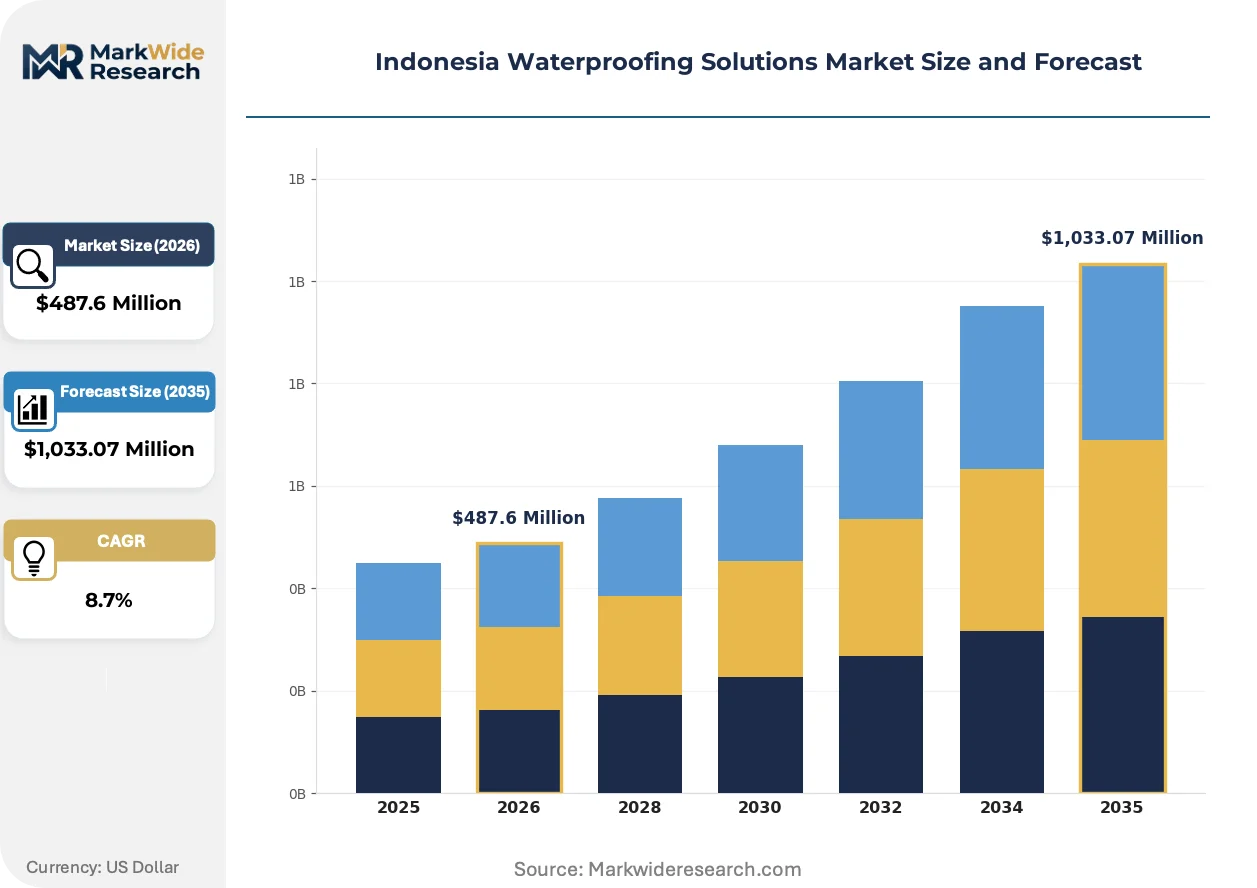
Market Dynamics
Indonesia's Ministry of Public Works and Housing is tightening building envelope standards for tropical climates, forcing property developers in Jakarta and Surabaya to upgrade from commodity bituminous sheets to performance-grade membrane systems with extended warranty terms.
Growth Catalysts
- Regulatory tightening:Indonesia's Ministry of Public Works and Housing mandates enhanced moisture protection for commercial high-rises in monsoon-exposed zones, accelerating specification of hydrostatic-resistant systems.
- Polyurethane cold-application:Contractors across Java's high-rise corridor prioritize cold-applied polyurethane resins over hot-melt bituminous methods to reduce labor time and fire risk in dense urban construction sites.
- Infrastructure warranty extension:Transportation and civil projects now demand membrane systems with factory-controlled thickness uniformity and warranty terms exceeding standard commercial practice.
Market Restraints
- Import dependency for polymer feedstocks:Polyurethane resin supply concentrates with regional petrochemical hubs outside Indonesia, exposing contractors to freight cost volatility and currency fluctuation risk.
- Skilled applicator scarcity:Complex liquid membrane detailing requires certified technicians that remain concentrated in Jakarta and Surabaya, limiting deployment speed in secondary cities.
- Cementitious substitution in budget segments:Low-rise residential developers in outer Java provinces increasingly specify cementitious blends for below-grade waterproofing, compressing addressable volume for advanced membrane systems.
Strategic Opportunities
- Green building certification alignment:Indonesia's expanding adoption of sustainability-linked procurement criteria in public tenders creates preference for low-VOC membrane systems that qualify for green building certification schemes.
- Secondary city channel buildout:Bandung, Medan, and Makassar exhibit underpenetrated specification of liquid-applied systems where humidity and seasonal flooding drive latent demand for advanced envelope protection.
- Silicone-polyurethane hybrid convergence:Next-generation formulations combining silicone weatherability with polyurethane elasticity target exposed roof applications in coastal industrial zones with extreme UV and salt exposure.
Industry Challenges
- BIS-equivalent certification timelines:Imported membrane systems face extended approval cycles under local standards harmonization with ASEAN frameworks, delaying market entry for foreign suppliers.
- Application quality assurance:Field-applied liquid membranes depend on consistent mil-thickness control that remains difficult to verify across subcontractor networks in remote project sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Waterproofing Solutions Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Membrane, Sheet Membrane, Coatings, Sealants Application: Residential, Commercial, Industrial, Infrastructure Technology: Polyurethane, Bituminous, Cementitious, Silicone End User: Contractors, Architects, Property Developers, Facility Managers |
| Companies Covered | Saint-Gobain, Sika AG, Soprema, MAPEI S.p.A., PT Selaras Cipta Global, PT Aspal Polimer Emulsindo, Fosroc Inc, Ardex Group, Avian Brands, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Waterproofing Solutions Market Trends and Innovations
Membrane technology evolution is splitting the Indonesian waterproofing market between premium specification for long-durability assets and cost-optimized tenders for shorter-hold developments. Regulatory pressure and contractor capability gaps are accelerating this segmentation.
Polyurethane liquid membrane technology is bifurcating competitive positioning in Indonesia's waterproofing sector. These cold-applied systems achieve elongation ratings exceeding 300 percent while enabling rapid installation without open-flame equipment. Tier-one contractors in Jakarta's high-rise corridor specify polyurethane for complex geometries and detailing-intensive podium decks. The technology is compressing margins for hot-melt bituminous specialists while creating premium pricing power for applicators with certified installation protocols.
ASEAN harmonization frameworks are reshaping material approval pathways for waterproofing imports into Indonesia. BIS-equivalent local standards now require documented tropical climate performance testing that many European and North American manufacturers lack. Commercial high-rise developers face extended procurement cycles as they verify cross-border certification alignment. Segment leaders are responding by establishing local testing partnerships and reformulating products for accelerated UV and humidity exposure validation.
Specification authority is migrating from general contractors to specialized envelope consultants in Indonesia's premium commercial segment. These technical buyers unbundle waterproofing from broader MEP packages and demand performance-based warranties with third-party inspection protocols. Distribution through traditional building material wholesalers is losing share to direct manufacturer-engagement models. This shift concentrates in Jakarta and Surabaya where foreign asset managers and institutional developers dominate project pipelines.
Indonesia Waterproofing Solutions Market Segmentation
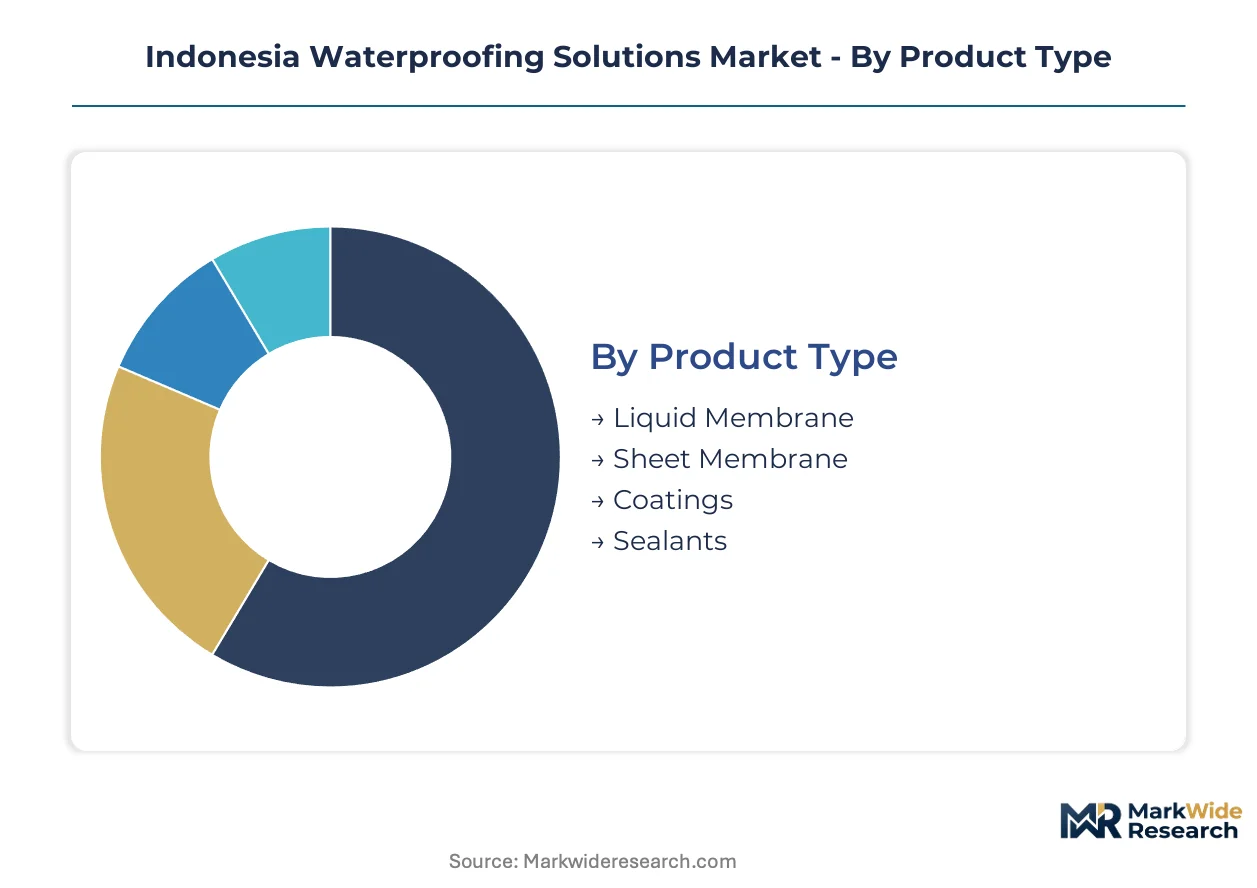
Segmentation in Indonesia's waterproofing market reveals how regulatory pressure and tropical climate exposure reshape procurement priorities across product categories. Contractors and developers navigate distinct specification tiers that balance hydrostatic performance against installation constraints and warranty requirements.
Product Type:
Indonesia's Ministry of Public Works and Housing mandates differentiated certification pathways for liquid versus sheet systems, with liquid membranes facing accelerated approval cycles for high-rise applications while sheet membranes carry stricter factory-audit requirements for infrastructure warranties.
- Liquid Membrane:Cold-applied polyurethane or bituminous formulations achieve seamless coverage across complex podium decks and detailing-intensive geometries. Demand concentrates in Jakarta's high-rise corridor where contractors prioritize installation speed and fire-safety compliance in dense urban sites. The Ministry's tightened envelope standards for commercial towers accelerate specification of systems with documented elongation exceeding 300 percent.
- Sheet Membrane:Factory-controlled thickness uniformity delivers predictable hydrostatic resistance for below-grade and infrastructure applications. Surabaya's transportation developers specify these systems where warranty terms must extend beyond standard commercial practice. Installation requires hot-melt equipment or self-adhesive variants that limit deployment speed.
- Coatings:Cementitious and polymer-modified cement systems serve budget-sensitive residential segments in outer Java provinces where below-grade waterproofing faces less stringent regulatory scrutiny.
- Sealants:Joint-sealing formulations complement primary membrane systems in expansion joints and penetrations across commercial and industrial envelopes.
Established volume favors sheet membrane in infrastructure; emerging adoption favors liquid membrane in high-rise commercial.
Application:
Cost tier differentiation separates premium commercial and infrastructure projects from economy residential developments, with regulatory enforcement intensity varying sharply across these application boundaries.
- Commercial:Jakarta and Surabaya high-rises drive specification of performance-grade systems with third-party inspection protocols. Foreign asset managers and institutional developers demand extended warranties that unbundle waterproofing from broader MEP packages.
- Infrastructure:Transportation and civil projects in Java's urban corridors require membrane systems with factory-controlled thickness uniformity and warranty terms exceeding standard commercial practice.
- Industrial:Coastal manufacturing facilities in Surabaya and Cilegon specify silicone-polyurethane hybrids for extreme UV and salt exposure.
- Residential:Low-rise developers in outer Java provinces increasingly substitute cementitious blends for below-grade waterproofing, compressing addressable volume for advanced membrane systems.
Commercial application commands premium pricing power; residential application faces margin compression from material substitution.
Technology:
Application method and installation capability requirements segment the technology landscape, with cold-applied systems gaining share where skilled applicator scarcity constrains hot-melt deployment.
- Polyurethane:Cold-applied resins achieve elongation ratings exceeding 300 percent while eliminating open-flame equipment. Tier-one contractors across Java's high-rise corridor specify this technology for complex geometries where installation speed reduces labor costs. The formulation category gains share fastest where certified technician networks concentrate.
- Bituminous:Hot-melt and self-adhesive sheet systems retain infrastructure preference where factory-controlled thickness uniformity supports extended warranty terms. Surabaya's transportation developers specify these systems despite slower installation.
- Cementitious:Polymer-modified cement blends serve budget residential segments in outer Java provinces where regulatory enforcement remains less stringent.
- Silicone:Weatherability-focused formulations target exposed roof applications in coastal industrial zones with extreme UV and salt exposure.
Polyurethane technology climbs the fastest in commercial specification; bituminous technology defends infrastructure position through warranty differentiation.
End User:
Customer type determines specification authority and procurement channel, with technical buyers increasingly unbundling waterproofing from broader construction packages.
- Property Developers:Institutional developers in Jakarta and Surabaya drive demand for performance-grade systems with third-party inspection protocols and extended warranty terms.
- Contractors:Tier-one contractors with certified installation protocols capture premium pricing for polyurethane liquid membrane application in high-rise corridors.
- Architects:Envelope consultants in premium commercial segments unbundle waterproofing specification from general MEP packages and demand performance-based warranties.
- Facility Managers:Asset managers prioritize low-VOC systems that align with expanding green building certification criteria in public tender protocols.
Property developers concentrate volume authority; facility managers drive sustainability-linked procurement criteria expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer feedstock supply concentrates with regional petrochemical hubs outside Indonesia, exposing contractors to freight cost volatility and currency fluctuation risk. Domestic membrane formulation capacity clusters in Java's industrial corridor, with specification authority migrating toward specialized envelope consultants in premium commercial segments.
Jakarta Metropolitan Area
High-rise commercial towers drive specification of liquid-applied polyurethane systems where complex podium deck geometries dominate. Indonesia's Ministry of Public Works and Housing mandates enhanced moisture protection standards for monsoon-exposed zones, accelerating hydrostatic-resistant system procurement. Foreign asset managers in the central business district demand third-party inspection protocols and extended warranty terms that unbundle waterproofing from broader MEP packages.
Surabaya
Transportation infrastructure and coastal industrial facilities anchor sheet membrane demand where factory-controlled thickness uniformity supports warranty extension beyond standard commercial practice. The Ministry's tightened building envelope standards for tropical climates force upgrade from commodity bituminous sheets to performance-grade systems. Manufacturing zones in Gresik and surrounding industrial estates specify silicone-polyurethane hybrids for extreme UV and salt exposure.
Bandung
Secondary city status leaves liquid-applied system penetration underdeveloped despite humidity and seasonal flooding driving latent demand for advanced envelope protection. Local building code enforcement varies from Jakarta's intensity, creating specification tier differentiation between premium commercial and economy residential developments. Emerging commercial corridors in the Greater Bandung area attract tier-one contractors expanding beyond Java's primary high-rise corridor.
Medan
Sumatra's largest urban center exhibits underpenetrated specification of advanced membrane systems where cementitious substitution dominates budget residential segments. The Ministry's national standards apply uniformly, yet certified technician networks remain concentrated in Java, constraining deployment speed for complex liquid membrane detailing. Industrial estates serving palm oil processing and logistics infrastructure create niche demand for durable below-grade waterproofing.
Makassar
Eastern Indonesia's commercial hub faces accelerated monsoon exposure and coastal flooding that structurally requires envelope protection upgrades. Supply chain distance from Java-based formulation centers amplifies import dependency challenges for polymer feedstocks. Public works projects in the Trans-Sulawesi corridor generate sporadic infrastructure-grade demand where extended warranty terms and factory-audit requirements apply.
Indonesia Waterproofing Solutions Market Competitive Landscape
Concentration sits with multinational specialty chemical groups and localized bituminous formulators competing across distinct specification tiers. The vendor base splits between premium polyurethane technology leaders and cost-optimized domestic compounders serving secondary cities. Three archetypes dominate: global membrane specialists with tropical climate certification, regional petrochemical-integrated formulators, and Java-based applicator-contractors with certified installation protocols. Competitive moves center on local testing partnerships for ASEAN harmonization compliance and direct manufacturer engagement models that bypass traditional building material wholesalers.
Among European-headquartered specialists, Sika AG and Saint-Gobain occupy positions anchoring premium specification conversations with tier-one contractors in Jakarta's high-rise corridor. Soprema exemplifies the membrane specialization archetype for infrastructure-grade applications where warranty differentiation matters. PT Selaras Cipta Global represents localized bituminous formulators competing on channel control across secondary cities outside Java's primary corridor.
| Leading Market Players |
|---|
| Saint-Gobain |
| Sika AG |
| Soprema |
| MAPEI S.p.A. |
| PT Selaras Cipta Global |
| PT Aspal Polimer Emulsindo |
| Fosroc Inc |
| Ardex Group |
| Avian Brands |
| Others |
Pricing and Supply Chain Analysis
ASEAN harmonization frameworks gate both supply qualification timelines and price differentiation tiers for imported membrane systems entering Indonesia. The Ministry of Public Works and Housing's tropical climate certification requirements force foreign suppliers to absorb extended testing costs while domestic bituminous compounders exploit faster approval pathways.
Pricing Analysis
Indonesia's Ministry of Public Works and Housing dictates the pricing tier structure through differentiated certification rigor for liquid versus sheet membrane systems. Premium polyurethane liquid membranes command project-based pricing with third-party inspection protocols bundled, while commodity bituminous sheets compete on per-square-meter transactional terms. Cost compression in the residential tier intensifies because cementitious substitution erodes membrane addressable volume. Property developers in Jakarta's high-rise corridor demonstrate lowest price sensitivity, prioritizing warranty extension and installation speed over unit cost.
Supply Chain Analysis
Singapore-Jakarta shipping lanes and the Strait of Malacca transit underwrite polymer feedstock delivery reliability for Indonesian membrane formulators. Polyurethane resin supply concentrates with petrochemical hubs in Singapore, South Korea, and Thailand, exposing contractors to freight cost volatility and currency fluctuation risk. Raw material dependency rests on MDI prepolymers, bitumen derivatives, and silicone intermediates sourced from regional exporters. Single-source vulnerability concentrates with Singapore-based resin distributors. Distribution runs through Java-based applicator-contractors with certified installation protocols, bypassing traditional building material wholesalers in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's waterproofing sector approaches a platform-economics inflection as specification authority migrates from general contractors to specialized envelope consultants, creating interoperability demands between membrane systems and digital building management platforms.
For Market Incumbents: Compound certification investment in BIS-equivalent tropical climate testing to defend specification conversations against emerging regional petrochemical-integrated formulators. Deepen backward integration into polymer feedstock supply through Singapore hub partnerships to mitigate currency exposure. Channel control in secondary cities remains the priority lever against domestic bituminous compounders expanding from Java.
For New Entrants and Emerging Players: Anchor in Bandung and Makassar where liquid-applied system penetration lags humidity-driven demand, exploiting certified technician scarcity that constrains incumbent deployment speed. Target industrial estate developers in Surabaya's Gresik corridor with silicone-polyurethane hybrid formulations for extreme UV and salt exposure. A direct manufacturer-engagement model bypassing traditional wholesalers captures specification authority from envelope consultants unbundling waterproofing from MEP packages.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional petrochemical formulators seeking ASEAN market expansion through Indonesia beachheads. Five-to-ten year viability hinges on regulatory alignment between national codes and green building certification schemes expanding across public tender protocols. Monitor Ministry procurement rulemaking for low-VOC mandate timing as the inflection signal for premium membrane system demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Local Testing Partnership Formation | Accelerates BIS-equivalent certification timelines for tropical climate performance validation. |
| Certified Applicator Network Expansion | Extends liquid membrane deployment capability beyond Jakarta-Surabaya technician concentration. |
| Low-VOC Formulation Development | Qualifies membrane systems for Indonesia's expanding green building tender criteria. |
| Backward Integration into Polymer Supply | Reduces freight cost volatility exposure from Singapore and South Korean resin hubs. |
| Direct Manufacturer Engagement Model | Bypasses traditional wholesalers to capture specification authority from envelope consultants. |
Research Methodology
A spread of perspectives from waterproofing applicators, envelope consultants, property development procurement leads, and Ministry of Public Works and Housing officials converged on the working assumptions underlying volume and value estimates. Primary field engagement with tier-one contractors in Jakarta's high-rise corridor and bituminous compounders in secondary cities combined with secondary validation against Indonesia trade statistics, ASEAN construction output indices, and building code harmonization documentation. Bottom-up project pipeline analysis triangulated with top-down construction spending forecasts.
Segmentation dimensions modeled span product type, application, technology, and end user across the projection horizon. The analytical framework incorporates regulatory enforcement intensity variation across Java versus outer island provinces, certified technician network density, and polymer feedstock import dependency. CAGRs derive from installation rate projections by membrane technology and warranty term extension trends in infrastructure procurement.
Material uncertainties — currency fluctuation impact on resin import costs, Ministry certification timeline variability, and cementitious substitution acceleration in residential segments — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory harmonization progress and technician training pipeline expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Construction
Construction Repaint Market
Specialty Construction
Welded Metal Bellows Market
Specialty Construction
Asia-Pacific Anchors and Grouts Market
Specialty Construction
Temporary Fencing Panels Market
Specialty Construction
India Anchors and Grouts Market
Specialty Construction
Asia-Pacific Waterproofing Solutions Market
Specialty Construction
Indonesia Anchors and Grouts Market
Specialty Construction
Shotcrete Accelerators Market
Specialty Construction
Europe Anchors and Grouts Market
Specialty Construction
Slab Repair Products Market
Specialty Construction
Portable Walls Market
Specialty Construction
Fire Hydrants Market
Specialty Construction
Expandable Shelter Market
Specialty Construction
ASEAN Waterproofing Market
Specialty Construction
Roller Shutter Market
Specialty Construction
Composite Repair Market