
 Composite Repair Market | 2026-2036
Composite Repair Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Repair Market Analysis
Buyer concentration among airline MRO providers is expanding as fleet operators consolidate maintenance contracts with fewer approved repair stations. Lufthansa Technik AG dominates European widebody composite repair capacity through its Hamburg and Malta facilities. 3M Company leverages its adhesive chemistry portfolio to supply bonding systems across multiple airline repair networks. Henkel AG & Co. KGaA sustains its position through Loctite-branded structural paste adhesives certified to OEM specifications.
Composite repair encompasses the restoration of fiber-reinforced polymer structures through bonded patches, scarfed laminates, or resin infusion to recover original mechanical properties such as tensile strength and interlaminar fracture toughness. These techniques restore primary load-bearing capacity in aircraft skins, wind turbine blades, and pressure vessels without complete component replacement. Structural repair applications command the deepest margin pools due to airworthiness certification requirements and specialized technician labor. Carbon fiber material types lead value contribution where aerospace OEMs mandate original-equivalence performance in primary structure restoration. Bonding repair types are displacing mechanical fastening in newer aircraft programs, shifting tool investment patterns across MRO facilities.
The FAA's Advisory Circular 20-107B establishes composite aircraft structure repair standards that determine market access for US-based MRO stations. EASA's Part 145 regulations govern European repair station approvals, while the EU AI Act introduces documentation requirements for automated inspection systems used in defect detection. Stakeholders must monitor evolving OEM repair specification updates and regulatory harmonization between FAA and EASA as next-generation aircraft enter service with higher composite content.
Market Dynamics
Fleet operators are consolidating maintenance contracts with fewer approved repair stations, concentrating buying power among airline MRO providers and compressing margins for independent composite repair facilities serving secondary markets.
Growth Catalysts
- FAA Airworthiness Directives:Updated mandates on composite airframe maintenance tighten compliance requirements, forcing fleet operators toward certified repair stations with documented structural restoration capabilities.
- Bonding Technology Advancement:Structural paste adhesives certified to OEM specifications are displacing mechanical fastening in newer aircraft programs, expanding addressable repair volume per airframe.
- German MRO Hub Concentration:Lufthansa Technik and Air France KLM E&M operate major composite repair facilities in Hamburg and Malta, creating regional capacity anchors that attract narrowbody and widebody fleet contracts.
Market Restraints
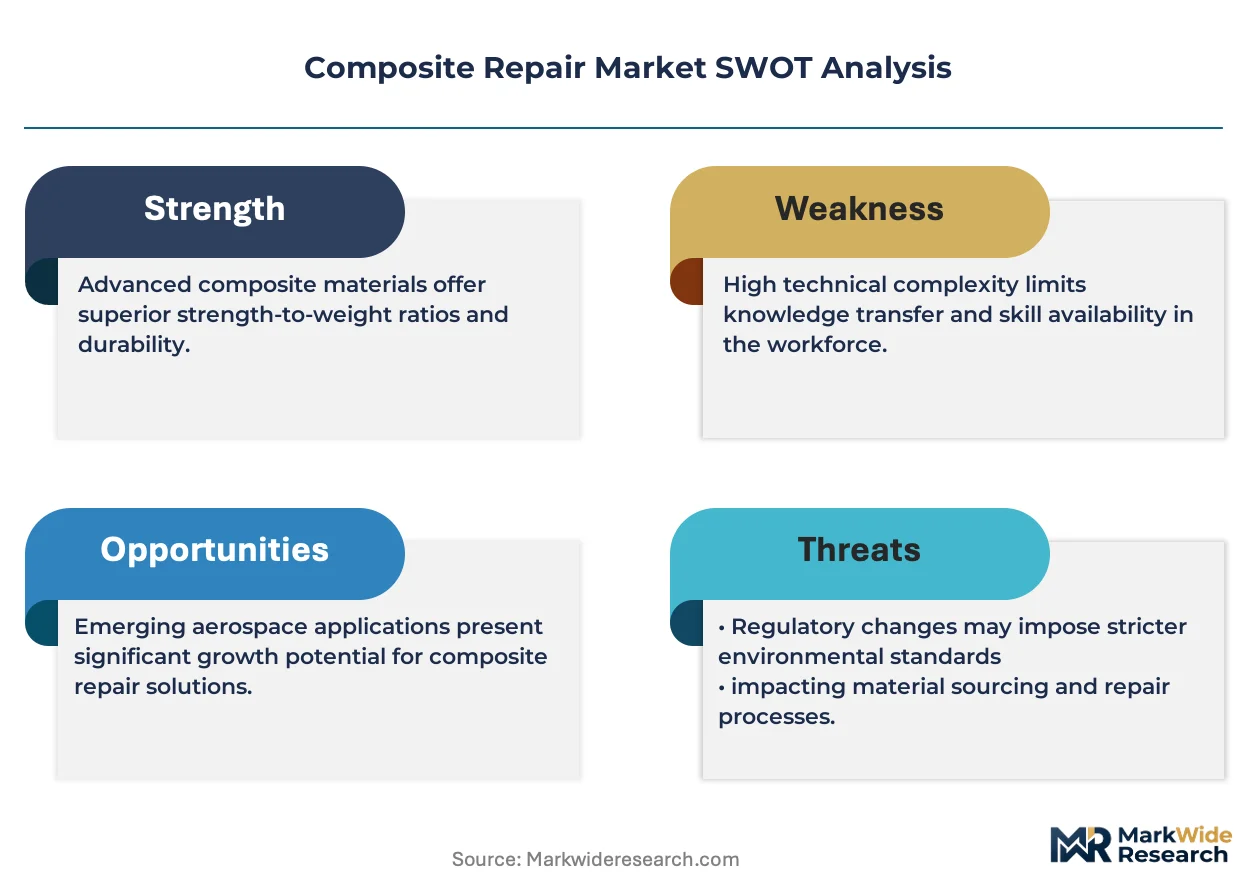
- Specialized Technician Scarcity:Structural composite repair requires certified laminators and NDT inspectors, with training pipelines failing to match fleet expansion rates in key aviation markets.
- Raw Material Concentration:Carbon fiber prepreg supply concentrates among Japanese and US chemical conglomerates, exposing MRO stations to aerospace-grade resin pricing volatility and allocation constraints.
- Equipment Depreciation Burden:Automated scarfing systems and thermal bonders require seven-figure capital commitments with ten-year depreciation schedules, freezing out smaller independent repair operators.
Strategic Opportunities
- Wind Turbine Blade Extension:Offshore wind installations in the North Sea and Baltic markets generate demand for structural restoration of 80-meter-plus blades, transferring aerospace bonding techniques to energy infrastructure.
- EU AI Act Documentation Pathway:Automated defect detection systems used in composite inspection gain regulatory clarity through European documentation requirements, accelerating MRO technology investment.
- Resin Infusion Process Convergence:Vacuum-assisted resin transfer molding from marine and automotive sectors migrates into aircraft secondary structure repair, reducing cure cycle times and technician labor hours.
Industry Challenges
- Multi-OEM Certification Burden:Repair stations must maintain separate approvals from Boeing, Airbus, and Bombardier for identical bonding procedures, duplicating audit costs and technical documentation.
- Legacy Metal-to-Composite Transition:Maintenance facilities built around aluminum sheet metal repair lack environmental controls for carbon fiber dust containment and temperature-humidity conditioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Repair Market |
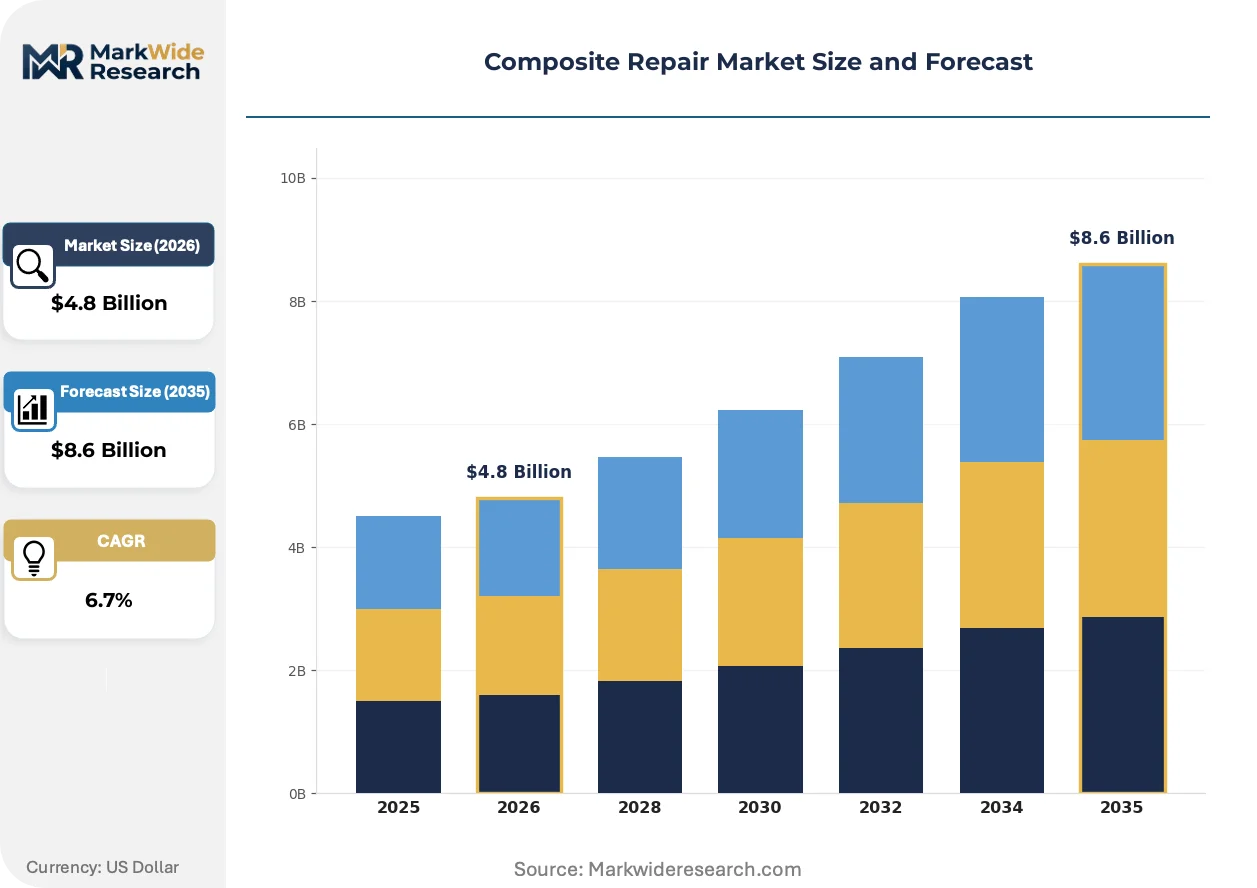
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Repair Type: Bonding, Patching, Coating, Reinforcing Industry Vertical: Aerospace, Automotive, Marine, Construction Material Type: Carbon Fiber, Glass Fiber, Aramid Fiber, Thermoplastic Application: Structural Repair, Surface Repair, Impact Repair, Cosmetic Repair |
| Companies Covered | Lufthansa Technik AG, Air France KLM E&M, HAECO, 3M Company, Henkel AG & Co. KGaA, Hexcel Corporation, Sika AG, Heatcon Composite Systems, Gurit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Repair Market Emerging Trajectories
Digital thread integration across design, manufacturing, and repair phases is collapsing information asymmetries between OEMs and MRO providers, reshaping how composite damage documentation flows through maintenance ecosystems.
Automated scarfing systems equipped with machine vision guidance are electrifying repair preparation workflows in primary structure restoration. Airlines with dense widebody fleets at Lufthansa Technik facilities in Hamburg are deploying these systems at scale, cutting scarf preparation time from eight hours to ninety minutes while standardizing taper geometries that manual methods cannot replicate. This compression is electrifying throughput capacity at European MRO hubs without proportional labor expansion.
EASA's Part 145 regulations governing European repair station approvals are tightening documentation requirements for composite structural repairs, mandating digital record retention that traces fiber orientation and cure cycles back to specific technician certifications. The industrial consequence is a bifurcation between capitalized MRO networks with integrated MES platforms and smaller stations facing six-figure compliance upgrade costs. German and French facilities serving flag carrier fleets are responding fastest, while Mediterranean independent operators lag in system implementation.
Airline procurement teams are unbundling composite repair from heavy maintenance checks, negotiating standalone rate-per-repair contracts rather than bundled labor-hour agreements. This disrupts traditional MRO pricing models that cross-subsidized structural work with line maintenance margins. The shift is most visible in North American carrier networks, where procurement functions centralize at headquarters and demand itemized cost transparency that legacy bundled contracts obscured.
Composite Repair Market Segmentation
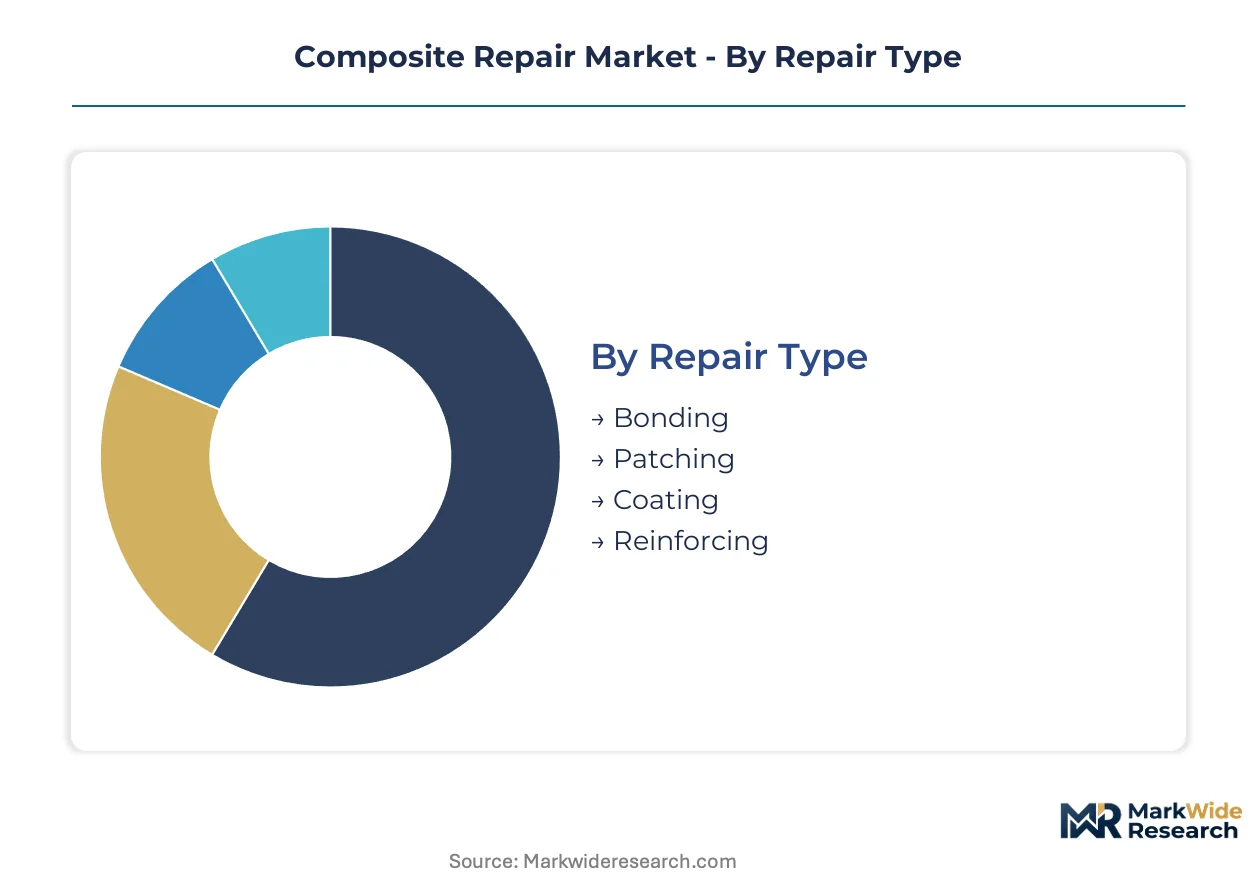
Segmentation in composite repair determines which MRO stations qualify for specific contracts based on material certifications and repair complexity tiers. Regulatory scope varies sharply across categories, with structural applications demanding FAA or EASA approvals that cosmetic work does not require.
Repair Type:
Bonding and patching procedures carry distinct certification burdens under FAA Advisory Circular 20-107B, while coating and reinforcing applications face lighter documentation requirements.
- Bonding:Structural paste adhesives create load-bearing joints between scarfed laminates, requiring technician certification in cure cycle management. Demand concentrates at Lufthansa Technik Hamburg and Air France KLM E&M Malta facilities serving Airbus A350 and Boeing 787 programs, where OEM specifications mandate original-equivalence performance restoration.
- Patching:Pre-cured composite patches restore strength to damaged skins through vacuum-bonded overlays, with scarf geometry determining airworthiness approval. North American MRO networks favor this method for narrowbody fleet maintenance, compressing turnaround times against heavy maintenance check schedules.
- Coating:Protective resin systems seal repaired surfaces against environmental degradation, requiring less specialized labor than structural methods.
- Reinforcing:Additional ply layers augment original laminate thickness in high-stress regions, common in wind turbine blade restoration.
Leading the category by volume: Bonding. Growing fastest: Patching.
Industry Vertical:
Cost tiers separate these verticals, with aerospace commanding premium pricing for airworthiness documentation that construction and marine segments do not replicate.
- Aerospace:Primary structure restoration on commercial aircraft demands traceable fiber orientation records and NDT verification per EASA Part 145. Fleet operators consolidate contracts with approved stations, compressing margins for independent facilities lacking OEM endorsements.
- Automotive:Carbon fiber body panel repair serves premium vehicle segments where OEM certification programs remain fragmented across manufacturer-specific networks.
- Marine:Vacuum-assisted resin transfer molding from yacht manufacturing migrates into hull repair, reducing cure cycles versus traditional hand layup.
- Construction:Bridge and infrastructure reinforcement uses glass fiber systems with lower performance thresholds than aerospace grades, expanding addressable technician pools.
Volume concentration: Aerospace. Steepest expansion trajectory: Marine.
Material Type:
Supply concentration shapes segment accessibility, with aerospace-grade carbon fiber prepreg allocating preferentially to certified MRO stations.
- Carbon Fiber:T700S and IM7 grades dominate primary aircraft structure restoration where tensile strength and interlaminar fracture toughness must match original specifications. Japanese and US chemical conglomerates control aerospace resin supply, exposing repair stations to allocation constraints during fleet expansion cycles.
- Glass Fiber:E-glass and S-glass variants serve secondary structures and marine applications with lower modulus requirements, broadening supplier options.
- Aramid Fiber:Kevlar and Twaron systems absorb impact energy in ballistic and aerospace applications, requiring specialized cutting equipment to prevent fiber fuzzing.
- Thermoplastic:PEEK and PPS matrices enable weldable repairs without lengthy cure cycles, emerging in next-generation aircraft programs.
Revenue concentration: Carbon Fiber. Climbing the fastest: Thermoplastic.
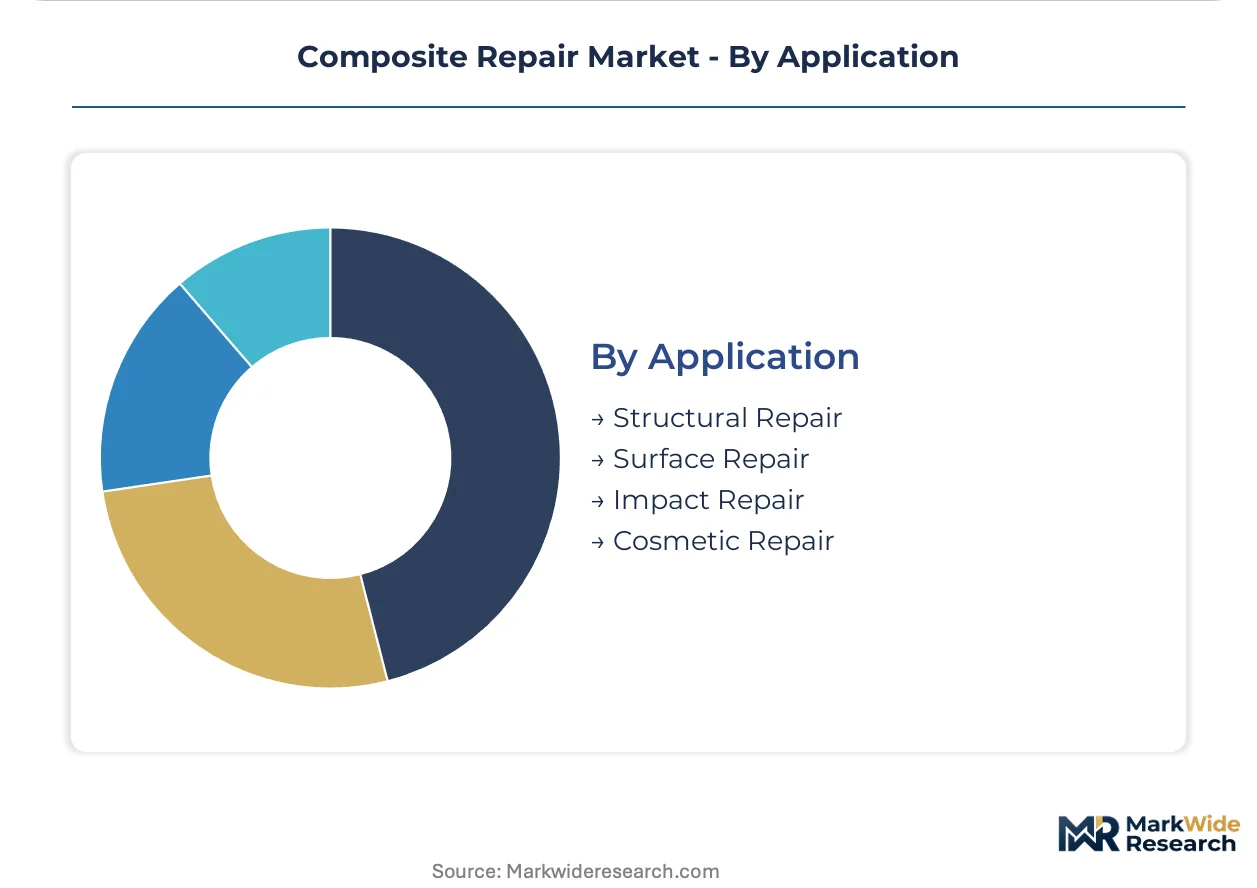
Application:
Customer type bifurcation separates structural from cosmetic work, with airlines and fleet operators demanding the former while independent owners tolerate the latter.
- Structural Repair:Restoration of load-bearing capacity in wings, fuselage sections, and pressure vessels requires documented mechanical property recovery. FAA airworthiness directives tighten compliance, forcing operators toward stations with bonded patch and scarfed laminate capabilities.
- Surface Repair:Gel coat and primer restoration protects underlying laminates without recovering primary strength, common in marine and wind turbine maintenance.
- Impact Repair:Dent and delamination treatment from bird strikes or ground equipment contact, prevalent in high-cycle narrowbody operations.
- Cosmetic Repair:Finish restoration for appearance without structural certification, serving private aviation and automotive collector markets.
Margin concentration: Structural Repair. Gaining share fastest: Impact Repair.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Airline MRO procurement concentrates buying power among German, US, and French flag carriers, reshaping repair station economics across three continents. Fleet operators now consolidate composite maintenance contracts with fewer approved facilities, forcing regional capacity realignment.
United States
American Airlines and Delta Air Lines drive narrowbody fleet maintenance demand through centralized procurement functions. The FAA's updated Advisory Circular 20-107B tightens documentation standards for bonded structural repairs. Repair stations in Wichita, Kansas and Everett, Washington specialize in Boeing 787 primary structure restoration, attracting fleet contracts from Pacific-based operators.
Germany
Lufthansa Technik AG dominates European widebody composite capacity through Hamburg and Malta facilities serving Airbus A350 programs. EASA Part 145 regulations mandate digital record retention tracing fiber orientation to technician certifications. The Hamburg cluster anchors continental repair volume, drawing narrowbody contracts from Ryanair and Eurowings.
France
Air France KLM E&M operates dual hubs in Paris and Amsterdam serving mixed Boeing-Airbus fleets. The EU AI Act introduces documentation requirements for automated defect detection systems used in scarf preparation. Toulouse-area facilities leverage proximity to Airbus manufacturing for OEM specification alignment in A320neo wing repairs.
China
COMAC C919 fleet expansion generates domestic repair demand previously served by foreign MRO stations. MIIT standards for carbon fiber prepreg allocation prioritize aerospace-grade resin supply to certified facilities. Shanghai Pudong and Tianjin clusters attract joint-venture partnerships between Chinese airlines and European MRO providers.
United Kingdom
British Airways consolidates widebody maintenance at Cardiff facilities serving Heathrow long-haul operations. The UK Civil Aviation Authority maintains bilateral recognition with EASA for repair station approvals post-Brexit. Manchester-area independent operators struggle with six-figure MES platform investments required for compliance documentation.
Composite Repair Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue thermoplastic repair methods and automated inspection systems. The vendor base stratifies across three tiers: multinational adhesive suppliers with aerospace certification portfolios, airline-captive MRO networks with OEM repair authority, and independent repair stations serving secondary markets. Strategic archetypes include chemistry-focused material suppliers, fleet-integrated maintenance providers, and equipment fabricators for automated scarfing systems. Competitive moves center on M&A to capture OEM repair specifications and capacity expansion at airport-adjacent facilities.
Within the airline-captive MRO tier, Lufthansa Technik AG and Air France KLM E&M exemplify fleet-integrated operators with OEM repair authority across multiple aircraft programs. Among material suppliers, 3M Company and Henkel AG & Co. KGaA represent chemistry-focused incumbents supplying structural paste adhesives certified to Boeing and Airbus specifications. These four entities anchor competitive positioning through distinct capability moats: MRO networks through repair station approvals, material suppliers through adhesive formulation lock-in.
| Leading Market Players |
|---|
| Lufthansa Technik AG |
| Air France KLM E&M |
| HAECO |
| 3M Company |
| Henkel AG & Co. KGaA |
| Hexcel Corporation |
| Sika AG |
| Heatcon Composite Systems |
| Gurit |
| Others |
Supply Flow & Price Mechanics
Automated scarfing systems with machine vision guidance are compressing repair preparation timelines from hours to minutes while concentrating capital requirements among MRO networks with thermal bonder and environmental control investments. This equipment transition simultaneously elevates technician productivity benchmarks and locks out independent operators lacking seven-figure depreciation capacity, reshaping how pricing power accumulates at certified repair stations.
Pricing Analysis
Structural restoration commands premium margins against cosmetic work, with airworthiness certification tiers separating OEM-authorized stations from independent facilities. Three-tier pricing structure across OEM-certified, MRO-network, and independent levels reflects documentation depth and technician specialization. Pricing pressure stems from airline procurement teams unbundling composite repair from heavy maintenance checks and demanding itemized rate-per-repair transparency. Low-volume independent operators face acute price sensitivity as fleet operators consolidate contracts with fewer approved stations.
Supply Chain Analysis
MIIT standards for carbon fiber prepreg allocation in China and domestic-content mandates across aerospace supply chains are redirecting resin sourcing toward certified facilities with documented traceability. Japanese and US chemical conglomerates control aerospace-grade carbon fiber and epoxy resin supply, exposing MRO stations to allocation constraints during fleet expansion cycles. Single-source vulnerability concentrates in Toray and Hexcel prepreg supply for primary structure restoration. Distribution runs through OEM-approved logistics networks with temperature-controlled handling requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bonding technology displacement of mechanical fastening represents a generational transition in aircraft maintenance, with structural paste adhesives certified to Boeing and Airbus specifications replacing riveted repairs in newer composite-intensive programs.
For Market Incumbents: Acquire automated inspection system capabilities to defend against emerging entrants with AI-driven defect detection platforms. Lufthansa Technik and Air France KLM E&M should expand OEM repair authority into COMAC C919 programs before Chinese MRO networks mature. Backward integration into adhesive formulation through partnerships with Henkel or 3M secures supply priority during resin allocation constraints. For New Entrants and Emerging Players: EU AI Act documentation requirements in Europe open a window for automated scarfing system providers to penetrate EASA Part 145 facilities facing six-figure compliance upgrade costs. Wind turbine blade restoration in the North Sea and Baltic markets offers the most penetrable application for aerospace bonding technique transfer. Target marine and construction verticals with lower certification barriers as beachhead segments before pursuing aerospace structural approvals. For Investors and Strategic Acquirers: Exit pathways concentrate in airline-captive MRO networks with multi-OEM repair authority and integrated MES platforms. Long-term viability favors facilities with environmental controls for carbon fiber dust containment and temperature-humidity conditioning. Watch for COMAC C919 fleet expansion rates as inflection indicator for Chinese MRO joint-venture opportunity timing.| Strategic Initiative | Industry Significance |
|---|---|
| OEM Repair Authority Expansion | Multi-aircraft program approvals from Boeing, Airbus, and COMAC attract consolidated fleet contracts. |
| Automated Scarfing System Deployment | Machine vision guidance cuts preparation time by 85% at Lufthansa Technik Hamburg facilities. |
| Adhesive Chemistry Partnership | Structural paste certification lock-in with 3M or Henkel secures bonding system supply priority. |
| Wind Turbine Blade Service Entry | Offshore wind installations transfer aerospace techniques to 80-meter-plus blade restoration. |
| MES Platform Integration | Digital record retention for fiber orientation traceability satisfies EASA Part 145 mandates. |
Methodological Framework
Multi-period observation of fleet expansion rates, MRO capacity utilization, and adhesive pricing trends anchored the trend analysis, supplemented by interviews with airline procurement directors, EASA Part 145 compliance officers, composite repair technicians, and carbon fiber prepreg supply managers. Secondary validation drew from FAA Advisory Circular updates, EASA regulatory filings, MIIT carbon fiber allocation directives, and OEM repair specification documentation. Bottom-up repair volume estimates triangulated against top-down fleet maintenance spend projections.
Segment-weighting across repair type, material grade, industry vertical, and application complexity shaped the analytical framework across the analysis window. Aerospace structural restoration received highest weighting given airworthiness certification requirements and margin concentration. Carbon fiber primary structure repairs, glass fiber secondary applications, and emerging thermoplastic weldable methods each carried distinct growth assumptions. CAGRs derived from technician training pipeline capacity, fleet composite content trajectories, and regulatory harmonization progress between FAA and EASA.
Caveats apply where COMAC C919 fleet delivery delays, carbon fiber prepreg supply allocation disruptions, or technician certification bottlenecks could materially shift the outlook. Forecasts reflect assumptions on regulatory harmonization pace and airline procurement centralization trends. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Construction
Europe Anchors and Grouts Market
Specialty Construction
Global Fencing Market
Specialty Construction
Indonesia Anchors and Grouts Market
Specialty Construction
Indonesia Waterproofing Solutions Market
Specialty Construction
Roller Shutter Market
Specialty Construction
Asia-Pacific Anchors and Grouts Market
Specialty Construction
Shotcrete Accelerators Market
Specialty Construction
Asia-Pacific Waterproofing Solutions Market
Specialty Construction
Construction Repaint Market
Specialty Construction
ASEAN Waterproofing Market
Specialty Construction
Fire Hydrants Market
Specialty Construction
Portable Walls Market
Specialty Construction
Expandable Shelter Market
Specialty Construction
Slab Repair Products Market
Specialty Construction
South America Anchors and Grouts Market
Specialty Construction
Temporary Fencing Panels Market