
 Fire Hydrants Market | 2026-2036
Fire Hydrants Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Hydrants Market Intelligence
Aftermarket service revenue is narrowing as original equipment manufacturers extend lifecycle support contracts to capture recurring income. Mueller Co. LLC leverages its foundry network to dominate municipal procurement channels across the Midwest. AVK International A/S anchors European demand through specialized corrosion-resistant coating systems. American Cast Iron Pipe Company sustains manufacturing scale via backward integration into ductile iron production.
Fire hydrants are pressurized water discharge devices installed along water distribution mains, typically manufactured from cast iron or ductile iron with brass or bronze valve components, designed to provide fire suppression crews with immediate access to high-flow water at standardized connection points. Wet barrel configurations lead in temperate climates where freeze risk is minimal, while dry barrel units represent the fastest-growing category in northern latitudes due to expanding cold-weather infrastructure investment. Cast iron material grades continue to occupy the largest volume share, though stainless steel segments are gaining ground in coastal and chemically aggressive environments where chloride-induced corrosion threatens standard alloy performance.
The US EPA, Underwriters Laboratories, and the American Water Works Association govern hydrant design, flow performance, and material safety standards across North American markets, with NSF/ANSI 61 certification now mandatory for all components contacting potable water. The EU F-Gas Regulation and national transpositions in Germany, France, and Italy impose parallel requirements on fire suppression system interoperability and environmental compatibility. Stakeholders must monitor evolving lead-content thresholds and flow-rate mandates as jurisdictions tighten public safety specifications without grandfathering existing installations.
Market Dynamics
Municipal water authorities across the United States are compressing replacement cycles for buried infrastructure as century-old cast iron networks reach material fatigue thresholds. The EPA Lead and Copper Rule revisions are forcing utilities to verify coating integrity and material composition at scale, redirecting capital budgets toward compliant hydrant procurement.
Growth Catalysts
- Wildfire risk escalation:Rapid urbanization across the southeastern United States is expanding municipal fire protection budgets and mandating higher-density hydrant placement in wildland-urban interface zones.
- NSF/ANSI 61 certification mandate:Potable water contact requirements now apply to all hydrant components, compelling wholesale system upgrades and replacement demand across legacy installations.
- Cold-weather infrastructure investment:Northern municipalities are accelerating dry barrel hydrant deployment as freeze-resistant designs displace wet barrel configurations in temperate-to-fringe climate zones.
Market Restraints
- Ductile iron price volatility:Foundry energy costs and scrap metal input fluctuations compress manufacturer margins and complicate municipal procurement forecasting.
- Coastal foundry concentration:Domestic casting capacity clusters along hurricane-exposed coastlines, exposing supply chains to weather-related production interruptions.
- Stainless steel substitution economics:Chloride-resistant alloys command 3-4x material premiums versus standard ductile iron, limiting adoption to chemically aggressive environments despite superior lifecycle performance.
Strategic Opportunities
- Smart city water grid integration:Pressure-monitoring hydrant retrofits create recurring telemetry revenue streams for manufacturers with IoT-enabled product architectures.
- EU F-Gas Regulation alignment:European interoperability standards for fire suppression systems open export pathways for North American producers with corrosion-resistant coating certifications.
- Lifecycle support contract expansion:Municipal buyers are unbundling installation from decades-long maintenance agreements, creating annuity revenue models for OEMs with field service networks.
Industry Challenges
- Certification timeline compression:NSF/ANSI 61 and AWWA C502 testing protocols now require 18-24 month validation cycles, delaying product launches and freezing R&D roadmaps.
- Foundry workforce attrition:Mold-making and metallurgical quality control expertise is concentrating among retiring craft workers, constraining production scaling for ductile iron casting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Hydrants Market |
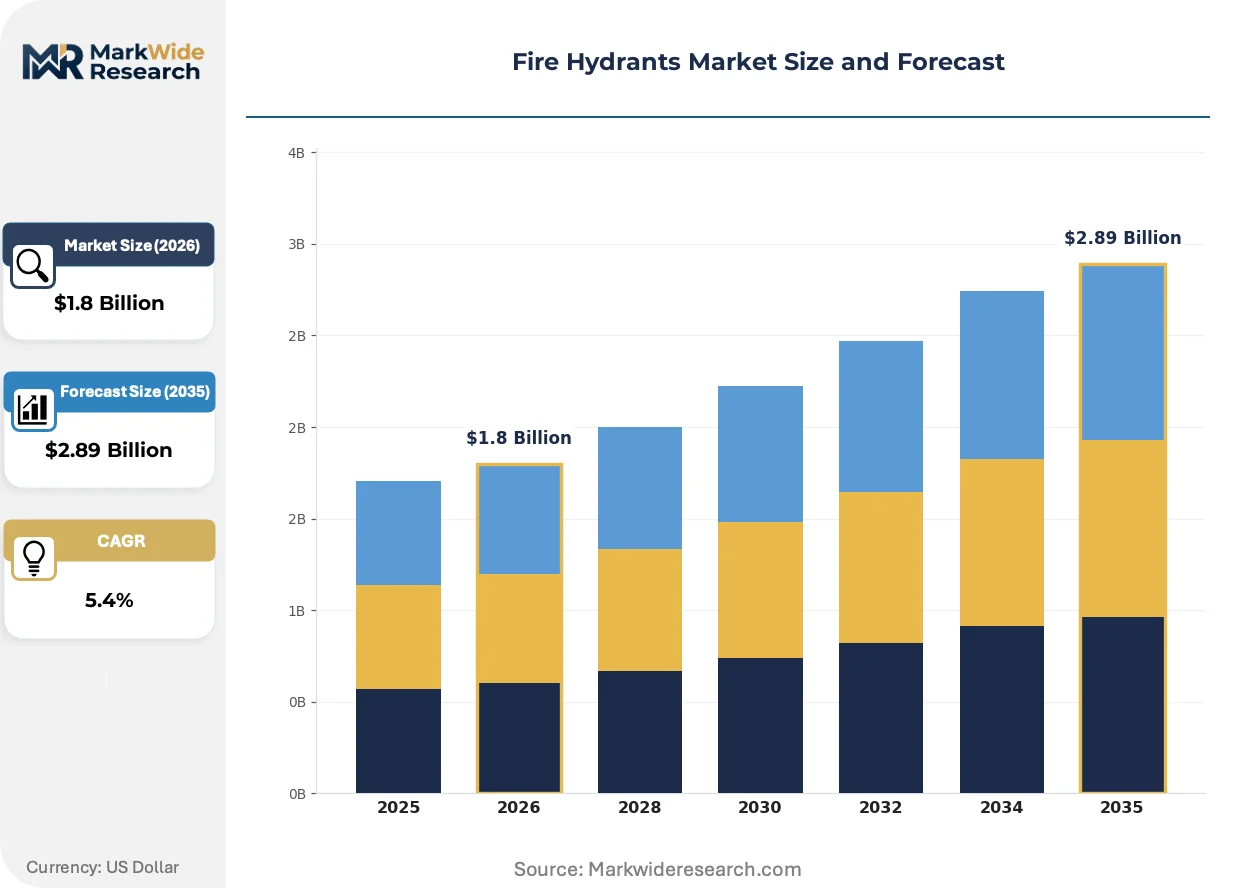
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.89 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Wet Barrel, Dry Barrel, Post Indicator Valve, Fire Department Connection Material: Cast Iron, Stainless Steel, Thermoplastic, Aluminum Feature: Corrosion Resistance, Increased Flow Rate, Easy Maintenance, Custom Color Options Installation Type: Bury, Above Ground, Hybrid, Remote Installation |
| Companies Covered | American Cast Iron Pipe Company, AVK International A/S, Mueller Co. LLC, McWane International, EJ Group Inc., Bocciolone Antincendio S.p.a., Kupferle Foundry Company, Kennedy Valve Company, Rapidrop Global Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Hydrants Market Strategic Shifts & Innovations
Digital instrumentation is penetrating buried water infrastructure, converting passive hydrants into active network monitoring nodes. Manufacturers are racing to embed pressure transducers and acoustic leak detection without compromising mechanical reliability or maintenance access.
Telemetry-enabled hydrant retrofits are virtualizing traditional asset management. Municipal water departments in Texas and Arizona are piloting cellular-connected pressure monitors that transmit flow anomalies in real-time. This capability is virtualizing scheduled physical inspections and compressing emergency response dispatch times for main breaks.
The EPA Lead and Copper Rule revisions are tightening material disclosure requirements for all potable water contact surfaces. Hydrant manufacturers must now document brass and bronze alloy compositions through supply chain tiers. California and Illinois water authorities are imposing the strictest verification protocols, rejecting bids without certified mill test reports.
Consolidated procurement through regional water authority cooperatives is displacing municipal-by-municipal purchasing. The Southeast Water Alliance and similar multi-state buying pools are standardizing specifications and compressing vendor lists to three approved manufacturers. This concentration is most visible across Florida, Georgia, and the Carolinas where rapid growth strains distributed procurement capacity.
Fire Hydrants Market Segmentation
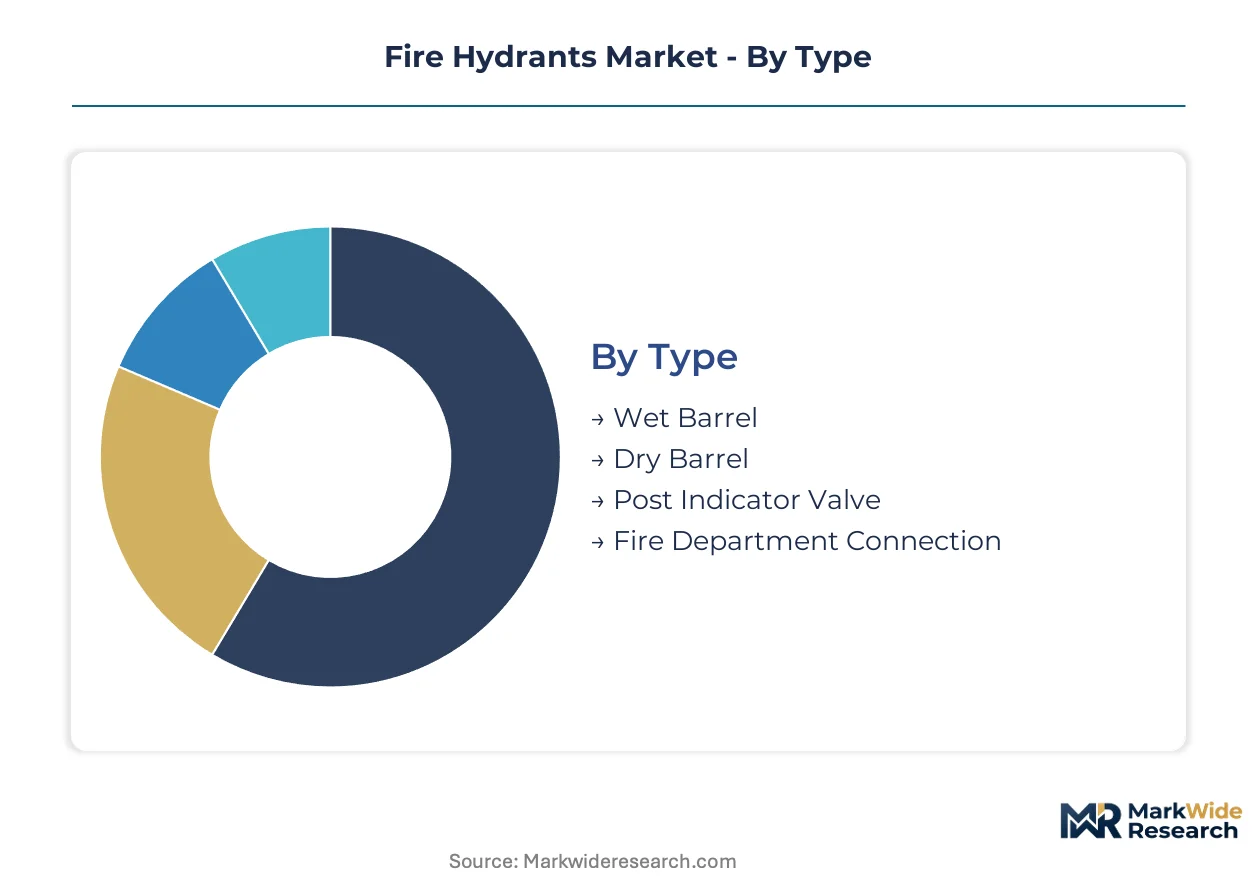
Fire hydrant procurement cycles vary dramatically by configuration and environment. Municipal buyers segment specifications by freeze risk, soil chemistry, and maintenance access constraints. Each dimension carries distinct replacement timelines and capital planning implications.
Type:
Wet barrel units turn over fastest in temperate zones where freeze damage is absent, while dry barrel configurations command longer cycles but accelerate replacement in expanding cold-climate infrastructure budgets.
- Wet Barrel:Above-ground valve assemblies remain pressurized year-round, eliminating drain mechanisms. Florida and Georgia municipal water authorities specify these for coastal subdivisions where frost penetration is negligible and maintenance access is unrestricted.
- Dry Barrel:Drainable designs isolate water below the frost line via compression seals. Minnesota and Wisconsin utilities are displacing legacy wet barrel stock in fringe climate zones as insurance underwriters mandate freeze-resistant specifications.
- Post Indicator Valve:Wall-mounted visual indicators serve specialized industrial and institutional campus applications.
- Fire Department Connection:Standpipe interfaces support high-rise and complex structure suppression systems.
Wet barrel configurations anchor the volume base while dry barrel designs gain share at the steepest rate.
Material:
Cost tiers separate commodity municipal procurement from premium coastal and chemical environment specifications.
- Cast Iron:Gray and ductile iron grades dominate standard municipal procurement through foundry economies of scale. EPA Lead and Copper Rule verification requirements are redirecting capital toward certified coating systems rather than material substitution.
- Stainless Steel:Austenitic and duplex alloys withstand chloride-induced corrosion in marine atmospheres and de-icing salt exposure. Texas coastal counties and California beach cities specify these despite material premiums that constrain adoption to high-risk infrastructure corridors.
- Thermoplastic:Composite housings serve temporary construction and corrosion-isolation applications.
- Aluminum:Lightweight alloys address aircraft rescue and specialized mobility requirements.
Cast iron retains the dominant procurement share while stainless steel climbs the fastest in coastal replacement cycles.
Feature:
Application-specific performance tiers separate baseline municipal compliance from premium service-level agreements.
- Corrosion Resistance:Fusion-bonded epoxy and polyurethane coating systems extend burial life in aggressive soils. Illinois and Ohio utilities facing sulfate-reducing bacteria degradation specify enhanced barrier protection.
- Increased Flow Rate:Large-diameter valve bores and streamlined barrel geometries support high-density suburban development. Arizona and Nevada fire marshals mandate these for wildland-urban interface zones where standpipe spacing is constrained.
- Easy Maintenance:Replaceable valve cartridges and top-entry designs reduce crew time.
- Custom Color Options:Municipal branding and utility identification coatings serve aesthetic and operational visibility requirements.
Corrosion resistance anchors the feature specification base while increased flow rate expands most quickly in high-growth southwestern development corridors.
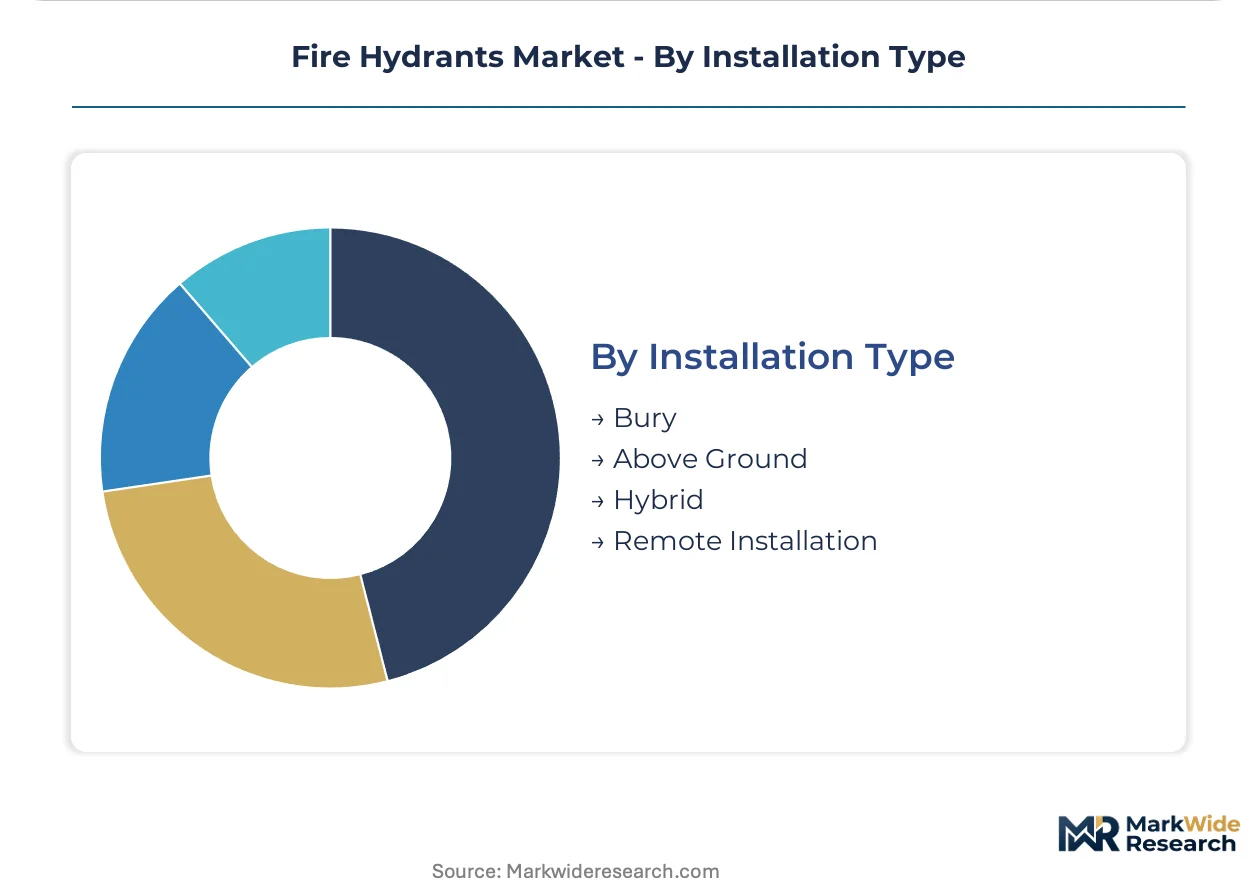
Installation Type:
Customer type and site constraints determine whether buried, exposed, or hybrid mounting prevails.
- Bury:Standard subsurface burial with traffic-rated castings dominates municipal street right-of-way deployment. Southeast Water Alliance cooperative procurement standardizes these specifications across Florida, Georgia, and the Carolinas.
- Above Ground:Exposed riser configurations serve flood-prone Louisiana bayou parishes and coastal surge zones where burial risks submersion contamination.
- Hybrid:Adjustable burial depth systems accommodate variable frost line and grade conditions.
- Remote Installation:Satellite-connected pressure monitoring nodes enable telemetry integration without physical access.
Bury installations anchor the volume base while remote installation gains share fastest in smart city water grid pilots.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal procurement elasticity varies sharply by geography. Southeast US water authorities prioritize rapid deployment over unit cost, while Midwestern utilities emphasize lifecycle value and coating durability.
United States
EPA Lead and Copper Rule revisions are compelling utilities across Illinois and Ohio to verify brass alloy compositions and coating integrity. The Southeast Water Alliance cooperative is consolidating procurement across Florida, Georgia, and the Carolinas. Texas coastal counties specify stainless steel configurations for chloride-rich environments despite material premiums.
Germany
EU F-Gas Regulation transpositions mandate fire suppression system interoperability standards that redirect municipal budgets toward certified corrosion-resistant coating systems. Bavarian water authorities are accelerating dry barrel deployment in Alpine fringe zones. Foundry capacity concentrates in North Rhine-Westphalia, where ductile iron casting expertise supports cross-border supply to Benelux markets.
China
Rapid urbanization across Yangtze River Delta municipalities is expanding fire protection infrastructure budgets for high-density residential corridors. GB standards for water distribution components are tightening material disclosure requirements. Foundry clusters in Shandong Peninsula are scaling ductile iron casting capacity to serve domestic cold-weather infrastructure investment.
Japan
METI guidelines for seismic-resistant infrastructure are mandating enhanced mechanical reliability specifications for buried water assets. Kanto region utilities are piloting pressure-monitoring retrofits in Tokyo metropolitan distribution networks. Osaka-based municipal cooperatives are standardizing wet barrel specifications for temperate coastal deployment.
Canada
Health Canada guidelines for lead content in potable water components are accelerating replacement cycles across Ontario and Quebec legacy networks. Prairie province municipalities are specifying dry barrel configurations for extreme freeze-thaw cycling. British Columbia water authorities prioritize corrosion-resistant coatings for coastal saline exposure.
Fire Hydrants Market Key Industry Players
Capability concentration sits with foundry-integrated manufacturers; scale advantage sits with procurement-channel dominators. The market structures around three tiers: municipal procurement incumbents with decades-long installed bases, corrosion-specialist coating innovators, and telemetry-enabled smart infrastructure entrants. Consolidation pressure is intensifying as regional water authority cooperatives compress vendor lists to three approved manufacturers. Backward integration into ductile iron production and lifecycle support contract expansion represent the dominant competitive vectors.
Among foundry-integrated specialists, American Cast Iron Pipe Company and Mueller Co. LLC exemplify the municipal procurement incumbent archetype through captive supply chains and field service networks. AVK International A/S occupies a position within the corrosion-resistant coating tier, anchoring European demand through specialized barrier protection systems. These three manufacturers represent the concentration pattern visible across North American and European procurement channels.
| Leading Market Players |
|---|
| American Cast Iron Pipe Company |
| AVK International A/S |
| Mueller Co. LLC |
| McWane International |
| EJ Group Inc. |
| Bocciolone Antincendio S.p.a. |
| Kupferle Foundry Company |
| Kennedy Valve Company |
| Rapidrop Global Ltd. |
| Others |
Cost & Logistics Intelligence
Overcapacity in Shandong Peninsula foundries is compressing ductile iron casting margins and forcing North American manufacturers to absorb energy cost volatility through long-term municipal contracts rather than spot adjustments.
Pricing Analysis
Lifecycle support contracts now drive lifetime value capture more than initial equipment sales. Three-tier pricing structure across premium corrosion-resistant coatings, standard NSF/ANSI 61 certified units, and economy municipal bid packages separates procurement tiers. Cost compression in standard ductile iron grades is intensifying because scrap metal input fluctuations and foundry energy surcharges squeeze manufacturer margins. Municipal cooperative buyers exhibit the highest price sensitivity, while coastal utilities facing chloride exposure accept material premiums for stainless steel configurations.
Supply Chain Analysis
Extended payment terms from regional water authority cooperatives are restructuring supplier cash flow requirements across the tier. Foundry capacity concentrates in China, the United States, and Germany, with ductile iron casting expertise anchoring supply security. Raw material dependencies rest on scrap steel feedstock, brass valve components, and fusion-bonded epoxy coating systems. Tariff exposure on Chinese casting imports creates procurement risk for North American utilities. Distribution runs through municipal procurement channels, regional cooperative buying pools, and specialized fire protection contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mold-making and metallurgical quality control expertise is concentrating among retiring craft workers, constraining production scaling and creating acquisition opportunities for firms with captive foundry talent pipelines.
For Market Incumbents: Insulate installed base relationships through backward integration into certified coating application facilities and exclusive lifecycle service agreements. Foundry workforce attrition threatens production scaling; secure mold-making expertise through apprenticeship pipelines and acquisition of retiring craft worker knowledge. Channel control through Southeast Water Alliance cooperative vendor list concentration protects against price erosion from low-cost casting imports. For New Entrants and Emerging Players: Build out telemetry-enabled hydrant retrofit capabilities targeting Texas and Arizona smart city water grid pilots where cellular-connected pressure monitoring creates recurring revenue white space. Coastal stainless steel specifications in California and Texas beach cities offer penetrable premium tiers where material science differentiation outweighs foundry scale disadvantages. Partner with IoT platform providers for rapid smart infrastructure certification rather than building telemetry stacks internally. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among foundry-integrated manufacturers with field service networks capable of unbundling installation from decades-long maintenance agreements. Long-term viability across the projection horizon favors firms with captive ductile iron supply and NSF/ANSI 61 certification infrastructure already validated. Monitor EPA Lead and Copper Rule enforcement intensity in Illinois and California as the inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Systems | Captive epoxy application facilities secure EPA compliance verification and shorten certification timelines. |
| Telemetry Platform Partnership | Cellular pressure monitoring integration converts passive hydrants into recurring-revenue smart grid nodes. |
| Foundry Workforce Apprenticeship Program | Mold-making expertise pipelines address retiring craft worker concentration in North Rhine-Westphalia and Ohio. |
| Regional Cooperative Vendor List Entry | Southeast Water Alliance standardization creates procurement access across Florida, Georgia, and Carolinas growth corridors. |
| Stainless Steel Casting Capacity Addition | Chloride-resistant alloy production addresses Texas and California coastal replacement premiums. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal water authority procurement directors, foundry operations managers, fire protection engineering consultants, and aftermarket service technicians. Secondary validation drew from EPA enforcement databases, AWWA technical standards publications, municipal cooperative procurement records, and ductile iron trade association capacity reports. Bottom-up unit shipment estimates triangulated against top-down infrastructure spending projections.
Calibration against historical replacement cycle data and regulatory enforcement patterns anchored volume assumptions across the projection horizon. Segmentation modeling spanned hydrant configuration type, material grade, corrosion protection tier, and climate zone deployment pattern. CAGRs were derived from infrastructure budget growth rates and regulatory compliance-driven replacement acceleration. Foundry capacity utilization and NSF/ANSI 61 certification timeline compression served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by low-cost Chinese casting exporters or rapid smart city telemetry platform consolidation would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Construction
Asia-Pacific Waterproofing Solutions Market
Specialty Construction
Shotcrete Accelerators Market
Specialty Construction
Temporary Fencing Panels Market
Specialty Construction
Asia-Pacific Anchors and Grouts Market
Specialty Construction
Slab Repair Products Market
Specialty Construction
Europe Anchors and Grouts Market
Specialty Construction
Indonesia Anchors and Grouts Market
Specialty Construction
Roller Shutter Market
Specialty Construction
Indonesia Waterproofing Solutions Market
Specialty Construction
Expandable Shelter Market
Specialty Construction
Portable Walls Market
Specialty Construction
India Anchors and Grouts Market
Specialty Construction
Global Fencing Market
Specialty Construction
Composite Repair Market
Specialty Construction
Welded Metal Bellows Market
Specialty Construction
Concrete and Cement Dissolver Market