
 Portable Walls Market | 2026-2036
Portable Walls Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Walls Market Analytics
Aluminum composite panels is recalibrating cost structures across mid-range portable wall offerings. Hufcor, Inc. dominates operable partition engineering through its vertically integrated track manufacturing. dormakaba Group leverages its access control heritage to anchor integrated smart-wall systems in European commercial fit-outs. HAWORTH INC. competes on workplace research credentials that shape its movable wall specifications for Fortune 500 headquarters.
Portable walls are relocatable partition systems, typically spanning 2.5 to 4.5 meters in height, engineered with steel or aluminum framing, infill panels of gypsum, glass, or acoustic composite, and overhead track hardware enabling reconfiguration without structural modification. Their primary commercial purpose is spatial division in leased or multi-purpose interiors where permanent construction triggers code complications or landlord restrictions. Folding walls command the largest installed base in education and municipal assembly halls where budget constraints favor proven hardware. Acoustic walls represent the fastest-expanding margin pool as open-plan office backlash drives specification of 45-50 STC-rated systems. Demountable walls sustain premium positioning through lease-end restoration cost avoidance in Class A commercial properties.
FCC guidelines on indoor wireless signal propagation influence glass-and-metal partition specifications in US commercial builds. OSHA workplace noise standards shape acoustic wall STC thresholds in manufacturing-adjacent office fit-outs. EPA recycled content requirements for federal procurement filter into manufacturer material sourcing disclosures. Stakeholders must weigh track hardware interoperability against proprietary panel ecosystems when specifying multi-vendor installations.
Market Dynamics
The EU Green Deal's embodied carbon requirements are forcing manufacturers to re-engineer core materials, compressing legacy gypsum-dominant supply chains while elevating recycled aluminum and bio-composite alternatives into specification-grade portfolios.
Growth Catalysts
- Corporate office redesign cycles:Fortune 500 headquarters in Frankfurt and Munich are specifying demountable wall systems to accelerate fit-out timelines and satisfy lease-end restoration clauses.
- FCC indoor wireless guidelines:US commercial builds now require glass-and-metal partition configurations that preserve signal propagation, favoring metal-framed portable walls over solid-core alternatives.
- Recycled aluminum sourcing:EU Green Deal mandates are pulling manufacturers toward low-carbon core materials, creating first-mover advantages for suppliers with verified circular supply chains.
Market Restraints
- Aluminum price volatility:LME aluminum futures swings compress margins on mid-range composite panel offerings, exposing non-integrated fabricators to input cost squeezes.
- Track hardware concentration:European overhead track manufacturing clusters around southern Germany create single-source vulnerability for multi-vendor installation projects.
- Acoustic performance ceilings:Current STC-rated composite panels hit technical limits near 50 STC, constraining specification in recording studios and broadcast facilities demanding 55+ isolation.
Strategic Opportunities
- Underpenetrated US healthcare:Hospital outpatient renovation cycles in Texas and Florida remain underserved by demountable wall specialists accustomed to commercial office specification protocols.
- Smart-wall convergence:Integration of embedded sensors and access control hardware with movable partition systems opens premium pricing in European commercial fit-outs.
- Lease-end restoration economics:Class A property managers in London and Paris are mandating demountable specifications to avoid drywall repair costs between tenants.
Industry Challenges
- Installation technician scarcity:Certified overhead track installers capable of precision alignment for acoustic-rated systems command wage premiums that erode project margins.
- Multi-vendor interoperability:Proprietary panel-to-track interfaces complicate specifications when architects source hardware and infill from separate suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Walls Market |
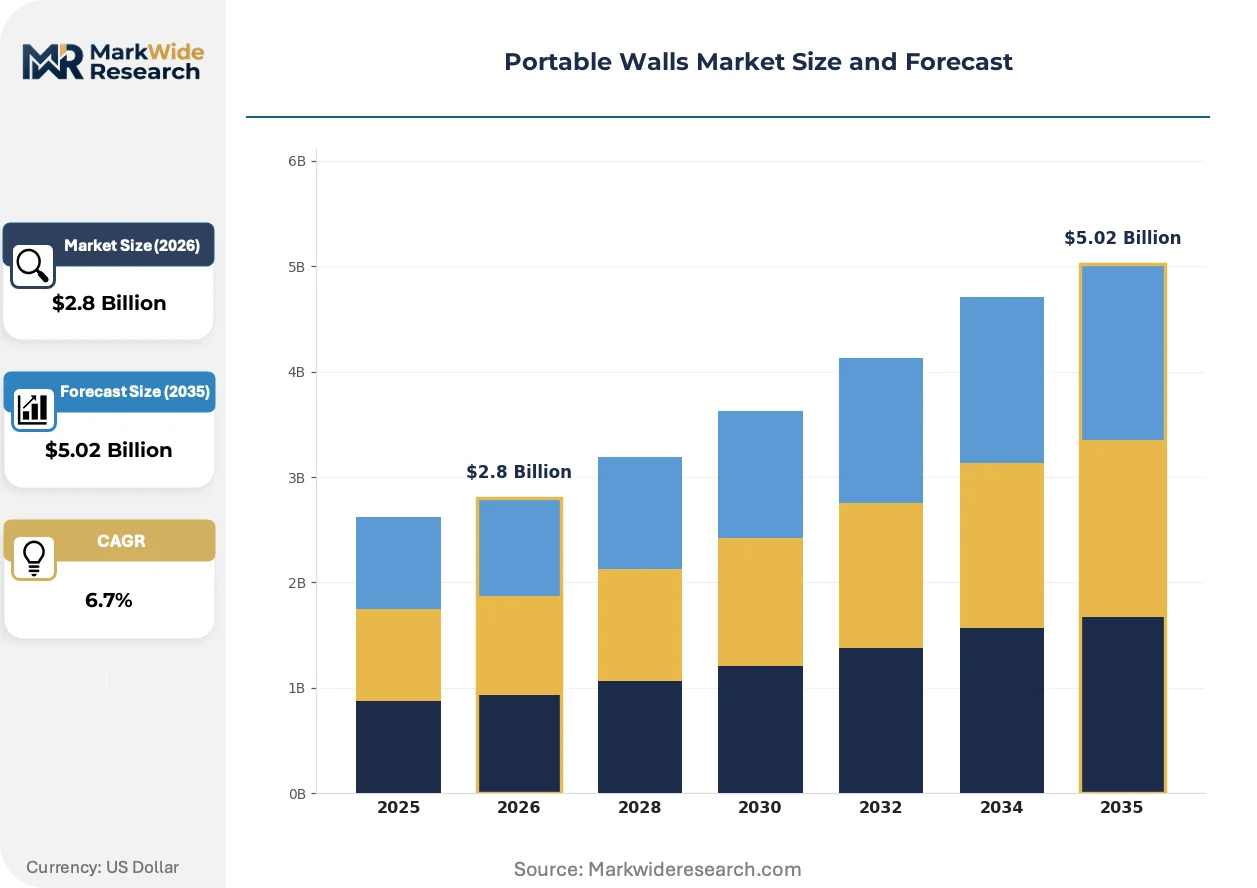
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Walls, Folding Walls, Demountable Walls, Acoustic Walls Material: Wood, Metal, Plastic, Glass Application: Commercial Spaces, Event Planning, Home Renovation, Temporary Exhibitions End User: Architects, Contractors, Event Organizers, Interior Designers |
| Companies Covered | Accordial Ltd, dormakaba Group, ENVIRONAMICS, Faraone, Fellowes Brands, Franz Nusing GmbH & Co KG, HAWORTH INC., HNI Corporation, Hufcor, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Walls Market Evolving Landscape
Material science advances and regulatory pressure on embodied carbon are converging to reshape portable wall engineering, with acoustic performance and circularity emerging as the primary axes of product differentiation.
Aluminum composite panel technology is modularizing portable wall construction by enabling thinner, lighter infill sections that maintain structural rigidity. Corporate office specifiers in Germany and the Netherlands are accelerating adoption of these systems for rapid reconfiguration cycles. The shift is compressing traditional gypsum-board supply chains while elevating fabricators with in-house composite lamination capabilities.
REACH chemical disclosure requirements are mandating transparency in adhesive and coating formulations across EU-manufactured partition systems. Manufacturers must now document SVHC content in track hardware finishes and panel edge banding. The compliance burden falls heaviest on mid-tier suppliers without dedicated regulatory affairs functions, pushing consolidation toward vertically integrated producers.
Facility managers are unbundling after-sales service contracts from initial hardware procurement, treating movable wall maintenance as a separate operating expenditure line item. Third-party service networks in US commercial real estate hubs are displacing manufacturer-captive installation crews for routine track adjustment and panel replacement. The disintermediation is most advanced in Chicago and Atlanta, where multi-tenant office turnover rates exceed national averages.
Portable Walls Market Segmentation
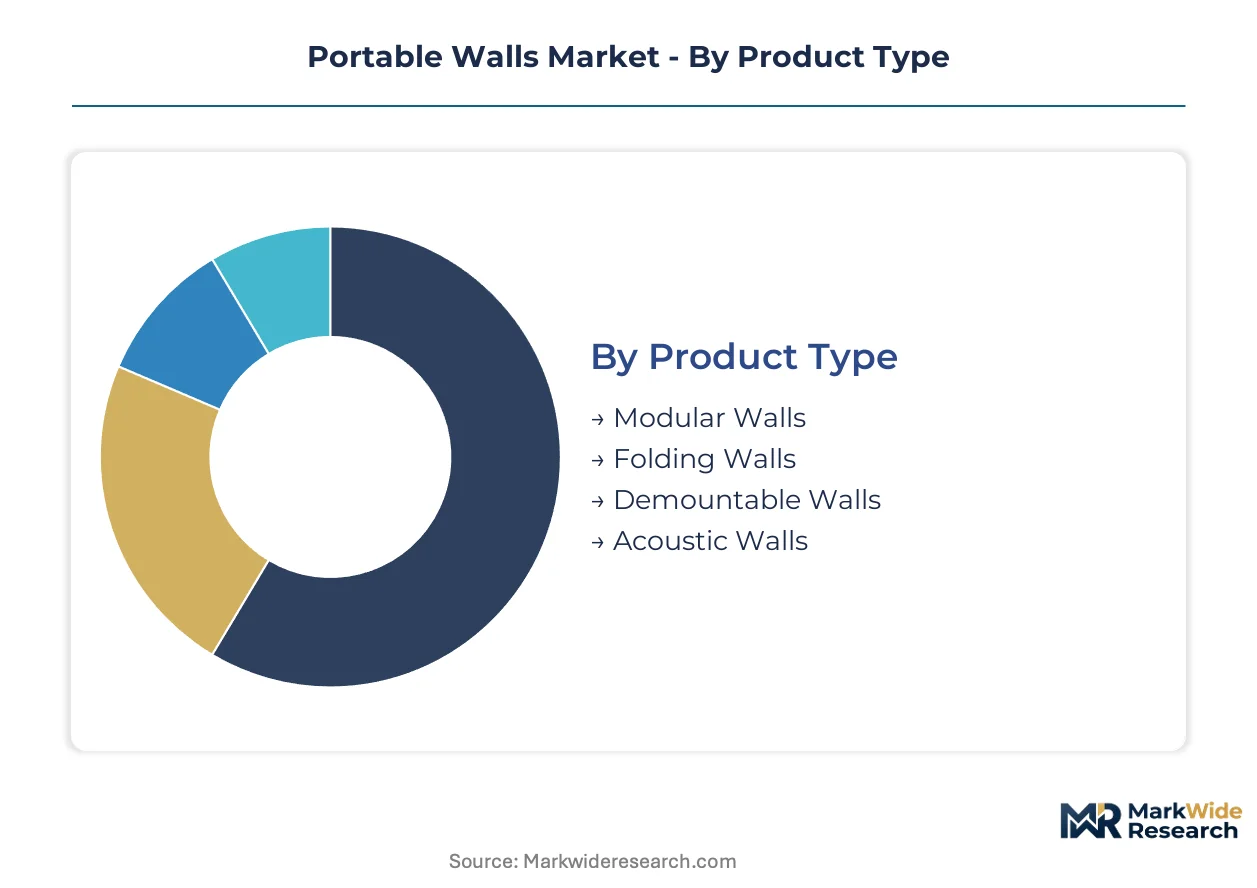
Portable walls fragment across four intersecting dimensions that determine specification protocols and margin structures. Product type dictates reconfiguration frequency and acoustic performance. Material selection reflects embodied carbon compliance and lease-end restoration economics. Application and end-user channels shape procurement authority and service bundling preferences.
Product Type:
Customization intensity spans from standardized folding hardware to architect-specified acoustic systems with integrated MEP routing.
- Folding Walls:Hinged panel assemblies mounted on ceiling tracks, typically 2.5–3.5 meters in height, with vinyl or fabric facings over honeycomb cores. Education and municipal assembly halls in Germany concentrate demand here, driven by capital budget constraints and proven durability in high-cycle environments.
- Acoustic Walls:Composite panel systems engineered to 45–50 STC ratings with mineral wool infill and mass-loaded vinyl barriers. Open-plan office backlash in Frankfurt and Munich commercial clusters is accelerating specification of these premium partitions for executive suites and focus rooms.
- Modular Walls:Pre-fabricated unitized frames with interchangeable infill options.
- Demountable Walls:Full-height systems designed for complete removal without trace at lease termination.
Most installed capacity flows through Folding Walls. Expansion is steepest in Acoustic Walls.
Material:
Cost tier stratification separates commodity inputs from specification-grade alternatives with verified circular supply chains.
- Metal:Aluminum and steel framing with recycled content certification, increasingly specified under EU Green Deal embodied carbon thresholds. Frankfurt Class A commercial developers now mandate EPD-documented aluminum cores to satisfy CSRD disclosure requirements.
- Glass:Tempered or laminated glazing with metal framing, preserving wireless signal propagation per FCC guidelines in US commercial builds while maximizing daylight penetration in Dutch and Danish office fit-outs.
- Wood:Timber framing with veneer or laminate facings.
- Plastic:PVC or polycarbonate panels for temporary and budget-sensitive deployments.
Metal commands the largest specification volume. Glass is gaining share fastest in premium commercial segments.
Application:
Volume concentration versus margin opportunity splits this category between cyclical renovation demand and recurring event logistics.
- Commercial Spaces:Corporate office fit-outs, co-working reconfigurations, and landlord base build specifications. Lease-end restoration clauses in London and Paris Class A properties are mandating demountable systems to avoid drywall repair costs between tenants.
- Event Planning:Temporary partition deployment for conferences, exhibitions, and corporate functions. Third-party rental networks in Chicago and Atlanta are displacing manufacturer-direct service for routine installation and strike cycles.
- Home Renovation:Residential room division and basement finishing applications.
- Temporary Exhibitions:Museum, gallery, and trade show partition systems.
Commercial Spaces absorb the majority of production volume. Event Planning exhibits the most volatile demand cyclicality.
End User:
Procurement authority and technical specification capability vary sharply across professional roles, shaping sales channel design.
- Architects:Design-phase specification authority with emphasis on aesthetic integration and acoustic performance documentation. German commercial real estate clusters around Munich see architect-driven selection of aluminum composite systems with verified EPDs.
- Contractors:Value engineering influence and installation risk allocation. US healthcare renovation contractors in Texas and Florida are underserved by demountable specialists accustomed to commercial office protocols.
- Interior Designers:Finish and hardware selection within architect-established performance parameters.
- Event Organizers:Rental procurement with emphasis on rapid deployment and strike logistics.
Architects control premium segment specification. Contractors dominate mid-market volume procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt and Munich commercial clusters anchor portable wall demand through Fortune 500 headquarters fit-outs. The EU Green Deal's embodied carbon mandates reshape specification protocols across German Class A properties. US healthcare renovation cycles in Texas and Florida remain underserved by demountable specialists.
Germany
Corporate headquarters in Frankfurt and Munich drive specification of demountable systems for rapid reconfiguration cycles. CSRD disclosure requirements under the EU Green Deal mandate EPD-documented aluminum cores in new commercial builds. Bavaria's manufacturing belt around Augsburg concentrates track hardware production for European distribution.
United States
FCC wireless propagation guidelines favor glass-and-metal partition configurations in commercial office fit-outs. OSHA workplace noise standards shape STC thresholds for manufacturing-adjacent office installations. Third-party service networks in Chicago and Atlanta displace manufacturer-captive crews for routine maintenance.
United Kingdom
Lease-end restoration clauses in London Class A properties mandate demountable specifications to avoid drywall repair costs. REACH chemical disclosure requirements burden mid-tier suppliers without dedicated regulatory functions. The Southeast corridor concentrates architect-driven selection of aluminum composite systems.
France
Paris commercial landlords specify full-height demountable systems to minimize tenant turnover downtime. ECHA oversight of SVHC content in track hardware finishes elevates vertically integrated producers. Île-de-France construction clusters absorb premium acoustic wall volumes for executive suite fit-outs.
Netherlands
Dutch office fit-outs maximize daylight penetration through glass-framed portable wall configurations. CE marking requirements for overhead track hardware create compliance barriers for non-EU fabricators. Randstad urban cores concentrate co-working reconfiguration demand for modular partition systems.
Portable Walls Market Competitive Landscape
Global majors compete with regional champions across track hardware engineering and panel fabrication capabilities. Market structure tilts toward consolidation at the premium acoustic tier while fragmenting across mid-range folding wall supply. Three archetypes dominate: vertically integrated track-and-panel producers, access-control-heritage integrators, and workplace-research-driven specifiers. Competitive moves center on backward integration into aluminum composite lamination and geographic expansion through third-party service network licensing.
Among European-heritage specialists, dormakaba Group and Hufcor, Inc. exemplify divergent strategic positions. dormakaba leverages access-control lineage to anchor integrated smart-wall systems in commercial fit-outs. Hufcor occupies the vertically integrated archetype through captive track manufacturing capabilities. HAWORTH INC. represents the research-driven specifier tier, translating workplace behavior studies into movable wall specifications for headquarters deployments. These three anchors illustrate how heritage capabilities—security integration, manufacturing control, and applied research—map to distinct competitive vectors in premium segment procurement.
| Leading Market Players |
|---|
| Accordial Ltd |
| dormakaba Group |
| ENVIRONAMICS |
| Faraone |
| Fellowes Brands |
| Franz Nusing GmbH & Co KG |
| HAWORTH INC. |
| HNI Corporation |
| Hufcor, Inc. |
| Others |
Value Network & Pricing Analysis
Certified overhead track installers in southern Germany command wage premiums that widen pricing spreads between premium acoustic systems and economy folding wall tiers. Labor-cost differentials between precision-certified technicians and generalist crews translate directly into three-tier pricing stratification across commercial specification channels.
Pricing Analysis
Input-cost pass-through from LME aluminum futures swings compresses margins on mid-range composite panel offerings, forcing non-integrated fabricators to absorb volatility or cede share. Pricing stratifies across premium, standard, and economy tiers based on STC certification grade and after-sales service bundling. Cost compression in standard-tier metal-framed systems is intensifying as Chinese aluminum extrusion capacity expands. Event planning rental networks exhibit highest price sensitivity; Fortune 500 headquarters procurement shows lowest.
Supply Chain Analysis
Reverse-logistics flows for track hardware refurbishment and panel remanufacturing are underdeveloped, creating stranded asset risk for lease-end demountable removals. Manufacturing concentrates in Germany, China, and the United States for track systems and composite lamination. Raw material dependencies include primary aluminum, gypsum board, and mass-loaded vinyl acoustic barriers. Single-source vulnerability clusters around Bavarian overhead track production. Distribution runs through manufacturer-direct specification for premium tiers and third-party rental networks for event applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion runway through lease-end restoration economics displacing drywall repair costs in Class A commercial properties.
For Market Incumbents: Extend captive aluminum composite lamination capabilities to capture embodied carbon compliance premiums under EU Green Deal mandates. Deepen installation technician certification programs to defend against third-party service network disintermediation in Chicago and Atlanta. Prioritize backward integration into recycled aluminum sourcing to secure low-carbon core material advantages. For New Entrants and Emerging Players: Launch via third-party service network licensing to bypass capital-intensive track manufacturing scale requirements. Target hospital outpatient renovation cycles in Texas and Florida, where demountable specialists remain underrepresented. Lead with rapid-deployment acoustic systems for co-working reconfiguration demand in Randstad urban cores. For Investors and Strategic Acquirers: Access control heritage integrators are the most active acquirer in this space, seeking smart-wall convergence capabilities. Five-to-ten year viability hinges on circular supply chain verification and EPD documentation infrastructure. Watch for aluminum price volatility inflection as signal for margin compression versus expansion windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Aluminum Sourcing | EU Green Deal EPD requirements favor suppliers with verified circular supply chains. |
| Smart-Wall Sensor Integration | dormakaba Group's access control heritage anchors premium positioning in European fit-outs. |
| Third-Party Service Network Licensing | Chicago and Atlanta multi-tenant turnover accelerates disintermediation of manufacturer-captive crews. |
| Healthcare Specification Protocol Adaptation | Texas and Florida hospital renovation cycles remain underserved by commercial-office-specialized incumbents. |
| Acoustic Performance Tier Expansion | STC-rated systems above 50 decibel isolation capture recording studio and broadcast facility demand. |
Research Methodology
Bottom-up commercial fit-out modeling reconciled against top-down track hardware production tracking forms the analytical core of this study. Primary interviews with facilities managers, architect specification leads, contractor procurement officers, and manufacturer product directors combined with secondary validation from SEC filings, customs trade records, and EPD certification databases. Triangulation across stakeholder inputs and supply-side data ensures segmentation integrity.
Input-output matrix framing connects aluminum extrusion capacity, gypsum board supply, and acoustic composite lamination throughput to installation project pipelines across the projection horizon. Segmentation dimensions modeled include product type, material certification tier, application channel, and end-user procurement authority. CAGRs derive from regression against commercial real estate vacancy cycles and embodied carbon regulatory phase-ins. Forecast inputs incorporate LME aluminum futures trajectory and CSRD disclosure adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under aluminum price spike conditions and installation technician labor shortage scenarios. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Construction
Indonesia Waterproofing Solutions Market
Specialty Construction
Welded Metal Bellows Market
Specialty Construction
India Anchors and Grouts Market
Specialty Construction
Asia-Pacific Waterproofing Solutions Market
Specialty Construction
Concrete and Cement Dissolver Market
Specialty Construction
Europe Anchors and Grouts Market
Specialty Construction
Construction Repaint Market
Specialty Construction
Shotcrete Accelerators Market
Specialty Construction
Temporary Fencing Panels Market
Specialty Construction
Asia-Pacific Anchors and Grouts Market
Specialty Construction
Roller Shutter Market
Specialty Construction
ASEAN Waterproofing Market
Specialty Construction
Indonesia Anchors and Grouts Market
Specialty Construction
Global Fencing Market
Specialty Construction
Fire Hydrants Market
Specialty Construction
South America Anchors and Grouts Market