
 Global Concrete Surface Retarders Market | 2026-2036
Global Concrete Surface Retarders Market Size, Share, and Industry Trends Forecast 2026-2036
Global Concrete Surface Retarders Market Intelligence
A wide capital-intensity divergence between multinational chemical conglomerates and regional admixture specialists is rotating competitive dynamics toward scale-dependent R&D investment. Sika AG leverages its global manufacturing footprint to sustain pricing power across liquid retarder formulations. W. R. Meadows, Inc. anchors its position through deep distribution relationships with North American paving contractors. Mapei S.p.A. competes by integrating surface retarders into broader decorative concrete systems.
Concrete surface retarders are chemical formulations—typically based on organic acids, sugars, or proprietary polymer blends—that delay the hydration of cement paste at the surface layer, enabling controlled removal to expose aggregate textures. These products function through topical application at specified depths ranging from one-sixteenth to three-quarters of an inch, serving primarily to create slip-resistant, aesthetically varied finishes on horizontal and vertical concrete elements. Liquid retarders dominate volume due to ease of spray application and uniform coverage, while paste retarders command margin premiums in architectural finishes requiring precise pattern masking. Powdered variants occupy niche positions in precast manufacturing where extended shelf stability and freight efficiency outweigh mixing complexity. Emulsion retarders represent the fastest-growing chemistry as water-based systems displace solvent-bearing alternatives under environmental compliance pressure.
EPA regulations on VOC emissions and REACH restrictions on hazardous substance classifications are reshaping formulation portfolios across the United States and European Union, compelling reformulation investments that smaller suppliers struggle to fund. China's GB standards and India's BIS certification requirements add parallel compliance layers for entrants targeting those construction markets. Stakeholders must monitor regulatory divergence between jurisdictions while calibrating product development pipelines toward low-carbon concrete compatibility and bio-based retarder chemistries.
Market Dynamics
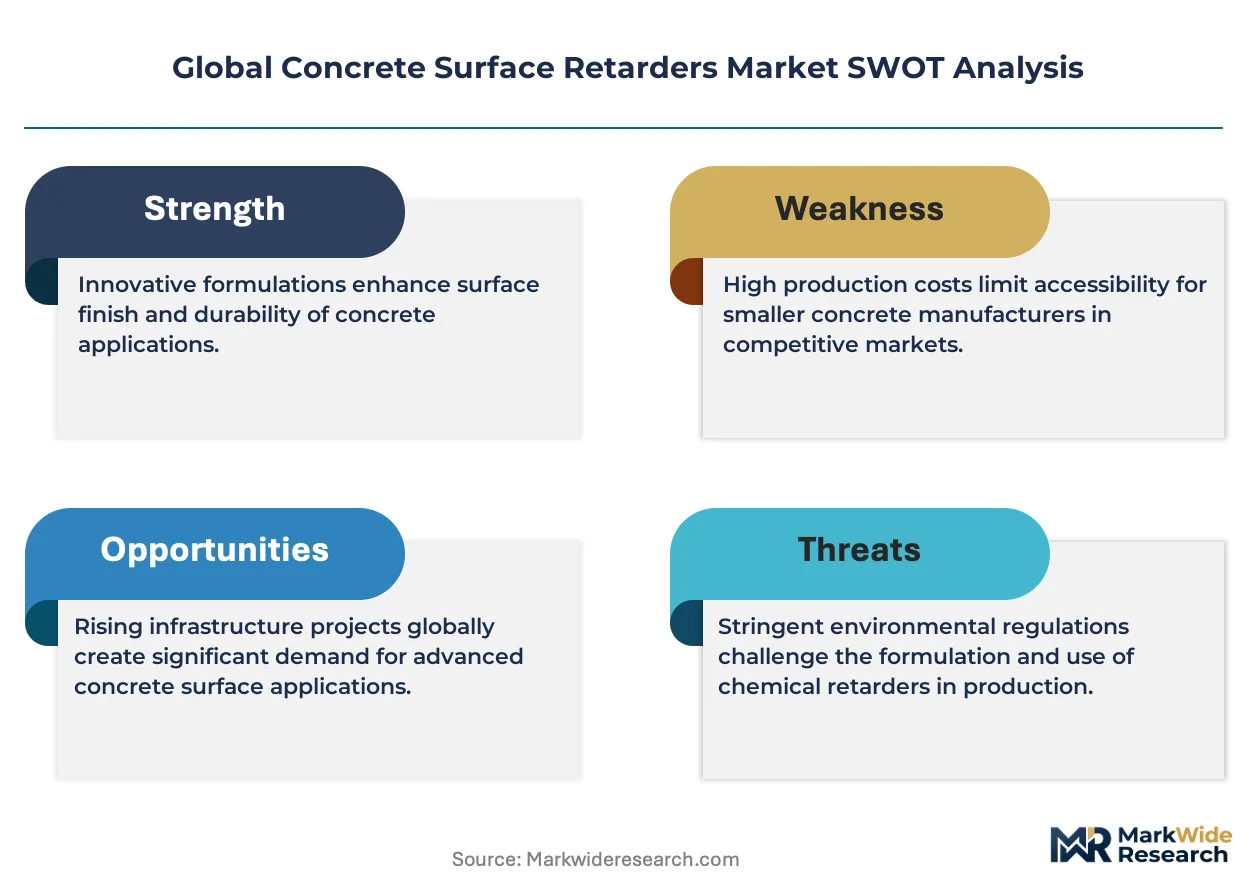
Water-based emulsion chemistry is rapidly displacing solvent-bearing formulations as REACH and EPA VOC restrictions harden compliance thresholds across construction chemical portfolios.
Growth Catalysts
- Exposed Aggregate Infrastructure Mandates:Highway and airport authorities in the United States, Germany, and Australia specify slip-resistant finishes for safety-critical surfaces, driving specification pull-through for spray-applied liquid retarders.
- REACH Phase-Down Schedules:ECHA restrictions on hazardous substance classifications are accelerating reformulation investment toward bio-based organic acid chemistries that maintain set-time control without aromatic solvents.
- Urban Renewal Density:Commercial construction clusters in Shanghai, Mumbai, and Sydney are generating concentrated demand for architectural-grade paste retarders that enable precise pattern masking on vertical concrete elements.
Market Restraints
- Petrochemical Feedstock Volatility:Proprietary polymer blend inputs fluctuate with crude-derived acrylic acid and sugar alcohol supply chains, compressing margin stability for mid-tier admixture suppliers.
- Technical Performance Ceilings:Water-based emulsions struggle to match solvent systems in sub-freezing application windows, limiting seasonal deployment latitude in northern climates.
- Substitution by Mechanical Methods:High-pressure water blasting and abrasive profiling equipment threaten retarder demand in cost-sensitive precast segments where surface texture tolerances permit mechanical alternatives.
Strategic Opportunities
- India BIS Certification Gap:Domestic admixture producers lack certified low-VOC retarder capacity, creating white space for compliant entrants ahead of anticipated GB-style standard harmonization.
- 3D-Printed Concrete Integration:Layered construction robotics require surface-set control at precise depths, opening specification channels for digitally dosed retarder systems in experimental building projects.
- EU Green Deal Procurement Rules:Public works tender scoring now weights embodied carbon and bio-based content, advantaging retarder portfolios with third-party EPD verification and renewable feedstock documentation.
Industry Challenges
- Formulation Chemistry Expertise Scarcity:Industrial chemists with cement hydration kinetics and polymer stabilization dual competency command premium compensation, constraining R&D team scaling for regional specialists.
- Multi-Jurisdiction Registration Burden:Parallel EPA, REACH, and BIS dossier preparation stretches compliance timelines to 18-24 months for novel chemistries, delaying commercialization and eroding first-mover advantage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Concrete Surface Retarders Market |
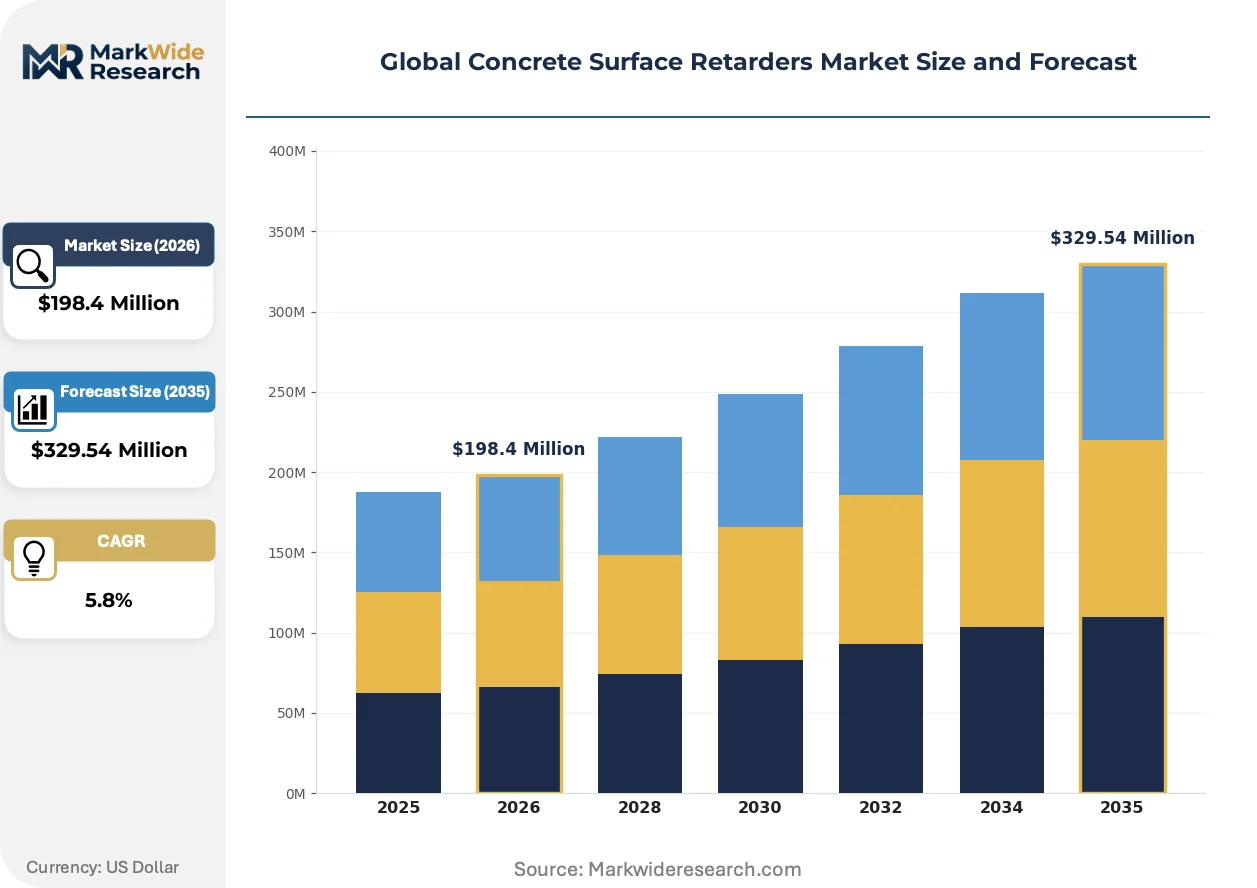
| Market Size in 2026 | $198.4 Million |
| Market Size in 2035 | $329.54 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Retarders, Paste Retarders, Powdered Retarders, Emulsion Retarders Application: Architectural Finishes, Pavement Texturing, Anti-Skid Surfaces, Decorative Panels, Formwork Removal End User: Construction Contractors, Concrete Producers, Infrastructure Developers, Precast Manufacturers, Specialty Contractors Distribution Channel: Direct Sales, Distributors & Dealers, Online Platforms, Retail Stores, Industrial Suppliers |
| Companies Covered | Sika AG, W. R. Meadows, Inc., Mapei S.p.A, Fosroc Inc., RussTech, Inc., BASF SE, GCP Applied Technologies, The Euclid Chemical Company, Cemex S.A.B. de C.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Concrete Surface Retarders Market Strategic Shifts & Innovations
Formulation science and specification workflows are converging around environmental compliance and digital application control, compressing traditional product lifecycles.
Water-based emulsion retarder chemistry is supplanting solvent-bearing alternatives in specification portfolios. Paving contractors in California and the Netherlands are adopting spray systems with integrated depth-control nozzles that reduce overspray waste. This transition is compressing demand for legacy aromatic formulations while expanding addressable market for low-emission construction chemicals in LEED-targeted projects.
REACH Annex XVII restrictions on volatile organic compounds are forcing reformulation of penetrating sealer-retarder combination products. Manufacturers must resubmit dossiers for extended safety data sheets, diverting technical resources from innovation pipelines. Architectural finish segments in France and Germany are responding fastest, with specification officers now requiring third-party VOC content certification before product approval.
Specification workflows are migrating to Building Information Modeling platforms where retarder selection integrates with surface finish simulation. Large general contractors in Australia and the United Arab Emirates are piloting digital twin validation of aggregate exposure patterns before pour scheduling. This behavioral shift compresses traditional sample-based approval cycles and rewards suppliers with parametric product data libraries compatible with Autodesk and Bentley platforms.
Global Concrete Surface Retarders Market Segmentation
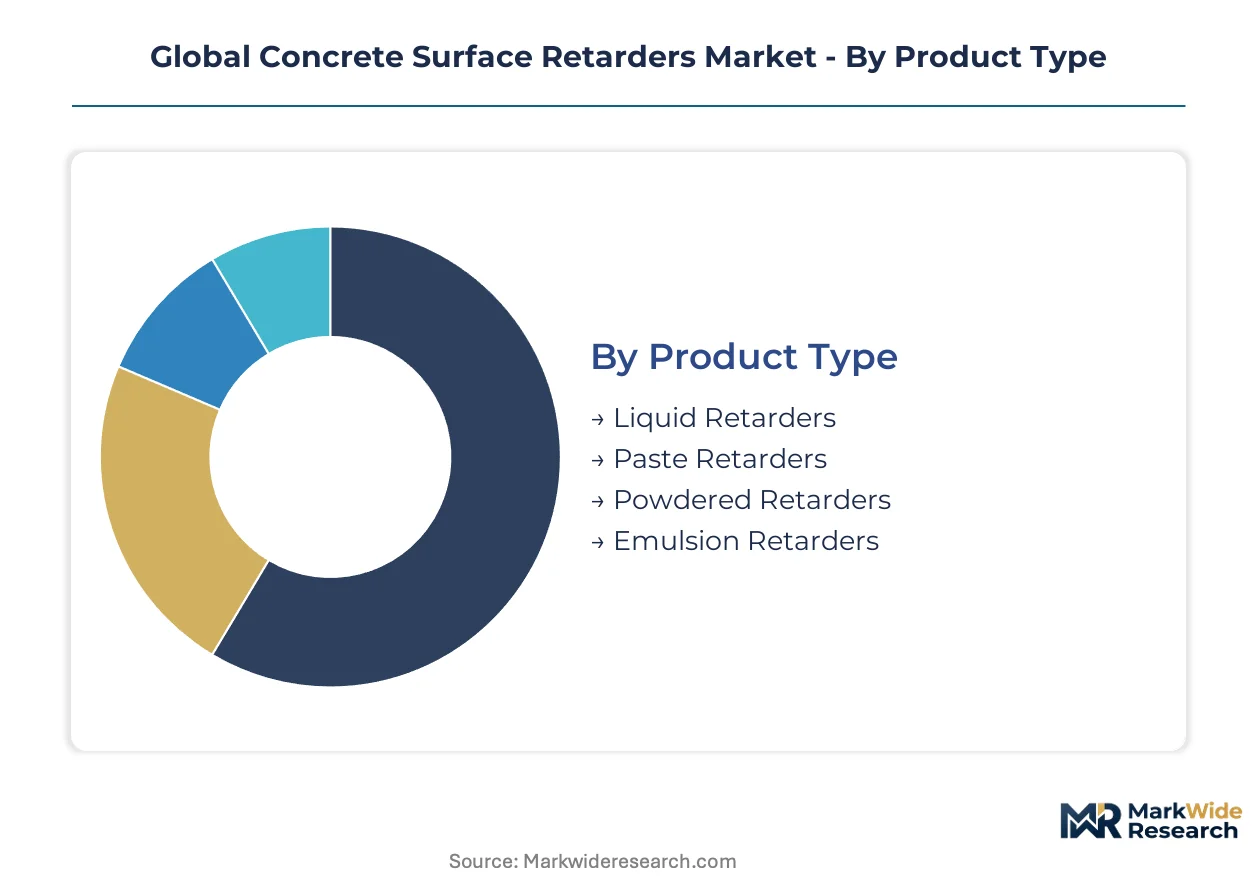
Segmentation in concrete surface retarders reveals how formulation chemistry, application method, and procurement channel intersect to create distinct margin pools. Specification requirements vary sharply between highway infrastructure and architectural concrete, fragmenting addressable markets by performance tier rather than geography alone.
Product Type:
Margin concentration sits with paste formulations where architectural precision commands premium pricing, while volume flows through liquid systems optimized for spray application efficiency.
- Liquid Retarders:Water-based or solvent-bearing solutions formulated for uniform spray application across horizontal surfaces. Demand clusters with United States highway contractors specifying slip-resistant finishes for interstate rehabilitation projects under Federal Highway Administration guidelines.
- Paste Retarders:Viscous formulations enabling stencil-based pattern masking on vertical concrete elements. German and Australian architectural firms specify these for commercial facades where aggregate exposure depth tolerances tighten to one-sixteenth inch.
- Powdered Retarders:Extended shelf stability drives adoption in Indian precast yards where freight efficiency outweighs on-site mixing labor.
- Emulsion Retarders:Water-based chemistry gaining specification share fastest as REACH and EPA VOC restrictions harden compliance thresholds across construction chemical portfolios.
Liquid retarders hold installed capacity. Emulsion retarders are rotating up the share rankings.
Application:
Application segmentation tracks where specification authority resides — infrastructure engineers versus architectural designers — determining formulation performance requirements and approval cycle length.
- Architectural Finishes:Decorative aggregate exposure on building facades and interior walls requiring precise depth control and color consistency. Sydney and Mumbai commercial construction clusters generate concentrated specification pull for paste-based systems.
- Pavement Texturing:Highway and airport surface treatments mandating slip resistance under wet conditions. United States state DOTs and German Autobahn maintenance authorities specify spray-applied liquid retarders for exposed aggregate concrete overlays.
- Anti-Skid Surfaces:Safety-critical installations on bridge decks and pedestrian walkways where friction coefficients must meet regulatory minimums.
- Decorative Panels:Precast cladding elements with varied aggregate blends for aesthetic differentiation in urban renewal districts.
- Formwork Removal:Controlled surface set delay enabling clean stripping without surface damage in repetitive casting operations.
Pavement texturing dominates volume throughput. Architectural finishes extract the steepest margin premiums.
End User:
End user structure reflects procurement sophistication divergence — multinational infrastructure developers with centralized specification authority versus fragmented specialty contractors bidding project-by-project.
- Construction Contractors:General and heavy civil contractors executing commercial and infrastructure pours. Australian and United Arab Emirates contractors are piloting Building Information Modeling-integrated retarder selection workflows.
- Concrete Producers:Ready-mix and precast operations incorporating retarders into batching protocols for consistent surface performance.
- Infrastructure Developers:Public and private entities financing highway, airport, and transit projects with multi-year specification lock-in.
- Precast Manufacturers:Factory-controlled environments where powdered retarder shelf stability and freight efficiency offset mixing complexity.
- Specialty Contractors:Niche finish specialists executing architectural exposed aggregate work with pattern masking expertise.
Infrastructure developers concentrate multi-year volume. Specialty contractors rotate up the value chain on technical service premiums.
Distribution Channel:
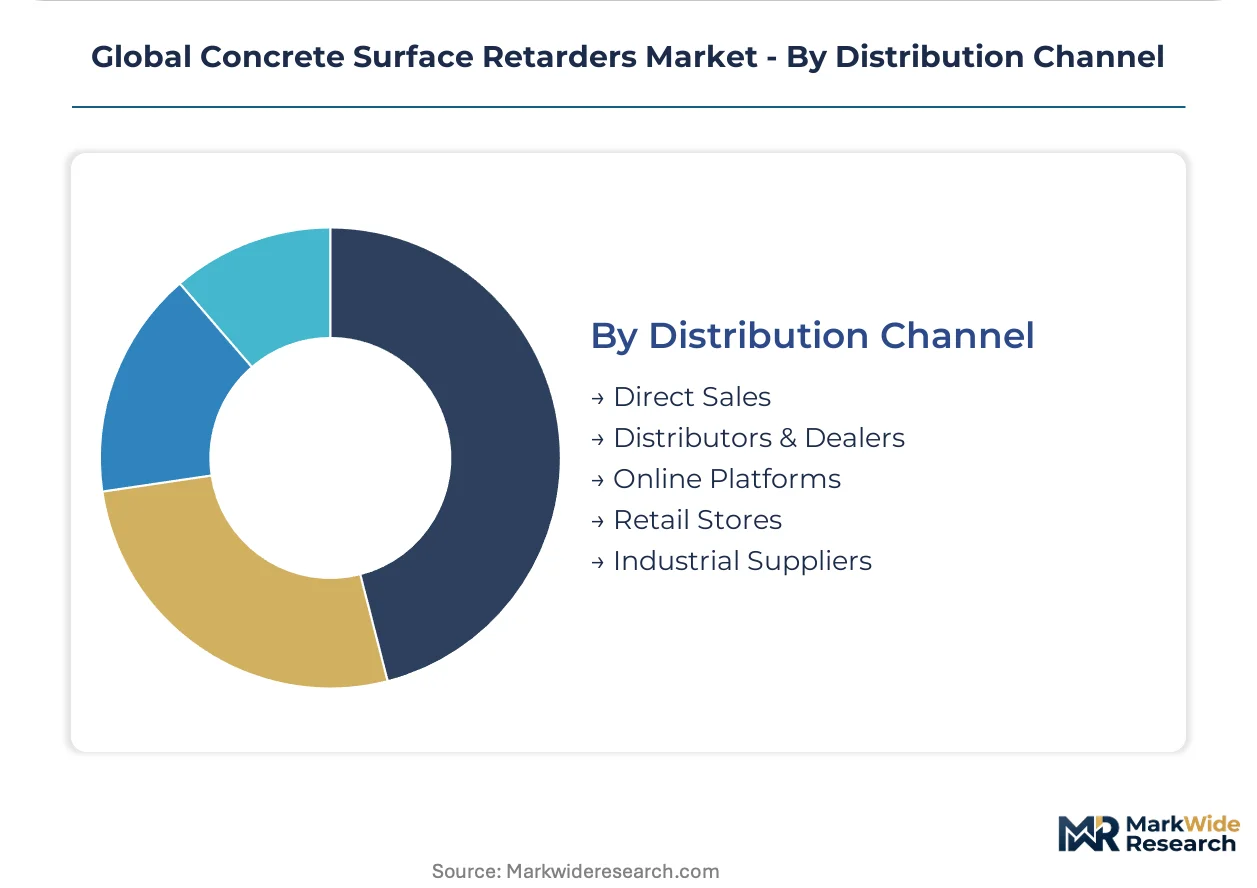
Channel segmentation tracks procurement decentralization — direct relationships with specification authorities versus transactional availability through construction supply intermediaries.
- Direct Sales:Manufacturer-to-contractor relationships for large infrastructure projects with technical service requirements. W. R. Meadows anchors North American positioning through deep paving contractor relationships.
- Distributors & Dealers:Regional construction chemical specialists stocking liquid formulations for contractor walk-up demand.
- Online Platforms:Emerging procurement channel for standardized liquid formulations in mid-market commercial construction.
- Retail Stores:Limited penetration for small-scale residential and light commercial repair applications.
- Industrial Suppliers:Integrated construction material distributors bundling retarders with formwork and reinforcement products.
Direct sales holds specification authority. Distributors are rotating up the transaction volume rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across construction markets. German and Australian buyers accept steep premiums for architectural-grade paste formulations, while Indian and Chinese contractors prioritize freight-efficient powdered variants that compress unit economics.
United States
Federal Highway Administration mandates for slip-resistant interstate surfaces drive specification pull for spray-applied liquid systems. EPA VOC restrictions under the Clean Air Act compel reformulation away from aromatic solvent carriers. California and Texas DOTs anchor volume concentration through multi-year pavement rehabilitation programs.
Germany
Autobahn maintenance authorities specify exposed aggregate overlays with tight depth tolerances for safety-critical surfaces. ECHA REACH Annex XVII restrictions on hazardous substance classifications accelerate bio-based organic acid chemistry adoption. The Rhine-Ruhr industrial corridor concentrates precast manufacturing demand for emulsion retarders with third-party EPD verification.
China
Shanghai and Beijing urban renewal clusters generate concentrated demand for architectural finishes on commercial facades. GB standards administered by SAMR impose parallel compliance layers for VOC content and cement compatibility testing. The Yangtze River Delta anchors production capacity for water-based emulsion chemistry serving domestic and export markets.
India
Mumbai and Delhi-NCR commercial construction drives specification interest in paste retarders for vertical decorative elements. BIS certification requirements for construction chemicals create entry barriers for uncertified low-VOC formulations. Domestic precast yards in Gujarat and Maharashtra favor powdered retarders where shelf stability offsets on-site mixing complexity.
Australia
Sydney and Melbourne infrastructure developers specify slip-resistant finishes for airport and highway projects under state procurement guidelines. TGA-aligned chemical safety assessments influence retarder registration timelines for imported formulations. Building Information Modeling integration is compressing traditional sample-based approval cycles among large general contractors.
Global Concrete Surface Retarders Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. The upper tier commands specification authority through multi-jurisdiction registration dossiers and centralized R&D investment. The specialist tier competes on regional distribution density and application technical service. Three archetypes dominate: multinational chemical conglomerates with construction chemical divisions, regional admixture specialists with deep contractor relationships, and integrated cement producers backward into chemical additives. Competitive moves concentrate on portfolio diversification toward low-emission formulations and geographic expansion through distributor partnerships in underpenetrated markets.
Within the multinational tier, Sika AG and BASF SE represent scale-driven archetypes with global manufacturing footprints and REACH-compliant formulation libraries. W. R. Meadows, Inc. exemplifies the regional specialist model through North American paving contractor relationships. Mapei S.p.A. occupies a position bridging both tiers, integrating surface retarders into broader decorative concrete systems with architectural specification pull. These three anchors demonstrate how competitive positioning rotates between scale-dependent R&D investment and distribution intimacy with application decision-makers.
| Leading Market Players |
|---|
| Sika AG |
| W. R. Meadows, Inc. |
| Mapei S.p.A |
| Fosroc Inc. |
| RussTech, Inc. |
| BASF SE |
| GCP Applied Technologies |
| The Euclid Chemical Company |
| Cemex S.A.B. de C.V. |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day lead times for REACH-compliant organic acid feedstocks concentrate pricing power with German and Swiss manufacturers holding multi-jurisdiction registration dossiers. This inventory band compresses margin flexibility for regional specialists competing on spray-applied liquid formulations.
Pricing Analysis
Technical service bundling drives lifetime value more than product margin alone. Three-tier pricing structure across architectural-grade paste, standard liquid emulsion, and economy powdered variants separates specification authority from transactional availability. Price differentiation rests on EPD certification depth and application technical support intensity. Cost compression in economy tiers intensifies because Indian precast yards prioritize freight efficiency over performance premiums. Infrastructure developers show least price sensitivity; residential repair contractors exhibit highest.
Supply Chain Analysis
Inventory cycles stretching 45-75 days for bio-based sugar alcohol feedstocks expose formulators to commodity volatility. Manufacturing concentrates in Germany, China, and the United States where polymer stabilization expertise clusters. Raw material dependencies include acrylic acid derivatives, fermented sugar alcohols, and proprietary surfactant packages. Single-source vulnerability runs through specialty organic acid suppliers serving REACH-compliant portfolios. Distribution runs through direct manufacturer-contractor relationships for large infrastructure projects and regional construction chemical distributors for walk-up demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial chemists commanding dual competency in cement hydration kinetics and polymer stabilization represent the scarcest capability layer, constraining R&D scaling for aspirants.
For Market Incumbents: Fortify formulation libraries through backward integration into bio-based organic acid feedstocks before ECHA phase-down schedules harden. Deepen technical service teams in Australian and Indian markets where Building Information Modeling integration compresses approval cycles. Prioritize multi-jurisdiction registration maintenance against emerging low-VOC admixture specialists. For New Entrants and Emerging Players: Application-layer gaps in digitally dosed retarder systems for 3D-printed concrete construction offer penetration vectors. Target Indian precast manufacturers ahead of anticipated BIS standard harmonization on low-VOC certification. Pursue distributor partnerships with construction chemical specialists in underpenetrated Middle Eastern urban renewal clusters. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because multi-jurisdiction registration barriers compound over time. Acquisition candidates include regional admixture specialists with deep contractor relationships and pending REACH dossiers. Watch for EPA enforcement acceleration on aromatic solvent formulations as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Secures supply continuity for ECHA-compliant organic acid chemistry ahead of phase-down deadlines. |
| EPD Certification Investment | Unlocks EU Green Deal procurement scoring weighting embodied carbon and renewable content documentation. |
| Building Information Modeling Data Library Development | Enables specification integration with Autodesk and Bentley platforms among Australian general contractors. |
| Long-Term Supply Agreement with Paving Contractors | Locks volume throughput under Federal Highway Administration interstate rehabilitation programs. |
| Joint Venture with Regional Distributor | Accelerates penetration into Indian precast yards where BIS certification gaps create white space. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with technical R&D directors at multinational chemical conglomerates, procurement leads at North American paving contractors, distribution channel partners in German construction chemical networks, and specification officers at Australian infrastructure developers. Secondary validation drew from ECHA REACH dossier databases, EPA Clean Air Act enforcement records, BIS certification registries, and customs trade data on organic acid feedstock flows. Bottom-up volume estimates triangulated against top-down construction spending allocation models.
Across the projection horizon, the analytical framework modeled demand through product type segmentation, application method differentiation, end-user procurement sophistication tiers, and regional regulatory cluster variations. CAGRs derived from regression analysis against historical construction chemical adoption curves and infrastructure spending commitment trajectories. Forecast inputs incorporated REACH phase-down schedule stringency assumptions and water-based emulsion displacement rates for solvent-bearing alternatives.
Forecasts assume regulatory continuity in EPA Clean Air Act enforcement and ECHA REACH Annex XVII restrictions; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Drywall Compound and Drywall Mud Market
Building & Construction Materials
Aerated Autoclaved Concrete (AAC) Market
Building & Construction Materials
East Africa Gypsum Plaster Market
Building & Construction Materials
Europe Green Buildings Market
Building & Construction Materials
Asia-Pacific Gypsum Board Market
Building & Construction Materials
Fiberglass Light Poles Market
Building & Construction Materials
Basalt Fiber Reinforced Polymer BFRP Market
Building & Construction Materials
Plastic Formwork Market
Building & Construction Materials
Steel Bolts and Nuts Market
Building & Construction Materials
Russia Cross Laminated Timber Market
Building & Construction Materials
Global Screw Piles Market
Building & Construction Materials
Europe Building Materials Market
Building & Construction Materials
Fire-Retardant Treated Wood Market
Building & Construction Materials
Japan Prefab Wood Building Market
Building & Construction Materials
Glue-Laminated Timber Market
Building & Construction Materials
Door Canopy Market