
 Europe Dry-Mix Mortar Market | 2026-2036
Europe Dry-Mix Mortar Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dry-Mix Mortar Market Foresight
Germany's capacity build-out in low-carbon dry-mix mortar production is rewriting the competitive map across Northern Europe. Saint-Gobain leverages its integrated plasterboard-to-mortar distribution network to dominate specification channels in French commercial construction. Sika AG sustains technology leadership through polymer-modified admixture systems that outperform traditional cementitious binders in freeze-thaw cycling. MAPEI S.p.A. anchors Southern European demand with specialized tile adhesive formulations engineered for Mediterranean climatic stressors.
Dry-mix mortar comprises pre-blended cementitious or gypsum-based powders, mineral aggregates, and functional additives that require only the addition of water at the point of application, with compressive strength ratings typically spanning 5 MPa to 60 MPa depending on formulation class. The material serves primarily as a factory-controlled alternative to site-mixed mortars, ensuring batch consistency and reducing construction waste in tiling, plastering, flooring, and masonry applications. Renders and polymer-modified adhesives command the strongest margin pools, as building envelope energy standards tighten across the continent. Traditional cementitious underlayment remains volume-heavy but faces displacement from air-entrained and water-resistant systems in infrastructure specifications exposed to cyclic moisture loading.
CE marking under the Construction Products Regulation, REACH chemical compliance overseen by ECHA, and the EU Green Deal's embodied carbon benchmarks collectively constrain formulation choices while creating premium positioning for low-clinker products. EMA and national building institutes in France and Germany are aligning test protocols to favor mortars with declared environmental product data. Stakeholders must monitor how the F-Gas Regulation's downstream effects on insulating material supply chains reshape render system economics and specification behavior across European procurement offices.
Market Dynamics
The EU Green Deal's embodied carbon benchmarks are compressing formulation choices across the value chain, forcing binder producers to requalify products under tightened CE marking protocols while energy retrofit mandates in Germany and France absorb premium thermal insulation renders.
Growth Catalysts
- Energy-efficient retrofit mandates:Germany's Building Energy Act specifications are pulling polymer-modified thermal insulation renders into residential renovation at accelerated specification rates.
- REACH chemical compliance:ECHA's tightening substance restrictions on traditional plasticizers are redirecting R&D spend toward bio-based admixture systems that maintain freeze-thaw performance.
- Recycled aggregate integration:Construction and demolition waste recovery infrastructure in the Netherlands and Belgium is enabling circular binder formulations that satisfy national environmental product declarations.
Market Restraints
- Clinker cost volatility:Portland cement input prices fluctuate with EU ETS carbon allowance auctions, compressing margin pools for standard-grade masonry mortars.
- Admixture supply concentration:Specialty polymer modifiers for water-resistant systems concentrate among German and Swiss chemical suppliers, creating bottleneck risk during capacity constraints.
- Site-mix substitution persistence:Cost-sensitive infrastructure contractors in Southern and Eastern Europe continue specifying traditional cement-sand field mixing for non-critical applications.
Strategic Opportunities
- Polish residential construction acceleration:EU cohesion fund absorption and housing deficit dynamics are expanding addressable volume for thin-bed tile adhesives and self-leveling underlayments.
- CSRD-aligned environmental product declarations:The Corporate Sustainability Reporting Directive's scope expansion is creating premium positioning for mortars with verified lifecycle carbon data across French commercial specifications.
- Digital specification platforms:BIM-integrated material selection tools are shortening the path from manufacturer technical data to architect and contractor procurement decisions.
Industry Challenges
- Formulation chemist scarcity:The specialized expertise required for low-clinker binder engineering sits concentrated among retiring technical workforces in Germany and Italy.
- CE marking retest timelines:Construction Products Regulation harmonized standard updates are forcing 12-18 month requalification cycles for modified product lines.
- Legacy distributor integration:Traditional merchant networks lack technical capacity to support specification-grade polymer-modified system sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dry-Mix Mortar Market |
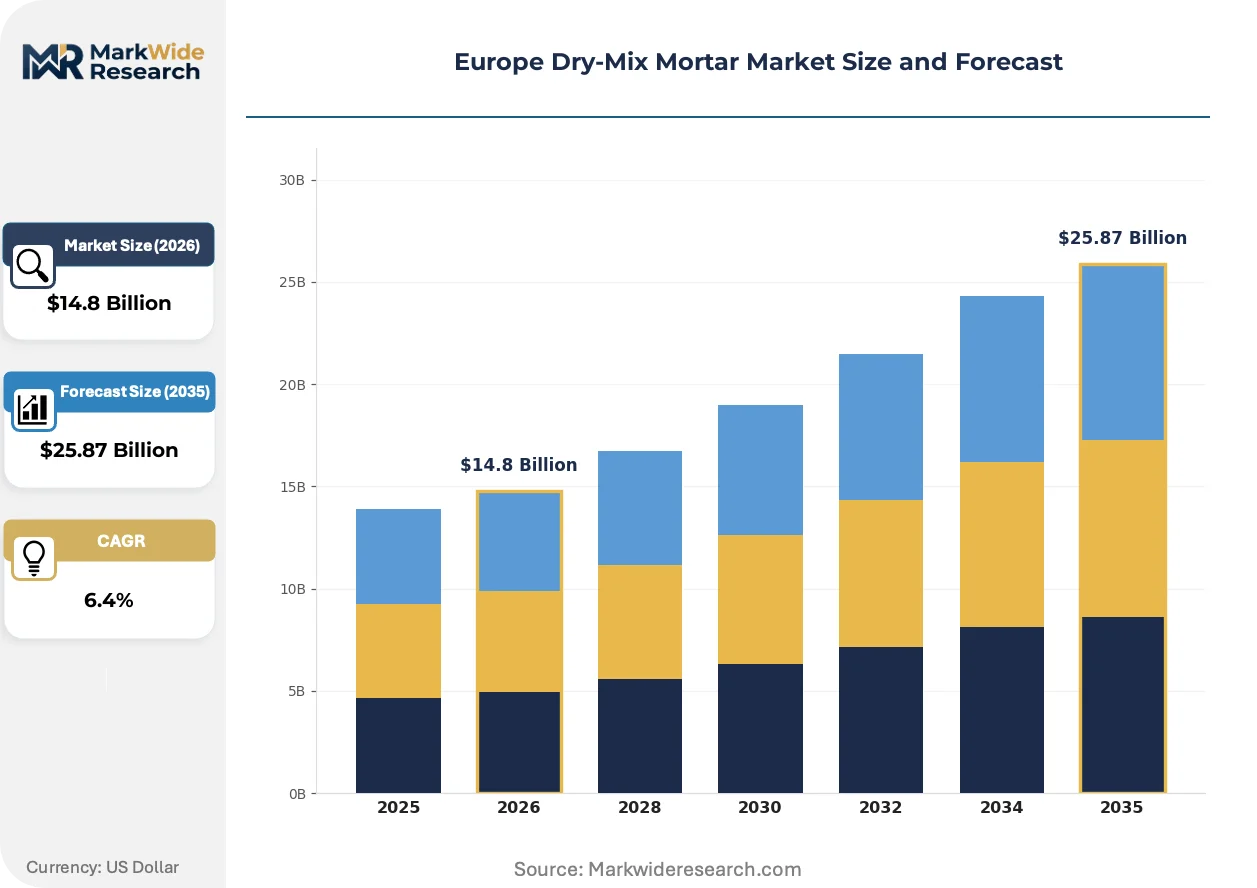
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesives, Renders, Grouts, Underlayment Application: Residential Construction, Commercial Construction, Repair & Renovation, Infrastructure Technology: Air-entrained, Water-resistant, Polymer-modified, Traditional End User: Contractors, Builders, DIY Enthusiasts, Government |
| Companies Covered | Saint-Gobain, Sika AG, MAPEI S.p.A., Holcim, Ardex Group, MBCC Group, Bostik SA, Grupo Puma, Bisley International, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dry-Mix Mortar Market Shifts & Advancements
Formulation chemistry, compliance architecture, and procurement digitization are converging to restructure how dry-mix mortar manufacturers capture value across specification channels.
Alkali-activated binder systems utilizing industrial byproduct precursors are achieving compressive performance parity with Portland cement in non-structural applications. Infrastructure contractors in the Nordic countries are piloting these formulations for drainage channel linings and utility bedding. The technology is rendering obsolete conventional clinker-intensive binders in specifications where carbon accounting drives award criteria.
The F-Gas Regulation's phase-down schedules for hydrofluorocarbon blowing agents are disrupting thermal insulation render supply chains. Manufacturers must reformulate spray-applied insulation systems using water-based or hydrocarbon alternatives while maintaining lambda values. German building physics institutes are revising certification protocols fastest, compressing time-to-market for compliant systems in that specification environment.
Specification behavior among French and German general contractors is compressing traditional merchant distribution layers. Large residential developers are contracting directly with mortar producers for packaged system supply including technical support and applicator training. This disintermediation is most visible in Paris and Munich metropolitan construction clusters where project scale justifies dedicated logistics arrangements.
Europe Dry-Mix Mortar Market Segmentation
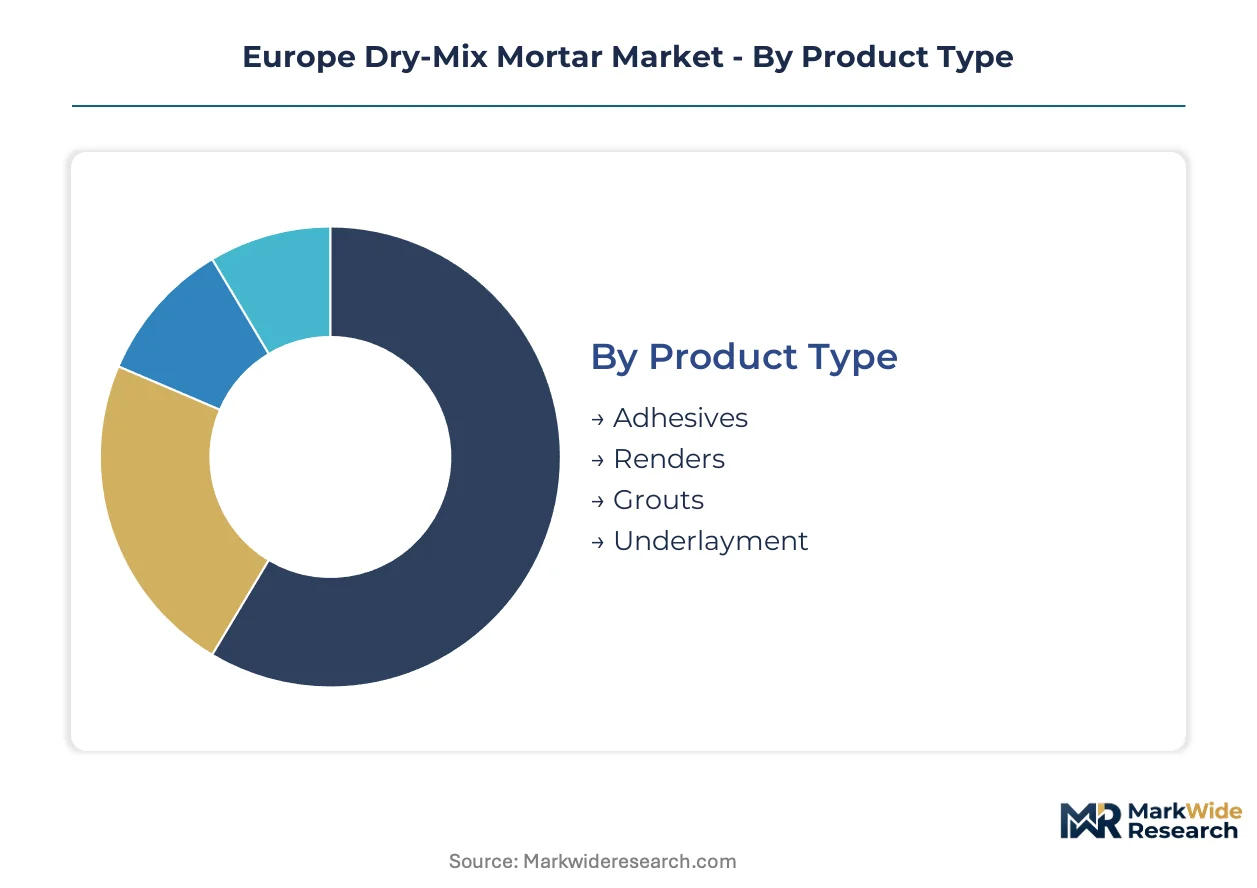
Dry-mix mortar manufacturers configure product portfolios across four intersecting dimensions. Specification-grade polymer systems command premium positioning in German and French energy retrofit channels, while standard masonry grades compete on logistics efficiency in price-sensitive Southern European markets.
Product Type:
Cost tier separation defines this dimension, with formulation complexity and performance certification driving margin stratification across the European specification environment.
- Renders:Factory-blended cementitious or gypsum-based coatings incorporate lightweight aggregates and hydrophobic additives for building envelope applications. German Building Energy Act compliance is pulling thermal insulation renders into residential renovation at volume, with declared thermal conductivity values now mandatory for public procurement.
- Adhesives:Polymer-modified thin-bed systems for ceramic and natural stone tiling utilize redispersible polymer powders to enhance bond strength and deformability. French commercial construction specifications favor these formulations for large-format tile installation in high-traffic retail environments.
- Grouts:Cementitious or epoxy-based joint fillers with controlled shrinkage and color stability properties serve tiling completion work across residential and commercial finish trades.
- Underlayment:Self-leveling compounds and screed systems provide substrate preparation for flooring installation, with fast-setting variants gaining traction in Polish residential construction acceleration.
Renders command the established base. The steepest expansion runs through polymer-modified adhesives.
Application:
Volume concentration across end-use contexts reflects regulatory pressure points and construction cycle positioning within the European built environment.
- Repair & Renovation:Energy retrofit mandates in Germany and France are absorbing premium thermal insulation renders and thin-bed adhesives for building envelope upgrades. CE marking retest timelines under Construction Products Regulation updates are compressing product requalification cycles for manufacturers serving this channel.
- Residential Construction:New-build housing in Poland and the Netherlands drives specification of self-leveling underlayments and standard masonry mortars, with EU cohesion fund absorption expanding addressable volume.
- Commercial Construction:Large-format retail and office developments in Paris and Munich metropolitan clusters favor specification-grade polymer-modified systems with direct manufacturer contracting.
- Infrastructure:Utility bedding and drainage applications in Nordic countries are piloting alkali-activated binder formulations as carbon accounting drives award criteria.
Repair & Renovation anchors current volume. Residential Construction in Poland and surrounding markets is climbing the fastest.
Technology:
Formulation chemistry maturity shapes competitive positioning, with advanced admixture systems capturing specification premiums against commodity-grade alternatives.
- Polymer-modified:Redispersible polymer powders and liquid latex admixtures enhance flexibility, adhesion, and freeze-thaw resistance. REACH chemical compliance overseen by ECHA is redirecting R&D spend toward bio-based admixture systems that maintain performance.
- Water-resistant:Hydrophobic additive packages and dense pore structures protect against cyclic moisture loading in facade and wet-area applications. German building physics institutes are revising certification protocols fastest for these systems.
- Air-entrained:Controlled microbubble incorporation improves workability and freeze-thaw durability in exterior masonry and rendering applications across Northern European climates.
- Traditional:Standard cement-sand formulations without functional additives face displacement in specification channels but persist in cost-sensitive Southern and Eastern European infrastructure contracting.
Traditional technology retains volume leadership. Polymer-modified systems are gaining share fastest in premium specification channels.
End User:
Customer type determines channel configuration, with technical support requirements and procurement scale dictating manufacturer engagement models.
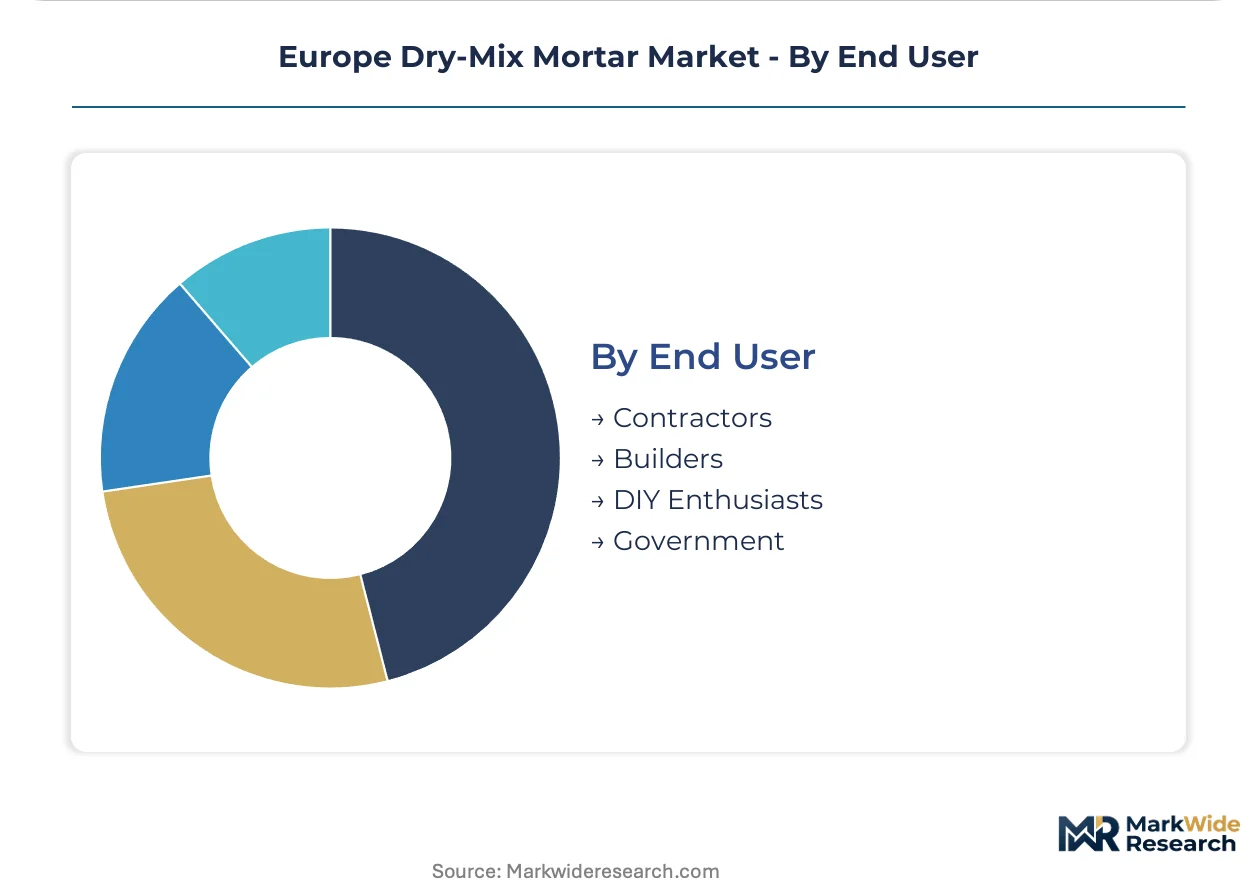
- Contractors:Professional applicators specify factory-controlled dry-mix systems for batch consistency and waste reduction, particularly in German residential renovation where energy-efficient retrofit mandates drive technical complexity.
- Builders:Large residential developers in Paris and Munich metropolitan clusters are contracting directly with mortar producers for packaged system supply including applicator training, compressing traditional merchant distribution layers.
- DIY Enthusiasts:Small-format retail packaging serves home improvement channels, with limited technical support requirements and price-sensitive positioning.
- Government:Public procurement across EU member states increasingly mandates declared environmental product data and low-carbon binder formulations under EU Green Deal embodied carbon benchmarks.
Contractors represent the established demand base. Government procurement with sustainability mandates is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capacity for low-carbon dry-mix mortar production concentrates in Germany and France, where integrated building material groups control specification channels through captive distribution networks. Northern European markets absorb premium polymer-modified systems at higher margins than Southern European price-sensitive segments.
Germany
Residential renovation absorbs thermal insulation renders and thin-bed adhesives under Building Energy Act retrofit mandates. CE marking protocols under the Construction Products Regulation compress requalification timelines for modified formulations. The Munich metropolitan cluster hosts direct manufacturer contracting with large developers, bypassing traditional merchant layers.
France
Commercial construction in Paris favors specification-grade polymer-modified systems for large-format retail installations. The EU Green Deal's embodied carbon benchmarks mandate declared environmental product data for public procurement. Saint-Gobain leverages integrated plasterboard-to-mortar distribution networks across French specification channels.
Poland
EU cohesion fund absorption and housing deficit dynamics expand volume for self-leveling underlayments and thin-bed tile adhesives. National building institutes align test protocols with German standards to accelerate product requalification. Warsaw and Kraków construction clusters drive residential construction acceleration across new-build housing.
Netherlands
Construction and demolition waste recovery infrastructure enables circular binder formulations with recycled aggregate content. ECHA's REACH chemical compliance redirects R&D toward bio-based admixture systems. The Randstad urban corridor concentrates demand for fast-setting underlayments in dense residential development.
Italy
MAPEI S.p.A. anchors Southern European demand with specialized tile adhesive formulations engineered for Mediterranean climatic stressors. National environmental product declarations gain traction under CSRD-aligned reporting requirements. Northern industrial districts around Milan maintain formulation chemistry expertise for low-clinker binder engineering.
Europe Dry-Mix Mortar Market Competitive Landscape
Integrated building material conglomerates and specialty chemical admixture suppliers split the market across specification-grade and commodity-grade tiers. Three strategic archetypes dominate: vertically integrated construction material groups controlling distribution channels, polymer technology specialists commanding premium admixture margins, and regional formulation houses serving price-sensitive local markets. Competitive moves concentrate on backward integration into raw material supply and direct contracting with large developers to compress distributor layers.
Among integrated construction material groups, Saint-Gobain and Holcim exemplify the channel-control archetype through captive distribution networks spanning plasterboard, cement, and mortar categories. Sika AG occupies a position within the polymer technology specialist tier, anchoring premium positioning through admixture chemistry capabilities. These three entities represent the dominant competitive anchors across Northern European specification channels.
| Leading Market Players |
|---|
| Saint-Gobain |
| Sika AG |
| MAPEI S.p.A. |
| Holcim |
| Ardex Group |
| MBCC Group |
| Bostik SA |
| Grupo Puma |
| Bisley International |
| Others |
Supply & Pricing Matrix
Rhine-Alpine corridor freight rates compress margin pools for standard-grade masonry mortars while amplifying price premiums for polymer-modified systems that justify dedicated logistics arrangements. Supply concentration in German chemical clusters and Belgian cement production shapes tiered pricing power across Northern European specification channels.
Pricing Analysis
The EU Green Deal's embodied carbon benchmarks dictate the pricing tier structure across European dry-mix mortar markets. Three-tier pricing separates premium polymer-modified systems with verified environmental product declarations from standard masonry grades and economy site-mix alternatives. Price differentiation hinges on CE marking certification level and volume scale, with large developers extracting contractual discounts through direct manufacturer engagement. Cost compression in commodity tiers intensifies because EU ETS carbon allowance auctions feed into Portland cement input volatility. Infrastructure contractors in Southern and Eastern Europe exhibit the highest price sensitivity, while German residential renovators prioritize thermal performance specifications over unit economics.
Supply Chain Analysis
Portland cement clinker, redispersible polymer powders, and lightweight aggregates anchor upstream feedstock dependencies for European dry-mix mortar production. Supply concentrates in Germany, Belgium, and Italy, with specialty polymer modifiers drawing from Swiss and German chemical manufacturing clusters. Single-source vulnerability runs through concentrated admixture suppliers for water-resistant and freeze-thaw resistant systems. Distribution runs through integrated building material merchants in France and Germany, though direct manufacturer contracting with large developers is compressing traditional layers in Paris and Munich metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BIM-integrated specification platforms are creating platform-economics inflection across European dry-mix mortar procurement, with interoperability between manufacturer technical data and architect design tools reordering channel control.
For Market Incumbents: Insulate specification-grade positioning by accelerating backward integration into recycled aggregate recovery infrastructure in the Netherlands and Belgium. Capture channel control through captive logistics networks that support just-in-time delivery for large developer direct contracts. Alkali-activated binder R&D investment defends against clinker cost volatility and carbon accounting-driven award criteria. For New Entrants and Emerging Players: Establish a beachhead in Polish residential construction acceleration, where EU cohesion fund absorption and housing deficit dynamics outpace incumbent capacity build-out. Target thin-bed tile adhesives and fast-setting underlayments in Warsaw and Kraków construction clusters. Partner with national building institutes for accelerated CE marking alignment with German test protocols. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated construction material conglomerates divesting non-core regional mortar operations. Long-term viability centers on formulation chemistry capabilities for low-clinker binders and circular material integration. Watch for F-Gas Regulation compliance timelines as inflection indicators for thermal insulation render system economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Aggregates | Circular binder formulations satisfy Netherlands and Belgium environmental product declarations under EU Green Deal benchmarks. |
| Direct Manufacturer Contracting | Bypasses traditional merchant layers in Paris and Munich metropolitan clusters where project scale justifies dedicated logistics. |
| BIM-Integrated Specification Platforms | Shortens path from technical data to architect procurement decisions across German and French commercial construction. |
| Alkali-Activated Binder Scale-Up | Achieves compressive performance parity with Portland cement in Nordic infrastructure specifications where carbon accounting drives awards. |
| CE Marking Retest Acceleration | Compresses 12-18 month requalification cycles for modified formulations under Construction Products Regulation updates. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the European dry-mix mortar value chain. Primary interviews engaged formulation chemists at German and Italian technical centers, procurement leads at French commercial developers, distribution channel partners in Belgium and the Netherlands, and plant managers at integrated building material facilities. Secondary validation drew from ECHA REACH substance restriction filings, CE marking harmonized standard updates under the Construction Products Regulation, EU ETS carbon allowance auction data, and national environmental product declaration registries. Bottom-up volume modeling across product type, application, technology, and end-user segments was triangulated against top-down construction output forecasts.
Calibration against historical capacity utilization rates and specification-grade penetration patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product complexity tier, end-use regulatory pressure, formulation chemistry maturity, and procurement channel configuration. CAGRs were derived from elasticity-adjusted demand curves incorporating energy retrofit mandate absorption rates and cohesion fund disbursement trajectories. Clinker substitution rates and recycled aggregate integration thresholds served as industry-specific forecast inputs.
Stress conditions across EU ETS price bands, REACH substance restriction timelines, and F-Gas Regulation phase-down schedules were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding Building Energy Act enforcement intensity and national building institute protocol alignment. Cross-checking against Eurostat construction output indices and national cement association shipment data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Concrete Market
Building Materials
Fly Ash Bricks Market
Building Materials
US Cement Tiles Market
Building Materials
United Kingdom Architectural Coatings Market
Building Materials
Building and Construction Sheets Market
Building Materials
Asia-Pacific Aluminum Door and Window Market
Building Materials
Polymer Concrete Market
Building Materials
Asia-Pacific Shotcrete Market
Building Materials
Polymer-Modified Cementitious Mortar Market
Building Materials
Shotcrete Market
Building Materials
Door Frame Metal Market
Building Materials
Glass Facade Market
Building Materials
US Facade Market
Building Materials
Ireland Cement Market
Building Materials
India Cement Market
Building Materials
Thin Brick Market