
 Construction Repaint Market | 2026-2036
Construction Repaint Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Repaint Market Analysis
Modular tinting systems bundled with color-matching software is realigning how professional contractors specify and procure coatings. The Sherwin-Williams Company leverages its captive retail network to control specification touchpoints across North America. Akzo Nobel anchors European demand through specialized marine and protective crossover technologies. Asian Paints dominates India's fragmented contractor base with localized shade libraries and same-day tinting capacity.
Construction repaint comprises the reapplication of architectural coatings to existing building substrates, including acrylic latex, alkyd, and epoxy formulations applied by brush, roller, or spray to restore protective and aesthetic functions. These coatings must achieve specified dry-film thickness, adhesion ratings per ASTM D3359, and VOC compliance thresholds to perform on weathered concrete, wood, or previously coated metal surfaces. Interior paint captures the largest volume pool due to shorter refresh cycles in leased commercial spaces, while specialty coatings represent the fastest-expanding margin segment as building owners specify antimicrobial and self-cleaning functionalities for healthcare and transit environments. The renovation application channel absorbs the majority of value as deferred maintenance backlogs from institutional owners convert into contracted repaint programs.
EPA VOC regulations under 40 CFR Part 59 constrain solvent-borne formulation options in the US, while REACH and the EU Green Deal drive substitution toward bio-based resin systems across European member states. India's BIS certification for architectural coatings adds compliance costs for imported products and reinforces domestic manufacturing incentives under the PLI scheme. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned R&D commitments.
Market Dynamics
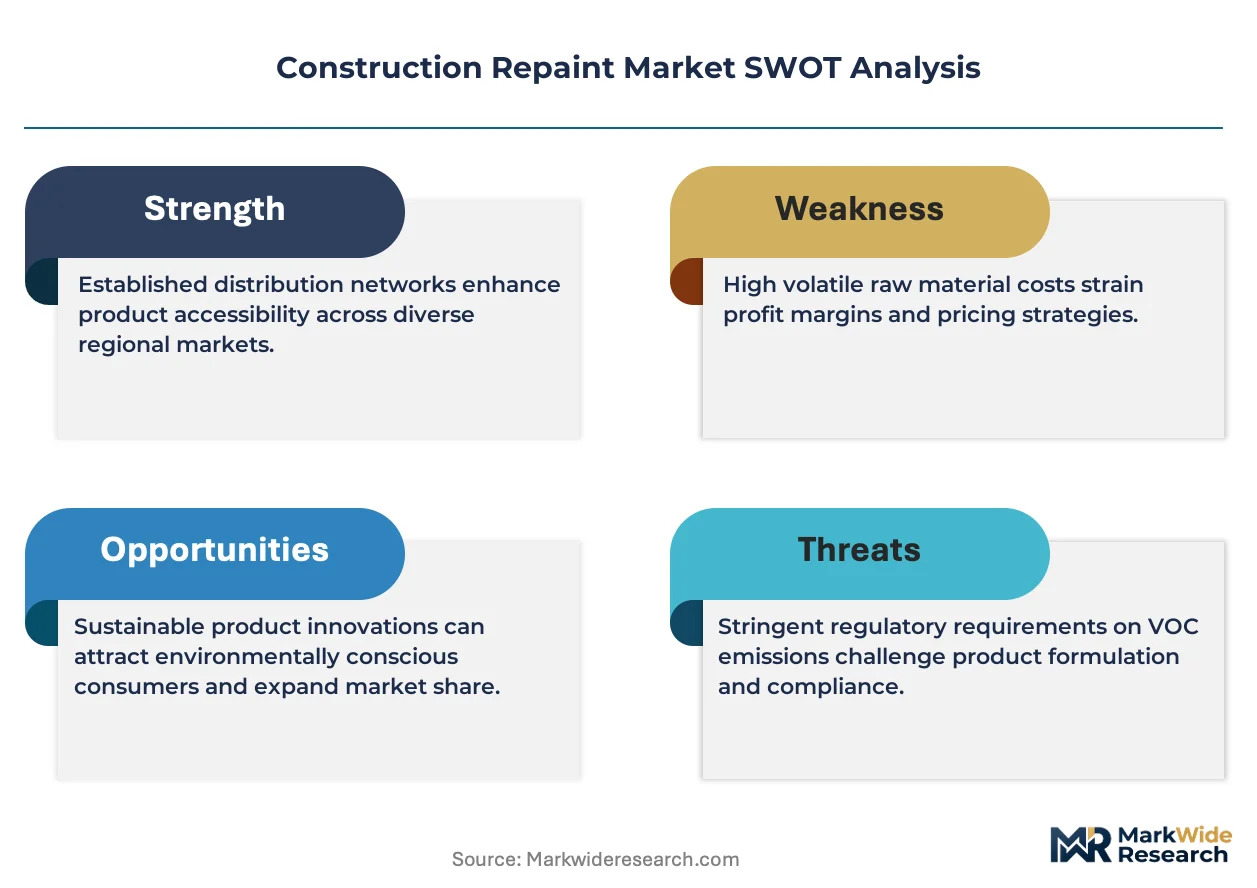
Waterborne formulation mandates across multiple jurisdictions are compressing solvent-borne capacity and forcing capital reallocation toward low-VOC resin systems and tinting infrastructure.
Growth Catalysts
- EPA 40 CFR Part 59 enforcement:Stricter VOC ceilings in architectural coatings accelerate waterborne substitution in US commercial repaint programs.
- India's urban building stock renewal:Aging government housing and transit infrastructure in Mumbai and Delhi generate sustained recoating demand from institutional owners.
- Modular tinting systems:Color-matching software paired with on-site dispensing equipment compresses contractor procurement cycles and reduces inventory carrying costs.
Market Restraints
- Titanium dioxide price volatility:Pigment cost swings compress margin predictability for mid-tier coating manufacturers serving price-sensitive renovation channels.
- Supply concentration in epoxy resin:Asian petrochemical complexes control upstream BPA and epichlorohydrin supply, exposing European formulators to freight and tariff exposure.
- REACH registration burdens:ECHA substance evaluation timelines extend new product commercialization cycles by 18-24 months for bio-based resin entrants.
Strategic Opportunities
- Antimicrobial coating specification in healthcare:Hospital renovation programs in Germany and France are mandating silver-ion or quaternary ammonium functionality for infection control.
- Self-cleaning photocatalytic formulations:TiO₂-doped exterior coatings for transit infrastructure offer maintenance cost reduction in high-pollution urban corridors.
- India PLI scheme for specialty chemicals:Domestic manufacturing incentives reduce import dependency for acrylic emulsion and enable localized supply to contractor networks.
Industry Challenges
- Skilled applicator shortage:Spray certification for high-build epoxy and polyurethane systems limits contractor capacity in commercial high-rise repaint segments.
- ASTM D3359 adhesion testing complexity:Substrate variability on weathered concrete and previously coated metal surfaces elevates warranty claim rates and specification disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Repaint Market |
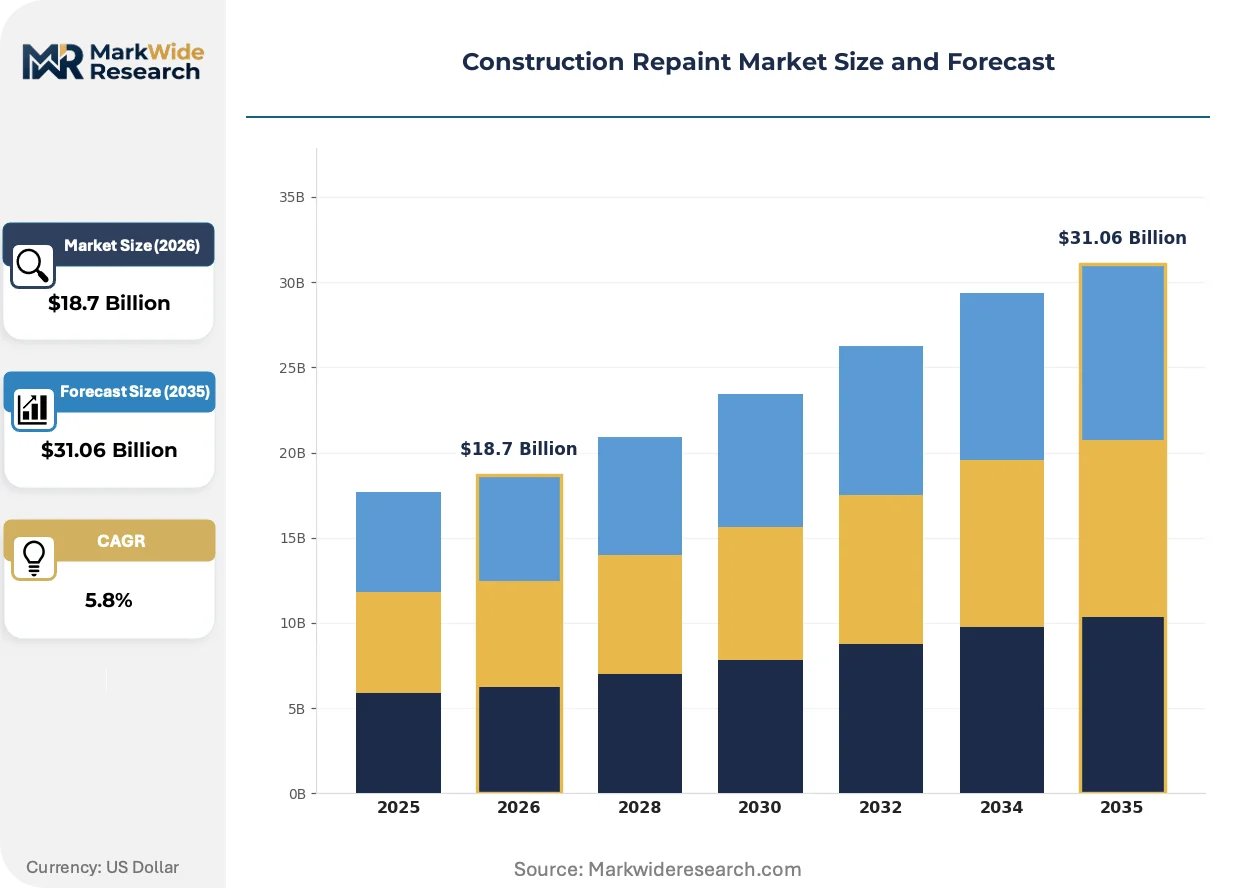
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interior Paint, Exterior Paint, Specialty Coatings, Primers End User: Commercial Buildings, Residential Properties, Infrastructure Projects, Industrial Facilities Application: New Construction, Renovation, Maintenance, Decorative Distribution Channel: Online Retail, Direct Sales, Wholesalers, Home Improvement Stores |
| Companies Covered | The Sherwin-Williams Company, PPG Industries, Akzo Nobel, Nippon Paint Holdings, RPM International, Axalta Coating Systems, Asian Paints, Jotun, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Repaint Market Emerging Trajectories
Digital color specification tools and on-site production systems are collapsing traditional distributor-warehouse networks and rewiring how professional painters access coating products.
Cloud-connected spectrophotometers paired with mobile tinting units are decentralizing color-matching authority from central laboratories to job sites. Large commercial contractors in Texas and California deploy these systems to eliminate shade-mismatch rework and compress project timelines. The technology is decentralizing specification control away from manufacturer technical service teams toward contractor operations managers.
REACH restriction proposals for microplastic additives in decorative coatings are forcing reformulation of textured exterior products across EU member states. Paint manufacturers must substitute synthetic thickeners with cellulose or associative rheology modifiers, elevating raw material costs by mid-single digits. Marine and protective coating specialists with existing bio-based resin expertise are cross-applying these formulations to architectural segments.
Building operators now bundle coating procurement with extended maintenance warranties, shifting risk from asset owners to applicator-contractor consortia. Facility management firms in leased commercial spaces compress refresh cycles from seven years to four, prioritizing rapid-dry low-odor systems that minimize tenant displacement. This pattern concentrates in US Class B office renovation and UK retail-to-residential conversion projects.
Construction Repaint Market Segmentation
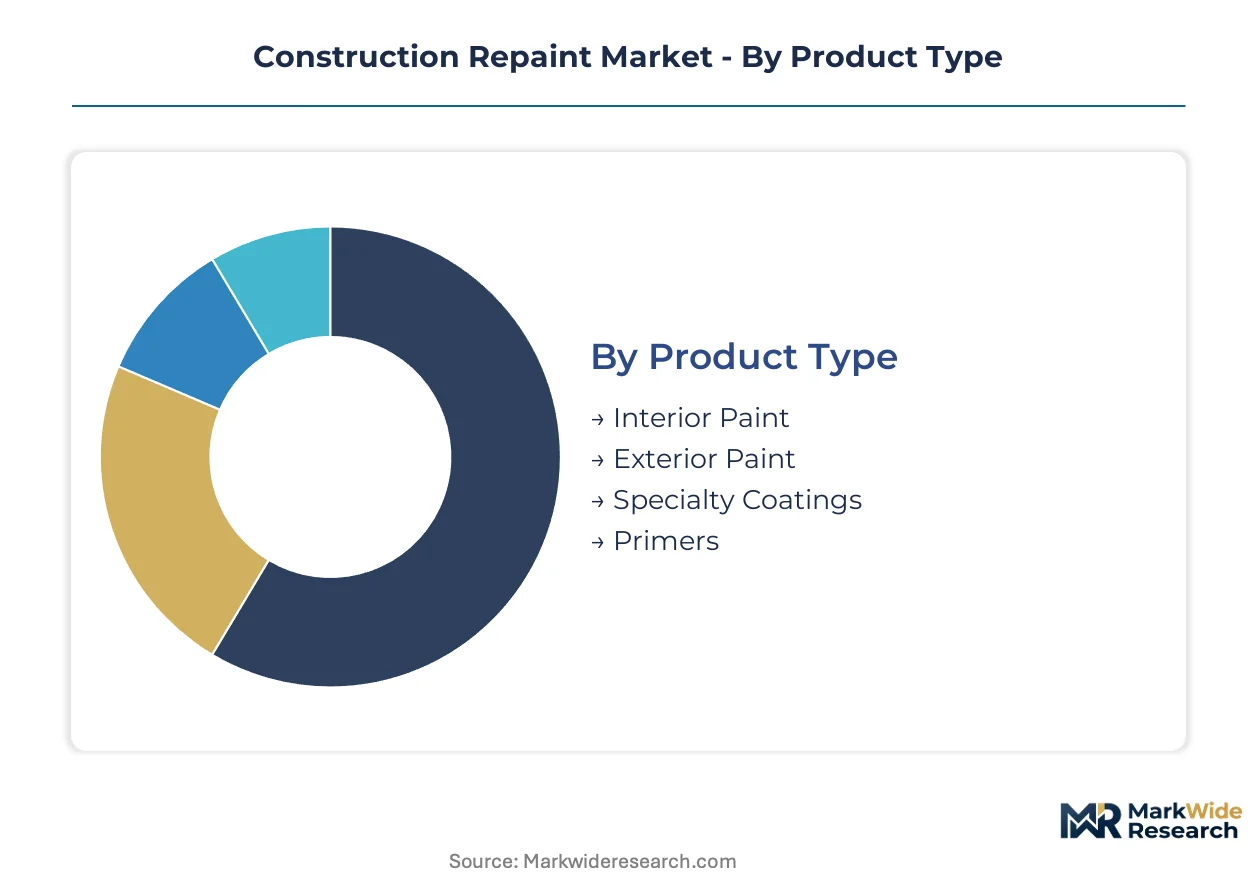
Segmentation in construction repaint reveals how specification authority, procurement patterns, and regulatory exposure fragment across buyer types. Understanding these divisions exposes where formulation investments concentrate and which channels capture margin.
Product Type:
Cost tier separates occasional renovators from institutional owners with compliance mandates.
- Interior Paint:Acrylic latex formulations dominate leased commercial spaces where rapid-dry low-odor systems minimize tenant displacement. Demand concentrates in US Class B office renovation and UK retail-to-residential conversions where refresh cycles compress from seven years to four.
- Exterior Paint:Alkyd and waterborne acrylic systems must achieve specified dry-film thickness and ASTM D3359 adhesion ratings on weathered substrates. Municipal housing authorities in Mumbai and Delhi drive volume through sustained recoating programs on aging concrete facades.
- Specialty Coatings:Antimicrobial and self-cleaning functionalities command premium specification in German and French healthcare renovation.
- Primers:Epoxy-based adhesion promoters anchor high-build systems on previously coated metal surfaces in industrial repaint.
Interior paint leads volumes today; specialty coatings are gaining share fastest.
End User:
Application scale determines whether procurement flows through contractor networks or direct manufacturer relationships.
- Commercial Buildings:Facility management firms bundle coating procurement with extended maintenance warranties, shifting risk from asset owners to applicator-contractor consortia. Deferred maintenance backlogs from institutional owners in Texas and California convert into contracted repaint programs.
- Residential Properties:Homeowners access products through home improvement stores and online retail, prioritizing color-matching convenience over technical specification.
- Infrastructure Projects:Transit agencies specify photocatalytic TiO₂-doped formulations for maintenance cost reduction in high-pollution urban corridors.
- Industrial Facilities:Spray certification requirements for high-build epoxy limit contractor capacity in commercial high-rise repaint segments.
Commercial buildings anchor revenue concentration; infrastructure projects show the steepest expansion trajectory.
Application:
Project timing dictates whether buyers prioritize speed, durability, or aesthetic flexibility.
- Renovation:Cloud-connected spectrophotometers paired with mobile tinting units eliminate shade-mismatch rework for large contractors. This channel absorbs the majority of value as deferred maintenance backlogs convert into programs.
- Maintenance:Cyclical recoating programs on government housing stock in India generate sustained demand from institutional owners.
- New Construction:Specification authority rests with general contractors and architects rather than repaint specialists.
- Decorative:Color trend cycles drive shorter refresh intervals in premium residential segments.
Renovation dominates value capture today; maintenance programs are climbing the fastest.
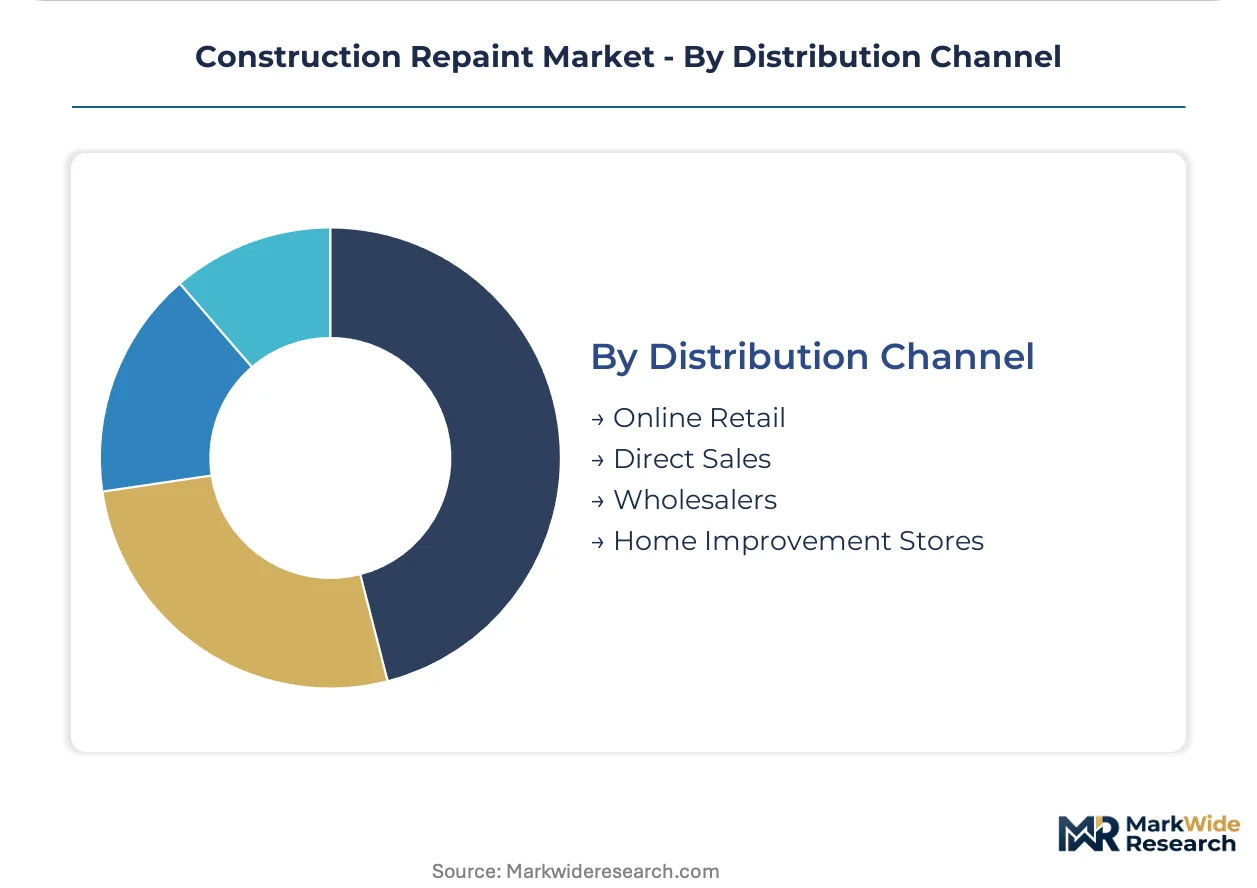
Distribution Channel:
Buyer sophistication determines whether procurement favors physical inspection or digital convenience.
- Direct Sales:Large commercial contractors deploy modular tinting systems with on-site dispensing equipment to compress procurement cycles and reduce inventory carrying costs.
- Home Improvement Stores:Captive retail networks control specification touchpoints for residential and light commercial buyers.
- Wholesalers:Regional distributors serve mid-tier contractors with localized shade libraries and same-day availability.
- Online Retail:Digital color specification tools are collapsing traditional distributor-warehouse networks for smaller project owners.
Direct sales leads margin capture today; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Architectural coatings manufacturing first scaled in the United States and Germany during the post-war housing boom, establishing formulation expertise and distribution infrastructure that later diffused to Asia-Pacific markets. Regional demand patterns now diverge sharply between mature stock-renewal economies and high-growth urban construction corridors.
United States
Class B office renovation and retail-to-residential conversion projects drive interior repaint volumes across Texas and California. EPA 40 CFR Part 59 enforcement tightens VOC ceilings and accelerates waterborne substitution in commercial programs. Facility management firms in Houston and Dallas bundle coating procurement with extended maintenance warranties.
Germany
Hospital renovation programs mandate antimicrobial functionality for infection control in Berlin and Munich healthcare facilities. REACH restriction proposals force reformulation of textured exterior products away from synthetic thickeners. Frankfurt and Hamburg contractors deploy cloud-connected spectrophotometers with mobile tinting units.
India
Aging government housing and transit infrastructure in Mumbai and Delhi generate sustained recoating demand from institutional owners. BIS certification for architectural coatings reinforces domestic manufacturing incentives under the PLI scheme. Same-day tinting capacity concentrates in Maharashtra and Gujarat contractor networks.
China
Urban renewal programs in the Yangtze River Delta and Pearl River Delta accelerate coating replacement on weathered concrete facades. Dual carbon goals under MEE guidance shift formulation priorities toward low-emission resin systems. Shanghai and Shenzhen building operators specify rapid-dry systems to minimize tenant displacement.
United Arab Emirates
Transit infrastructure maintenance programs in Dubai and Abu Dhabi specify photocatalytic TiO₂-doped formulations for dust-prone environments. MOHAP guidelines influence coating selection in healthcare facility renovation. High-pollution urban corridors drive self-cleaning functionality adoption across Gulf Cooperation Council specification standards.
Construction Repaint Market Vendor Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and specification authority in the construction repaint sector. The vendor base stratifies into captive retail network operators, specialized marine-protective crossover technologists, and localized shade-library providers. Three archetypes dominate: multinational integrated coating manufacturers with distribution control, regional specialists with regulatory navigation expertise, and contractor-facing service platforms with on-site tinting infrastructure. Competitive moves concentrate on modular tinting system deployment and bio-based resin R&D partnerships.
Within the multinational integrated tier, The Sherwin-Williams Company and PPG Industries exemplify North American operators with captive retail touchpoint control. Akzo Nobel occupies a position representing European specialists with marine-protective crossover capabilities. Asian Paints anchors the localized service archetype in high-fragmentation emerging markets. These three entities demonstrate how geographic origin and company structure correlate with competitive positioning across premium versus commodity margin capture.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| PPG Industries |
| Akzo Nobel |
| Nippon Paint Holdings |
| RPM International |
| Axalta Coating Systems |
| Asian Paints |
| Jotun |
| BASF |
| Others |
Supply Flow & Price Mechanics
Waterborne formulation mandates across multiple jurisdictions are compressing solvent-borne capacity and forcing capital reallocation toward low-VOC resin systems and tinting infrastructure. This technology transition simultaneously elevates upfront production costs and concentrates supply power among petrochemical complexes with integrated emulsion capabilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates antimicrobial specialty coatings from commodity interior latex and budget renovation-grade products. Price differentiation hinges on VOC compliance certification tier and volume procurement scale. Pricing pressure stems from titanium dioxide feedstock volatility squeezing mid-tier manufacturer margins. Residential DIY buyers exhibit highest price sensitivity; healthcare facility managers prioritize infection-control functionality over unit cost.
Supply Chain Analysis
India's PLI scheme for specialty chemicals and China's dual carbon goals under MEE guidance are reshaping sourcing patterns toward domestic resin production. Upstream supply draws from petrochemical complexes in China, South Korea, and Saudi Arabia for BPA and epichlorohydrin feedstocks. Single-source vulnerability concentrates in Asian epoxy resin manufacturing. Distribution runs through contractor-facing service platforms with on-site tinting infrastructure rather than traditional warehouse networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA 40 CFR Part 59 enforcement and REACH restriction timelines mechanically expand waterborne formulation demand.
For Market Incumbents: To counter titanium dioxide cost volatility, deepen backward integration into pigment supply or lock long-term offtake agreements with sulfate-process producers. Counter modular tinting system disruption by embedding proprietary color-matching software into contractor equipment fleets. For New Entrants and Emerging Players: Launch via cloud-connected spectrophotometer partnerships with large commercial contractors in Texas and California. Target India's fragmented contractor base in Maharashtra and Gujarat with localized shade libraries and same-day tinting capacity. Penetrate through antimicrobial coating specification in German and French healthcare renovation programs. For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists with regulatory navigation expertise but limited tinting infrastructure. Long-term viability favors bio-based resin R&D partnerships and captive distribution control. Watch ECHA substance evaluation timelines as inflection signal for new product commercialization cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Supply | Captive titanium dioxide sourcing insulates margin from sulfate-process price swings. |
| Modular Tinting System Deployment | On-site dispensing equipment compresses contractor procurement cycles and locks specification control. |
| Bio-based Resin R&D Partnership | Marine-protective coating expertise cross-applies to REACH-compliant architectural formulations. |
| Extended Maintenance Warranty Bundling | Risk transfer from facility management firms to applicator-contractor consortia anchors recurring revenue. |
| Localized Shade Library Expansion | Same-day tinting capacity in high-fragmentation markets captures specification authority from multinational competitors. |
Methodological Framework
Bottom-up contractor procurement modeling reconciled against top-down resin production tracking forms the analytical core of this study. Primary interviews with facility management directors, commercial painting contractors, coating formulation R&D leads, and distribution channel managers were validated against customs data, EPA enforcement records, ECHA registration databases, and BIS certification filings. Secondary sources include SEC 10-K disclosures, Cefic production statistics, and Indian PLI scheme beneficiary reports.
Input-output matrices map acrylic emulsion and alkyd resin supply through formulation tiers to end-use segments across the projection horizon. Segmentation dimensions encompass product type, end-user category, application channel, and distribution model. CAGRs derive from volume trajectory modeling against regulatory compliance deadlines and building stock renewal cycles. Forecast inputs incorporate REACH restriction proposal timelines and India's urban infrastructure maintenance program announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under raw material price spike conditions or ECHA substance evaluation delays. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Construction
Concrete and Cement Dissolver Market
Specialty Construction
Welded Metal Bellows Market
Specialty Construction
Fire Hydrants Market
Specialty Construction
Composite Repair Market
Specialty Construction
India Anchors and Grouts Market
Specialty Construction
ASEAN Waterproofing Market
Specialty Construction
Asia-Pacific Anchors and Grouts Market
Specialty Construction
Temporary Fencing Panels Market
Specialty Construction
Europe Anchors and Grouts Market
Specialty Construction
South America Anchors and Grouts Market
Specialty Construction
Asia-Pacific Waterproofing Solutions Market
Specialty Construction
Portable Walls Market
Specialty Construction
Roller Shutter Market
Specialty Construction
Slab Repair Products Market
Specialty Construction
Global Fencing Market
Specialty Construction
Shotcrete Accelerators Market