
 ASEAN Waterproofing Market | 2026-2036
ASEAN Waterproofing Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Waterproofing Market Outlook
Distributor networks across Southeast Asia are reshaping how waterproofing specifications reach end users, with regional stockists now carrying application-grade technical support capabilities. Sika AG leverages its Thai manufacturing base to sustain rapid fulfillment across mainland Southeast Asia. Dow competes through specialized polymer intermediates supplied to regional formulators. Oriental Yuhong Waterproof Technology anchors its ASEAN push with dedicated technical centers in Singapore and Malaysia.
Waterproofing encompasses engineered barrier systems—typically comprising bituminous membranes, polyurethane or acrylic liquid formulations, cementitious crystalline admixtures, or synthetic polymer sheets—designed to prevent liquid water ingress into structural substrates under hydrostatic or atmospheric pressure. Liquid membrane systems lead specification volumes in tropical climates where complex geometries complicate sheet application, while rigid sheets dominate tunnel and basement segments requiring puncture resistance under soil loads. Infrastructure end users represent the fastest-growing demand pool as ASEAN governments expand rail, port, and flood-management investments requiring substructure durability.
Thailand's Board of Investment, Indonesia's SNI standards body, and Singapore's Building and Construction Authority collectively enforce performance-grade certifications that filter substandard imports from regional supply chains. Malaysia's CIDB mandates material traceability for public infrastructure waterproofing, tightening market access for uncertified suppliers. Stakeholders must monitor evolving green-building codes across Vietnam and the Philippines, where emerging carbon-accounting rules for construction materials will soon reshape procurement criteria and product qualification pathways.
Market Dynamics
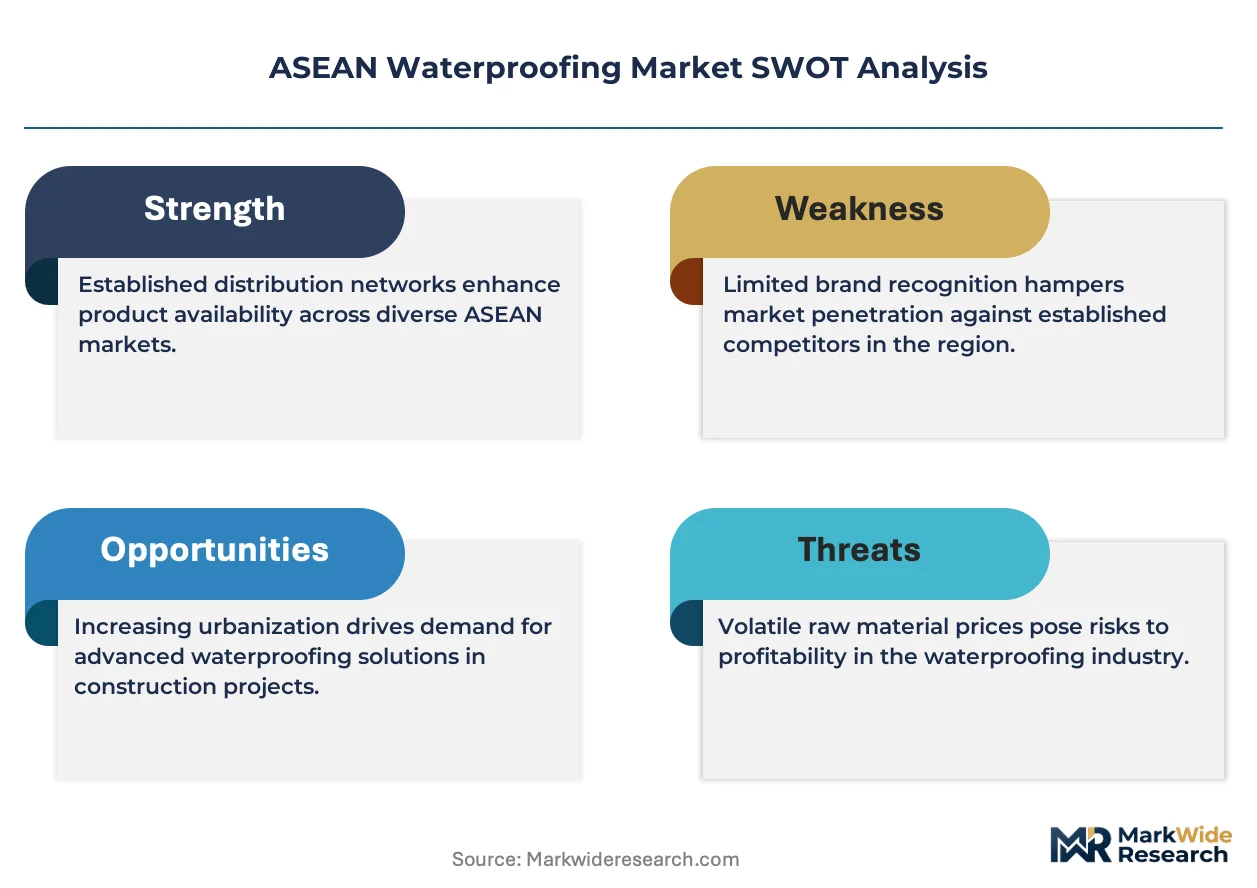
Green-building certification mandates across Thailand, Indonesia, and Singapore are rerouting specification flows toward certified liquid-applied membrane systems, compressing lead times for uncertified imports and rewarding regional manufacturing investments.
Growth Catalysts
- Thailand's Board of Investment incentives:Tax holidays and import duty exemptions for green building materials are accelerating specification of certified liquid-applied products in commercial developments.
- Rail and port infrastructure pipelines:Government capital programs across Indonesia, Vietnam, and the Philippines are generating concentrated demand for below-grade and substructure waterproofing systems.
- Liquid membrane technology:Complex geometries in tropical high-rise construction favor spray-applied polyurethane and acrylic formulations over rigid sheet alternatives.
Market Restraints
- Petrochemical input volatility:Polyurethane resin and bitumen feedstock prices fluctuate with regional refinery output, squeezing formulator margins.
- Supply concentration in Thai manufacturing:Mainland Southeast Asia fulfillment depends heavily on a narrow corridor of production assets near Bangkok.
- Malaysia's CIDB material traceability mandate:Public infrastructure projects require documented supply chain provenance, filtering out informal importers.
Strategic Opportunities
- Vietnam's emerging green-building codes:Draft carbon-accounting rules for construction materials will create first-mover advantage for certified low-VOC product lines.
- Application-grade technical support:Distributors carrying in-house specification capabilities can capture margin previously held by manufacturer direct sales.
- Cementitious crystalline admixtures:Hybrid systems combining crystalline technology with conventional membranes open specification in water-retaining structures.
Industry Challenges
- Certified applicator scarcity:Liquid membrane systems require trained installation crews, and regional technical training capacity lags specification volume.
- Multi-standard compliance complexity:Products must simultaneously satisfy Thailand's BOI criteria, Indonesia's SNI standards, and Singapore's BCA requirements.
- Substrate condition variability:Tropical humidity and existing building stock quality create inconsistent preparation requirements across project sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Waterproofing Market |
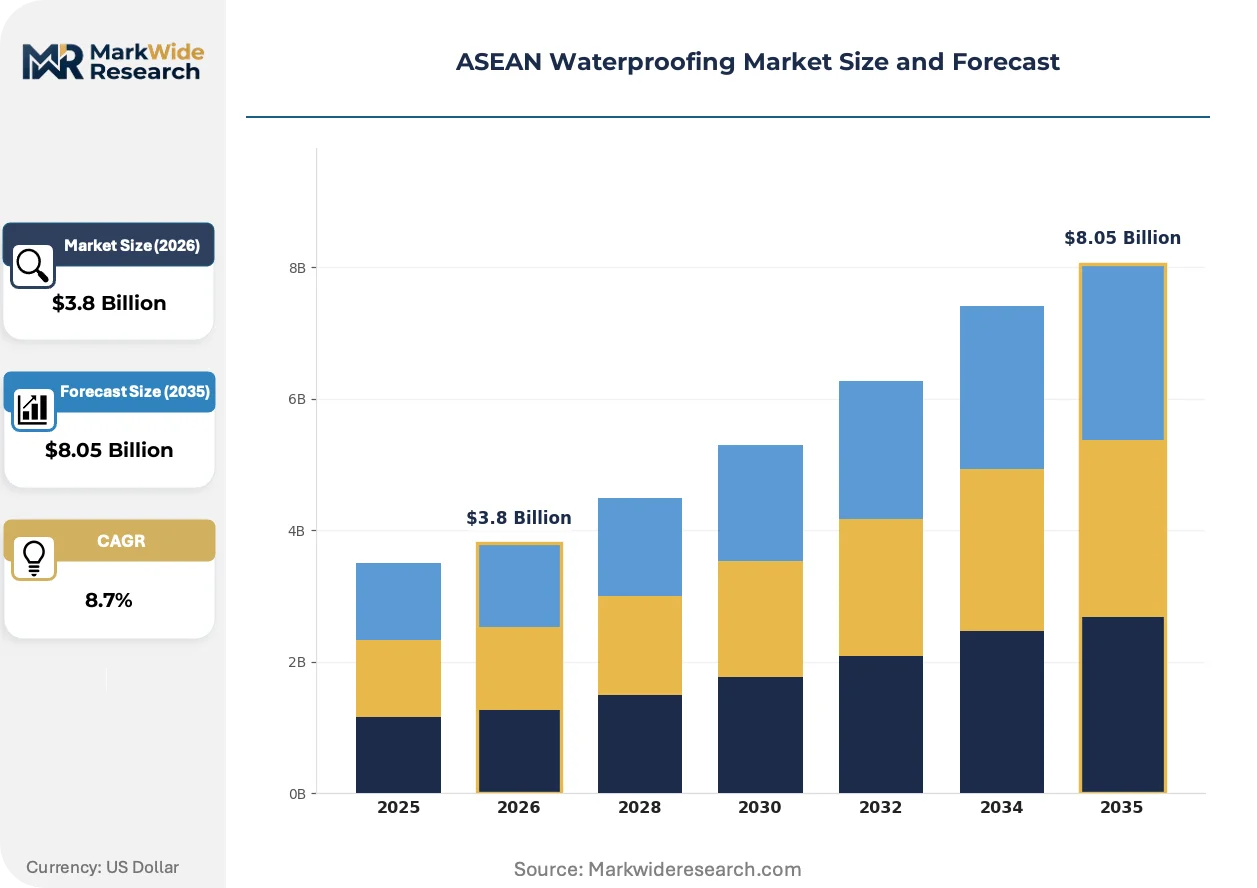
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Membrane, Rigid Sheets, Coatings, Sealants Application: Roofing, Basement, Tunnel, Bridge End User: Residential, Commercial, Industrial, Infrastructure Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Saint-Gobain, Dow, Sika AG, KCC Corporation, Fosroc International Limited, BASF SE, Bostik, Oriental Yuhong Waterproof Technology, Mapei S.p.A., Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Waterproofing Market Strategic Shifts
Specification workflows across Southeast Asia are digitizing, with distributor technical centers replacing traditional manufacturer-direct relationships and compressing the path from product selection to site delivery.
Self-healing polymer technology is collapsing the distinction between preventive and remedial waterproofing applications. Commercial developers in Jakarta and Bangkok are specifying these materials for high-risk podium and basement structures. The technology is collapsing warranty cost structures by reducing callback frequency and enabling longer performance guarantees.
Singapore's Building and Construction Authority has tightened VOC emission thresholds for wet-applied construction materials. Formulators are reformulating solvent-based polyurethane systems to water-borne alternatives. High-rise residential and hospitality segments in Singapore and Kuala Lumpur are absorbing reformulation costs fastest, passing premiums through green-financing mechanisms.
Asset owners are unbundling material procurement from installation services, separating waterproofing specification from general contractor package deals. Specialist applicators in Indonesia and the Philippines are winning direct contracts with developers, bypassing traditional construction supply chains. This pattern concentrates most visibly in Jakarta-Bandung corridor megaprojects where schedule risk drives direct specialist engagement.
ASEAN Waterproofing Market Segmentation
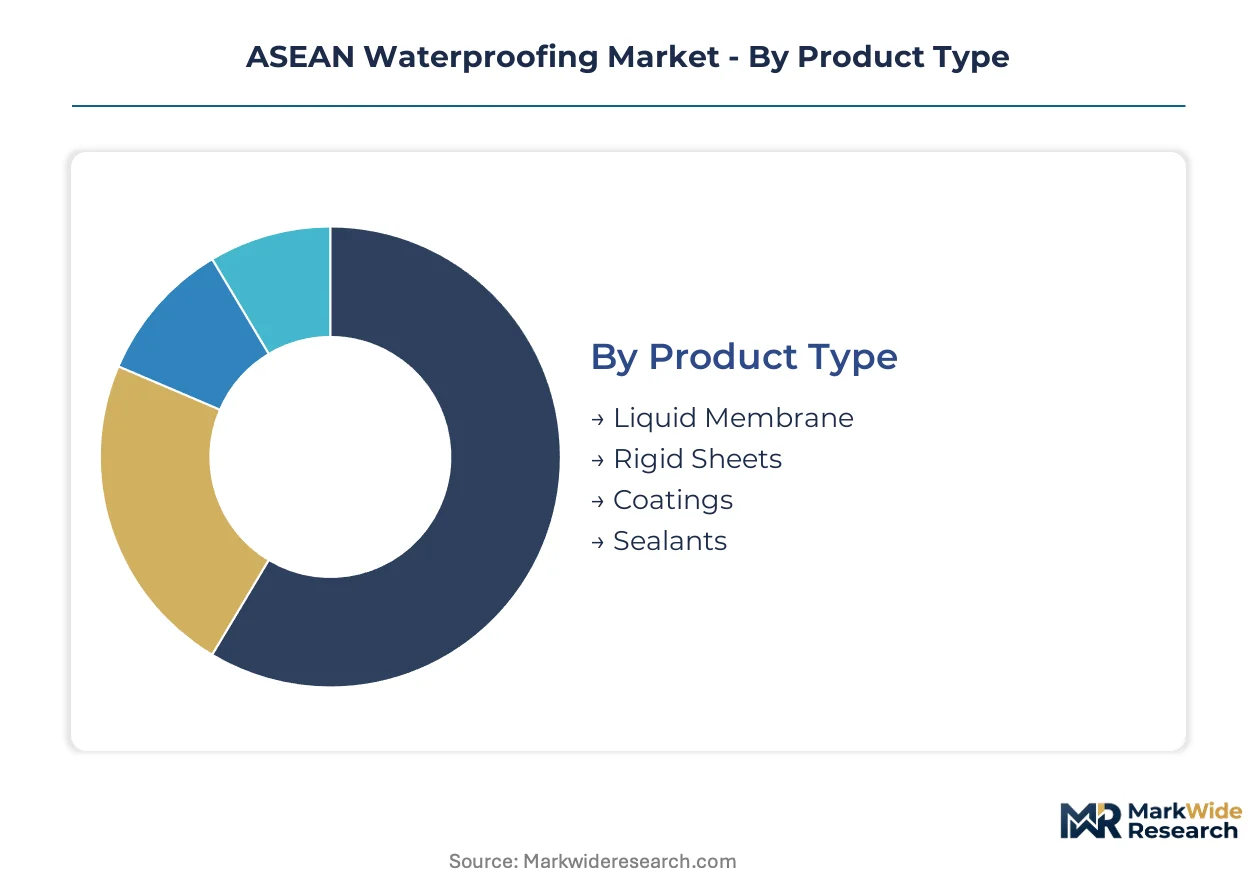
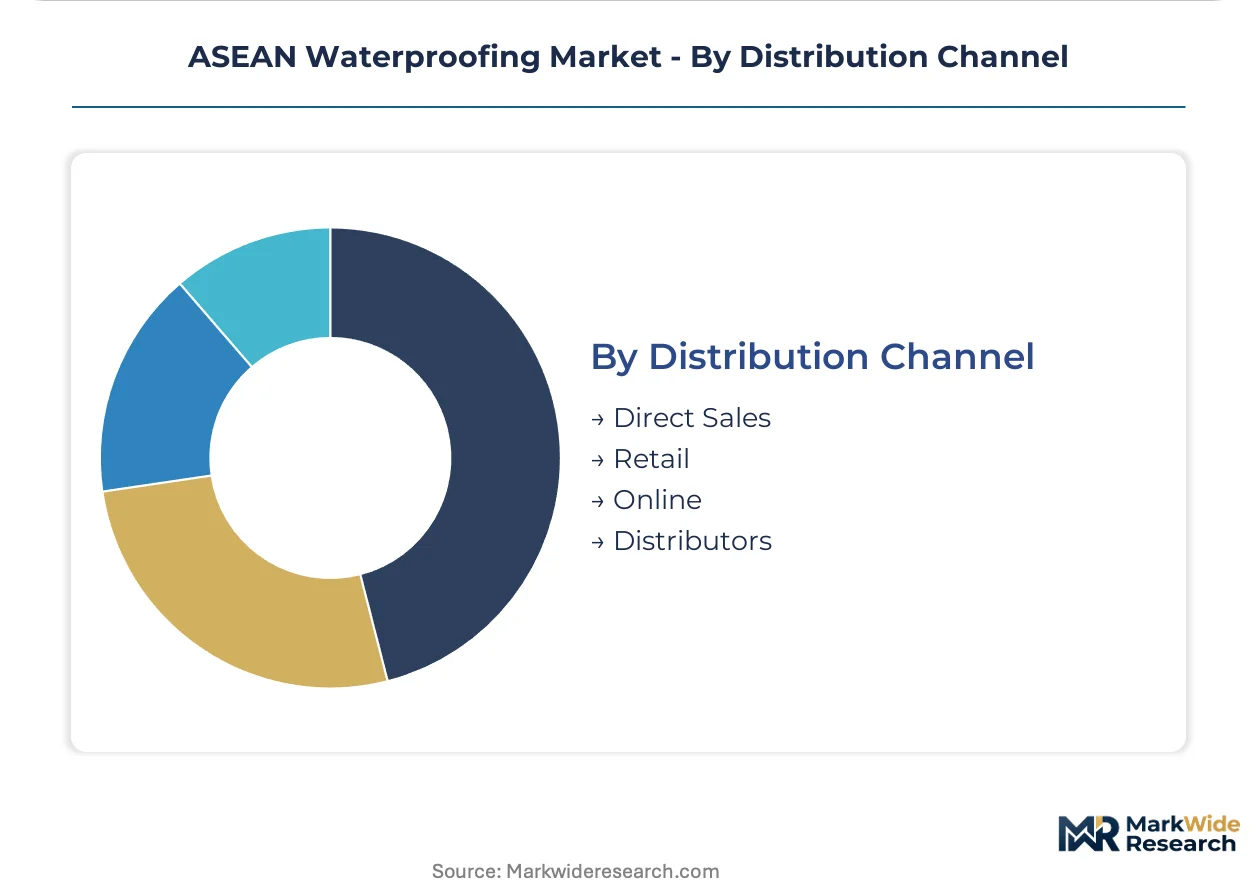
Waterproofing procurement patterns across Southeast Asia diverge sharply by construction phase and project scale. Specification workflows route different product categories through distinct channel structures, with infrastructure tenders favoring direct manufacturer relationships while commercial developments rely on distributor technical support.
Product Type:
Mature bituminous systems coexist with emerging polymer technologies as formulators respond to tropical climate performance requirements.
- Liquid Membrane:Polyurethane and acrylic formulations cure into seamless elastomeric barriers that accommodate complex geometries in high-rise podium decks. Singapore's BCA VOC thresholds are accelerating water-borne reformulations, with commercial developers in Kuala Lumpur absorbing green-financing premiums fastest.
- Rigid Sheets:Modified bitumen and synthetic polymer sheets deliver puncture resistance for below-grade structures under hydrostatic soil loads. Indonesia's Jakarta-Bandung corridor megaprojects specify these systems for basement and tunnel segments where mechanical damage risk dominates.
- Coatings:Cementitious crystalline admixtures penetrate concrete capillaries to block water migration in water-retaining structures.
- Sealants:Joint-sealing compounds address movement accommodation in expansion and construction joints across bridge and building envelope applications.
Liquid membrane handles the majority of specification volume in tropical high-rise construction; rigid sheets are gaining share fastest in infrastructure substructure applications.
Application:
Cost-tier differentiation separates premium below-grade systems from standard roofing specifications across ASEAN procurement workflows.
- Roofing:Exposed membrane systems must withstand UV degradation and thermal cycling in equatorial climates. Thailand's BOI-certified liquid-applied products are capturing specification share in Bangkok commercial developments seeking green-building accreditation.
- Basement:Negative-side waterproofing demands hydrostatic pressure resistance and substrate adhesion to damp concrete. Vietnam's emerging high-rise clusters in Ho Chi Minh City are driving demand for hybrid crystalline-membrane systems.
- Tunnel:Sheet-applied membranes with geotextile protection layers address groundwater ingress in rail and road infrastructure.
- Bridge:Expansion joint sealing and deck waterproofing require elastomeric systems accommodating dynamic load movement.
Roofing absorbs the largest share of product volume; basement waterproofing is expanding most quickly as urban density drives deeper excavation.
End User:
Customer-type segmentation reveals divergent procurement sophistication between institutional infrastructure buyers and fragmented residential channels.
- Residential:Individual homeowners and small developers prioritize cost over performance verification, sourcing through retail hardware networks with limited technical guidance.
- Commercial:Mall, hotel, and office developers in Jakarta, Bangkok, and Singapore specify certified systems to meet green-building mandates and warranty requirements. Malaysia's CIDB traceability rules filter uncertified products from public-private partnership projects.
- Industrial:Manufacturing facilities require chemical-resistant membranes for process areas and containment structures.
- Infrastructure:Government rail, port, and flood-management programs generate concentrated demand for below-grade durability. Indonesia's state-owned construction holding companies are consolidating procurement through pre-qualified supplier panels.
Infrastructure commands the highest specification rigor; commercial end-use is climbing the fastest as green-certification mandates proliferate.
Distribution Channel:
Supply concentration in Thai manufacturing shapes fulfillment patterns across mainland Southeast Asia.
- Direct Sales:Manufacturer technical teams engage directly with infrastructure contractors and major developers on complex below-grade specifications. Sika AG leverages its Thai production base for rapid fulfillment across the Mekong sub-region.
- Retail:Hardware chains and building-material yards serve residential repair and small-scale construction with limited application support.
- Online:E-commerce platforms are emerging for standardized coating products, though liquid membrane systems remain specification-driven rather than transactionally purchased.
- Distributors:Regional stockists with in-house technical capabilities are displacing manufacturer-direct relationships in commercial segments. Application-grade support allows distributors to capture margin previously held by direct sales forces.
Distributors handle the majority of commercial specification flow; direct sales channels are expanding most quickly in infrastructure procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jakarta-Bandung high-speed rail corridor anchors Indonesia's waterproofing demand as megaproject basements and tunnels require extensive below-grade protection. Thailand's Eastern Economic Corridor deep-sea port expansions and Vietnam's North-South Expressway segments concentrate procurement for substructure membrane systems. Singapore's mass rapid transit extensions and flood-management reservoirs complete the regional infrastructure matrix driving specification volumes.
Indonesia
Jakarta-Bandung corridor megaprojects and new capital city construction in Nusantara generate concentrated demand for rigid sheet membranes in tunnel and basement segments. Indonesia's SNI standards body enforces performance-grade certifications that filter substandard imports from supply chains. State-owned construction holding companies in Greater Jakarta are consolidating procurement through pre-qualified supplier panels for rail and port infrastructure.
Thailand
Bangkok commercial developments and Eastern Economic Corridor industrial zones accelerate specification of certified liquid-applied products. Thailand's Board of Investment offers tax holidays and import duty exemptions for green building materials that redirect flows toward certified systems. Manufacturing assets near Bangkok sustain rapid fulfillment across mainland Southeast Asia for Sika AG and regional formulators.
Vietnam
Ho Chi Minh City high-rise clusters and North-South Expressway segments drive demand for hybrid crystalline-membrane basement systems. Draft carbon-accounting rules for construction materials will create first-mover advantage for certified low-VOC product lines. Da Nang-Quang Nam industrial zones are absorbing green-building code premiums fastest through developer direct contracts with specialist applicators.
Singapore
Mass rapid transit extensions and flood-management reservoir programs generate specification for below-grade durability in dense urban conditions. Singapore's Building and Construction Authority enforces tightened VOC emission thresholds for wet-applied construction materials. Marina Bay and Jurong Lake District commercial developments are passing reformulation costs through green-financing mechanisms.
Malaysia
Kuala Lumpur high-rise residential and hospitality segments absorb water-borne polyurethane premiums driven by green-certification mandates. Malaysia's CIDB mandates material traceability for public infrastructure waterproofing, tightening market access for uncertified suppliers. Iskandar Malaysia and Klang Valley developments are unbundling material procurement from installation services, concentrating specialist applicator contracts.
ASEAN Waterproofing Market Competitive Environment
On the supply side, the industry is tiered between integrated multinational formulators and regional distributors carrying application-grade technical capabilities. Concentration centers on Thai manufacturing assets that serve mainland Southeast Asia fulfillment, while specification influence flows through Singapore-based technical centers. Three archetypes dominate: polymer intermediate suppliers, integrated membrane manufacturers, and distributor-technical hybrids. Capacity expansion near Bangkok and strategic partnerships for crystalline technology licensing represent the dominant competitive vectors.
Among integrated membrane manufacturers, Sika AG leverages its Thai production base for rapid Mekong sub-region fulfillment, while Dow competes through specialized polymer intermediates supplied to regional formulators. Oriental Yuhong Waterproof Technology anchors its ASEAN push with dedicated technical centers in Singapore and Malaysia, exemplifying the distributor-technical hybrid archetype that captures margin previously held by manufacturer direct sales forces.
| Leading Market Players |
|---|
| Saint-Gobain |
| Dow |
| Sika AG |
| KCC Corporation |
| Fosroc International Limited |
| BASF SE |
| Bostik |
| Oriental Yuhong Waterproof Technology |
| Mapei S.p.A. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Thai liquid membrane production is pressuring regional formulators to absorb petrochemical input volatility while defending margin positions across certification tiers.
Pricing Analysis
Volume-discount tiering separates BOI-certified liquid-applied systems from uncertified imports and generic retail-grade alternatives. Price differentiation hinges on green-building certification grade and project scale, with Jakarta-Bandung megaproject procurement commanding favorable terms through direct manufacturer engagement. Cost compression in economy-grade retail channels is intensifying because Indonesian SNI compliance investments filter informal suppliers. Residential repair segments exhibit highest price sensitivity; infrastructure contractors demonstrate lowest sensitivity due to warranty and performance guarantees.
Supply Chain Analysis
Contract-manufacturing concentration rests with Sika AG's Thai production base and Dow's polymer intermediate supply to regional formulators. Geographic supply concentration centers on Thailand, Singapore, and Malaysia, with Bangkok-corridor assets feeding mainland Southeast Asia fulfillment. Raw material dependencies draw from regional bitumen refineries, polyurethane resin streams, and cementitious crystalline admixture imports. Single-source vulnerability concentrates in Thai manufacturing corridors serving Mekong sub-region demand. Distribution runs through technical-capable distributors displacing traditional manufacturer-direct relationships in commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified applicator shortages and multi-standard compliance complexity are constraining execution capacity, creating defendable positions for stakeholders who bridge this capability gap.
For Market Incumbents: Pre-empt distributor technical center expansion by embedding application-grade support capabilities within existing Thai manufacturing footprints. Consolidate procurement relationships with Indonesia's state-owned construction holding companies before pre-qualified supplier panels harden. Channel control through certified applicator training programs offers the strongest defensive lever against emerging technical-capable distributors. For New Entrants and Emerging Players: Vietnam's Da Nang-Quang Nam industrial zones present underpenetrated demand for hybrid crystalline-membrane basement systems as draft carbon-accounting rules reshape procurement criteria. Direct contracts with specialist applicators bypass entrenched general contractor supply chains fastest in high-rise residential clusters. Green-financing mechanism alignment unlocks premium positioning in Kuala Lumpur and Singapore hospitality segments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across liquid membrane manufacturing as water-borne reformulation investments and VOC compliance infrastructure reshape cost structures. Acquisition targets should display backward integration into polymer intermediates or captive certified applicator networks. Monitor Thailand's BOI incentive renewal schedules as inflection indicators for regional manufacturing competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Applicator Training Program | Addresses scarcity constraining liquid membrane specification volume across tropical high-rise construction. |
| Water-Borne Polyurethane Reformulation | Aligns product lines with Singapore's BCA VOC thresholds and green-financing eligibility requirements. |
| Thai Manufacturing Capacity Expansion | Reduces fulfillment lead times for Mekong sub-region infrastructure tenders requiring rapid site delivery. |
| Crystalline Technology Licensing Partnership | Opens specification in Vietnam's water-retaining structures and Indonesia's flood-management reservoirs. |
| Distributor Technical Center Acquisition | Captures margin displacement from manufacturer-direct relationships in commercial development channels. |
Study Parameters
Operator-level perspectives from waterproofing applicators, commercial development procurement managers, infrastructure project engineers, and distributor technical directors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against Thailand's BOI incentive disclosures, Indonesia's SNI certification registries, Singapore's BCA building codes, and customs trade data for bitumen and polyurethane resin flows. Bottom-up project pipeline assessments and top-down construction spending forecasts were triangulated to cross-check volume assumptions.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning product type, application, end user, and distribution channel. CAGRs were derived from fitted growth curves applied to validated base-year estimates, incorporating infrastructure capital program timelines and green-building code adoption trajectories as industry-specific forecast inputs.
Practitioners should monitor petrochemical input price volatility, regulatory certification requirement changes, and certified applicator training capacity expansion for early signals of forecast revision. Quarterly review of infrastructure tender award volumes and BOI incentive utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Construction
Indonesia Waterproofing Solutions Market
Specialty Construction
Slab Repair Products Market
Specialty Construction
Construction Repaint Market
Specialty Construction
Indonesia Anchors and Grouts Market
Specialty Construction
South America Anchors and Grouts Market
Specialty Construction
Shotcrete Accelerators Market
Specialty Construction
Fire Hydrants Market
Specialty Construction
Composite Repair Market
Specialty Construction
Concrete and Cement Dissolver Market
Specialty Construction
Portable Walls Market
Specialty Construction
Welded Metal Bellows Market
Specialty Construction
India Anchors and Grouts Market
Specialty Construction
Roller Shutter Market
Specialty Construction
Expandable Shelter Market
Specialty Construction
Asia-Pacific Waterproofing Solutions Market
Specialty Construction
Temporary Fencing Panels Market