
 Temporary Fencing Panels Market | 2026-2036
Temporary Fencing Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Temporary Fencing Panels Market Outlook
The EU Construction Products Regulation is hardening material traceability requirements for temporary fencing deployed on European infrastructure sites. Betafence leverages its galvanized steel production network to meet these certification thresholds across continental markets. ZND anchors its position through integrated mesh welding and powder-coating capacity in the United Kingdom. Master Halco competes in North America with a broad distributor footprint serving contractor and municipal accounts.
Temporary fencing panels are modular barrier systems, typically fabricated from welded wire mesh attached to tubular steel or aluminum frames, designed for rapid deployment, relocation, and removal without permanent foundation work. Steel-framed panels with anti-climb mesh profiles dominate commercial procurement due to impact resistance and compatibility with ballast bases on uneven terrain. The application dimension shows construction sites generating the largest volume pull, while events and public gatherings represent a faster-growing margin pool as security protocols tighten around temporary crowd management. Among end users, municipalities are expanding specifications for crash-rated and anti-terror configurations at public infrastructure sites.
OSHA governs worker protection boundaries on U.S. construction sites, while the EU Construction Products Regulation mandates CE marking and performance declarations for fencing used in permanent-works-adjacent temporary applications. Australia's Work Health and Safety regulators and state-level building codes impose additional fall-protection and public-safety standards for perimeter barriers. Stakeholders must monitor evolving national security designations that reclassify temporary fencing as critical infrastructure protection equipment.
Market Dynamics
OSHA fall-protection mandates and EU CE marking requirements for temporary perimeter barriers are compressing product lifecycles and forcing rapid specification upgrades across contractor procurement channels.
Growth Catalysts
- EU Construction Products Regulation:CE marking mandates for temporary fencing adjacent to permanent works are accelerating replacement cycles across German and French infrastructure sites.
- Steel mesh welding automation:Robotic fabrication lines are reducing panel production lead times and enabling just-in-time delivery to large-scale construction projects.
- Event security hardening:Municipalities in Australia and the United States are expanding anti-terror fencing specifications for public gatherings and temporary crowd control zones.
Market Restraints
- Hot-rolled steel price volatility:Input cost swings for galvanized steel tubing are compressing margins for fabricators without long-term raw material hedging.
- Chinese supply concentration:Dependence on imported wire mesh from select Asian producers creates tariff exposure and quality inconsistency risks.
- Ballast base weight limits:OSHA lifting restrictions on manual handling constrain rapid deployment speed for concrete-filled bases on uneven terrain.
Strategic Opportunities
- Crash-rated temporary barriers:K-rated and M-rated fencing systems for critical infrastructure protection are expanding addressable market beyond standard construction panels.
- Mesh-to-frame bonding adhesives:Structural adhesive technologies are converging with traditional welding to enable lighter aluminum-frame panels with equivalent impact resistance.
- Rental fleet digitization:RFID-tagged panel tracking systems are opening subscription-based revenue streams for equipment rental operators serving recurring event contracts.
Industry Challenges
- Welding certification backlog:AWS D1.1 structural welding qualifications for galvanized steel are creating bottlenecks in workforce scaling for peak construction seasons.
- Multi-jurisdiction compliance mapping:Contractors operating across state lines must reconcile varying OSHA regional interpretations with municipal specification databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Temporary Fencing Panels Market |
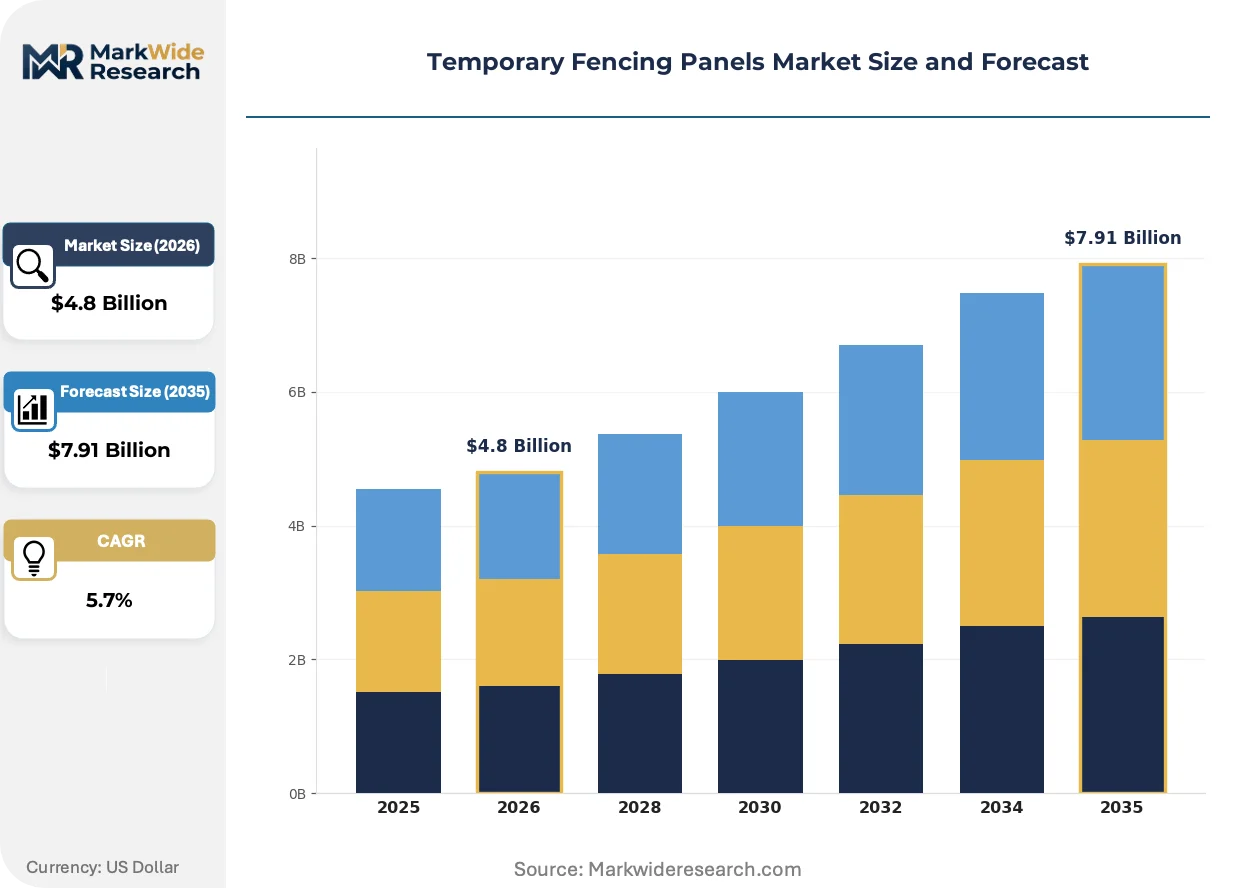
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel, Aluminum, Plastic, Composite Application: Construction Sites, Events, Public Gatherings, Sports Venues End User: Contractors, Event Organizers, Municipalities, Security Providers Installation Type: Portable, Permanent, Semi-Permanent, Adjustable |
| Companies Covered | Lion Fencing and Steel Supplies, MDWS Fence, ZND, Betafence, Fenceweb, Blok 'N' Mesh, Hoover Fence Company, Ameristar Perimeter Security, Master Halco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Temporary Fencing Panels Market Strategic Shifts
Modular barrier systems are absorbing sensor integration and sustainable material pressures that originated in permanent infrastructure markets.
Anti-climb mesh profiles with reduced apertures are expanding into municipal and utility security applications where perimeter breach prevention now matches construction site safety as a procurement priority. Water treatment facilities and electrical substations are specifying these panels for temporary worksite isolation during maintenance windows. The technology is expanding into segments previously served by chain-link or hoarding systems, compressing the addressable market for legacy barrier types.
REACH substance restrictions on hexavalent chromium in galvanizing processes are forcing European fabricators to shift toward zinc-aluminum coating chemistries or post-galvanizing sealing treatments. The industrial consequence is a 15-20% coating cost premium that is being passed through to public-sector buyers with sustainability mandates. German and Dutch infrastructure authorities are responding by incorporating total-life-cycle carbon metrics into temporary fencing tender evaluations.
Equipment-as-a-service models are disrupting traditional capital purchase patterns for large panel fleets. Major event management firms and film production coordinators are shifting toward multi-year rental agreements with maintenance and rapid-relocation clauses. This behavioral pivot is most visible in California and New South Wales where seasonal event density justifies dedicated inventory pools over spot procurement.
Temporary Fencing Panels Market Segmentation
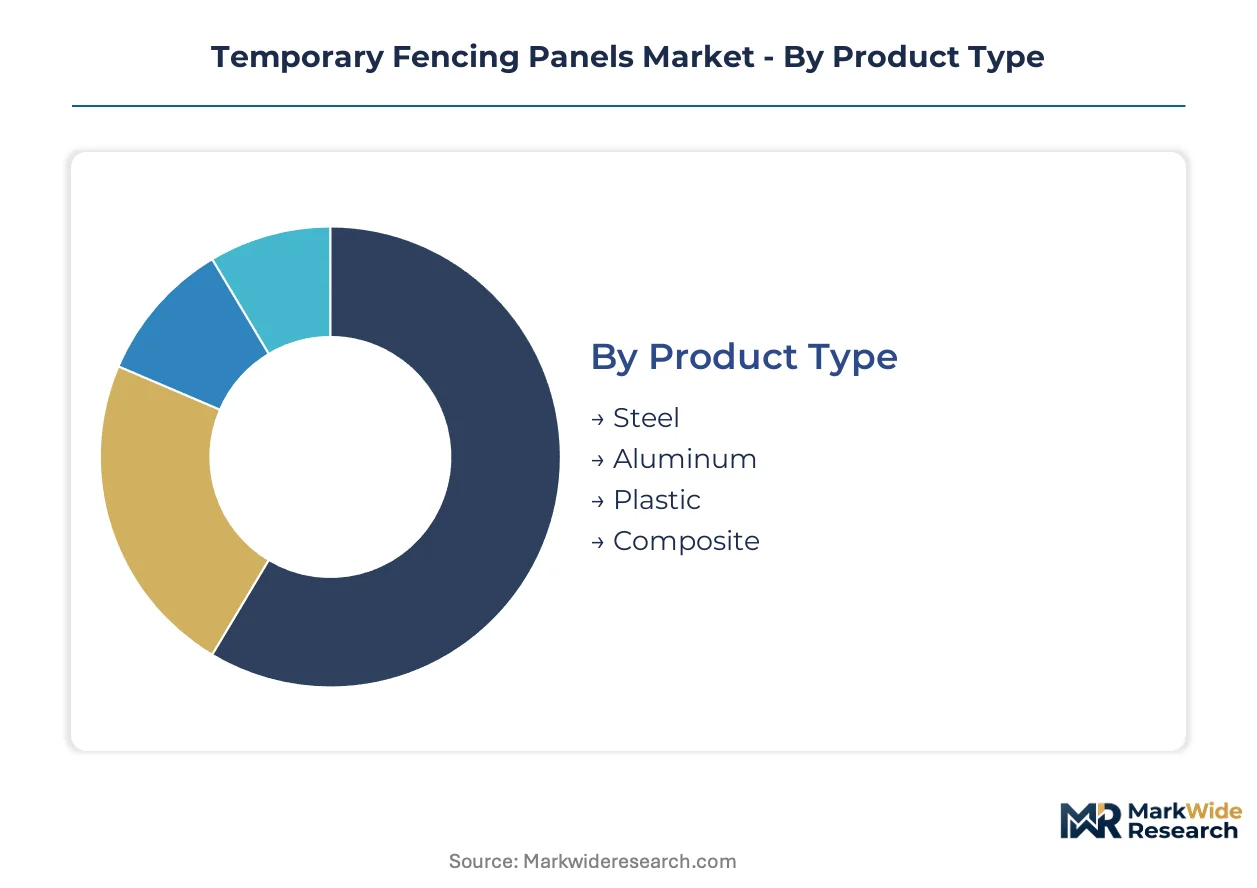
Temporary fencing panels segment across material composition, deployment duration, and procurement authority, each dimension carrying distinct margin profiles and specification rigor. Contractors, municipalities, and event operators source through divergent channels with incompatible lead-time and certification requirements.
Product Type:
Steel fabrication demands the heaviest capital commitment, with robotic welding lines and galvanizing baths requiring seven-figure infrastructure outlays that aluminum and plastic extrusion avoid.
- Steel:Welded wire mesh affixed to galvanized tubular frames delivers impact resistance for uneven terrain and ballast-base compatibility. German infrastructure authorities specify steel panels for permanent-works-adjacent temporary barriers under EU Construction Products Regulation CE marking mandates.
- Aluminum:Lighter frame weight reduces OSHA manual-handling compliance burdens while maintaining structural integrity for rapid event deployment. Australian rental fleets are converting aluminum inventories for seasonal festival circuits where relocation frequency exceeds durability priorities.
- Plastic:Polyethylene and PVC formulations serve low-security crowd channeling where cost minimization outweighs anti-climb requirements.
- Composite:Fiber-reinforced polymer hybrids target sustainability-mandated public tenders with reduced lifecycle carbon metrics.
Most installed capacity flows through Steel. Expansion is steepest in Aluminum.
Application:
Volume concentration and margin structure diverge sharply across these deployment contexts, with construction absorbing raw tonnage while events command rental premiums.
- Construction Sites:Perimeter security and fall-protection boundaries on commercial and residential builds generate baseline demand. OSHA mandates in the United States and Work Health and Safety regulations in Australia enforce continuous barrier specifications during active phases.
- Events:Temporary crowd management for concerts, festivals, and corporate gatherings demands rapid-install configurations with aesthetic finishes. Municipalities in California and New South Wales are expanding anti-terror fencing specifications for high-attendance public assemblies.
- Public Gatherings:Political rallies and civic ceremonies require modular barriers with integrated access gates for emergency vehicle passage.
- Sports Venues:Stadium perimeters and pitch-side separation utilize crash-rated configurations where spectator safety protocols intersect with broadcast visibility requirements.
Construction Sites absorb the majority of panel shipments. Events generate the steepest margin expansion trajectory.
End User:
Procurement sophistication and specification authority vary dramatically, with municipalities imposing certification burdens that contractor spot-buying bypasses.
- Contractors:General and specialty construction firms purchase or lease panels through distributor networks for project-specific durations. Price sensitivity dominates, though tier-one builders are adopting RFID-tracked rental fleets for multi-site efficiency.
- Municipalities:City and county agencies specify K-rated and M-rated crash barriers for critical infrastructure protection, with total-life-cycle carbon metrics entering tender evaluations in the Netherlands and Germany.
- Event Organizers:Production coordinators and festival operators prioritize rapid-deployment speed and relocation clauses over capital ownership, driving equipment-as-a-service adoption in high-event-density markets.
- Security Providers:Private firms serving utilities and data centers procure anti-climb mesh configurations for temporary worksite isolation during maintenance windows.
Contractors deploy the largest panel volumes. Municipalities are climbing the fastest as security hardening reclassifies temporary barriers as critical infrastructure.
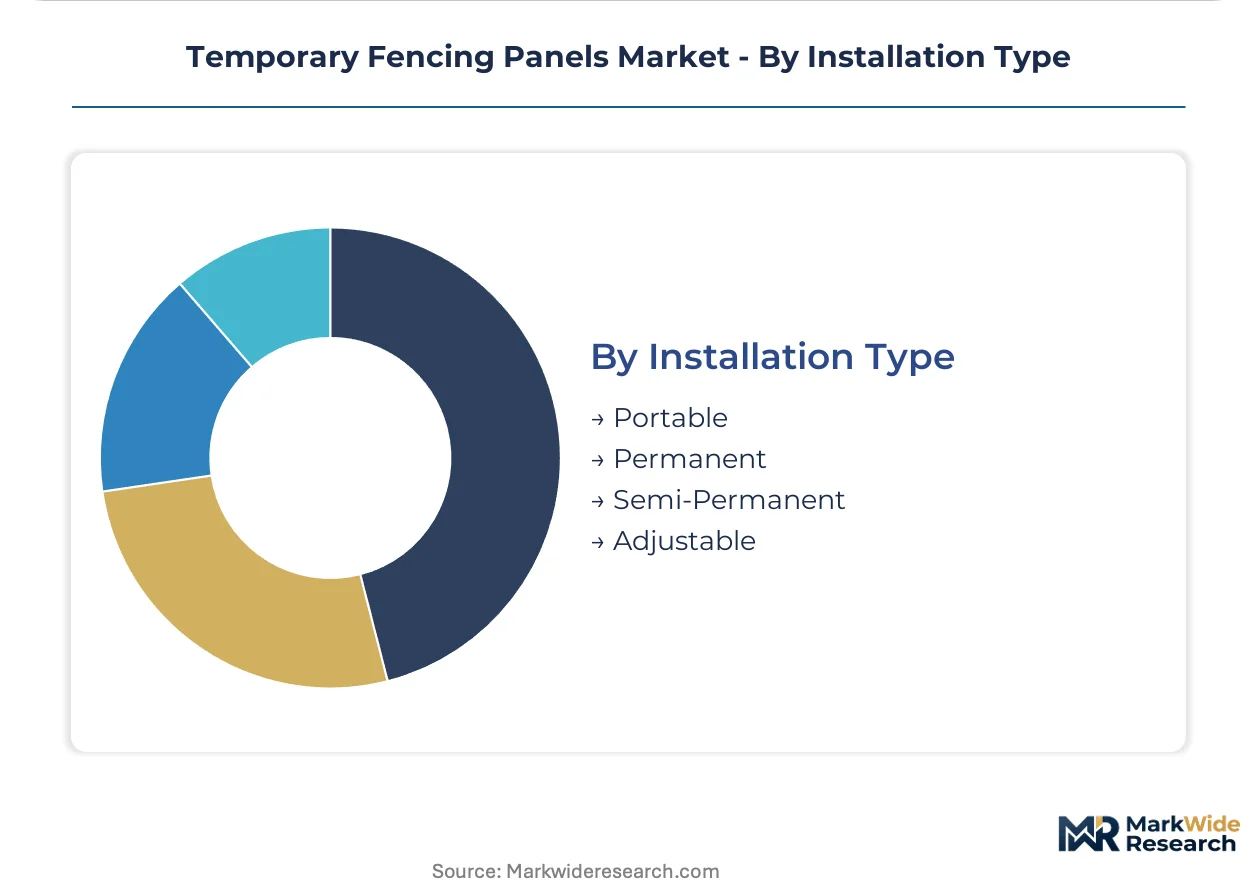
Installation Type:
Foundation requirements and redeployment velocity determine total cost of ownership, with portable systems commanding rental premiums that permanent installations amortize over extended tenures.
- Portable:Ballast-based systems without ground penetration enable same-day relocation on uneven terrain. OSHA lifting restrictions on concrete-filled bases constrain manual handling speeds, driving demand for composite ballast alternatives in the United States.
- Semi-Permanent:Surface-mounted anchoring with shallow footings suits seasonal construction phases and recurring event circuits where removal is planned but infrequent.
- Adjustable:Telescoping or modular height configurations accommodate variable security protocols across multi-phase infrastructure projects.
- Permanent:Deep foundation fencing intended for extended-duration deployment blurs category boundaries with permanent barrier markets.
Portable systems dominate rental fleet composition. Semi-Permanent configurations are gaining share fastest as multi-year infrastructure timelines lengthen deployment horizons.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The temporary fencing panels industry traces its modern industrial lineage to post-war European steel fabrication clusters, where German and British manufacturers pioneered modular barrier systems for reconstruction-era construction sites. These early fabrication networks established the galvanized steel welding protocols and portable ballast-base designs that now dominate procurement specifications across industrialized markets.
United States
Construction contractors in Texas and Florida are expanding steel-panel procurement for hurricane-resilient infrastructure projects. OSHA fall-protection mandates enforce continuous perimeter barriers on commercial builds exceeding six stories. Houston's energy corridor hosts rental fleet operators serving recurring petrochemical turnaround maintenance contracts.
Germany
Rhineland infrastructure authorities are accelerating panel replacement cycles under tightened EU Construction Products Regulation CE marking requirements. The country's national construction regulator mandates material traceability documentation for galvanized steel deployed on federal highway projects. Bavarian fabrication clusters around Nuremberg supply automated welding capacity for just-in-time delivery to multi-phase industrial builds.
Australia
Sydney and Melbourne event operators are converting aluminum-panel inventories for seasonal festival circuits where rapid relocation exceeds durability priorities. Work Health and Safety regulators in New South Wales impose additional public-safety standards for crowd-control barriers at high-attendance assemblies. Queensland mining contractors specify anti-climb mesh configurations for temporary worksite isolation during maintenance windows.
United Kingdom
Integrated mesh welding and powder-coating capacity in the Midlands serves municipal procurement for crash-rated temporary barriers at critical infrastructure sites. The country's building safety regulator incorporates total-life-cycle carbon metrics into tender evaluations for public-sector fencing contracts. London's event management firms are shifting toward multi-year rental agreements with RFID-tracked panel fleets.
Netherlands
Rotterdam port authorities are specifying K-rated fencing systems for temporary perimeter hardening around maritime logistics facilities. Dutch infrastructure procurement guidelines prioritize sustainability-mandated tenders with reduced lifecycle carbon thresholds for galvanized steel alternatives. Randstad region rental operators are deploying composite ballast alternatives to circumvent manual-handling weight restrictions on concrete-filled bases.
Temporary Fencing Panels Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification-tier and coating-technology dimensions. The vendor base stratifies into three tiers: integrated steel producers with captive galvanizing capacity, specialized mesh fabricators serving regional contractor networks, and rental fleet operators monetizing inventory through subscription-based tracking systems. Dominant competitive moves include backward integration into wire drawing and zinc-aluminum coating chemistries, plus geographic expansion through distributor footprint densification in high-infrastructure-spending states.
Among UK-based fabricators, ZND and Blok 'N' Mesh exemplify the integrated-production archetype with in-house welding and surface-treatment capacity. Betafence represents the continental European model of galvanized steel production networks scaled to meet EU certification thresholds. Master Halco anchors the North American distributor-centric positioning, serving contractor and municipal accounts through broad logistics coverage rather than captive manufacturing.
| Leading Market Players |
|---|
| Lion Fencing and Steel Supplies |
| MDWS Fence |
| ZND |
| Betafence |
| Fenceweb |
| Blok 'N' Mesh |
| Hoover Fence Company |
| Ameristar Perimeter Security |
| Master Halco |
| Others |
Value Chain & Pricing Dynamics
Backward integration into captive galvanizing capacity anchors both supply security and pricing power for steel-panel fabricators serving EU infrastructure tenders. German and British producers with in-house zinc-aluminum coating lines command premium positioning against distributor-dependent competitors exposed to hot-rolled steel price swings.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates CE-certified crash-rated systems from basic construction panels and plastic crowd-channeling units. Certification grade and volume scale drive price differentiation, with K-rated municipal specifications carrying 40-60% premiums over contractor-grade alternatives. Cost compression in the standard tier is intensifying because Chinese wire mesh imports undercut domestic welding operations. Contractor spot-buying shows highest price sensitivity, while municipalities with sustainability mandates accept lifecycle-cost premiums for low-carbon galvanized alternatives.
Supply Chain Analysis
Domestic-content mandates in German federal highway procurement are reshaping sourcing patterns, favoring Rhineland and Bavarian fabrication clusters over Benelux distributors. Supply concentrates in China for wire mesh feedstock, Germany and the United Kingdom for finished panel fabrication, and Australia for aluminum-frame rental fleets. Raw material dependencies rest on hot-rolled steel tubing, zinc for galvanizing baths, and aluminum extrusion billet. Single-source vulnerability in Chinese mesh supply creates tariff exposure and quality inconsistency risks. Distribution runs through specialized equipment rental operators and construction distributor networks serving contractor accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where OSHA fall-protection mandates and EU CE marking requirements continuously refresh replacement demand across infrastructure and event security applications.
For Market Incumbents: Lock in certification-tier positioning by securing AWS D1.1 welding qualifications ahead of peak construction seasons, while extending captive galvanizing capacity to offset zinc price volatility. RFID-tracked rental fleet investments defend against equipment-as-a-service disruptors in high-event-density markets like California and New South Wales. For New Entrants and Emerging Players: Capture the aluminum-panel conversion opportunity in Australian festival circuits where rapid relocation priorities exceed steel durability requirements. Composite ballast alternatives for OSHA manual-handling compliance represent the most penetrable white-space, with go-to-market traction through direct rental fleet partnerships rather than distributor channels. For Investors and Strategic Acquirers: Roll-up economics work for regional mesh fabricators with dormant CE marking capability because EU Construction Products Regulation enforcement is consolidating procurement toward certified suppliers. Mid-cap specialists with automated welding lines and municipal account relationships present acquisition targets. The signal to watch is German infrastructure tender specifications incorporating total-life-cycle carbon metrics, which will reprice low-carbon coating technologies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Galvanizing | Captive zinc-aluminum coating capacity insulates margins from REACH substance restriction compliance costs. |
| RFID Fleet Tracking Deployment | Subscription-based panel monitoring enables recurring revenue from event management firms in California. |
| Crash-Rated Certification Investment | K-rated and M-rated systems access municipal critical infrastructure protection budgets in Germany and the Netherlands. |
| Composite Ballast Development | Lightweight base alternatives circumvent OSHA lifting restrictions on concrete-filled systems in Texas and Florida. |
| Rental Fleet Geographic Expansion | Dedicated inventory pools in New South Wales capture seasonal festival circuit demand from spot procurement. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with construction procurement managers, municipal infrastructure planners, event rental fleet operators, and steel fabrication plant engineers with secondary validation through EU Construction Products Regulation filings, OSHA enforcement databases, customs trade records, and ACC steel shipment reports. Bottom-up panel shipment estimates from regional distributor networks were triangulated against top-down infrastructure spending projections.
Historical reference periods anchored volume and value outputs to pre-pandemic baseline construction activity, with the projection horizon extending across the analysis window. Segmentation dimensions modeled include material composition, deployment duration, procurement authority, and certification tier. CAGRs were derived from regression analysis of infrastructure spending correlation with panel replacement cycles, incorporating hot-rolled steel price indices and regulatory compliance cost trajectories as industry-specific forecast inputs.
Raw material price volatility, regulatory interpretation shifts, and event security protocol changes are the dominant revision risks for forecast trajectories. Forecasts reflect assumptions documented in the analytical framework without guarantee of realization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Construction
Portable Walls Market
Specialty Construction
Construction Repaint Market
Specialty Construction
Expandable Shelter Market
Specialty Construction
Asia-Pacific Anchors and Grouts Market
Specialty Construction
Indonesia Anchors and Grouts Market
Specialty Construction
Asia-Pacific Waterproofing Solutions Market
Specialty Construction
South America Anchors and Grouts Market
Specialty Construction
Welded Metal Bellows Market
Specialty Construction
Roller Shutter Market
Specialty Construction
Shotcrete Accelerators Market
Specialty Construction
Indonesia Waterproofing Solutions Market
Specialty Construction
India Anchors and Grouts Market
Specialty Construction
Europe Anchors and Grouts Market
Specialty Construction
Concrete and Cement Dissolver Market
Specialty Construction
ASEAN Waterproofing Market
Specialty Construction
Slab Repair Products Market