
 India Anchors and Grouts Market | 2026-2036
India Anchors and Grouts Market Size, Share, and Industry Trends Forecast 2026-2036
India Anchors and Grouts Market Insights
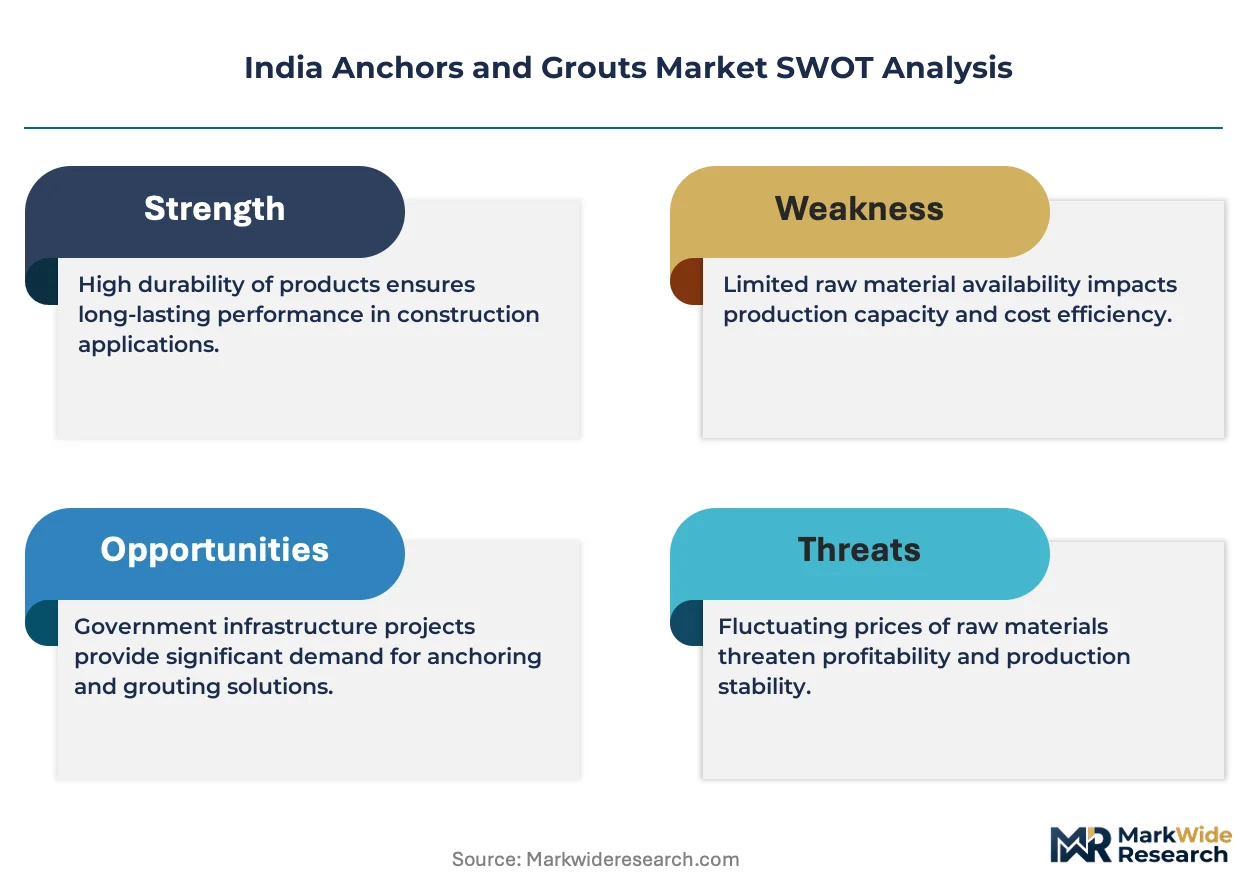
Multi-source procurement among EPC contractors is restructuring supply relationships across India's anchors and grouts sector. Sika AG leverages its technical service network to secure specification-led sales with infrastructure developers. MYK LATICRETE India anchors its position through localized manufacturing and deep distributor relationships in southern states. MAPEI S.p.A competes on formulation breadth, offering project-specific grout systems for seismic zones.
Anchors and grouts encompass mechanical and chemical fastening systems plus cementitious and epoxy-based fill materials engineered to bond loads exceeding 50 MPa into concrete, masonry, and rock substrates for structural reinforcement and equipment anchoring. Mechanical anchors dominate volume in standard construction applications where cost sensitivity prevails, while chemical anchors capture premium margins in critical infrastructure requiring seismic compliance and underwater curing. Grout materials lead absolute consumption in power plant and heavy machinery base-plate installations, with specialty grouts representing the fastest-expanding margin pool as precision tolerances tighten in metro rail and nuclear projects.
BIS mandates IS 2386 and IS 15622 compliance for structural anchors used in public works, compelling domestic formulation upgrades and third-party testing investments. The CDSCO framework governs epoxy resin imports for chemical anchors, creating import substitution incentives for local polymer blending capacity. State-level urban development authorities in Maharashtra and Tamil Nadu embed FOSROC-equivalent performance benchmarks into tender documents, effectively pre-qualifying multinational suppliers. Stakeholders must monitor evolving BIS harmonization with Eurocode 2 standards and assess captive resin synthesis versus imported epoxy economics before committing capacity expansion.
Market Dynamics
Multi-source procurement among EPC contractors is restructuring supply relationships across India's anchors and grouts sector, fragmenting long-standing distributor monopolies and forcing manufacturers to build direct technical service capabilities.
Growth Catalysts
- Metro Rail Expansion:Tunneling projects across Maharashtra and Gujarat are accelerating procurement of high-performance chemical anchors for seismic-compliant infrastructure.
- BIS Certification Mandates:IS 2386 and IS 15622 compliance requirements for structural fasteners are tightening product standards nationwide and upgrading domestic formulation quality.
- Polymer Blending Localization:CDSCO import substitution incentives for epoxy resin are driving captive synthesis investments and reducing foreign exchange exposure.
Market Restraints
- Epoxy Resin Import Dependency:CDSCO framework governs specialty polymer imports, creating supply bottlenecks and working capital intensity for chemical anchor producers.
- Western India Supply Concentration:Mumbai-Ahmedabad industrial corridor activity concentrates bulk orders with specialized contractors, leaving other regions underserved.
- Mechanical Anchor Price Floors:Cost-sensitive standard construction applications resist premium chemical systems despite performance advantages.
Strategic Opportunities
- Southern States Penetration:Tamil Nadu urban development authorities embed FOSROC-equivalent performance benchmarks into tenders, pre-qualifying suppliers with localized manufacturing.
- Nuclear Project Precision Grouts:Specialty grouts with sub-millimeter tolerance specifications represent expanding margin pools in power plant base-plate installations.
- Eurocode 2 Harmonization:Evolving BIS alignment with European structural standards creates export pathway development for compliant domestic manufacturers.
Industry Challenges
- Third-Party Testing Capacity:BIS compliance investments require extended certification timelines and qualified laboratory access that lags demand growth.
- Seismic Engineering Talent Scarcity:Project-specific grout system design for seismic zones requires specialized structural engineers in short supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Anchors and Grouts Market |
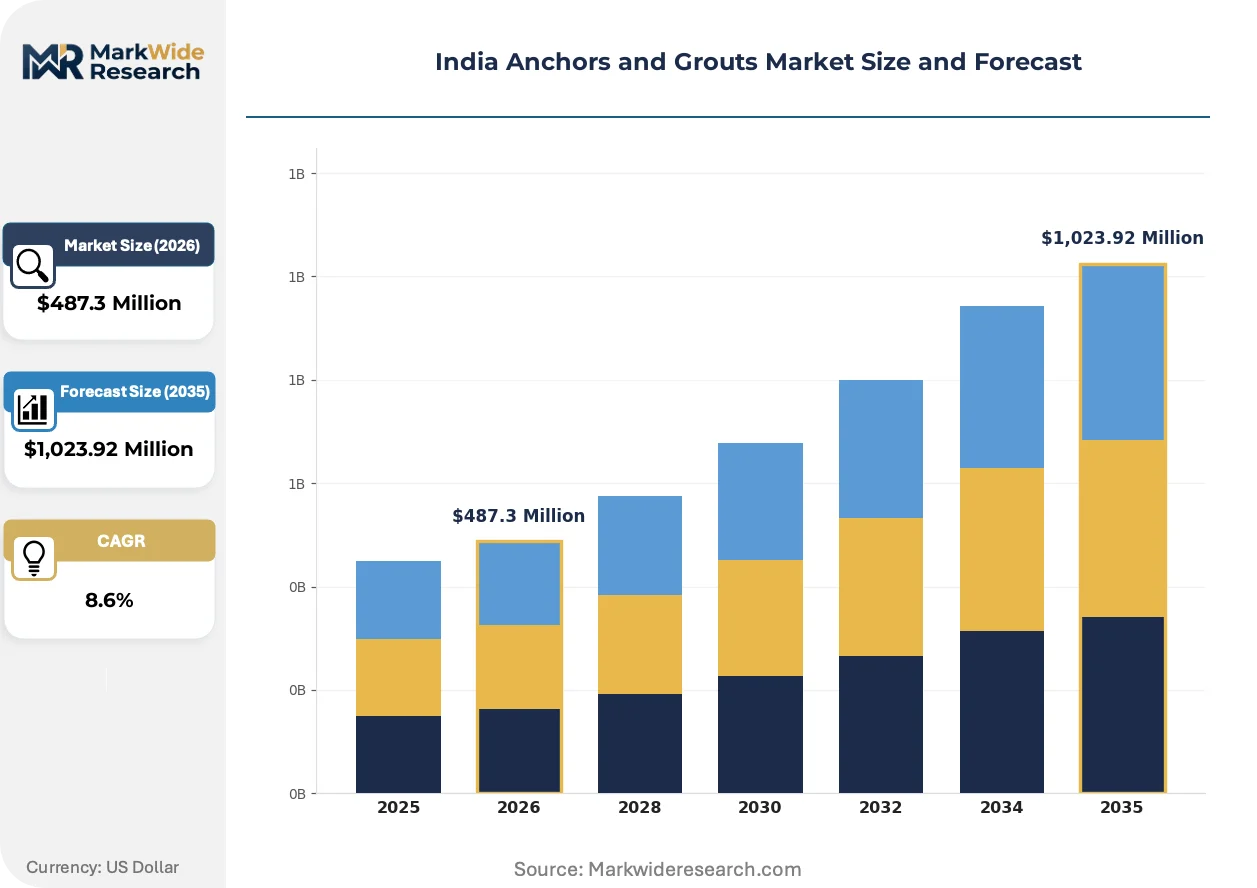
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Anchors, Chemical Anchors, Grout Materials, Specialty Grouts Application: Construction, Road Infrastructure, Marine Applications, Industrial Projects End User: Contractors, Engineers, Architects, Construction Companies Distribution Channel: Direct Sales, Distributors, Online Retail, Retail Outlets |
| Companies Covered | Saint-Gobain, Sika AG, MBCC Group, LATICRETE International Inc, Fosroc Inc, Ardex Group, MAPEI S.p.A, Thermax Limited, MYK LATICRETE India, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Anchors and Grouts Market Trends and Innovations
Formulation chemistry and specification-led selling are displacing commodity trading in India's anchors and grouts landscape. Technical service integration now determines contract capture.
Vinyl ester hybrid resins are rewriting performance benchmarks for underwater and high-moisture curing applications. Coastal infrastructure contractors in Gujarat are specifying these systems for jetty and marine pile anchoring. The technology is compressing the addressable market for traditional epoxy grouts in critical infrastructure segments.
BIS harmonization with Eurocode 2 standards is mandating pull-out testing protocols and traceability documentation for structural anchors used in public works. This regulatory friction is elevating compliance costs for smaller domestic blenders. Maharashtra state urban development authorities are embedding these standards into metro rail tender documents ahead of national adoption.
Specification-led procurement is consolidating buying power among tier-one EPC contractors with in-house engineering capabilities. Regional distributors are losing ground to manufacturers offering embedded technical support during project design phases. This channel compression is most visible in western India, where Mumbai-Ahmedabad corridor projects demand direct manufacturer involvement.
India Anchors and Grouts Market Segmentation
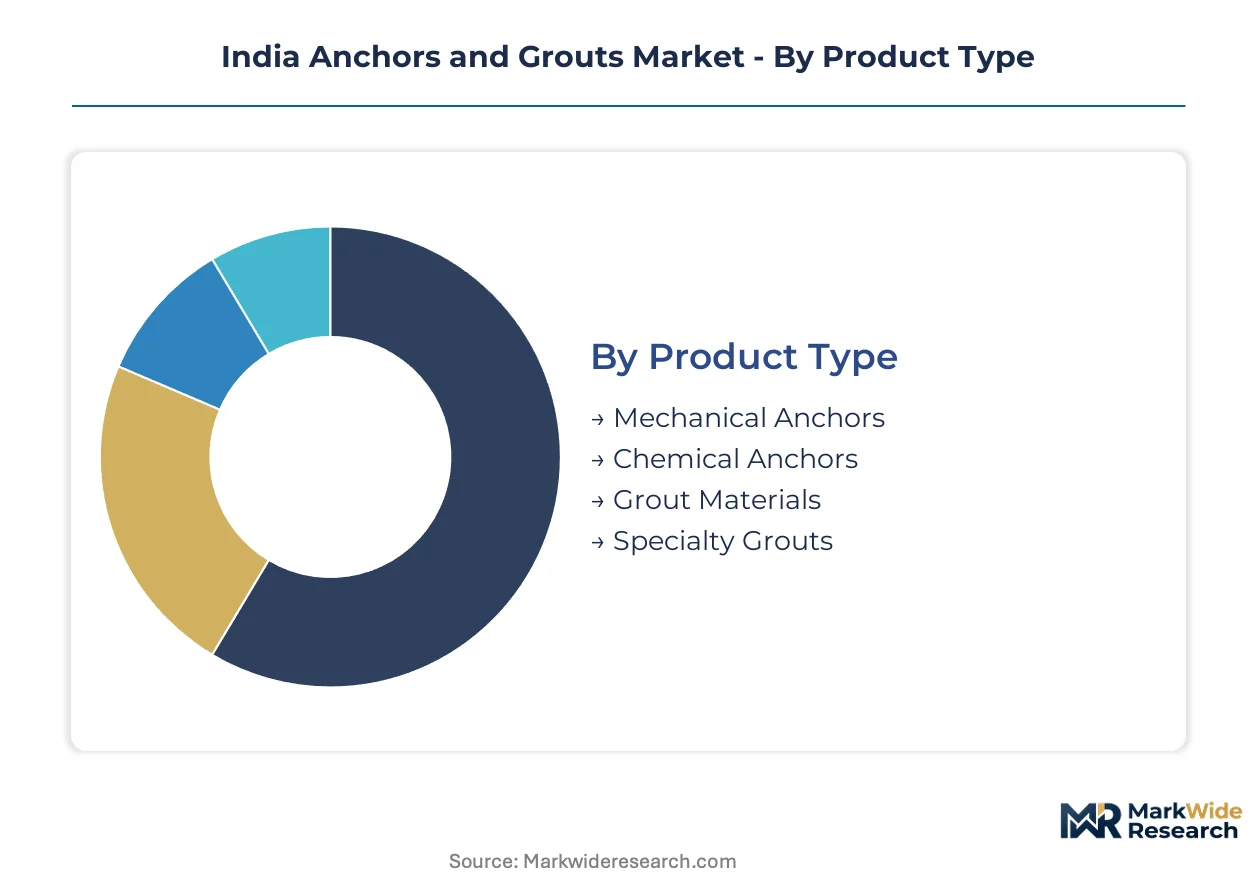
Segmentation in India's anchors and grouts sector reveals how specification complexity, procurement authority, and channel economics fragment addressable value pools. Understanding these divisions exposes where technical selling outperforms commodity trading.
Product Type:
Performance specifications and substrate requirements divide the product landscape into distinct technical tiers with divergent margin structures.
- Mechanical Anchors:Expansion and undercut designs in carbon steel and stainless steel configurations deliver immediate load-bearing without curing delays. Standard construction applications across cost-sensitive housing projects in tier-2 cities drive volume procurement, though price floors resist premium migration despite BIS compliance upgrades.
- Chemical Anchors:Epoxy, vinyl ester, and hybrid resin systems bonded into drilled holes achieve seismic-compliant performance exceeding 50 MPa pull-out strength. Metro rail tunneling projects in Maharashtra and Gujarat specify these systems for critical infrastructure, capturing premium margins through underwater curing capabilities and CDSCO-regulated polymer formulations.
- Grout Materials:Cementitious and epoxy-based fills for machinery base plates and structural voids.
- Specialty Grouts:Sub-millimeter tolerance formulations for nuclear power plant installations and precision equipment anchoring.
Mechanical anchors lead on scale; specialty grouts lead on momentum.
Application:
Project scale and regulatory scrutiny create divergent customer acquisition economics across end-use environments.
- Construction:High-rise commercial and residential structures requiring structural reinforcement and facade anchoring systems. Mumbai-Ahmedabad corridor activity concentrates bulk orders with specialized contractors capable of BIS IS 2386 documentation.
- Road Infrastructure:Bridge expansion joints, signage anchoring, and crash barrier installations. State public works departments in Tamil Nadu embed FOSROC-equivalent performance benchmarks into tender specifications, pre-qualifying suppliers with localized manufacturing footprints.
- Marine Applications:Jetty piles, coastal defense structures, and port equipment anchoring exposed to saltwater corrosion.
- Industrial Projects:Heavy machinery installation and power plant base-plate grouting requiring precision tolerances.
Road infrastructure commands procurement volume; marine applications expand most quickly on vinyl ester hybrid adoption.
End User:
Technical decision authority and specification influence determine supplier relationship intensity across buyer types.
- Contractors:Execution-focused purchasers prioritizing installation speed and material availability. Multi-source procurement patterns among EPC contractors fragment long-standing distributor monopolies, forcing manufacturers to embed technical service capabilities directly.
- Engineers:Specification authors controlling anchor selection through structural calculations and pull-out testing protocols. BIS harmonization with Eurocode 2 standards elevates their influence in public works procurement.
- Architects:Aesthetic and spatial integration requirements for exposed anchoring systems.
- Construction Companies:Integrated developers with captive procurement functions and volume leverage.
Contractors dominate transaction volume; engineers control specification-led margin capture.
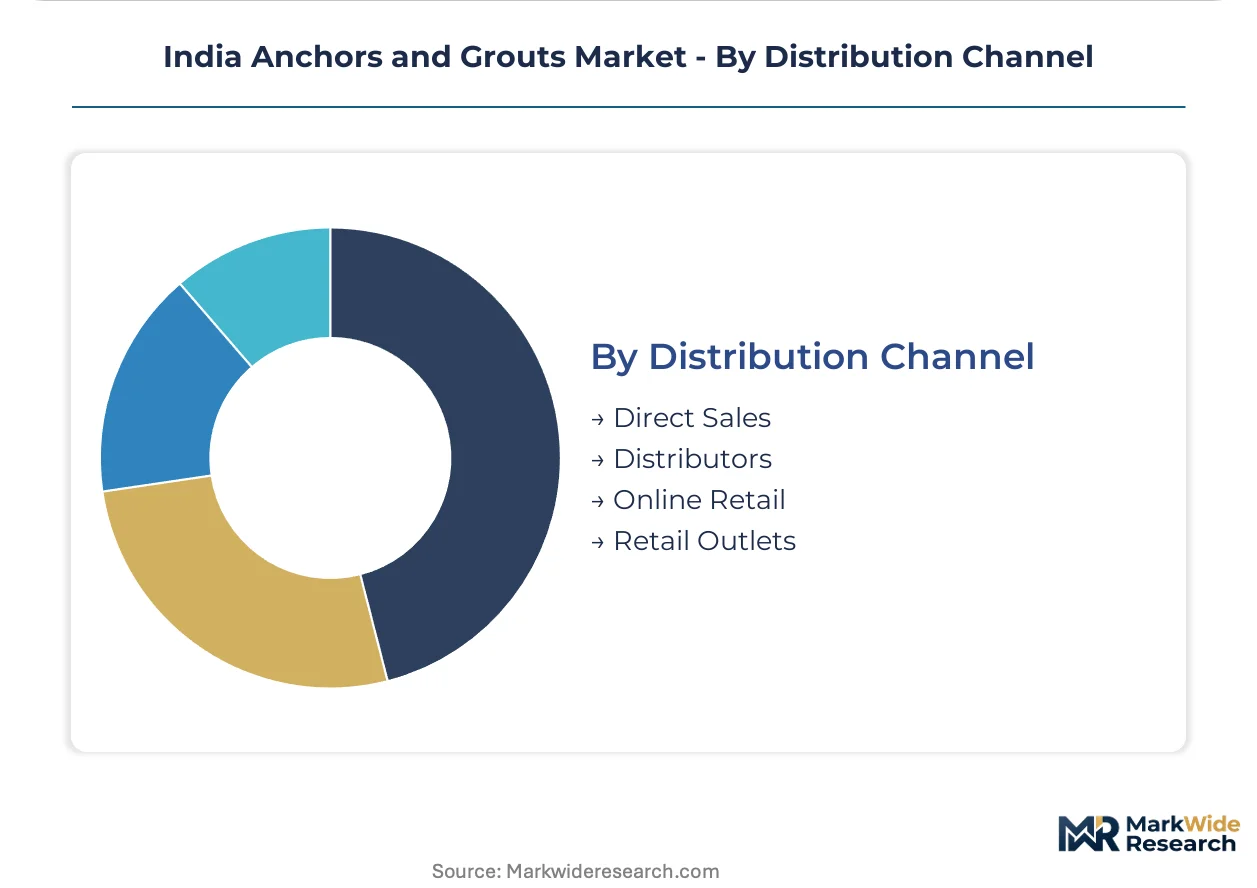
Distribution Channel:
Channel configuration determines working capital intensity and technical service reach across customer touchpoints.
- Direct Sales:Manufacturer-employed technical representatives engaging EPC contractors during project design phases. Western India corridor projects demand this channel for seismic engineering support and BIS compliance documentation.
- Distributors:Regional inventory holders with localized logistics and credit extension. Southern states penetration relies on deep distributor relationships for contractor access outside metro rail corridors.
- Online Retail:Digital platforms serving small contractors and maintenance applications with standardized mechanical anchors.
- Retail Outlets:Counter sales for emergency replacement and small-scale construction in tier-3 cities.
Distributors retain volume leadership; direct sales gains share fastest on specification complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as domestic producers exploit BIS compliance cost gaps against import-dependent competitors. Maharashtra and Gujarat dominate procurement volumes, while southern states attract localized formulation investments.
Maharashtra
Mumbai-Ahmedabad industrial corridor projects and metro rail tunneling drive chemical anchor procurement at scale. State urban development authorities embed Eurocode 2-aligned pull-out testing protocols into public tenders ahead of national BIS adoption. Mumbai-Pune manufacturing clusters host captive epoxy blending facilities serving western infrastructure demand.
Gujarat
Coastal infrastructure and port modernization accelerate vinyl ester hybrid resin specification for marine pile anchoring. CDSCO import substitution incentives support local polymer synthesis investments reducing foreign exchange exposure. Hazira-Surat industrial belt concentrates specialty grout production for precision machinery installations.
Tamil Nadu
State public works departments embed FOSROC-equivalent performance benchmarks into road infrastructure tenders, pre-qualifying suppliers with manufacturing presence. Chennai-Coimbatore corridor attracts distributors building deep contractor relationships outside metro rail concentrations. Urban development authorities mandate seismic-compliant anchoring for high-rise commercial construction.
Karnataka
Bengaluru metro expansion and data center construction drive demand for precision grouting systems with sub-millimeter tolerances. State industrial policy incentives support technical service capabilities for specification-led procurement. Peenya industrial area hosts mechanical anchor fabrication serving cost-sensitive tier-2 construction markets.
Delhi-NCR
National capital region infrastructure projects concentrate engineering specification authority for structural fasteners. Central government public works departments enforce IS 2386 and IS 15622 compliance documentation requirements. Faridabad-Ghaziabad manufacturing belt supplies standardized mechanical anchors for northern housing construction.
India Anchors and Grouts Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specification-led technical service capabilities to capture premium infrastructure contracts. Market structure fragments across multinational formulation specialists, domestic manufacturing licensees, and regional distribution networks. Three archetypes dominate: global chemical companies with localized blending, Indian manufacturing joint ventures with technical service depth, and regional distributors pivoting toward direct contractor engagement. Competitive intensity concentrates on BIS certification speed and seismic engineering talent acquisition.
Among multinational specialists, Sika AG and MAPEI S.p.A exemplify the specification-led archetype through embedded technical service networks. MYK LATICRETE India represents the domestic manufacturing joint venture model combining localized production with southern states distribution depth. These three anchors illustrate how competitive positioning separates premium chemical system providers from commodity mechanical anchor suppliers.
| Leading Market Players |
|---|
| Saint-Gobain |
| Sika AG |
| MBCC Group |
| LATICRETE International Inc |
| Fosroc Inc |
| Ardex Group |
| MAPEI S.p.A |
| Thermax Limited |
| MYK LATICRETE India |
| Others |
Pricing and Supply Chain Analysis
Epoxy resin import indices and domestic vinyl ester pricing cascades through India's anchors and grouts supply chain into three distinct procurement tiers. CDSCO-regulated polymer costs compress margins for chemical anchor producers while BIS certification investments elevate entry thresholds, concentrating pricing power among formulation specialists with captive blending capacity.
Pricing Analysis
Input-cost pass-through from specialty polymer imports governs pricing dynamics across the sector. Three-tier pricing structure across premium, standard, and economy levels separates seismic-compliant chemical systems from mechanical anchors and commodity-grade cementitious grouts. Price differentiation hinges on BIS IS 2386 certification grade and volume scale, with metro rail contractors showing least sensitivity due to specification mandates. Pricing pressure stems from CDSCO import bottlenecks and working capital intensity for epoxy-dependent producers.
Supply Chain Analysis
Epoxy resin supply rests on South Korean, German, and Chinese specialty chemical producers, with domestic blending capacity concentrated in Maharashtra and Gujarat. Raw material dependencies span vinyl ester monomers, amine hardeners, and high-grade silica fillers. Single-source vulnerability around pharmaceutical-grade epoxy imports creates structural exposure to CDSCO regulatory delays. Distribution runs through regional distributors in southern states and direct technical service teams for western corridor projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in India's anchors and grouts sector derives from vinyl ester hybrid localization and specification-led premium tier migration away from commodity mechanical anchors.
For Market Incumbents: Extend technical service networks into Tamil Nadu and Karnataka to preempt FOSROC-equivalent tender pre-qualification. Build backward integration into amine hardener synthesis to reduce CDSCO import exposure. Defend against emerging domestic blenders by accelerating BIS certification speed for seismic-grade systems. For New Entrants and Emerging Players: Capture precision grout opportunities in Bengaluru data center and nuclear power plant installations where sub-millimeter tolerance specifications command premium positioning. Target southern states road infrastructure tenders embedding performance benchmarks that favor localized manufacturing footprints. Lead with specification-led selling during engineer design phases rather than distributor price competition. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic manufacturers possessing captive polymer blending and BIS certification infrastructure. Long-term viability centers on Eurocode 2 harmonization readiness and export pathway development. Watch CDSCO import substitution policy acceleration as the inflection signal for local capacity valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Synthesis | CDSCO import substitution incentives reward captive polymer production with reduced foreign exchange exposure. |
| BIS Certification Acceleration | IS 2386 and IS 15622 compliance speed determines specification capture in Maharashtra metro rail tenders. |
| Technical Service Network Expansion | Direct engineer engagement during design phases displaces distributor-dependent procurement in western India. |
| Vinyl Ester Hybrid Capacity Buildout | Coastal infrastructure specifications in Gujarat favor underwater curing systems over traditional epoxy grouts. |
| Southern States Distribution Depth | Tamil Nadu and Karnataka tender structures pre-qualify suppliers with localized manufacturing presence. |
Research Methodology
Coverage spans Maharashtra, Gujarat, Tamil Nadu, Karnataka, and Delhi-NCR, with primary inputs from each region's infrastructure development authorities. Primary interviews with EPC contractor procurement heads, structural engineering consultants, BIS certification laboratory directors, and polymer blending plant managers combined with secondary validation from CDSCO import records, state public works department tender documents, and BIS standard harmonization notifications. Bottom-up project pipeline aggregation and top-down sectoral spend analysis provided triangulation.
Rate-of-change decomposition across metro rail capital expenditure trajectories, industrial corridor investment schedules, and BIS adoption timelines anchored the forecasting framework. Segmentation modeling spanned product type, application environment, end-user procurement authority, and distribution channel configuration. CAGRs derived from weighted average of project-based demand curves and replacement cycle assumptions. Industry-specific inputs included epoxy resin import volume trends and state-level urban development authority expenditure commitments.
Polymer price volatility, BIS certification timeline extensions, and state election cycles affecting infrastructure procurement are the dominant revision risks to forecast assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Construction
Europe Anchors and Grouts Market
Specialty Construction
Asia-Pacific Waterproofing Solutions Market
Specialty Construction
Global Fencing Market
Specialty Construction
Welded Metal Bellows Market
Specialty Construction
South America Anchors and Grouts Market
Specialty Construction
Construction Repaint Market
Specialty Construction
Expandable Shelter Market
Specialty Construction
Composite Repair Market
Specialty Construction
Slab Repair Products Market
Specialty Construction
Roller Shutter Market
Specialty Construction
Indonesia Waterproofing Solutions Market
Specialty Construction
Temporary Fencing Panels Market
Specialty Construction
Fire Hydrants Market
Specialty Construction
Shotcrete Accelerators Market
Specialty Construction
Concrete and Cement Dissolver Market
Specialty Construction
Portable Walls Market