
 Expandable Shelter Market | 2026-2036
Expandable Shelter Market Size, Share, and Industry Trends Forecast 2026-2036
Expandable Shelter Market Insights
Aftermarket service revenue for field repair, redeployment logistics, and lifecycle refurbishment is rewriting margin allocation across the expandable shelter value chain. HDT Global leverages its integrated manufacturing and field-support infrastructure to sustain long-term defense contracts. General Dynamics Corporation anchors its position through scale production of military-grade rigid-frame systems. Saab AB competes in Nordic and broader European defense procurement with specialized cold-climate shelter solutions.
Expandable shelters are transportable, rapidly deployable enclosures engineered with aluminum or composite frame structures, tensioned fabric membranes, and integrated climate-control interfaces, designed to expand from compact transit volumes into functional occupied spaces for military, medical, or industrial use. Modular shelters command the largest installed base due to their reconfigurability across mission profiles, while inflatable technology represents the fastest-expanding segment as defense forces prioritize reduced logistical footprints and helicopter-portable weights. Mechanical linkage systems retain dominance in permanent-leaning construction site applications where structural longevity outweighs speed of deployment.
The U.S. Department of Defense mandates MIL-STD-810 environmental testing and MIL-PRF-32505 performance specifications for all expeditionary shelter acquisitions, while NATO's STANAG 4370 standardizes climatic and mechanical interoperability across allied force procurements. The EU Green Deal's embodied-carbon tracking requirements and REACH chemical compliance for fabric coatings are reshaping supplier qualification criteria for European defense and humanitarian tenders. Stakeholders must monitor evolving sustainability mandates alongside operational performance benchmarks as procurement evaluation weights shift.
Market Dynamics
Defense procurement agencies are consolidating vendor pools around integrated lifecycle service capabilities, compressing contract structures from discrete equipment purchases into decade-long performance partnerships that bundle manufacturing, field deployment, and refurbishment obligations.
Growth Catalysts
- NATO STANAG 4370:Standardized climatic and mechanical interoperability requirements across allied force procurements are eliminating fragmented national specifications, enabling cross-border tender participation and scale manufacturing efficiencies.
- Helicopter-portable inflatable systems:Reduced logistical footprints and sub-ton deployment weights are displacing rigid-frame alternatives in rapid-response medical and command applications.
- Forward operating base infrastructure:Persistent expeditionary posture requirements in contested logistics environments are mandating shelters with sub-30-minute deployment timelines and integrated CBRN protection.
Market Restraints
- Aluminum alloy price volatility:Frame material cost swings tied to energy-intensive smelting operations in China and Russia are compressing fabrication margins and triggering contract renegotiation clauses.
- Specialized fabric coating supply concentration:PVDF and silicone-coated textile production clusters in Germany and Japan create single-source vulnerability for climate-resistant membrane procurement.
- MIL-STD-810 certification timelines:Extended environmental testing protocols for sand, dust, and thermal shock resistance delay new entrant market access by 18-24 months.
Strategic Opportunities
- Humanitarian response tenders:United Nations Office for the Coordination of Humanitarian Affairs procurement frameworks for rapid-deployment medical facilities in conflict zones represent underpenetrated demand outside traditional defense channels.
- EU Green Deal embodied-carbon tracking:REACH-compliant low-VOC coating formulations and recyclable membrane materials unlock preferential scoring in European defense and civil protection tenders.
- Containerized hybrid systems:Convergence of ISO shipping container logistics with pneumatic expansion mechanisms enables seamless multimodal transport across road, rail, and sea networks.
Industry Challenges
- Composite fabrication technician scarcity:Specialized workforce for automated fiber placement and resin transfer molding of structural frame components limits production scaling.
- Legacy climate-control integration:Field retrofitting of HVAC and power distribution interfaces with existing shelter inventories demands customized engineering and extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Expandable Shelter Market |
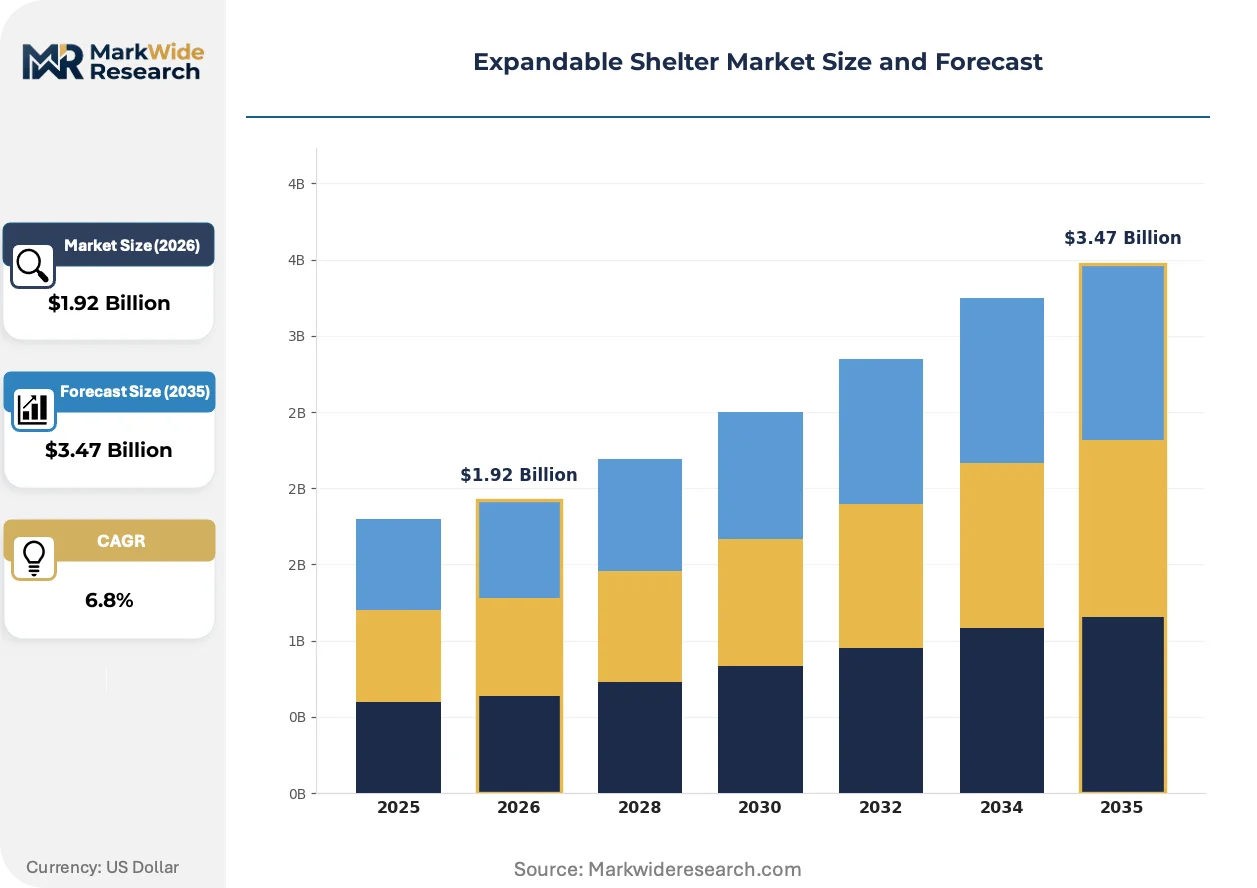
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $3.47 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foldable Tents, Retractable Barracks, Modular Shelters, Collapsible Cabins, Telescopic Covers Technology: Inflatable, Rigid Frame, Fabric Composite, Pneumatic, Mechanical Linkage Application: Military Camps, Disaster Relief, Field Hospitals, Construction Sites, Event Hosting End User: Defense Forces, Humanitarian Agencies, Mining Operations, Research Stations, Outdoor Recreation |
| Companies Covered | HDT Global, General Dynamics Corporation, AAR Corp., UTS Systems, Saab AB, Weatherhaven Global Resources Ltd, Alaska Structures, Rubb Buildings Ltd, Losberger GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Expandable Shelter Market Trends and Innovations
Active digitization of shelter monitoring and control systems is compressing the gap between static infrastructure and connected expeditionary platforms, enabling predictive maintenance and remote environmental management.
Embedded sensor networks are digitizing structural health monitoring, power consumption tracking, and climate system performance in real time. U.S. Army Rapid Capabilities and Critical Technologies Office procurement specifications now mandate IoT-enabled shelters for contested logistics environments. This connectivity layer is digitizing traditional aftermarket service models, shifting vendor revenue from reactive repair to subscription-based performance guarantees.
EU Green Deal embodied-carbon disclosure requirements and REACH chemical restrictions on perfluorinated compounds are forcing coating chemistry reformulation across European supply chains. Fabric membrane suppliers must now submit lifecycle carbon footprints and substitution plans for legacy waterproofing treatments. Nordic defense procurement agencies have adopted the strictest interpretation, disqualifying tenders lacking third-party verified environmental product declarations.
Consolidated multi-year performance contracts are displacing transactional equipment purchases across NATO member defense agencies. Buyers now bundle manufacturing, field support, and end-of-life refurbishment into single vendor relationships, transferring operational risk to suppliers. Germany's Federal Office of Bundeswehr Equipment, Information Technology and In-Service Support has pioneered this structure, with the United Kingdom's Defence Equipment and Support following in 2024 framework agreements.
Expandable Shelter Market Segmentation
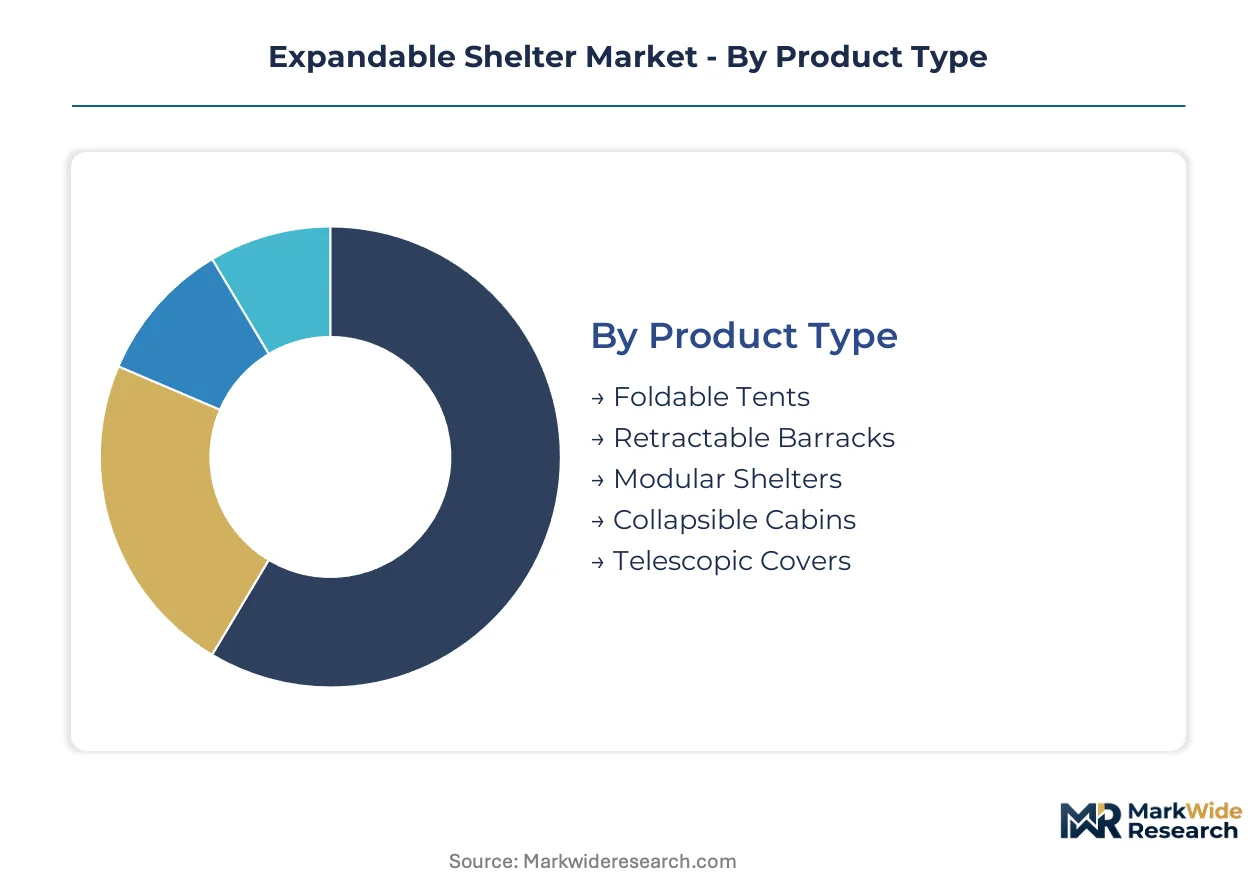
Expandable shelter procurement flows through distinct technical and operational channels, each with divergent performance specifications and vendor qualification requirements. Segmentation reveals where capital concentrates and which technology trajectories command investment priority.
Product Type:
Cost tier stratification separates expeditionary rapid-deployment units from permanent-leaning infrastructure investments.
- Modular Shelters:Aluminum or composite frame systems with reconfigurable panel interfaces dominate NATO forward operating base procurement. U.S. Department of Defense Modular Force policy mandates interoperable dimensions across command, medical, and logistics variants.
- Inflatable Systems:Tensioned fabric membranes supported by pneumatic pressure achieve sub-ton helicopter-portable weights. German Bundeswehr rapid-response medical units prioritize these for sub-30-minute deployment timelines in contested logistics environments.
- Foldable Tents:Traditional pole-supported designs retain position in humanitarian stockpiles where cost minimization outweighs speed requirements.
- Retractable Barracks:Sliding frame mechanisms optimize footprint efficiency in semi-permanent military housing installations.
- Collapsible Cabins:Rigid-wall folding systems serve research stations requiring thermal insulation performance beyond fabric alternatives.
- Telescopic Covers:Extendable hard-shell enclosures protect construction equipment in European industrial zones with severe weather exposure.
Modular shelters command the established base. The steepest expansion runs through inflatable systems.
Technology:
Application environment dictates material selection between pneumatic speed and structural longevity trade-offs.
- Mechanical Linkage:Articulated aluminum or steel frame joints deliver load-bearing capacity for construction site shelters where crane-assisted deployment is acceptable. United Kingdom Defence Equipment and Support specifications favor these for semi-permanent base infrastructure.
- Fabric Composite:Silicone-coated high-tenacity polyester or aramid laminates balance weight and durability in Nordic cold-climate operations. Saab AB specializes in STANAG 4370-compliant variants for Swedish and Finnish defense procurement.
- Inflatable:Air-beam or constant-pressure architectures eliminate rigid frame mass for medical and command applications requiring rotary-wing transport.
- Rigid Frame:Welded aluminum truss systems anchor permanent-leaning installations with decades-long service life expectations.
- Pneumatic:Hybrid air-cell and tensioned membrane designs enable rapid volume expansion from compact ISO container footprints.
Mechanical linkage retains the largest installed capacity. Fabric composite solutions are climbing the fastest as cold-climate specifications tighten.
Application:
Customer mission profile determines deployment speed requirements and integrated system complexity.
- Military Camps:Forward operating base infrastructure demands MIL-STD-810 environmental resilience and CBRN protection integration. NATO STANAG 4370 standardization enables cross-border equipment pooling among allied forces.
- Field Hospitals:Medical shelter procurement emphasizes HVAC filtration, surgical lighting compatibility, and rapid sterilization turnaround. UN Office for the Coordination of Humanitarian Affairs frameworks represent expanding non-defense demand.
- Disaster Relief:Stockpiled rapid-deployment units require compatibility with mixed-modal logistics across road, rail, and air networks.
- Construction Sites:Weather protection shelters prioritize structural longevity over deployment speed in European civil engineering contracts.
- Event Hosting:Temporary hospitality structures emphasize aesthetic finish and climate comfort for commercial rental operators.
Military camps anchor procurement volume. Field hospitals are gaining share fastest as expeditionary medical capabilities expand.
End User:
Volume concentration and margin structure diverge sharply between sovereign defense budgets and commercial industrial purchasers.
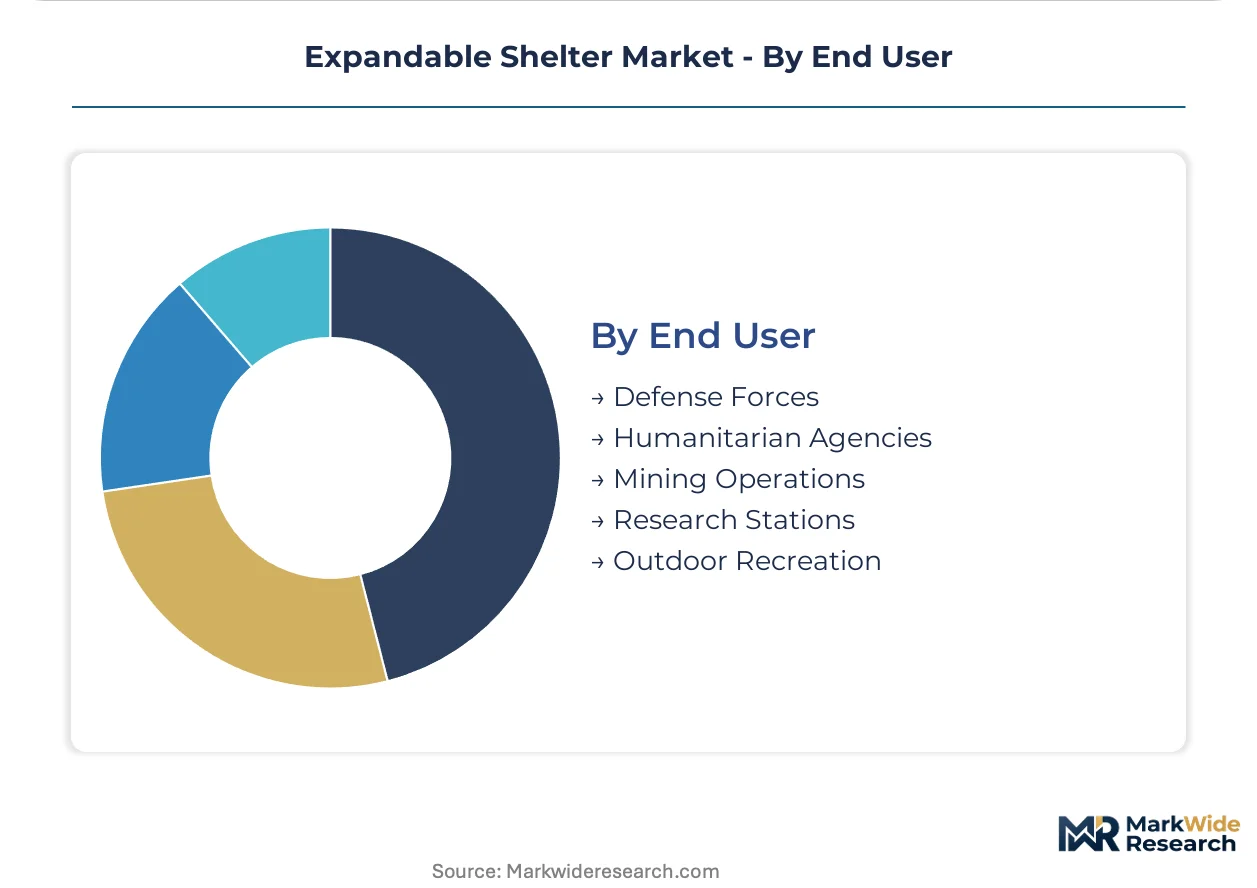
- Defense Forces:Multi-year performance contracts bundle manufacturing, field support, and lifecycle refurbishment. Germany's Federal Office for Bundeswehr Equipment pioneered this consolidated procurement structure.
- Humanitarian Agencies:UN and Red Cross procurement frameworks prioritize cost efficiency and rapid global pre-positioning over advanced technical specifications.
- Mining Operations:Remote site infrastructure in Australia and Canada demands extreme climate resilience for workforce housing.
- Research Stations:Antarctic and Arctic scientific outposts require specialized thermal performance beyond standard military specifications.
- Outdoor Recreation:Commercial camping and glamping operators drive demand for premium aesthetic finishes in European leisure markets.
Defense forces control the dominant revenue share. Humanitarian agencies are expanding most quickly as conflict-zone medical infrastructure investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between expeditionary military procurement in NATO economies and humanitarian stockpiling in conflict-adjacent regions. Helicopter-portable inflatable systems dominate allied defense budgets, while modular rigid-frame shelters anchor European construction and mining applications.
United States
Department of Defense Modular Force policy drives standardization across command, medical, and logistics shelter variants. MIL-STD-810 environmental testing mandates compress vendor qualification timelines. Huntsville, Alabama hosts concentrated defense contractor engineering clusters serving expeditionary base infrastructure programs.
Germany
Bundeswehr rapid-response medical units prioritize sub-30-minute deployment specifications for forward surgical teams. The Federal Office for Bundeswehr Equipment pioneered decade-long performance contracts bundling manufacturing with field support. Bavaria shelters specialized cold-climate shelter fabricators supplying Nordic defense procurement.
United Kingdom
Defence Equipment and Support framework agreements consolidated multi-year shelter procurement starting in 2024. STANAG 4370 interoperability compliance enables cross-border equipment pooling with allied forces. South West England maintains legacy rigid-frame production capacity for semi-permanent base infrastructure.
Sweden
Swedish defense procurement prioritizes arctic-rated fabric composite solutions under tightening climatic specifications. Nordic environmental product declaration requirements exceed baseline EU Green Deal thresholds. Stockholm anchors specialized membrane engineering clusters serving Finnish and Norwegian allied tenders.
Australia
Remote mining operations in Western Australia and Queensland drive demand for extreme climate resilience in workforce housing. The country's national defense procurement agency integrates expeditionary shelter requirements with regional humanitarian response stockpiles. Perth hosts maintenance and refurbishment hubs serving Indo-Pacific deployment logistics.
Expandable Shelter Market Competitive Landscape
Capability concentration sits with integrated lifecycle service providers; scale advantage sits with defense prime contractors manufacturing standardized rigid-frame systems. The vendor base stratifies around three archetypes: full-service defense contractors bundling field support, specialized climate-rated fabricators, and regional rapid-deployment specialists. Consolidation pressures favor multi-year performance partnerships over transactional equipment sales. Geographic expansion through NATO cross-border tender participation and backward integration into membrane coating supply represent dominant competitive vectors.
Within the integrated service tier, HDT Global exemplifies the bundled manufacturing and field-support model sustaining long-term defense relationships. General Dynamics Corporation occupies a position anchoring scale production of military-grade rigid-frame systems. Saab AB represents the specialized cold-climate archetype competing in Nordic and broader European defense procurement frameworks. These three anchors illustrate how vendor positioning diverges across capability depth, production scale, and regional climatic specialization.
| Leading Market Players |
|---|
| HDT Global |
| General Dynamics Corporation |
| AAR Corp. |
| UTS Systems |
| Saab AB |
| Weatherhaven Global Resources Ltd |
| Alaska Structures |
| Rubb Buildings Ltd |
| Losberger GmbH |
| Others |
Pricing and Supply Chain Analysis
PVDF and silicone-coated textile production concentration in Germany and Japan creates single-source vulnerability that compresses procurement options across both premium military-grade and standard commercial tiers while forcing buyers toward multi-year offtake structures to secure membrane allocation.
Pricing Analysis
Long-term performance contracts now dominate defense procurement, displacing spot equipment purchases with decade-long partnerships bundling manufacturing, field support, and lifecycle refurbishment. Three-tier pricing structure across expeditionary rapid-deployment, semi-permanent base infrastructure, and commercial industrial levels separates MIL-STD-810 certified systems from STANAG 4370 compliant variants and uncertified commercial alternatives. Cost compression in aluminum alloy frame fabrication is intensifying because energy-intensive smelting operations in China and Russia drive material price volatility. Humanitarian agencies exhibit the highest price sensitivity, prioritizing cost efficiency over advanced technical specifications, while defense forces accept premium pricing for integrated CBRN protection and sub-30-minute deployment capabilities.
Supply Chain Analysis
Tariff exposure between China and NATO member states dominates raw material cost planning for aluminum alloy frame components and specialized fabric coatings. Production gravity centers on Germany for PVDF membrane coatings, Japan for silicone-treated high-tenacity polyester, and China for aluminum alloy extrusions. Frame fabrication draws from energy-intensive smelting operations, tensioned fabric membranes rely on fluoropolymer chemistry, and climate-control interfaces hinge on semiconductor-dependent HVAC components. Single-source vulnerability for climate-resistant membrane procurement creates supply chain risk that triggers contract renegotiation clauses during price spikes. Distribution runs through defense prime contractor networks for military end-users, UN procurement frameworks for humanitarian agencies, and regional equipment rental channels for commercial construction applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as NATO defense procurement agencies consolidate vendor pools around integrated lifecycle service providers, compressing contract structures and transferring operational risk to suppliers.
For Market Incumbents: Entrench position through backward integration into membrane coating supply chains and captive production of aluminum alloy frame components in Germany or Japan to eliminate single-source dependency. Invest in REACH-compliant low-VOC coating formulations to capture preferential scoring in European tenders as Nordic agencies tighten environmental product declaration requirements. Expand field-support infrastructure in Huntsville, Alabama and Perth, Australia to sustain long-term defense relationships against emerging rapid-deployment specialists. For New Entrants and Emerging Players: Establish a beachhead in UN Office for the Coordination of Humanitarian Affairs procurement frameworks for rapid-deployment medical facilities, where traditional defense contractors maintain limited presence. Target containerized hybrid systems converging ISO shipping container logistics with pneumatic expansion mechanisms, as this segment lacks established incumbents and enables seamless multimodal transport credentials. Lead with subscription-based performance guarantees rather than transactional equipment sales to align with consolidating procurement patterns. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated lifecycle service providers with field-support infrastructure over pure manufacturing plays. Five-to-ten year viability hinges on positioning within NATO multi-year performance contract structures rather than spot procurement exposure. Target acquisition archetypes include specialized cold-climate fabricators with STANAG 4370 compliance and regional rapid-deployment specialists with UN framework access. Watch for inflection signals in EU Green Deal embodied-carbon disclosure enforcement, which will disqualify non-compliant suppliers and create distressed acquisition opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Coating Supply | Eliminates single-source dependency on German and Japanese PVDF suppliers while securing REACH compliance pathways. |
| Long-term Performance Contract Structuring | Aligns with Germany's Federal Office for Bundeswehr Equipment consolidated procurement model bundling manufacturing and field support. |
| EU Green Deal Certification Investment | Unlocks preferential scoring in Nordic defense tenders requiring third-party verified environmental product declarations. |
| Containerized Hybrid System Development | Enables multimodal transport across road, rail, and sea networks for UN humanitarian response frameworks. |
| IoT-Enabled Shelter Platform Launch | Meets U.S. Army Rapid Capabilities and Critical Technologies Office specifications for contested logistics environments. |
Research Methodology
A spread of perspectives from defense procurement officers at NATO member agencies, shelter manufacturing engineering leads, field-support operations managers, and humanitarian logistics coordinators converged on the working assumptions. Primary interviews with Bundeswehr rapid-response medical unit commanders, U.S. Army expeditionary base infrastructure planners, and UN OCHA procurement specialists were cross-validated against secondary sources including NATO STANAG 4370 documentation, EU Green Deal regulatory filings, and U.S. Department of Defense Modular Force policy directives. Customs trade data for aluminum alloy and coated textile imports, SEC 10-K disclosures from defense prime contractors, and specialized defense procurement databases provided shipment and contract award triangulation. Bottom-up shelter deployment volume estimates were reconciled with top-down defense budget allocation analysis.
Demand-supply balance modeling across the projection horizon segmented procurement by product type, technology architecture, application mission profile, and end-user budget authority. The analytical framework incorporated expeditionary rapid-deployment versus semi-permanent infrastructure investment cycles, helicopter-portable weight thresholds, and climatic specification tiers from arctic-rated to temperate compliance. CAGRs were derived from deployment timeline acceleration trends, NATO standardization mandate adoption curves, and EU sustainability disclosure phase-in schedules. Forecast inputs included aluminum alloy price volatility indices, PVDF coating capacity utilization rates, and defense prime contractor backlog-to-revenue ratios.
Stress conditions across aluminum smelting energy cost spikes, REACH chemical restriction enforcement timelines, and NATO member defense budget reallocation scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding STANAG 4370 interoperability adoption rates and EU Green Deal embodied-carbon tracking implementation stringency. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Construction
Slab Repair Products Market
Specialty Construction
Indonesia Anchors and Grouts Market
Specialty Construction
Fire Hydrants Market
Specialty Construction
ASEAN Waterproofing Market
Specialty Construction
India Anchors and Grouts Market
Specialty Construction
Concrete and Cement Dissolver Market
Specialty Construction
Construction Repaint Market
Specialty Construction
Composite Repair Market
Specialty Construction
Roller Shutter Market
Specialty Construction
Global Fencing Market
Specialty Construction
Asia-Pacific Anchors and Grouts Market
Specialty Construction
Europe Anchors and Grouts Market
Specialty Construction
Asia-Pacific Waterproofing Solutions Market
Specialty Construction
Indonesia Waterproofing Solutions Market
Specialty Construction
Portable Walls Market
Specialty Construction
Shotcrete Accelerators Market