
 Welded Metal Bellows Market | 2026-2036
Welded Metal Bellows Market Size, Share, and Industry Trends Forecast 2026-2036
Welded Metal Bellows Market Intelligence
A shift from single-source to dual-source procurement for critical vacuum assemblies is recalibrating supplier relationships across the welded metal bellows supply base. Senior Flexonics leverages its North American manufacturing footprint to anchor long-term contracts with aerospace OEMs requiring Nadcap-certified weld traceability. EagleBurgmann competes through backward integration into precision stamping and electron-beam welding cells, sustaining cost advantages in nested bellows for semiconductor OEMs. BOA Group dominates European demand for convoluted stainless-steel bellows in district heating expansion joints, controlling specification standards through active participation in EN 1532 working groups.
Welded metal bellows are precision-engineered flexible pressure vessels fabricated from nested diaphragms joined by plasma, laser, or electron-beam welding, designed to accommodate axial, lateral, or angular displacement while maintaining hermetic sealing under cyclic pressure or thermal load. Their primary industrial purpose spans vacuum isolation, pressure and temperature compensation, and leak-free motion transfer in fluid systems subject to fatigue or corrosive media. Edge welded bellows occupy the highest margin pool due to extreme cleanliness requirements in semiconductor lithography vacuum stages, where titanium and Inconel alloys command premium positioning. Convoluted stainless-steel variants sustain volume leadership across industrial valve and oilfield applications, though copper alloy and Monel configurations are displacing standard grades in sour gas environments requiring NACE MR0175 compliance.
ASME Boiler and Pressure Vessel Code Section VIII shapes North American product qualification pathways, while EPA New Source Performance Standards for volatile organic compound containment drive retrofit demand in chemical processing. REACH restrictions on nickel alloy processing chemicals in Europe constrain surface treatment options, redirecting some finishing operations to suppliers with closed-loop electrolyte recovery. Semiconductor fabricators and aerospace Tier-1 suppliers must monitor evolving ISO 9001:2015 and AS9100D audit intensity, as registrar consolidation raises certification costs for sub-tier bellows manufacturers without dedicated quality systems personnel.
Market Dynamics
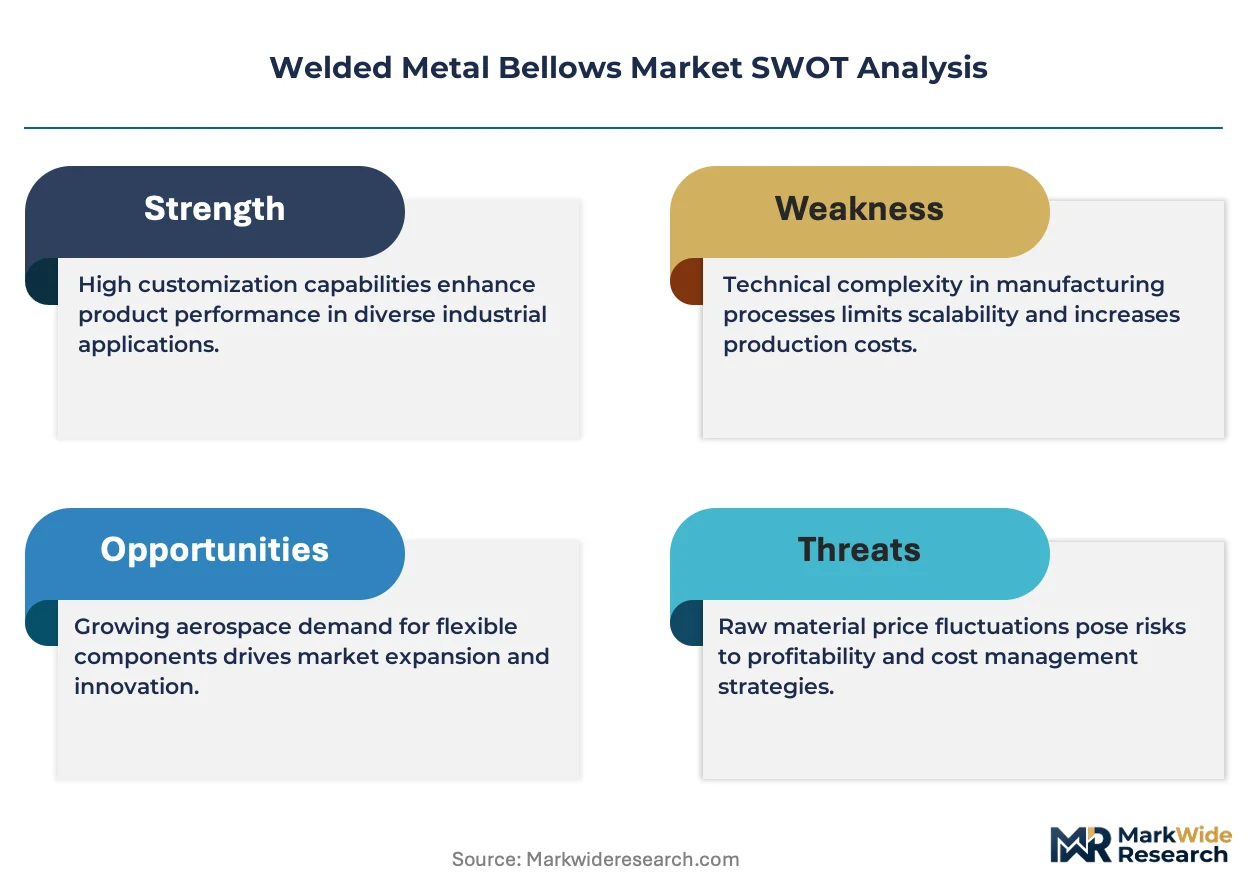
Dual-source procurement mandates from semiconductor and aerospace OEMs are fragmenting supplier relationships across the welded metal bellows value chain, forcing manufacturers to invest in redundant welding certifications and quality systems to retain contract eligibility.
Growth Catalysts
- EPA New Source Performance Standards:Tightened volatile organic compound containment rules in US chemical processing drive retrofit demand for hermetic metal bellows seals in legacy valve assemblies.
- Semiconductor lithography vacuum stages:East Asian fabricators expand procurement of edge-welded titanium bellows for extreme cleanliness requirements in EUV scanner isolation chambers.
- ASME Section VIII:Pressure vessel code compliance requirements in North American oilfield equipment anchor demand for nested Inconel bellows in sour gas service.
Market Restraints
- Nickel alloy input volatility:Inconel and Monel price swings compress margin pools for convoluted bellows producers serving industrial valve OEMs.
- REACH electrolyte restrictions:European surface treatment constraints redirect finishing operations to suppliers with closed-loop recovery, lengthening lead times.
- Hydraulic actuator substitution:Oilfield equipment makers in cost-sensitive basins specify piston-style seals over metal bellows in non-critical pressure compensation roles.
Strategic Opportunities
- India PLI scheme:Domestic semiconductor fabrication incentives create localized demand for vacuum-grade bellows with reduced import dependency.
- Hydrogen fueling infrastructure:High-pressure dispensing protocols require fatigue-resistant edge-welded bellows in cryogenic pump seals and recirculation compressors.
- Direct OEM contracting:Aerospace Tier-1 suppliers bypass distribution layers to secure Nadcap-certified weld traceability through long-term master service agreements.
Industry Challenges
- Electron-beam welder operator scarcity:Precision fusion welding for nested diaphragm assemblies requires specialized technicians with vacuum chamber experience, constraining capacity expansion.
- AS9100D registrar consolidation:Reduced competition among certification bodies extends audit timelines for sub-tier manufacturers without dedicated quality personnel.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Welded Metal Bellows Market |
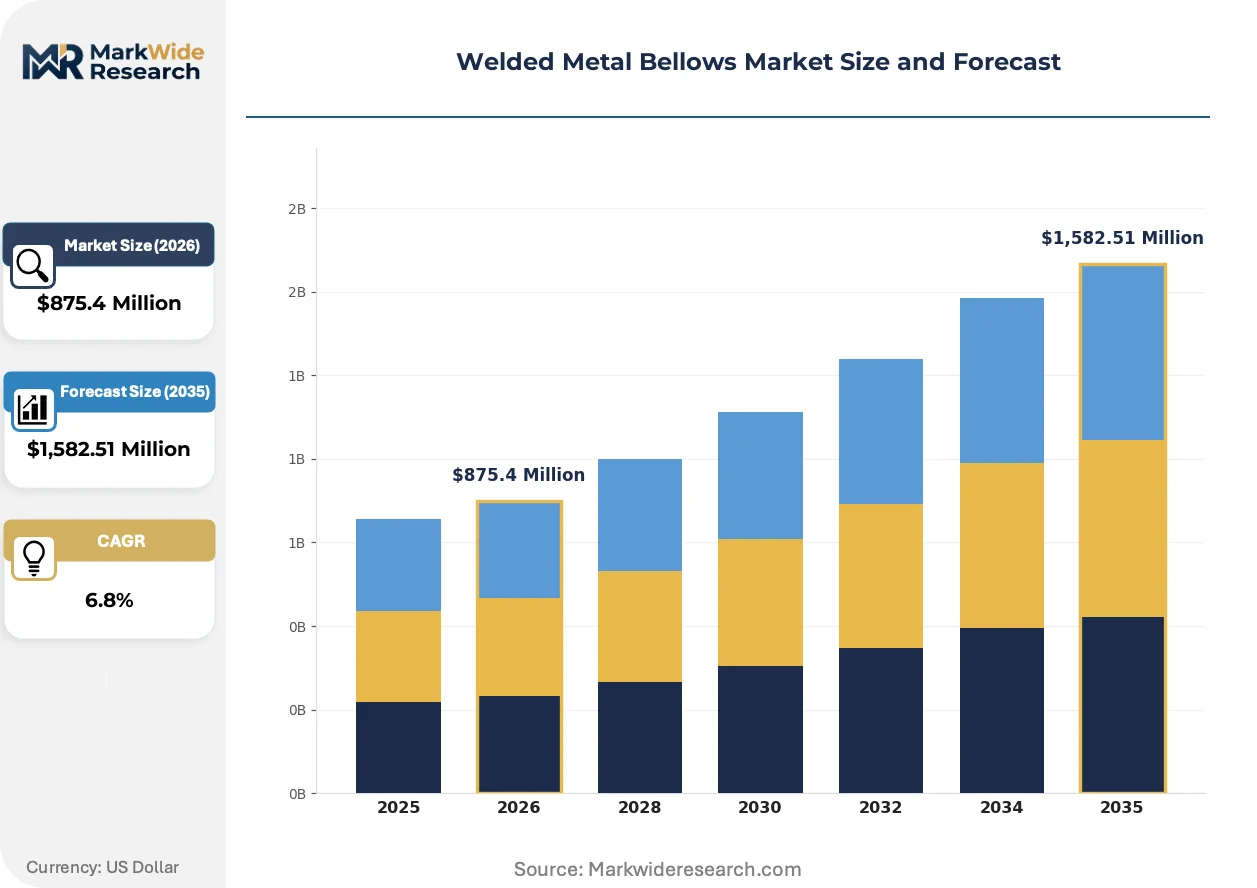
| Market Size in 2026 | $875.4 Million |
| Market Size in 2035 | $1,582.51 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Convoluted, Edge Welded, Tied, Multi-Ply, Nested Material: Stainless Steel, Inconel, Titanium, Copper Alloy, Monel Application: Vacuum Systems, Aerospace Actuation, Semiconductor Manufacturing, Oilfield Equipment, Industrial Valves End User: Process Control Manufacturers, Aerospace Manufacturers, Semiconductor Fabricators, Oil & Gas Companies, Power Generation Firms |
| Companies Covered | Senior Flexonics, Hyspan Precision Products, MW Industries, Technetics Group, Duraflex Inc., BOA Group, Technoflex Corporation, KSM Co., Ltd., EagleBurgmann, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Welded Metal Bellows Market Strategic Shifts & Innovations
Laser welding protocols and additive manufacturing of diaphragm blanks are compressing production cycles for complex nested geometries, while regulatory pressure on emissions containment reshapes material selection across end-use verticals.
Additive manufacturing of near-net-shape diaphragm blanks is rewriting procurement economics for prototype and low-volume bellows assemblies. Aerospace actuator suppliers in Germany's Stuttgart cluster adopt laser-powder-bed fusion for Inconel preforms, cutting raw material waste by eliminating multi-step stamping operations. This capability is compressing lead times for thermal cycling endurance testing and accelerating design iteration cycles.
REACH restrictions on nickel alloy processing chemicals constrain European surface treatment options for convoluted stainless-steel bellows. Manufacturers serving district heating expansion joint specifications redirect electrolytic polishing to suppliers with closed-loop recovery systems in Eastern Europe. BOA Group's participation in EN 1532 working groups shapes compliance pathways while smaller competitors absorb certification cost premiums.
Dual-source mandates from semiconductor OEMs are fragmenting supplier relationships across the vacuum assembly value chain. Procurement teams in Taiwan and South Korea split edge-welded bellows contracts between incumbent Japanese suppliers and qualified second sources, unbundling volume commitments to mitigate disruption risk. This pattern is most visible in EUV lithography stage isolation, where cleanliness specifications exceed standard industrial grades.
Welded Metal Bellows Market Segmentation
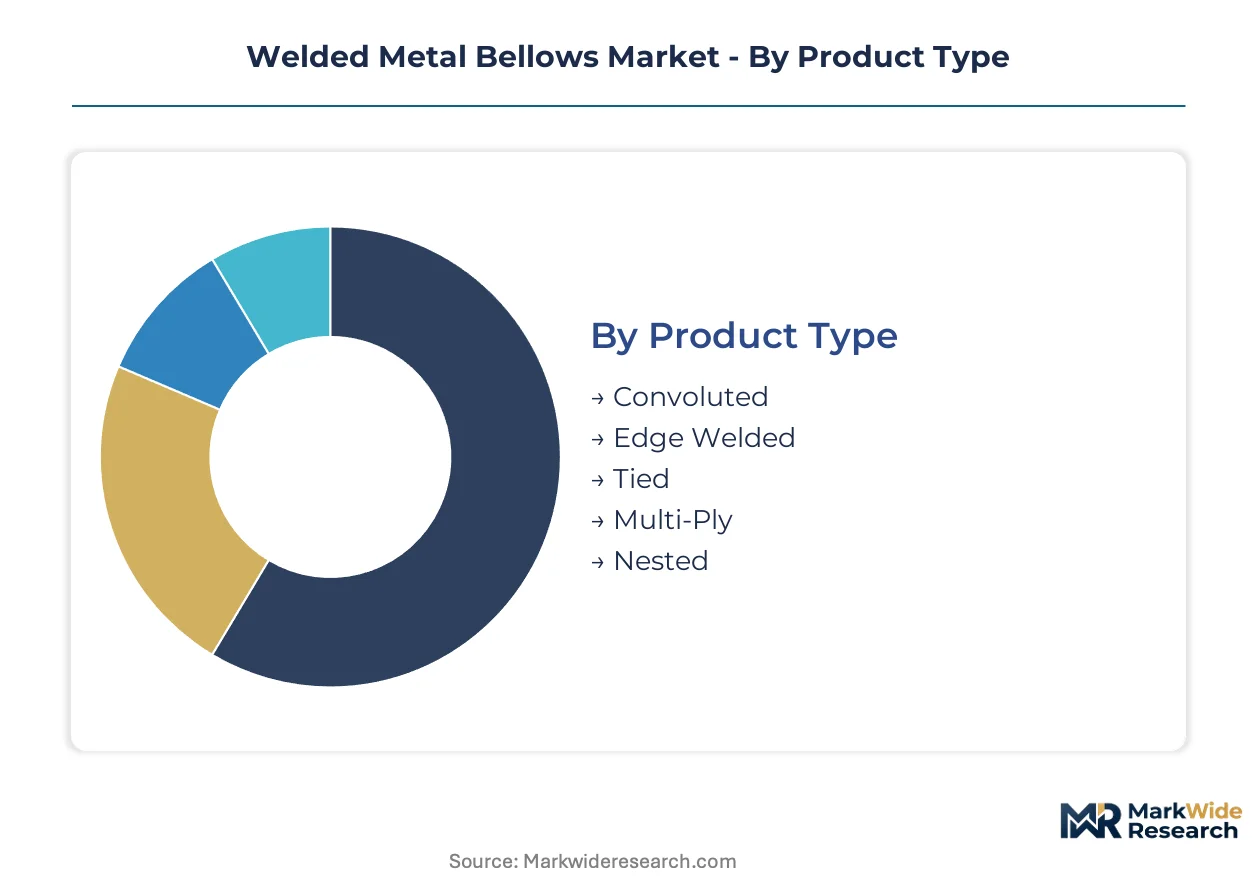
Segmentation in welded metal bellows reveals divergent capital requirements across geometries and alloys. Precision welding infrastructure and material certification costs fragment competitive intensity between commodity convoluted designs and premium edge-welded architectures.
Product Type:
Capital intensity peaks at electron-beam welding cells for nested geometries, while convoluted variants require lower upfront stamping investment.
- Edge Welded:Fabricated from nested diaphragms joined by plasma or electron-beam fusion, these assemblies achieve extreme cleanliness for EUV lithography vacuum stages. Taiwan and South Korea semiconductor fabricators dominate procurement, driven by dual-source mandates that fragment supplier relationships.
- Convoluted:Formed from single-piece hydraulic or mechanical expansion of metal tubes, these bellows serve industrial valve and oilfield pressure compensation. Germany's district heating expansion joint specifications anchor European volume, though hydraulic actuator substitution threatens cost-sensitive basins.
- Tied:External restraining rings limit stroke length for high-pressure containment. Oilfield equipment makers specify these for sour gas service where ASME Section VIII compliance is mandatory.
- Multi-Ply:Layered diaphragm construction multiplies pressure rating without proportional thickness increase. Aerospace actuator suppliers in Stuttgart source these for thermal cycling endurance.
- Nested:Concentric bellows assemblies enable multi-directional displacement in compact envelopes. Precision engineering clusters demand Nadcap-certified weld traceability.
Most installed capacity flows through Convoluted. Expansion is steepest in Edge Welded.
Material:
Raw material volatility and REACH electrolyte restrictions reshape sourcing economics across alloy grades.
- Inconel:Nickel-chromium superalloy withstands thermal cycling and corrosive media in aerospace actuation. Stuttgart cluster procurement concentrates here, though nickel price swings compress margins.
- Stainless Steel:Austenitic grades dominate district heating and industrial valve applications. BOA Group's EN 1532 participation shapes European specification standards.
- Titanium:Biocompatible and non-magnetic properties suit semiconductor lithography where contamination control exceeds standard grades. East Asian fabricators expand procurement for EUV scanner isolation.
- Copper Alloy:Superior thermal conductivity serves cryogenic pump seals in hydrogen fueling infrastructure. Fatigue resistance under high-pressure dispensing protocols drives specification.
- Monel:Nickel-copper alloy resists sour gas corrosion per NACE MR0175. Oilfield equipment makers displace standard grades in emissions-critical valve assemblies.
Volume concentrates in Stainless Steel. Titanium is climbing the fastest.
Application:
End-use certification requirements and cleanliness specifications stratify margin pools across verticals.
- Semiconductor Manufacturing:EUV lithography vacuum stages demand titanium and Inconel edge-welded bellows with particle counts below semiconductor-grade thresholds. Procurement fragmentation accelerates with dual-source mandates.
- Aerospace Actuation:Thermal cycling endurance and Nadcap weld traceability anchor long-term master service agreements. Germany's precision engineering cluster controls nested bellows specification.
- Vacuum Systems:Research and industrial process isolation require hermetic sealing under cyclic thermal load. Edge-welded geometries command premium positioning.
- Oilfield Equipment:Sour gas service and EPA emissions monitoring drive hermetic metal bellows seals. Hydraulic actuator substitution threatens non-critical pressure compensation roles.
- Industrial Valves:Convoluted stainless-steel variants serve pressure and temperature compensation. REACH restrictions redirect surface treatment to Eastern European suppliers.
Revenue concentrates in Semiconductor Manufacturing. Hydrogen fueling infrastructure is expanding most quickly.
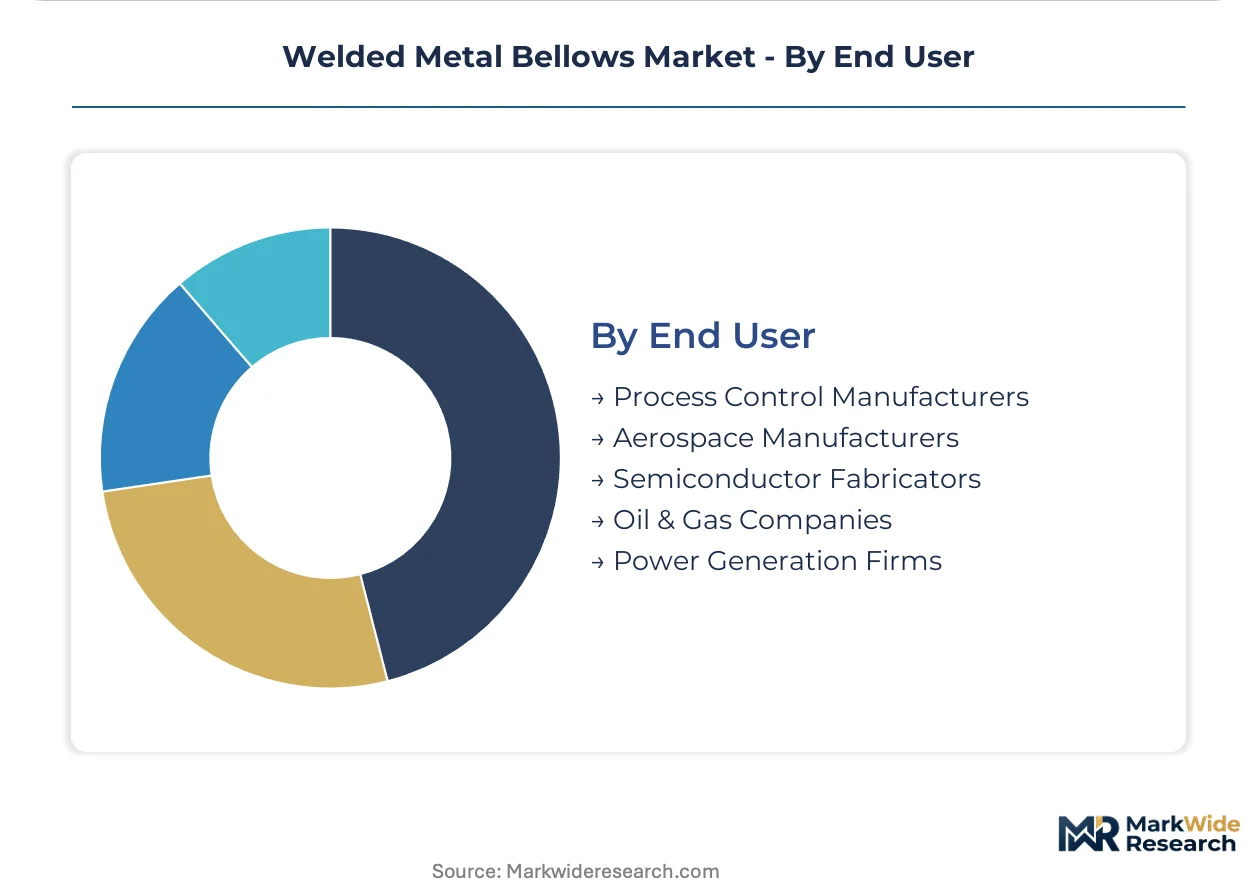
End User:
Procurement authority and quality system sophistication determine contract eligibility across customer tiers.
- Semiconductor Fabricators:Taiwan and South Korea OEMs split edge-welded contracts between Japanese incumbents and qualified second sources. Unbundled volume commitments mitigate disruption risk.
- Aerospace Manufacturers:Tier-1 suppliers bypass distribution for Nadcap-certified weld traceability. Long-term agreements anchor supplier relationships.
- Oil & Gas Companies:ASME Section VIII compliance and EPA New Source Performance Standards drive retrofit demand in legacy valve assemblies.
- Process Control Manufacturers:Industrial automation and fluid system OEMs specify convoluted bellows for pressure compensation.
- Power Generation Firms:District heating expansion joints and turbine sealing applications sustain convoluted stainless-steel volume.
Contract value concentrates with Semiconductor Fabricators. Direct OEM contracting is accelerating fastest among Aerospace Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart's precision engineering cluster anchors European demand for nested Inconel bellows in aerospace thermal cycling applications. Procurement patterns across major economies reflect divergent regulatory pressures and end-use concentrations.
United States
EPA New Source Performance Standards for volatile organic compound containment drive retrofit demand in chemical processing valve assemblies. ASME Boiler and Pressure Vessel Code Section VIII compliance requirements anchor procurement for sour gas service equipment. Houston's oilfield equipment corridor concentrates specification authority for hermetic metal bellows seals.
Germany
REACH restrictions on nickel alloy processing chemicals constrain surface treatment options for convoluted stainless-steel bellows. EN 1532 working group participation shapes European specification standards for district heating expansion joints. BOA Group's Baden-Württemberg operations control compliance pathways while smaller competitors absorb certification premiums.
China
Domestic semiconductor fabrication capacity expansion accelerates procurement of edge-welded titanium bellows for EUV lithography vacuum stages. MIIT industrial upgrading programs prioritize precision welding infrastructure localization. Yangtze River Delta fabricators split contracts between incumbent Japanese suppliers and qualified domestic second sources.
South Korea
Dual-source procurement mandates from memory and logic chip OEMs fragment supplier relationships across vacuum assembly value chains. MFDS-equivalent semiconductor equipment regulations enforce cleanliness specifications exceeding standard industrial grades. Suwon and Pyeongtaek fabrication corridors unbundle volume commitments between Japanese incumbents and emerging qualified alternatives.
Japan
Established precision welding expertise sustains incumbent positioning in edge-welded bellows for EUV scanner isolation chambers. METI technology roadmaps prioritize domestic supply chain resilience for critical vacuum components. Nagoya and Osaka industrial belts maintain specification authority through electron-beam welding cell concentration.
Welded Metal Bellows Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue semiconductor-grade cleanliness certification and hydrogen infrastructure positioning. The supplier base stratifies across three maturity tiers: legacy industrial valve specialists, aerospace-certified precision welders, and diversified sealing technology conglomerates. Competitive intensity concentrates in electron-beam welding capacity and Nadcap traceability systems. Capacity expansion and backward integration into precision stamping represent dominant competitive moves.
Within the precision welding tier, Senior Flexonics and Hyspan Precision Products exemplify North American fabrication archetypes with aerospace certification depth. EagleBurgmann occupies a position among diversified sealing technology providers with integrated electron-beam welding capabilities. BOA Group represents European convoluted bellows specialization with standards-setting influence through EN working group participation. KSM Co., Ltd. anchors Korean supplier emergence under dual-source procurement fragmentation.
| Leading Market Players |
|---|
| Senior Flexonics |
| Hyspan Precision Products |
| MW Industries |
| Technetics Group |
| Duraflex Inc. |
| BOA Group |
| Technoflex Corporation |
| KSM Co., Ltd. |
| EagleBurgmann |
| Others |
Cost & Logistics Intelligence
Nickel alloy spot volatility propagates through Inconel and Monel input costs, compressing margin pools for convoluted bellows producers while amplifying price spreads between aerospace-certified edge-welded assemblies and commodity industrial grades. REACH electrolyte restrictions in Europe lengthen surface treatment lead times, forcing buyers to absorb premium pricing for closed-loop recovery compliance or divert procurement to Eastern European finishers with captive electrolyte systems.
Pricing Analysis
Input-cost pass-through from nickel alloy swings dominates pricing dynamics, with Inconel and Monel price movements compressing margins for convoluted bellows serving industrial valve OEMs within one to two quarters. Pricing stratifies across Nadcap-certified aerospace tiers, standard ASME-compliant oilfield grades, and economy convoluted variants for district heating, with certification grade and electron-beam welding traceability as primary differentiation drivers. Cost compression in commodity convoluted segments is intensifying because hydraulic actuator substitution threatens non-critical pressure compensation roles. Process control manufacturers exhibit highest price sensitivity due to volume procurement and specification fungibility, while semiconductor fabricators show lowest sensitivity given EUV cleanliness requirements and dual-source risk mitigation priorities.
Supply Chain Analysis
Dual-sourcing mandates from Taiwan and South Korea semiconductor OEMs fragment supplier relationships, unbundling edge-welded bellows contracts between Japanese incumbents and qualified second sources to mitigate disruption risk. Supply concentration centers on Japan for precision electron-beam welding expertise, Germany for aerospace nested bellows fabrication, and the United States for ASME-compliant oilfield equipment. Raw material dependencies draw from nickel alloy producers, titanium sponge refiners, and precision stamping operations. Single-source vulnerability persists in electron-beam welder operator scarcity, constraining capacity expansion for nested diaphragm assemblies. Distribution runs through direct OEM contracting for aerospace Tier-1 suppliers and specialized industrial distributors for process control and power generation segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH-constrained European surface treatment costs and Eastern European closed-loop recovery capacity, with procurement teams redirecting finishing operations to capture compliance cost differentials.
For Market Incumbents: Hedge nickel alloy exposure through long-term offtake agreements with specialty metals producers, locking input costs before spot volatility propagates to quoted pricing. Defend margin position by deepening backward integration into precision stamping and electron-beam welding cells, replicating EagleBurgmann's cost structure in nested bellows for semiconductor OEMs. Monitor hydraulic actuator substitution threats in cost-sensitive oilfield basins, prioritizing hermetic seal specifications in emissions-critical valve assemblies where EPA monitoring enforces metal bellows retention.
For New Entrants and Emerging Players: Launch via direct contracting with India-based semiconductor fabricators benefiting from PLI scheme localization incentives, bypassing incumbent Japanese supplier relationships in Taiwan and South Korea. Target hydrogen fueling infrastructure as the most penetrable white-space segment, where cryogenic pump seal and recirculation compressor specifications for high-pressure dispensing protocols remain undersupplied. Pursue copper alloy fatigue resistance certification as the differentiated go-to-market angle, displacing standard grades in emerging hydrogen economy applications.
For Investors and Strategic Acquirers: Consolidation pressure builds where electron-beam welding operator scarcity constrains capacity expansion and AS9100D registrar consolidation extends audit timelines for sub-tier manufacturers without dedicated quality personnel. Long-term viability over the next decade hinges on positioning within semiconductor-grade cleanliness certification or hydrogen infrastructure supply chains, with commodity convoluted bellows facing structural margin compression. Acquisition target archetype: precision welding specialists with Nadcap traceability systems and existing aerospace Tier-1 relationships. The signal to watch is dual-source procurement mandate expansion beyond East Asian semiconductor fabricators into European aerospace supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Electron-Beam Welder Capacity Expansion | Addresses operator scarcity constraining nested bellows output for EUV lithography stages. |
| Backward Integration into Precision Stamping | Replicates cost advantages in diaphragm blank production for aerospace actuator suppliers. |
| Closed-Loop Electrolyte Recovery Investment | Captures European procurement diverted by REACH surface treatment restrictions. |
| Nadcap Certification Depth Addition | Enables direct OEM contracting bypassing distribution layers for aerospace Tier-1 suppliers. |
| Hydrogen Infrastructure Grade Qualification | Positions for cryogenic pump seal demand in high-pressure fueling protocol deployment. |
Research Approach
Bottom-up semiconductor and aerospace actuator modeling reconciled against top-down electron-beam welding capacity tracking forms the analytical core of this study. Primary interviews with vacuum chamber procurement managers at Taiwan and South Korea fabricators, aerospace Tier-1 supplier quality directors, oilfield equipment specification engineers, and precision welding cell operators combined with secondary validation from SEC filings of sealing technology providers, ASME Boiler and Pressure Vessel Code documentation, EPA New Source Performance Standards regulatory texts, and EN 1532 working group proceedings. Triangulation between demand-side procurement patterns and supply-side certification capacity ensures segment-level accuracy.
Historical trendline analysis of nested bellows lead times, nickel alloy price pass-through coefficients, and dual-source procurement mandate adoption rates informed the projection framework. Segmentation modeling spans product type geometry, alloy grade tier, end-use vertical certification requirements, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted input-cost scenarios and capacity expansion timelines across electron-beam welding installations. Industry-specific forecast inputs include EUV lithography stage deployment schedules and hydrogen fueling infrastructure buildout protocols.
Several conditions sit outside the modeled scope, including unannounced EPA regulatory revisions, abrupt nickel alloy supply disruptions from mining jurisdictions, and breakthrough hydraulic actuator technologies displacing metal bellows in pressure compensation roles. Forecasts reflect assumptions about sustained semiconductor capital expenditure and aerospace production rates. Deviation in dual-source procurement mandate geographic expansion or REACH electrolyte restriction enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Construction
Slab Repair Products Market
Specialty Construction
South America Anchors and Grouts Market
Specialty Construction
Composite Repair Market
Specialty Construction
Asia-Pacific Anchors and Grouts Market
Specialty Construction
India Anchors and Grouts Market
Specialty Construction
Fire Hydrants Market
Specialty Construction
Construction Repaint Market
Specialty Construction
Asia-Pacific Waterproofing Solutions Market
Specialty Construction
Europe Anchors and Grouts Market
Specialty Construction
Portable Walls Market
Specialty Construction
ASEAN Waterproofing Market
Specialty Construction
Concrete and Cement Dissolver Market
Specialty Construction
Indonesia Anchors and Grouts Market
Specialty Construction
Indonesia Waterproofing Solutions Market
Specialty Construction
Global Fencing Market
Specialty Construction
Roller Shutter Market