
 Global Fencing Market | 2026-2036
Global Fencing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fencing Market Analysis
China is tilting toward expanded welded wire and chain link capacity to serve domestic infrastructure and export markets. Bekaert leverages its steel wire technology leadership across European and Asian production bases. Ameristar Fence Products Incorporated anchors its position through vertical integration in ornamental and high-security perimeter systems. Associated Materials LLC competes via specialized vinyl and aluminum fabrication networks across North American residential channels.
Fencing encompasses engineered barrier systems fabricated from steel, aluminum, PVC, wrought iron, composite, or bamboo fiber, designed to demarcate, secure, or enclose physical perimeters with specified height, gauge, and tensile ratings. These structures serve residential, agricultural, commercial, and institutional end users requiring controlled access, livestock containment, or property boundary definition. Chain link and welded wire segments dominate volume due to cost efficiency in agricultural and industrial applications, while vinyl and composite materials capture premium margin pools in residential replacement cycles. Electric fencing represents the fastest-growing product category, driven by livestock management automation and perimeter intrusion detection integration.
The US EPA regulates pressure-treated wood preservatives under the Federal Insecticide, Fungicide, and Rodenticide Act, directly shaping material substitution toward steel and composite alternatives. REACH compliance in Europe restricts hexavalent chromium in metal coatings, compelling Bekaert and Betafence NV to reformulate galvanization processes. China's GB standards mandate specific tensile strength and corrosion resistance thresholds for steel fencing deployed in infrastructure projects. Stakeholders must monitor regulatory divergence between jurisdictions as carbon border adjustments and circular economy mandates redefine competitive cost structures.
Market Dynamics
Embodied carbon mandates from the EU Green Deal are forcing reformulation across galvanized steel and composite supply chains, while smart city infrastructure in China and Germany accelerates demand for integrated perimeter detection systems.
Growth Catalysts
- EU Green Deal carbon thresholds:Recycled steel and bio-composite formulations gain cost advantage over virgin materials as border adjustments phase in.
- Livestock automation:Electric fencing with IoT-enabled voltage monitoring displaces manual herding across Australian and Brazilian agricultural operations.
- Welded wire infrastructure:China's high-speed rail and highway expansion consumes industrial-grade barrier systems at scale unmatched elsewhere.
Market Restraints
- Zinc price volatility:Hot-dip galvanization input costs swing with London Metal Exchange pricing, compressing margin on chain link and welded wire segments.
- Scrap steel concentration:Turkish and Indian electric arc furnace operators control secondary steel supply, exposing European fabricators to export restriction risk.
- Hexavalent chromium phase-out:REACH compliance deadlines force coating line retooling before alternatives achieve equivalent salt-spray performance.
Strategic Opportunities
- India smart city perimeter:Urban infrastructure tenders specify integrated video-analytics fencing with minimal installed base to displace.
- Agrivoltaic dual-use fencing:Solar farm developers require livestock-compatible barriers that merge electrical containment with structural mounting.
- US Inflation Reduction Act domestic content:Buy America preferences for federally funded projects advantage North American wire-drawing and coating capacity.
Industry Challenges
- Galvanization chemist scarcity:Formulation expertise for trivalent chromium and zinc-aluminum coatings outpaces vocational training pipeline in Western Europe.
- Multi-jurisdiction certification:Fence systems for cross-border infrastructure must satisfy divergent GB, ASTM, and EN tensile testing protocols simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fencing Market |
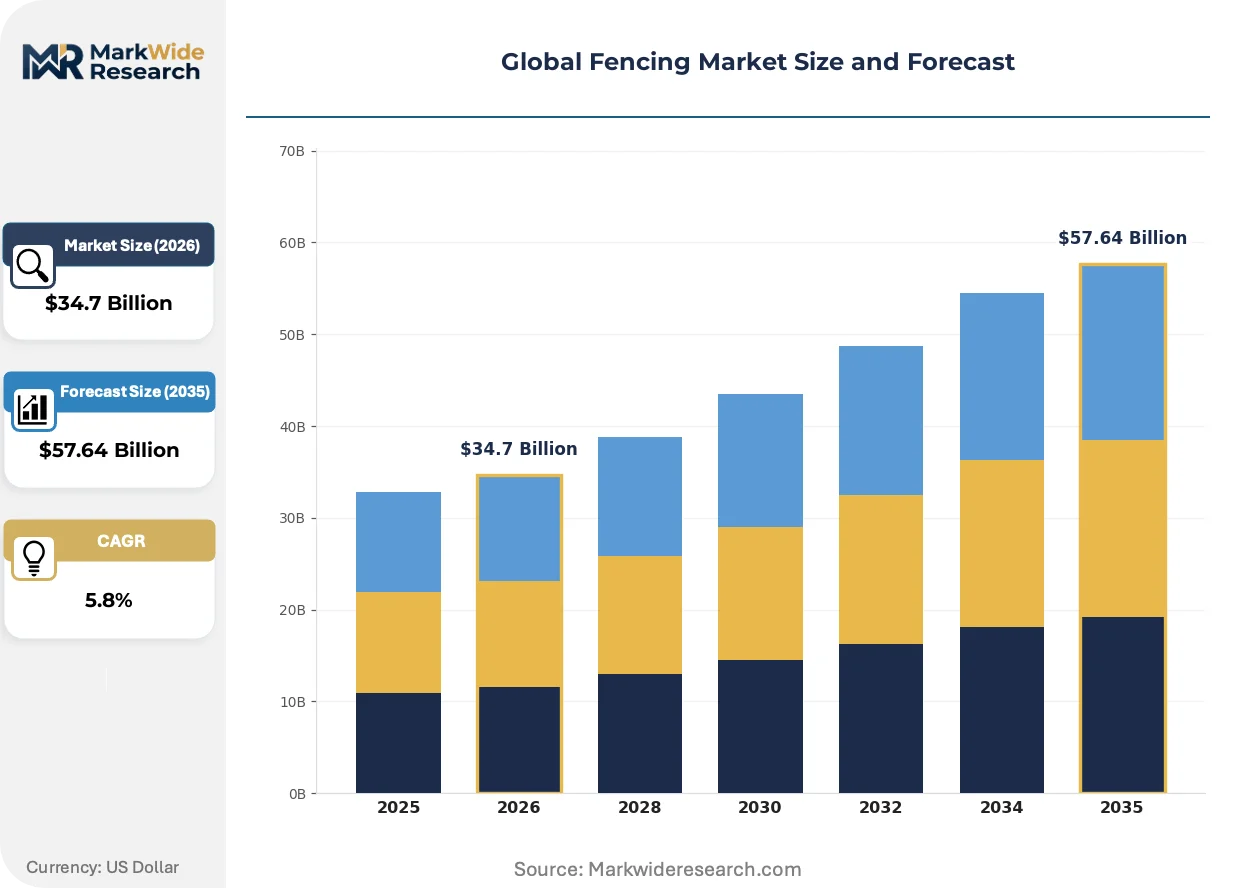
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $57.64 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chain Link, Bamboo, Vinyl, Electric, Welded Wire, Wood End User: Residential Properties, Agricultural Sites, Commercial Facilities, Sports Complexes, Educational Institutions, Government Buildings Installation Type: Permanent, Temporary, Semi-Permanent, Modular Material: Steel, Aluminum, PVC, Wrought Iron, Composite, Bamboo Fiber |
| Companies Covered | Ameristar Fence Products Incorporated, Allied Tube & Conduit, Bekaert, CertainTeed Corporation, Betafence NV, Associated Materials LLC, Gregory Industries, Inc., Master Halco Inc, Ply Gem Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fencing Market Emerging Trajectories
Perimeter security is converging with building management systems and renewable energy infrastructure, creating hybrid product categories that challenge traditional segmentation boundaries.
Composite bamboo-fiber reinforced polymers are rendering obsolete pressure-treated lumber in suburban residential installations. California and Florida property developers specify these materials for coastal humidity resistance and termite immunity. The shift is compressing demand for EPA-regulated wood preservatives and redirecting R&D spend toward bio-resin curing processes.
REACH restrictions on hexavalent chromium are compelling Dutch and Belgian coating houses to accelerate trivalent conversion. Galvanization lines face 18-month qualification cycles for salt-spray performance equivalence. High-security ornamental fencing for Dutch port facilities and German data centers carries the highest compliance burden and pricing premium.
Specification bundling is consolidating buyer influence among national infrastructure contractors. Traditional distributor networks lose share to direct procurement by state-owned rail and highway authorities in China and India. This concentration is most visible in welded wire tenders where volume commitments override brand preference and technical support access.
Global Fencing Market Segmentation
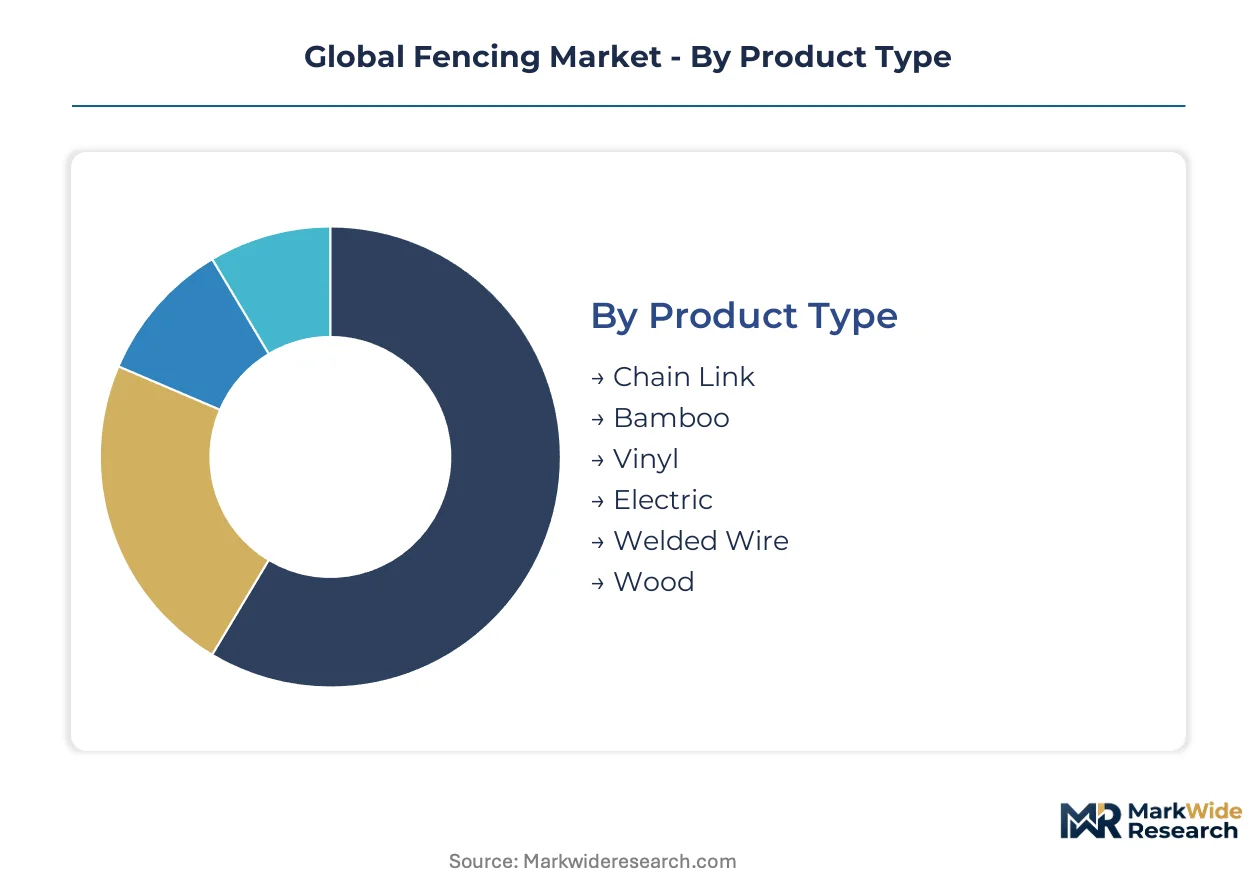
Material composition and installation permanence determine warranty obligations and service contract structures across fencing categories. Product type selection drives replacement cycle timing and aftermarket revenue potential for manufacturers.
Product Type:
After-sales service intensity varies sharply across product categories, with electric systems demanding continuous monitoring and welded wire requiring minimal post-installation support.
- Chain Link:Galvanized steel wire woven into diamond mesh patterns with specified gauge and tensile ratings. Agricultural operations in Brazil and industrial zones in India absorb volume for perimeter demarcation where cost efficiency outweighs aesthetic requirements.
- Welded Wire:Rigid grid panels formed by resistance-welding steel wires at intersections, offering superior structural integrity for high-security applications. Chinese high-speed rail corridors and German data center perimeters specify heavy-gauge variants with integrated intrusion detection mounting points.
- Electric:Energized conductors delivering pulsating voltage for livestock containment or perimeter security, with IoT-enabled voltage monitoring now standard. Australian cattle stations and Brazilian soy plantations are displacing manual herding with automated boundary systems.
- Vinyl:Extruded PVC profiles reinforced with internal ribs, offering color stability and termite immunity for residential replacement cycles. Florida and California developers specify these for coastal humidity resistance without EPA-regulated wood preservatives.
- Wood:Pressure-treated lumber posts and pickets, facing regulatory pressure from US EPA FIFRA restrictions on chemical preservatives. Demand concentrates in rural North American markets where traditional aesthetics override maintenance burden.
- Bamboo:Engineered grass-fiber composites with bio-resin binders, emerging as a sustainable alternative to tropical hardwoods. European garden designers and Japanese temple restoration projects drive niche specification.
Chain Link holds the largest share; momentum sits with Electric as livestock automation accelerates.
End User:
Cost tier stratification separates specification authority between procurement departments with capital budget constraints and facilities managers prioritizing lifecycle value.
- Residential Properties:Single-family subdivisions and multi-family complexes requiring privacy screening, pool safety compliance, and curb appeal enhancement. Suburban North American developers specify vinyl and ornamental aluminum for homeowner association approval compatibility.
- Agricultural Sites:Livestock containment, crop protection, and farmstead perimeter demarcation across varying terrain and climate exposure. Brazilian cattle ranches and Australian sheep stations are electrifying boundaries previously maintained by manual labor.
- Commercial Facilities:Retail parks, logistics hubs, and manufacturing plants requiring controlled access and liability protection. German automotive plants and Chinese electronics assembly zones specify welded wire with integrated video analytics.
- Government Buildings:Embassies, military installations, and critical infrastructure with mandated security ratings. Dutch port authorities and Indian smart city tenders specify anti-ram barriers with crash-test certification.
- Educational Institutions:K-12 campuses and university grounds balancing security imperatives with welcoming aesthetics. US school districts prioritize climb-resistant designs with emergency egress compatibility.
- Sports Complexes:Stadium perimeters, training facilities, and recreational fields requiring spectator control and ball containment. FIFA World Cup venues in Qatar and Olympic facilities in Paris drove temporary modular specification.
Agricultural Sites dominate volume throughput; Government Buildings command the steepest pricing premium.
Installation Type:
Application permanence determines foundation engineering, anchoring systems, and decommissioning liability exposure for contractors.
- Permanent:Concrete-embedded posts with welded or bolted connections designed for 25-year service life. German highway sound barriers and US-Mexico border infrastructure specify hot-dip galvanized steel with cathodic protection.
- Modular:Pre-fabricated panels with standardized connection hardware enabling rapid deployment and reconfiguration. Indian smart city contractors and European music festival organizers favor these for permit flexibility.
- Temporary:Portable barriers for construction sites, event crowd control, and emergency response with minimal ground disturbance. Chinese urban renewal projects and Brazilian carnival security operations drive rental market expansion.
- Semi-Permanent:Surface-mounted systems with removable anchoring for seasonal agricultural use or rotating construction phases. Australian vineyard operators deploy these for harvest-period deer exclusion.
Permanent installations retain the majority of installed base value; Modular systems are gaining share fastest in urban infrastructure.
Material:
Supply concentration for raw inputs—zinc for galvanization, aluminum billets, and PVC resin—shapes regional manufacturing footprints and import dependency.
- Steel:Hot-rolled and cold-drawn wire rod processed through galvanization or polymer coating lines. Turkish and Indian electric arc furnace operators control secondary supply, exposing European fabricators to scrap export restrictions.
- Composite:Bamboo fiber reinforced with bio-based resins, offering embodied carbon advantages under EU Green Deal thresholds. Dutch coating houses and Belgian fabricators are qualifying these for port facility specification.
- Aluminum:Extruded and cast alloys with anodized or powder-coated finishes for corrosion resistance without galvanization. Coastal California and Florida residential channels specify these for salt-air immunity.
- PVC:Virgin and recycled vinyl formulations extruded into picket, privacy, and ranch-rail profiles. REACH compliance on plasticizer additives constrains European formulation flexibility versus North American producers.
- Wrought Iron:Forged and fabricated ornamental designs for heritage restoration and high-end residential gates. French château restoration and Charleston historic district guidelines preserve artisan fabrication demand.
- Bamboo Fiber:Processed grass stems laminated or extruded with binding agents, positioned as carbon-negative alternative to pressure-treated lumber. Japanese temple carpenters and Scandinavian landscape architects specify these for biogenic content certification.
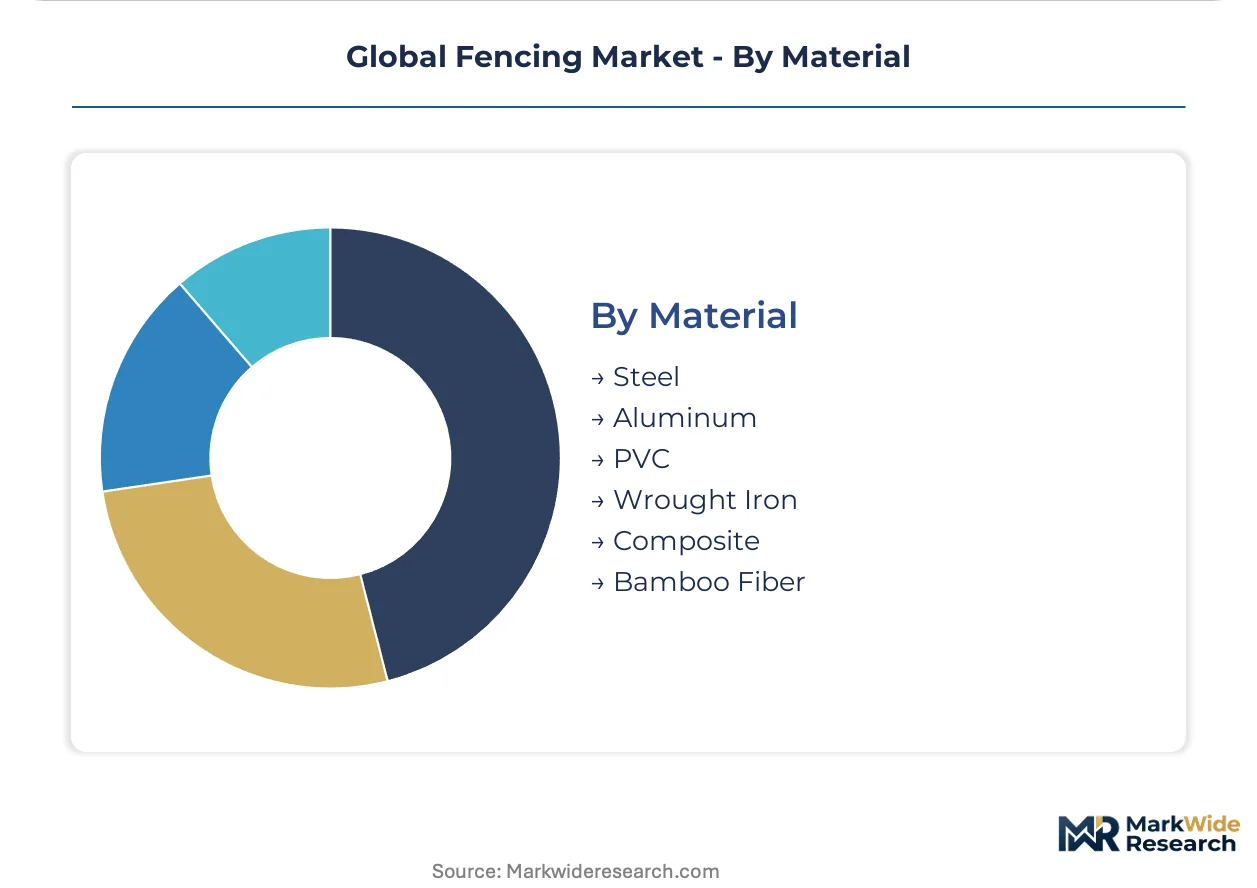
Steel commands the dominant material position; Composite formulations are climbing the fastest as carbon accounting penetrates procurement criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States prioritizes ornamental residential installations with aesthetic compliance requirements. China deploys industrial-grade welded wire at infrastructure scale. Germany mandates embodied carbon thresholds that reshape material procurement. Brazil electrifies agricultural boundaries for livestock automation. India tenders smart city perimeters with integrated detection systems.
United States
Suburban property developers specify vinyl and ornamental aluminum for homeowner association compatibility. The EPA regulates pressure-treated wood preservatives under FIFRA, accelerating substitution toward steel and composite alternatives. California and Florida coastal markets favor salt-air resistant materials for perimeter installations.
China
High-speed rail corridors and highway expansion consume welded wire barrier systems at unmatched volume. GB standards mandate specific tensile strength and corrosion resistance thresholds for infrastructure-grade steel fencing. Yangtze River Delta fabrication clusters supply domestic demand while expanding export capacity.
Germany
Data center perimeters and port facilities specify high-security welded wire with anti-ram certification. REACH restrictions on hexavalent chromium in metal coatings compel coating houses to reformulate galvanization processes. Ruhr Valley industrial zones concentrate qualification expertise for salt-spray performance equivalence.
Brazil
Cattle ranches and soy plantations displace manual herding with IoT-enabled electric fencing systems. ANVISA oversees agricultural input regulations that intersect with electrified perimeter safety standards. São Paulo state agricultural cooperatives drive automation adoption across pasture management.
India
Smart city infrastructure tenders specify integrated video-analytics fencing with minimal incumbent installed base to displace. BIS certification requirements shape material specifications for government procurement. Delhi-Mumbai Industrial Corridor projects concentrate demand for modular perimeter systems.
Global Fencing Market Vendor Landscape
Capability concentration sits with specialized coating and formulation houses; scale advantage sits with integrated wire-drawing and fabrication networks. The vendor base separates into three tiers: multinational steel wire technology leaders, regional fabricators with captive distribution, and niche specialists in electrified or composite systems. Dominant competitive moves include backward integration into zinc-aluminum coating capacity and geographic expansion through specification bundling with national infrastructure contractors.
Among European-anchored steel wire specialists, Bekaert exemplifies technology leadership across galvanization processes. Ameristar Fence Products Incorporated occupies a position within the North American ornamental and high-security perimeter tier. Associated Materials LLC represents specialized vinyl and aluminum fabrication networks serving residential replacement cycles. Betafence NV sits within the continental European welded wire segment, navigating REACH compliance deadlines for coating line retooling.
| Leading Market Players |
|---|
| Ameristar Fence Products Incorporated |
| Allied Tube & Conduit |
| Bekaert |
| CertainTeed Corporation |
| Betafence NV |
| Associated Materials LLC |
| Gregory Industries, Inc. |
| Master Halco Inc |
| Ply Gem Holdings Inc. |
| Others |
Supply Flow & Price Mechanics
Zinc price volatility on the London Metal Exchange determines both the spread between economy-grade chain link and premium welded wire systems and the geographic distribution of galvanization capacity. Turkish and Indian electric arc furnace operators control secondary steel supply, exposing European fabricators to export restriction risk while compressing margin pools across mid-tier product categories.
Pricing Analysis
Geographic price spreads separate North American ornamental installations from Chinese infrastructure-grade volumes by a factor reflecting coating technology and certification burden. Three-tier pricing structure across premium, standard, and economy levels stratifies by tensile rating and salt-spray performance, with REACH-compliant trivalent chromium coatings commanding premium positioning. Pricing pressure stems from scrap steel export restrictions out of Turkey and India, which elevate input costs for European wire-drawing operations. Agricultural buyers in Brazil and Australia demonstrate highest price sensitivity, while Dutch port authorities and German data center operators absorb premium positioning for anti-ram certification.
Supply Chain Analysis
Extended payment terms from Chinese state-owned rail contractors now structure working capital requirements across Yangtze River Delta fabrication clusters. Supply concentrates in China, Turkey, and India for wire rod and secondary steel, with Belgian and Dutch coating houses anchoring European galvanization expertise. Raw material dependencies center on zinc for hot-dip galvanization, aluminum billets for coastal residential applications, and bio-resin formulations for EU Green Deal compliance. Single-source vulnerability runs through Turkish scrap steel export licensing. Distribution runs through national infrastructure contractors consolidating welded wire procurement, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's embodied carbon thresholds constitute a regulatory inflection that is concentrating competitive advantage among coating houses with qualified trivalent chromium lines. This disruption favors players with backward integration into recycled steel supply and penalizes virgin-material-dependent fabricators.
For Market Incumbents: Insulate margin position by accelerating in-house production of zinc-aluminum coating capacity before REACH compliance deadlines force third-party dependency. Secure captive supply of secondary steel through long-term offtake agreements with Turkish electric arc furnace operators. Threat substitution from bamboo-fiber composites in California and Florida residential channels demands R&D allocation toward bio-resin curing qualification. For New Entrants and Emerging Players: Establish a beachhead in Indian smart city perimeter tenders, where integrated video-analytics fencing carries minimal incumbent installed base to displace. Target agrivoltaic dual-use fencing specifications merging livestock containment with solar farm structural mounting. Go-to-market leverage rests on modular system design enabling rapid permit flexibility for urban infrastructure contractors. For Investors and Strategic Acquirers: REACH trivalent chromium phase-out deadlines reshape the acquisition landscape toward coating houses with 18-month salt-spray qualification cycles already completed. Long-term viability over the next decade hinges on carbon-accounting penetration into procurement criteria. Acquisition target archetype: Belgian or Dutch galvanization specialists with port facility certification track records. Signal to watch: BIS certification acceleration for Indian government tenders as indicator of modular system demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Capacity | REACH compliance deadlines force trivalent chromium line ownership to preserve margin pools. |
| Recycled Steel Supply Agreement | Turkish and Indian electric arc furnace operators control secondary input critical for EU Green Deal thresholds. |
| Modular System Certification | Indian smart city tenders specify rapid-deployment fencing with BIS compliance for infrastructure scale. |
| Agrivoltaic Dual-Use Development | Solar farm developers require livestock-compatible barriers merging electrical containment with structural mounting. |
| Bio-Composite Formulation Investment | California and Florida developers specify bamboo-fiber alternatives to EPA-regulated pressure-treated lumber. |
Methodological Framework
The analysis maps welded wire infrastructure, electric fencing automation, vinyl residential replacement, and composite material substitution, each validated through coating house technical directors, national infrastructure procurement officers, agricultural cooperative managers, and residential developer specification leads. Primary interviews with wire-drawing plant engineers and galvanization line operators combined with secondary validation from SEC filings of listed steel wire producers, ECHA REACH registration databases, and Chinese GB standards documentation. Bottom-up and top-down triangulation cross-referenced production capacity disclosures with tender award volumes across Indian smart city authorities and Chinese state rail bureaus.
Assumptions held fixed include EU Green Deal carbon border adjustment phase-in schedules and REACH hexavalent chromium sunset timelines, while zinc price volatility and Turkish scrap export licensing were varied across stress bands. Segmentation dimensions modeled span material composition, installation permanence, end-user vertical, and geographic regulatory cluster. CAGRs were derived from volume-weighted average of segment growth rates calibrated to infrastructure spend forecasts and livestock automation penetration curves. Industry-specific inputs incorporated galvanization line qualification cycle durations and BIS certification processing intervals.
Stress conditions across zinc price bands, Turkish scrap export restriction scenarios, and REACH compliance deadline adherence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Construction
Roller Shutter Market
Specialty Construction
Welded Metal Bellows Market
Specialty Construction
ASEAN Waterproofing Market
Specialty Construction
Slab Repair Products Market
Specialty Construction
Indonesia Anchors and Grouts Market
Specialty Construction
Shotcrete Accelerators Market
Specialty Construction
India Anchors and Grouts Market
Specialty Construction
Composite Repair Market
Specialty Construction
Expandable Shelter Market
Specialty Construction
Concrete and Cement Dissolver Market
Specialty Construction
Construction Repaint Market
Specialty Construction
Asia-Pacific Anchors and Grouts Market
Specialty Construction
Indonesia Waterproofing Solutions Market
Specialty Construction
Europe Anchors and Grouts Market
Specialty Construction
Fire Hydrants Market
Specialty Construction
Portable Walls Market