
 Concrete and Cement Dissolver Market | 2026-2036
Concrete and Cement Dissolver Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete and Cement Dissolver Market Analytics
Construction supply wholesaling is reshaping how concrete and cement dissolvers reach end users across fragmented regional markets. Sika AG leverages its integrated admixtures portfolio to bundle dissolvers with waterproofing systems for large contractors. BASF SE anchors its position through R&D intensity in biodegradable chelating agents that reduce surface damage on delicate substrates. Mapei S.p.A. competes via specialized gel formulations designed for vertical concrete removal in heritage restoration.
Concrete and cement dissolvers comprise acidic, alkaline, or enzymatic chemical formulations typically containing glycolic acid, phosphoric acid, or citric acid derivatives that break calcium-silicate bonds through chelation or acid-base reactions, enabling non-mechanical removal of hardened Portland cement residues from equipment, vehicles, and finished surfaces. Liquid formulations dominate volume sales due to spray-applied efficiency on horizontal surfaces and rapid penetration into porous concrete layers; gel variants command premium positioning in vertical and overhead applications where dwell time and adhesion determine performance. Foam dissolvers represent the fastest-growing product category, driven by expanded use in demolition pre-treatment where controlled expansion improves coverage on irregular debris surfaces. Contractors constitute the largest end user segment, though industrial users in ready-mix concrete production are deepening procurement of bulk dissolver systems to reduce drum cleaning downtime.
EPA regulations under the Resource Conservation and Recovery Act govern hazardous waste classification of spent acidic dissolvers, while OSHA permissible exposure limits dictate formulation choices and personal protective equipment requirements on commercial jobsites. REACH compliance in Europe restricts certain corrosive acid concentrations, pushing manufacturers toward citric acid and enzymatic alternatives that meet biodegradability thresholds. Stakeholders must monitor evolving chemical restriction frameworks across multiple jurisdictions while assessing whether enzymatic platforms can achieve performance parity with traditional mineral acid systems at commercial scale.
Market Dynamics
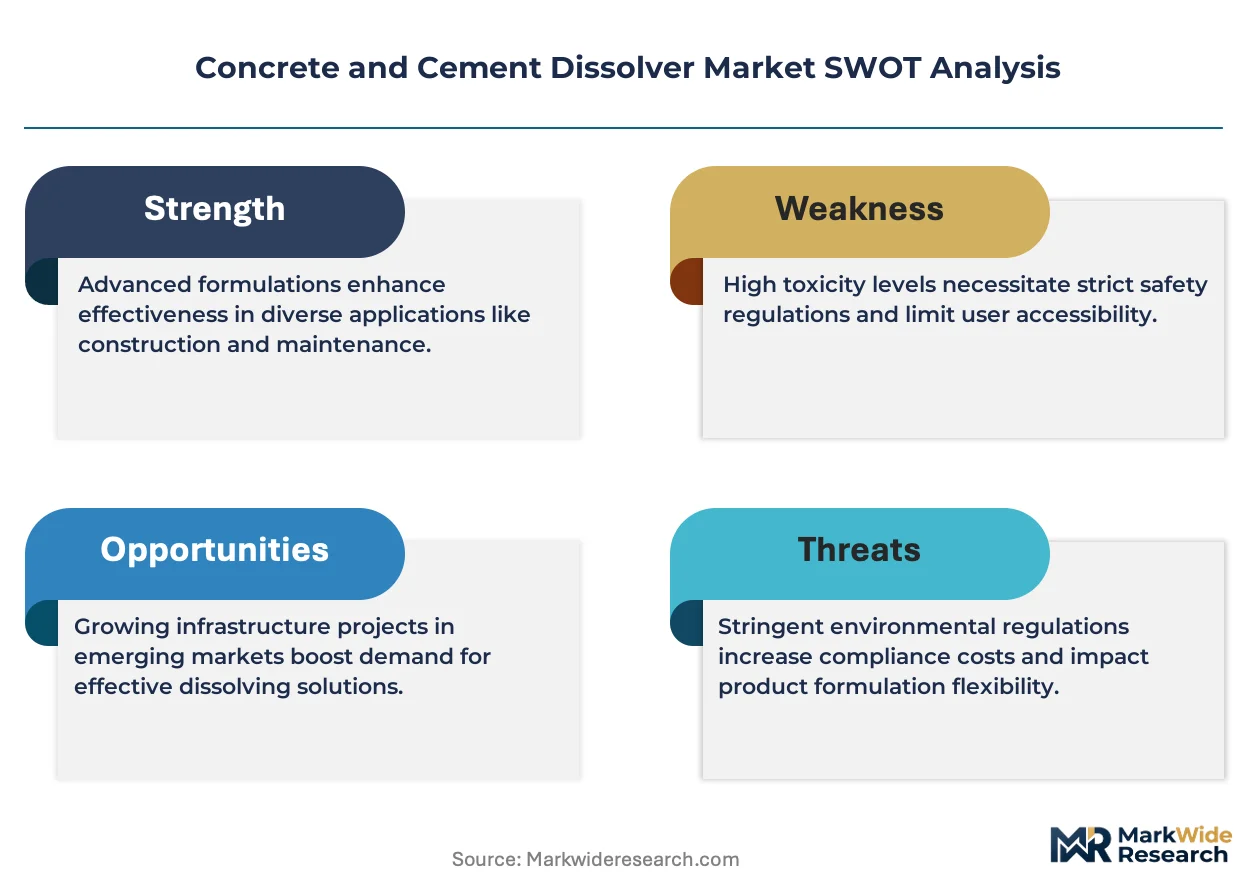
Municipal infrastructure maintenance budgets are expanding across OECD countries, pulling low-corrosion dissolver formulations into routine bridge deck and roadway rehabilitation contracts while tightening EPA and OSHA exposure limits force reformulation of acid-based products.
Growth Catalysts
- REACH biodegradability thresholds:European chemical restrictions are accelerating citric acid and enzymatic platform development, opening municipal procurement channels previously closed to mineral acid products.
- Heritage concrete restoration:Germany's federal monument preservation programs require specialized gel-based removal systems for pre-cast architectural elements, creating premium application demand.
- Ready-mix drum cleaning automation:Industrial batch plant operators are integrating bulk dissolver dosing systems to reduce equipment downtime and manual cleaning labor.
Market Restraints
- Phosphoric acid feedstock volatility:Fertilizer industry demand swings create input cost instability for traditional acidic formulation producers.
- Enzymatic performance gaps:Current biological platforms fail to match mineral acid kinetics on high-density Portland cement residues, limiting substitution rates.
- RCRA hazardous waste classification:EPA rules governing spent acidic dissolver disposal add compliance costs and liability exposure for contractors.
Strategic Opportunities
- Demolition pre-treatment foam systems:Controlled-expansion formulations improve coverage on irregular debris surfaces, opening salvage and deconstruction verticals.
- OSHA permissible exposure limit tightening:Anticipated reductions in workplace acid concentration limits will advantage low-fume gel and enzymatic alternatives.
- Waterproofing system bundling:Admixture suppliers can integrate dissolvers into protective coating packages for large infrastructure contractors.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in chelating agent synthesis and substrate compatibility testing is concentrated among aging technical workforces.
- Certification timeline compression:Biodegradable alternatives must demonstrate performance parity through extended field trials before municipal agencies approve specification changes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete and Cement Dissolver Market |
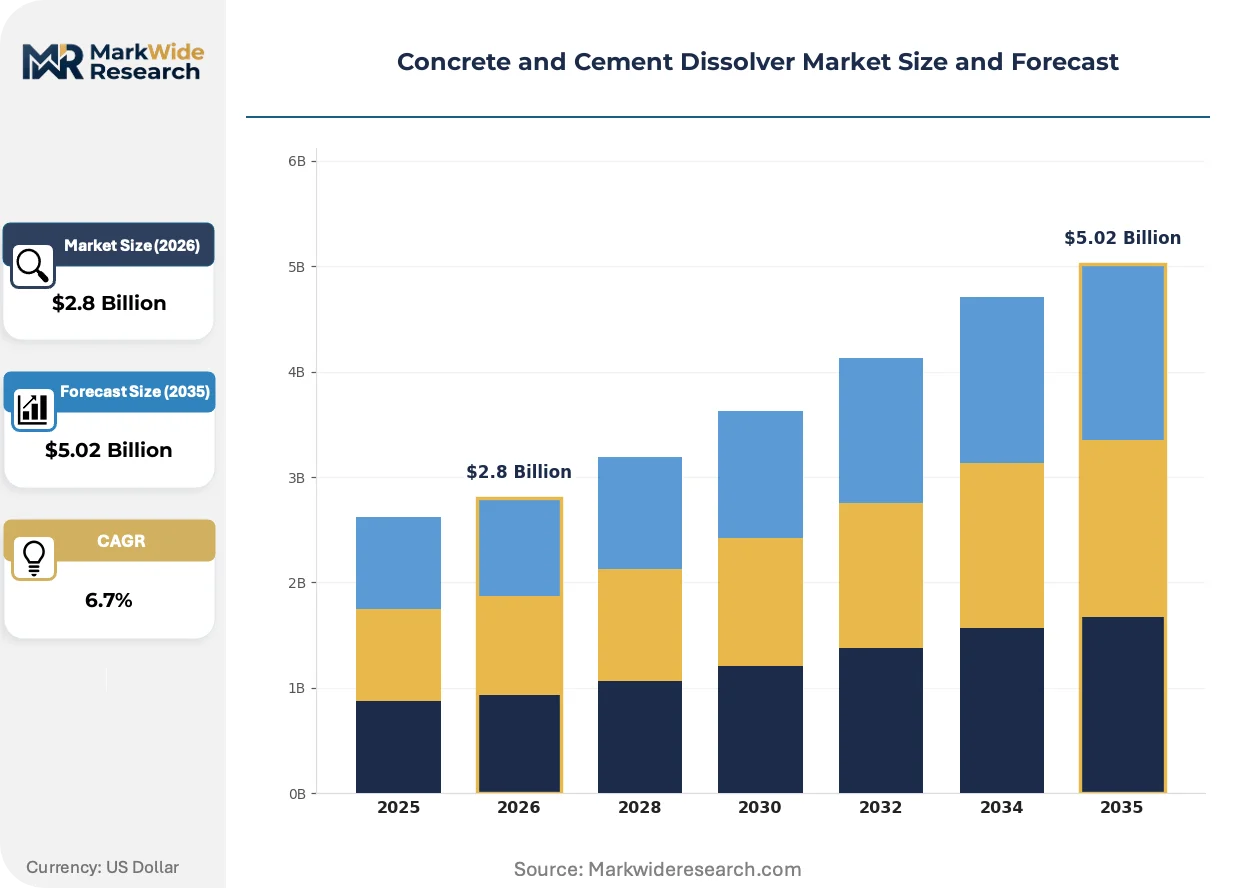
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Gel, Powder, Foam Application: Construction, Renovation, Demolition, Maintenance End User: Contractors, Homeowners, Industrial Users, Municipalities Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Sika AG, BASF SE, Mapei S.p.A., Fosroc International Ltd., RPM International Inc., Arkema, Evonik Industries AG, PPG Industries Inc., Prosoco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete and Cement Dissolver Market Evolving Landscape
Formulation chemistry is converging with application engineering as manufacturers engineer dwell-time control and substrate specificity into next-generation removal systems.
Enzymatic dissolver technology is hybridizing acid-base reaction kinetics with biological catalysis, enabling contractors to target specific calcium-silicate bond structures without etching adjacent masonry. Heritage restoration specialists in Germany and Italy are piloting these platforms on limestone-adjacent concrete removal. The structural consequence is compression of the performance-premium gap between biological and mineral acid systems.
EPA Resource Conservation and Recovery Act enforcement is intensifying scrutiny of spent dissolver drum disposal practices, forcing waste management contractors to invest in neutralization infrastructure. Ready-mix producers face reclassification risk for acidic rinsewater previously treated as non-hazardous. The industrial response concentrates in Texas and California, where batch plants are installing on-site pH adjustment systems.
Service unbundling is fragmenting traditional supply relationships as contractors separate chemical procurement from application equipment leasing. Equipment rental channels are capturing dissolver volume previously flowing through construction supply wholesalers. This pattern is most visible in the US Sun Belt, where independent rental yards are adding sprayer systems and bulk tanks to concrete specialty offerings.
Concrete and Cement Dissolver Market Segmentation
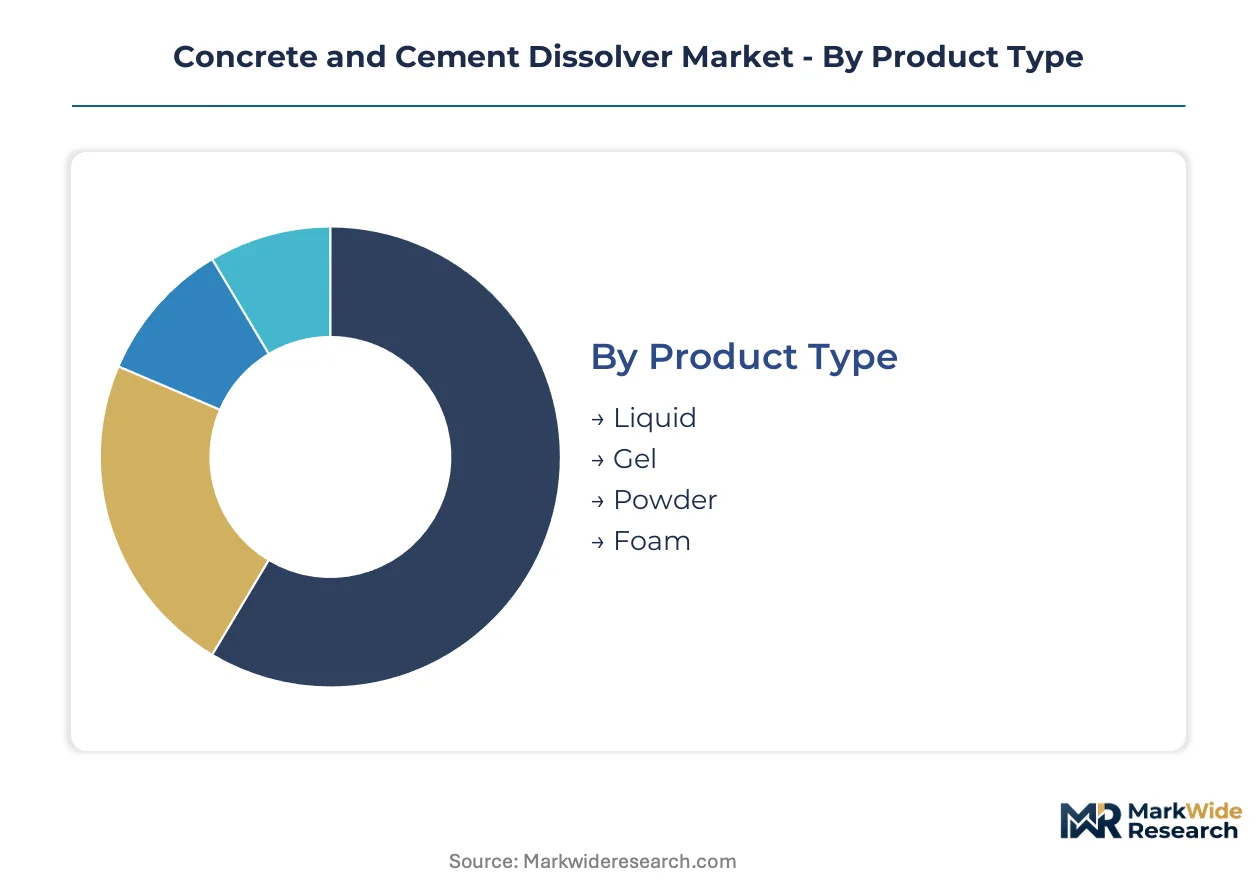
Segmentation in concrete and cement dissolvers reveals how formulation chemistry, application constraints, and procurement channels create distinct competitive arenas. Each dimension governs margin structure and customer loyalty differently.
Product Type:
Mature liquid formulations dominate volume, while emerging gel and foam platforms capture premium positioning through application-specific performance.
- Liquid:Spray-applied formulations containing glycolic or phosphoric acid derivatives penetrate porous concrete layers rapidly. Demand concentrates among ready-mix contractors in Texas and Florida, where drum cleaning throughput determines operational economics. EPA RCRA classification of spent rinsewater creates compliance cost pressure that favors bulk neutralization systems.
- Gel:Thickened acid or enzymatic systems adhere to vertical and overhead surfaces, extending dwell time on heritage restoration projects. Germany's federal monument preservation programs specify these formulations for pre-cast architectural elements, creating procurement specifications that lock out liquid competitors.
- Powder:Dry concentrates reconstituted on-site reduce shipping costs for remote construction camps in Canada and Australia.
- Foam:Controlled-expansion systems improve coverage on irregular debris surfaces during demolition pre-treatment.
Liquid handles the majority of throughput; foam is the fastest mover on share.
Application:
Cost tier stratification separates commodity removal from specialized restoration work.
- Construction:Equipment and vehicle cleaning during active pours drives recurring consumption. Large contractors in California integrate dissolvers into site service contracts, bundling chemical supply with application equipment leasing.
- Renovation:Surface preparation for coating adhesion requires low-corrosion formulations that preserve substrate integrity. Heritage specialists in Italy specify citric acid platforms for limestone-adjacent concrete removal.
- Demolition:Pre-treatment softening of hardened debris accelerates mechanical removal. OSHA permissible exposure limits on demolition sites favor low-fume gel alternatives.
- Maintenance:Bridge deck and roadway rehabilitation contracts pull low-corrosion formulations into municipal procurement channels.
Construction absorbs the largest chemical volume; renovation commands the steepest price premiums per liter.
End User:
Customer type determines specification authority and procurement method.
- Contractors:General and specialty trade contractors specify dissolvers based on substrate compatibility and dwell time requirements. Equipment rental channels in the US Sun Belt capture volume previously flowing through construction supply wholesalers.
- Industrial Users:Ready-mix batch plant operators automate bulk dissolver dosing to reduce drum cleaning downtime. Texas and California plants lead installation of on-site pH adjustment systems.
- Homeowners:DIY concrete removal from driveways and patios drives retail channel volume.
- Municipalities:Infrastructure agencies specify low-corrosion formulations for bridge deck rehabilitation, with REACH biodegradability thresholds opening procurement to citric acid alternatives.
Contractors drive the bulk of specification decisions; industrial users are converting fastest to automated dosing systems.
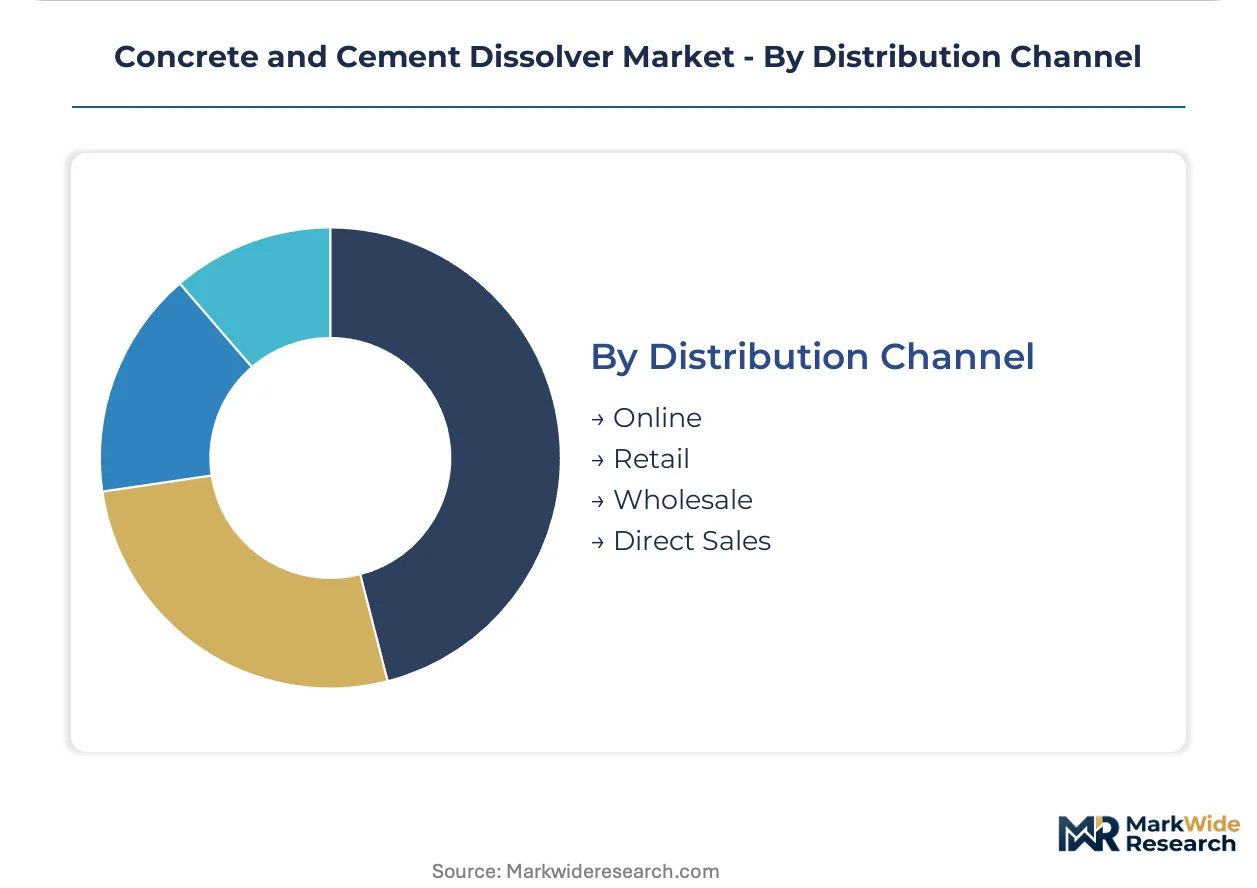
Distribution Channel:
Supply concentration varies sharply by customer scale and urgency requirements.
- Wholesale:Construction supply distributors bundle dissolvers with waterproofing and admixture portfolios for large infrastructure contractors. Sika AG leverages integrated product lines to secure specification lock-in.
- Direct Sales:Bulk supply agreements serve ready-mix producers with automated drum cleaning systems. BASF SE anchors relationships through R&D collaboration on biodegradable chelating agents.
- Online:E-commerce platforms serve small contractors and homeowners with rapid replenishment.
- Retail:Big-box home improvement stores stock consumer-grade formulations for DIY applications.
Wholesale moves the highest absolute volume; direct sales is climbing the fastest as industrial automation spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Germany's heritage restoration corridor, while volume-driven competition intensifies across the US Sun Belt. This asymmetry shapes manufacturer portfolio allocation and R&D investment geography.
United States
Texas and Florida ready-mix batch plants drive bulk dissolver consumption through automated drum cleaning systems. EPA RCRA enforcement tightens disposal rules for acidic rinsewater, forcing on-site pH neutralization investments. California contractors lead adoption of low-fume gel alternatives as OSHA permissible exposure limits compress.
Germany
Federal monument preservation programs specify gel-based removal systems for pre-cast architectural heritage elements. REACH biodegradability thresholds lock mineral acid formulations out of municipal procurement channels. Bavarian restoration specialists pilot enzymatic platforms on limestone-adjacent concrete removal projects.
China
Urban renewal demolition volumes accelerate foam dissolver uptake for debris pre-treatment softening. MEE enforcement of dual carbon goals pressures manufacturers toward citric acid alternatives. Yangtze River Delta construction supply wholesalers bundle dissolvers with waterproofing portfolios for infrastructure contractors.
India
Smart city infrastructure maintenance budgets expand low-corrosion formulation procurement for bridge deck rehabilitation. BIS certification timelines compress as biodegradable alternatives seek performance parity demonstration. Maharashtra ready-mix producers automate bulk dosing systems to reduce equipment downtime.
United Arab Emirates
Mega-project concrete equipment cleaning contracts pull high-throughput liquid formulations into procurement specifications. MOHAP chemical exposure guidelines influence contractor PPE and formulation selection. Dubai-based construction supply distributors integrate dissolvers into site service leasing packages.
Concrete and Cement Dissolver Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in formulation chemistry. The vendor base stratifies between consolidated admixture conglomerates and specialized restoration chemical houses. Three archetypes dominate: integrated construction chemical platforms, heritage restoration specialists, and industrial bulk supply operators. Competitive moves concentrate on waterproofing system bundling and enzymatic platform development partnerships.
Among Swiss-integrated construction chemical platforms, Sika AG occupies the system-tier position exemplifying portfolio bundling strategies. German diversified chemical conglomerates BASF SE and Evonik Industries AG anchor the R&D-intensive tier, representing the shift toward biodegradable chelating agent development. Italian heritage restoration specialists Mapei S.p.A. sit within the premium-application segment, illustrating gel formulation specialization for vertical concrete removal.
| Leading Market Players |
|---|
| Sika AG |
| BASF SE |
| Mapei S.p.A. |
| Fosroc International Ltd. |
| RPM International Inc. |
| Arkema |
| Evonik Industries AG |
| PPG Industries Inc. |
| Prosoco |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese phosphoric acid derivative production is compressing input costs for acidic formulation producers while simultaneously eroding pricing power for standard liquid dissolvers in export markets. German gel-formulation specialists maintain premium positioning through REACH-compliant certification barriers that insulate them from commodity price swings.
Pricing Analysis
The customization-premium spread separates standard liquid formulations from configured-to-order gel systems engineered for heritage substrate compatibility. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with REACH biodegradability thresholds commanding substantial markups. Cost compression in standard liquid tiers is intensifying because ready-mix batch plants negotiate volume-based annual contracts. Industrial users in Texas and Florida exhibit highest price sensitivity, while Bavarian restoration specialists demonstrate lowest sensitivity due to specification lock-in.
Supply Chain Analysis
Contract-manufacturing concentration for glycolic acid derivatives sits with Chinese and Indian specialty chemical producers, while German and Swiss houses retain captive production of enzymatic platforms. Raw material flows draw from phosphate rock processing in Morocco and China, citric acid fermentation in Thailand and Brazil, and chelating agent synthesis in Germany. Single-source vulnerability in phosphoric acid feedstock creates exposure to fertilizer industry demand swings. Distribution runs through construction supply wholesalers in North America and direct bulk agreements for European industrial users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in chelating agent synthesis and substrate compatibility testing is concentrated among aging technical workforces, creating a capability bottleneck that will constrain formulation innovation velocity.
For Market Incumbents: Insulate premium positioning by deepening backward integration into biodegradable chelating agent production and securing exclusive supply agreements with heritage restoration contractors in Germany and Italy. The enzymatic platform threat from R&D-intensive chemical conglomerates demands accelerated field trial investment to maintain performance parity claims. For New Entrants and Emerging Players: Foam dissolver systems for demolition pre-treatment in China's Yangtze River Delta represent the most penetrable entry point, given MEE enforcement of dual carbon goals and limited incumbent specialization. Partnering with equipment rental channels in the US Sun Belt offers a capital-light go-to-market path that bypasses wholesale distributor consolidation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among industrial batch plant operators with automated dosing systems, suggesting long-term viability rests on securing specification lock-in through service bundling. Acquisition targets should prioritize enzymatic platform developers with demonstrated limestone-substrate compatibility. The signal to watch is OSHA permissible exposure limit tightening, which would accelerate substitution toward low-fume alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chelating Agent Synthesis | Captive supply of biodegradable formulations reduces REACH compliance cost exposure for German manufacturers. |
| Long-term Supply Agreement with Heritage Restoration Specialists | Specification lock-in with Bavarian monument preservation programs secures premium pricing tiers. |
| Joint Venture for Enzymatic Platform Development | Combines mineral acid kinetics with biological catalysis to close performance gaps on high-density residues. |
| Capacity Expansion in Automated Dosing Systems | Texas and California ready-mix plants demand integrated bulk supply to reduce drum cleaning downtime. |
| Green Manufacturing Transition to Citric Acid Platforms | MEE dual carbon goals in China and REACH thresholds in Europe favor biodegradable alternatives. |
Research Methodology
Cross-validation between primary interviews with formulation chemists, ready-mix plant managers, and heritage restoration contractors and secondary validation through customs trade data, SEC filings of construction chemical conglomerates, and EPA enforcement records anchors the qualitative findings. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators across the analysis window.
Calibration against historical volume trajectories in drum cleaning applications and bridge deck rehabilitation contracts shapes the analytical framework. Segmentation dimensions include formulation chemistry tier, application surface orientation, end-user procurement method, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand curves incorporating phosphoric acid feedstock volatility and municipal infrastructure budget cycles.
Macroeconomic conditions sit as an overlay; deviation in construction spending indices and fertilizer industry demand swings would shift the trajectory. Forecasts reflect documented assumptions on enzymatic performance parity achievement timelines and OSHA regulatory compression schedules. Quarterly review of heritage restoration contract awards and ready-mix plant automation investment announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Construction
South America Anchors and Grouts Market
Specialty Construction
Temporary Fencing Panels Market
Specialty Construction
Global Fencing Market
Specialty Construction
Shotcrete Accelerators Market
Specialty Construction
Slab Repair Products Market
Specialty Construction
Fire Hydrants Market
Specialty Construction
ASEAN Waterproofing Market
Specialty Construction
Asia-Pacific Anchors and Grouts Market
Specialty Construction
Asia-Pacific Waterproofing Solutions Market
Specialty Construction
India Anchors and Grouts Market
Specialty Construction
Portable Walls Market
Specialty Construction
Indonesia Anchors and Grouts Market
Specialty Construction
Roller Shutter Market
Specialty Construction
Construction Repaint Market
Specialty Construction
Europe Anchors and Grouts Market
Specialty Construction
Indonesia Waterproofing Solutions Market