
 Shopping Centers Market | 2026-2036
Shopping Centers Market Size, Share, and Industry Trends Forecast 2026-2036
Shopping Centers Market Intelligence
Experiential retail and entertainment-oriented tenant mixes is expanding within shopping center portfolios. Simon Property Group leverages its scale to anchor premium entertainment venues in superregional malls. Taubman Centers specializes in luxury retail environments that sustain higher per-square-foot productivity. Westfield LLC competes through urban-format properties positioned near transit corridors.
Shopping centers are purpose-built commercial complexes integrating retail storefronts, food service, entertainment, and service amenities within controlled pedestrian environments, typically ranging from neighborhood-scale properties to mega centers exceeding one million square feet of gross leasable area. Community centers and lifestyle centers represent the fastest-growing size categories as developers prioritize convenience-oriented formats with lower capital intensity and faster lease-up timelines. Regional malls retain the largest share of total leasable inventory but face structural pressure from e-commerce substitution, while food courts and entertainment venues command disproportionate foot traffic and extended dwell times.
Local zoning boards, the EPA, and municipal building codes shape shopping center development through density restrictions, environmental impact assessments, and accessibility mandates. Fire safety standards from the National Fire Protection Association and energy efficiency benchmarks from ASHRAE impose ongoing compliance costs on owners of large-format properties. Stakeholders must monitor how evolving municipal incentives for mixed-use conversion reshape the investability of obsolete mall assets.
Market Dynamics
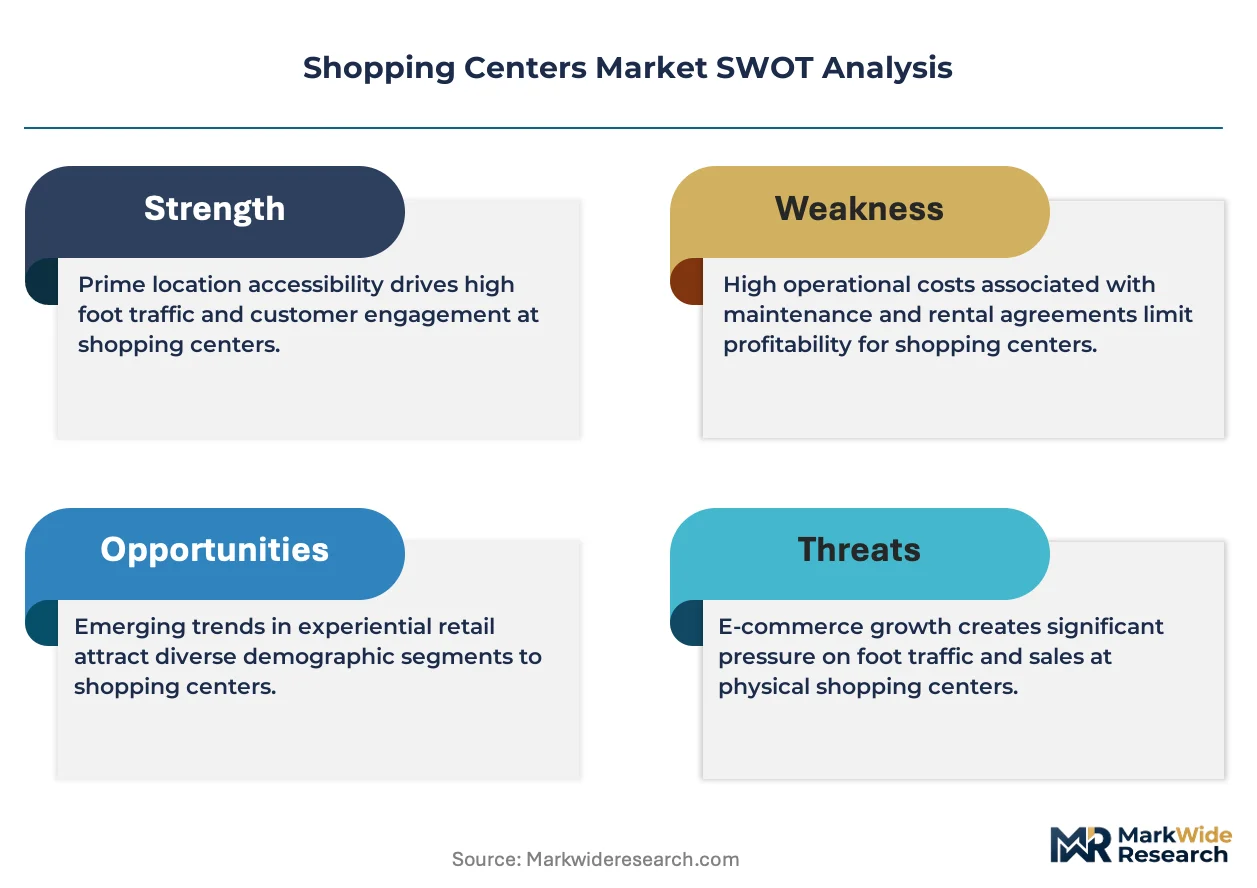
Experiential retail formats are compressing traditional lease structures as foot traffic migrates toward entertainment-anchored properties, forcing landlords to renegotiate tenant mixes and dwell-time metrics.
Growth Catalysts
- Municipal zoning reforms:Select North American metros accelerate mixed-use redevelopment approvals for aging retail assets, unlocking densification premiums.
- Experiential retail demand:Families and young adults drive repeat visitation to entertainment-oriented tenant configurations, extending average visit duration.
- Transit-oriented development:Urban-format properties positioned near commuter corridors capture higher pedestrian capture rates and premium rents.
Market Restraints
- E-commerce substitution:Regional malls face structural vacancy pressure as apparel and electronics sales migrate to digital channels.
- Capital intensity barriers:Large-format redevelopment requires sustained construction financing unavailable to mid-scale ownership groups.
- Environmental compliance costs:ASHRAE energy efficiency benchmarks and EPA assessments impose recurring operational expenditures on aging inventory.
Strategic Opportunities
- Obsolete mall conversion:Underutilized regional mall sites in the United States present infill residential and logistics repositioning potential.
- Community center expansion:Convenience-oriented formats with faster lease-up timelines attract institutional capital seeking yield stability.
- Food service integration:Culinary halls and local chef concepts replace traditional food courts, commanding higher per-square-foot sales productivity.
Industry Challenges
- Tenant credit underwriting:Experiential operators carry higher default risk than national retail chains, complicating lease guarantee structures.
- Phased redevelopment coordination:Mixed-use conversions require synchronized residential pre-sales and retail pre-leasing timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shopping Centers Market |
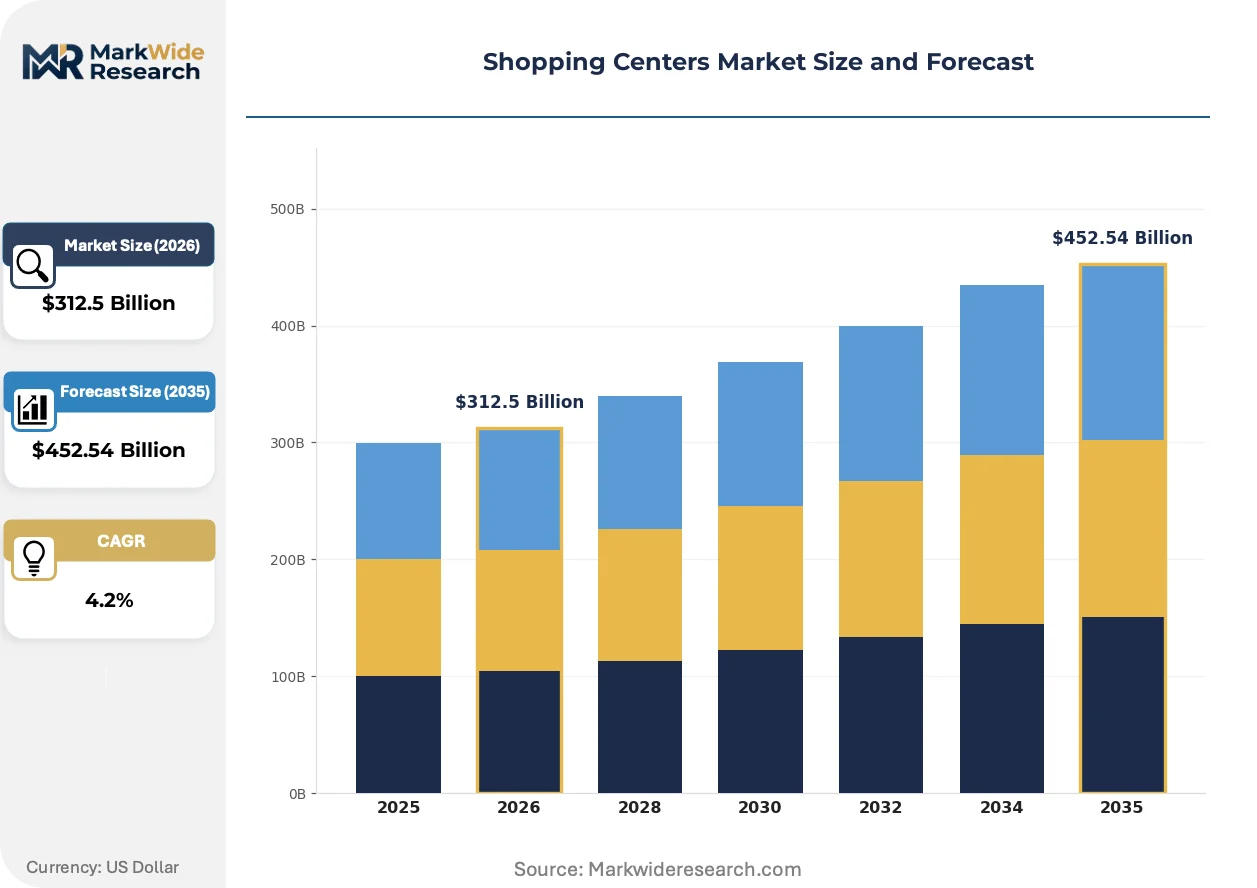
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $452.54 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Regional Malls, Superregional Malls, Community Centers, Lifestyle Centers Customer Type: Families, Young Adults, Seniors, Tourists Commercial Offering: Retail Stores, Food Courts, Entertainment Venues, Service Facilities Size: Small Centers, Medium Centers, Large Centers, Mega Centers |
| Companies Covered | Centro Properties Group, The Inland Real Estate Group, Simon Property Group, Taubman Centers, Weingarten Realty, General Growth Properties, Westfield LLC, Philips Edison & Co., Kimco Realty, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shopping Centers Market Strategic Shifts & Innovations
Digital infrastructure and tenant experience platforms are redefining how shopping centers capture and monetize visitor data, shifting competitive advantage toward technology-enabled operators.
Smart building management systems is unifying HVAC, lighting, and security controls into single-dashboard operations. Institutional landlords deploy these platforms across superregional portfolios to reduce energy expenditures and predictive maintenance costs. This convergence is unifying operational silos that previously required separate vendor relationships and capital planning cycles.
REACH chemical safety regulations in Europe impose substance disclosure requirements on construction materials and interior finishes. Shopping center developers sourcing cross-border building products face expanded documentation obligations and supplier audit protocols. Retail tenants with EU expansion plans now prioritize lease structures that accommodate material substitution timelines.
Visitor data monetization is emerging as a distinct revenue layer as footfall analytics platforms mature. Mall operators in the United Arab Emirates and Australia package anonymized movement patterns to anchor tenants and adjacent property developers. This behavioral intelligence exchange displaces traditional co-tenancy clauses as the primary mechanism for tenant placement optimization.
Shopping Centers Market Segmentation
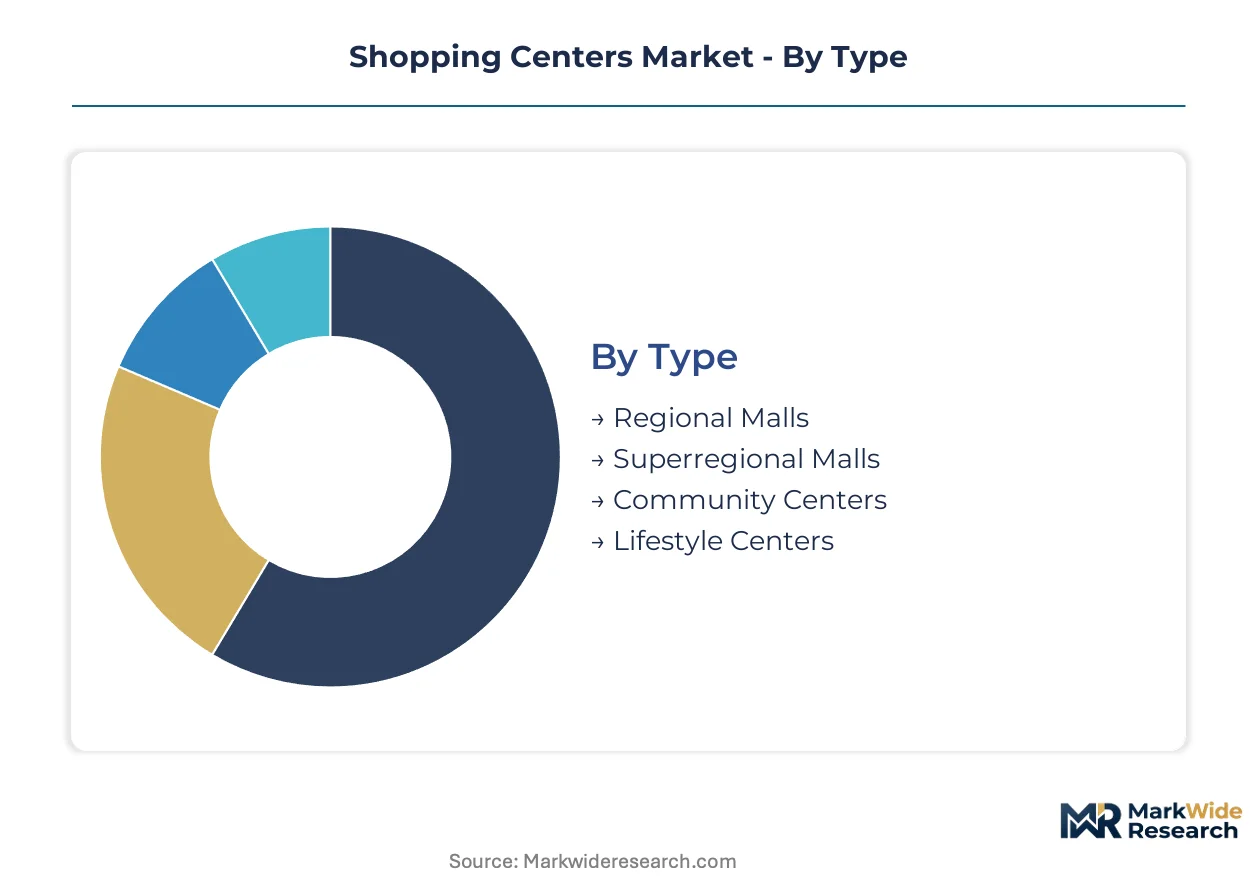
Shopping center developers calibrate format specifications against local demand density and capital availability. Segmentation decisions determine lease structures, anchor tenant profiles, and repositioning flexibility across asset lifecycles.
Type:
Format customization ranges from enclosed climate-controlled environments to open-air configurations with lower operational overhead.
- Regional Malls:Enclosed properties typically anchor department stores and national retail chains within 400,000 to 800,000 square feet of gross leasable area. These assets concentrate in suburban United States corridors where household density supports sustained foot traffic, though e-commerce substitution pressures vacancy rates and tenant credit quality.
- Superregional Malls:Properties exceeding 800,000 square feet integrate premium entertainment venues and destination dining alongside retail. Simon Property Group deploys this format to capture extended dwell times from families and young adults seeking experiential outings rather than transactional shopping.
- Community Centers:Convenience-oriented formats prioritize grocery anchors and service retail with faster lease-up timelines and lower capital intensity.
- Lifestyle Centers:Open-air configurations emphasize local chef concepts and boutique retail in pedestrian-friendly streetscapes.
Leading the category by volume: Regional Malls. Expanding most quickly: Lifestyle Centers.
Customer Type:
Visitor composition shapes tenant mix decisions and operating hour configurations across portfolio assets.
- Families:Multi-generational units drive weekend visitation peaks and demand integrated entertainment-anchored properties with supervised activity zones and diverse dining options.
- Young Adults:Demographic cohorts aged 18-34 prioritize social media-worthy experiences, local culinary concepts, and fitness-oriented amenities over traditional apparel retail.
- Seniors:Daytime-dominant visitation patterns favor accessible parking, seated rest areas, and medical service integration.
- Tourists:Transient visitors concentrate in United Arab Emirates and Australian gateway cities where shopping centers function as destination attractions rather than convenience retail.
Most concentrated by foot traffic: Families. Steepest expansion trajectory: Young Adults.
Commercial Offering:
Revenue mix diversification separates experiential-anchored properties from transaction-dependent formats.
- Retail Stores:Traditional merchandise sales occupy the largest share of leasable area but face margin compression from digital channel substitution.
- Food Courts:Quick-service aggregations are yielding to culinary halls with local chef concepts that command higher per-square-foot productivity and extended dwell times.
- Entertainment Venues:Cinema complexes, indoor adventure parks, and immersive experience operators generate repeat visitation from experience-seeking customer segments.
- Service Facilities:Medical clinics, fitness centers, and personal service providers occupy peripheral space with stable credit profiles.
Dominant by lease revenue: Retail Stores. Gaining share fastest: Entertainment Venues.
Size:
Capital deployment scale determines repositioning flexibility and institutional investor access.
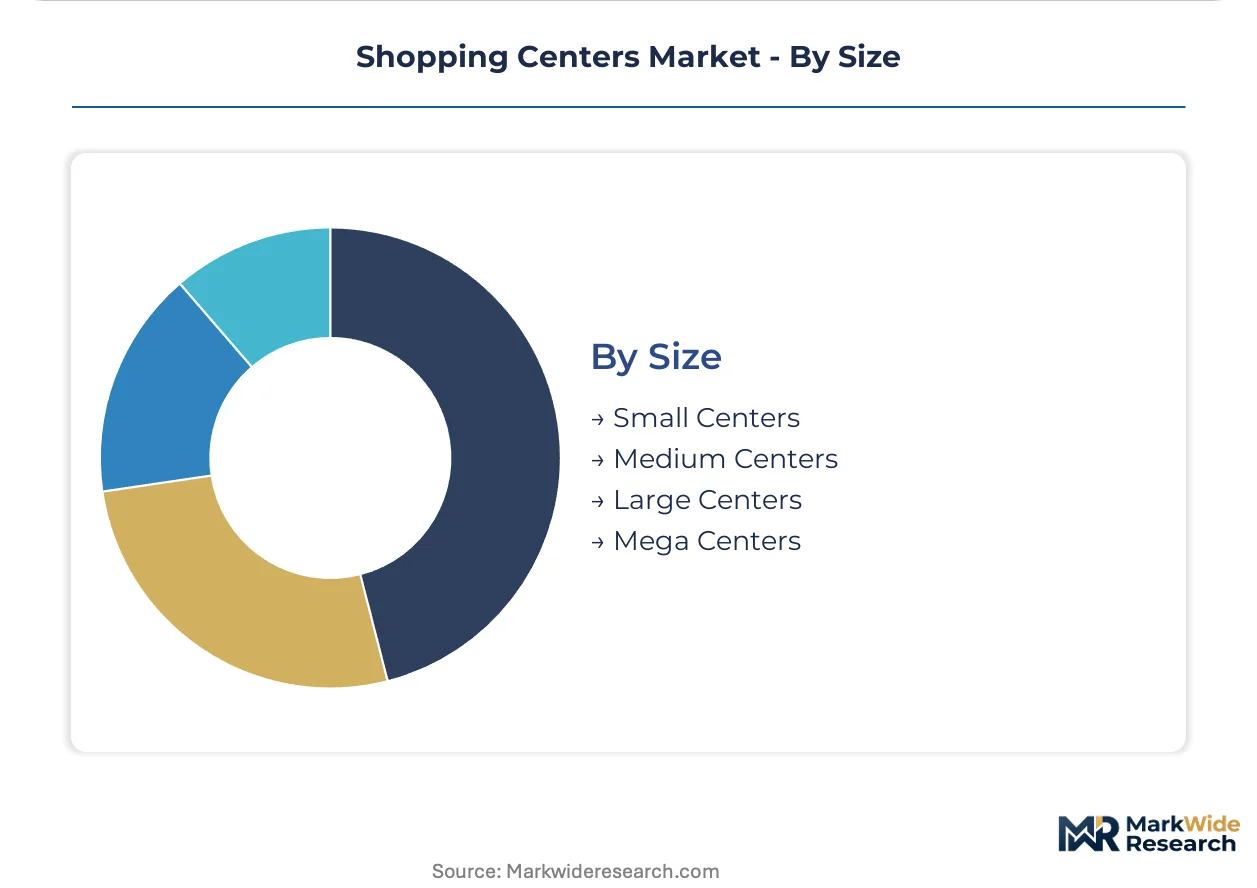
- Small Centers:Neighborhood-scale properties under 100,000 square feet serve convenience retail with limited entertainment integration.
- Medium Centers:Mid-market formats balance anchor tenant stability with specialty retail diversification.
- Large Centers:Properties exceeding 400,000 square feet require sustained construction financing and sophisticated asset management capabilities.
- Mega Centers:Developments surpassing one million square feet integrate residential, office, and hospitality components in mixed-use configurations.
Most numerous by asset count: Small Centers. Climbing the fastest: Large Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Developed markets consume the bulk of experiential retail investment, while emerging economies concentrate new construction pipelines. Supply chains for construction materials and entertainment technology span multiple continents.
United States
Municipal zoning reforms in metros like Austin and Denver accelerate mixed-use conversions of obsolete regional malls. The EPA enforces environmental assessments on large-format redevelopments. Simon Property Group anchors superregional entertainment venues across suburban Texas and Florida corridors.
United Arab Emirates
Tourist visitation and luxury retail demand drive mega-center expansions in Dubai and Abu Dhabi. MOHAP regulates commercial space health and safety standards. Mall operators package anonymized footfall analytics to anchor tenants in the Dubai Marina cluster.
Australia
Transit-oriented lifestyle centers capture premium rents near Sydney and Melbourne commuter corridors. The TGA influences medical service tenant integration through clinic licensing requirements. Westfield LLC competes through urban-format properties positioned along the Sydney Metro expansion.
China
Domestic consumption stimulus and middle-class leisure spending expand experiential retail footprints in tier-one cities. MIIT governs smart building system certifications for new developments. Mixed-use mega centers integrate residential and office components in the Yangtze River Delta cluster.
Germany
Energy efficiency mandates and brownfield redevelopment incentives reshape community center construction in Berlin and Munich. REACH chemical safety regulations impose substance disclosure requirements on interior finishes. Taubman Centers specializes in luxury retail environments that sustain higher productivity in the Frankfurt Rhine-Main region.
Shopping Centers Market Key Industry Players
Top-tier vendors anchor superregional and mega-center portfolios, while mid-scale operators concentrate on convenience-oriented community formats. Institutional capital access separates scale players from regional developers. Three archetypes dominate: integrated entertainment-anchored landlords, luxury retail specialists, and transit-oriented urban formatters. Competitive moves center on mixed-use conversion partnerships and smart building technology licensing.
Among North American-based landlords, Simon Property Group, Taubman Centers, and Westfield LLC occupy distinct positioning vectors. Simon Property Group represents the scale-driven entertainment anchor archetype. Taubman Centers exemplifies luxury retail environment specialization. Westfield LLC sits within the transit-oriented urban format tier, leveraging proximity to commuter infrastructure.
| Leading Market Players |
|---|
| Centro Properties Group |
| The Inland Real Estate Group |
| Simon Property Group |
| Taubman Centers |
| Weingarten Realty |
| General Growth Properties |
| Westfield LLC |
| Philips Edison & Co. |
| Kimco Realty |
| Others |
Cost & Logistics Intelligence
Steel price indices and construction material benchmarks cascade through shopping center development budgets, compressing developer margins on large-format projects while creating pricing stratification between institutional-scale landlords and mid-market operators.
Pricing Analysis
Margin tightening in superregional mall repositioning reflects ASHRAE energy compliance retrofit costs and extended construction financing timelines. Three-tier pricing structure across premium, standard, and economy levels separates trophy assets with entertainment anchors from convenience-oriented community centers. Price differentiation hinges on footfall analytics capabilities and smart building certification tiers. Cost-down pressure on mid-market formats accelerates because institutional capital concentrates in experiential-anchored properties with proven dwell-time metrics.
Supply Chain Analysis
Regional distribution centers for entertainment technology and HVAC systems anchor hub-and-spoke patterns across the United States, the United Arab Emirates, and Australia. Manufacturing concentrates in China for digital infrastructure components, Germany for building automation systems, and South Korea for LED and display technologies. Raw material dependencies span structural steel, copper wiring, and specialized glass curtainwall systems. Single-source vulnerability in smart building control modules creates procurement risk for phased redevelopments. Distribution runs through specialized commercial real estate logistics networks serving tenant improvement and capital expenditure cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA environmental assessments and ASHRAE energy benchmarks construct a cost-of-compliance barrier that favors institutional landlords with dedicated sustainability teams and long-dated capital commitments.
For Market Incumbents: To counter e-commerce substitution in regional mall apparel and electronics categories, Simon Property Group and peers accelerate entertainment-anchored tenant mixes while deploying backward integration into proprietary footfall analytics platforms. Certification investment in smart building management systems defends rent premiums against transit-oriented lifestyle center competition. For New Entrants and Emerging Players: Capture obsolete mall conversion opportunities in Austin and Denver where municipal zoning reforms unlock densification premiums for mixed-use residential repositioning. The most penetrable segment lies in mid-scale community center food service integration, replacing legacy food courts with local chef culinary halls through joint venture structures with regional restaurant groups. For Investors and Strategic Acquirers: Distressed-cycle entries favor superregional mall operators with demonstrated experiential tenant placement capabilities in Florida and Texas suburban corridors. Long-term viability across the analysis window rests on conversion execution timelines synchronized with residential pre-sales. The signal to watch is municipal incentive program adoption rates for mixed-use redevelopment approvals.| Strategic Initiative | Industry Significance |
|---|---|
| Obsolete Mall Conversion | Unlocks residential and logistics repositioning potential on underutilized suburban sites in the United States. |
| Smart Building Technology Licensing | Reduces ASHRAE compliance costs through unified HVAC and lighting control dashboards across institutional portfolios. |
| Experiential Tenant Partnership | Generates repeat visitation from families and young adults seeking entertainment-anchored destinations rather than transactional retail. |
| Transit-Oriented Development Expansion | Captures premium rents near Sydney Metro and Dubai Metro commuter corridors with urban-format properties. |
| Food Service Integration | Replaces traditional food courts with culinary halls commanding higher per-square-foot sales productivity from local chef concepts. |
Research Approach
Document review covered municipal zoning filings, EPA environmental assessment records, and ASHRAE compliance documentation, complemented by interviews with shopping center asset managers, municipal planning directors, experiential tenant operators, and institutional real estate investors. Secondary validation drew from SEC REIT filings, trade association construction cost indices, and smart building technology vendor disclosures. Bottom-up lease revenue modeling and top-down macroeconomic scenario analysis enabled triangulation across data sources.
Market size outputs incorporate segment-level projections across format type, customer demographic, commercial offering mix, and asset size tier throughout the forecast period. CAGRs derive from historical absorption rates, capital availability trends, and regulatory implementation timelines specific to mixed-use redevelopment incentives. Modeled inputs include entertainment technology deployment cycles, transit infrastructure completion schedules, and municipal zoning reform adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to e-commerce penetration rates, construction financing availability, and energy efficiency mandate stringency. Outputs reflect documented assumptions around experiential retail demand durability and municipal incentive program continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate
Nigeria Facility Management Services Market
Real Estate
Luxembourg Facility Management Market
Real Estate
Spain Residential Real Estate Market
Real Estate
Relocation Management Service Market
Real Estate
Turkey Residential Real Estate Market
Real Estate
Europe Condominiums and Apartments Market
Real Estate
United States Luxury Residential Real Estate Market
Real Estate
Hong Kong Warehousing Market
Real Estate
Global Manufactured Housing Market
Real Estate
Singapore Luxury Residential Real Estate Market
Real Estate
United Arab Emirates Real Estate Services Market
Real Estate
India Luxury Residential Real Estate Market
Real Estate
Czech Republic Facility Management Market
Real Estate
Singapore Self-Storage Market
Real Estate
Iceland Facility Management Market
Real Estate
South Korea Office Real Estate Market