
 Europe Condominiums and Apartments Market | 2026-2036
Europe Condominiums and Apartments Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Condominiums and Apartments Market Foresight
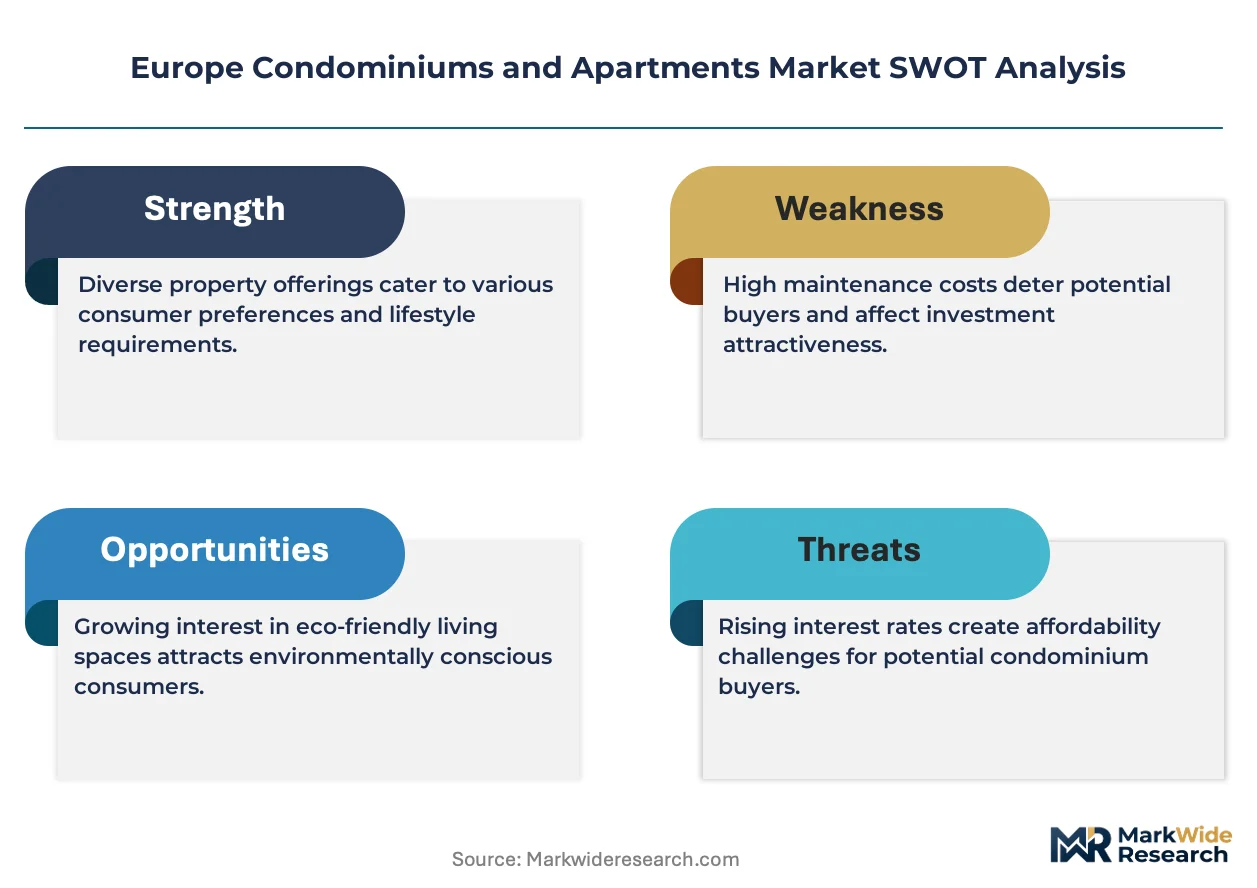
Property management fee income is narrowing as a share of total returns as European institutional landlords shift capital toward development-to-core strategies. Vonovia SE leverages its scale across German metropolitan clusters to control operating costs per unit. LEG Immobilien AG anchors its portfolio in North Rhine-Westphalia and Lower Saxony, competing on density-adjusted yields. Elm Group differentiates through energy-efficient refurbishment pipelines that qualify for national subsidy programs.
Europe condominiums and apartments encompass individually owned residential units within multi-unit structures, typically featuring reinforced concrete or steel-frame construction with shared common elements including lobbies, elevators, and mechanical systems; these assets serve as primary housing stock, rental income vehicles, and wealth preservation instruments for households and institutions. Luxury apartments command persistent price premiums in central business districts, while studio apartments attract the fastest-growing renter cohort of single-person households in Madrid, Berlin, and Lisbon. The renovated units segment carries outsized regulatory compliance costs but captures deepening margin pools as EU Green Deal deadlines tighten building performance standards.
The EU Green Deal and national transpositions under the Energy Performance of Buildings Directive shape product standards by mandating near-zero energy thresholds for new construction and major renovations. ESG disclosure rules under CSRD and national building codes in France, Germany, and Italy constrain market access for non-compliant developers and force capital allocation toward retrofit pipelines. Stakeholders must monitor how REPowerEU-linked financing instruments and evolving mortgage greenium spreads reshape acquisition underwriting criteria.
Market Dynamics
The EU Green Deal's Energy Performance of Buildings Directive is compressing renovation timelines across European multifamily portfolios. Institutional landlords now face capital allocation decisions between demolition-rebuild and deep energy retrofit pathways as national transpositions tighten compliance windows.
Growth Catalysts
- CSRD disclosure mandates:Corporate Sustainability Reporting Directive rules force institutional investors to quantify building-level emissions, redirecting capital toward certified green assets in France and Germany.
- Single-person household formation:Demographic shifts in Madrid, Berlin, and Lisbon drive absorption of micro-units and studio apartments purpose-built for solo renters.
- REPowerEU financing instruments:Subsidized retrofit loans accelerate building envelope upgrades that qualify apartments for green mortgage spreads.
Market Restraints
- Construction input volatility:Reinforced concrete and steel-frame material costs fluctuate with energy-intensive production curbs under EU ETS phase-in schedules.
- Skilled trade scarcity:Certified energy auditors and deep retrofit contractors concentrate in German and French metropolitan clusters, constraining pipeline velocity elsewhere.
- Interest rate sensitivity:Floating-rate development finance exposes projects to ECB policy transmission, compressing yield spreads in leveraged acquisitions.
Strategic Opportunities
- Portuguese secondary cities:Lisbon's price escalation pushes yield-seeking capital toward Porto and Coimbra where renovation pipelines remain underdeveloped.
- Heat pump integration:Hybrid systems combining air-source heat pumps with legacy district heating infrastructure unlock compliance in Nordic and Baltic apartment stocks.
- Build-to-rent institutionalization:Professionalized operating platforms capture management fee pools previously fragmented among small private landlords in Spain and Italy.
Industry Challenges
- Cross-border contractor coordination:EU-wide project delivery requires navigating divergent national building codes and trade certification reciprocity gaps.
- Tenant displacement during deep retrofit:Temporary relocation logistics and rent stabilization rules complicate construction phasing in rent-controlled jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Condominiums and Apartments Market |
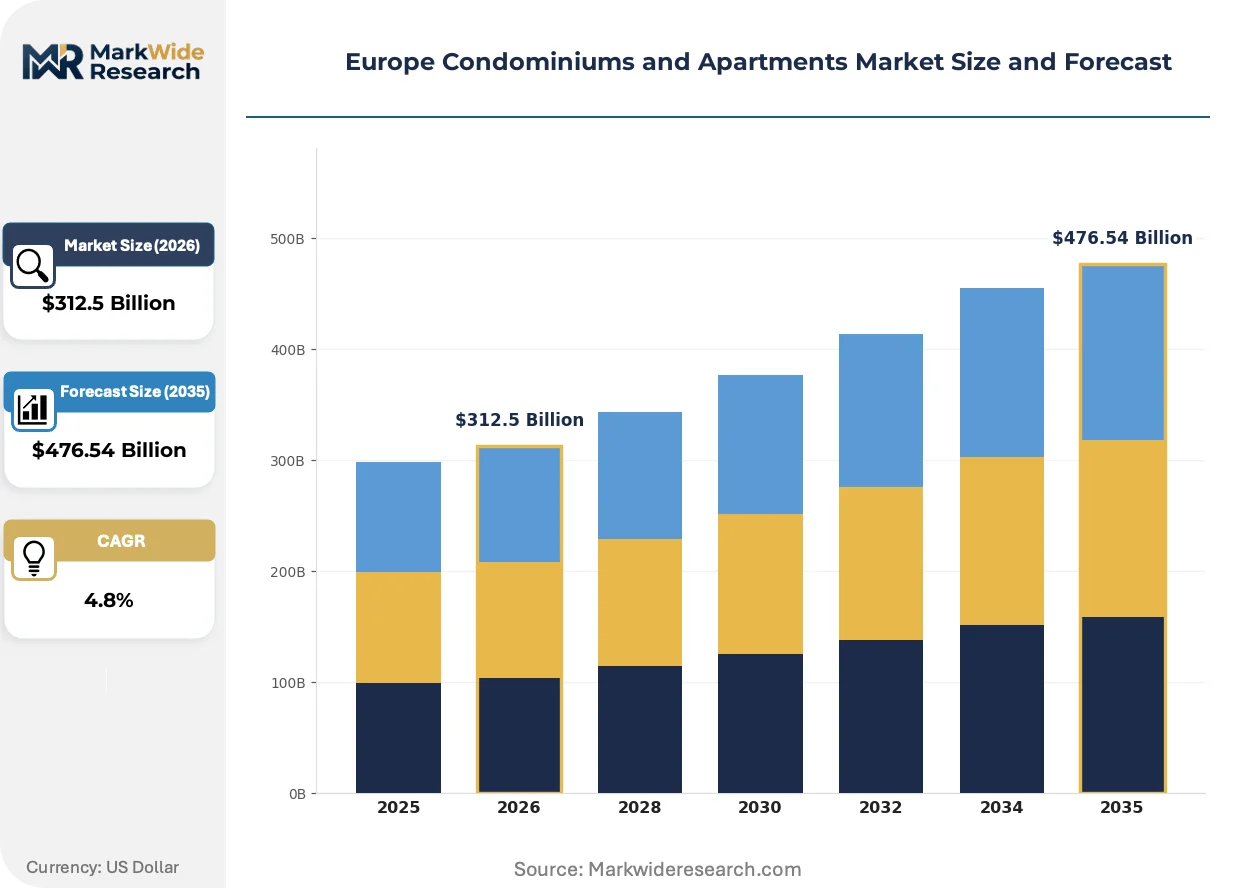
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $476.54 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury Apartments, Studio Apartments, One-Bedroom Condominiums, Two-Bedroom Condominiums End User: Investors, First-time Buyers, Retirees, Vacation Home Buyers Price Tier: Affordable, Mid-range, Premium, High-end Building Type: New Construction, Renovated Units, High-rise Buildings, Low-rise Buildings |
| Companies Covered | Vonovia SE, LEG Immobilien AG, Elm Group, CPI Property Group, Aroundtown Property Holdings, Places for People Group Limited, Castellum AB, Altarea Cogedim, Covivio, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Condominiums and Apartments Market Shifts & Advancements
Building automation and prefabrication are compressing construction timelines while regulatory pressure forces asset-level energy transparency. These forces reshape how European multifamily portfolios are financed, operated, and traded.
Prefabricated bathroom and kitchen modules are migrating from niche hospitality applications into mid-market apartment construction. German and Dutch developers adopt volumetric methods to cut on-site labor hours by half. The technology is migrating from speed advantages toward quality consistency that reduces post-handover defect liability.
Energy Performance Certificates under the EU Green Deal's national transpositions now trigger mortgage lending restrictions in France and Germany. Banks apply risk-weighted capital charges against non-compliant collateral. The regulatory pressure is migrating from disclosure toward outright financing prohibition for the worst-performing building stock.
Institutional lease structures are displacing traditional private landlord arrangements in Spanish and Portuguese urban cores. Build-to-rent operators offer flexible terms and bundled services that small owners cannot match. The shift concentrates demand in professionally managed assets with centralized maintenance and smart building infrastructure.
Europe Condominiums and Apartments Market Segmentation
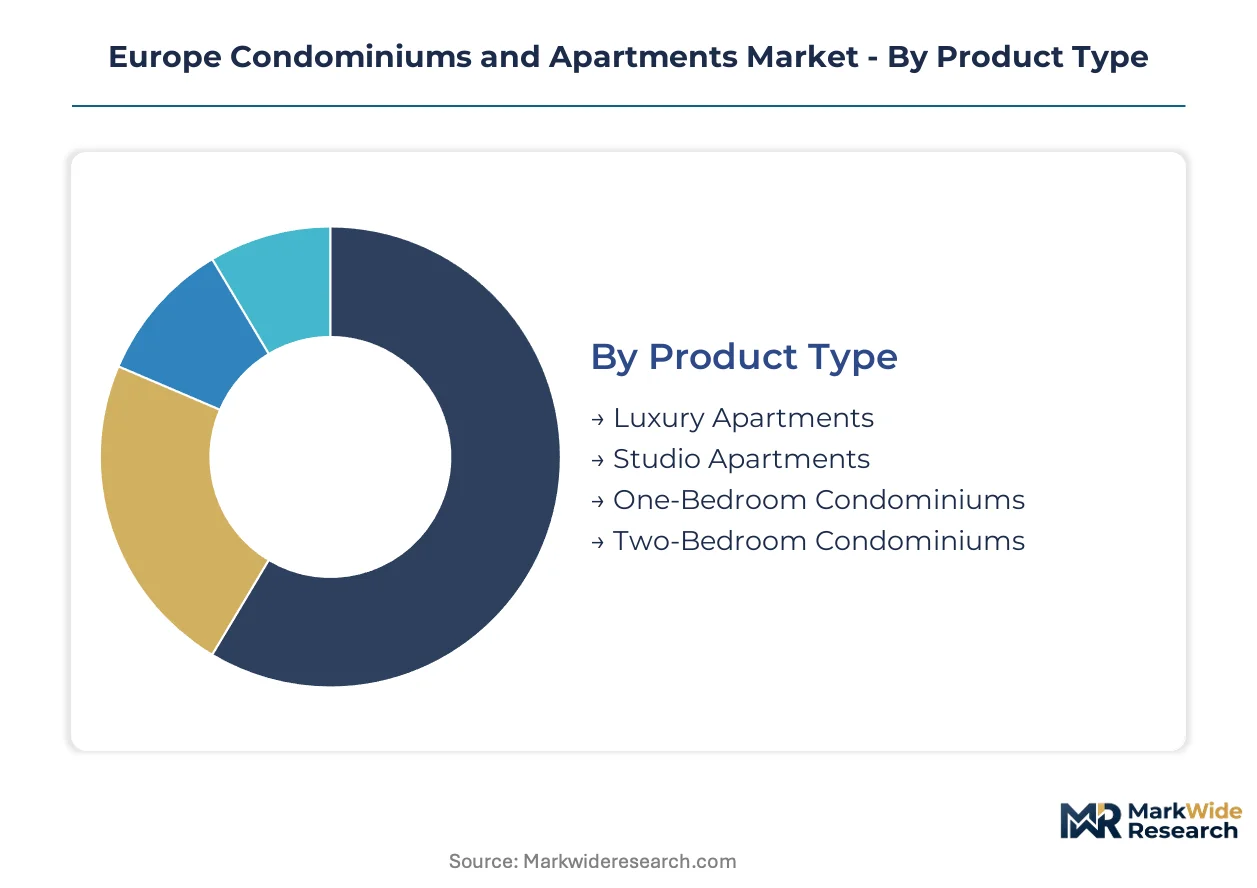
Segmentation in European multifamily housing reveals divergent capital recovery timelines and regulatory exposure profiles. Investors weight product type liquidity against end-user stability when constructing portfolios across eurozone jurisdictions.
Product Type:
Studio apartments turn inventory fastest in Lisbon and Berlin rental markets, while luxury apartments in Paris and London carry extended marketing periods. One-bedroom and two-bedroom condominiums occupy intermediate velocity positions shaped by household formation patterns.
- Luxury Apartments:Prime-location units in central business districts command sustained price premiums through reinforced concrete and steel-frame construction with concierge services and smart building infrastructure. Demand concentrates among institutional investors and high-net-worth individuals in Frankfurt, Munich, and Milan seeking inflation hedges and visa-linked residency programs.
- Studio Apartments:Compact single-room units optimized for solo occupancy with integrated kitchenettes and space-efficient layouts. Madrid, Berlin, and Lisbon absorb these fastest as single-person household formation outpaces family-oriented development pipelines.
- One-Bedroom Condominiums:Separate sleeping quarters appeal to young professionals in Amsterdam and Copenhagen prioritizing location over square footage.
- Two-Bedroom Condominiums:Dual-bedroom configurations attract remote-worker couples in Barcelona and Vienna seeking dedicated home office space.
Two-bedroom condominiums anchor the volume base while studio apartments gain share at the steepest rate.
End User:
Investor demand concentrates in German and Dutch metropolitan clusters where yield compression has been least severe. First-time buyers face mounting deposit requirements in Southern European markets where mortgage greenium spreads widen access gaps.
- Investors:Institutional landlords and private buy-to-let operators acquire stabilized rental income streams, with Vonovia SE and LEG Immobilien AG dominating German multifamily aggregation. Yield-seeking capital flows into Porto and Coimbra as Lisbon price escalation accelerates.
- First-time Buyers:Households entering ownership face stricter Energy Performance Certificate requirements under EU Green Deal national transpositions that restrict mortgage availability for non-compliant collateral. French and German banks apply risk-weighted capital charges against poor-performing building stock.
- Retirees:Downsizing households prioritize single-level access and proximity to healthcare infrastructure in Spanish Costa del Sol and Portuguese Algarve markets.
- Vacation Home Buyers:Seasonal occupancy investors target Alpine ski condominiums and Mediterranean coastal apartments with fractional ownership structures.
Investors anchor the volume base while first-time buyers face the steepest access barriers.
Price Tier:
Affordable segments carry heaviest regulatory compliance burdens as EU Green Deal deadlines force capital-intensive retrofits. Premium and high-end tiers absorb green technology costs through pricing power in supply-constrained central locations.
- Affordable:Subsidized and social housing units subject to rent stabilization and tenant protection regimes complicate renovation phasing in French and Italian rent-controlled jurisdictions.
- Mid-range:Mass-market condominiums in suburban Warsaw and Prague clusters compete on transport connectivity and school district proximity.
- Premium:Upper-middle specifications with energy-efficient certifications qualify for REPowerEU financing instruments and green mortgage spreads in Nordic markets.
- High-end:Ultra-luxury penthouses and branded residences in Monaco, Geneva, and Luxembourg trade through private placement with minimal market transparency.
Mid-range units anchor the volume base while premium tier assets expand most quickly.
Building Type:
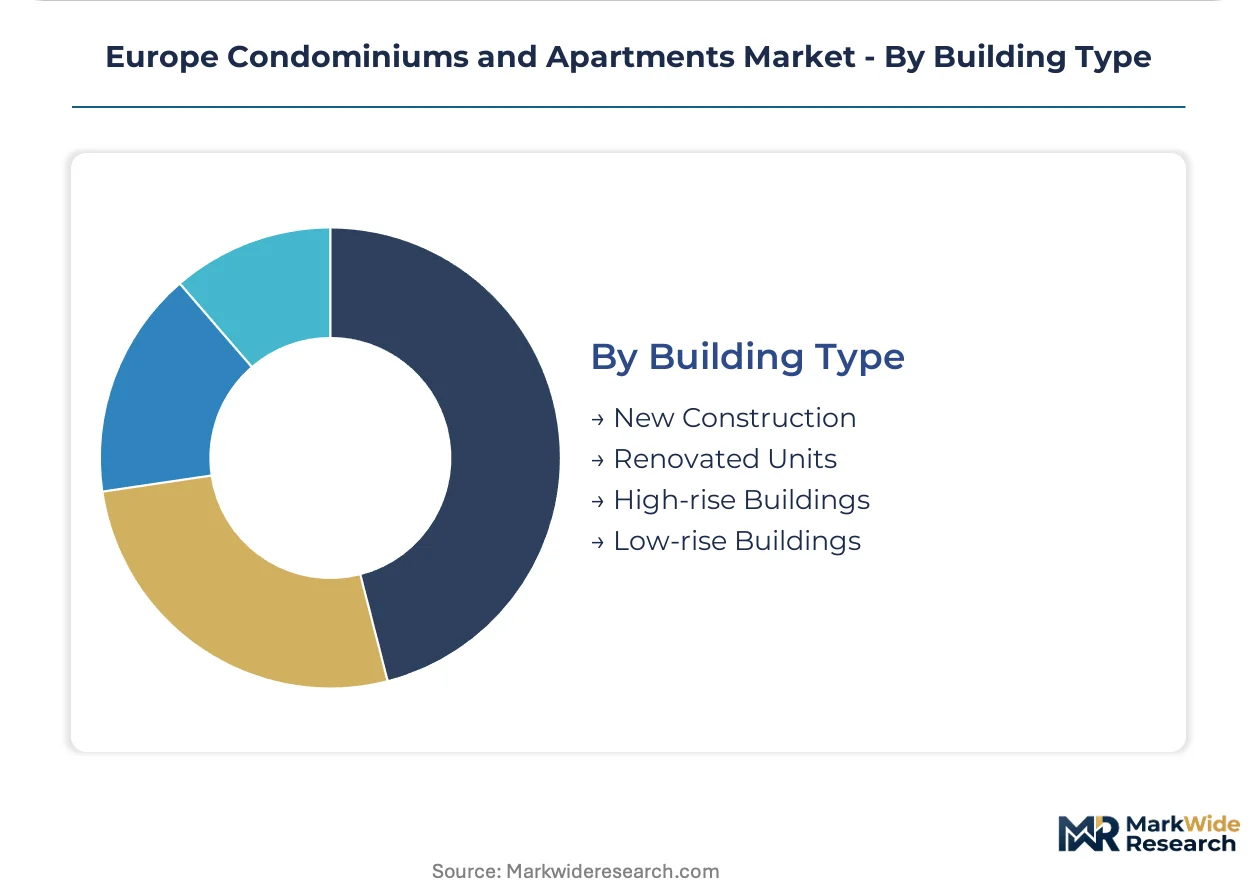
New construction carries extended approval timelines under tightening environmental impact assessments. Renovated units face compressed compliance windows as Energy Performance of Buildings Directive transpositions accelerate across member states.
- New Construction:Ground-up development with near-zero energy thresholds mandated by national building codes in France, Germany, and Italy. Prefabricated bathroom and kitchen modules cut on-site labor hours for German and Dutch developers.
- Renovated Units:Deep energy retrofits of existing stock qualify for national subsidy programs but trigger tenant displacement logistics and rent stabilization complications. Elm Group differentiates through refurbishment pipelines targeting these incentives.
- High-rise Buildings:Vertical density in Warsaw and Bucharest city centers maximizes land value but requires specialized facade maintenance reserves.
- Low-rise Buildings:Garden-style apartments in suburban Stockholm and Helsinki clusters integrate heat pump systems with legacy district heating infrastructure.
Renovated units anchor the volume base while new construction climbs the fastest as developers front-run tightening standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spanish and Portuguese buyers demonstrate the highest price elasticity as Lisbon and Madrid absorption rates fluctuate with mortgage rate movements, while German institutional demand remains inelastic due to yield-seeking capital allocation and index-linked rental contracts.
Germany
Institutional landlords dominate acquisition activity in Berlin, Munich, and Hamburg as private households retreat from deposit requirements. The national building energy code transposition of the Energy Performance of Buildings Directive mandates near-zero energy thresholds for new construction by 2028. Vonovia SE and LEG Immobilien AG concentrate portfolio density across North Rhine-Westphalia and Lower Saxony metropolitan clusters.
France
First-time buyers face mounting Energy Performance Certificate barriers as French banks apply risk-weighted capital charges against non-compliant collateral under CSRD-linked disclosure rules. The REPowerEU financing instruments subsidize deep retrofit loans that qualify renovated Parisian apartments for green mortgage spreads. Altarea Cogedim anchors development pipelines in Île-de-France and secondary city cores.
Spain
Single-person household formation drives studio apartment absorption in Madrid and Barcelona at rates outpacing family-oriented unit deliveries. National transpositions of EU Green Deal building codes compress renovation timelines for existing rental stock. Build-to-rent institutionalization concentrates in Madrid's Chamartín and Barcelona's 22@ districts as professionalized platforms displace fragmented private landlords.
Italy
Retiree downsizing demand concentrates in Milan and Rome central districts while younger households migrate to peripheral transit corridors. Rent stabilization regimes complicate deep retrofit phasing in rent-controlled jurisdictions across Lombardy and Lazio. Covivio positions energy-efficient refurbishment pipelines to capture national subsidy programs targeting building envelope upgrades.
Netherlands
Prefabricated volumetric construction methods cut on-site labor hours by half for Dutch developers targeting Amsterdam and Rotterdam density zones. The Energy Performance of Buildings Directive national transposition accelerates compliance windows for existing social housing stock. Institutional lease structures displace traditional private arrangements in Randstad urban cores as bundled service offerings concentrate demand in professionally managed assets.
Europe Condominiums and Apartments Market Competitive Landscape
Capability concentration sits with specialized retrofit contractors holding certified energy auditor credentials; scale advantage sits with integrated landlords commanding portfolio-wide procurement leverage. The market structures around three tiers: pan-European institutional aggregators with development-to-core strategies, national mid-cap specialists competing on density-adjusted yields, and local value-add operators targeting subsidy-qualifying renovation pipelines. Dominant competitive moves include portfolio consolidation through block trades and vertical integration into in-house property management platforms.
Among German-based institutional landlords, Vonovia SE and LEG Immobilien AG exemplify the scale-driven tier through metropolitan cluster density, while Elm Group represents the specialization vector through energy-efficient refurbishment pipelines. These three entities anchor distinct strategic positions: Vonovia SE leverages cross-portfolio operating cost control, LEG Immobilien AG competes on North Rhine-Westphalia geographic concentration, and Elm Group differentiates through national subsidy program qualification.
| Leading Market Players |
|---|
| Vonovia SE |
| LEG Immobilien AG |
| Elm Group |
| CPI Property Group |
| Aroundtown Property Holdings |
| Places for People Group Limited |
| Castellum AB |
| Altarea Cogedim |
| Covivio |
| Others |
Supply & Pricing Matrix
EU ETS carbon border adjustments on reinforced concrete and steel-frame inputs determine both construction cost tier spreads and supply chain geography across European multifamily development. Developers front-run compliance deadlines by locking long-term offtake agreements with certified low-carbon suppliers, compressing margins on spot-market material procurement.
Pricing Analysis
Long-term offtake contracts dominate institutional development pipelines, insulating Vonovia SE and LEG Immobilien AG from spot volatility in cement and structural steel. Price differentiation hinges on Energy Performance Certificate tier and green mortgage eligibility, with near-zero energy units commanding financing spreads unavailable to standard stock. Cost compression in mid-range segments intensifies as REPowerEU subsidies concentrate demand on certified contractors. First-time buyers exhibit acute price sensitivity, while institutional aggregators absorb premium tiers with index-linked rental contracts.
Supply Chain Analysis
Export-control regimes on heat pump compressors and building automation controllers limit flows from Chinese and South Korean manufacturers into EU retrofit pipelines. Supply concentrates in German, Dutch, and Polish prefabrication facilities for volumetric bathroom and kitchen modules. Reinforced concrete, engineered timber, and facade systems anchor raw material dependencies. Single-source vulnerability runs through certified energy auditor networks concentrated in French and German metropolitan clusters. Distribution runs through national developer-procurement consortia and cross-border contractor alliances serving pan-European institutional landlords.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern European multifamily housing as smart building infrastructure and centralized property management systems create winner-take-most dynamics. Interoperability between energy monitoring, tenant services, and financing qualification systems determines which assets capture institutional capital flows.
For Market Incumbents: Build switching-cost moats through captive energy service company structures that bundle heating, maintenance, and insurance into single-contract offerings. Deepen retrofit contractor relationships to lock scarce certified labor capacity. Consolidate block trades in Spanish and Portuguese urban cores before build-to-rent institutionalization fragments acquisition opportunities.
For New Entrants and Emerging Players: Build out white-space positions in Portuguese secondary cities where Porto and Coimbra renovation pipelines remain underdeveloped relative to Lisbon price escalation. Target studio apartment micro-units in Madrid and Berlin where single-person household formation outstrips supply. Pursue subsidy-qualifying refurbishment specialization as the fastest path to institutional capital access.
For Investors and Strategic Acquirers: Energy Performance of Buildings Directive national transpositions reshape the acquisition landscape by rendering non-compliant collateral ineligible for regulated bank financing. Long-term viability centers on portfolios with clear retrofit pathways to near-zero energy thresholds. Acquisition targets should display concentrated geographic density enabling procurement leverage. Monitor mortgage greenium spread compression as the signal for capital rotation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Development-to-Core Pipeline Conversion | Institutional landlords capture yield compression by self-delivering stabilized assets in Berlin and Munich clusters. |
| Deep Retrofit Contractor Verticalization | In-house energy auditor and certified trades capacity secures pipeline velocity under tightening compliance windows. |
| Smart Building Infrastructure Deployment | Centralized IoT platforms generate operating data that qualifies assets for CSRD-compliant ESG disclosure. |
| REPowerEU Financing Instrument Access | Subsidized loan qualification unlocks green mortgage spreads and reduces weighted average cost of capital. |
| Prefabricated Module Manufacturing Scale-Up | German and Dutch developers cut on-site labor hours by half through volumetric construction methods. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with property development executives, portfolio managers at institutional landlords, national energy agency officials, and certified retrofit contractors; and secondary validation against EU Green Deal national transposition documents, Energy Performance Certificate databases, ECB mortgage lending surveys, and REPowerEU financing instrument disclosures. Bottom-up unit economics and top-down sector aggregation were triangulated against cross-referenced regulatory filings.
Forecast inputs incorporated construction cost indices, household formation demographics, and mortgage rate transmission effects across the projection horizon. Segmentation dimensions modeled include product type, end-user category, price tier, and building type. CAGRs were derived from supply-demand balance projections and capital flow velocity assumptions. Energy Performance of Buildings Directive compliance timelines and CSRD disclosure phase-ins shaped scenario weightings.
Stress conditions across ECB policy rates, construction input costs, and tenant relocation logistics were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and subsidy program continuity. Material shifts in Energy Performance of Buildings Directive transposition schedules or REPowerEU funding allocations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condominium and Apartments
Latin America Condominiums and Apartments Market
Condominium and Apartments
UAE Condominiums and Apartments Market
Condominium and Apartments
India Condominium and Apartments Market
Condominium and Apartments
ASEAN Condominiums and Apartments Market
Condominium and Apartments
Canada Condominiums and Apartments Market
Condominium and Apartments
Egypt Condominiums and Apartments Market
Condominium and Apartments
Asia-Pacific Condominiums and Apartments Market
Condominium and Apartments
Global Condominiums and Apartments Market
Condominium and Apartments
Germany Condominiums and Apartments Market
Condominium and Apartments
Spain Condominiums and Apartments Market
Condominium and Apartments
Condom Market
Condominium and Apartments
Qatar Condominium and Apartment Market
Condominium and Apartments
Saudi Arabia Condominiums and Apartments Market
Condominium and Apartments
Japan Condominiums and Apartments Market
Condominium and Apartments
Italy Condominiums and Apartments Market