
 United States Office Real Estate Market | 2026-2036
United States Office Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
United States Office Real Estate Market Analytics
Class A specification upgrades is rotating capital toward higher-quality assets with superior HVAC, floorplates, and amenity packages. Blackstone Inc. leverages its scale to acquire and reposition dated towers into premium product. Hines anchors development pipelines in transit-oriented submarkets with institutional-grade construction. Brookfield competes through its integrated operating platform spanning acquisition, development, and property management.
United States office real estate comprises income-producing commercial buildings designed for professional services, typically constructed with steel or reinforced concrete frames, curtain wall glazing systems, and floor-to-floor heights of 13 to 15 feet to accommodate raised-floor infrastructure and mechanical distribution. Class A assets command rent premiums in gateway markets while smart building integrations drive operating efficiency across the stock. Green certified properties attract corporate tenants with net-zero commitments, and flex spaces capture demand from firms seeking lease term optionality without traditional long-term obligations.
EPA energy benchmarking rules, SEC climate disclosure mandates, and local jurisdictions adopting ASHRAE ventilation standards collectively reshape tenant requirements and capital allocation decisions. FERC interconnection queues for on-site renewables and municipal electrification codes further filter which assets qualify for institutional capital. Stakeholders must monitor how evolving ESG compliance thresholds redefine obsolescence risk across the existing building stock.
Market Dynamics
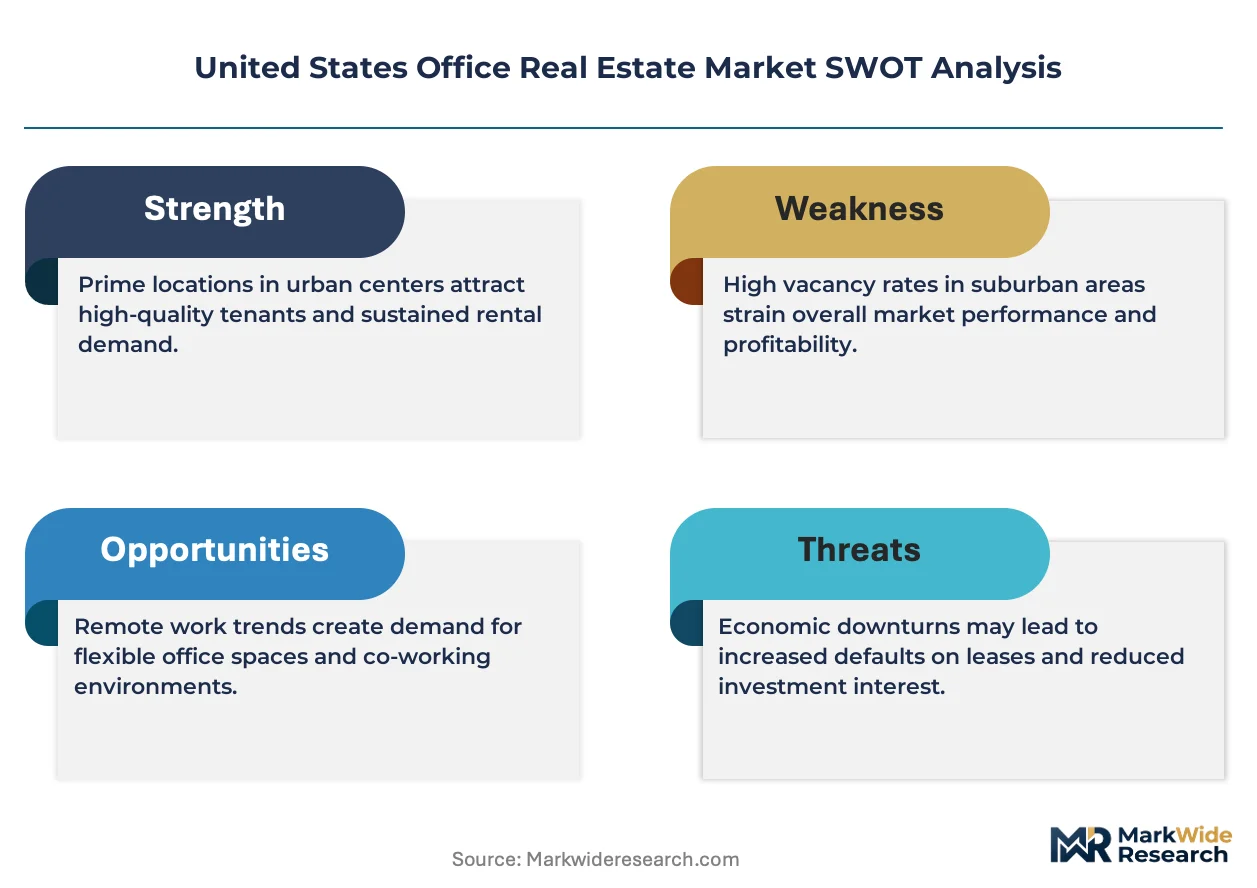
The SEC's climate disclosure rules are compressing capital flows toward green-certified assets while stranding Class B inventory in secondary metros. Institutional investors now treat ASHRAE ventilation compliance and on-site renewable interconnection as threshold criteria rather than value-add features.
Growth Catalysts
- Technology sector expansion:Cloud computing and AI labs are absorbing premium Class A floorplates in Austin, Nashville, and Raleigh-Durham with above-market tenant improvement allowances.
- IRA clean energy incentives:The Inflation Reduction Act's investment tax credits accelerate on-site solar and battery storage deployment across office rooftops and parking structures.
- FERC interconnection reforms:Queue reform proposals aim to reduce utility-scale renewable connection delays, enabling faster electrification of building systems.
Market Restraints
- Construction cost escalation:Steel and concrete input volatility, combined with skilled labor shortages in electrical and HVAC trades, compress development yields on speculative projects.
- Regional bank exposure:Concentrated CRE loan portfolios at sub-$100 billion asset institutions create refinancing friction for maturing office mortgages.
- Remote work persistence:Hybrid schedules reduce effective space utilization rates, lengthening lease rollover exposure in legacy central business district towers.
Strategic Opportunities
- Adaptive reuse conversions:Obsolete suburban office parks in Texas and Florida present repositioning candidates for life science and logistics facilities with lower basis costs.
- Smart building convergence:Integration of IoT sensors with AI-driven HVAC optimization creates differentiated operating expense structures for net-zero-committed tenants.
- Transit-oriented submarkets:EPA-funded brownfield remediation and FTA rail extensions unlock development sites in Denver, Salt Lake City, and Charlotte with embedded transportation access premiums.
Industry Challenges
- ESG data verification gaps:Inconsistent utility benchmarking across municipal disclosure regimes complicates green bond eligibility and GRESB scoring for cross-portfolio assets.
- Electrification retrofit complexity:Legacy steam heating distribution and asbestos-containing materials in pre-1980s buildings obstruct heat pump conversions and full building electrification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Office Real Estate Market |
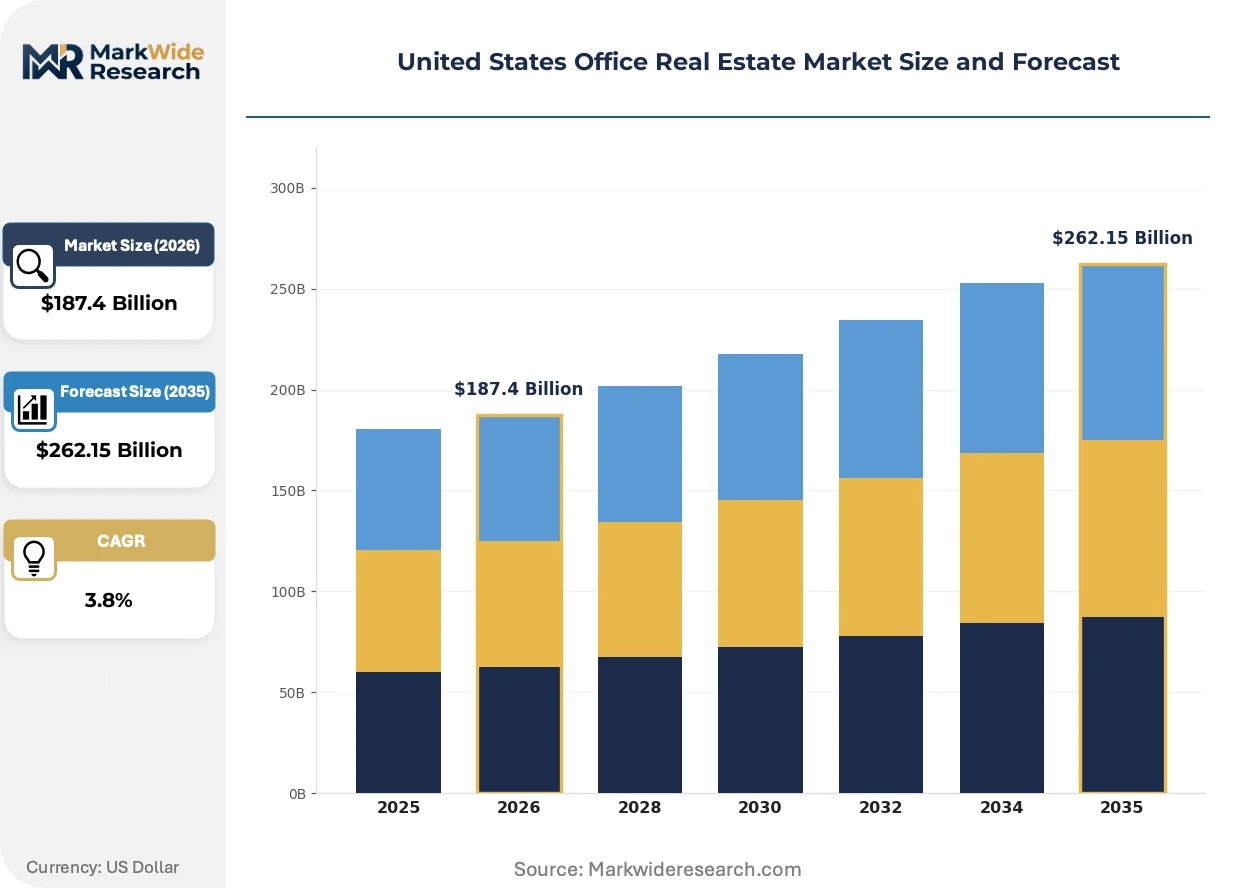
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $262.15 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Class A, Class B, Class C, Co-working Spaces, Flex Spaces Lease Term: Short-term, Mid-term, Long-term, Month-to-Month, Triple Net Occupant Industry: Technology Firms, Financial Services, Legal Services, Consulting Agencies, Government Entities Building Feature: Green Certified, Smart Building, High-rise, Low-rise, Renovated Historic |
| Companies Covered | CBRE Investment Management, Nuveen Real Estate, Blackstone Inc., Starwood Capital Group, Hines, Brookfield, PGIM Real Estate Inc., LaSalle Investment Management, Invesco Investment Services, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Office Real Estate Market Evolving Landscape
Capital allocation is rotating toward operating platforms that compress energy intensity and lease friction simultaneously. Three distinct vectors are reshaping how buildings compete for tenant commitment and institutional equity.
Smart building infrastructure is bifurcating the competitive landscape between connected assets and stranded inventory. Sensors monitoring occupancy, air quality, and thermal comfort feed AI-driven HVAC adjustments that cut operating expenses. Technology and professional services tenants now specify API-accessible building systems as standard lease requirements.
EPA benchmarking mandates and SEC climate disclosure rules are hardening ESG compliance from voluntary marketing to contractual necessity. Landlords must procure third-party verification of energy and carbon metrics to satisfy institutional lease covenants. Assets without LEED, BREEAM, or WELL certification face exclusion from corporate occupier shortlists and green-focused investment mandates.
Tenant procurement of space is compressing toward shorter-term, flexible structures with embedded expansion rights. Enterprise users are trading traditional ten-year commitments for three-to-five-year leases with modular square footage adjustments. This preference shift is most visible in Sun Belt metros where technology and healthcare services firms prioritize operational agility over occupancy cost stability.
United States Office Real Estate Market Segmentation
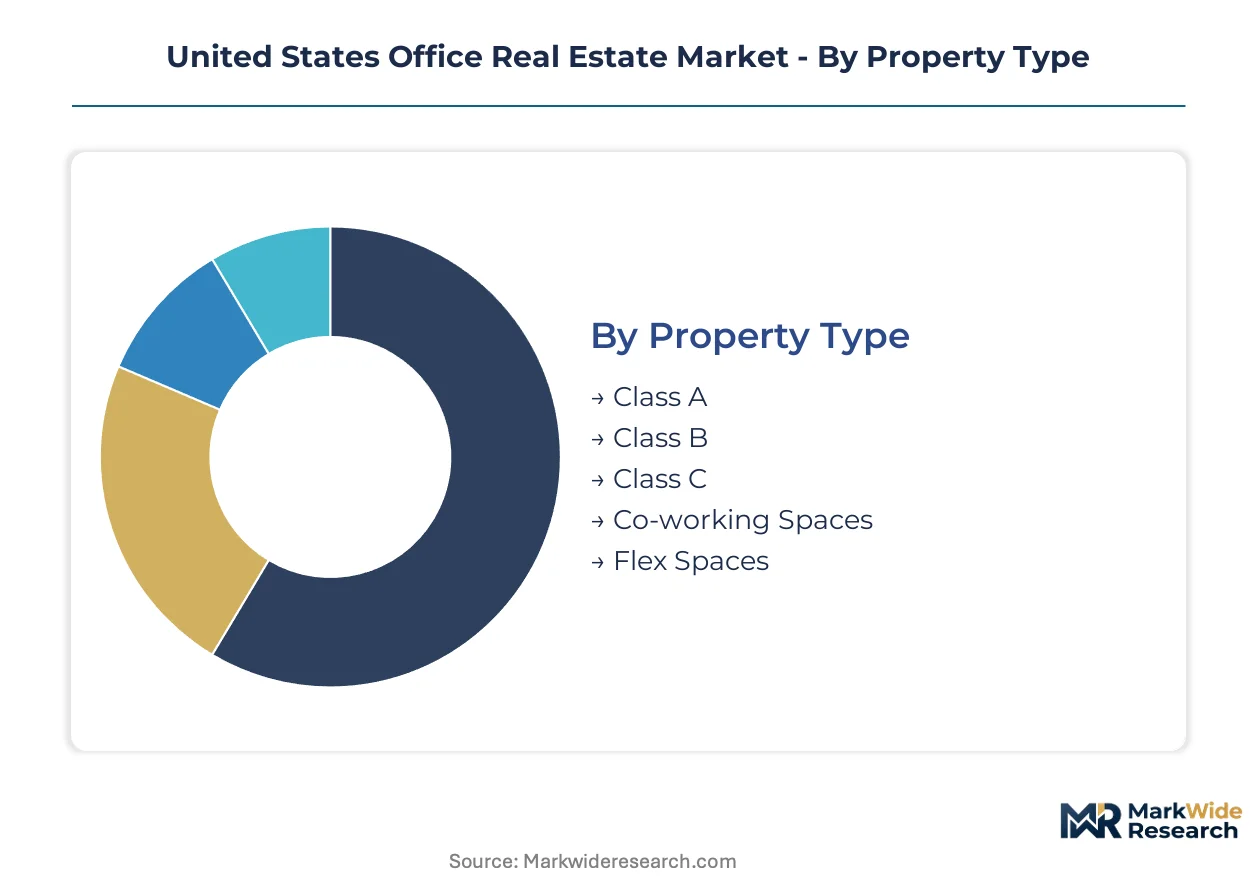
Segmentation reveals how capital allocation and tenant procurement diverge across quality tiers, lease structures, and functional specifications. Understanding these divisions exposes where obsolescence risk concentrates and where repositioning opportunities emerge.
Property Type:
Substitution pressure from flex and co-working models is eroding traditional multi-year lease economics, forcing Class B and C assets toward functional obsolescence.
- Class A:Premium construction with floor-to-floor heights of 13 to 15 feet accommodates raised-floor infrastructure and advanced mechanical distribution. Technology firms in Austin and Nashville absorb these assets with above-market tenant improvement allowances, prioritizing HVAC performance and amenity density.
- Class B:Aging infrastructure with dated curtain wall systems and inferior thermal performance faces stranded capital risk as SEC climate disclosure rules harden tenant requirements. Regional bank exposure concentrates refinancing friction in these assets across secondary metros.
- Class C:Functional obsolescence accelerates as corporate occupiers with net-zero commitments filter these assets from shortlists entirely.
- Co-working Spaces:WeWork's restructuring and operator consolidation have compressed valuations, though demand persists among early-stage technology firms seeking lease term optionality.
- Flex Spaces:Hybrid work persistence drives procurement toward modular square footage with embedded expansion rights, capturing demand from professional services firms in Sun Belt metros.
Class A retains volume leadership; Flex Spaces holds the steepest expansion curve.
Lease Term:
Cost tier stratification separates institutional-grade commitments from operational agility premiums, with pricing spreads widening between certainty and flexibility.
- Long-term:Ten to fifteen-year commitments with fixed escalations dominate financial services and legal services occupancy in gateway markets. Credit tenant lease structures attract life insurance and pension fund capital seeking yield stability.
- Mid-term:Three-to-five-year structures with renewal options balance cost predictability against growth optionality. Technology firms in Raleigh-Durham favor this tier to accommodate headcount volatility.
- Short-term:Compressed commitments of one to two years command rent premiums of 15 to 25 percent above long-term equivalents.
- Month-to-Month:Maximum flexibility for project-based consulting agencies and seasonal government contractors.
- Triple Net:Operating expense pass-through structures shift HVAC, property tax, and insurance burdens to tenants, common in single-tenant suburban office and life science conversions.
Long-term commitments anchor institutional capital deployment; Short-term structures are climbing the fastest as tenant procurement compresses.
Occupant Industry:
Application-driven demand segmentation shows technology procurement diverging from traditional professional services in space specification and location strategy.
- Technology Firms:Cloud computing and AI labs specify API-accessible building systems, raised-floor load capacity, and redundant electrical infrastructure as threshold requirements. Concentration in Austin, Nashville, and Raleigh-Durham drives above-market absorption of Class A floorplates.
- Financial Services:Trading floors and compliance-intensive operations require dedicated HVAC zones and enhanced physical security, anchoring demand in central business districts with transit access.
- Legal Services:Partnership structures and client confidentiality requirements sustain traditional ten-year lease preferences in trophy assets.
- Consulting Agencies:Project-based staffing models drive preference for flex spaces with modular expansion rights.
- Government Entities:Federal procurement standards and security clearance requirements filter eligible assets, with GSA leases anchoring stability in Washington DC and regional administrative centers.
Financial Services retains volume leadership; Technology Firms are gaining share fastest.
Building Feature:
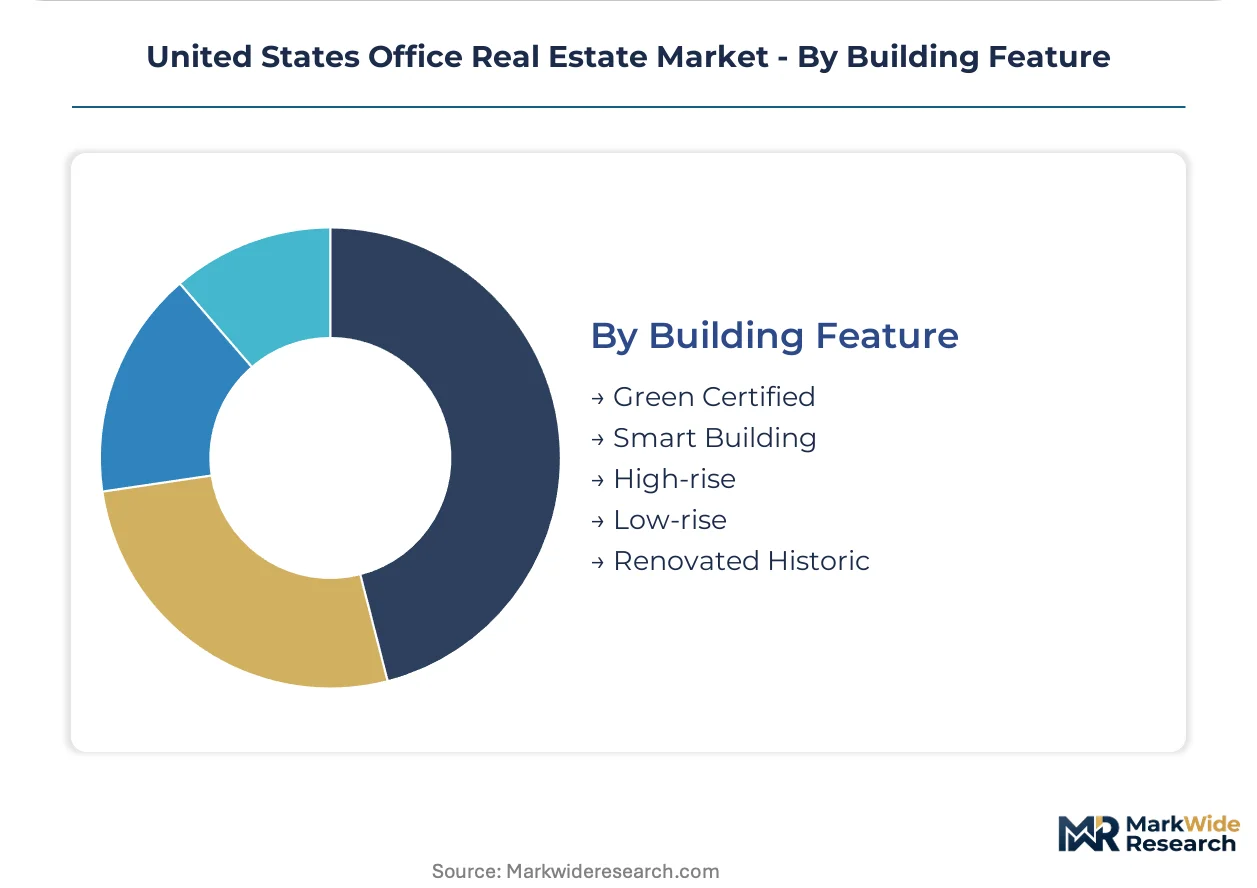
Maturity-stage differentiation separates certified, connected assets from legacy inventory facing accelerated functional obsolescence under hardening ESG compliance thresholds.
- Green Certified:LEED, BREEAM, or WELL certification provides third-party verification of energy and carbon metrics required by institutional lease covenants. EPA benchmarking mandates and SEC climate disclosure rules have transformed certification from voluntary marketing to contractual necessity.
- Smart Building:IoT sensors monitoring occupancy, air quality, and thermal comfort feed AI-driven HVAC optimization that cuts operating expenses. Technology tenants now specify API-accessible systems as standard requirements.
- High-rise:Central business district towers face lengthening lease rollover exposure as hybrid schedules reduce effective space utilization.
- Low-rise:Suburban garden product in Texas and Florida presents adaptive reuse candidates for life science and logistics conversion.
- Renovated Historic:Tax credit eligibility and character premiums attract creative-class tenants, though asbestos-containing materials obstruct full electrification timelines.
Green Certified retains volume leadership; Smart Building holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Development pipelines concentrate in Sun Belt metros where technology migration and IRA clean energy incentives compress project timelines. Institutional capital tracks EPA-funded brownfield remediation and FTA rail extensions to identify embedded transportation access premiums. Sub-regional differentiation is sharpening between transit-oriented cores and obsolete suburban inventory facing conversion pressure.
Texas
Cloud computing and AI labs from Austin to Dallas-Fort Worth absorb Class A floorplates with redundant electrical infrastructure specifications. Municipal electrification codes in Houston and San Antonio filter development permits toward heat pump-ready construction. The Austin metro anchors the steepest rent growth trajectory as technology firms prioritize operational agility over occupancy cost stability.
California
Net-zero-committed corporate tenants drive procurement toward LEED and WELL-certified assets in Los Angeles and San Francisco. The California Energy Commission's building electrification mandates accelerate heat pump conversions and obstruct legacy steam heating distribution in pre-1980s inventory. Silicon Valley submarkets face lengthening lease rollover exposure as hybrid schedules reduce effective space utilization in central business district towers.
Florida
Life science conversion candidates emerge across obsolete suburban office parks in Tampa and Orlando with lower basis costs than ground-up development. EPA energy benchmarking rules harden tenant requirements and compress capital flows toward green-certified assets. Miami's urban core attracts institutional-grade construction as FTA-funded transit extensions unlock development sites with embedded transportation access premiums.
New York Metro
Financial services and legal services sustain traditional ten-year lease preferences in trophy assets with dedicated HVAC zones and enhanced physical security. Local Law 97 carbon emissions caps force building owners toward ASHRAE ventilation compliance and on-site renewable interconnection as threshold criteria. Manhattan's central business district faces selective demand as hybrid work persistence lengthens lease rollover exposure in legacy towers.
North Carolina
Technology firms in Raleigh-Durham favor three-to-five-year lease structures with renewal options to accommodate headcount volatility. The Inflation Reduction Act's investment tax credits accelerate on-site solar deployment across Research Triangle Park rooftops and parking structures. Charlotte's EPA-funded brownfield remediation unlocks transit-oriented development sites with embedded rail access premiums.
United States Office Real Estate Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the United States office real estate market. The competitive structure tiers around scale-driven platforms with integrated operating capabilities, specialized repositioning specialists, and institutional fund managers with sector-specific mandates. Dominant competitive moves include portfolio diversification through adaptive reuse conversions and geographic concentration in Sun Belt metros with above-market absorption fundamentals.
Among scale-driven platforms, Blackstone Inc. and Brookfield occupy positions representing integrated acquisition-to-operations capabilities. Hines anchors the development-specialist archetype with institutional-grade construction pipelines in transit-oriented submarkets. CBRE Investment Management exemplifies the fund-management tier with sector-specific mandates tracking ESG compliance thresholds and tenant procurement shifts toward shorter-term, flexible lease structures.
| Leading Market Players |
|---|
| CBRE Investment Management |
| Nuveen Real Estate |
| Blackstone Inc. |
| Starwood Capital Group |
| Hines |
| Brookfield |
| PGIM Real Estate Inc. |
| LaSalle Investment Management |
| Invesco Investment Services, Inc. |
| Others |
Value Network & Pricing Analysis
Ninety-day construction material lead times in steel and curtain wall glazing systems concentrate pricing power with domestic fabricators holding strategic inventory positions, while project delays compress developer margins and accelerate procurement toward pre-committed supplier contracts. This inventory-cost nexus shapes how Class A assets command rent premiums against Class B alternatives facing stranded capital risk.
Pricing Analysis
EPA energy benchmarking mandates and SEC climate disclosure rules dictate the pricing tier structure across green-certified, smart-connected, and legacy inventory segments. Three-tier pricing structure across premium Class A, repositionable Class B, and functionally obsolete Class C levels separates assets by certification grade and HVAC performance specifications. Pricing pressure stems from construction cost escalation in electrical and HVAC trades, with technology firms in Austin and Nashville showing least price sensitivity due to above-market tenant improvement allowances, while professional services firms in secondary metros exhibit highest sensitivity to occupancy cost volatility.
Supply Chain Analysis
Just-in-time procurement dominates speculative development pipelines, though institutional developers maintain strategic stockpiles of steel framing and glazing systems to hedge against trade policy volatility. Domestic fabrication in Texas, California, and Ohio feeds from Chinese aluminum extrusions, Mexican steel rebar, and Canadian engineered lumber, creating tariff exposure at multiple input nodes. Distribution runs through regional building material distributors with direct-to-site logistics contracts, compressing last-mile delivery windows for time-sensitive tenant improvement schedules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
United States office real estate sits in early-cycle expansion as IRA clean energy incentives and FERC interconnection reforms accelerate green retrofit adoption across institutional portfolios. Technology sector absorption in Sun Belt metros provides the penetration tailwind justifying forward capital deployment.
For Market Incumbents: Fortify portfolio resilience through accelerated LEED and WELL certification investments that satisfy hardening SEC climate disclosure requirements, while consolidating operating platforms to capture scale efficiencies in HVAC optimization and tenant service delivery. Regional bank exposure in maturing mortgage portfolios presents refinancing friction that scale-driven platforms can exploit through distressed asset acquisition. For New Entrants and Emerging Players: Lead with adaptive reuse conversion expertise targeting obsolete suburban office parks in Texas and Florida, where lower basis costs enable competitive positioning against ground-up development. Life science and logistics repositioning candidates offer the most penetrable white-space, with municipal electrification code compliance as the differentiated go-to-market credential. For Investors and Strategic Acquirers: Long-term, this sits as a quality-tier consolidation play because ESG compliance thresholds are structurally bifurcating the investable universe toward certified, connected assets. Acquisition targets should emphasize transit-oriented submarkets with embedded transportation access premiums. The signal to watch is technology firm lease commencement velocity in Raleigh-Durham and Nashville as absorption inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Green Certification Acceleration | LEED and WELL credentials satisfy SEC climate disclosure mandates and institutional lease covenants. |
| Adaptive Reuse Conversion | Life science repositioning of obsolete suburban parks in Texas captures lower basis cost advantages. |
| Smart Building Integration | API-accessible HVAC systems attract technology tenants specifying IoT infrastructure as standard requirements. |
| Transit-Oriented Development | EPA-funded brownfield remediation in Denver and Charlotte unlocks sites with rail access premiums. |
| On-Site Renewable Deployment | IRA investment tax credits accelerate solar and battery storage across rooftops and parking structures. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured interviews with asset managers at institutional funds, development executives at vertically integrated platforms, tenant representation brokers, and sustainability officers at corporate occupiers with net-zero commitments. Secondary validation drew from SEC filings, EPA energy benchmarking databases, GRESB sustainability scores, and municipal building permit records. Bottom-up project pipeline tracking and top-down macroeconomic scenario modeling were triangulated to anchor volume and value estimates.
Across the analysis window, the forecasting framework modeled property type segmentation by quality tier, lease term structures by commitment duration, occupant industry verticals, and building feature specifications including certification status and connectivity infrastructure. CAGRs were derived from absorption rate trajectories, rent growth elasticities to employment concentration, and capital flow shifts toward ESG-compliant assets. IRA incentive uptake curves and FERC interconnection queue reform timelines fed specific scenario inputs.
The analysis sits within stated boundaries; outcomes outside sustained technology sector expansion in Sun Belt metros or accelerated electrification code adoption would require recalibration. Forecasts reflect assumptions regarding hybrid work persistence, regional bank credit availability, and construction cost normalization. Revision becomes warranted when remote work utilization rates cross thresholds that fundamentally alter effective space demand calculations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
Japan Office Real Estate Market
Office Real Estate
Europe Flexible Office Market
Office Real Estate
Europe Office Real Estate Market
Office Real Estate
Saudi Arabia Office Real Estate Market
Office Real Estate
Saudi Arabia Real Estate Brokerage Market
Office Real Estate
India Office Real Estate Market
Office Real Estate
India Co-Working Office Spaces Market
Office Real Estate
United States Co-Working Office Space Market
Office Real Estate
Flexible Office Market
Office Real Estate
UAE Flexible Office Space Market
Office Real Estate
Saudi Arabia Flexible Office Space Market
Office Real Estate
France Office Real Estate Market
Office Real Estate
Bahrain Co-Working Office Space Market
Office Real Estate
Office Real Estate Market
Office Real Estate
Canada Flexible Office Space Market
Office Real Estate
China Office Real Estate Market