
 United States Luxury Residential Real Estate Market | 2026-2036
United States Luxury Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
United States Luxury Residential Real Estate Market Analytics
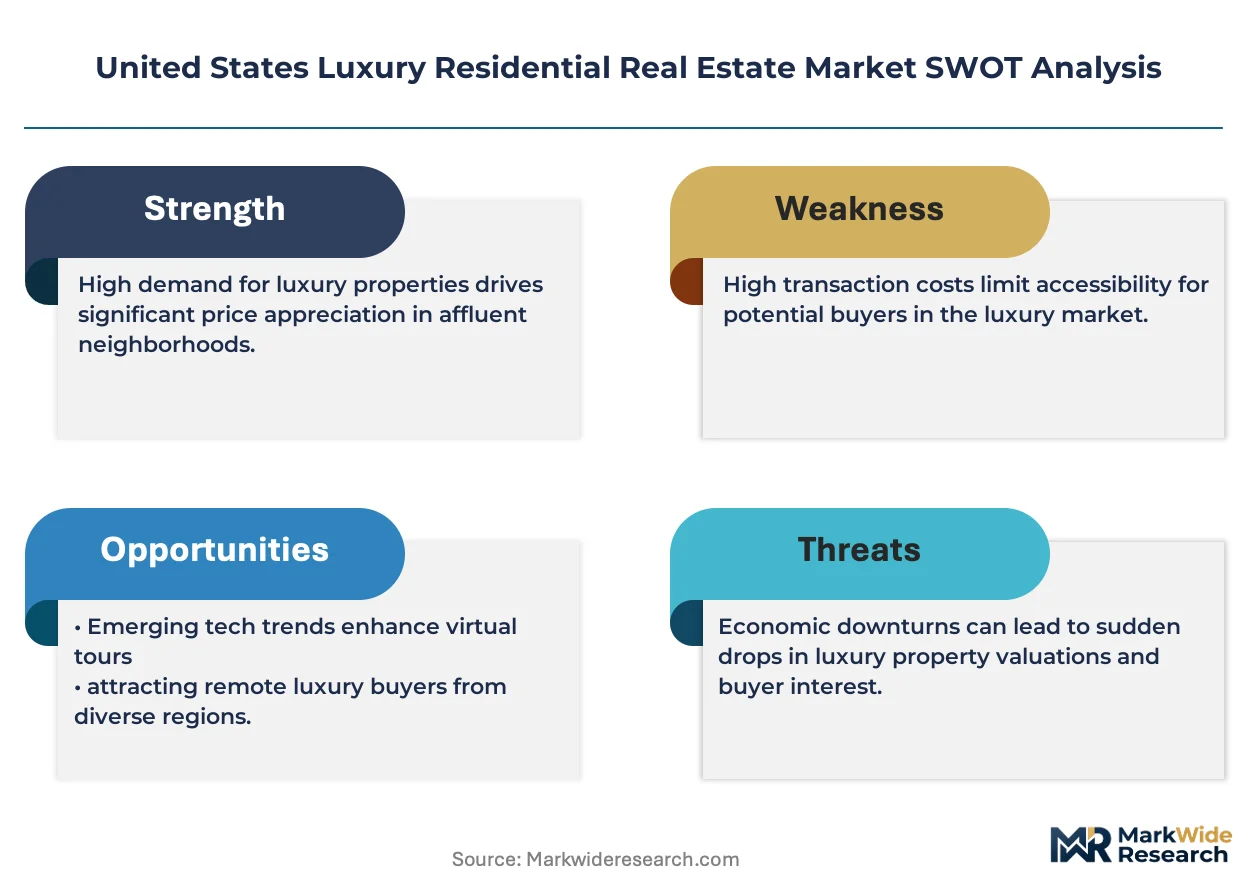
Concierge property management and subscription-based home services is rebalancing what buyers expect beyond the initial transaction. Sotheby's International Realty leverages its global referral network to sustain cross-border deal flow into Florida and California. Hines anchors its competitive position through vertical development control in trophy multifamily assets. Engel & Völkers differentiates via localized franchise expertise in resort and secondary-home markets.
United States luxury residential real estate encompasses single-family homes, condominiums, townhouses, and luxury estates trading above one million dollars, typically featuring premium materials, smart-home infrastructure, and architectural distinction designed for wealth preservation and lifestyle enhancement. Single-family homes command the deepest buyer pools and longest holding periods, while ultra-luxury estates above ten million dollars concentrate in supply-constrained coastal enclaves where scarcity supports pricing power. Condominiums in Miami and New York attract international investors seeking dollar-denominated assets, though co-op board oversight limits market access in select Manhattan buildings.
FHA lending thresholds, IRS Section 1031 exchange rules, and FinCEN beneficial ownership reporting requirements shape transaction structuring, financing availability, and disclosure obligations for domestic and foreign purchasers. State-level transfer taxes in New York and California influence timing decisions for portfolio reallocations. Stakeholders must monitor evolving beneficial ownership transparency mandates and their chilling effect on privacy-seeking international capital.
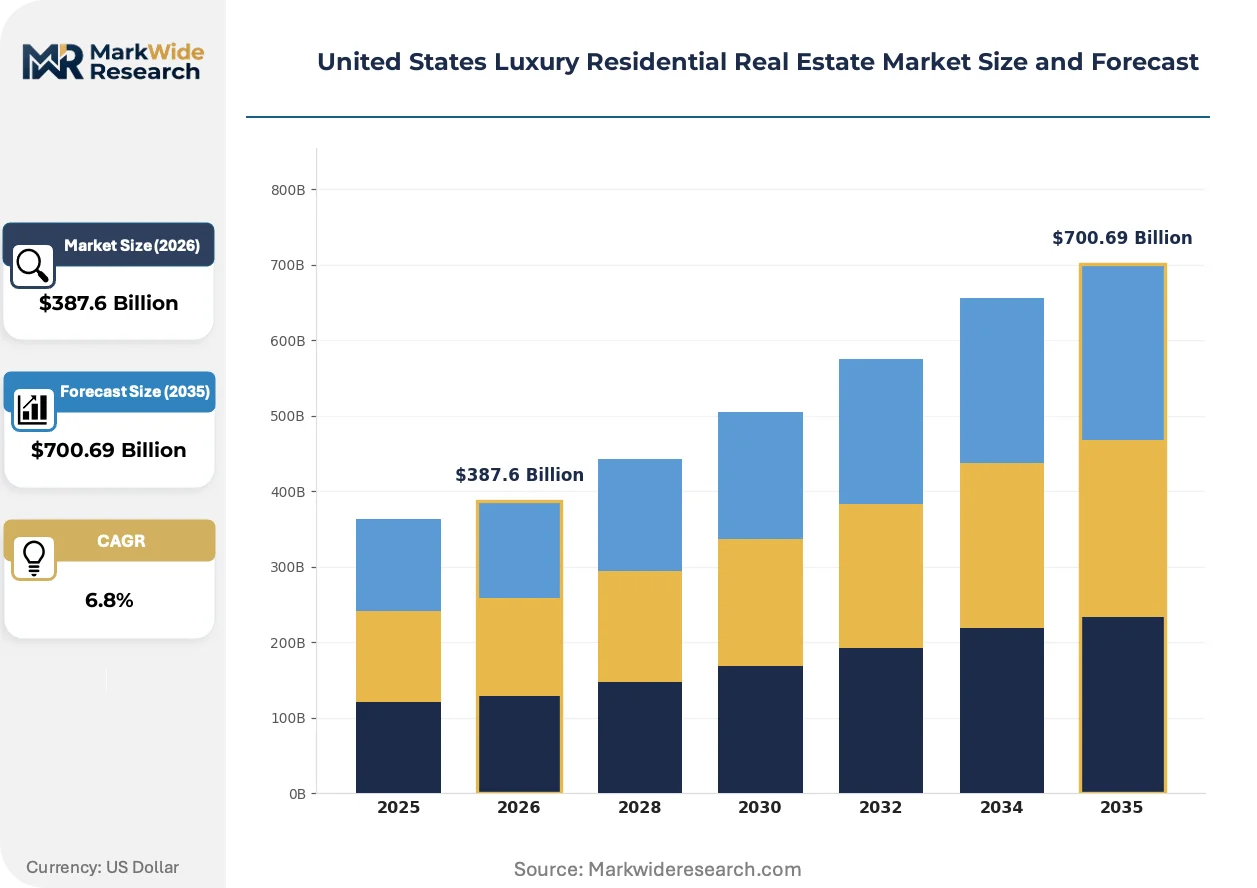
Market Dynamics
Wealth migration from high-tax coastal metros is compressing transaction timelines and inflating land values in Florida and Texas, while SEC beneficial ownership disclosure rules are forcing international purchasers to restructure holding vehicles.
Growth Catalysts
- 1031 Exchange Preservation:IRS Section 1031 rules enable deferred capital gains on like-kind exchanges, sustaining reinvestment velocity among portfolio holders reallocating from California and New York into Austin and Miami.
- Smart-Home Infrastructure:Integrated automation systems for climate, security, and energy management are becoming baseline expectations in new construction above two million dollars, differentiating trophy assets from renovated inventory.
- Florida:Zero state income tax and business-friendly migration policies are drawing technology-sector ultra-high-net-worth individuals into Naples and Miami Beach, deepening buyer pools for waterfront single-family homes.
Market Restraints
- Beneficial Ownership Transparency:SEC expanded disclosure mandates for residential transactions above threshold values are chilling privacy-seeking international capital and extending due diligence timelines.
- Labor Concentration:Skilled artisan trades for custom millwork and stone installation concentrate in legacy Northeast and California markets, creating bottlenecks for trophy construction in emerging Sun Belt metros.
- Co-op Board Gatekeeping:Manhattan cooperative ownership structures impose liquidity constraints through discretionary approval processes, limiting market access for foreign purchasers and liquid investors.
Strategic Opportunities
- Subscription Property Management:Concierge home services bundled as recurring revenue models are capturing lifetime value beyond the initial transaction, deepening client retention for brokerages and developers.
- Texas Hill Country:Underdeveloped luxury inventory between Austin and San Antonio offers land-banking and vertical development control opportunities ahead of infrastructure completion.
- FinCEN Reporting Gaps:Evolving beneficial ownership mandates are creating advisory service demand for legal and tax structuring around compliant purchasing vehicles.
Industry Challenges
- Artisan Talent Scarcity:Master craftspeople capable of executing architectural-grade millwork and natural stone fabrication are aging out of the workforce faster than apprenticeship pipelines replenish.
- Legacy System Integration:Brokerage CRM and transaction management platforms require costly reconfiguration to support cryptocurrency-originated down payments and digital closing workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Luxury Residential Real Estate Market |
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Single-Family Homes, Condominiums, Townhouses, Luxury Estates Price Tier: Above $1 Million, Above $5 Million, Above $10 Million, Ultra-Luxury Customer Type: Domestic Buyers, International Investors, Real Estate Developers, First-Time Luxury Buyers Market Channel: Online Listings, Exclusive Auctions, Real Estate Agencies, Off-Market Sales |
| Companies Covered | RE/MAX, Savills, Sotheby's International Realty, Hines, Engel & Völkers, Coldwell Banker, eXp Realty, Lennar, Keller Williams Realty, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Luxury Residential Real Estate Market Evolving Landscape
Digital transaction infrastructure and climate-resilient design standards are compressing traditional brokerage workflows while elevating asset durability expectations in coastal exposure zones.
Biometric access control and AI-powered surveillance systems are expanding into the standard specification set for single-family homes above five million dollars. Ultra-high-net-worth buyers from technology and finance sectors are demanding these integrations during new construction, not retrofit. The technology is expanding into pre-construction planning phases, compressing traditional security consultancy timelines and elevating architect-contractor coordination requirements.
FinCEN's beneficial ownership reporting framework for residential real estate is tightening disclosure obligations for cash purchasers in select metropolitan statistical areas. The regulation is extending due diligence timelines and increasing legal structuring costs for privacy-oriented international investors. Miami-Dade and Manhattan transaction volumes are showing early sensitivity to these friction increases, with some capital rotating toward Texas markets with lighter oversight intensity.
Wealth preservation priorities are displacing speculative appreciation as the primary purchase motivation among coastal metro emigrants. Buyers exiting California and New York are prioritizing dollar-denominated hard assets with lower carrying costs over leveraged appreciation plays. Austin and Naples are capturing this behavioral rotation, with transaction structures emphasizing all-cash closes and shorter contingency periods.
United States Luxury Residential Real Estate Market Segmentation
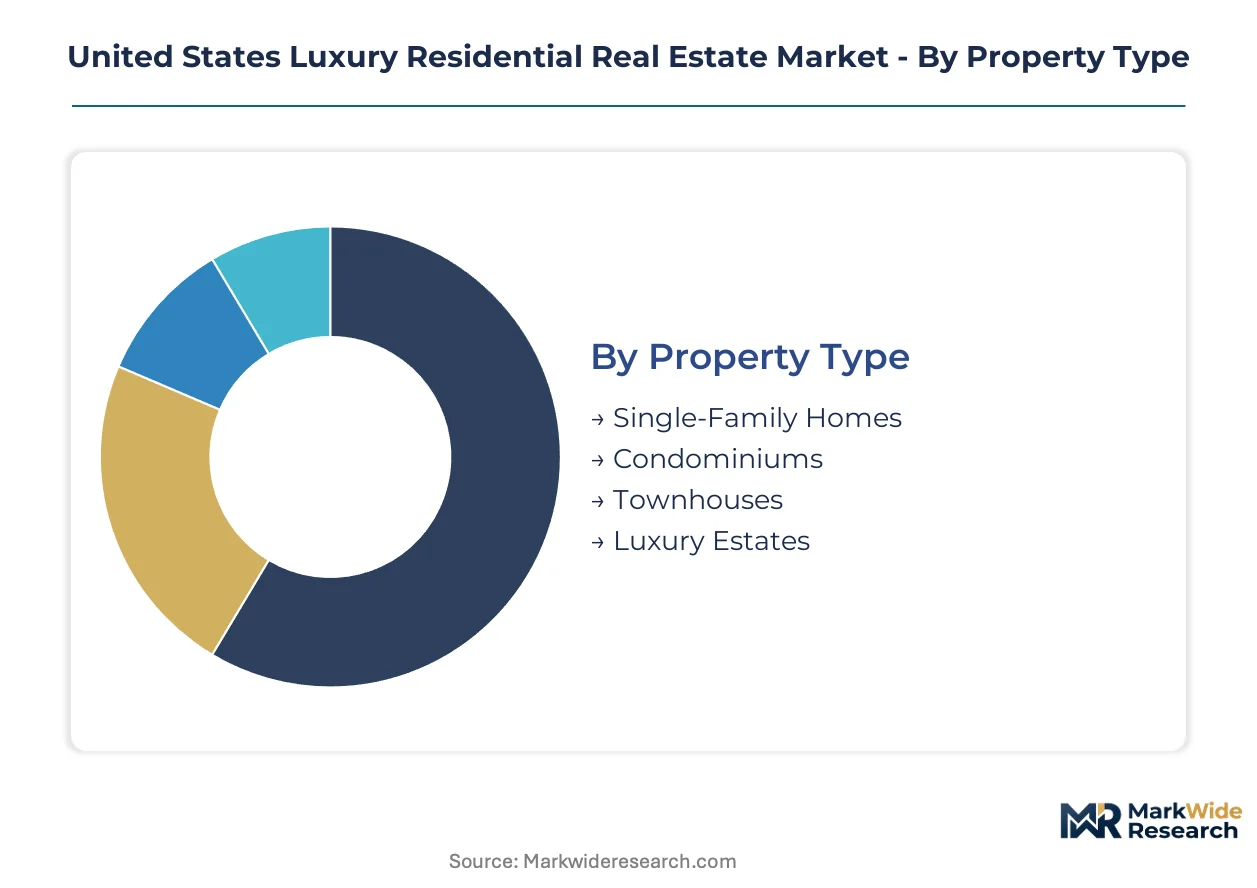
Segmentation in United States luxury residential real estate reveals how capital deployment, buyer motivation, and transaction mechanics vary across property types and price thresholds. Understanding these divisions enables stakeholders to align development pipelines, marketing spend, and advisory services with the specific requirements of each buyer cohort and asset class.
Property Type:
Capital intensity varies sharply across property types, with land assembly and horizontal infrastructure demanding the heaviest upfront commitment for trophy single-family development.
- Single-Family Homes:Detached structures on individually titled land parcels command the deepest buyer pools and longest holding periods in the United States luxury residential real estate market. Demand concentrates in Naples and Austin as technology-sector ultra-high-net-worth individuals seek privacy and space for remote work infrastructure.
- Condominiums:Vertical ownership in multi-unit buildings offers lower maintenance burdens and amenity access, attracting international investors seeking dollar-denominated assets in Miami and New York. FinCEN beneficial ownership reporting requirements are extending due diligence timelines for cash purchasers in these markets.
- Townhouses:Attached multi-level residences bridge density and privacy preferences, typically trading in urban infill locations with limited land availability.
- Luxury Estates:Acreage properties with custom architecture and extensive grounds concentrate in supply-constrained coastal enclaves where scarcity supports pricing power.
Most installed capacity flows through Single-Family Homes. Expansion is steepest in Luxury Estates as wealth preservation priorities displace speculative appreciation among coastal metro emigrants.
Price Tier:
Transaction velocity and buyer sophistication diverge meaningfully across price thresholds, with ultra-luxury segments requiring bespoke advisory and extended marketing timelines.
- Above $1 Million:The entry threshold for United States luxury residential real estate classification, encompassing premium materials and smart-home infrastructure as baseline specifications. This tier captures the broadest geographic distribution across Sun Belt metros experiencing wealth migration.
- Above $5 Million:Assets at this level increasingly feature integrated automation systems for climate, security, and energy management as standard expectations rather than retrofits.
- Above $10 Million:Trophy properties in this bracket concentrate in waterfront and heritage locations with irreplaceable locational attributes. Manhattan cooperative ownership structures impose liquidity constraints through discretionary board approval processes.
- Ultra-Luxury:The apex segment encompasses architecturally significant estates with bespoke millwork and natural stone fabrication requiring master craftspeople concentrated in legacy Northeast and California markets.
Transaction volume concentrates in Above $1 Million. Buyer registration is climbing fastest in Ultra-Luxury as zero state income tax policies in Florida deepen technology-sector footprint.
Customer Type:
Buyer origin and investment horizon shape transaction structuring, with international purchasers facing heightened disclosure obligations under SEC expanded beneficial ownership rules.
- Domestic Buyers:Primary residence purchasers and portfolio reallocators leveraging IRS Section 1031 exchanges to defer capital gains on like-kind property swaps. This cohort is reallocating from California and New York into Austin and Miami at accelerating velocity.
- International Investors:Privacy-oriented capital from Latin America, Europe, and Asia seeking dollar-denominated hard assets. SEC disclosure mandates are chilling some deal flow and forcing restructuring of holding vehicles into compliant purchasing structures.
- Real Estate Developers:Institutional and family-office capital deploying vertical development control strategies in trophy multifamily and land-banking opportunities ahead of infrastructure completion.
- First-Time Luxury Buyers:Technology and finance professionals executing inaugural premium purchases, typically prioritizing smart-home infrastructure and concierge property management bundles.
Deal flow dominance sits with Domestic Buyers. Advisory service demand is expanding most quickly among International Investors navigating FinCEN reporting gaps and evolving transparency mandates.
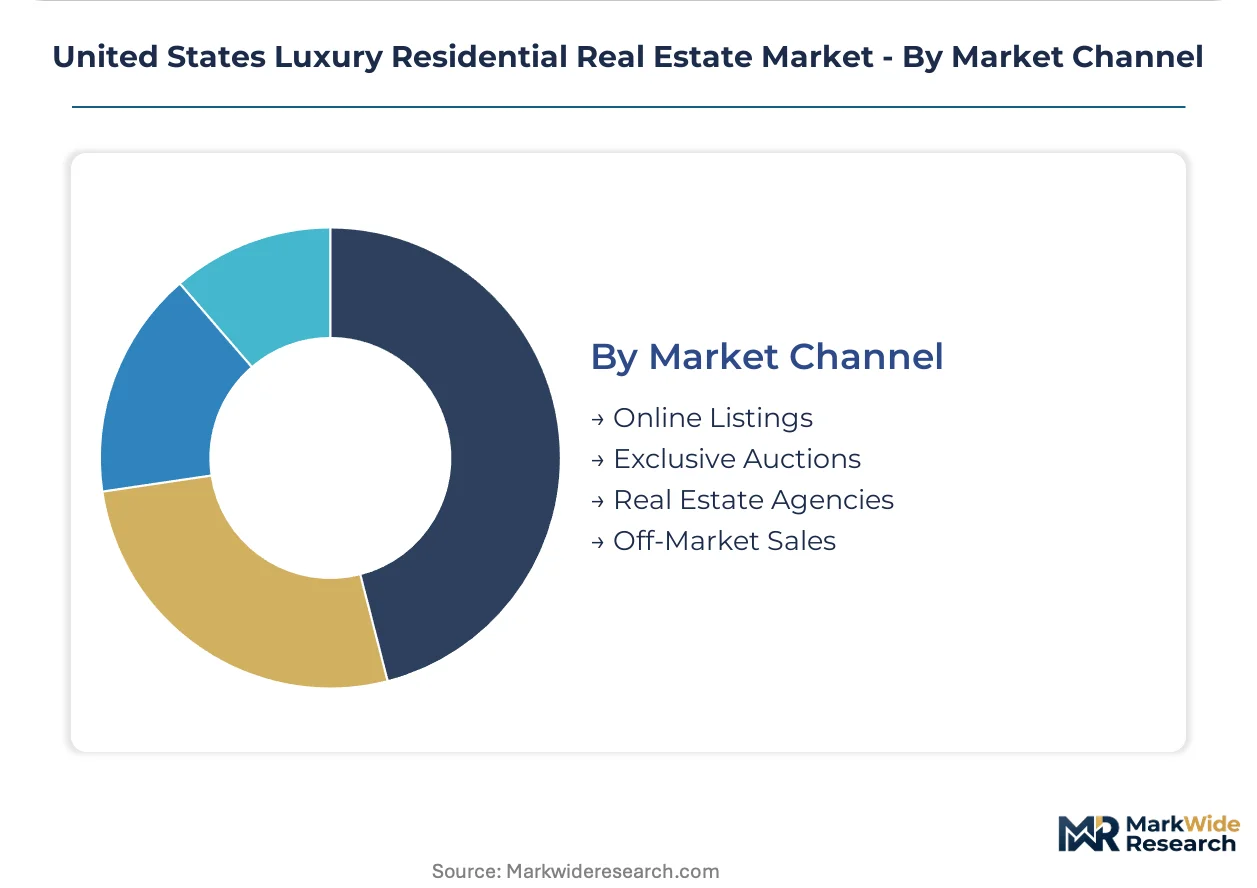
Market Channel:
Channel selection reflects asset uniqueness and seller privacy preferences, with off-market mechanisms preserving discretion for trophy properties.
- Online Listings:Digital platforms standard for Above $1 Million inventory, compressing initial discovery timelines but requiring legacy CRM reconfiguration to support cryptocurrency-originated down payments.
- Exclusive Auctions:Time-bound competitive bidding for distressed or uniquely positioned assets, generating price discovery in opaque market segments.
- Real Estate Agencies:Brokerage networks with global referral capabilities sustain cross-border deal flow into Florida and California through localized franchise expertise.
- Off-Market Sales:Discreet transactions avoiding public listing exposure, preferred by privacy-seeking sellers and international purchasers in Miami-Dade and Manhattan where regulatory scrutiny has intensified.
Listing volume flows predominantly through Real Estate Agencies. Transaction growth is steepest in Off-Market Sales as beneficial ownership transparency mandates increase sensitivity to public exposure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Florida's zero state income tax policy attracts technology-sector wealth faster than California's regulatory burden repels it, while Texas markets absorb portfolio capital fleeing Northeast transfer taxes. These migration patterns concentrate transaction velocity in Sun Belt metros with lighter disclosure mandates.
Florida
Waterfront single-family homes in Miami Beach and Naples draw ultra-high-net-worth individuals from technology and finance sectors seeking privacy and remote work infrastructure. The state's absence of personal income tax sustains reinvestment velocity among coastal metro emigrants. Miami-Dade transaction volumes show early sensitivity to beneficial ownership transparency mandates, with some capital rotating toward offshore-market structures.
Texas
Austin and Dallas-Fort Worth capture IRS Section 1031 exchange flows from California and New York as buyers prioritize lower carrying costs and dollar-denominated hard assets. FinCEN reporting requirements apply with lighter oversight intensity than coastal markets. The Texas Hill Country corridor between Austin and San Antonio presents land-banking opportunities ahead of infrastructure completion.
California
Supply-constrained coastal enclaves in Los Angeles and San Francisco maintain pricing power for trophy estates above ten million dollars, though state-level transfer taxes accelerate portfolio reallocation timelines. Master craftspeople capable of architectural-grade millwork concentrate in legacy Northeast and California markets, creating construction bottlenecks. Los Angeles and Orange County sustain ultra-luxury transaction activity despite outbound migration.
New York
Manhattan cooperative ownership structures impose liquidity constraints through discretionary board approval processes, limiting market access for foreign purchasers and liquid investors. FinCEN expanded disclosure mandates extend due diligence timelines for cash purchasers in New York metropolitan statistical areas. Trophy properties in the Hamptons and Hudson Valley capture wealth preservation capital from metropolitan emigrants.
Arizona
Greater Phoenix and Scottsdale markets absorb secondary-home demand from California retirees and technology professionals seeking lower cost structures. The state's business-friendly regulatory environment supports concierge property management and subscription-based home services expansion. Desert luxury estates in Paradise Valley and Arcadia attract capital prioritizing climate resilience and smart-home infrastructure.
United States Luxury Residential Real Estate Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with established brokerage networks commanding cross-border deal flow while digital-native platforms compress transaction timelines. The vendor base organizes around three archetypes: global referral networks with localized franchise expertise, vertically integrated developers controlling trophy multifamily pipelines, and technology-enabled platforms capturing first-time luxury buyers. Dominant competitive moves include geographic expansion into Sun Belt migration corridors and strategic partnerships bundling concierge services with property management.
Within the global referral network tier, Sotheby's International Realty and Engel & Völkers occupy positions anchored by localized franchise expertise in resort and secondary-home markets. Hines exemplifies the vertically integrated developer archetype through upstream control over trophy multifamily asset pipelines. These three entities represent contrasting scale and specialization strategies: Sotheby's International Realty leverages auction-house brand heritage, Engel & Völkers operates through European-originated franchise density, and Hines concentrates institutional capital deployment in supply-constrained urban cores.
| Leading Market Players |
|---|
| RE/MAX |
| Savills |
| Sotheby's International Realty |
| Hines |
| Engel & Völkers |
| Coldwell Banker |
| eXp Realty |
| Lennar |
| Keller Williams Realty |
| Others |
Value Network & Pricing Analysis
Master craftspeople capable of architectural-grade millwork and natural stone fabrication concentrated in legacy Northeast and California markets widen labor-cost differentials between ultra-luxury estates and standard premium inventory. These artisan scarcity premiums compress margins on trophy construction in emerging Sun Belt metros while elevating price floors for bespoke assets in supply-constrained coastal enclaves.
Pricing Analysis
Capacity additions in Austin and Dallas-Fort Worth are reshaping price floors for new construction above two million dollars as developers compete for technology-sector buyers. Three-tier pricing structure across ultra-luxury, premium, and entry-luxury levels separates properties by smart-home infrastructure completeness and architectural distinction. Cost compression in mid-tier condominiums is intensifying because international capital rotation toward compliant purchasing structures extends marketing timelines. First-time luxury buyers from technology sectors demonstrate highest price sensitivity to concierge service bundling, while ultra-high-net-worth portfolio reallocators show least sensitivity to carrying cost differentials.
Supply Chain Analysis
Refurbishment flows for aging trophy properties in Manhattan and coastal California create secondary demand for master craftspeople capable of heritage millwork restoration. Geographic supply concentration for architectural-grade materials centers on Italy, Spain, and Portugal for natural stone, while smart-home infrastructure components draw from Taiwan, South Korea, and domestic US technology corridors. Supply chain risk rests on single-source vulnerability for artisan trades approaching generational transition without adequate apprenticeship pipelines. Distribution runs through vertically integrated developers controlling trophy multifamily pipelines and localized franchise networks with concierge service bundling capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where wealth preservation priorities among coastal metro emigrants displace speculative appreciation as the dominant purchase motivation. Buyers prioritize dollar-denominated hard assets with irreplaceable locational attributes and lower carrying costs over leveraged appreciation plays.
For Market Incumbents: Hedge concentration risk in Miami-Dade and Manhattan by accelerating franchise expansion into Austin and Naples ahead of infrastructure completion. Deepen vertical integration into concierge property management and subscription-based home services to capture lifetime value beyond initial transactions, defending against digital-native platforms compressing traditional brokerage workflows. For New Entrants and Emerging Players: Enter via the Texas Hill Country corridor between Austin and San Antonio, where underdeveloped luxury inventory and lighter FinCEN oversight intensity create white-space opportunities for land-banking and vertical development control. Target first-time luxury buyers from technology sectors through smart-home infrastructure bundling and cryptocurrency-originated down payment facilitation. For Investors and Strategic Acquirers: Family offices with trophy multifamily deployment capabilities are the most active acquirer in this space, seeking supply-constrained urban cores with pricing power durability over the coming decade. Acquisition target archetypes include localized franchise networks with global referral capabilities and concierge service integration. Monitor SEC beneficial ownership disclosure rule expansion timelines as early signals for capital rotation patterns and compliant vehicle structuring demand.| Strategic Initiative | Industry Significance |
|---|---|
| Concierge Service Bundling | Subscription-based home services capture lifetime value beyond initial property transactions for brokerages. |
| Smart-Home Infrastructure Integration | AI-powered surveillance and biometric access control differentiate trophy assets in pre-construction planning phases. |
| Geographic Expansion into Sun Belt Corridors | Zero state income tax policies in Florida and Texas deepen technology-sector buyer pools for waterfront estates. |
| Compliant Vehicle Structuring Services | Advisory capabilities around FinCEN reporting gaps attract privacy-oriented international capital rotating from Manhattan. |
| Artisan Apprenticeship Pipeline Development | Master craftspeople aging out of workforce faster than replenishment threatens trophy construction timelines in emerging markets. |
Research Methodology
Bottom-up property-type modeling reconciled against top-down migration-flow tracking forms the analytical core of this study. Primary interviews with luxury residential developers, franchise brokerage principals, concierge service operators, and wealth management advisors intersected with secondary validation from SEC regulatory filings, IRS Section 1031 exchange data, FinCEN beneficial ownership reporting frameworks, and metropolitan statistical area transaction records. Triangulation between supply-side capacity assessments and demand-side buyer registration patterns anchored segmentation-specific estimates.
Historical trendline analysis of transaction velocity across price tiers and property types established baseline growth patterns without reliance on single-source projections. Segmentation dimensions modeled encompass property type, price threshold, buyer origin, and market channel, with regional regulatory intensity as an industry-specific overlay. CAGRs were derived from reconciliation between macroeconomic migration drivers and micro-level land-value appreciation in supply-constrained submarkets. Forecast inputs incorporated wealth migration velocity from high-tax coastal metros and evolving disclosure mandate implementation timelines.
Inputs from brokerage transaction databases and metropolitan planning records were available through the study window; gaps in offshore holding vehicle transparency introduce uncertainty bands around international investor participation estimates. Forecasts reflect assumptions regarding sustained technology-sector wealth migration and stable beneficial ownership reporting frameworks. Practitioners should monitor SEC disclosure threshold adjustments and state-level transfer tax policy shifts for early signals of capital rotation and transaction structuring evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Residential Real Estate Market
Italy Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Oman Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Belgium Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Sweden Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Vietnam Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Bahrain Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Canada Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Saudi Arabia Luxury Market
Luxury Residential Real Estate Market
Australia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
UAE Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Denmark Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Residential Real Estate Market
Luxury Residential Real Estate Market
Qatar Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
India Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Switzerland Luxury Residential Real Estate Market