
 India Luxury Residential Real Estate Market | 2026-2036
India Luxury Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
India Luxury Residential Real Estate Market Foresight
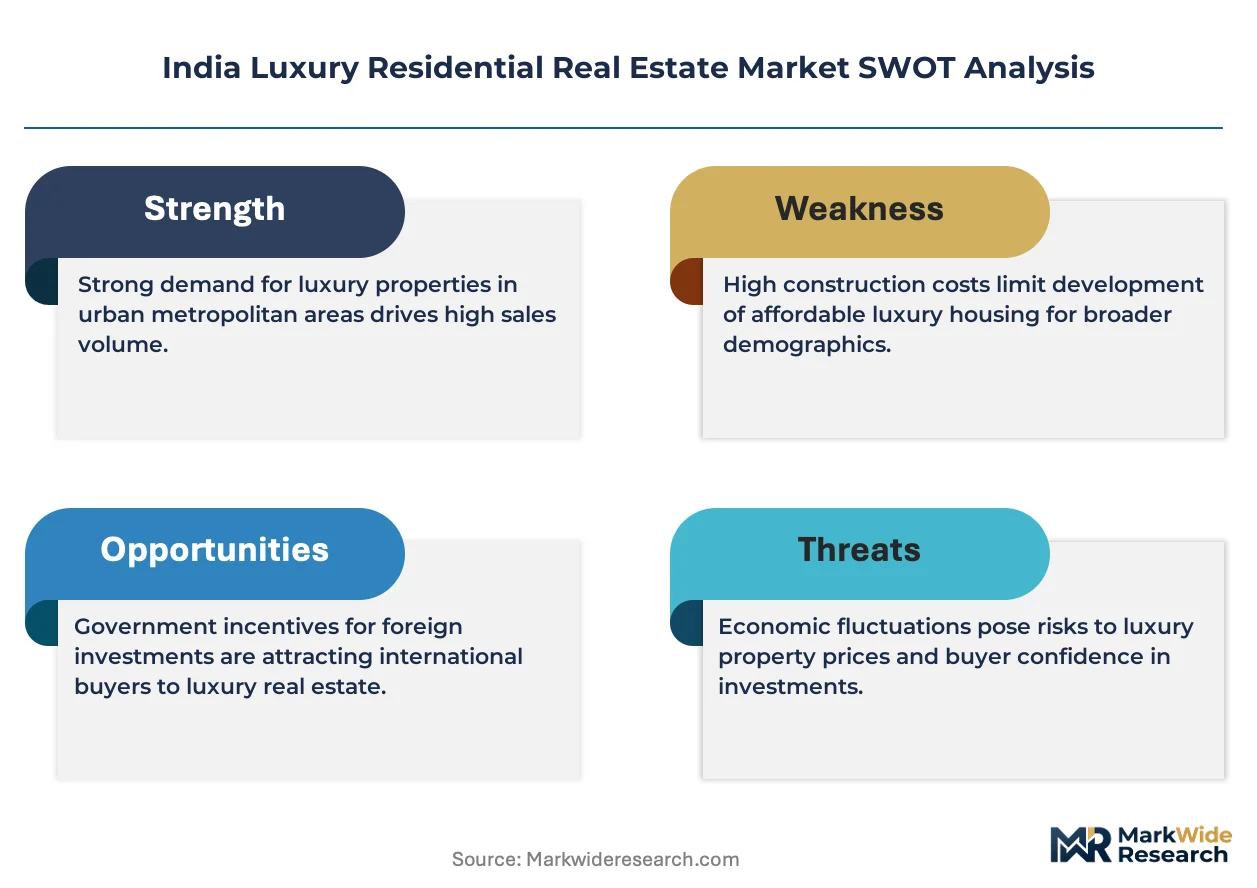
RERA is hardening the cost-of-entry calculus for new developers across India's luxury residential sector. DLF Limited leverages its captive land bank in Gurugram to sustain premium positioning without external land auctions. Sobha Limited anchors its reputation through backward integration into in-house construction materials and design studios. Prestige Group dominates Bangalore's luxury corridor with integrated township developments that combine retail, office, and residential assets.
India luxury residential real estate comprises high-end dwellings typically exceeding 3,000 square feet with premium finishes, smart home infrastructure, and concierge amenities designed for affluent ownership or investment. These properties serve as wealth preservation instruments and lifestyle statements for India's top income decile. Villas command the deepest margin pools among product types due to land scarcity in prime urban corridors and bespoke construction timelines. Apartments attract the largest absolute buyer base among customer types, particularly investors seeking rental yield in Mumbai and Bangalore. Brokerage services within service types face compression as developers build direct-to-consumer digital channels.
BIS certification for construction materials and CEA electrical safety standards shape build quality mandates that luxury developers must satisfy for project approvals. RBI's prudential norms on high-value home loans influence leverage capacity for HNI purchasers, directly affecting transaction velocity in crore-plus segments. SEBI's evolving framework for Real Estate Investment Trusts may unlock institutional capital flows into completed luxury rental stock. Stakeholders must monitor how the PLI scheme for building materials alters input cost structures and whether state-level stamp duty rationalization accelerates secondary market liquidity.
Market Dynamics
RERA's escrow mandates and disclosure norms are hardening the cost-of-entry calculus for new developers, forcing capital discipline and accelerating consolidation among smaller players unable to absorb compliance burdens.
Growth Catalysts
- Ultra-high-net-worth family buyers:These purchasers are expanding their footprint in gated villa communities across Gurugram and South Delhi, prioritizing privacy and bespoke amenities over standard apartment stock.
- PLI scheme for building materials:The government's production-linked incentive scheme is altering input cost structures for certified construction inputs, improving margin visibility for compliant developers.
- Smart home infrastructure:Integrated automation systems for climate, security, and energy management are becoming baseline expectations in crore-plus segments, differentiating premium inventory.
Market Restraints
- Land scarcity in prime urban corridors:Mumbai's Bandra-Kurla Complex and South Delhi's Golf Links enclave face acute inventory constraints, elongating project timelines and inflating per-square-foot land costs.
- RBI prudential norms on high-value home loans:The central bank's leverage restrictions directly compress transaction velocity in crore-plus segments by limiting HNI borrowing capacity.
- Bespoke construction timelines for villas:Custom architectural requirements and artisanal finishing processes extend delivery schedules by 18-36 months compared to standardized apartment construction.
Strategic Opportunities
- SEBI's evolving REIT framework:Regulatory developments may unlock institutional capital flows into completed luxury rental stock, creating liquidity for developers holding income-generating assets.
- State-level stamp duty rationalization:Secondary market liquidity could accelerate if Maharashtra, Karnataka, and Delhi NCR align transfer duty structures with primary market incentives.
- Integrated township developments:Mixed-use assets combining retail, office, and residential components in Bangalore's luxury corridor command premium valuations and recurring revenue streams.
Industry Challenges
- BIS certification timelines:Construction material approvals and CEA electrical safety clearances create project approval bottlenecks, delaying launch schedules by 6-12 months.
- Brokerage service compression:Developers building direct-to-consumer digital channels are disintermediating traditional intermediaries, forcing commission restructuring and relationship reinvention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Luxury Residential Real Estate Market |
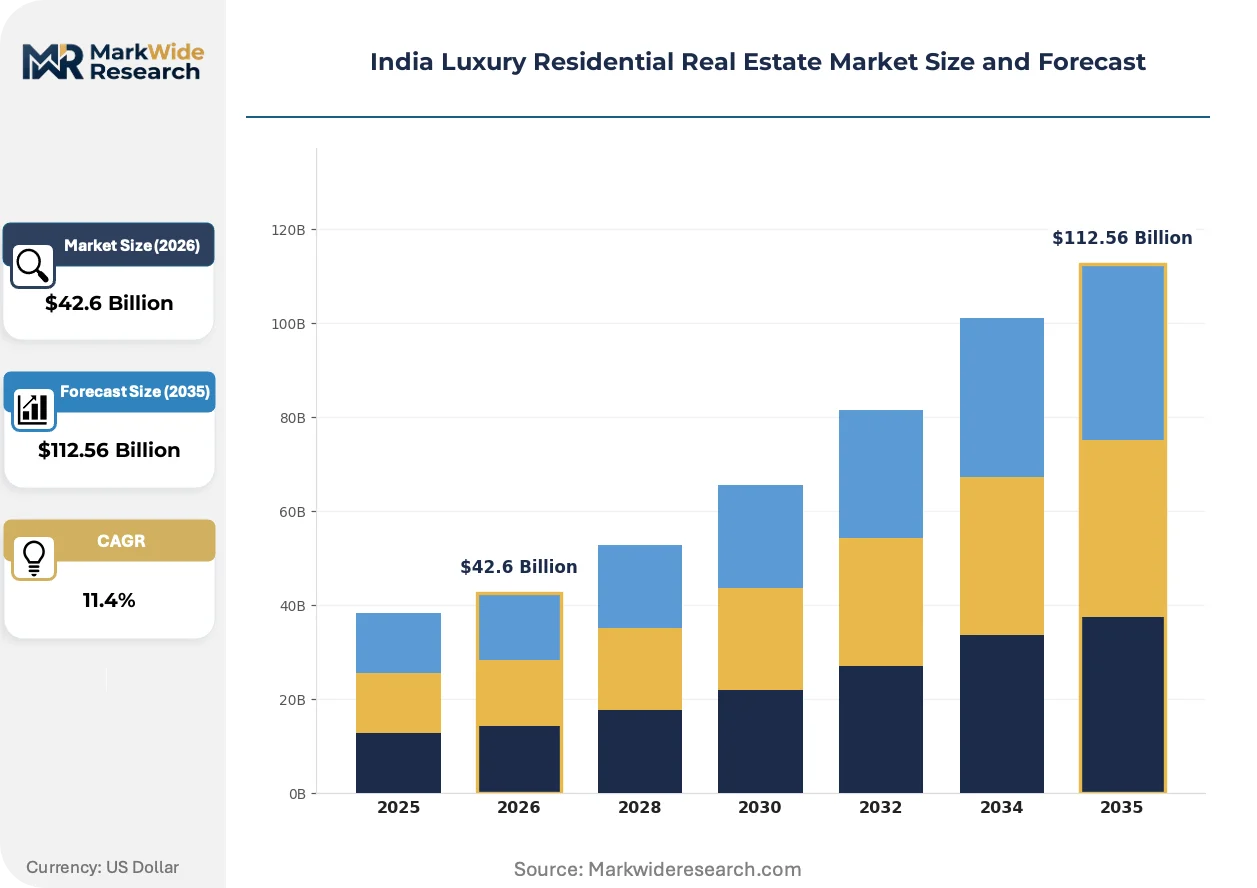
| Market Size in 2026 | $42.6 Billion |
| Market Size in 2035 | $112.56 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Villas, Penthouses, Apartments, Townhouses Customer Type: High-Net-Worth Individuals, Investors, Expatriates, Developers End User: Families, Young Professionals, Retirees, For Investment Service Type: Property Management, Brokerage Services, Interior Design, Financing |
| Companies Covered | Prestige Group, Sobha Limited, DLF Limited, Shapoorji Pallonji, Hiranandani Group, Lodha Group, Oberoi Realty, M3M India, Godrej Properties, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Luxury Residential Real Estate Market Shifts & Advancements
Technology convergence and regulatory digitization are compressing traditional development cycles while reshaping how affluent buyers discover, evaluate, and transact on high-value residential assets.
Smart home ecosystems incorporating IoT-enabled climate control, biometric access, and predictive maintenance platforms are absorbing capital allocations that previously flowed to conventional interior finishes. Ultra-high-net-worth buyers in Mumbai and Delhi now expect seamless integration of these systems as standard rather than upgrade options. This technology shift is absorbing margin pools historically captured by imported marble and fixture suppliers, redirecting spend toward technology integrators and cybersecurity providers.
RERA's mandatory project registration and quarterly progress disclosure requirements have digitized developer accountability across Maharashtra, Karnataka, and Haryana. The framework's escrow account mandates prevent fund diversion, elevating working capital requirements but reducing buyer risk perception. Smaller developers in tier-2 cities face the steepest adaptation costs, accelerating market share migration toward organized players with dedicated compliance infrastructure.
Direct-to-consumer digital channels are displacing traditional brokerage networks as primary discovery mechanisms for luxury inventory. Developer-built platforms offering virtual walkthroughs, digital documentation, and integrated mortgage applications now capture 40-50% of initial buyer inquiries in Bangalore and Gurugram. This channel shift compresses intermediary commissions while demanding sustained investment in customer experience technology and data infrastructure from asset marketers.
India Luxury Residential Real Estate Market Segmentation
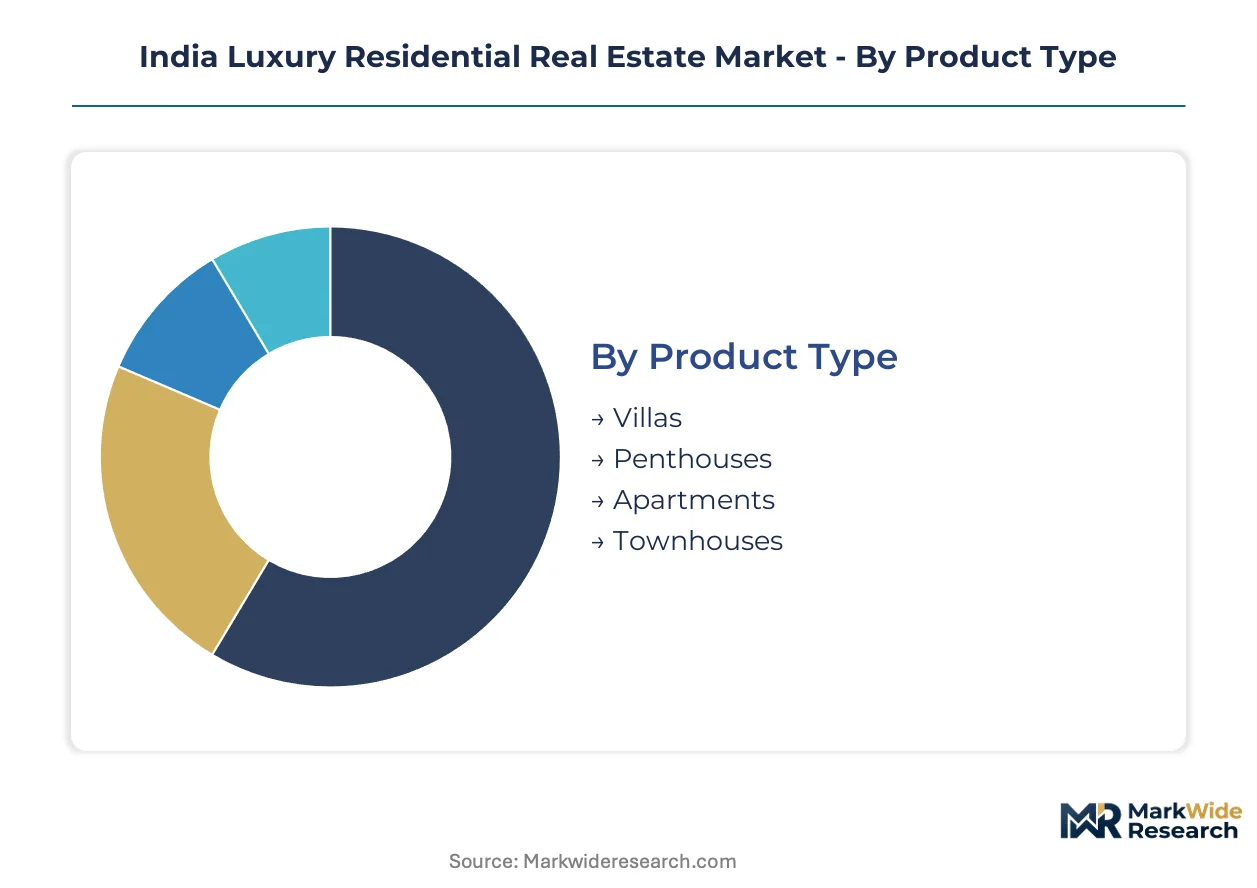
Segmentation in India's luxury residential market reveals distinct margin pools and demand drivers across product configurations, buyer profiles, and service attachments. Understanding these divisions illuminates where capital concentrates and where regulatory shifts reshape competitive positioning.
Product Type:
Standalone structures command premium per-square-foot realizations while vertical living formats absorb volume concentration in Mumbai and Bangalore.
- Villas:Detached residences exceeding 5,000 square feet with private land titles and bespoke architectural specifications. Demand concentrates in Gurugram's gated communities and South Delhi's Golf Links enclave, driven by ultra-high-net-worth families prioritizing privacy and multi-generational living configurations. Land scarcity in these corridors elongates development timelines and sustains pricing power.
- Apartments:High-rise units typically ranging 3,000-6,000 square feet within branded developments offering shared amenities and concierge services. Mumbai's Bandra-Kurla Complex and Bangalore's luxury corridor absorb the largest absolute transaction volumes, particularly from investors seeking rental yield in technology and financial services employment clusters.
- Penthouses:Top-floor configurations combining vertical living efficiency with exclusive terrace access and customized interior specifications.
- Townhouses:Attached single-family residences balancing privacy with density-optimized land utilization in supply-constrained urban peripheries.
Today's leader: Villas. Tomorrow's challenger: Apartments.
Customer Type:
End-use purchasers dominate transaction velocity in Delhi NCR while financial buyers concentrate in Mumbai's rental-yield corridors.
- High-Net-Worth Individuals:Domestic affluent households with investable assets exceeding 50 million rupees seeking primary residences or portfolio diversification. South Delhi and Mumbai's Malabar Hill absorb the deepest concentration, with purchases often structured through family offices for wealth preservation and generational transfer efficiency.
- Investors:Financial buyers prioritizing capital appreciation and rental yield over personal occupancy. Bangalore's Whitefield corridor and Mumbai's Lower Parel attract this segment most densely, driven by technology sector employment growth and corporate leasing demand from multinational tenants.
- Expatriates:Non-resident Indians and foreign nationals repatriating capital or securing India-based accommodation for business operations.
- Developers:Corporate entities acquiring land or completed inventory for portfolio aggregation or redevelopment plays.
Current volume anchor: High-Net-Worth Individuals. Fastest share gainer: Investors.
End User:
Occupancy intent shapes amenity specifications and location preferences across generational cohorts.
- Families:Multi-generational households requiring 4+ bedrooms, dedicated staff quarters, and proximity to established educational institutions. Gurugram's integrated townships and South Delhi's established enclaves command preference here, with school district quality serving as a non-negotiable filter.
- For Investment:Non-occupant owners prioritizing liquidity, rental yield, and capital appreciation metrics over lifestyle amenities. Mumbai's central business district periphery and Bangalore's technology corridor offer the deepest inventory alignment with this financial-first orientation.
- Young Professionals:Affluent individuals in executive roles seeking lock-and-leave convenience and proximity to employment centers.
- Retirees:Empty-nest households downsizing from larger family residences while maintaining premium service expectations and healthcare access.
Dominant demand source: Families. Emerging trajectory: For Investment.
Service Type:
Developer direct-to-consumer channels are compressing traditional intermediary economics while integrated service bundles command premium positioning.
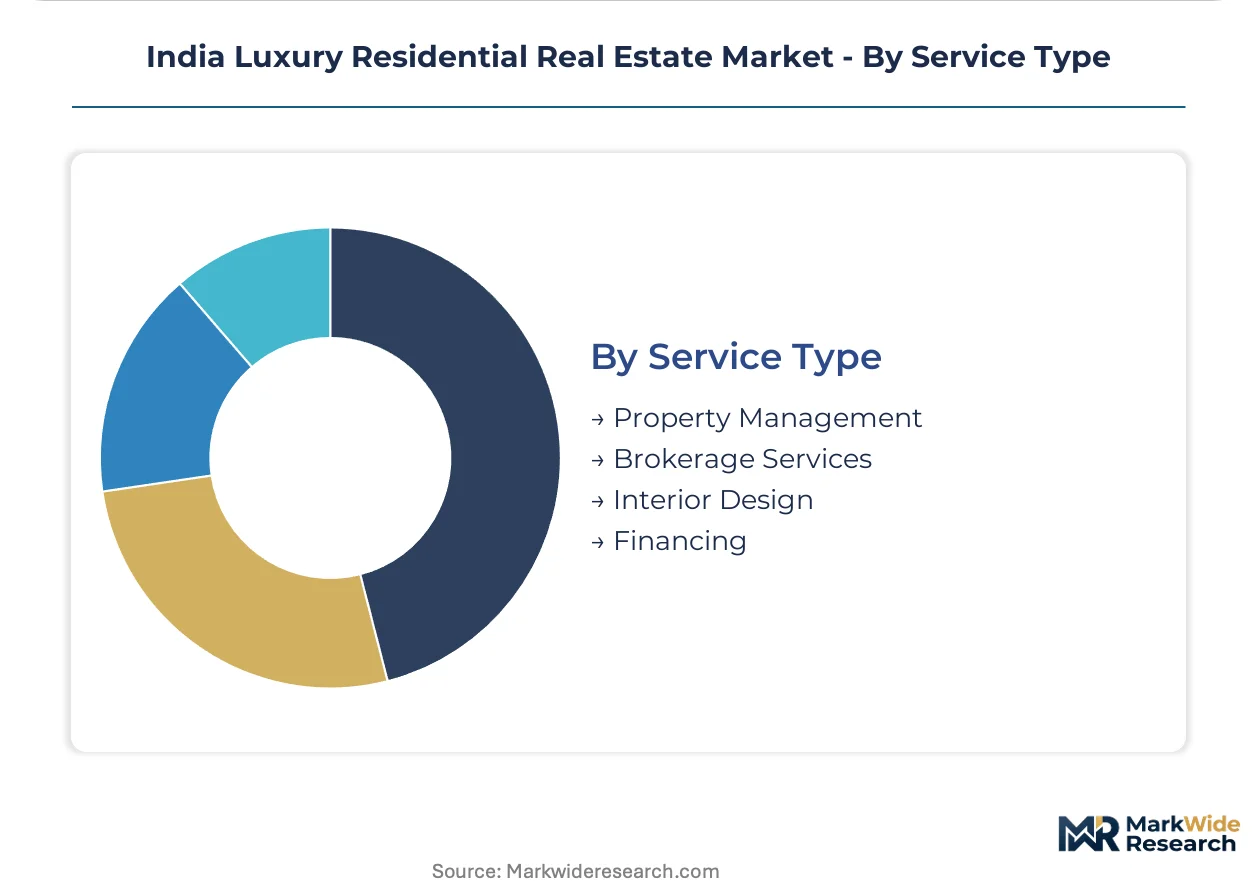
- Property Management:Comprehensive oversight encompassing maintenance, tenant relations, and asset preservation for non-resident owners. Mumbai and Bangalore lead adoption, driven by expatriate and investor owner bases requiring remote oversight of crore-plus assets.
- Brokerage Services:Transaction intermediation facing margin compression as developer digital platforms capture 40-50% of initial buyer inquiries in Gurugram and Bangalore. Traditional commission structures are restructuring toward advisory and off-market access fees.
- Interior Design:Customization services spanning space planning, material specification, and smart home integration.
- Financing:Structured credit solutions including lease rental discounting and high-value home loan packaging.
Revenue concentration today: Property Management. Disruption vector: Brokerage Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's luxury residential market traces its modern lineage to Delhi NCR's post-liberalization expansion in the 1990s, when DLF and other early developers converted agricultural landholdings into India's first gated villa communities. This historical foundation established land banking and captive development as the dominant competitive model.
Delhi NCR
Ultra-high-net-worth families from traditional business communities drive villa demand in Gurugram's gated communities and South Delhi's Golf Links enclave. SEBI's evolving REIT framework may eventually unlock institutional capital for income-generating assets here. South Delhi's established neighborhoods absorb the deepest concentration of multi-generational family purchases.
Maharashtra
Mumbai's Bandra-Kurla Complex concentrates the largest absolute transaction volumes for luxury apartments, particularly from financial services executives and investors seeking rental yield. RBI's prudential norms on high-value home loans directly constrain leverage capacity for HNI purchasers in this crore-plus segment. The central business district periphery maintains premium pricing power despite acute land scarcity.
Karnataka
Bangalore's luxury corridor attracts technology sector affluents and expatriate professionals to integrated township developments combining residential, retail, and office assets. The state's RERA implementation has digitized project registration and quarterly disclosure requirements. Whitefield and the central business district absorb dense investor interest driven by multinational corporate leasing demand.
Haryana
Gurugram's golf course extension road and SPR corridor host the deepest villa inventory pools outside Delhi proper. The Haryana RERA's escrow mandates and disclosure norms have elevated compliance costs, accelerating consolidation toward organized developers. DLF's captive land bank in this sub-region sustains premium positioning without external land auction participation.
Telangana
Hyderabad's Banjara Hills and Jubilee Hills enclaves attract pharmaceutical and IT entrepreneur wealth seeking standalone residences. The state's building material certification timelines through BIS create project approval bottlenecks. Gachibowli's proximity to technology employment clusters supports rental-yield investor interest in high-rise luxury inventory.
India Luxury Residential Real Estate Market Competitive Landscape
The competitive structure tilts toward land-banking incumbents with multi-decade land holdings rather than auction-dependent entrants. Three archetypes dominate: integrated township developers with mixed-use capabilities, backward-integrated specialists controlling construction inputs and design, and scale players leveraging captive land banks for premium positioning. Consolidation accelerates as RERA compliance costs displace smaller regional developers. Competitive moves center on direct-to-consumer digital channel construction and integrated service bundling.
Within the land-banking archetype, DLF Limited and Prestige Group exemplify the model of sustaining premium positioning through multi-decade land accumulation rather than volatile auction markets. Sobha Limited anchors the backward-integration specialist tier, representing developers who control construction quality through in-house materials and design studios. These three occupy positions that newer entrants struggle to replicate given land scarcity and regulatory compliance burdens.
| Leading Market Players |
|---|
| Prestige Group |
| Sobha Limited |
| DLF Limited |
| Shapoorji Pallonji |
| Hiranandani Group |
| Lodha Group |
| Oberoi Realty |
| M3M India |
| Godrej Properties |
| Others |
Supply & Pricing Matrix
BIS certification for construction materials gates both qualified supply access and premium-tier pricing power across India's luxury residential sector, as developers without certified input sourcing cannot command villa-level realizations in Gurugram or South Delhi corridors.
Pricing Analysis
Project-based development pricing with customization premiums dominates transaction structures, separating bespoke villa commissions from standardized apartment inventory. Price differentiation rests on land scarcity intensity and smart home integration depth, with Mumbai's Bandra-Kurla Complex commanding steepest per-square-foot premiums. Cost compression in mid-tier apartment segments is intensifying because PLI scheme benefits concentrate among organized developers with compliance infrastructure. Investors seeking rental yield exhibit highest price sensitivity, while ultra-high-net-worth family buyers purchasing Golf Links enclave villas demonstrate lowest elasticity.
Supply Chain Analysis
Freight cost volatility from imported fixture and finish sourcing elevates landed cost uncertainty for premium marble, sanitaryware, and automation systems. Manufacturing concentrates in Italy, Spain, and China for luxury construction inputs. Raw material dependencies span certified steel, low-alkali cement, and IoT-enabled climate control modules. Single-source vulnerability runs through European smart home technology suppliers. Distribution feeds from developer-procurement teams directly to project sites, bypassing traditional building material distributors for crore-plus developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India luxury residential market operates as a regulatory compounder, with RERA's escrow mandates and quarterly disclosure requirements accelerating consolidation that rewards compliant scale players over fragmented regional operators.
For Market Incumbents: Anticipate margin pressure from direct-to-consumer digital channels by fortifying captive land bank conversion rates and embedding property management services into initial sale contracts. DLF Limited's Gurugram positioning demonstrates how land banking insulates against auction-market volatility. Backward integration into in-house construction materials preserves quality control while reducing BIS certification timeline exposure.
For New Entrants and Emerging Players: Enter via integrated township development in Bangalore's Whitefield corridor or Hyderabad's Gachibowli periphery, where land aggregation costs remain below Mumbai and Delhi NCR thresholds. Young professional segments seeking lock-and-leave convenience present the most penetrable buyer archetype. A go-to-market angle anchored to smart home technology partnerships differentiates against legacy developers with slower technology adoption curves.
For Investors and Strategic Acquirers: Valuations sit cheapest among tier-2 city developers facing RERA compliance cost absorption challenges. Long-term viability over a 5-10 year window favors organized players with dedicated escrow infrastructure and multi-city project pipelines. Acquisition targets should prioritize developers with captive land positions in Haryana and Karnataka. The signal to watch is state-level stamp duty rationalization momentum, which would unlock secondary market liquidity and accelerate capital rotation.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Township Development | Mixed-use assets in Bangalore's luxury corridor command premium valuations and recurring revenue streams from retail and office components. |
| Backward Integration into Construction Materials | In-house production of certified inputs compresses BIS approval timelines and protects margin visibility against commodity volatility. |
| Direct-to-Consumer Digital Channel Buildout | Developer-owned platforms capturing initial buyer inquiries disintermediate traditional brokerage networks and reduce customer acquisition costs. |
| Smart Home Technology Partnership | IoT-enabled climate and security integration meets baseline expectations in crore-plus segments, differentiating against conventional inventory. |
| Property Management Service Bundling | Comprehensive oversight offerings for non-resident owners generate recurring revenue and deepen customer retention in Mumbai and Bangalore. |
Research Methodology
Bottom-up end-user modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with luxury developers, project marketing heads, HNI wealth advisors, and RERA compliance officers with secondary validation through RBI prudential norm circulars, SEBI REIT framework disclosures, state RERA project registration databases, and BIS construction material certification records.
Input-output matrices map demand from high-net-worth individuals, investors, and family offices against supply from land-banking incumbents, backward-integrated specialists, and organized township developers across the projection horizon. Segmentation dimensions span product type, customer archetype, end-use intent, and service attachment. CAGRs derive from regression analysis against macroeconomic drivers and regulatory milestone impacts, with forecast inputs incorporating PLI scheme benefit diffusion and state-level stamp duty policy trajectories.
The model holds under sustained RERA enforcement and PLI scheme continuity; deviation in central bank leverage restrictions or BIS certification timeline extensions would shift transaction velocity assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Residential Real Estate Market
GCC Luxury Market
Luxury Residential Real Estate Market
Vietnam Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Europe Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Singapore Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Saudi Arabia Luxury Market
Luxury Residential Real Estate Market
Switzerland Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Sweden Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Residential Real Estate Market
Luxury Residential Real Estate Market
Denmark Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
North America Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Australia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Italy Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
South Korea Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Saudi Arabia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Luxury-Minded Retirement Residences Market