
 Relocation Management Service Market | 2026-2036
Relocation Management Service Market Size, Share, and Industry Trends Forecast 2026-2036
Relocation Management Service Market Insights
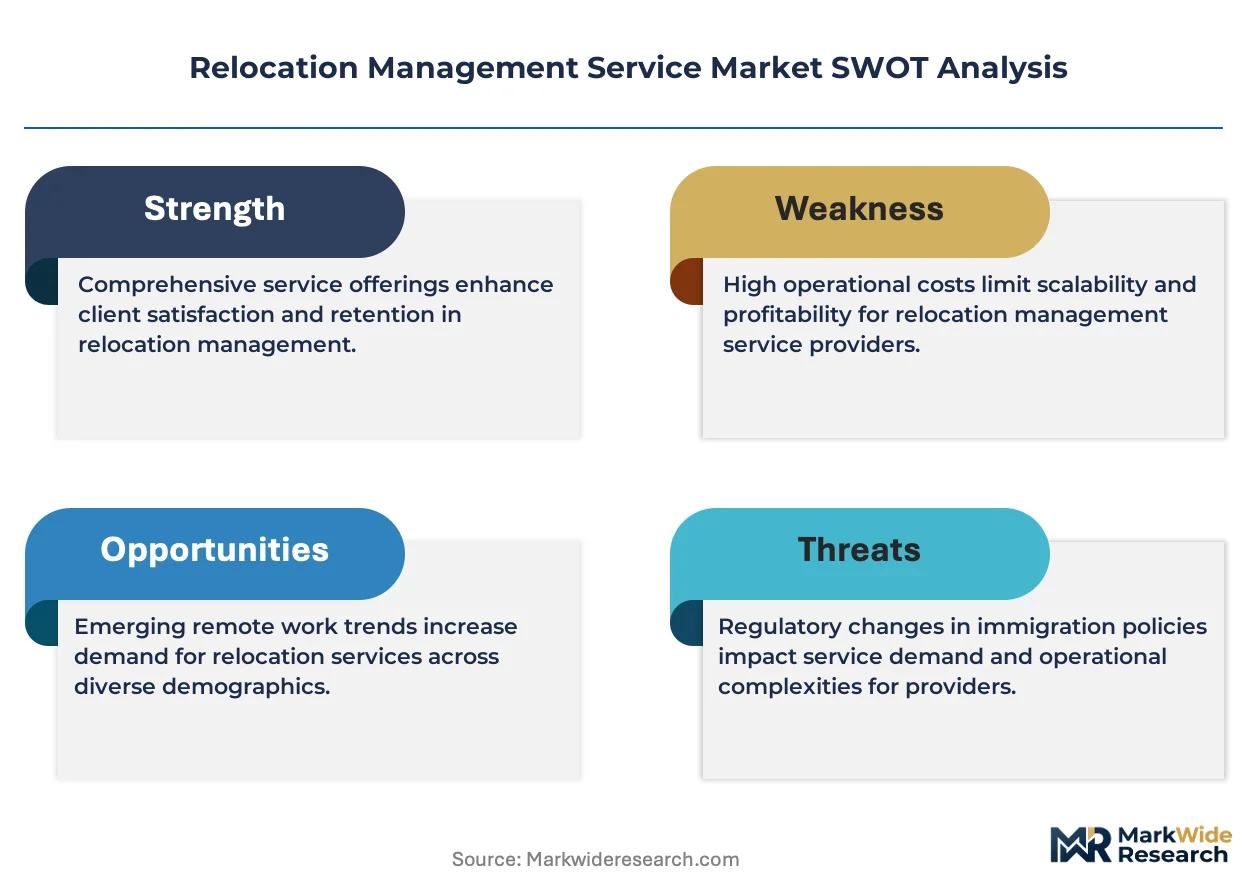
Modular service bundling is shifting how enterprises procure relocation support, unbundling traditional all-inclusive packages into configurable components. Cartus leverages its global network density to sustain premium positioning across complex international assignments. Graebel anchors its competitiveness through specialized supply chain control over household goods logistics. SIRVA differentiates via integrated real estate and mortgage services tied to corporate mobility programs.
Relocation management service encompasses the coordinated planning, execution, and oversight of workforce and personal transitions across geographic boundaries, incorporating immigration compliance, household goods shipment tracking with GPS-enabled visibility, temporary housing procurement, and destination orientation protocols. The primary commercial purpose is to minimize productivity loss and legal exposure for employers while ensuring employee satisfaction during disruptive moves. Corporate relocation dominates current revenue pools due to sustained enterprise investment in talent retention and global deployment. Employee benefits services represent the fastest-expanding segment as organizations compete for skilled workers through enhanced mobility perks. Full-service delivery models retain the largest margin concentration despite gradual hybrid adoption.
US employers navigate FERC guidelines for interstate commerce logistics alongside Department of State protocols governing visa sponsorship and foreign national compliance. European operations face REACH documentation requirements for household chemical inventories during cross-border moves plus GDPR constraints on employee data transmission between jurisdictions. Immigration authorities in Singapore and Australia enforce strict documentation standards that reshape service provider certification requirements. Stakeholders must monitor evolving digital nomad visa frameworks and carbon accounting rules for employee travel as these forces redefine competitive service design.
Market Dynamics
Modular service unbundling is fragmenting procurement patterns across corporate relocation programs, forcing providers to reconfigure legacy bundled offerings into configurable component menus that align with decentralized HR technology stacks.
Growth Catalysts
- Remote Work Normalization:Distributed workforce policies are expanding permanent relocation volumes as employers relocate talent to lower-cost jurisdictions without office proximity constraints.
- GDPR Cross-Border Data Frameworks:European data portability requirements are accelerating demand for compliant employee record transfer protocols between EU member states and third countries.
- Digital Nomad Visa Proliferation:Portugal, Estonia, and Costa Rica have enacted specialized visa categories that institutionalize extended-stay mobility programs for knowledge workers.
Market Restraints
- Household Goods Logistics Concentration:Ocean freight capacity bottlenecks at Singapore and Rotterdam ports are constraining container availability for international shipment volumes.
- Immigration Processing Friction:USCIS backlogs and consular appointment scarcity in India and Brazil are extending assignment start-date uncertainty beyond employer tolerance thresholds.
- Substitution by Virtual Mobility:Persistent video collaboration infrastructure is reducing physical relocation necessity for roles previously requiring geographic presence.
Strategic Opportunities
- Carbon Accounting Integration:EU CSRD disclosure mandates are creating demand for emissions-tracked relocation packages that quantify Scope 3 employee travel footprints.
- APAC Policy Divergence:Australia's permanent residency pathway reforms and Singapore's COMPASS framework are attracting employer regional headquarters investment in mobility infrastructure.
- AI-Enabled Destination Matching:Machine learning algorithms analyzing school quality, healthcare access, and spousal employment prospects are personalizing assignment acceptance rates.
Industry Challenges
- Certification Fragmentation:FIDI-FAIM, EuRA Quality Seal, and ISO 20700 standards lack mutual recognition, forcing multi-certification cost burdens on mid-tier providers.
- Legacy System Integration:HRIS platforms from Workday, SAP SuccessFactors, and Oracle require custom API development for real-time relocation spend visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Relocation Management Service Market |
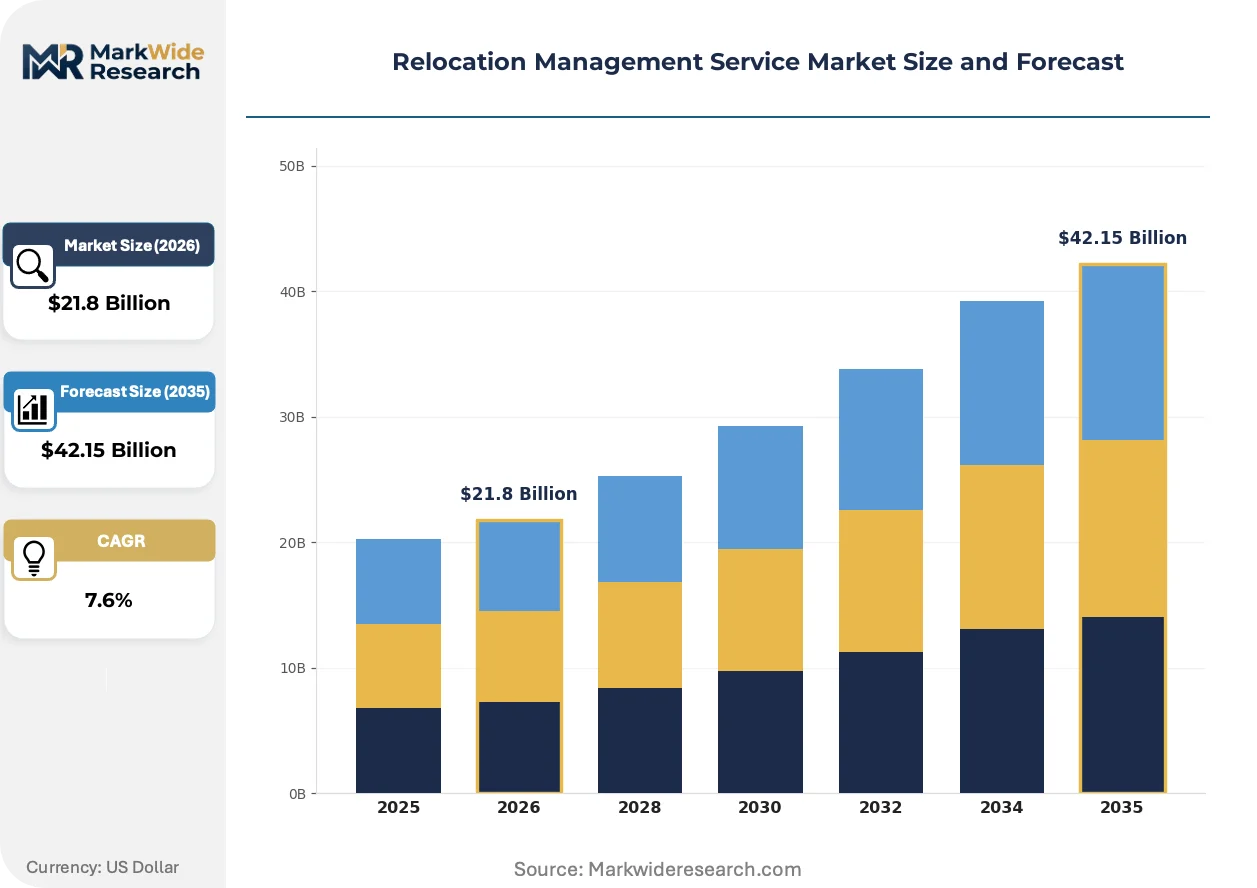
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $42.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Corporate Relocation, International Moving, Domestic Moving, Employee Benefits Client Type: Individuals, Corporates, Government Agencies, Non-profit Organizations Delivery Model: Full-Service, Self-Service, Hybrid, Online Assistance Insurance Option: Full Value Protection, Released Value, Third-Party Insurance, No Insurance |
| Companies Covered | Cartus, SIRVA, Graebel, Aires, Altair Global, Sterling Lexicon, XONEX, NEI, TRC Global Mobility, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Relocation Management Service Market Trends and Innovations
Technology convergence and policy complexity are compressing service delivery timelines while elevating data transparency expectations across corporate mobility functions.
Blockchain-based shipment documentation is absorbing verification overhead in household goods supply chains. Multinational employers with high-frequency relocation programs are piloting distributed ledger systems for customs clearance acceleration. This distributed verification architecture is absorbing intermediary documentation costs while compressing port-to-door delivery windows.
EU AI Act risk classification frameworks are reshaping automated immigration eligibility screening tools. Relocation management platforms deploying algorithmic visa qualification assessments must now implement human-in-the-loop review protocols for high-risk categorizations. European operations face mandatory conformity assessments that delay feature rollouts by six to twelve months relative to North American deployment schedules.
Subscription-based mobility benefits are displacing per-assignment procurement for remote-first employers. Technology sector firms with distributed workforces are consolidating relocation, travel, and temporary housing into annual platform licenses. This consumption pattern shift is most visible among San Francisco and Seattle headquartered enterprises with over five thousand remote employees.
Relocation Management Service Market Segmentation
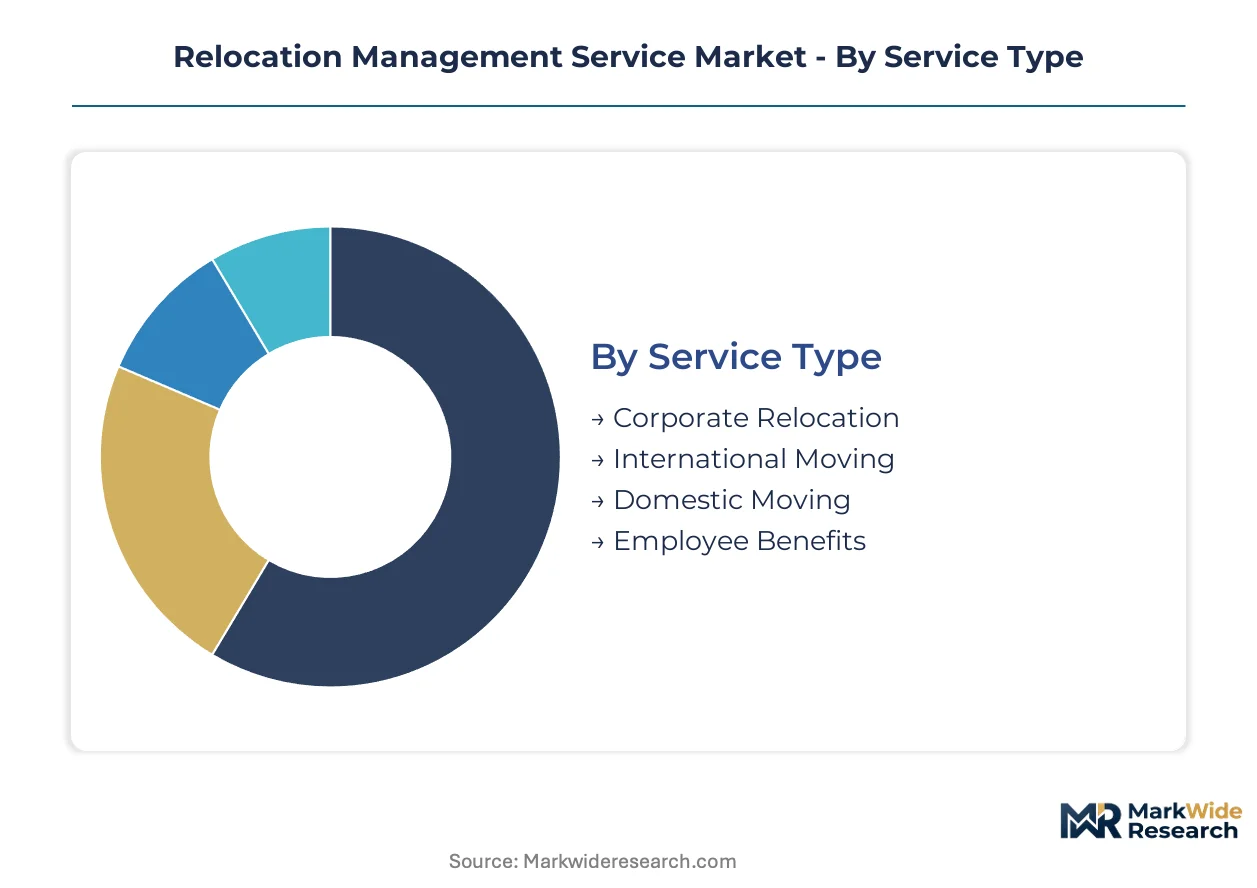
Relocation management services fragment across four distinct dimensions that shape procurement economics and provider specialization. Each segmentation axis reveals divergent margin profiles, technology requirements, and competitive intensity patterns that determine vendor selection criteria.
Service Type:
Corporate relocation commands premium pricing through bundled immigration, housing, and logistics coordination, while employee benefits services gain share fastest through subscription-based mobility perks.
- Corporate Relocation:Comprehensive workforce transition management spanning visa processing, household goods shipment, temporary housing, and destination orientation. Demand concentrates among US and German multinational employers with high-frequency international assignment programs. FERC interstate commerce guidelines and Department of State visa protocols shape service design complexity.
- Employee Benefits:Mobility perks packaged as retention tools including relocation allowances, spousal job search support, and school placement assistance. Technology sector employers in Singapore and Seattle drive adoption through competitive talent acquisition strategies. Subscription licensing models are displacing per-assignment procurement in remote-first organizations.
- International Moving:Cross-border household goods logistics with customs documentation and ocean freight coordination.
- Domestic Moving:Intra-country workforce transitions with shorter cycle times and lower compliance overhead.
Today's leader: Corporate Relocation. Tomorrow's challenger: Employee Benefits.
Client Type:
Government and non-profit procurement runs through rigid RFP processes with extended sales cycles, while corporate clients prioritize speed and configurability.
- Corporates:Enterprise mobility programs with centralized HR technology stacks demanding API-integrated spend visibility. REACH documentation requirements for EU chemical inventories and GDPR cross-border data frameworks reshape vendor qualification standards.
- Government Agencies:Diplomatic and military relocation with security-cleared personnel handling and classified shipment protocols. Australia's TGA and Singapore's immigration authorities enforce strict documentation standards that limit provider eligibility.
- Individuals:Consumer-direct relocation with price-sensitive procurement and limited service bundling.
- Non-profit Organizations:Mission-driven mobility with grant-funded budgets and volunteer coordination requirements.
Corporates anchor current revenue pools. Government Agencies represent the stickiest contract base.
Delivery Model:
Full-service retains margin concentration despite gradual hybrid adoption, while self-service platforms capture cost-conscious segments through technology-enabled disintermediation.
- Full-Service:End-to-end orchestration with dedicated relocation counselors managing all touchpoints. Cartus and SIRVA sustain positioning through counselor-to-assignee ratios and global network density. EU AI Act conformity assessments delay automated feature rollouts by six to twelve months relative to North American deployment.
- Hybrid:Modular component selection allowing employers to self-manage selected workstreams while outsourcing complex immigration or household goods segments. Decentralized HR technology stacks from Workday and SAP SuccessFactors drive demand for configurable API integration.
- Self-Service:Technology platforms with automated workflow tools and reduced human intervention.
- Online Assistance:Chat-based and portal-guided support for standardized relocation transactions.
Full-Service dominates margin capture. Hybrid delivery is climbing the fastest.
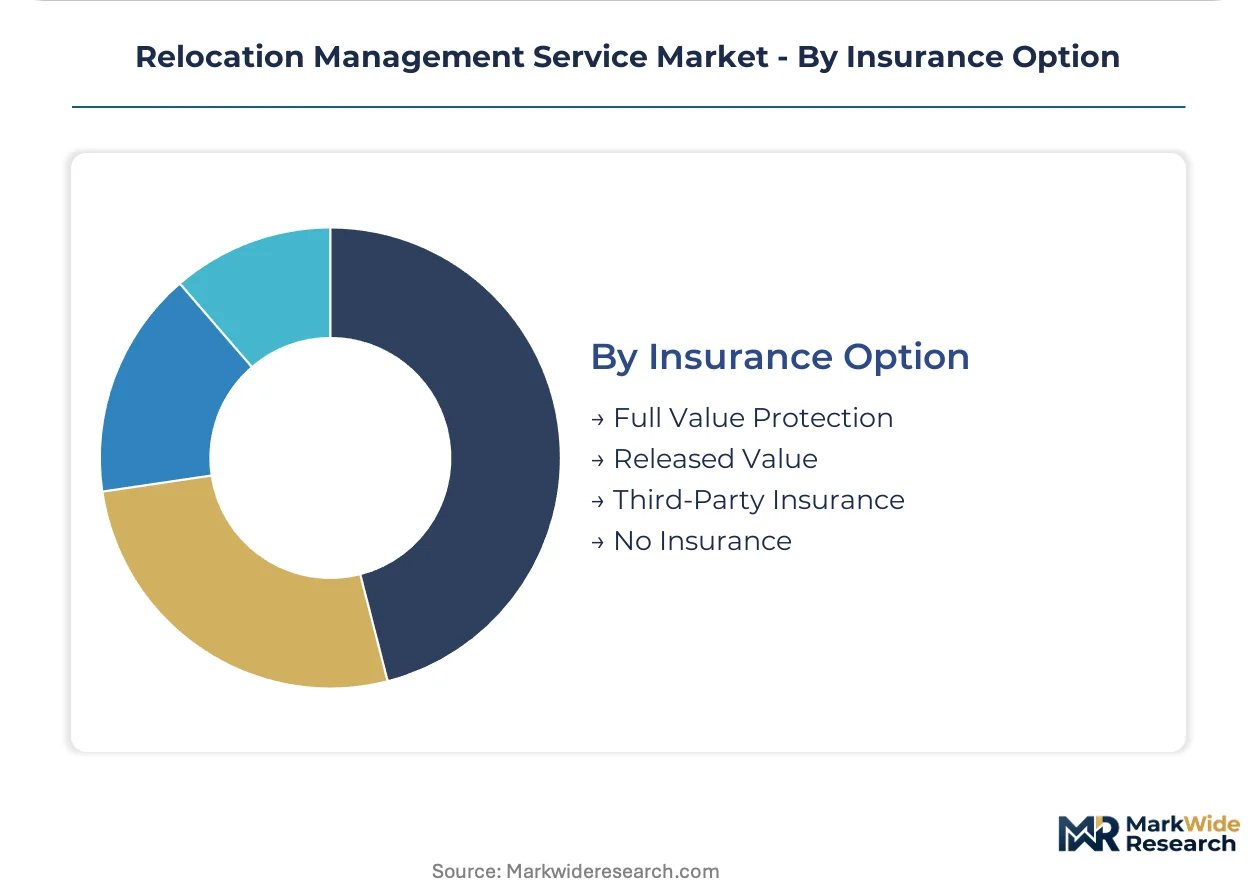
Insurance Option:
Risk transfer preferences split between employer-funded comprehensive coverage and cost-minimized released value acceptance.
- Full Value Protection:Comprehensive replacement-cost coverage for household goods with streamlined claims processing. Corporate relocation programs in Germany and Singapore mandate this tier for executive assignments. Blockchain-based shipment documentation is absorbing verification overhead in high-value claims.
- Third-Party Insurance:Specialized coverage from independent underwriters supplementing carrier liability limits. Port congestion at Rotterdam and Singapore is extending transit windows and elevating loss exposure.
- Released Value:Minimal liability coverage at per-pound rates with significant claimant cost exposure.
- No Insurance:Self-insured acceptance of total loss risk, prevalent in domestic short-haul moves.
Full Value Protection holds the premium tier. Third-Party Insurance is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The relocation management service industry traces its modern commercial roots to post-war corporate expansion programs in the United States, where standardized workforce mobility protocols first emerged to support multinational enterprise growth.
United States
Enterprise technology firms and financial services institutions sustain the highest assignment volumes for cross-border executive transfers. FERC interstate commerce guidelines govern household goods logistics coordination across state lines. The San Francisco Bay Area and Seattle metropolitan clusters anchor demand for subscription-based mobility benefits among remote-first technology employers.
Germany
Automotive and industrial machinery conglomerates drive structured expatriate programs for engineering talent deployment. REACH documentation requirements mandate chemical inventory disclosure during cross-border household relocations. The Rhine-Ruhr industrial corridor concentrates provider service centers supporting manufacturing sector mobility.
Singapore
Regional headquarters operations for Asia-Pacific talent mobility generate premium service demand from banking and commodities trading sectors. The Ministry of Manpower's COMPASS framework for employment pass eligibility reshapes immigration service provider certification standards. The central business district and One-North technology precinct concentrate corporate relocation procurement decision-making.
Australia
Permanent residency pathway reforms attract skilled migration programs from healthcare and resources employers. The Therapeutic Goods Administration enforces strict documentation standards for pharmaceutical shipments within household goods consignments. Sydney and Melbourne metropolitan areas concentrate destination service infrastructure for inbound assignees.
United Kingdom
Professional services firms and fintech employers sustain intra-European and transatlantic assignment volumes despite post-Brexit friction. GDPR cross-border data portability requirements mandate compliant employee record transfer protocols for EU-UK movements. The City of London and Thames Valley technology corridor anchor corporate mobility program administration.
Relocation Management Service Market Competitive Landscape
The competitive structure tilts toward full-service orchestration specialists with global network density. Tiered differentiation separates premium counselors from technology-enabled platform operators. Three archetypes dominate: integrated real estate-mortgage providers, supply chain-controlled logistics specialists, and modular API-first platforms. Consolidation pressure favors M&A activity targeting regional license holders and HR technology integration capabilities.
Within the premium full-service tier, Cartus and SIRVA occupy positions anchored by counselor-to-assignee ratios and destination service infrastructure. Graebel exemplifies supply chain-controlled competitiveness through specialized household goods logistics management. These three entities represent the dominant archetypes shaping procurement evaluation criteria across Fortune 500 mobility programs.
| Leading Market Players |
|---|
| Cartus |
| SIRVA |
| Graebel |
| Aires |
| Altair Global |
| Sterling Lexicon |
| XONEX |
| NEI |
| TRC Global Mobility |
| Others |
Pricing and Supply Chain Analysis
Enterprise procurement teams demanding configurable component menus are forcing providers to restructure legacy bundled offerings, compressing margins on standardized services while creating pricing power for specialized immigration and logistics capabilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates corporate relocation procurement, with differentiation driven by counselor-to-assignee ratios and ISO 20700 certification status. Cost compression in the economy tier is intensifying because technology-enabled self-service platforms disintermediate traditional counseling. Government agency clients exhibit the lowest price sensitivity due to security-cleared handling requirements, while individual consumers drive the hardest bargain on international moving services.
Supply Chain Analysis
Dual-sourcing requirements mandated by Fortune 500 mobility programs are fragmenting household goods logistics networks across Germany, Singapore, and the United States. Ocean freight capacity draws from Rotterdam, Singapore, and Los Angeles port systems, with container availability and customs brokerage capacity serving as critical bottlenecks. Tariff exposure on cross-border household shipments creates margin volatility for international moving coordinators. Distribution runs through centralized relocation management platforms with API-integrated spend visibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The relocation management service market functions as a stable compounder, with multinational talent mobility programs generating recurring revenue streams that withstand economic cyclicality.
For Market Incumbents: Anticipate virtual mobility substitution by embedding AI-enabled destination matching and carbon-tracked relocation packages into core offerings. Consolidate regional license holders to capture HR technology integration capabilities. The EU AI Act conformity assessment delays threaten feature parity across Atlantic operations.
For New Entrants and Emerging Players: COMPASS framework reforms in Singapore open a window for specialized APAC immigration compliance platforms targeting banking and commodities trading regional headquarters. White-space exists in subscription-based mobility benefits for remote-first technology employers. Lead with API-first modular architecture to bypass incumbent counselor infrastructure.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier providers holding FIDI-FAIM certification and proprietary household goods tracking technology. The five-to-ten year viability window favors platforms with demonstrated Workday and SAP SuccessFactors integration. Watch for digital nomad visa volume inflection as the signal for remote-work relocation infrastructure demand.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Destination Matching | Machine learning personalization improves assignment acceptance rates for corporate clients. |
| Carbon Accounting Integration | EU CSRD disclosure mandates create demand for emissions-tracked relocation packages. |
| Blockchain Shipment Documentation | Distributed ledger verification absorbs customs clearance overhead in household goods supply chains. |
| HR Technology Platform Integration | API development for Workday and SAP SuccessFactors enables real-time spend visibility. |
| APAC Regional Headquarters Expansion | Singapore COMPASS framework attracts employer investment in mobility infrastructure. |
Research Methodology
Multiple input streams — mobility program directors at multinational employers, immigration compliance officers, household goods logistics coordinators, and HR technology procurement leads — were reconciled against corporate relocation spend databases, FIDI-FAIM certification registries, customs trade documentation, and SEC filings from publicly traded service providers. Bottom-up assignment volume estimates triangulated with top-down enterprise mobility budget allocations.
Historical relocation volume trajectories cross-referenced against panel input from mobility program administrators shaped the analytical framework across service type, client type, delivery model, and insurance option dimensions. CAGRs derived from regression analysis of assignment frequency against enterprise headcount expansion and remote work policy adoption. Immigration processing time data and ocean freight rate indices fed corridor-specific growth assumptions.
Revisions become necessary when USCIS backlogs extend beyond employer tolerance thresholds or digital nomad visa frameworks proliferate faster than infrastructure deployment. Deviation in EU AI Act implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
Latin America Coworking Spaces Market
Real Estate Services
Warehousing Services Market
Real Estate Services
Singapore Customs Brokerage Market
Real Estate Services
Vietnam Self-Storage Market
Real Estate Services
Second-Hand Housing Trading Platform Market
Real Estate Services
US Landscaping Services Market
Real Estate Services
United States Real Estate Services Market
Real Estate Services
Green Lease Market
Real Estate Services
United Arab Emirates Real Estate Services Market
Real Estate Services
Co-Working Space Services Market
Real Estate Services
US Home Service Market
Real Estate Services
GCC Interior Design Services Market
Real Estate Services
Switzerland Self-Storage Market
Real Estate Services
Germany Real Estate Services Market
Real Estate Services
IBC Rental Business Market
Real Estate Services
Global Home Services Market