
 Iceland Facility Management Market | 2026-2036
Iceland Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Iceland Facility Management Market Foresight
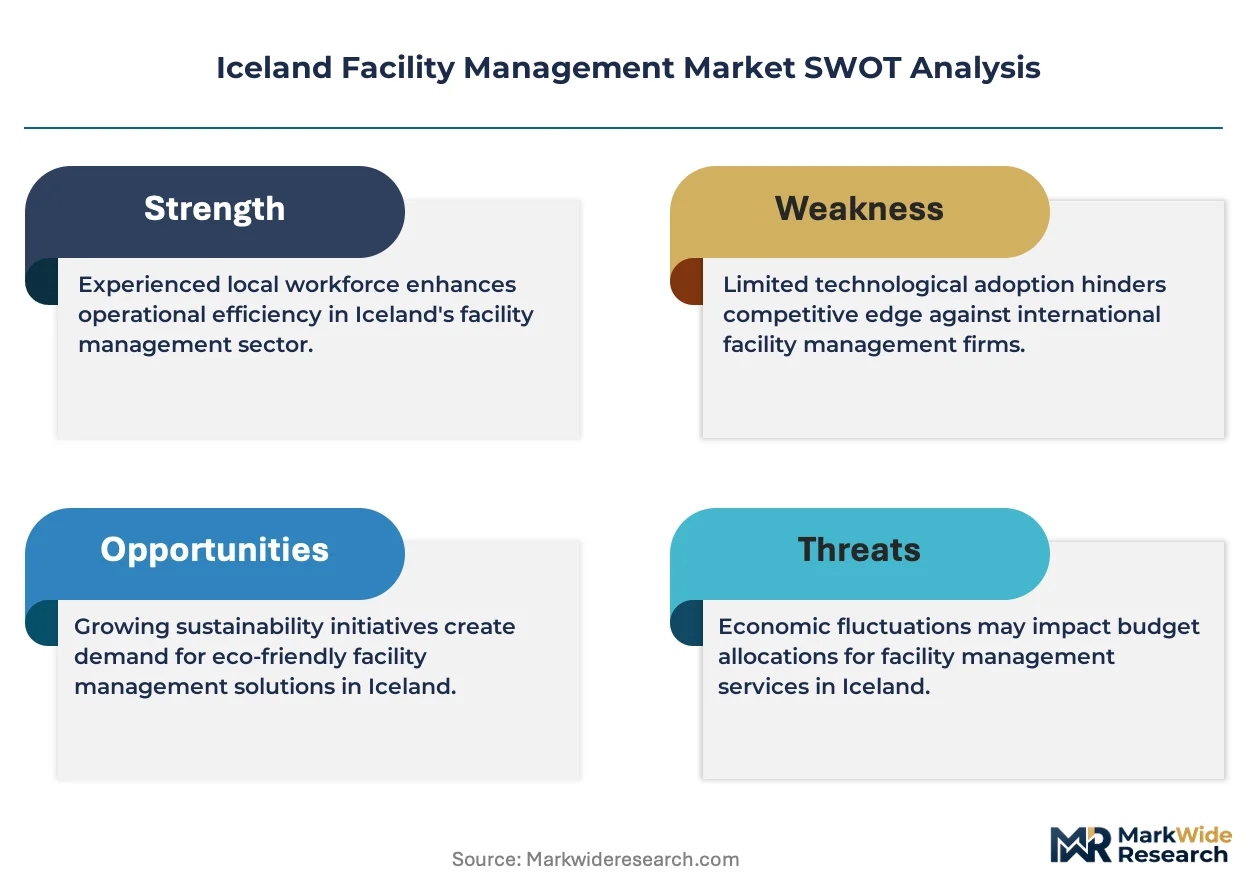
Iceland's national building energy standard is broadening the scope of mandatory energy audits and retrofit compliance across commercial property portfolios. KEY Facilities Management leverages its domestic service network to anchor large-scale maintenance contracts for public buildings. ISS Facility Services competes through specialized cleaning and hygiene protocols developed for pharmaceutical and food processing clients. ClevAir differentiates by controlling integrated HVAC and indoor air quality monitoring systems for data center operators.
Facility management encompasses the professional coordination of building operations, maintenance, cleaning, security, and energy systems to ensure safe, efficient, and compliant commercial and industrial environments. The discipline integrates preventive maintenance scheduling, thermal performance monitoring, and regulatory compliance tracking to extend asset lifecycles and reduce operational downtime. Cleaning and maintenance services occupy the largest revenue pool given Iceland's dispersed building stock and harsh climatic wear on structures. Energy management technology represents the fastest-expanding segment as building owners deploy IoT sensors and automation platforms to meet tightening thermal efficiency mandates. The outsourcing contract type dominates procurement patterns as organizations transfer operational risk to specialized service providers.
Iceland's national building regulator enforces thermal performance standards that directly shape retrofit investment cycles and service procurement specifications. The country's competition authority monitors contract concentration in municipal and state facility services to preserve tender access for mid-size operators. The central bank's macroprudential rules for commercial real estate lending indirectly influence facility upgrade timelines through financing availability. Stakeholders must track how geothermal district heating integration requirements evolve and whether in-house technical teams can match specialist providers on decarbonization compliance.
Market Dynamics
Iceland's facility management sector is being restructured by the national building energy standard's tightening thermal performance mandates, which force commercial property owners to outsource complex retrofit compliance and continuous monitoring to specialized service providers.
Growth Catalysts
- Geothermal District Heating Mandates:Municipalities across Greater Reykjavik are requiring building operators to integrate with district heating networks, creating demand for thermal system retrofit expertise and ongoing performance contracting.
- Data Center Cluster Expansion:Green computing facilities in Keflavik and Reykjanes are extending facility management contracts to cover specialized cooling, humidity control, and redundant power maintenance protocols.
- National Energy Audit Requirements:Iceland's building regulator mandates periodic energy assessments for commercial portfolios above specified floor areas, institutionalizing third-party inspection and remediation services.
Market Restraints
- Skilled Technician Scarcity:Iceland's domestic labor pool lacks sufficient certified HVAC and building automation specialists, forcing service providers to import talent or invest in extended training pipelines.
- Geographic Dispersion Costs:Facilities outside the capital region incur disproportionate travel and logistics expenses, compressing margins on maintenance contracts for rural municipal buildings and industrial sites.
- Input Material Volatility:Imported building materials and specialized equipment face currency fluctuation exposure through the Icelandic króna, creating unpredictable cost bases for multi-year service agreements.
Strategic Opportunities
- Arctic Climate Specialization Export:Icelandic facility management firms can commercialize expertise in extreme-weather building operations for Greenland, Faroe Islands, and northern Norwegian markets facing similar thermal stress conditions.
- IoT-Enabled Predictive Maintenance:Integration of wireless sensor networks with cloud-based analytics platforms allows service providers to offer guaranteed uptime contracts that differentiate against reactive maintenance competitors.
- Public-Private Partnership Models:Municipal asset privatization initiatives create long-term concession opportunities for integrated facility management operators willing to assume lifecycle cost risks on schools, hospitals, and administrative buildings.
Industry Challenges
- Building Automation System Interoperability:Legacy HVAC controls from multiple manufacturers resist integration with modern IoT platforms, requiring costly middleware development or full system replacement.
- Certification Timeline Compression:The national building energy standard's phased compliance deadlines force simultaneous retrofit execution across multiple properties, straining contractor capacity and quality assurance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iceland Facility Management Market |
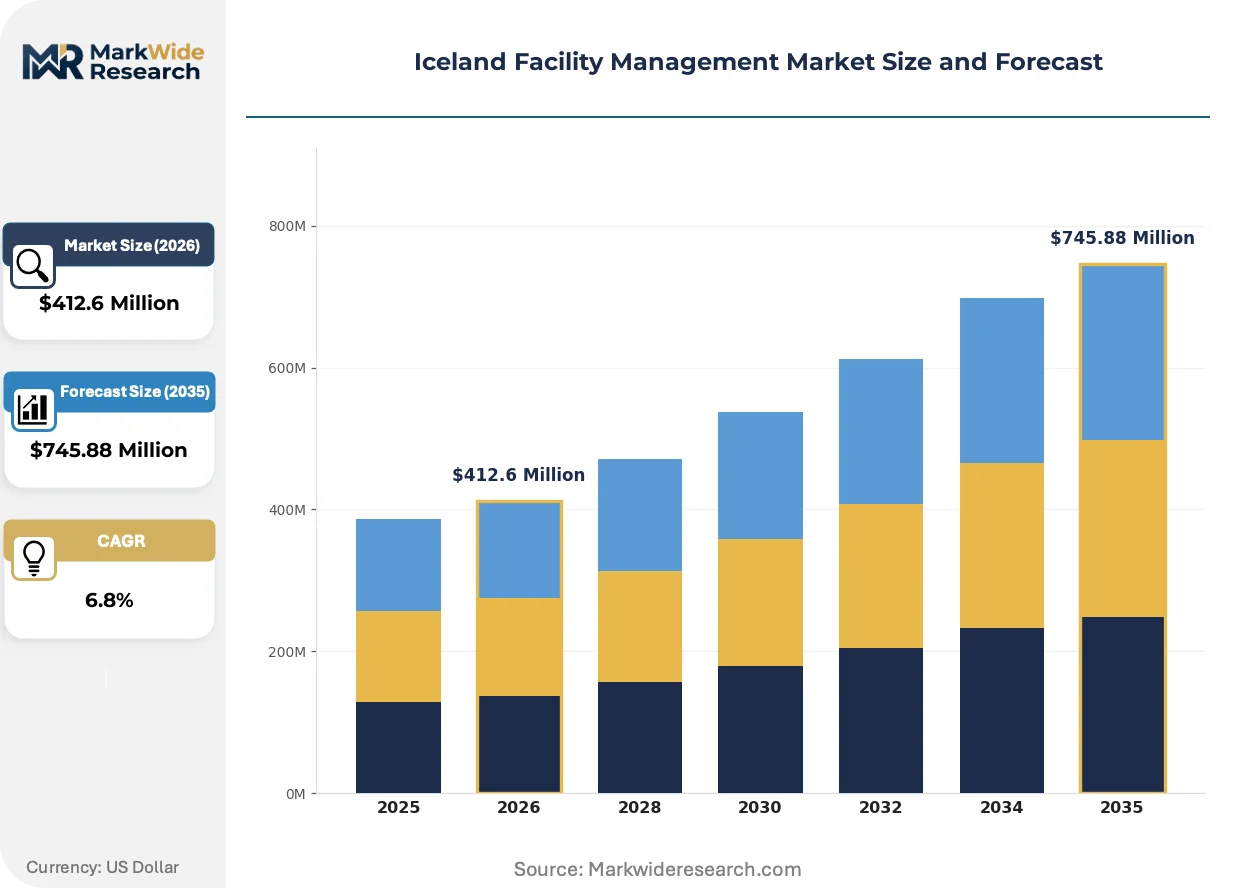
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Maintenance, Security, Landscaping Client Type: Commercial, Residential, Industrial, Government Technology: Automation, IoT, Energy Management, Waste Management Contract Type: Outsourcing, In-house, Hybrid, Ad-hoc |
| Companies Covered | KEY Facilities Management, ISS Facility Services, Diversey Holdings Ltd, ClevAir, Securitas Iceland, BG Cleaning Systems, Reitir fasteignafelag hf, Veitur, EG MainManager, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iceland Facility Management Market Shifts & Advancements
Digital infrastructure is penetrating Iceland's dispersed building stock, transforming how thermal performance is monitored and how service contracts are structured around measurable outcomes rather than scheduled visits.
Building energy management software is electrifying facility operations by centralizing control of heating, ventilation, and lighting systems through unified dashboards. Data center operators and large commercial landlords in Reykjavik are deploying these platforms to automate demand response and document compliance with tightening efficiency mandates. This technology is electrifying competitive positioning by enabling providers to offer guaranteed energy reduction contracts that traditional maintenance firms cannot match.
Iceland's national building regulator enforces thermal performance standards that mandate specific U-values for building envelopes and require documented retrofit progress across commercial portfolios. Property owners must commission certified energy audits and implement recommended improvements on fixed timelines to maintain occupancy permits. Data center and pharmaceutical manufacturing facilities face the most stringent interpretation given their continuous operational profiles and international sustainability reporting obligations.
Facility managers are consolidating vendor relationships to reduce coordination overhead and transfer operational risk through single-point accountability. Large commercial property owners in Greater Reykjavik are replacing fragmented service contracts with integrated agreements covering maintenance, cleaning, security, and energy management. This concentration is most visible among institutional investors and REITs managing multi-building portfolios who prioritize predictable operational expenditure over lowest-bid procurement.
Iceland Facility Management Market Segmentation
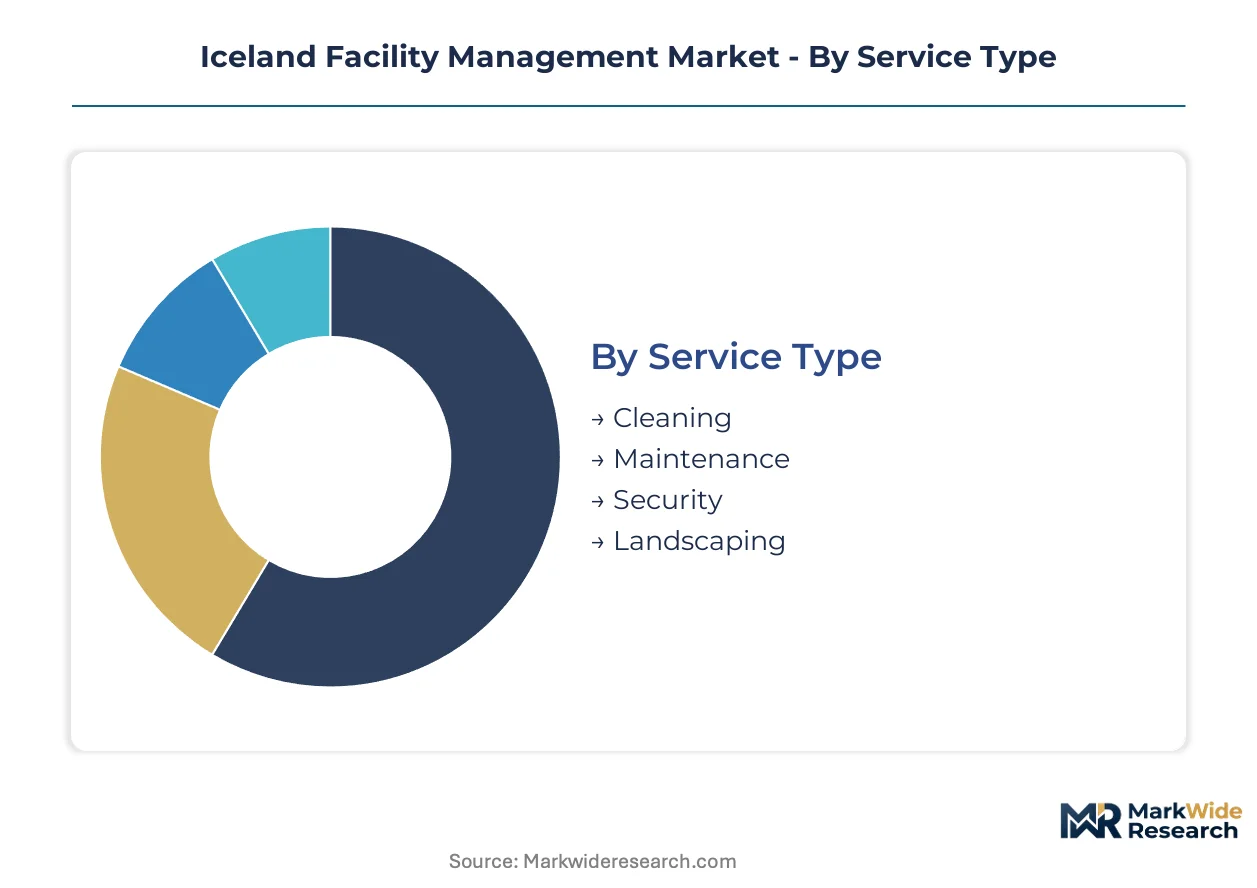
Iceland's facility management providers structure service portfolios around distinct operational rhythms and asset ownership patterns. Segment boundaries reflect how geothermal heating integration, data center cooling demands, and municipal procurement rules reshape contract specifications across the island.
Service Type:
Upgrade cycles for building systems and exterior surfaces dictate renewal frequency and contract bundling strategies across Iceland's climatic stress zones.
- Cleaning:Specialized protocols address salt corrosion on coastal commercial facades and volcanic particulate accumulation in rural municipal structures. Demand clusters around pharmaceutical manufacturing plants in Reykjavik and food processing facilities requiring hygienic zone compliance.
- Maintenance:Preventive scheduling for HVAC, electrical, and structural systems extends asset lifecycles against freeze-thaw degradation. Data center operators in Keflavik and Reykjanes contract for redundant cooling system uptime guarantees and geothermal heat exchanger maintenance.
- Security:Remote monitoring and physical guarding services protect dispersed industrial sites and public buildings. Rural logistics centers and harbor facilities require integrated access control against weather-related intrusion risks.
- Landscaping:Arctic-hardscape design and snow-load management for commercial exteriors. Limited deployment outside Reykjavik's corporate headquarters and hospitality clusters.
Volume placements concentrate in Maintenance; the faster expansion belongs to Cleaning as pharmaceutical and food safety audits intensify.
Client Type:
Cost tier differentiation separates institutional procurement with lifecycle accountability from transactional service purchasing.
- Commercial:Multi-tenant office buildings and retail portfolios in Greater Reykjavik drive integrated facility management contracts. Property investors prioritize predictable operational expenditure over fragmented vendor coordination.
- Industrial:Aluminum smelters, fish processing plants, and data centers require specialized environmental controls and continuous operational support. Geothermal power integration mandates thermal system expertise unique to Iceland's energy infrastructure.
- Government:Municipal and state buildings face tightening energy audit compliance under national building standards. Public procurement concentrates maintenance contracts through framework agreements favoring domestic service networks.
- Residential:Condominium associations and rental property managers purchase discrete cleaning and maintenance services. Limited bundling compared to commercial portfolios due to smaller scale and owner fragmentation.
Commercial clients generate the deepest contract values; Government procurement is climbing fastest as energy retrofit mandates expand public building portfolios.
Technology:
Application maturity separates proven building automation from emerging predictive platforms requiring sensor infrastructure investment.
- Energy Management:Centralized dashboards control geothermal district heating integration, lighting, and ventilation across commercial portfolios. Large landlords deploy these platforms to automate demand response and document regulatory compliance.
- IoT:Wireless sensor networks monitor thermal performance, occupancy patterns, and equipment health in real time. Data center operators lead adoption for cooling optimization and humidity control in Iceland's green computing cluster.
- Automation:Building management systems execute scheduled HVAC setpoints and lighting controls with limited adaptive capability. Established presence in newer commercial construction and retrofitted public buildings.
- Waste Management:Smart sorting and collection logistics for commercial and industrial generators. Emerging deployment around circular economy mandates in manufacturing and hospitality sectors.
Automation holds the installed base advantage; IoT is gaining share fastest as guaranteed uptime contracts displace reactive maintenance models.
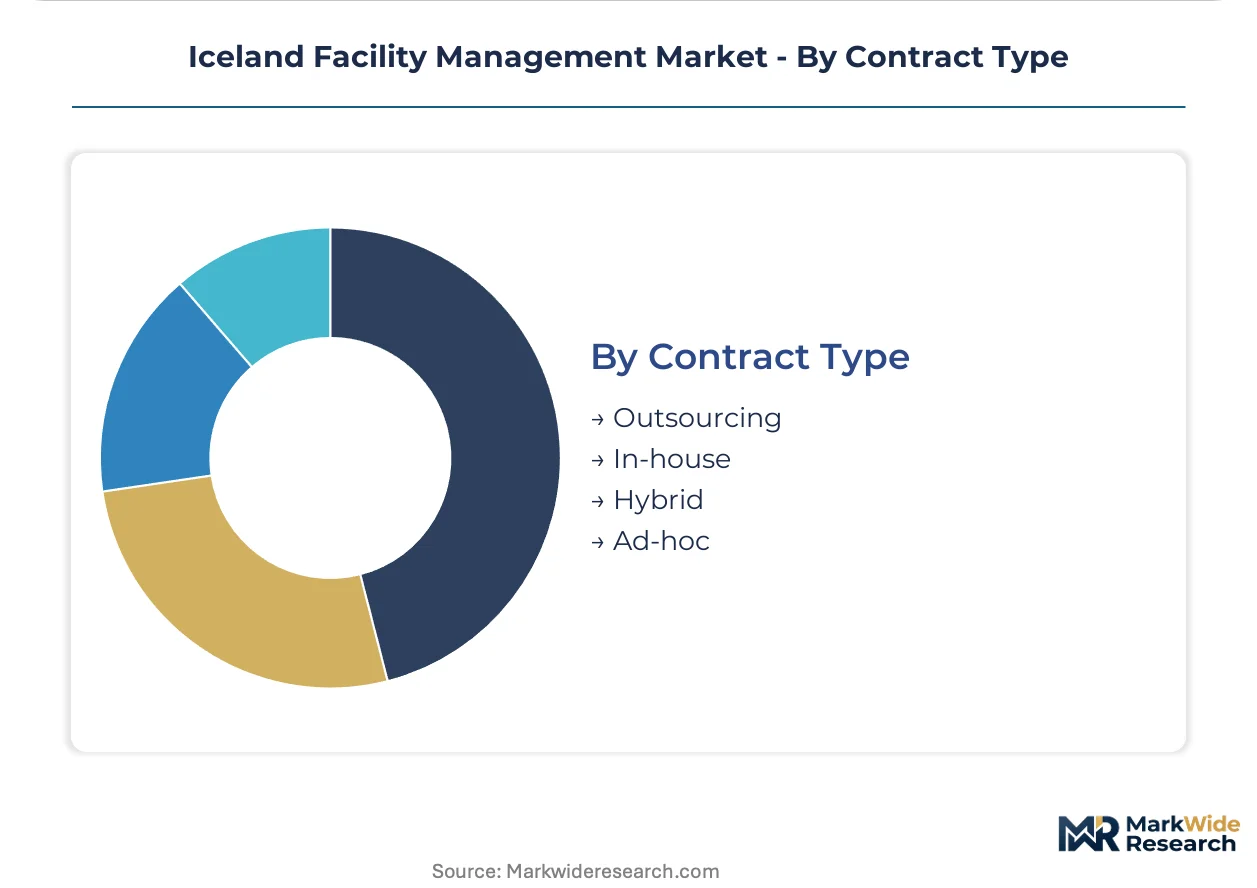
Contract Type:
Customer risk appetite determines whether operational accountability stays internal or transfers to specialized providers.
- Outsourcing:Comprehensive service agreements transfer full facility operations to third-party managers. Institutional investors and REITs favor this structure for multi-building portfolios requiring single-point accountability.
- Hybrid:Core maintenance stays in-house while specialized cleaning, security, or energy services are contracted externally. Mid-size commercial owners balance control with access to technical expertise.
- In-house:Direct employment of maintenance and operations staff retained by industrial operators with proprietary processes. Data center and pharmaceutical facilities maintain captive teams for critical system oversight.
- Ad-hoc:Transactional purchasing for discrete projects or emergency response without ongoing service relationships. Small residential associations and rural municipal buildings rely on spot contracting.
Outsourcing commands the largest contract value pool; Hybrid arrangements are expanding most quickly as owners segment critical from commodity services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Reykjavik anchors Iceland's facility management demand through its concentration of corporate headquarters, public administration buildings, and data center operations. The capital region generates the majority of contract value as institutional investors consolidate multi-building portfolios under integrated service agreements. Service providers face acute trade-offs between scale economies in Reykjavik and margin compression from rural logistics costs.
Greater Reykjavik
Multi-tenant office buildings and retail portfolios drive integrated facility management procurement as property investors prioritize predictable operational expenditure. Iceland's national building regulator enforces tightening thermal performance standards that mandate periodic energy audits and documented retrofit progress. The Keflavik and Reykjanes data center cluster extends specialized contracts covering redundant cooling system maintenance and geothermal heat exchanger oversight.
South Iceland
Aluminum smelters and fish processing plants require continuous operational support with specialized environmental controls tied to geothermal power integration. Municipal procurement frameworks concentrate maintenance contracts for public buildings through agreements favoring domestic service networks. The rural municipal building stock outside Reykjavik faces disproportionate travel and logistics expenses that compress service margins.
North Iceland
Harbor facilities and logistics centers demand integrated access control and remote monitoring against weather-related intrusion risks. The country's competition authority monitors contract concentration in municipal facility services to preserve tender access for mid-size operators. Akureyri's regional commercial hub generates discrete cleaning and maintenance purchasing from smaller-scale property managers.
East Iceland
Industrial sites and dispersed public buildings rely on spot contracting for emergency response without ongoing service relationships. The central bank's macroprudential rules for commercial real estate lending indirectly influence facility upgrade timelines through financing availability constraints. Limited procurement volume restricts integrated contract development outside framework agreements for state administrative buildings.
Westfjords
Extreme geographic isolation forces service providers to absorb elevated travel costs or decline maintenance contracts entirely. The national building energy standard's phased compliance deadlines strain contractor capacity across simultaneous rural retrofit execution requirements. Small municipal buildings and isolated industrial installations depend on ad-hoc transactional purchasing with minimal bundling.
Iceland Facility Management Market Competitive Landscape
Premium-margin players sit above commodity-margin players across specialization depth and regulatory compliance capability. The market structures around domestic incumbents with established public sector relationships, international operators with standardized protocols, and technology-focused entrants with IoT-enabled service models. Three archetypes dominate: integrated full-service providers, specialized technical contractors, and digital-native monitoring platforms. Competitive moves concentrate on vendor consolidation for single-point accountability and technology licensing for predictive maintenance capabilities.
Within the integrated service tier, KEY Facilities Management and ISS Facility Services occupy positions defined by scale and protocol standardization. ClevAir exemplifies the technology-specialist archetype through its positioning around HVAC and indoor air quality monitoring systems. These three companies represent the competitive spectrum from domestic network leverage through international operational standards to sensor-based service differentiation.
| Leading Market Players |
|---|
| KEY Facilities Management |
| ISS Facility Services |
| Diversey Holdings Ltd |
| ClevAir |
| Securitas Iceland |
| BG Cleaning Systems |
| Reitir fasteignafelag hf |
| Veitur |
| EG MainManager |
| Others |
Supply & Pricing Matrix
Institutional investors and REITs managing multi-building portfolios in Greater Reykjavik anchor pricing power through integrated service agreements that transfer operational risk to single-point providers. This buyer concentration forces facility management firms to compete on guaranteed uptime contracts and energy reduction outcomes rather than hourly labor rates.
Pricing Analysis
Guaranteed energy reduction contracts tied to measurable thermal performance outcomes command premium positioning in Iceland's facility management market. Pricing stratifies across integrated full-service agreements, specialized technical modules, and transactional spot contracts based on certification depth and regulatory compliance capability. Cost compression in rural maintenance tiers intensifies because geographic dispersion erodes margin buffers on travel and logistics. Municipal procurement frameworks exhibit highest price sensitivity due to fixed budget cycles, while data center operators prioritize uptime guarantees over lowest-bid procurement.
Supply Chain Analysis
Equipment refurbishment and component remanufacturing flows remain underdeveloped in Iceland's facility management sector, creating dependency on new equipment imports from Germany, Denmark, and the Netherlands. HVAC automation hardware, geothermal heat exchanger components, and IoT sensor networks draw from continental European manufacturing hubs. Single-source vulnerability concentrates in specialized building automation controllers where middleware integration requires vendor-specific licensing. Distribution runs through Reykjavik-based technical wholesalers serving the capital region, with direct manufacturer relationships required for data center and industrial clients in Keflavik and Reykjanes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Iceland's facility management sector is becoming a vertical-integration race as providers pursue backward control over geothermal system expertise and IoT platform development to escape commodity maintenance pricing.
For Market Incumbents: Cement dominance in public sector framework agreements by deepening geothermal district heating specialization before municipal retrofit mandates accelerate. Acquire mid-size technical contractors in South Iceland to preempt capacity constraints during simultaneous rural compliance deadlines. Lock in data center operators through captive heat exchanger maintenance capabilities that foreign competitors cannot replicate. For New Entrants and Emerging Players: Enter via Arctic climate specialization for Greenland and Faroe Islands markets, leveraging Iceland's extreme-weather building operations expertise as a beachhead. Target East Iceland and Westfjords municipal buildings abandoned by national providers due to logistics costs, offering remote monitoring platforms that reduce physical site visits. Lead with IoT-enabled predictive maintenance guarantees that differentiate against reactive competitors in underserved regions. For Investors and Strategic Acquirers: Distressed-cycle entries favor technology-specialist firms with proven sensor-to-cloud platforms in Greater Reykjavik, where facility owner consolidation creates demand for scalable monitoring infrastructure. Long-term viability hinges on regulatory compliance automation capabilities as Iceland's national building energy standard tightens enforcement timelines. Monitor municipal privatization announcements for public-private partnership concession opportunities as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Geothermal System Specialization | Captures municipal retrofit mandates tied to Iceland's district heating integration requirements. |
| IoT Platform Development | Enables guaranteed uptime contracts that displace reactive maintenance competitors in data centers. |
| Arctic Climate Export Capability | Commercializes extreme-weather expertise for Greenland and Faroe Islands markets facing similar thermal stress. |
| Public-Private Partnership Concessions | Transfers lifecycle cost risk on schools and hospitals while securing multi-decade revenue streams. |
| Technical Talent Pipeline Investment | Addresses certified HVAC and automation specialist scarcity constraining national service capacity. |
Research Methodology
Multi-period observation of municipal procurement patterns, energy audit compliance timelines, and data center contract extensions anchored the trend analysis, supplemented by interviews with facility directors at institutional property investors, municipal asset managers, geothermal utility engineers, and building automation specialists. Secondary validation drew from Iceland's national building regulator filings, central bank commercial real estate lending data, municipal tender databases, and competition authority contract concentration reports. Bottom-up service provider revenue estimates triangulated against top-down construction and property investment flows.
Segment-weighting approaches distributed value across service type, client vertical, technology deployment, and contract structure dimensions throughout the forecast period. CAGRs were derived from fitted growth curves calibrated to documented retrofit investment cycles and outsourcing penetration trends. Modeling incorporated geothermal district heating mandate phase-ins, data center cluster expansion timelines, and national energy audit compliance deadlines as industry-specific trajectory inputs.
Revisions become necessary when municipal privatization timelines shift, geothermal integration mandates accelerate, or currency volatility disrupts imported equipment cost structures. Forecasts reflect documented assumptions about regulatory enforcement intensity and contractor capacity expansion. Practitioners should monitor municipal framework agreement re-tendering schedules and central bank macroprudential rule adjustments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Malaysia Facility Management Market
Facility Management
United Kingdom (UK) Facility Management Market
Facility Management
Malta Facility Management Market
Facility Management
Asia-Pacific Soft Facility Management Market
Facility Management
Global Facility Management Software Market
Facility Management
Poland Facility Management Market
Facility Management
Spain Facility Management Market
Facility Management
Philippines Facility Management Market
Facility Management
Moldova Facility Management Market
Facility Management
Greece Facility Management Market
Facility Management
Switzerland Facility Management Market
Facility Management
Albania Facility Management Market
Facility Management
Brazil Facility Management Market
Facility Management
China Facility Management Market
Facility Management
Japan Facility Management Market
Facility Management
Saudi Arabia Soft Facility Management Market