
 Turkey Residential Real Estate Market | 2026-2036
Turkey Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Turkey Residential Real Estate Market Insights
Cross-laminated timber and prefabricated steel systems are decoupling residential construction from traditional reinforced-concrete cost structures in Turkey's mid-rise segment. Sur Yapı leverages captive concrete-mixing and formwork capabilities to sustain margin control across Anatolian cities. Emlak Konut GYO anchors Istanbul's urban regeneration pipeline through public-private partnerships with municipal authorities. NEF Real Estate differentiates via compact-unit designs targeting young professionals in transit-oriented zones.
Turkey residential real estate comprises land parcels, structures, and attached rights for private habitation, typically engineered to local seismic codes with reinforced-concrete shear walls or steel moment frames designed for Zone-1 earthquake loads. Apartments dominate transaction volumes across Istanbul and Ankara where vertical density aligns with land scarcity and metro expansion. Luxury villas along the Aegean and Mediterranean coasts capture premium margins from Gulf-state and Russian expat buyers. Mid-range units attract the largest first-time buyer pool, though budget-tier stock in peripheral Anatolian provinces faces oversupply risk.
TOKİ operates under Housing Development Administration statutes that mandate social-housing quotas in private developments, while the Banking Regulation and Supervision Agency (BDDK) governs mortgage-loan-to-value ratios that directly constrain buyer leverage. The Ministry of Environment, Urbanization and Climate Change enforces earthquake-risk building inventories that accelerate demolition permits in Istanbul's Zeytinburnu and Fatih districts. Stakeholders must monitor whether BDDK eases interest-rate corridors ahead of municipal election cycles, as credit availability historically triggers demand surges that outpace construction permitting capacity.
Market Dynamics
Urban regeneration mandates from Turkey's Ministry of Environment, Urbanization and Climate Change are accelerating demolition-permit issuance in Istanbul's high-risk seismic zones, compressing replacement timelines for aging reinforced-concrete stock and redirecting developer capital toward compliant new-build pipelines.
Growth Catalysts
- Citizenship-by-investment thresholds:Foreign buyers from Gulf states and Russia qualify for Turkish passports through property purchases above statutory minimums, channeling cross-border capital into luxury coastal and metropolitan segments.
- TOKİ social-housing quotas:Mandatory affordable-unit set-asides in private developments expand addressable demand pools for first-time buyers priced out of unregulated supply.
- Cross-laminated timber engineering:Prefabricated timber systems reduce foundation-to-enclosure timelines by half versus cast-in-place concrete, enabling faster inventory turnover in Anatolian secondary cities.
Market Restraints
- Rebar and cement cost volatility:Input price swings for Turkish steel reinforcement and clinker squeeze gross margins for developers locked into fixed-price presale contracts.
- BDDK loan-to-value ceilings:Banking Regulation and Supervision Agency mortgage caps constrain buyer leverage, compressing transaction velocity during rate-tightening cycles.
- Seismic-zone construction premiums:Zone-1 earthquake engineering requirements add structural steel and foundation costs that peripheral provinces cannot absorb in rental-yield calculations.
Strategic Opportunities
- Transit-oriented micro-units:Compact 35-50 square meter designs along Istanbul's Marmaray and metro extensions capture unmet demand from young professionals seeking proximity-over-space tradeoffs.
- VAT exemption extensions:Treasury incentives for first-time purchasers create pricing headroom that developers can monetize through volume-based absorption strategies.
- Smart-home infrastructure bundles:IoT-ready electrical and HVAC rough-ins differentiate mid-range stock in Ankara's Çankaya and İzmir's Konak districts where tech-literate buyer segments concentrate.
Industry Challenges
- Licensed geotechnical engineer scarcity:Site-specific soil analysis and foundation design bottlenecks delay permitting for hillside projects in Istanbul's Beykoz and Sarıyer districts.
- Title-deed clearance complexity:Multi-generational inheritance disputes and unregistered additions in Fatih and Zeytinburnu regeneration zones stall demolition timelines and financing approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkey Residential Real Estate Market |
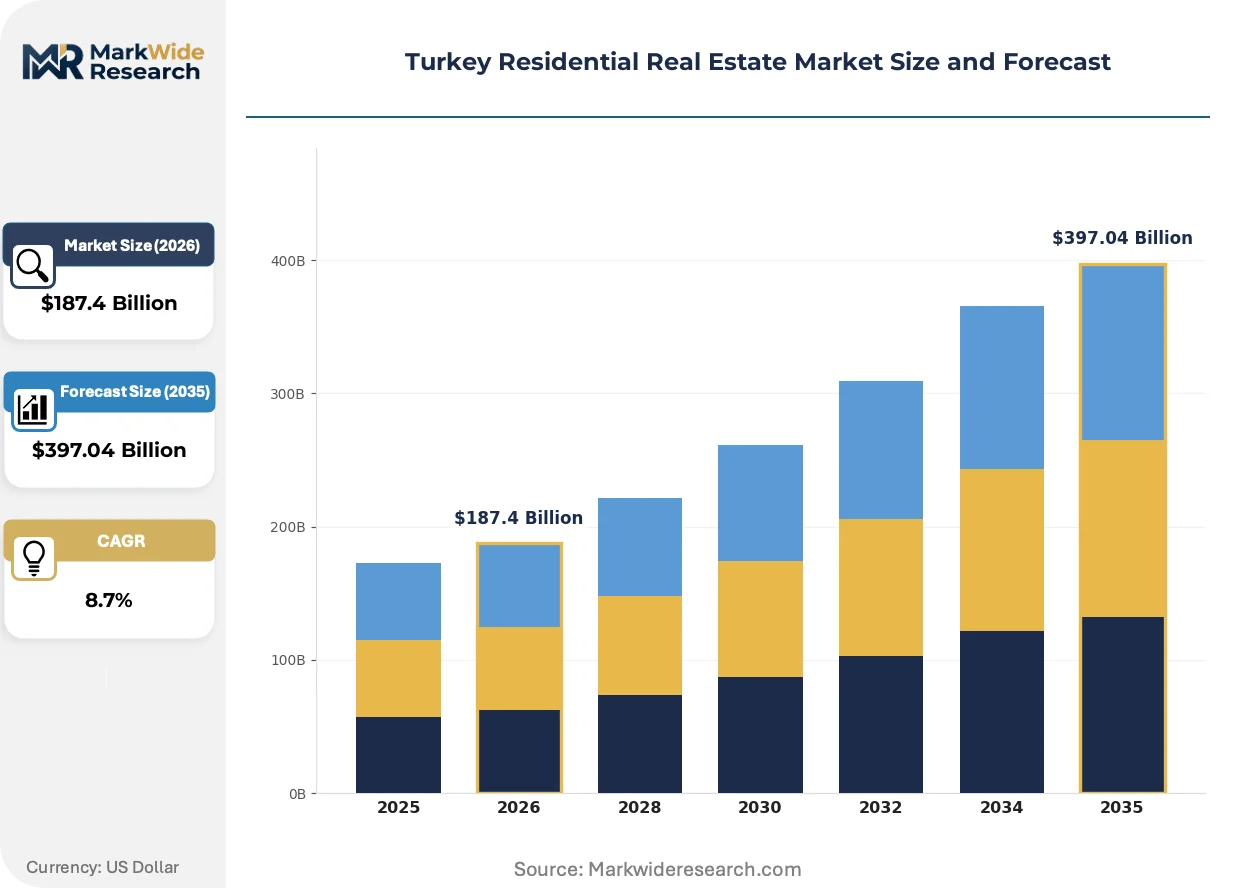
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Apartments, Villas, Townhouses, Duplexes Price Tier: Luxury, Mid-Range, Affordable, Budget Buyer Type: First-Time Buyers, Investors, Expats, Local Residents Financing Option: Cash Purchase, Mortgage, Installment Plans, Developer Financing |
| Companies Covered | Sur Yapı, NEF Real Estate, Emlak Konut GYO, Tahincioğlu Real Estate, Kuzu Group, Toplu Konut İdaresi (TOKİ), Ağaoğlu Şirketler Grubu, Nurol GYO, Sinpaş GYO, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkey Residential Real Estate Market Trends and Innovations
Digital construction workflows and modular fabrication methods are compressing project delivery cycles while regulatory pressure on seismic resilience reshapes material specifications across Turkey's residential pipeline.
Building information modeling integrated with drone-based site surveying is automating quantity-takeoff accuracy and clash-detection workflows. Mid-scale developers in Ankara and İzmir are adopting these platforms to reduce rework costs on mid-rise reinforced-concrete frames. The technology is automating schedule coordination between structural, MEP, and finishing trades that previously required manual sequencing.
Earthquake-risk building inventories enforced by the Ministry of Environment, Urbanization and Climate Change are triggering mandatory retrofit-or-demolish orders in Istanbul's Zeytinburnu and Fatih districts. Developers holding land in these zones face accelerated depreciation of existing rental stock and compressed windows for entitlement approvals. Large-scale regeneration consortia are consolidating fragmented ownership to unlock municipal density bonuses before inventory deadlines tighten.
Young professional households are prioritizing lease-to-own transition pathways over traditional mortgage-dependent purchases. Digital-native buyers in Istanbul's Kadıköy and Beşiktaş corridors favor build-to-rent operators offering equity-conversion clauses after five-year tenancies. This preference shift is diverting capital from speculative presale models toward income-producing stabilized assets with institutional-grade property management.
Turkey Residential Real Estate Market Segmentation
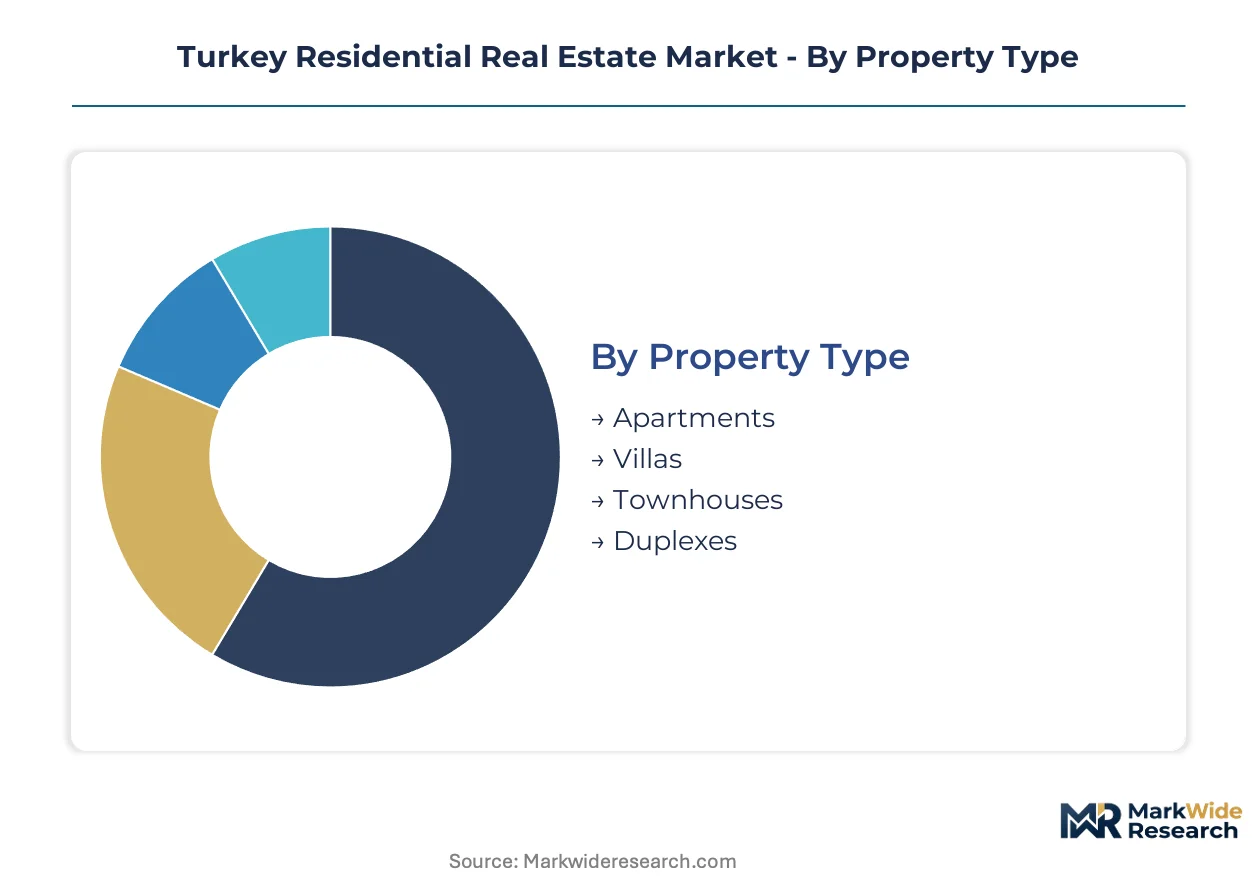
Property segmentation in Turkey's residential market reveals distinct capital requirements, buyer leverage profiles, and regulatory exposure across asset classes. Understanding these divides enables precise positioning for developers navigating Istanbul's regeneration zones versus Anatolian greenfield expansion.
Property Type:
Capital intensity varies sharply across structural forms, with vertical construction demanding foundation systems engineered for Zone-1 seismic loads while horizontal development spreads land preparation costs across larger footprints.
- Apartments:Reinforced-concrete shear-wall structures dominate transaction volumes in Istanbul and Ankara where land scarcity forces vertical density. Demand concentrates along Marmaray and metro corridor extensions where transit-oriented development bonuses from municipal authorities offset structural engineering premiums.
- Villas:Low-rise reinforced-concrete or steel moment-frame construction captures premium margins along Aegean and Mediterranean coasts. Gulf-state and Russian citizenship-by-investment buyers concentrate demand in Bodrum, Fethiye, and Antalya districts where title-deed clearance complexity remains lower than Istanbul's regeneration zones.
- Townhouses:Attached single-family units bridge density and privacy preferences in Ankara's Çankaya and İzmir's Bornova districts. TOKİ social-housing quotas increasingly incorporate townhouse typologies to diversify affordable stock beyond tower blocks.
- Duplexes:Two-level units within apartment blocks or standalone structures appeal to multi-generational households in secondary Anatolian cities. Prefabricated steel frame systems from cross-laminated timber suppliers are reducing enclosure timelines for this segment.
Most installed capacity flows through Apartments. Expansion is steepest in Villas.
Price Tier:
Margin structures stratify across pricing bands, with luxury developments absorbing seismic engineering premiums through square-meter rates while budget tiers face input cost volatility that fixed-price presale contracts cannot hedge.
- Luxury:Premium finishes, smart-home infrastructure bundles, and concierge services define this segment in Istanbul's Beşiktaş and Sarıyer districts. BDDK mortgage caps matter less here as cash purchases from domestic wealth and foreign passport-seekers dominate transaction settlement.
- Mid-Range:Standard reinforced-concrete construction with branded kitchen and bath packages attracts the largest first-time buyer pool in Ankara and İzmir. VAT exemptions and title-deed fee reductions from Treasury incentives create pricing headroom that volume-focused developers monetize through absorption velocity.
- Affordable:Compact unit designs below statutory social-housing thresholds leverage TOKİ partnership structures to access municipal density bonuses. Young professional households in Istanbul's Kadıköy corridor favor lease-to-own transition pathways within this tier.
- Budget:Peripheral Anatolian provinces face oversupply risk as rebar and cement cost volatility squeezes gross margins for developers locked into fixed-price commitments. Rental yields in these markets cannot absorb Zone-1 earthquake engineering requirements.
Revenue concentration sits in Mid-Range. Volume expansion is climbing the fastest in Affordable.
Buyer Type:
Financing flexibility and regulatory pathway complexity segment purchaser profiles, with foreign investors navigating citizenship thresholds while domestic first-time buyers depend on BDDK-governed leverage limits.
- First-Time Buyers:Domestic households entering ownership rely on mortgage products constrained by Banking Regulation and Supervision Agency loan-to-value ceilings. Demand surges historically outpace construction permitting capacity when BDDK eases interest-rate corridors ahead of electoral cycles.
- Investors:Portfolio purchasers prioritize rental yield stability in Istanbul's European-side regeneration districts where urban renewal mandates accelerate depreciation of aging stock. Income-producing stabilized assets with institutional-grade property management attract capital diverted from speculative presale models.
- Expats:Russian and Gulf-state buyers qualify for Turkish passports through property purchases above statutory minimums, channeling cross-border capital into luxury coastal and metropolitan segments. Currency hedging considerations influence timing of entry.
- Local Residents:Established households trading up or consolidating ownership navigate title-deed clearance complexity in multi-generational inheritance disputes, particularly in Fatih and Zeytinburnu regeneration zones where unregistered additions stall demolition timelines.
Transaction velocity is highest among Local Residents. Buyer base diversification is expanding most quickly in Expats.
Financing Option:
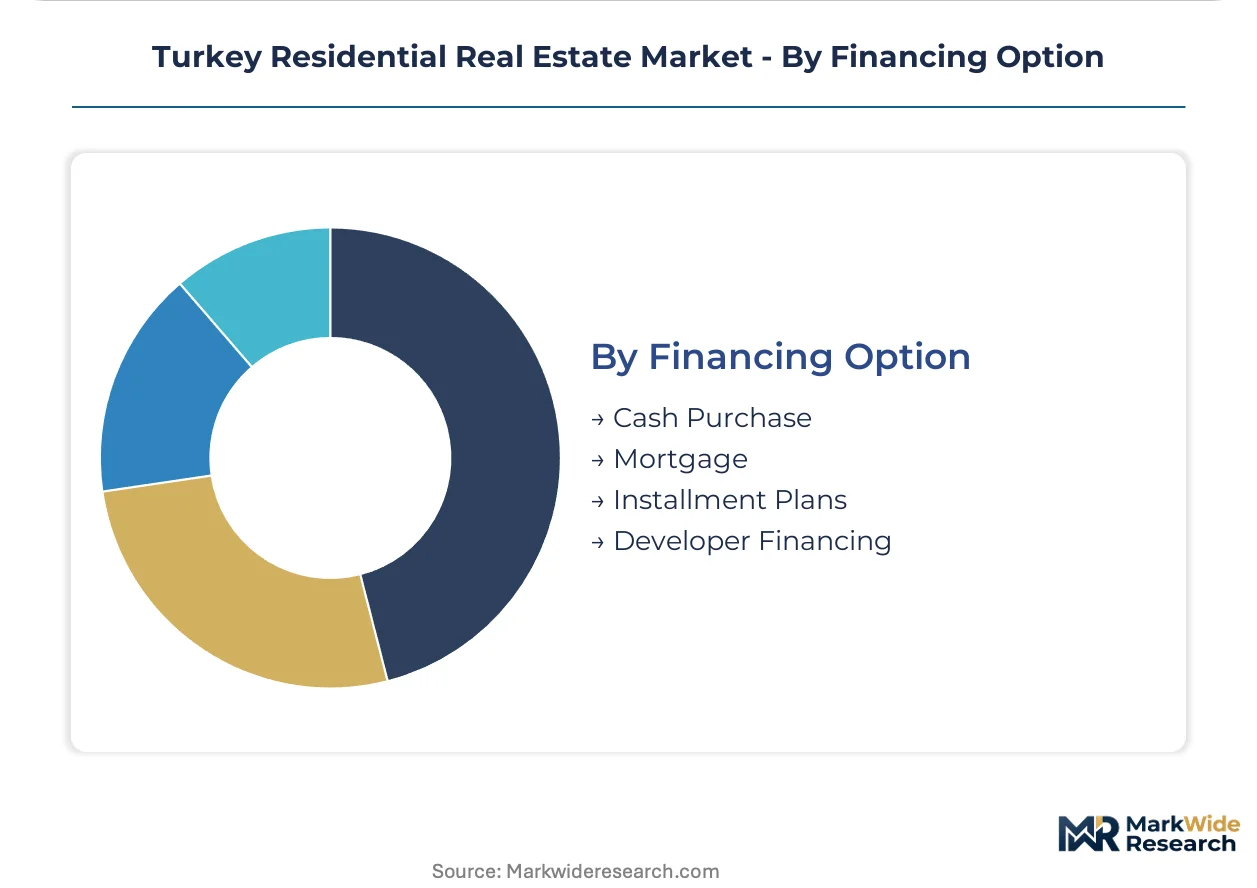
Capital source structures determine developer cash flow timing and buyer qualification barriers, with cash purchases enabling rapid settlement while installment plans extend receivables risk.
- Cash Purchase:Immediate settlement without BDDK leverage constraints dominates luxury villa transactions and citizenship-by-investment pathways. Foreign exchange inflows from Russian and Gulf-state buyers reduce developer exposure to lira volatility during construction phases.
- Mortgage:Banking Regulation and Supervision Agency-governed loan-to-value ratios compress transaction velocity during rate-tightening cycles. State-owned banks periodically offer subsidized rate windows that trigger demand surges.
- Installment Plans:Developer-extended payment terms bridge buyer qualification gaps in mid-range Anatolian markets. Receivables duration extends working capital requirements for developers lacking captive financing subsidiaries.
- Developer Financing:Captive lending arms of large-scale developers like Emlak Konut GYO and Sur Yapı internalize credit risk to accelerate absorption. Regulatory scrutiny from the Banking Regulation and Supervision Agency constrains scale of these operations.
Settlement volume runs highest through Cash Purchase. Structural innovation is advancing most rapidly in Developer Financing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Istanbul anchors Turkey's residential real estate pipeline, absorbing developer capital through urban regeneration mandates and transit-oriented density bonuses along Marmaray corridor extensions.
Istanbul
European-side districts including Zeytinburnu and Fatih drive demolition-permit acceleration under Ministry of Environment, Urbanization and Climate Change earthquake-risk inventories. TOKİ social-housing quotas mandate affordable-unit set-asides in private developments. Large-scale regeneration consortia consolidate fragmented ownership to unlock municipal density bonuses before inventory deadlines tighten.
Ankara
Çankaya district concentrates mid-range demand from civil servant households and young professionals seeking proximity to government employment clusters. BDDK-governed mortgage loan-to-value ratios constrain buyer leverage during rate-tightening cycles. Cross-laminated timber engineering reduces foundation-to-enclosure timelines for townhouse developments in Bornova-adjacent planning zones.
İzmir
Konak and Bornova districts attract tech-literate buyer segments prioritizing smart-home infrastructure bundles in mid-range stock. VAT exemptions and title-deed fee reductions for first-time purchasers create pricing headroom that volume-focused developers monetize. Aegean coastal villas in Çeşme and Alaçatı capture premium margins from Gulf-state citizenship-by-investment buyers.
Antalya
Mediterranean coastline developments concentrate foreign capital inflows from Russian passport-seekers qualifying through statutory property minimums. Title-deed clearance complexity remains lower than Istanbul's regeneration zones, accelerating settlement timelines. Resort-zone villa typologies dominate transaction structures with cash purchases circumventing BDDK leverage constraints.
Bursa
Osmangazi and Nilüfer districts absorb overflow demand from Istanbul's price-pressured first-time buyer pool. Industrial zone adjacency supports dual-income household formation in mid-range apartment stock. Rebar and cement cost volatility squeezes gross margins for developers locked into fixed-price presale contracts in this secondary Anatolian market.
Turkey Residential Real Estate Market Competitive Landscape
Global capital allocators compete with regional development champions across citizenship-by-investment pathways and urban regeneration pipelines. Market structure tilts toward consolidation around state-affiliated developers with land-bank advantages and captive financing capabilities. Three archetypes dominate: public-private partnership anchors, vertically integrated construction-to-sales operators, and foreign-capital-focused luxury specialists. Competitive positioning hardens through municipal density bonus capture and presale contract structuring that hedges input cost volatility.
Within the state-affiliated tier, Emlak Konut GYO and TOKİ exemplify public-private partnership models leveraging statutory land access and social-housing quota mandates. Sur Yapı occupies a position among vertically integrated operators controlling concrete-mixing and formwork capabilities across Anatolian cities. NEF Real Estate anchors the design-differentiated segment targeting compact-unit demand from young professionals in transit-oriented zones.
| Leading Market Players |
|---|
| Sur Yapı |
| NEF Real Estate |
| Emlak Konut GYO |
| Tahincioğlu Real Estate |
| Kuzu Group |
| Toplu Konut İdaresi (TOKİ) |
| Ağaoğlu Şirketler Grubu |
| Nurol GYO |
| Sinpaş GYO |
| Others |
Pricing and Supply Chain Analysis
Captive concrete-mixing and formwork capabilities at vertically integrated developers like Sur Yapı anchor both supply security and margin control across Turkey's residential construction pipeline. This backward integration into critical inputs insulates presale contract pricing from rebar and cement volatility while enabling fixed-cost absorption strategies in Anatolian secondary cities.
Pricing Analysis
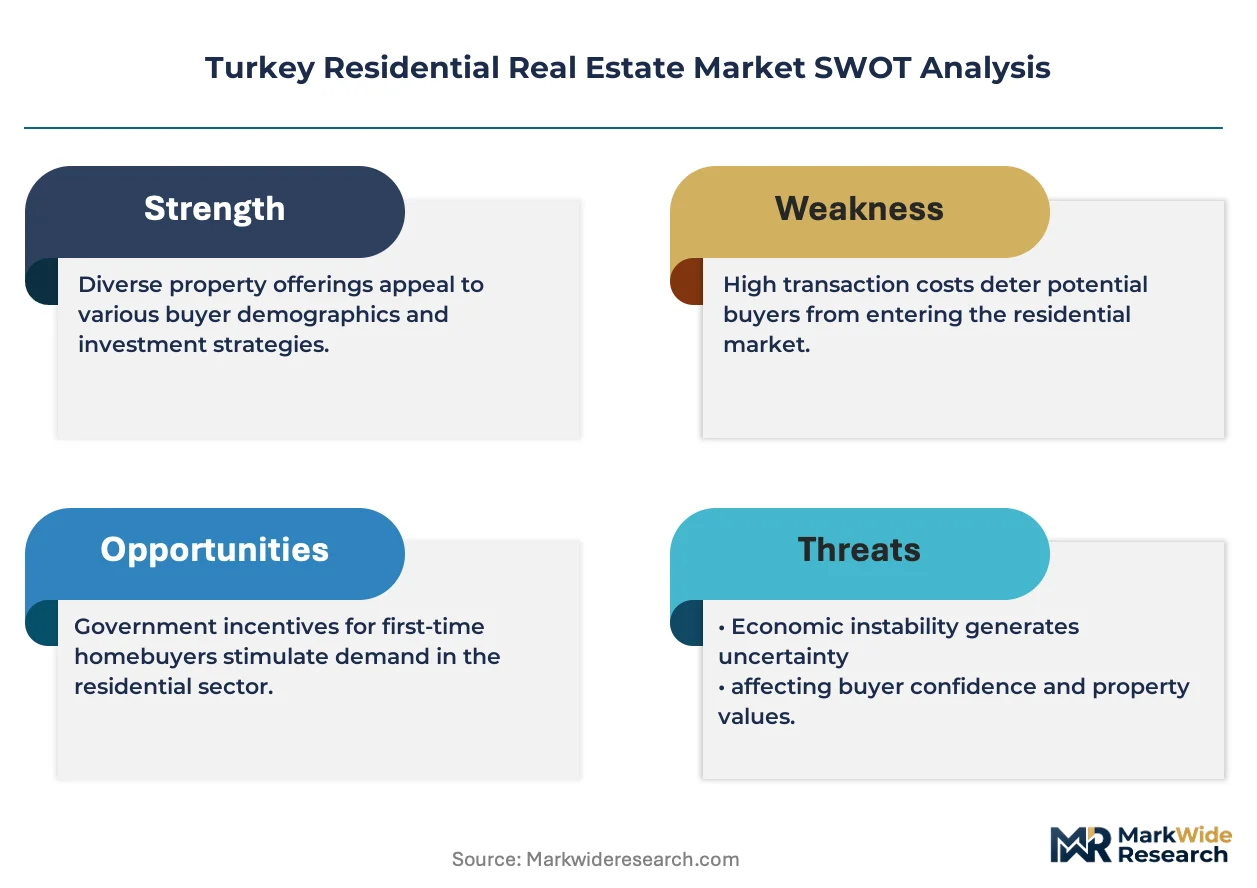
Input-cost pass-through from Turkish steel reinforcement and clinker swings compresses gross margins for developers locked into fixed-price presale commitments. Three-tier pricing structure across premium, standard, and economy levels stratifies by seismic engineering intensity and title-deed clearance complexity. Cost compression in budget-tier Anatolian stock is intensifying because rental yields cannot absorb Zone-1 foundation premiums. First-time buyers in Istanbul's regeneration zones exhibit highest price sensitivity; citizenship-by-investment purchasers in coastal villa markets show least.
Supply Chain Analysis
Licensed geotechnical engineer scarcity in Istanbul's Beykoz and Sarıyer districts bottlenecks site-specific soil analysis and foundation design workflows. Turkey's residential construction draws from domestic rebar mills, imported clinker, and cross-laminated timber systems from European suppliers. Single-source vulnerability concentrates in seismic-zone structural steel certified for Zone-1 loads. Distribution runs through developer-direct presale channels and state-owned bank mortgage products governed by BDDK loan-to-value ceilings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Turkey's residential real estate functions as a stable compounder anchored by irreversible urbanization flows into Istanbul, Ankara, and İzmir metropolitan corridors. Municipal density bonuses and citizenship-by-investment pathways generate predictable absorption velocity across economic cycles.
For Market Incumbents: Deploy captive financing subsidiaries to accelerate absorption velocity. Emlak Konut GYO and Sur Yapı demonstrate how internalized credit risk circumvents BDDK leverage constraints during rate-tightening cycles. Consolidate fragmented ownership in Zeytinburnu and Fatih regeneration zones before inventory deadlines tighten entitlement windows.
For New Entrants and Emerging Players: Capture transit-oriented micro-unit demand along Marmaray corridor extensions where compact 35-50 square meter designs address unmet young professional preferences. Lease-to-own transition pathways in Kadıköy and Beşiktaş corridors offer lower title-deed clearance complexity than regeneration zone redevelopment. Partner with municipal authorities on density bonus negotiations rather than competing for raw land.
For Investors and Strategic Acquirers: Roll-up economics work for build-to-rent operators because young professional households are diverting capital from speculative presale models toward income-producing stabilized assets with institutional-grade property management. Long-term viability centers on capturing yield compression in Istanbul's European-side districts where urban renewal mandates accelerate depreciation of aging stock. Monitor BDDK interest-rate corridor easing ahead of municipal election cycles as inflection indicator for demand surge timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Urban Regeneration Consortium Formation | Consolidates fragmented ownership in Zeytinburnu and Fatih to unlock municipal density bonuses before inventory deadlines. |
| Cross-Laminated Timber Engineering Adoption | Reduces foundation-to-enclosure timelines by half versus cast-in-place concrete in Anatolian secondary cities. |
| Citizenship-by-Investment Pipeline Development | Channels Gulf-state and Russian cross-border capital into luxury coastal and metropolitan segments above statutory minimums. |
| TOKİ Social-Housing Partnership Structure | Accesses municipal density bonuses through mandatory affordable-unit set-asides in private developments. |
| Smart-Home Infrastructure Bundle Integration | Differentiates mid-range stock in Ankara's Çankaya and İzmir's Konak districts where tech-literate buyer segments concentrate. |
Research Methodology
Direct dialogue with development project directors, municipal planning officers, mortgage product managers at state-owned banks, and geotechnical engineering consultants grounded qualitative findings in operational reality. Secondary validation drew from Ministry of Environment building inventory disclosures, BDDK regulatory bulletins, TOKİ partnership agreements, and municipal density bonus frameworks. Bottom-up project pipeline enumeration triangulated against top-down transaction volume estimates from title-deed registration systems.
Market size and growth trajectory outputs across the analysis window reflect segmentation by property type, price tier, buyer category, and financing structure. CAGRs were derived from historical absorption velocity correlated with BDDK policy cycle timing and urban regeneration permit issuance rates. Forecast inputs incorporated seismic-zone construction premium trajectories and foreign capital inflow sensitivity to lira volatility.
Regulatory enforcement intensity in earthquake-risk zones, BDDK interest-rate corridor adjustments, and citizenship-by-investment threshold modifications are the dominant revision risks that could materially alter absorption assumptions. Material deviation in these triggers warrants pause and re-evaluation of developer capital allocation and buyer qualification models.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
Mexico Residential Real Estate Market
Residential Real Estate Market
France Luxury Residential Real Estate Market
Residential Real Estate Market
Global Log Cabins or Log Homes Market
Residential Real Estate Market
India Manufactured Homes Market
Residential Real Estate Market
Japan Manufactured Homes Market
Residential Real Estate Market
Asia Pacific Manufactured Homes Market
Residential Real Estate Market
US E-House Market
Residential Real Estate Market
Spain Residential Real Estate Market
Residential Real Estate Market
Europe Residential Real Estate Market
Residential Real Estate Market
E House Market
Residential Real Estate Market
France Manufactured Homes Market
Residential Real Estate Market
Saudi Arabia Residential Real Estate Market
Residential Real Estate Market
Malaysia Residential Real Estate Market
Residential Real Estate Market
Indonesia Residential Real Estate Market
Residential Real Estate Market
Qatar Residential Real Estate Market
Residential Real Estate Market
ASEAN Manufactured Homes Market