
 Hong Kong Warehousing Market | 2026-2036
Hong Kong Warehousing Market Size, Share, and Industry Trends Forecast 2026-2036
Hong Kong Warehousing Market Insights
Greater Bay Area cross-border infrastructure is reshaping Hong Kong's warehousing landscape, with new bonded facilities and intermodal terminals altering cargo flows. ESR Cayman Limited leverages its pan-Asian development pipeline to anchor large-format distribution centers near the airport corridor. Kerry Logistics Network Limited sustains competitive positioning through integrated port-to-warehouse service bundles. Goodman Hong Kong Logistics Partnership dominates premium cold-chain and automated facilities targeting pharmaceutical and food-grade tenants.
Hong Kong warehousing comprises climate-controlled and ambient storage structures designed for inventory holding, consolidation, and last-mile distribution, typically featuring reinforced flooring systems, fire suppression arrays, and vertical clearances exceeding twelve meters to accommodate high-density racking. Distribution centers and fulfillment centers capture the majority of new construction activity as e-commerce platforms and third-party logistics operators expand their footprint. Cold storage represents a higher-margin segment where Sun Wah Cold Storage Limited and China Resources Logistics specialize in temperature-controlled infrastructure for food suppliers and pharmaceutical handlers.
Hong Kong's Buildings Department enforces fire safety and structural codes that govern warehouse design, while the Environmental Protection Department administers air quality and noise ordinances affecting logistics site selection and vehicle access windows. The Electrical and Mechanical Services Department sets energy efficiency standards that increasingly shape cooling system specifications for new facilities. Stakeholders must weigh land scarcity against automation intensity as labor costs and cross-border regulatory coordination evolve.
Market Dynamics
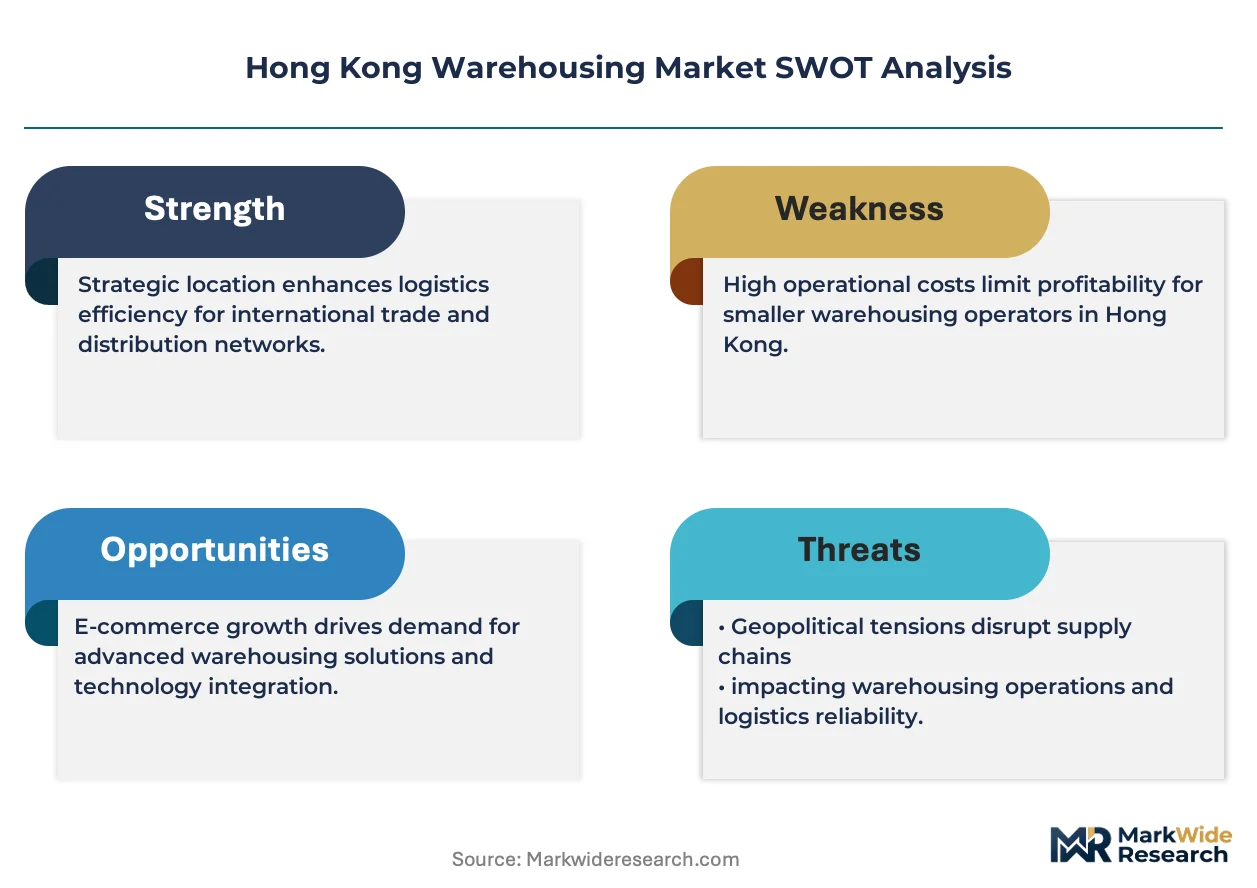
Greater Bay Area cross-border infrastructure is compressing lead times and redrawing logistics catchment boundaries, forcing warehouse operators to reposition assets closer to Shenzhen port clusters and intermodal terminals.
Growth Catalysts
- Building Energy Code Amendments:Hong Kong's Buildings Department mandates stricter thermal performance and renewable integration for new logistics facilities, accelerating demand for high-specification warehouse stock.
- Pharmaceutical Cold Chain Expansion:Temperature-controlled storage requirements from biologics distributors are pulling investment into automated cold storage infrastructure with redundant cooling systems.
- E-commerce Fulfillment Density:Platform operators are consolidating last-mile nodes near New Territories population corridors, creating sustained absorption of modern distribution centers.
Market Restraints
- Land Scarcity Premium:Industrial site availability in Hong Kong's developed areas commands rental multiples that compress operator margins and limit expansion feasibility.
- Labor Cost Escalation:Warehouse operative wages in the territory outpace regional competitors, eroding cost competitiveness for labor-intensive sorting and kitting operations.
- Cross-Border Regulatory Friction:Customs coordination protocols between Hong Kong and mainland China create documentation bottlenecks that extend dwell times at bonded facilities.
Strategic Opportunities
- Automated Storage and Retrieval Convergence:Integration of robotic shuttle systems with warehouse management software is opening greenfield development premiums in the airport corridor.
- Reverse Logistics Infrastructure:Returns processing centers serving cross-border e-commerce represent an underdeveloped segment with volume scaling potential.
- Green Building Certification Tailwinds:BEAM Plus and LEED recognition unlocks preferential financing and tenant premiums for developers targeting institutional capital.
Industry Challenges
- Automation Engineering Talent Gap:Shortage of technicians qualified to maintain robotic material handling systems is extending commissioning timelines and inflating service contract costs.
- Legacy System Integration Complexity:Older warehouse management platforms lack API architectures that modern robotics and IoT sensors require, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hong Kong Warehousing Market |
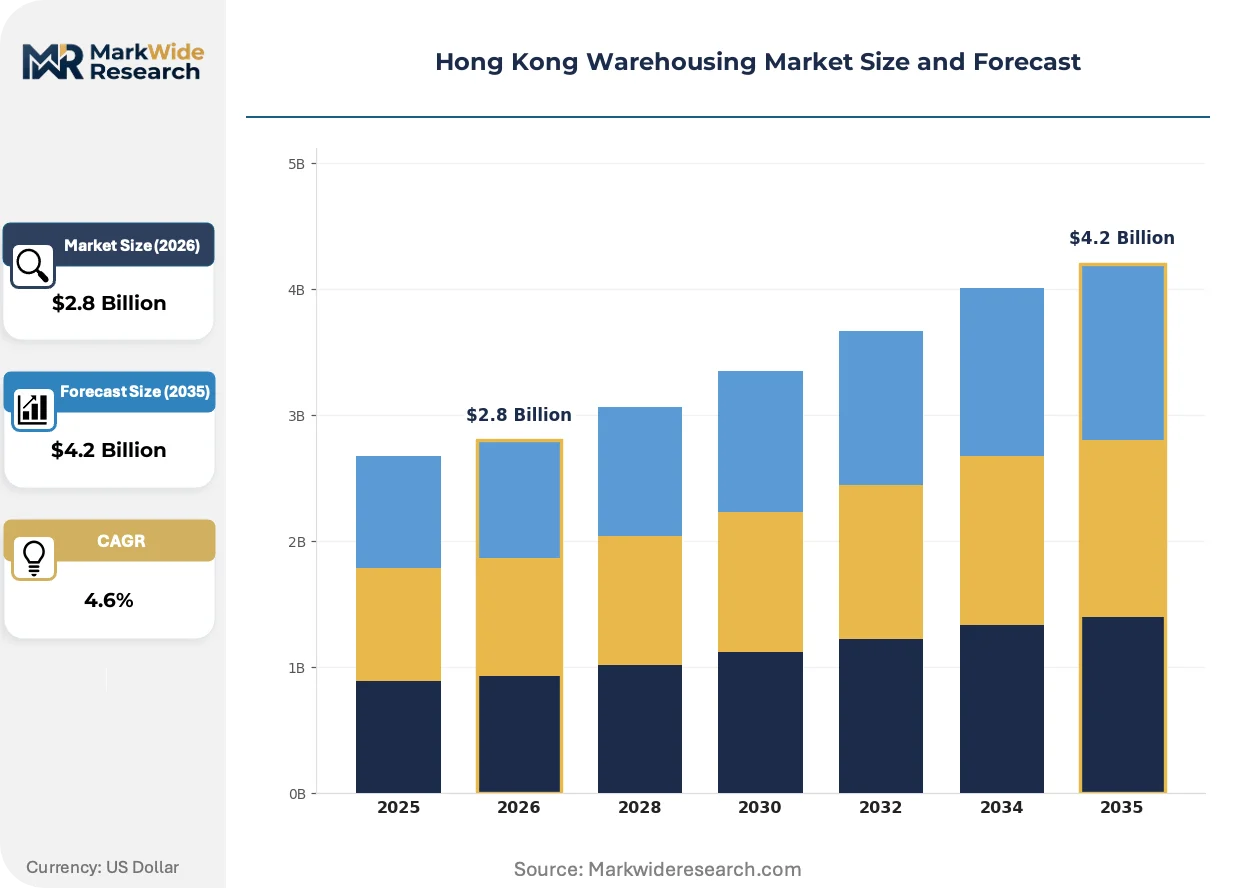
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Warehouse Type: Distribution Centers, Cold Storage, Fulfillment Centers, Bulk Warehouses Technology: Automated Systems, IoT Solutions, Inventory Management Software, Robotics End User: Retail Businesses, E-commerce Platforms, Food Suppliers, Third-party Logistics Service Type: Storage Services, Inventory Control, Order Fulfillment, Cross-docking |
| Companies Covered | ESR Cayman Limited, Goodman Hong Kong Logistics Partnership, Kerry Logistics Network Limited, Link REIT, SF Express, Dragon Crown Group Holdings Limited, Daido Group Limited, China Resources Logistics (Shatin Cold Storage) Limited, Sun Wah Cold Storage Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hong Kong Warehousing Market Trends and Innovations
Automation architectures and sustainability mandates are converging to redefine facility specifications, with capital deployment increasingly favoring assets that compress operational carbon intensity while expanding throughput capacity.
Autonomous mobile robots for pallet transport and goods-to-person picking are hybridizing warehouse labor models across Hong Kong's third-party logistics sector. Mid-size operators with 50,000 to 150,000 square meter portfolios are piloting mixed fleets of automated guided vehicles and collaborative robotic arms. This hybridization is compressing unit labor costs while raising minimum viable facility scale for competitive operation.
Hong Kong's Buildings Department energy efficiency standards now mandate heat recovery systems and high-performance envelope specifications for new warehouse approvals. The Electrical and Mechanical Services Department enforcement timeline is accelerating replacement cycles for aging refrigeration plant in cold storage assets. Pharmaceutical and food-grade tenants are responding by pre-leasing space only in facilities with certified low-carbon operations.
Platform operators are consolidating fulfillment nodes into fewer, larger facilities with direct Shenzhen highway access, displacing scattered urban depots. This concentration is reshaping last-mile subcontractor networks and compressing delivery radius economics. The shift is most visible in the New Territories, where new intermodal terminals enable single-hub coverage of both Hong Kong Island and Pearl River Delta manufacturing zones.
Hong Kong Warehousing Market Segmentation
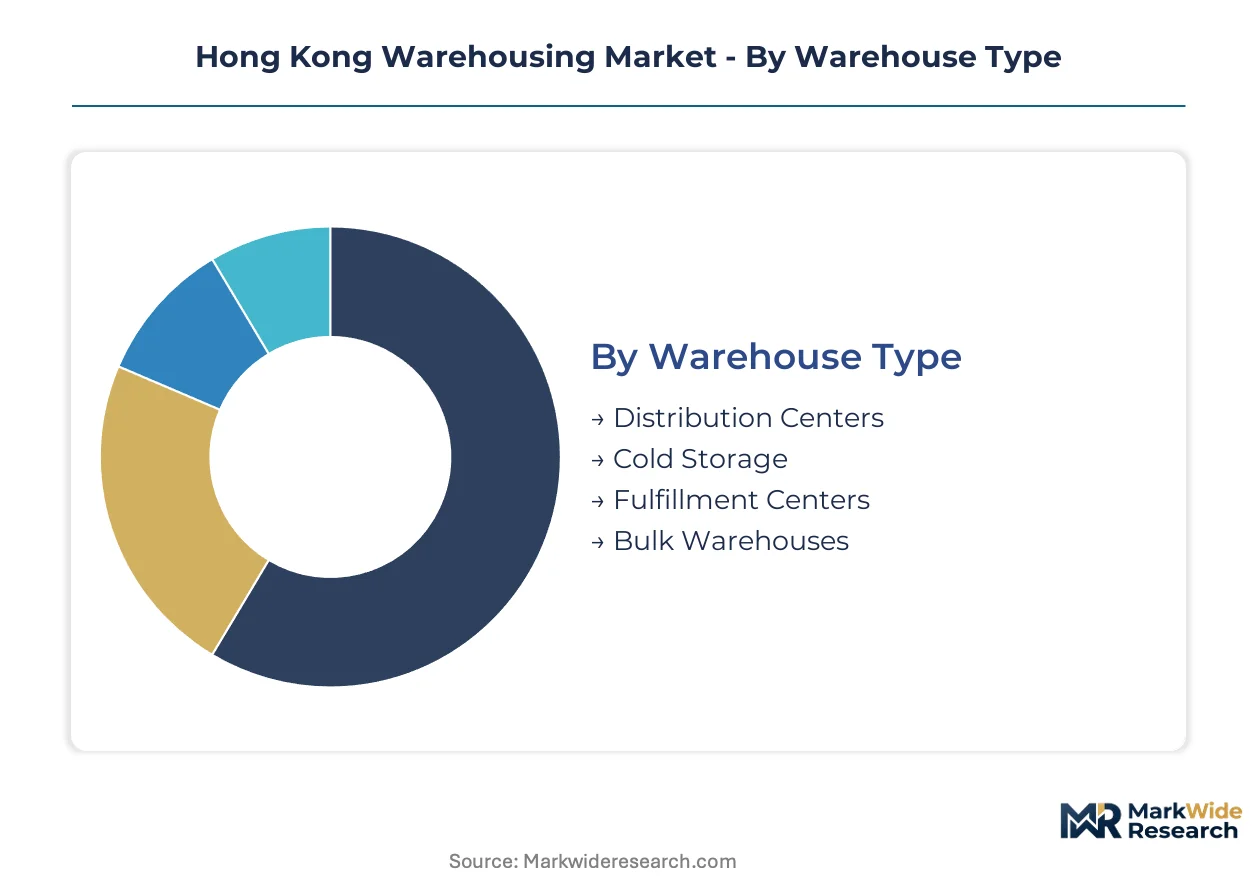
Warehouse type and technology configurations determine capital intensity and tenant premiums in Hong Kong's land-constrained logistics sector. Segmentation reveals where automation investments and cold-chain specifications are compressing operational margins or unlocking rental escalations.
Warehouse Type:
Mature formats dominate existing stock while emerging configurations capture development permits near cross-border infrastructure.
- Distribution Centers:Large-format facilities with reinforced flooring and high-bay racking accommodate consolidated inventory for regional distribution. Demand concentrates in the New Territories near Shenzhen border crossings as e-commerce platforms seek single-hub coverage of Hong Kong Island and Pearl River Delta manufacturing zones.
- Cold Storage:Temperature-controlled infrastructure with redundant cooling systems and pharmaceutical-grade monitoring serves food suppliers and biologics distributors. The Buildings Department energy efficiency standards are accelerating replacement cycles for aging refrigeration plant, pulling investment into automated cold storage with certified low-carbon operations.
- Fulfillment Centers:Last-mile nodes with goods-to-person picking systems and rapid sortation for parcel consolidation.
- Bulk Warehouses:Ambient storage structures for commodity inventory holding with minimal value-added services.
Distribution Centers retain volume leadership; Cold Storage holds the steepest expansion curve.
Technology:
Cost tier differentiation separates premium automated deployments from baseline digital infrastructure.
- Automated Systems:Robotic shuttle systems and automated storage and retrieval equipment compress labor dependence while raising minimum viable facility scale. Integration with warehouse management software is opening greenfield development premiums in the airport corridor where land costs justify capital intensity.
- Robotics:Autonomous mobile robots for pallet transport and collaborative robotic arms for piece picking hybridize labor models across third-party logistics operators. Mid-size portfolios are piloting mixed fleets that compress unit labor costs while extending commissioning timelines due to technician shortages.
- IoT Solutions:Sensor networks for environmental monitoring and asset tracking with real-time data transmission.
- Inventory Management Software:Cloud-based platforms for stock visibility and demand forecasting with API architectures for robotics integration.
Automated Systems command the highest capital deployment; Robotics is climbing the fastest as labor costs escalate.
End User:
Application concentration varies across consumer-facing platforms and industrial supply chains.
- E-commerce Platforms:Operators consolidating fulfillment nodes into fewer, larger facilities with direct Shenzhen highway access. Platform expansion across the territory is sustaining absorption of modern distribution centers in the New Territories population corridors.
- Third-party Logistics:Integrated service providers bundling port-to-warehouse offerings with value-added kitting and returns processing. Competitive positioning depends on cross-border regulatory coordination capabilities as customs protocols create documentation bottlenecks.
- Retail Businesses:Omnichannel merchants requiring flexible inventory positioning between online and physical channels.
- Food Suppliers:Temperature-sensitive handlers dependent on certified cold-chain infrastructure with BEAM Plus recognition.
E-commerce Platforms drive the largest square footage commitments; Third-party Logistics is gaining share fastest through service bundling.
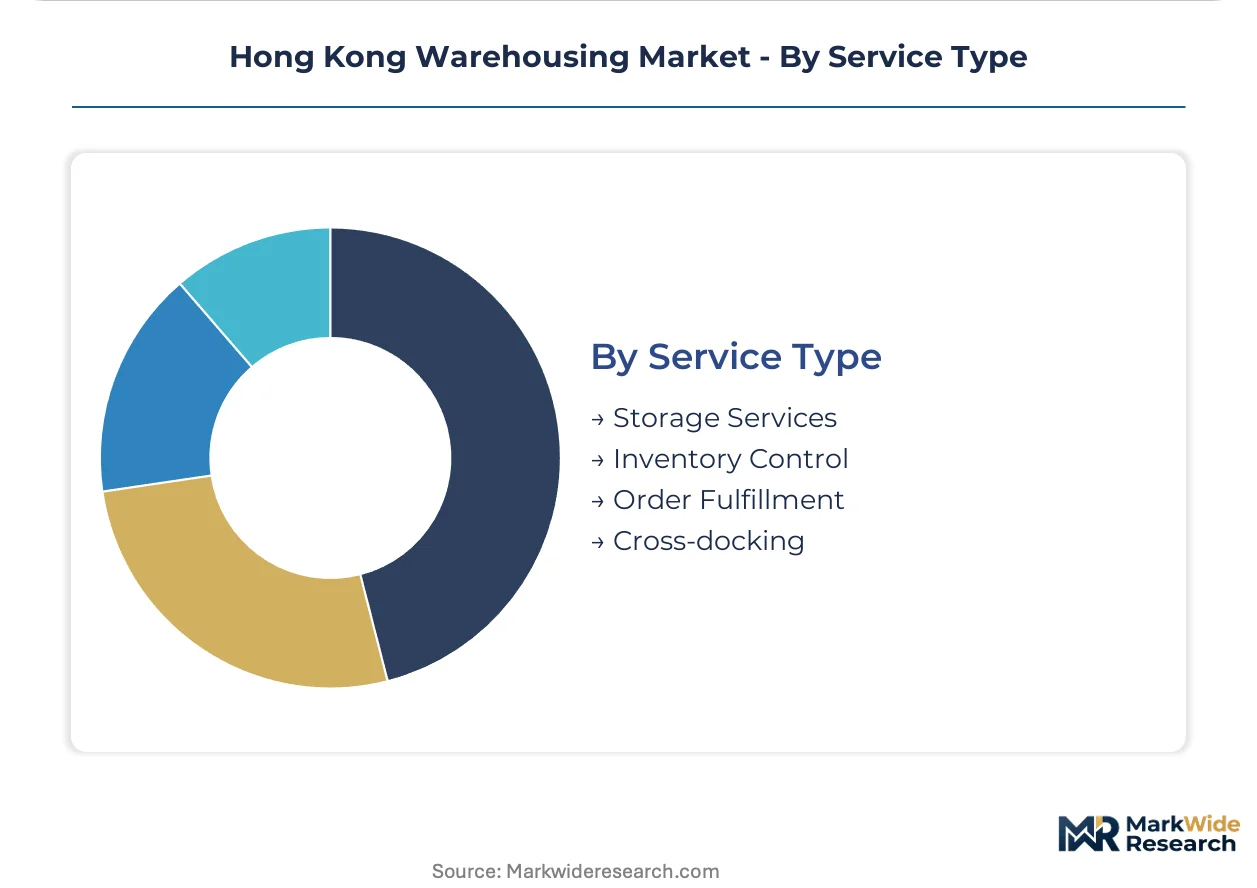
Service Type:
Margin structure separates commodity storage from value-added fulfillment capabilities.
- Order Fulfillment:Pick-pack-ship operations with same-day processing windows and returns handling. Returns processing centers serving cross-border e-commerce represent an underdeveloped segment with volume scaling potential as platform operators expand their footprint.
- Cross-docking:Direct transfer facilities minimizing inventory dwell time between inbound and outbound transportation. Greater Bay Area infrastructure compression of lead times is redrawing logistics catchment boundaries and repositioning assets closer to Shenzhen port clusters.
- Storage Services:Basic inventory holding with standard racking and climate control.
- Inventory Control:Cycle counting, quality inspection, and stock reconciliation services.
Order Fulfillment captures the highest service premiums; Cross-docking is expanding most quickly with intermodal terminal development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hong Kong's warehousing consumption pattern diverges from mainland China through its emphasis on premium cold-chain and cross-border bonded facilities rather than bulk commodity storage, reflecting the territory's role as a high-value logistics gateway rather than a manufacturing hinterland.
Kowloon
E-commerce fulfillment platforms drive warehouse absorption in urban Kowloon, with operators seeking last-mile proximity to dense population corridors. The Buildings Department enforces stringent fire safety and structural codes that elevate construction costs for vertical facilities. Kwun Tong and Kowloon Bay industrial zones are repurposing aging factory estates into automated distribution centers with goods-to-person picking systems.
New Territories
Cross-border infrastructure expansion is concentrating new warehouse development near Shenzhen border crossings, with single-hub facilities serving both Hong Kong Island and Pearl River Delta manufacturing zones. The Electrical and Mechanical Services Department mandates heat recovery systems and high-performance envelope specifications for new logistics approvals. Yuen Long and Tuen Mun corridors host large-format distribution centers with direct highway access to mainland ports.
Hong Kong Island
Pharmaceutical and food-grade tenants sustain premium cold storage demand in Central and Eastern districts, prioritizing certified low-carbon operations with redundant cooling systems. The Environmental Protection Department administers air quality and noise ordinances that restrict vehicle access windows for urban deliveries. Quarry Bay and Chai Wan retain limited warehouse stock focused on high-value inventory holding rather than throughput operations.
Lantau Island
Airport corridor development is attracting automated storage and retrieval systems with land costs justifying capital-intensive robotics integration. The Buildings Department energy efficiency standards accelerate replacement cycles for aging refrigeration plant in adjacent cold storage assets. Tung Chung and airport logistics zones are emerging as greenfield sites for pharmaceutical-grade bonded warehousing with direct air cargo connectivity.
Hong Kong Warehousing Market Competitive Landscape
Capability concentration sits with developers possessing pan-Asian pipelines and integrated service bundles; scale advantage sits with logistics operators leveraging port-to-warehouse coordination and last-mile networks. The market exhibits tiered specialization across cold-chain infrastructure, automated fulfillment, and cross-border bonded facilities. Three archetypes dominate: pan-Asian real estate developers with airport-adjacent land banks, integrated third-party logistics providers bundling customs brokerage with warehousing, and cold-chain specialists serving pharmaceutical and food-grade tenants. Competitive moves center on automation capital deployment and cross-border regulatory coordination capabilities.
Among Hong Kong-based operators, Kerry Logistics Network Limited and Link REIT exemplify the integrated service and real estate archetypes respectively, while ESR Cayman Limited anchors the pan-Asian development tier with large-format distribution center pipelines. Goodman Hong Kong Logistics Partnership occupies a position in premium automated and cold-chain facilities, reflecting the market's stratification between commodity storage and high-specification assets. These operators represent the competitive spectrum from scale-driven consolidation to specialization in temperature-controlled and pharmaceutical-grade infrastructure.
| Leading Market Players |
|---|
| ESR Cayman Limited |
| Goodman Hong Kong Logistics Partnership |
| Kerry Logistics Network Limited |
| Link REIT |
| SF Express |
| Dragon Crown Group Holdings Limited |
| Daido Group Limited |
| China Resources Logistics (Shatin Cold Storage) Limited |
| Sun Wah Cold Storage Limited |
| Others |
Pricing and Supply Chain Analysis
Shenzhen Bay Corridor freight costs compress margins for Hong Kong warehouse operators while simultaneously creating price differentiation between bonded and non-bonded facilities. Supply concentration in the New Territories near border infrastructure feeds downstream pricing power to landlords with direct highway access, leaving urban depots in Kowloon and Hong Kong Island exposed to cost pressure from last-mile density requirements.
Pricing Analysis
Rental spreads between Yuen Long distribution centers and Kowloon urban depots now exceed three-to-one multiples, with cold storage commanding further premiums based on BEAM Plus certification and redundant cooling specifications. Three-tier pricing structure across premium automated, standard high-bay, and economy bulk storage levels separates facilities by automation intensity and cross-border access. Pricing pressure stems from land scarcity premiums in developed areas that compress operator margins. E-commerce platforms show lowest price sensitivity given throughput requirements, while commodity traders face acute margin pressure from ambient storage commoditization.
Supply Chain Analysis
Tariff exposure between Hong Kong and mainland China dominates supply chain risk profiles for bonded warehouse operators navigating customs coordination protocols. Manufacturing equipment and automation hardware concentrates in China, Germany, and Japan, while refrigeration plant and racking systems draw from South Korea and Taiwan. Raw material dependencies span structural steel from Chinese mills, cooling compressors from Japanese suppliers, and warehouse management software from US and European vendors. Distribution runs through port-to-warehouse bundles controlled by integrated third-party logistics operators with customs brokerage capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hong Kong's warehousing sector rewards operators possessing automation engineering talent and cross-border regulatory expertise, with scarcity in both domains constraining competitive entry. Facility commissioning delays and service contract inflation trace directly to technician shortages, while customs documentation bottlenecks favor incumbents with established mainland coordination protocols.
For Market Incumbents: Insulate market position by deepening automation engineering capabilities through captive training programs and technician retention premiums, while securing additional development permits in the airport corridor before land scarcity intensifies. Threats from pan-Asian developers with lower capital costs necessitate differentiation through integrated service bundles combining customs brokerage with temperature-controlled infrastructure. Certification investment in BEAM Plus and pharmaceutical-grade cold-chain standards serves as the priority defensive lever. For New Entrants and Emerging Players: Reverse logistics infrastructure for cross-border e-commerce returns represents the most penetrable entry point, with volume scaling potential as platform operators consolidate fulfillment footprints. Mid-size automated facilities in Tuen Mun and Tung Chung corridors offer lower land cost entry with direct Shenzhen highway access. Go-to-market positioning should emphasize API-native warehouse management platforms that bypass legacy system integration complexity plaguing incumbent operators. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate logistics divisions with underutilized cold storage assets and stranded automation investments requiring operational turnaround expertise. Long-term viability centers on facilities with certified low-carbon operations and direct Greater Bay Area infrastructure connectivity. The signal to watch is BEAM Plus pre-leasing rates among pharmaceutical and food-grade tenants as a proxy for rental premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Automation Capital Deployment | Robotic shuttle integration in airport corridor facilities compresses labor dependence and unlocks greenfield premiums. |
| Cross-Border Regulatory Coordination | Customs brokerage capabilities bundled with warehousing reduce dwell times at bonded facilities near Shenzhen crossings. |
| Green Building Certification | BEAM Plus recognition unlocks preferential financing and tenant premiums from institutional pharmaceutical capital. |
| Cold Storage Infrastructure Expansion | Automated temperature-controlled assets with redundant cooling serve biologics distributors requiring pharmaceutical-grade monitoring. |
| Reverse Logistics Network Buildout | Returns processing centers for cross-border e-commerce capture underdeveloped segment with volume scaling potential. |
Research Methodology
The analysis maps distribution centers, cold storage facilities, fulfillment centers, and bulk warehouses, each validated through facility operators, logistics procurement managers, real estate developers, and cold-chain specialists. Primary interviews with warehouse management executives, automation system integrators, and customs brokerage professionals combined with secondary validation against Buildings Department permitting records, Electrical and Mechanical Services Department energy efficiency filings, and logistics operator SEC disclosures. Bottom-up facility inventory counts triangulated against top-down Greater Bay Area trade flow estimates.
Fixed assumptions include sustained e-commerce platform expansion across the territory and continued Buildings Department enforcement of amended energy codes, while variable conditions span cross-border customs protocol evolution and automation equipment import tariff schedules. Segmentation dimensions modeled cover warehouse type, technology configuration, end-user application, and service type across the projection horizon. CAGRs derived from facility absorption rates, replacement cycle timing for aging refrigeration plant, and automation penetration curves in third-party logistics portfolios. Forecast inputs include pharmaceutical cold-chain demand from biologics distributors and intermodal terminal development timelines.
Macroeconomic conditions sit as an overlay; deviation in Greater Bay Area trade volumes, Hong Kong industrial land release schedules, or mainland China customs digitization pace would shift the trajectory. Forecasts reflect documented assumptions subject to revision from regulatory enforcement intensity or technological substitution in material handling systems. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate
Germany Self-Storage Market
Real Estate
United Kingdom (UK) Facility Management Market
Real Estate
Qatar Luxury Residential Real Estate Market
Real Estate
Facility Management Services Market
Real Estate
UK Real Estate Market
Real Estate
North America Coworking Spaces Market
Real Estate
Asia Pacific REIT Market
Real Estate
Russia Luxury Residential Real Estate Market
Real Estate
China Smart Building Market
Real Estate
Egypt Commercial Real Estate Market
Real Estate
Europe Self Storage Market
Real Estate
United States Real Estate Brokerage Market
Real Estate
Singapore Luxury Residential Real Estate Market
Real Estate
Coworking Spaces Market
Real Estate
India Flexible Office Space Market
Real Estate
Africa Facility Management Market