
 Residential Real Estate Market | 2026-2036
Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Real Estate Market Analysis
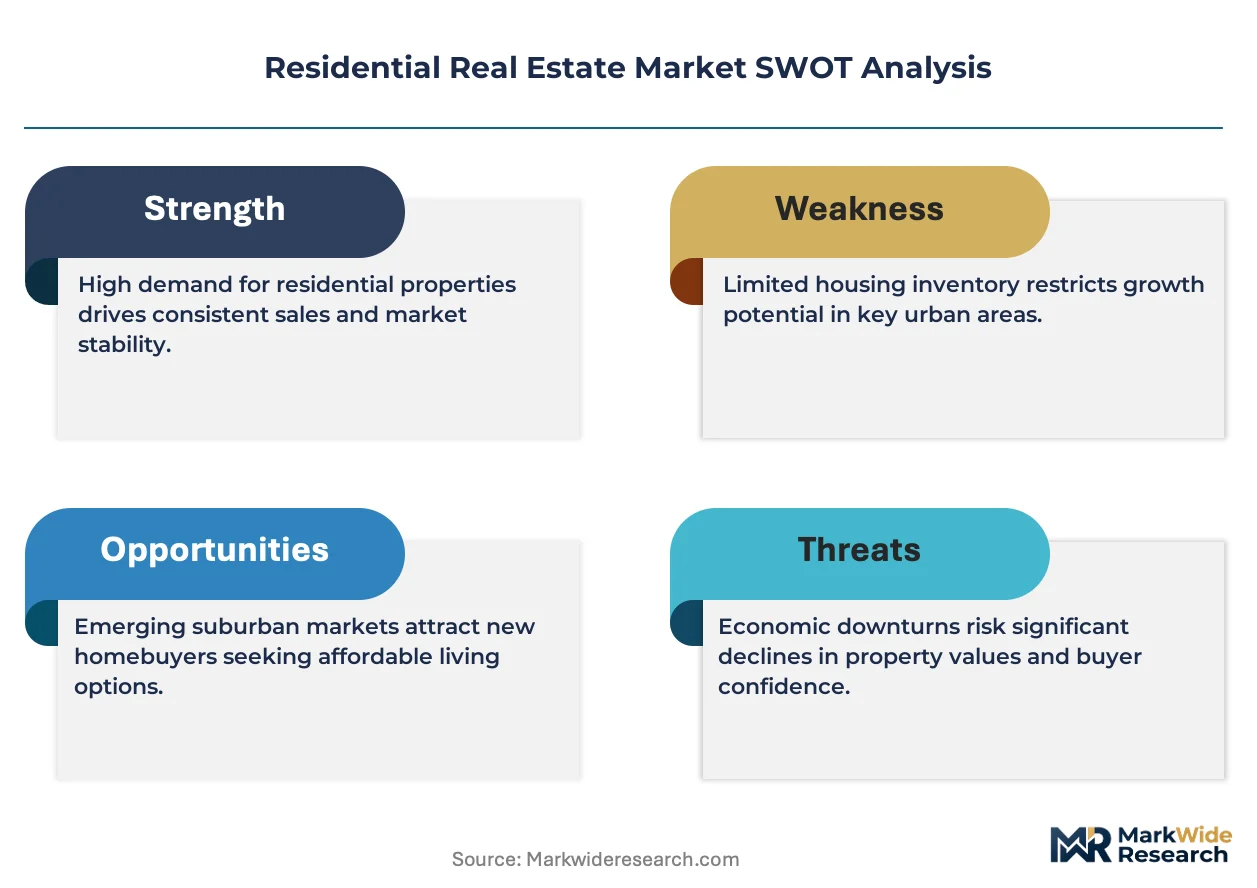
Millennial household formation is pivoting the buyer mix toward first-time purchasers seeking entry-level single-family homes. Invitation Homes leverages its institutional scale to control thousands of single-family rental units across fragmented Sun Belt metros. Vonovia SE anchors European multifamily exposure through its concentrated German portfolio. Greystar Real Estate Partners specializes in build-to-rent communities that compete directly with traditional for-sale housing.
Residential real estate comprises land parcels, permanent structures, and attached fixtures designed for human habitation, with valuation methodologies incorporating comparable sales analysis, income capitalization, and replacement cost approaches. The asset class serves primary shelter needs, wealth accumulation, and portfolio diversification for institutional and retail capital pools. Single-family homes occupy the largest value share across developed markets, while multi-family units generate superior rental yield stability in dense urban nodes. First-time buyers face structural affordability constraints as conventional loan qualification thresholds tighten, pushing volume toward FHA-backed financing. Cash purchases concentrate among investors and luxury buyers in coastal gateway cities where bidding wars persist.
FHA loan thresholds, VA eligibility standards, and local inclusionary zoning ordinances collectively shape transaction velocity and product feasibility across US submarkets. The EPA's lead-based paint disclosure requirements and state-level energy code adoptions add compliance layers that filter development economics. Stakeholders must monitor interest rate trajectories and municipal zoning liberalization as dual levers that will determine which buyer segments and property types capture marginal transaction flow.
Market Dynamics
Millennial household formation is compressing entry-level inventory across Sun Belt metropolitan areas, forcing developers to recalibrate product mix toward smaller-lot single-family homes and attached townhome formats that satisfy FHA debt-to-income thresholds.
Growth Catalysts
- FHA loan limit expansions:The Federal Housing Administration's elevated conforming thresholds in high-cost counties are unlocking purchasing power for first-time buyers previously priced out of conventional financing.
- Zoning liberalization in Austin, Texas:Municipal code amendments permitting duplex and triplex development on formerly single-family-only parcels are expanding feasible unit counts without raw land acquisition.
- Build-to-render construction platforms:Virtual design tools compress pre-development timelines and reduce soft costs for multifamily projects in supply-constrained submarkets.
Market Restraints
- Lumber futures volatility:Framing material cost swings destabilize pro forma underwriting for wood-dependent single-family production in southeastern states.
- Local inclusionary zoning mandates:California's density bonus requirements impose affordability set-asides that erode developer yields and slow entitlement timelines.
- Skilled trade labor scarcity:Electrician and plumber availability constraints in Phoenix and Dallas-Fort Worth extend construction schedules and inflate hard costs.
Strategic Opportunities
- Accessory dwelling unit policy windows:California and Oregon state preemption laws overriding local ADU prohibitions create infill development pathways without greenfield land costs.
- Single-family rental institutionalization:Professional property management platforms and bundled service offerings attract capital seeking yield stability relative to multifamily.
- Energy code convergence:IECC 2021 adoption across Mountain West jurisdictions creates demand for high-performance envelope systems and heat pump HVAC specifications.
Industry Challenges
- Entitlement timeline elongation:Environmental review processes and community opposition in coastal California metros extend project approval cycles beyond 36 months.
- Legacy system integration:Property management software migration from on-premise servers to cloud-native platforms requires substantial retraining of site-level staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Real Estate Market |
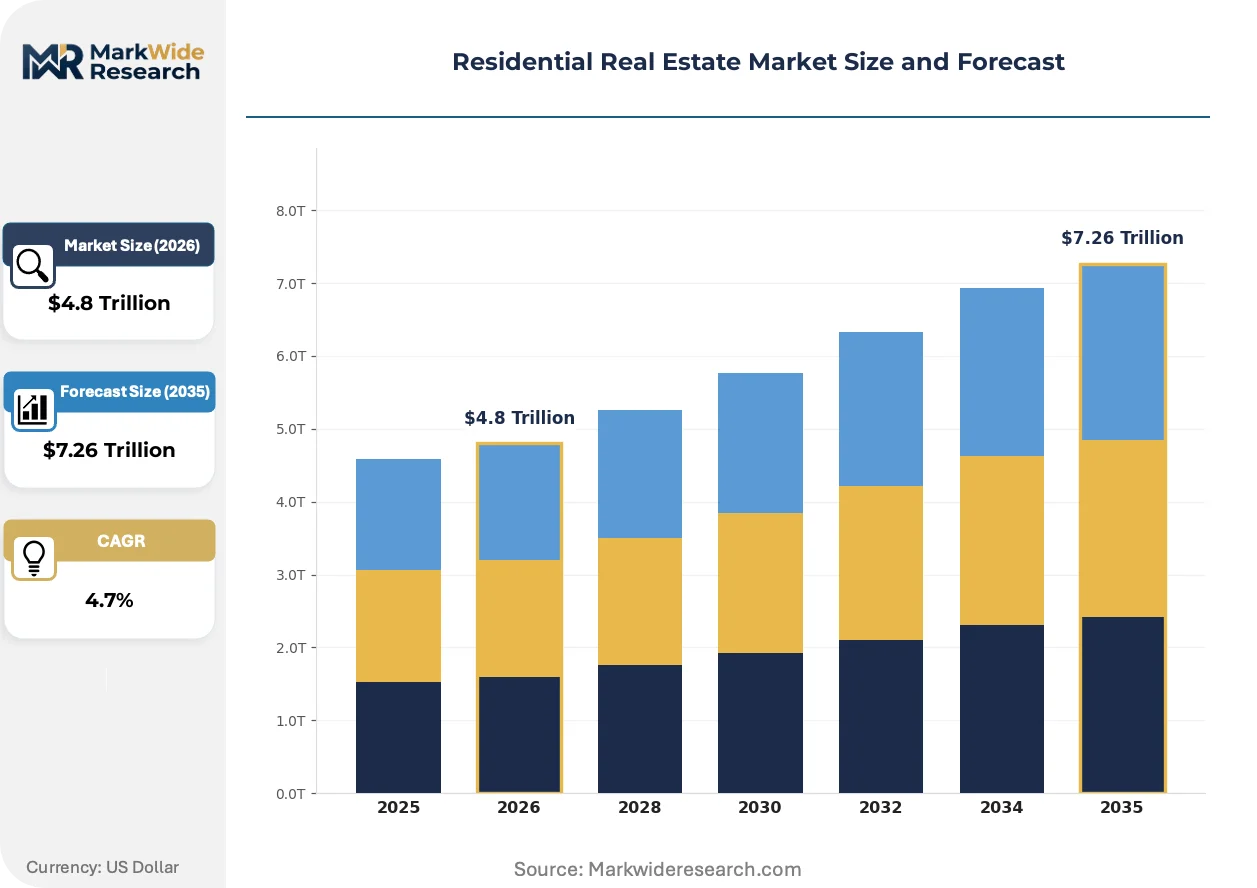
| Market Size in 2026 | $4.8 Trillion |
| Market Size in 2035 | $7.26 Trillion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Single-Family Homes, Condominiums, Townhouses, Multi-Family Units Buyer Type: First-Time Buyers, Investors, Luxury Buyers, Empty Nesters Financing Option: Conventional Loans, FHA Loans, VA Loans, Cash Purchases Sales Channel: Real Estate Agents, Online Listings, Auctions, FSBO |
| Companies Covered | Invitation Homes, AvalonBay Communities, Vonovia SE, Emaar Properties, Essex Property Trust, China Vanke Co., Ltd, Equity Residential, Tishman Speyer, Greystar Real Estate Partners, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Real Estate Market Emerging Trajectories
Digital transaction infrastructure and modular construction methods are compressing development timelines while municipal policy experiments reshape where housing can legally be built.
PropTech platforms integrating automated valuation models with digital mortgage origination are rewriting how buyers qualify and close on residential transactions. First-time purchasers in Sun Belt metros are adopting these tools at accelerating rates. The compression of closing timelines is shifting competitive advantage toward sellers who can accommodate accelerated contingencies.
The EPA's lead-based paint disclosure enforcement expansion is elevating remediation costs for pre-1978 housing stock in legacy industrial cities. Sellers in these markets face mandatory inspection protocols that delay listings. Buyers are redirecting search activity toward post-1990 construction in adjacent submarkets to circumvent compliance friction.
Institutional capital deployment into single-family rental aggregators is fragmenting traditional for-sale buyer pools in Atlanta and Charlotte. Individual purchasers compete against algorithmic acquisition programs that waive inspection contingencies. The displacement of conventional buyer segments is most pronounced in entry-level price tiers where inventory scarcity already constrains options.
Residential Real Estate Market Segmentation
Property characteristics, buyer profiles, financing mechanisms, and transaction channels each exert distinct pressure on pricing dynamics and inventory velocity. Developers and brokerages calibrate product mix and marketing spend against these axes to capture marginal transaction flow.
Property Type:
Structural specifications and density configurations determine land-use efficiency, construction cost profiles, and target buyer pools across submarkets.
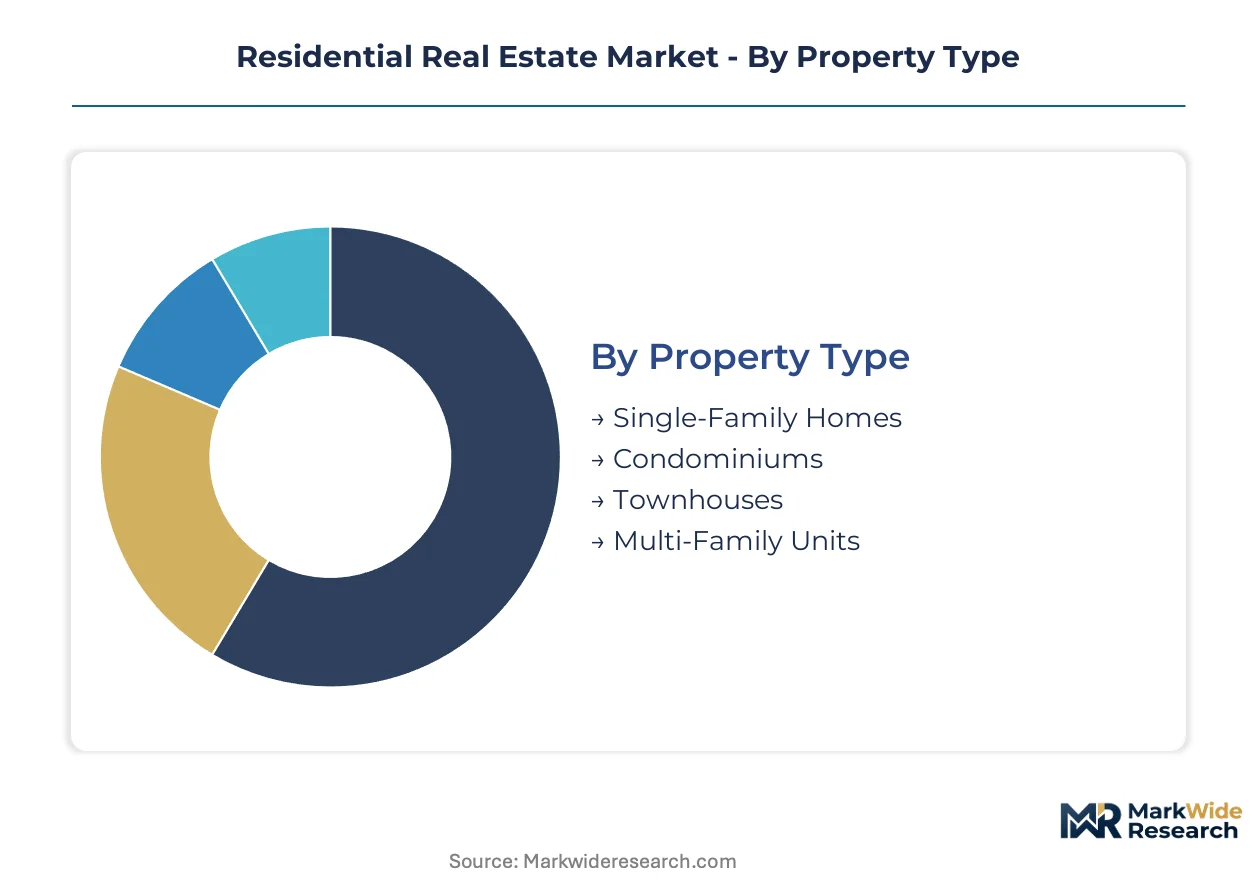
- Single-Family Homes:Detached structures on individually titled land parcels dominate suburban development patterns. Demand concentrates in Sun Belt metros where millennial household formation seeks entry-level inventory with yard space and parking provisions.
- Condominiums:Individual unit ownership within multi-story buildings with shared common elements and association governance. Newer deployment is concentrating in infill submarkets where land scarcity and zoning liberalization enable vertical density without greenfield acquisition.
- Townhouses:Attached single-family units sharing party walls with fee-simple or condominium ownership structures. Mature deployment sits with established Northeast and Midwest corridors.
- Multi-Family Units:Rental-oriented buildings containing five or more dwelling units under single ownership. Demand is climbing fastest in Austin, Phoenix, and Charlotte where institutional capital targets yield stability.
Mature deployment sits with Single-Family Homes. Newer deployment is concentrated in Multi-Family Units.
Buyer Type:
House formation stage, wealth accumulation, and investment objectives segment purchasing power and financing preference across price tiers.
- First-Time Buyers:Households entering ownership for the first time, typically constrained by debt-to-income thresholds and down payment capacity. FHA loan eligibility and zoning reforms in Texas and Florida are expanding feasible inventory access.
- Investors:Capital pools seeking rental yield or appreciation through single-family rental aggregation or small-multifamily acquisition. Algorithmic acquisition programs in Atlanta and Charlotte are displacing conventional buyer competition.
- Luxury Buyers:High-net-worth purchasers acquiring properties above local median price multiples, often with cash or jumbo financing. Coastal gateway markets retain concentration despite tax code shifts.
- Empty Nesters:Downsizing households transitioning from peak-family homes to lower-maintenance configurations. Demand is shifting toward lock-and-leave condominiums in Arizona and Nevada retirement corridors.
Volume leadership rests with First-Time Buyers. Margin expansion tracks with Luxury Buyers.
Financing Option:
Capital source and underwriting standards filter which buyer segments can transact at specific price points and velocity.
- Conventional Loans:Privately originated mortgages meeting GSE conforming limits with standard down payment requirements. Credit box tightening has pushed marginal volume toward government-backed alternatives.
- FHA Loans:Federal Housing Administration-insured mortgages with elevated debt-to-income thresholds and reduced down payment minimums. Threshold expansions in high-cost counties are unlocking purchasing power for credit-constrained entrants.
- VA Loans:Department of Veterans Affairs guaranteed financing with zero-down provisions for eligible service members and veterans. Concentration tracks with military installation adjacency in Texas, North Carolina, and Colorado.
- Cash Purchases:Unleveraged acquisitions by investors, luxury buyers, and equity-rich sellers recycling proceeds. Institutional deployment into single-family rental aggregators is elevating cash share in entry-level tiers.
FHA Loans are expanding most quickly in high-cost submarkets. Cash Purchases retain dominance in investor-heavy corridors.
Sales Channel:
Transaction facilitation mechanisms are compressing search timelines and shifting commission economics across buyer demographics.
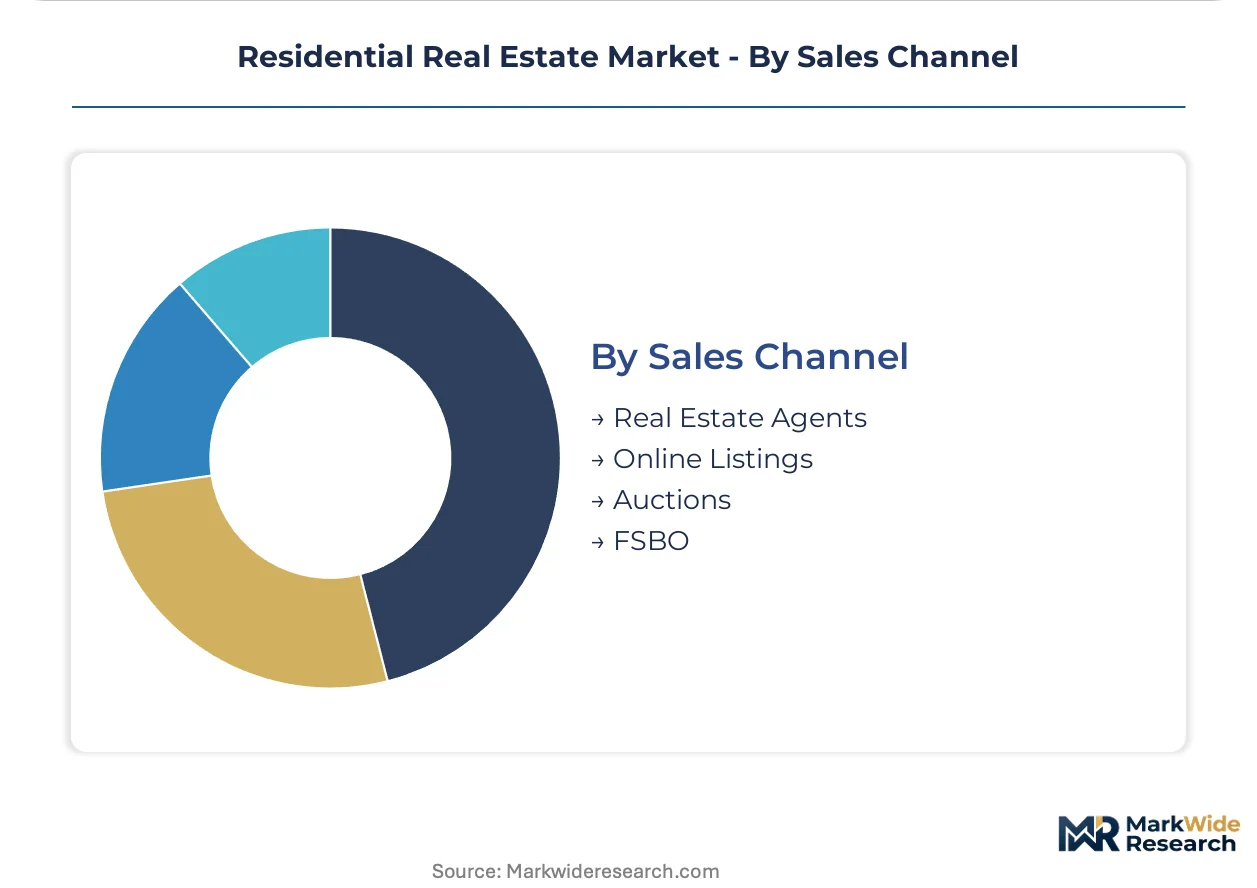
- Real Estate Agents:Licensed professionals providing listing exposure, negotiation representation, and closing coordination. Traditional commission structures face compression from alternative models.
- Online Listings:Digital platforms aggregating property data, virtual tours, and automated valuation outputs. First-time buyers in Sun Belt metros are adopting these tools at accelerating rates.
- Auctions:Accelerated sale mechanisms for distressed inventory, estate properties, and developer closeouts. Judicial foreclosure pipelines in Florida and Illinois sustain auction volume.
- FSBO:For-sale-by-owner transactions bypassing agent representation through flat-fee listing services or direct marketing. Adoption tracks with seller confidence in pricing accuracy and legal compliance.
Channel maturity centers on Real Estate Agents. Platform innovation is concentrating in Online Listings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity zones across Sun Belt metropolitan areas are channeling institutional capital into residential development corridors where tax-deferred reinvestment provisions accelerate project feasibility.
United States
Millennial household formation is compressing entry-level inventory in Austin, Phoenix, and Charlotte. The Federal Housing Administration's elevated conforming thresholds in high-cost counties unlock purchasing power for first-time buyers. Invitation Homes leverages institutional scale to control thousands of single-family rental units across fragmented Sun Belt metros.
Germany
Demographic compression in major urban centers sustains demand for multifamily rental stability. Vonovia SE anchors European exposure through its concentrated German portfolio concentrated in Berlin, Munich, and Hamburg. The country's rent brake regulations and energy efficiency mandates reshape redevelopment economics for legacy housing stock.
China
Urbanization tailwinds and policy-supported homebuyer incentives sustain transaction velocity in tier-one cities. China Vanke Co., Ltd operates as a leading developer across residential segments. The Yangtze River Delta and Pearl River Delta clusters concentrate new supply deployment where local governments experiment with purchase restriction relaxations.
United Arab Emirates
Expatriate residency reforms and golden visa programs are expanding addressable demand for luxury and mid-market units. Emaar Properties anchors development activity across Dubai's master-planned communities. The emirate's freehold ownership zones for foreign buyers differentiate regulatory treatment from regional peers.
United Kingdom
Housing supply deficits in Greater London and the Southeast sustain pricing pressure despite mortgage rate volatility. Help-to-Equity schemes and stamp duty adjustments filter first-time buyer access. Build-to-rent institutionalization is accelerating in Manchester and Birmingham where planning liberalization enables denser multifamily deployment.
Residential Real Estate Market Vendor Landscape
Top-tier vendors anchor institutional-scale portfolios across multiple metropolitan areas, while mid-tier specialists concentrate on single-region density or niche product formats. The vendor base stratifies across REITs with diversified multifamily exposure, single-family rental aggregators, and development-focused platforms. Three archetypes dominate: yield-stabilized rental operators, build-to-rent community developers, and luxury master-planned community creators. Competitive positioning depends on portfolio diversification across geographic corridors and capital structure optimization for interest rate sensitivity.
Among single-family rental aggregators, Invitation Homes exemplifies institutional-scale deployment across fragmented Sun Belt markets. Within multifamily REITs, AvalonBay Communities and Equity Residential occupy positions emphasizing coastal gateway exposure and urban infill density. Greystar Real Estate Partners represents the build-to-rent specialist archetype, competing directly with traditional for-sale housing through professionally managed single-family rental communities. Vonovia SE anchors European concentration through German multifamily dominance, while Emaar Properties exemplifies master-planned community development in high-growth emerging market corridors.
| Leading Market Players |
|---|
| Invitation Homes |
| AvalonBay Communities |
| Vonovia SE |
| Emaar Properties |
| Essex Property Trust |
| China Vanke Co., Ltd |
| Equity Residential |
| Tishman Speyer |
| Greystar Real Estate Partners |
| Others |
Supply Flow & Price Mechanics
Lumber futures volatility cascades through residential construction supply chains, compressing margins for wood-framed single-family production in southeastern states while elevating pricing tiers for concrete and steel alternatives in multi-family vertical development.
Pricing Analysis
Short lead-time premiums command pricing power for build-to-rent communities delivering immediate occupancy, while spot inventory of completed spec homes trades at modest discounts to absorb carrying costs. Three-tier pricing structure across premium custom builds, standard production homes, and economy entry-level inventory reflects material grade differentiation and lot location premiums. Cost compression in entry-level tiers is intensifying because FHA debt-to-income thresholds constrain buyer purchasing power. First-time buyers exhibit highest price sensitivity, while luxury cash purchasers demonstrate minimal elasticity.
Supply Chain Analysis
Reverse-logistics flows for appliance returns and fixture refurbishment create secondary supply channels that reduce new-material procurement for affordable housing developers and renovation specialists. Raw material dependencies center on Canadian softwood lumber, Chinese steel rebar, and Mexican ceramic tile imports. Geographic supply concentration rests on Canada, China, and Mexico for critical construction inputs. Single-source vulnerability in treated lumber from British Columbia exposes Sun Belt builders to tariff and trade policy disruption. Distribution runs through regional lumber yards, direct-from-mill procurement for large developers, and big-box retail channels for repair and remodeling segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Residential real estate is becoming a vertical-integration race where developers pursue captive land pipelines and in-house construction crews to control cost escalation and accelerate entitlement timelines.
For Market Incumbents: Deepen land banking positions in Austin and Phoenix entitlement pipelines before zoning liberalization windows close. Institutional single-family rental aggregators threaten traditional for-sale incumbents through algorithmic acquisition programs that waive contingencies. Backward integration into in-house framing and finishing crews mitigates skilled trade labor scarcity in Dallas-Fort Worth corridors. For New Entrants and Emerging Players: Launch via accessory dwelling unit development platforms in California and Oregon where state preemption laws override local prohibitions. The most penetrable white-space sits with infill townhome products satisfying FHA thresholds in supply-constrained Sun Belt metros. Go-to-market positioning should emphasize digital transaction infrastructure and accelerated closing timelines to attract millennial first-time buyers. For Investors and Strategic Acquirers: Distressed-cycle entries favor build-to-rent community developers in Phoenix and Charlotte where rental yield stability attracts institutional capital. Long-term viability over a five-to-ten-year window hinges on municipal zoning liberalization sustaining development feasibility. Monitor Federal Housing Administration loan limit adjustments as the critical inflection signal for entry-level buyer purchasing power expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Land Pipeline Accumulation | Captive lot supply in Austin and Phoenix insulates developers from raw land cost inflation. |
| Zoning Pre-Entitlement Investment | Early positioning in California ADU corridors secures development rights before municipal code amendments. |
| Build-to-Rent Platform Scale | Professional management infrastructure attracts yield-seeking institutional capital away from traditional multifamily. |
| Digital Transaction Integration | Automated valuation models and digital mortgage origination compress closing timelines for competitive advantage. |
| Skilled Trade Labor Captive | In-house framing and finishing crews in Phoenix and Dallas-Fort Worth reduce schedule risk and hard cost volatility. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this residential real estate analysis. Primary interviews with land acquisition directors, municipal planning officials, mortgage underwriting executives, and single-family rental portfolio managers combined with bottom-up transaction database triangulation. Secondary sources included National Association of Realtors transaction reports, Census Bureau building permit filings, FHA endorsement data, and lumber futures exchange records.
Granularity-level modeling operated at metropolitan statistical area resolution for supply-demand balances, with property type and buyer segment dimensions disaggregated within each geography. CAGRs derived from rolling average construction cost indices, household formation demographics, and financing accessibility trends across the projection horizon. Forecast inputs incorporated interest rate trajectory assumptions, municipal zoning reform timelines, and institutional capital deployment patterns into rental aggregation platforms.
The model assumes a particular technology adoption path for modular construction and virtual design tools; alternative pathways for factory-built housing penetration would alter the outlook for traditional stick-built production timelines. Practitioners should monitor Federal Reserve policy shifts, state-level ADU legislation, and skilled trade apprenticeship graduation rates for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
Spain Residential Real Estate Market
Residential Real Estate Market
Singapore Real Estate Market
Residential Real Estate Market
Germany Residential Real Estate Market
Residential Real Estate Market
South Africa Residential Real Estate Market
Residential Real Estate Market
Canada E-House Market
Residential Real Estate Market
North America Tiny Homes Market
Residential Real Estate Market
Global Manufactured Housing Market
Residential Real Estate Market
Indonesia Residential Real Estate Market
Residential Real Estate Market
Turkey Residential Real Estate Market
Residential Real Estate Market
India Residential Construction Market
Residential Real Estate Market
Japan Manufactured Homes Market
Residential Real Estate Market
Bahrain Senior Living Market
Residential Real Estate Market
United States Manufactured Homes Market
Residential Real Estate Market
Malaysia Real Estate Market
Residential Real Estate Market
Online Home Rental Market
Residential Real Estate Market
Indonesia Real Estate Market