
 Luxembourg Facility Management Market | 2026-2036
Luxembourg Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Luxembourg Facility Management Market Foresight
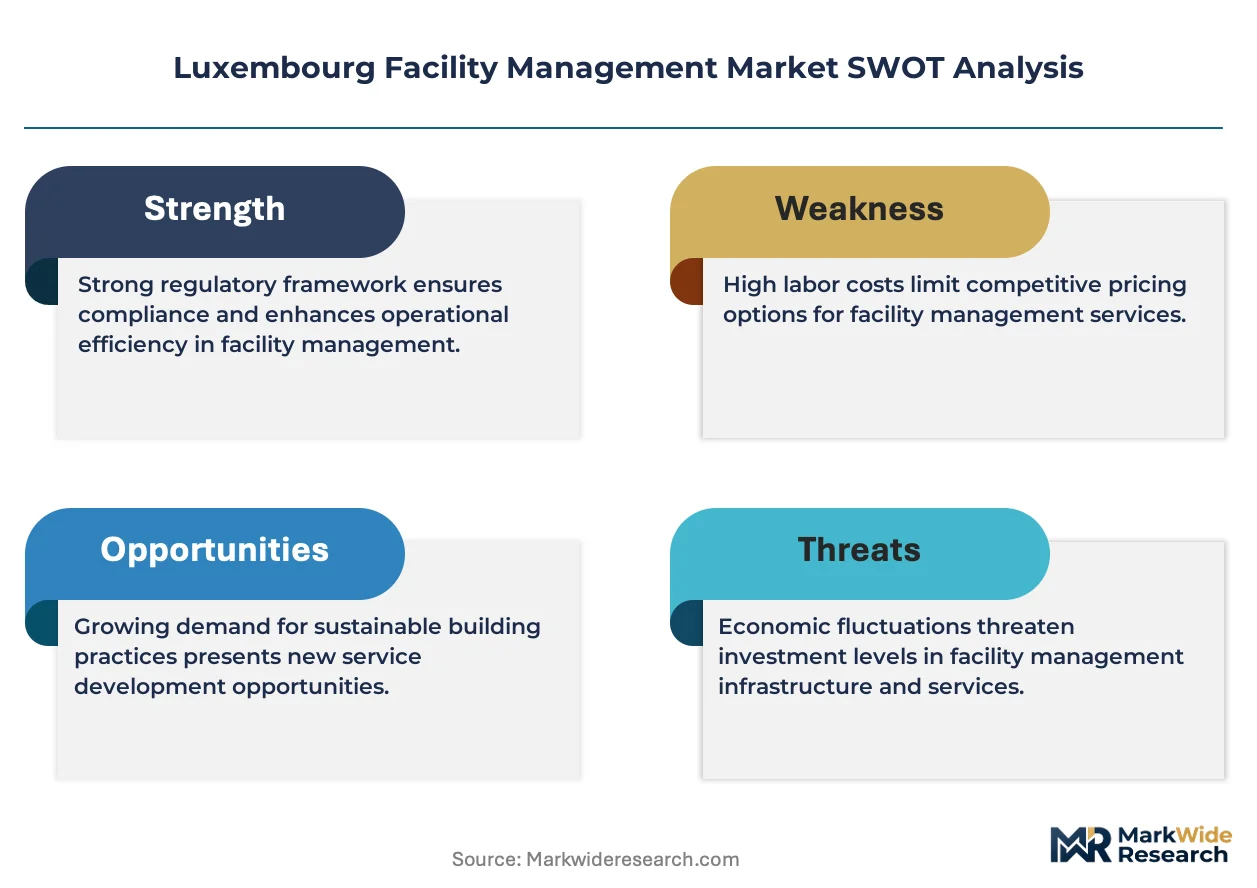
The gap between premium integrated facility services and commodity cleaning contracts is realigning competitive strategy across Luxembourg. CBRE Luxembourg leverages its cross-border platform to anchor large banking campus contracts in Kirchberg. ISS Luxembourg competes through bundled service density, while Sodexo differentiates via workplace experience technology embedded in government and healthcare estates.
Facility management encompasses the operational coordination of buildings, infrastructure, and support services through planned maintenance, cleaning protocols, security systems, and space utilization software to ensure safe, efficient, and compliant working environments. Hard maintenance and energy management command margin premiums as building automation retrofits accelerate under tightening efficiency codes. Soft services like cleaning and security remain volume-driven with hybrid contract structures gaining traction among cost-conscious commercial end users.
Luxembourg's national energy efficiency obligations and the EU Green Deal's building renovation targets shape procurement criteria for public and private portfolios alike. The country's financial regulator and EU taxonomy alignment requirements push institutional investors to demand certified sustainable facility operations. Stakeholders must weigh captive in-house capabilities against outsourced technology platforms as workplace occupancy patterns reset permanently.
Market Dynamics
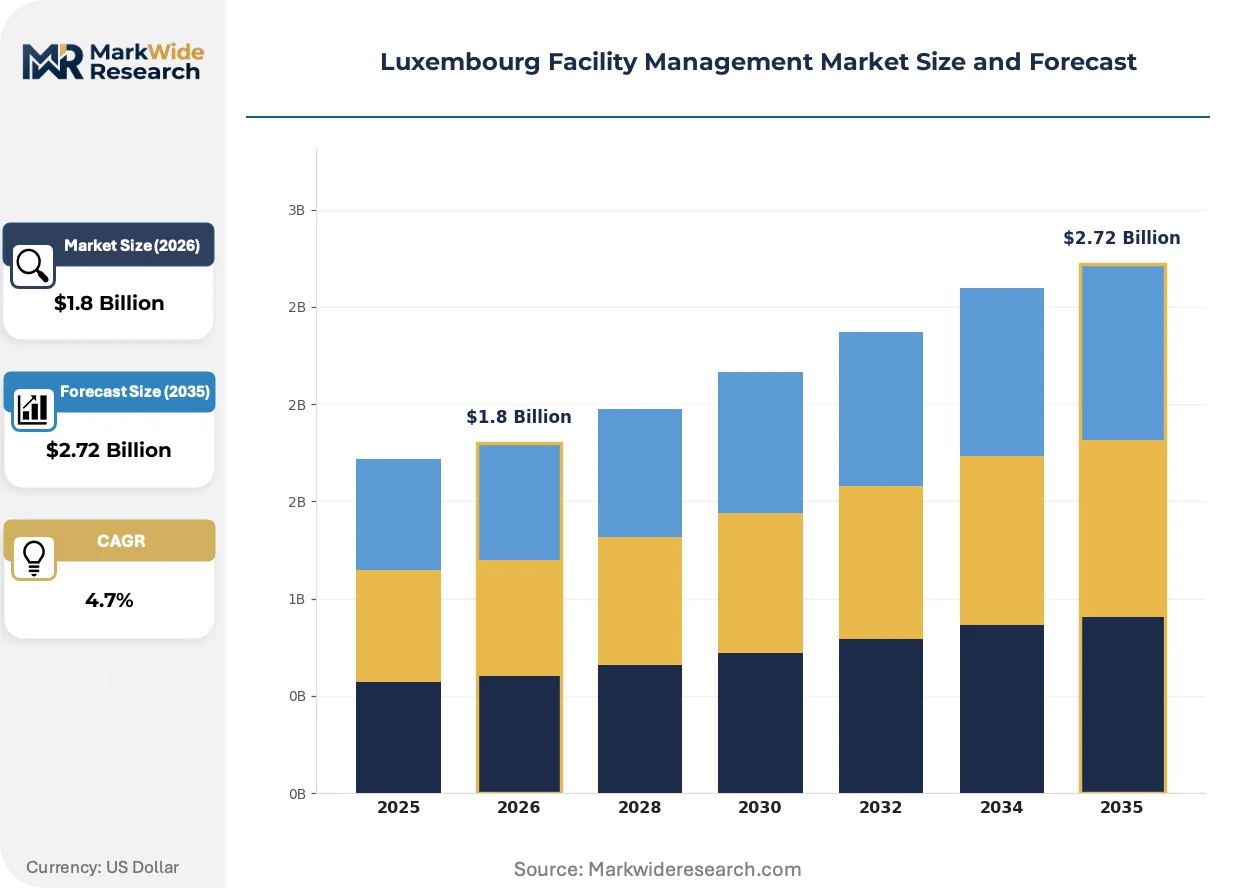
EU Green Deal building renovation targets and Luxembourg's national energy efficiency obligations are compressing maintenance cycles while elevating certified sustainable operations as a procurement gatekeeper across institutional portfolios.
Growth Catalysts
- EU Green Deal renovation mandates:Binding building performance standards accelerate retrofit demand across aging commercial stock in Luxembourg City and Esch-sur-Alzette.
- Banking sector outsourcing:Financial services institutions in Kirchberg drive integrated workplace management contracts as core operations.
- Building automation retrofits:Smart HVAC and energy management systems penetrate mid-market commercial estates under tightening efficiency codes.
Market Restraints
- Skilled technician scarcity:Certified building automation specialists concentrate in Greater Luxembourg, constraining service expansion.
- Energy input cost volatility:Natural gas and electricity price swings compress margins on fixed-price maintenance contracts.
- EU taxonomy alignment friction:Institutional investors demand verified sustainable operations that smaller service providers struggle to document.
Strategic Opportunities
- Healthcare estate digitization:Hospital and eldercare facilities adopt predictive maintenance platforms for critical infrastructure.
- Public sector bundled contracts:Government procurement frameworks favor single-source integrated facility services over fragmented vendor panels.
- Cross-border service platforms:Providers leverage proximity to Belgium, France, and Germany for shared service centers and talent pools.
Industry Challenges
- Workplace occupancy pattern reset:Hybrid work models destabilize space utilization forecasting and cleaning frequency optimization.
- Legacy system integration complexity:Proprietary building management systems from the 2000s resist API connectivity with modern IoT platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxembourg Facility Management Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Security, Maintenance, Space Management End User: Commercial, Residential, Industrial, Government Technology: Building Automation, Integrated Workplace Management, IoT Solutions, Energy Management Contract Type: Outsourced, In-House, Hybrid, Short-Term |
| Companies Covered | CBRE Luxembourg, Cushman & Wakefield, ISS Luxembourg, Apleona, Dussmann Service SRL, Sodexo, Samsic Luxembourg, Vinci Facilities, Atalian Global Services Luxembourg, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxembourg Facility Management Market Shifts & Advancements
Digital twin technology and outcome-based service models are restructuring how facility operators deliver and price maintenance, cleaning, and energy management across Luxembourg's concentrated commercial estate market.
Digital twin platforms replicate building infrastructure in real-time virtual environments to simulate energy performance and predict equipment failure. Large banking campuses in Kirchberg deploy these systems to optimize HVAC runtime and space conditioning. The technology is expanding into mid-size commercial properties as cloud deployment costs compress.
Luxembourg's transposition of the EU Energy Performance of Buildings Directive mandates operational energy disclosure for commercial structures over 1000 square meters. Property owners now face penalties for non-compliance with renovation roadmaps. Hard maintenance providers capture premium margins by bundling efficiency certification into service contracts.
Corporate real estate teams increasingly unbundle long-term integrated contracts into modular service components with shorter renewal cycles. Cost-conscious tenants in Luxembourg City's Weickerseck district favor spot purchasing for cleaning and security while retaining strategic control of energy management. This pattern concentrates in financial services verticals where workplace strategy teams negotiate directly with point solution vendors.
Luxembourg Facility Management Market Segmentation
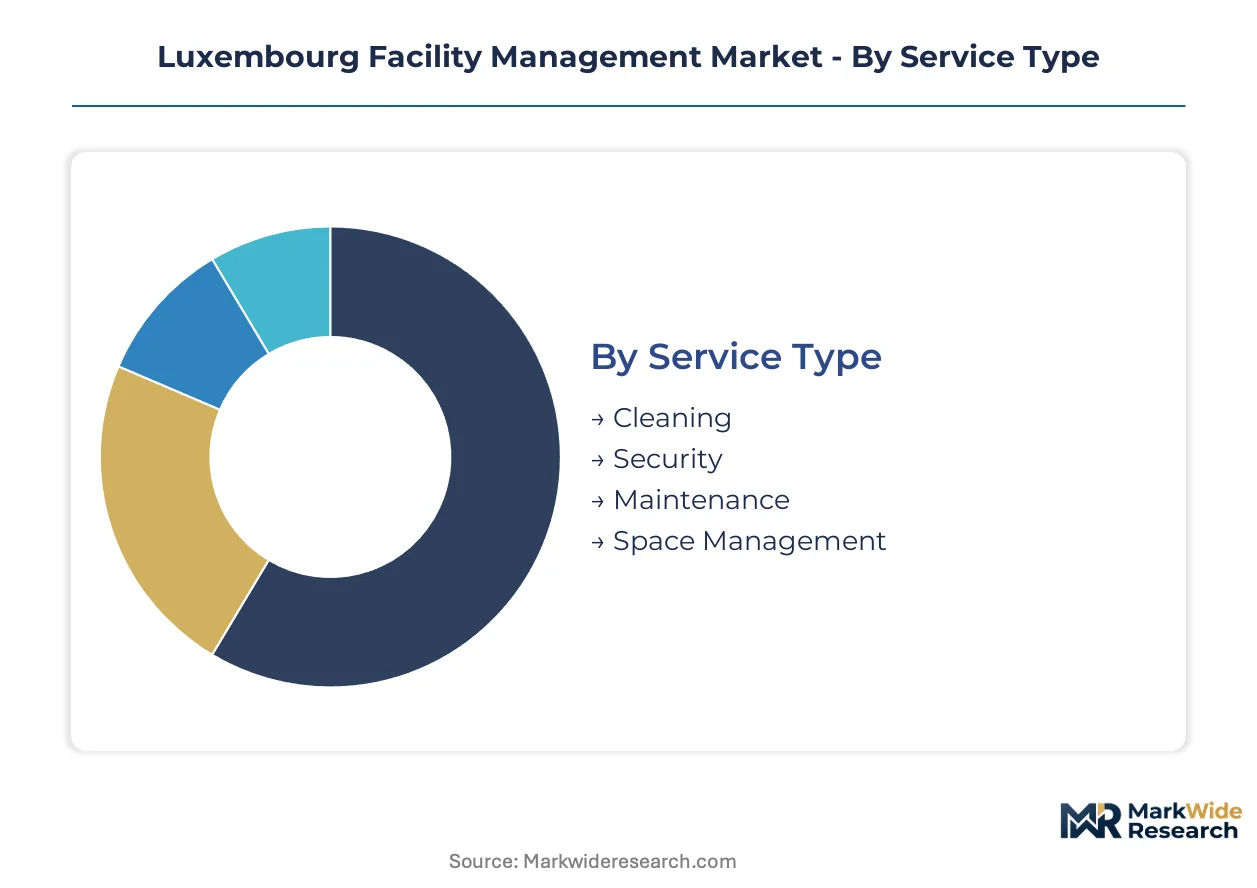
Service configuration and contract architecture determine competitive positioning across Luxembourg's concentrated commercial estate market. Procurement patterns diverge sharply between financial services campuses requiring integrated platforms and fragmented retail portfolios optimizing spot purchasing.
Service Type:
Buyer sophistication separates premium integrated contracts from commodity procurement in Luxembourg's service landscape.
- Maintenance:Hard maintenance encompasses HVAC, electrical, and mechanical systems repair with predictive scheduling protocols. Banking campuses in Kirchberg and government estates in Luxembourg City drive demand for certified technicians under tightening EU Green Deal efficiency codes.
- Cleaning:Soft service operations span daily janitorial, specialized sanitization, and periodic deep-cleaning protocols. Hybrid work patterns in Weickerseck commercial buildings destabilize frequency optimization and contract structuring.
- Security:Physical guarding, access control systems, and surveillance monitoring protect institutional portfolios. Demand concentrates in financial services verticals with regulatory compliance requirements.
- Space Management:Workplace planning, occupancy analytics, and furniture asset coordination optimize utilization rates. Corporate real estate teams in Esch-sur-Alzette adopt these services as hybrid models reset footprint requirements.
Volume sits with Cleaning; growth tilts toward Maintenance.
End User:
Portfolio scale and regulatory exposure shape service bundling decisions across customer types.
- Commercial:Office buildings, retail centers, and hospitality properties constitute the dominant demand base. Financial services institutions in Kirchberg anchor integrated workplace management contracts with multi-year terms.
- Government:Public administration buildings, military installations, and civic infrastructure require compliance with national procurement frameworks. Bundled single-source contracts are displacing fragmented vendor panels under EU public procurement directives.
- Industrial:Manufacturing facilities, logistics warehouses, and utility infrastructure demand specialized hard maintenance. Esch-sur-Alzette's industrial corridor generates concentrated demand for energy management integration.
- Residential:Multi-unit housing complexes, condominiums, and senior living facilities purchase cleaning and security services. Cost sensitivity drives shorter contract cycles and spot purchasing patterns.
Commercial captures dominant volume; Government represents the steepest expansion trajectory under public sector modernization programs.
Technology:
Digital maturity separates technology-forward estates from legacy-dependent portfolios in procurement decisions.
- Building Automation:Smart HVAC, lighting controls, and access systems integrate through centralized management platforms. Mid-market commercial properties accelerate adoption as cloud deployment costs compress and EU efficiency codes tighten.
- Energy Management:Consumption monitoring, demand response systems, and carbon accounting tools track operational performance. Institutional investors demand these capabilities for EU taxonomy alignment and sustainability certification.
- Integrated Workplace Management:IWMS platforms unify space planning, maintenance scheduling, and vendor coordination through single dashboards. Large banking campuses deploy these systems for cross-border portfolio standardization.
- IoT Solutions:Sensor networks for occupancy detection, air quality monitoring, and predictive equipment diagnostics generate real-time operational data. Healthcare estates in Luxembourg adopt these for critical infrastructure reliability.
Building Automation holds installed base dominance; Energy Management gains share fastest under regulatory disclosure mandates.
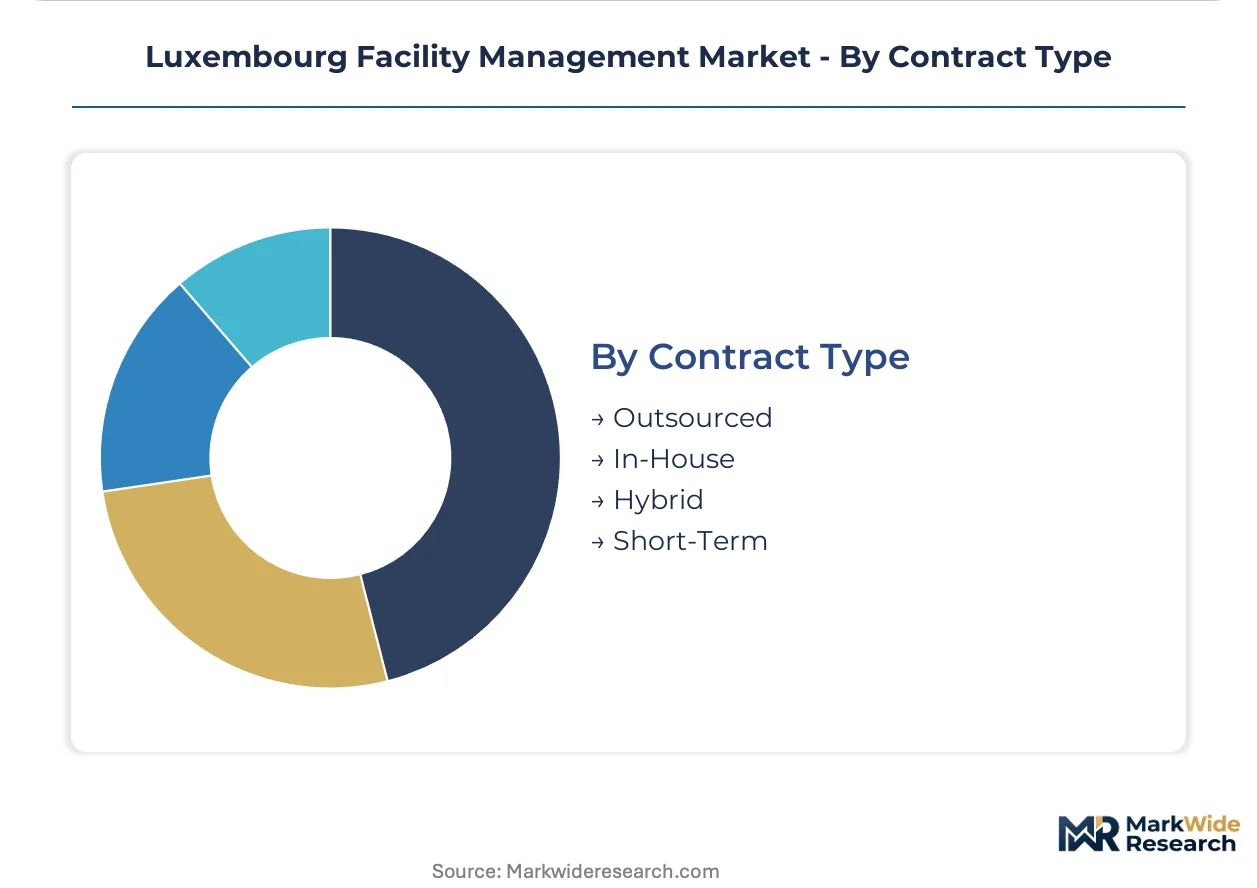
Contract Type:
Risk allocation preferences and internal capability assessments determine sourcing architecture.
- Outsourced:Third-party providers deliver complete service portfolios under multi-year agreements with performance metrics. Financial services institutions favor this model for non-core operational functions.
- Hybrid:Strategic control of energy management and space planning combines with outsourced cleaning and security execution. Cost-conscious tenants in Luxembourg City's commercial district favor this modular approach.
- In-House:Captive teams execute maintenance and facilities operations with direct employment structures. Public sector estates maintain these capabilities for critical infrastructure security.
- Short-Term:Spot contracts, project-based engagements, and trial arrangements test provider capabilities before commitment. Retail and hospitality verticals use these for seasonal demand fluctuation.
Outsourced commands revenue concentration; Hybrid expands most quickly as corporate real estate teams unbundle long-term integrated agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kirchberg anchors Luxembourg's facility management demand through its dense concentration of banking campuses and EU institutional headquarters. The district's premium commercial stock drives integrated workplace management contracts with multi-year terms. Service providers cluster here to capture cross-border portfolio standardization opportunities.
Luxembourg City
Financial services institutions and government estates dominate procurement in the capital district. The EU Green Deal's building renovation targets compress maintenance cycles for aging commercial stock. Weickerseck commercial buildings show rising adoption of hybrid contract structures as corporate real estate teams unbundle integrated agreements.
Esch-sur-Alzette
Industrial facilities and logistics warehouses generate concentrated demand for energy management integration. The country's national energy efficiency obligations push retrofit activity across manufacturing corridors. Mid-market commercial properties here accelerate building automation adoption as cloud deployment costs compress.
Belgium (Cross-Border)
Service providers leverage proximity to Belgium for shared service centers and talent pools. Belgian regulatory frameworks on energy performance influence cross-border contract structuring. The Arlon corridor serves as a staging point for technician deployment into southern Luxembourg estates.
France (Cross-Border)
Metz and Thionville supply certified building automation specialists to Greater Luxembourg. French technical training programs feed skilled labor into Luxembourg's constrained technician market. Cross-border procurement frameworks allow French providers to compete for public sector bundled contracts.
Germany (Cross-Border)
Saarland-based engineering firms supply predictive maintenance platforms to Luxembourg healthcare estates. German industrial standards on HVAC efficiency shape procurement criteria for institutional investors. The Trier-Saarbrücken axis enables rapid response capacity for critical infrastructure contracts.
Luxembourg Facility Management Market Competitive Landscape
Premium-margin players sit above commodity-margin players across service bundling intensity and technology integration depth. The market structures around three tiers: integrated platform providers anchoring large banking contracts, bundled service specialists capturing government and healthcare estates, and point-solution vendors competing on spot cleaning and security purchasing. Cross-border platform leverage and outcome-based pricing models represent the dominant competitive moves reshaping contract architecture.
Within the integrated platform tier, CBRE Luxembourg and ISS Luxembourg exemplify archetypes of cross-border scale deployment versus bundled service density concentration. Sodexo occupies a position emphasizing workplace experience technology embedded in government and healthcare verticals. These three anchors represent divergent strategic postures: real estate services extension, multi-service execution scale, and experience-centric differentiation.
| Leading Market Players |
|---|
| CBRE Luxembourg |
| Cushman & Wakefield |
| ISS Luxembourg |
| Apleona |
| Dussmann Service SRL |
| Sodexo |
| Samsic Luxembourg |
| Vinci Facilities |
| Atalian Global Services Luxembourg |
| Others |
Supply & Pricing Matrix
Banking campuses in Kirchberg anchor value-based pricing through outcome-linked maintenance contracts tied to energy performance guarantees. Procurement concentration among EU institutional headquarters and financial services estates compresses margin negotiation leverage for mid-tier providers.
Pricing Analysis
Outcome-based pricing tied to building energy performance certifications commands premium positioning across Luxembourg's institutional portfolio market. Three-tier pricing structure across integrated platform, bundled service, and point-solution levels differentiates contracts by technology depth and compliance documentation burden. Cost compression in commodity cleaning and security segments intensifies as hybrid work patterns reduce frequency requirements and spot purchasing expands. Retail and hospitality verticals exhibit highest price sensitivity, while banking and government estates prioritize certified sustainable operations over unit cost.
Supply Chain Analysis
Regional distribution centers in Belgium's Arlon corridor and France's Metz-Thionville axis feed technician deployment networks into Greater Luxembourg estates. Skilled labor supply draws from French technical training programs and German engineering standards, with building automation components sourcing from German industrial suppliers and Dutch HVAC manufacturers. Single-source vulnerability concentrates in certified building automation specialist pools. Distribution runs through cross-border hub-and-spoke patterns with same-day response capacity for critical infrastructure contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Luxembourg's facility management market operates as a cost-of-compliance arena where EU Green Deal building renovation mandates and national energy efficiency obligations erect certification barriers that favor capitalized incumbents over fragmented local operators.
For Market Incumbents: To counter technician scarcity constraining service expansion, anchor cross-border talent pipelines through Belgian and French training partnerships while hardening margin position via backward integration into energy management technology platforms. Deepen compliance documentation capabilities to capture EU taxonomy-aligned institutional procurement. For New Entrants and Emerging Players: EU Green Deal renovation mandates in Luxembourg open a window for specialized retrofit consultancies targeting mid-market commercial estates in Esch-sur-Alzette's industrial corridor. Penetrate through predictive maintenance platform offerings for healthcare estates, leveraging SaaS deployment models to bypass capital-intensive integrated service infrastructure. For Investors and Strategic Acquirers: The window for entry favors technology-enabled service platforms with certified sustainability operations over pure-play staffing models. Monitor building automation retrofit penetration rates in mid-market commercial properties as the inflection signal for platform consolidation timing. Long-term viability hinges on regulatory compliance moats deepening through successive EU efficiency code tightening cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Border Talent Platform | Belgian and French technician pipelines address skilled labor scarcity in Greater Luxembourg. |
| Energy Certification Bundling | EU taxonomy alignment documentation captures institutional investor procurement criteria. |
| Predictive Maintenance Platform | IoT-enabled diagnostics penetrate healthcare estates requiring critical infrastructure reliability. |
| Modular Service Unbundling | Hybrid contract structures respond to corporate real estate cost optimization mandates. |
| Building Automation Retrofit | Smart HVAC integration addresses EU Green Deal efficiency disclosure requirements. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with facility management directors, corporate real estate executives, public procurement officers, and building automation engineers. Bottom-up service provider revenue estimates triangulated against top-down commercial estate stock assessments and energy efficiency obligation implementation timelines. Secondary sources included EU Energy Performance of Buildings Directive transposition documents, Luxembourg national energy agency reports, and cross-border labor market statistics from Belgian and French regional employment authorities.
Segment-level modeling operated at service type, end user vertical, contract architecture, and technology deployment dimensions across the analysis window. CAGRs derived from regression analysis against commercial construction permitting data, banking sector employment trends, and public sector modernization program announcements. Forecast inputs incorporated EU Green Deal renovation target trajectories, building automation cost compression curves, and hybrid workplace occupancy pattern stabilization assumptions.
The model assumes a particular technology adoption path; alternative pathways for digital twin platform deployment would alter the outlook for predictive maintenance service penetration. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and cross-border labor mobility. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Middle East and Africa Hard Facility Management Market
Facility Management
UK Facility Management Market
Facility Management
Ireland Facility Management Market
Facility Management
Soft Facility Management Market
Facility Management
Europe Hard Facility Management Market
Facility Management
Asia-Pacific Hard Facility Management Market
Facility Management
Bulgaria Facility Management Market
Facility Management
Europe Soft Facility Management Market
Facility Management
Brazil Facility Management Market
Facility Management
Panama Facility Management Market
Facility Management
Qatar Facility Management Market
Facility Management
Mexico Facility Management Market
Facility Management
Refrigerated Warehousing Market
Facility Management
Spain Facility Management Market
Facility Management
India Facility Management Market
Facility Management
Singapore Facility Management Market