
 South Korea Office Real Estate Market | 2026-2036
South Korea Office Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Office Real Estate Market Analytics
Capital-intensity divergence between institutional landlords and mid-tier developers is collapsing as green retrofit mandates raise baseline compliance costs. Samsung C&T Corporation leverages its engineering consortium to self-deliver smart building infrastructure across mixed-use towers. IGIS Asset Management anchors portfolio resilience through concentrated Grade A exposure in Seoul's Gangnam Business District. Hanwha Real Estate differentiates via integrated solar facade systems that reduce operational carbon intensity.
South Korea Office Real Estate comprises commercial structures designed for professional services occupancy, typically featuring floor plates exceeding 1,500 square meters, raised floor systems for cable management, and centralized HVAC with particulate filtration. These assets serve as operational headquarters for knowledge-intensive industries requiring proximity to transit, talent pools, and financial infrastructure. Grade A Office commands premium lease spreads due to scarcity of LEED- or WELL-certified stock in prime Seoul submarkets. Co-working Space and Serviced Office segments are expanding fastest among venture-backed startups and foreign market entrants seeking flexible tenure. Full Service Lease structures dominate institutional tenant relationships, though Short-term Lease penetration rises among technology sector occupiers prioritizing agility.
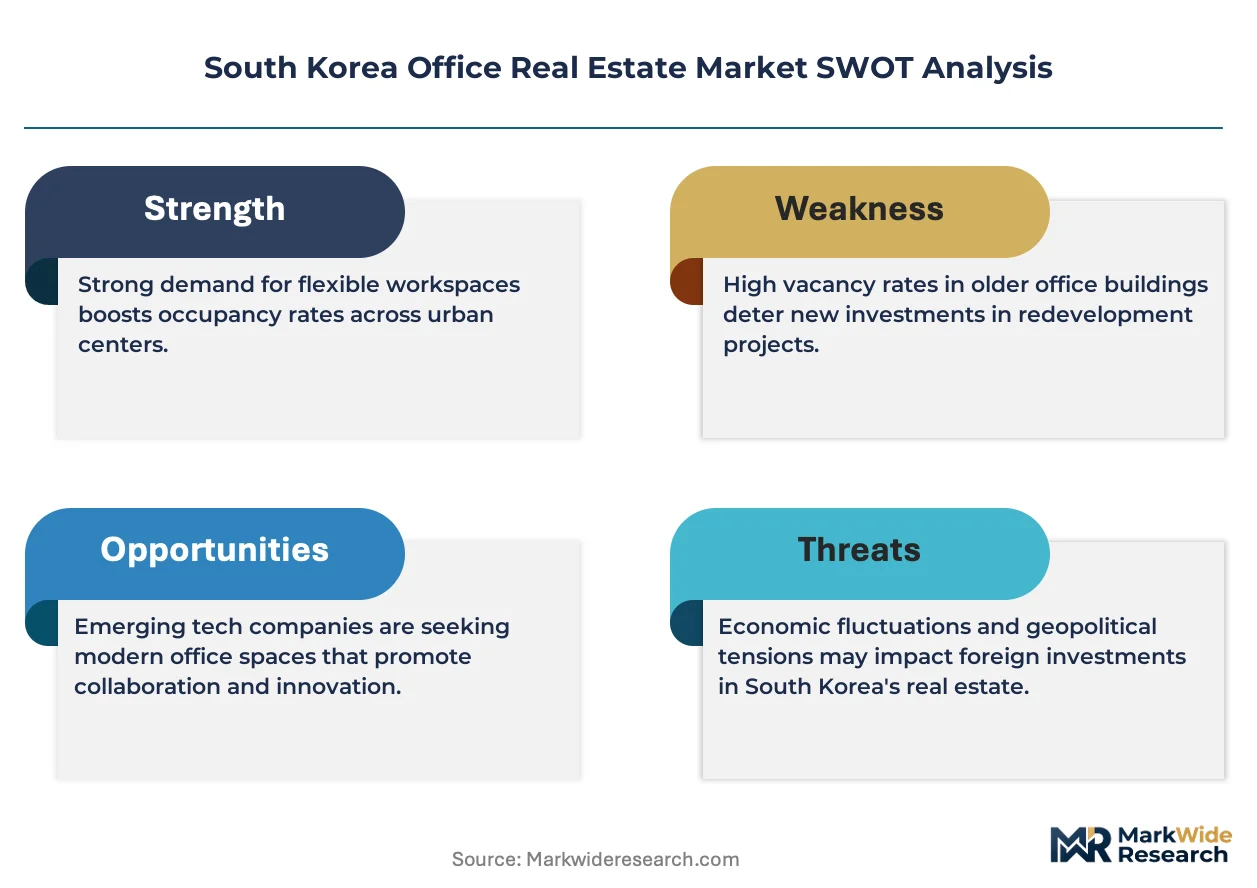
MFDS guidelines on indoor air quality and MFDS-aligned wellness standards shape landlord improvement specifications for pharmaceutical and biotech tenants. Seoul Metropolitan Government building energy codes and national Green Building Certification standards restrict redevelopment economics for pre-2010 stock, filtering speculative supply. Stakeholders must weigh regulatory compliance timelines against tenant preference for hybrid-ready floor plans and wellness amenities.
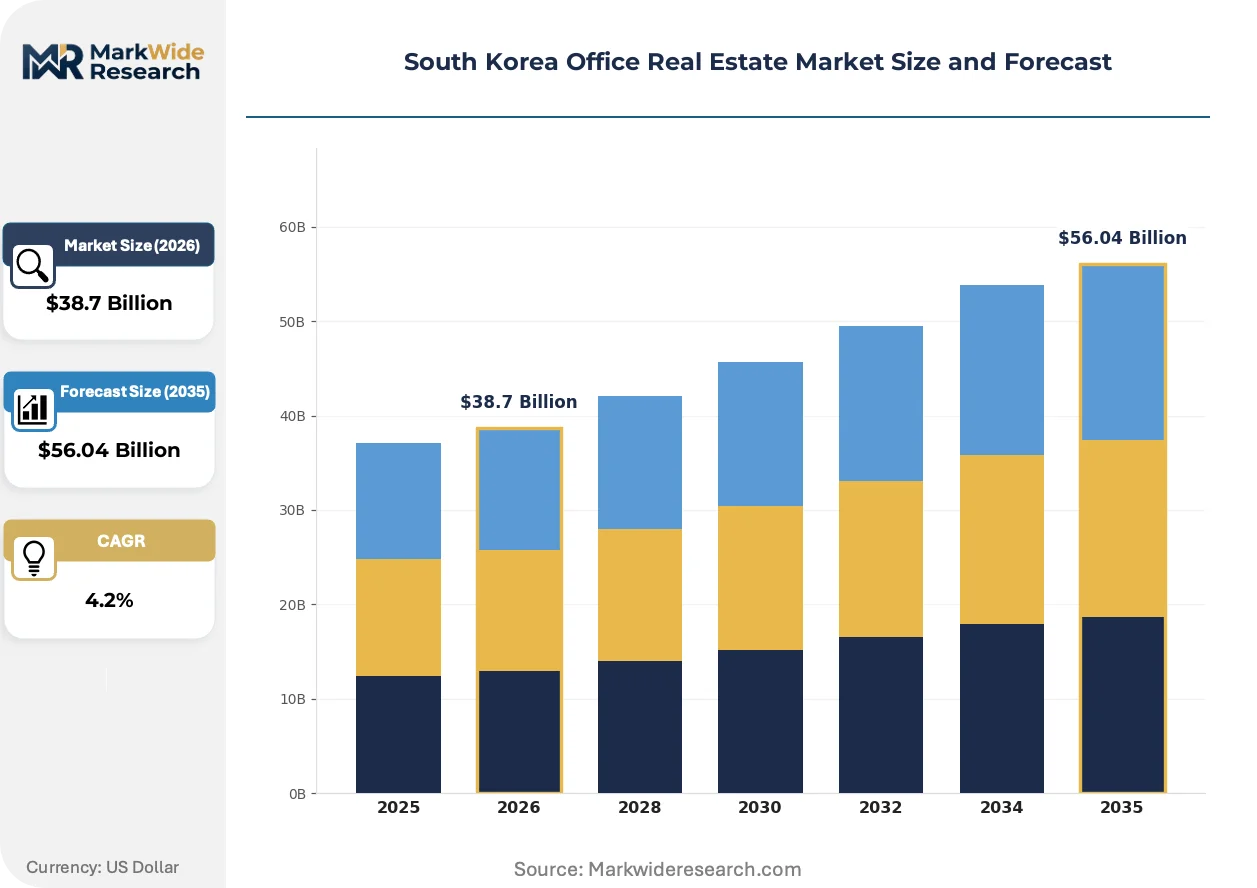
Market Dynamics
Green building certification mandates from Seoul Metropolitan Government are compressing redevelopment timelines for pre-2010 office stock while technology tenants demand flexible, wellness-aligned workspace configurations.
Growth Catalysts
- MFDS Indoor Air Quality Guidelines:Pharmaceutical and biotech tenants now require MFDS-aligned filtration systems, expanding landlord improvement specifications and lease premiums for compliant buildings.
- Technology Sector Footprint Expansion:Venture-backed startups and platform enterprises are scaling co-working and serviced office requirements in Seoul's Gangnam and Yeouido corridors.
- Smart HVAC Retrofit Mandates:National Green Building Certification standards are accelerating capital deployment into sensor-based climate systems that reduce operational carbon intensity.
Market Restraints
- Green Compliance Cost Escalation:Baseline retrofit expenses for pre-2010 stock have risen sharply as Seoul energy codes tighten envelope and mechanical specifications.
- Prime Submarket Supply Concentration:Scarcity of LEED- or WELL-certified Grade A inventory in Gangnam Business District and Yeouido Business District limits tenant choice and inflates lease spreads.
- Land Assembly Friction:Fragmented ownership patterns in established Seoul office corridors complicate site aggregation for institutional-scale redevelopment.
Strategic Opportunities
- Busan Haeundae Secondary Node:Port-city logistics and maritime finance tenants are creating demand for Grade A office outside Seoul's dominant submarkets.
- Integrated Solar Facade Systems:Building-integrated photovoltaics are opening new revenue streams through net-metering arrangements and green lease structures.
- Hybrid-Ready Floor Plan Innovation:Short-term lease structures and modular interior systems cater to technology occupiers prioritizing agility over tenure security.
Industry Challenges
- Smart Building Integration Complexity:Retrofitting legacy mechanical systems with IoT-enabled controls requires specialized commissioning expertise that remains scarce in the domestic contractor base.
- Wellness Certification Timeline Compression:WELL and Fitwel pursuit cycles now overlap with tenant fit-out schedules, compressing landlord delivery obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Office Real Estate Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $56.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Grade A Office, Grade B Office, Serviced Office, Co-working Space, Business Center Lease Structure: Full Service Lease, Net Lease, Modified Gross Lease, Gross Lease, Short-term Lease Tenant Industry: Information Technology, Financial Services, Legal Firms, Media & Entertainment, Consulting Firms Investment Type: Direct Acquisition, Real Estate Investment Trusts, Joint Ventures, Private Equity Funds, Sale-Leaseback |
| Companies Covered | Brookfield Asset Management, CBRE, IGIS Asset Management, Hanwha Real Estate, Jones Lang LaSalle IP, Inc., Samsung C&T Corporation, Hines, Lotte Property & Development, SK D&D Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Office Real Estate Market Evolving Landscape
Building intelligence systems and wellness certification protocols are restructuring how office assets compete for tenant commitment and capital allocation across South Korea's major business districts.
Digital twin platforms are decomposing traditional facilities management by creating real-time building performance simulations. Institutional landlords in Seoul's Gangnam corridor are deploying these systems to optimize energy load and predictive maintenance. The technology is decomposing the landlord-tenant information asymmetry that previously obscured true operating cost exposures.
Seoul Metropolitan Government's building energy codes now mandate disclosure of operational carbon intensity for commercial structures exceeding specified floor areas. This regulatory pressure is filtering speculative supply by rendering marginal pre-2010 redevelopment projects economically unviable. Grade A assets with existing green certifications command disproportionate tenant preference as compliance risk migrates down-market.
Tenants are unbundling full-service lease commitments into component procurement decisions. Technology sector occupiers now separately negotiate base building terms, interior fit-out allowances, and amenity access, treating each as distinct purchasing events. This pattern concentrates in venture-backed startups seeking to preserve capital flexibility during scaling phases.
South Korea Office Real Estate Market Segmentation
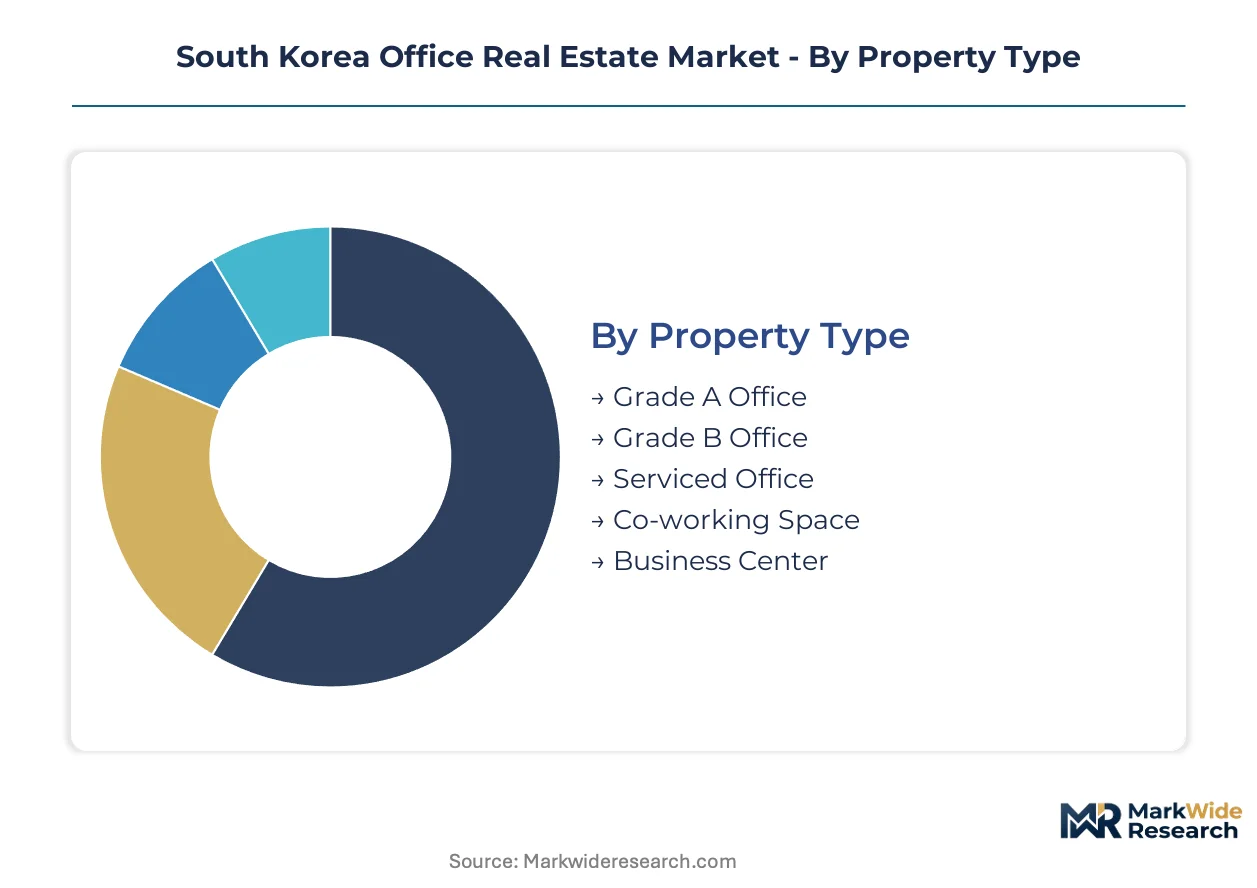
Segmentation reveals how capital allocation and tenant procurement patterns diverge across South Korea's office stock. Each dimension exposes distinct risk-return profiles and regulatory exposure that shape institutional strategy.
Property Type:
Co-working and serviced formats exert substitution pressure on traditional lease structures, compressing demand for secondary-grade assets while elevating premium stock scarcity.
- Grade A Office:Premium structures exceeding 1,500 square meter floor plates with raised flooring and centralized HVAC filtration. Seoul's Gangnam Business District and Yeouido Business District concentrate demand from financial and technology tenants seeking MFDS-aligned wellness certifications and LEED credentials.
- Co-working Space:Flexible membership models with modular interior systems and short-term tenure structures. Venture-backed startups in Seoul's Gangnam corridor drive expansion, prioritizing capital agility over lease security during scaling phases.
- Grade B Office:Mid-tier assets lacking modern mechanical specifications or green certification.
- Serviced Office:Turnkey executive suites with bundled reception and IT infrastructure.
- Business Center:Hybrid facilities combining meeting rooms, virtual office services, and limited dedicated space.
Grade A Office retains volume leadership; Co-working Space holds the steepest expansion curve.
Lease Structure:
Cost tier stratification separates institutional-grade commitments from agility-oriented alternatives, with technology sector procurement driving divergence at the margin.
- Full Service Lease:Landlord-assumed operating expenses including utilities, maintenance, and property management. Financial services and legal firms in Seoul's Yeouido Business District favor this structure for budget predictability and compliance accountability.
- Short-term Lease:Tenure periods under 36 months with minimal tenant improvement allowances. Platform enterprises and foreign market entrants prioritize this format to preserve strategic flexibility amid regulatory uncertainty.
- Net Lease:Tenant responsibility for property taxes, insurance, and maintenance costs.
- Modified Gross Lease:Hybrid cost-sharing with expense stop provisions.
- Gross Lease:All-inclusive rent with landlord absorbing operational volatility.
Full Service Lease dominates institutional relationships; Short-term Lease is gaining share fastest among technology occupiers.
Tenant Industry:
Application-specific requirements fragment demand, with biotech and fintech procurement standards diverging sharply from traditional professional services.
- Information Technology:Platform companies and venture-backed enterprises requiring hybrid-ready floor plans, high-density power, and redundant connectivity. Seoul Metropolitan Government smart building codes and flexible tenure preferences reshape landlord specifications for this cohort.
- Financial Services:Banks, asset managers, and insurers demanding secure data infrastructure and proximity to transit and regulatory bodies. Yeouido Business District concentration reflects this segment's infrastructure requirements.
- Legal Firms:Partnership structures with stable headcounts and traditional full-service lease preferences.
- Media & Entertainment:Content production and creative agencies with variable space needs and acoustic specifications.
- Consulting Firms:Project-based staffing models driving fluctuating footprint requirements.
Financial Services anchors lease volume; Information Technology shows the most rapid demand trajectory shift.
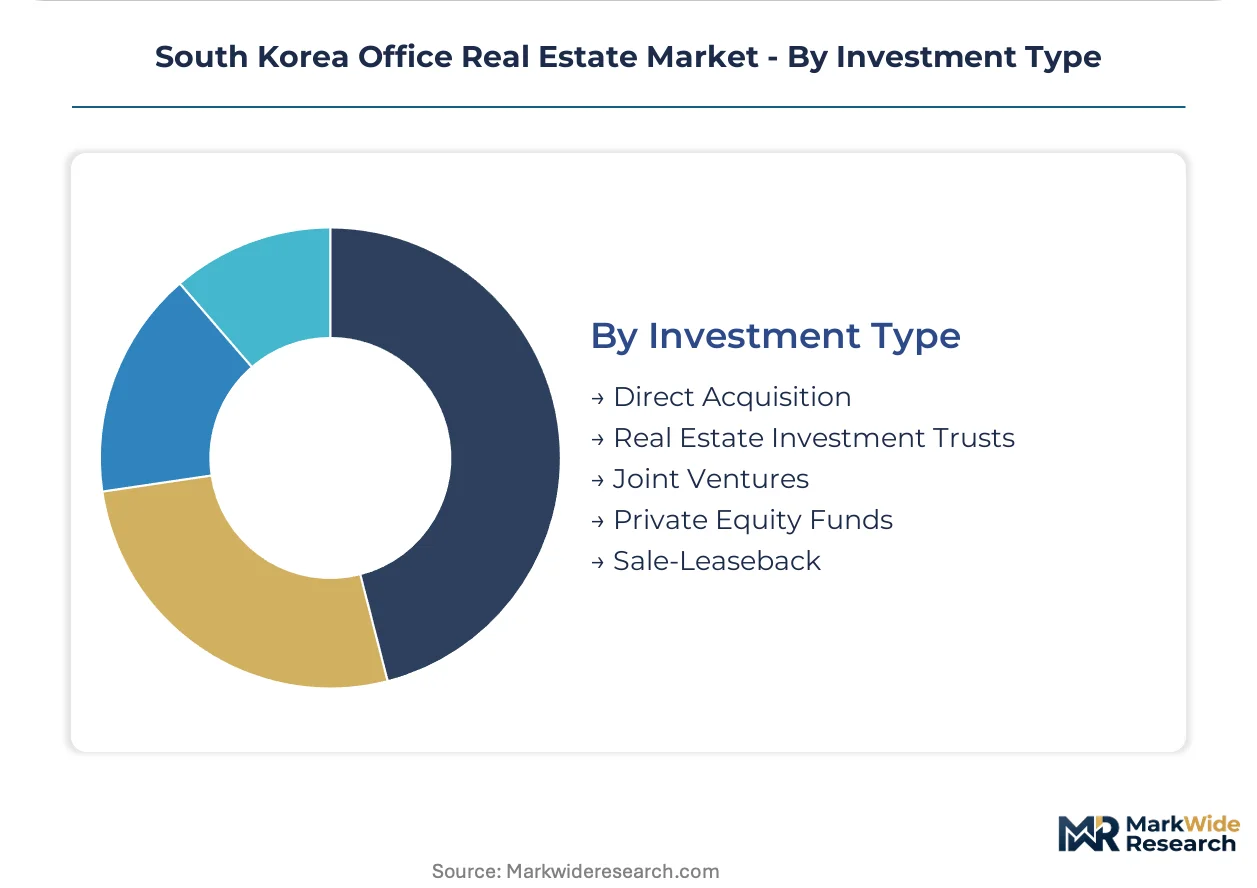
Investment Type:
Supply concentration among domestic institutional platforms limits access for foreign capital, elevating joint venture and fund structures as primary entry mechanisms.
- Real Estate Investment Trusts:Regulated pooled vehicles providing liquidity and diversification for retail and institutional participants. Seoul's Grade A concentration in Gangnam and Yeouido corridors dominates underlying asset composition.
- Joint Ventures:Partnership structures pairing domestic developers with foreign capital sources. Busan Haeundae secondary node development and Seoul land assembly projects rely on this format to navigate fragmented ownership patterns.
- Direct Acquisition:Single-asset purchases by sovereign wealth and pension funds.
- Private Equity Funds:Value-add strategies targeting pre-2010 retrofit opportunities.
- Sale-Leaseback:Corporate monetization of owned real estate with operational retention.
Real Estate Investment Trusts command the largest capital deployment base; Joint Ventures are expanding most quickly as foreign participation rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's office real estate consumption concentrates in Seoul's submarkets, where financial and technology tenants prioritize wellness-certified stock, while Busan and secondary metros exhibit divergent demand patterns tied to maritime logistics and regional corporate migration.
Seoul Capital Area
Technology sector tenants from venture-backed startups to platform enterprises are expanding footprint requirements in Gangnam and Yeouido corridors. Seoul Metropolitan Government building energy codes and MFDS-aligned indoor air quality guidelines reshape landlord capital deployment specifications. The Gangnam Business District and Yeouido Business District concentrate Grade A scarcity premiums as green-certified inventory fails to match institutional tenant procurement timelines.
Busan-Ulsan
Port-city logistics operators and maritime finance tenants are generating demand for Grade A office outside Seoul's dominant submarkets. National Green Building Certification standards apply uniform compliance thresholds across all metropolitan areas. Busan's Haeundae district anchors this secondary node development as foreign capital joint ventures target fragmented land assembly opportunities.
Daegu-Gyeongbuk
Manufacturing headquarters and regional banking operations sustain mid-tier office absorption in this southeastern industrial belt. Seoul energy code equivalents administered through metropolitan government structures govern envelope and mechanical specifications. Daegu's downtown core experiences selective retrofit activity as pharmaceutical tenants apply MFDS filtration standards to regional facility requirements.
Daejeon-Sejong
Government agency relocations to Sejong City have redistributed administrative tenant demand away from traditional Seoul concentration. Public sector procurement standards now incorporate wellness certification preferences that cascade into private landlord specifications. The Sejong administrative cluster functions as a testbed for smart building integration mandates that subsequently diffuse to commercial submarkets.
Gwangju-Honam
Regional creative industries and light manufacturing headquarters generate specialized office requirements distinct from Seoul's financial-technology axis. Green building certification compliance costs filter speculative supply as effectively as in primary metros. Gwangju's downtown corridor sees selective Grade B renovation activity targeting cost-conscious corporate tenants seeking alternatives to capital-intensive Seoul commitments.
South Korea Office Real Estate Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with domestic conglomerate affiliates and global institutional platforms occupying distinct competitive positions. Samsung C&T Corporation leverages engineering consortium capabilities for self-delivered smart building infrastructure, while IGIS Asset Management and Hanwha Real Estate anchor portfolio strategies through concentrated Grade A exposure. Strategic differentiation vectors include integrated solar facade systems, wellness certification pursuit timelines, and joint venture structures for foreign capital participation.
Within the integrated engineering-developer tier, Samsung C&T Corporation exemplifies vertical capability deployment across mixed-use tower delivery. Among asset management specialists, IGIS Asset Management and Hanwha Real Estate occupy positions defined by sustainability-linked capital allocation and green lease structure innovation. Global institutional platforms including Brookfield Asset Management and Hines represent foreign capital entry mechanisms through joint venture formats that navigate fragmented Seoul land ownership patterns.
| Leading Market Players |
|---|
| Brookfield Asset Management |
| CBRE |
| IGIS Asset Management |
| Hanwha Real Estate |
| Jones Lang LaSalle IP, Inc. |
| Samsung C&T Corporation |
| Hines |
| Lotte Property & Development |
| SK D&D Co. Ltd |
| Others |
Value Network & Pricing Analysis
Full-service lease structures with expense stop provisions lock in landlord operating cost visibility while insulating institutional tenants from MFDS compliance escalation. These contracts concentrate pricing power with Grade A landlords in Seoul's Gangnam and Yeouido corridors who control scarce wellness-certified inventory.
Pricing Analysis
Long-term offtake agreements dominate institutional tenant relationships, though short-term lease penetration accelerates among technology sector occupiers. Price differentiation rests on LEED or WELL certification tier and proximity to Seoul Metro transit nodes. Cost compression in Grade B stock intensifies as green retrofit mandates render pre-2010 assets economically marginal. Venture-backed startups exhibit highest price sensitivity; financial services firms absorb premium spreads for compliance accountability.
Supply Chain Analysis
Port congestion at Busan and container availability fluctuations on Asia-Pacific trade lanes elevate inbound logistics costs for building materials and smart HVAC components. Domestic manufacturing draws from South Korea, China, and Japan for raised flooring systems, sensor-based climate controls, and integrated solar facade materials. Single-source vulnerability concentrates in specialized commissioning expertise for IoT-enabled mechanical retrofits. Distribution runs through domestic engineering consortiums and institutional developer self-delivery channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Facility management service contracts and predictive maintenance subscriptions expand faster than base building rents, creating recurring revenue layers that outpace hardware-intensive development returns.
For Market Incumbents: Secure Grade A scarcity premiums in Gangnam and Yeouido through accelerated WELL certification timelines that outpace tenant procurement schedules. Consolidate land assembly positions via joint venture structures that navigate fragmented Seoul corridor ownership. Green retrofit mandates threaten pre-2010 portfolio obsolescence; vertical integration into smart building commissioning preserves margin control against specialist contractor scarcity. For New Entrants and Emerging Players: MFDS-aligned wellness certification fast-tracks unlock pharmaceutical and biotech tenant segments underserved by legacy landlords. Target Busan Haeundae's secondary node development where maritime finance demand outpaces institutional supply concentration. Co-working and serviced office formats offer lowest capital barrier to technology sector procurement with shortest payback horizons. For Investors and Strategic Acquirers: Pre-2010 retrofit specialists with captive commissioning capabilities represent the optimal acquisition archetype for value-add strategies. Long-term viability across the analysis window hinges on regulatory compliance cost pass-through mechanics and green lease structure innovation. Watch MFDS guideline expansion beyond pharmaceutical tenants as the inflection signal for wellness certification standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Smart HVAC Retrofit Deployment | MFDS indoor air quality mandates accelerate sensor-based climate system adoption in Seoul Grade A stock. |
| Wellness Certification Fast-Track | WELL and Fitwel pursuit timelines compress delivery obligations for pharmaceutical tenant requirements. |
| Joint Venture Land Assembly | Foreign capital partnerships navigate fragmented ownership patterns in established Seoul office corridors. |
| Integrated Solar Facade Installation | Building-integrated photovoltaics open net-metering revenue streams through Seoul energy code compliance. |
| Hybrid-Ready Floor Plan Innovation | Modular interior systems and short-term lease structures capture technology sector agility preferences. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with asset managers, tenant representation brokers, facilities directors, and smart building commissioning specialists. Secondary validation drew from Seoul Metropolitan Government building energy code filings, MFDS regulatory guidance documents, national Green Building Certification standards, and domestic REIT portfolio disclosures. Bottom-up lease transaction analysis triangulated against top-down capital deployment tracking across the projection horizon.
Across the analysis window, value and volume outputs reflect segmentation modeling across property type, lease structure, tenant industry, and investment vehicle dimensions. CAGRs were derived from fitted growth curves anchored to historical absorption patterns and regulatory compliance timeline assumptions. Forecast inputs incorporated Seoul energy code enforcement trajectories and technology sector footprint expansion scenarios specific to Gangnam and Yeouido corridor dynamics.
Decision-makers should treat outputs as directional under base assumptions of sustained MFDS regulatory expansion and technology tenant preference for flexible tenure; material deviation in green retrofit cost trajectories or interest rate environments would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
North America Flexible Office Market
Office Real Estate
Flexible Office Market
Office Real Estate
Qatar Co-Working Office Spaces Market
Office Real Estate
France Office Real Estate Market
Office Real Estate
Spain Office Real Estate Market
Office Real Estate
Australia Flexible Office Space Market
Office Real Estate
United States Office Real Estate Market
Office Real Estate
UAE Flexible Office Space Market
Office Real Estate
Asia Pacific Flexible Office Market
Office Real Estate
Saudi Arabia Office Real Estate Market
Office Real Estate
Bahrain Flexible Office Space Market
Office Real Estate
China Office Real Estate Market
Office Real Estate
Australia Co-Working Office Spaces Market
Office Real Estate
China Co Working Office Space Market
Office Real Estate
United States Co-Working Office Space Market
Office Real Estate
Germany Office Real Estate Market