
 Singapore Luxury Residential Real Estate Market | 2026-2036
Singapore Luxury Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Luxury Residential Real Estate Market Analytics
ABSD qualification tiers is bifurcating the competitive landscape for developers serving foreign capital. Frasers Property Singapore leverages its integrated hospitality-retail playbook to anchor mixed-use luxury schemes in prime districts. CDL differentiates through heritage conservation expertise, converting protected shophouse stock into boutique residences. GuocoLand specializes in ultra-luxury tower developments, competing on design pedigree and scarcity value in the Tanjong Pagar corridor.
Singapore luxury residential real estate comprises freehold and leasehold dwellings exceeding SGD 5 million in transacted value, typically exceeding 2,000 square feet with bespoke interior specifications and full-building concierge infrastructure. The product serves wealth preservation, generational asset transfer, and residency-by-investment objectives for transnational capital holders. Condominiums dominate transaction volume across the Core Central Region, while bungalows command the deepest per-square-foot margin pools due to restricted land release. Penthouses represent the fastest-appreciating category as developers ration sky villa inventory within new launches. Foreign investors concentrate in leasehold condominiums where ABSD exposure is most actively managed through corporate structuring.
The Urban Redevelopment Authority governs land use intensity and enforces conservation guidelines that constrain supply elasticity in prime districts. The Monetary Authority of Singapore monitors leverage caps through total debt servicing ratio limits, filtering speculative participation from end-user demand. Stakeholders must track how the Inland Revenue Authority of Singapore interprets beneficial ownership for trust structures, as this determines which buyer profiles retain feasible market access under evolving stamp duty frameworks.
Market Dynamics
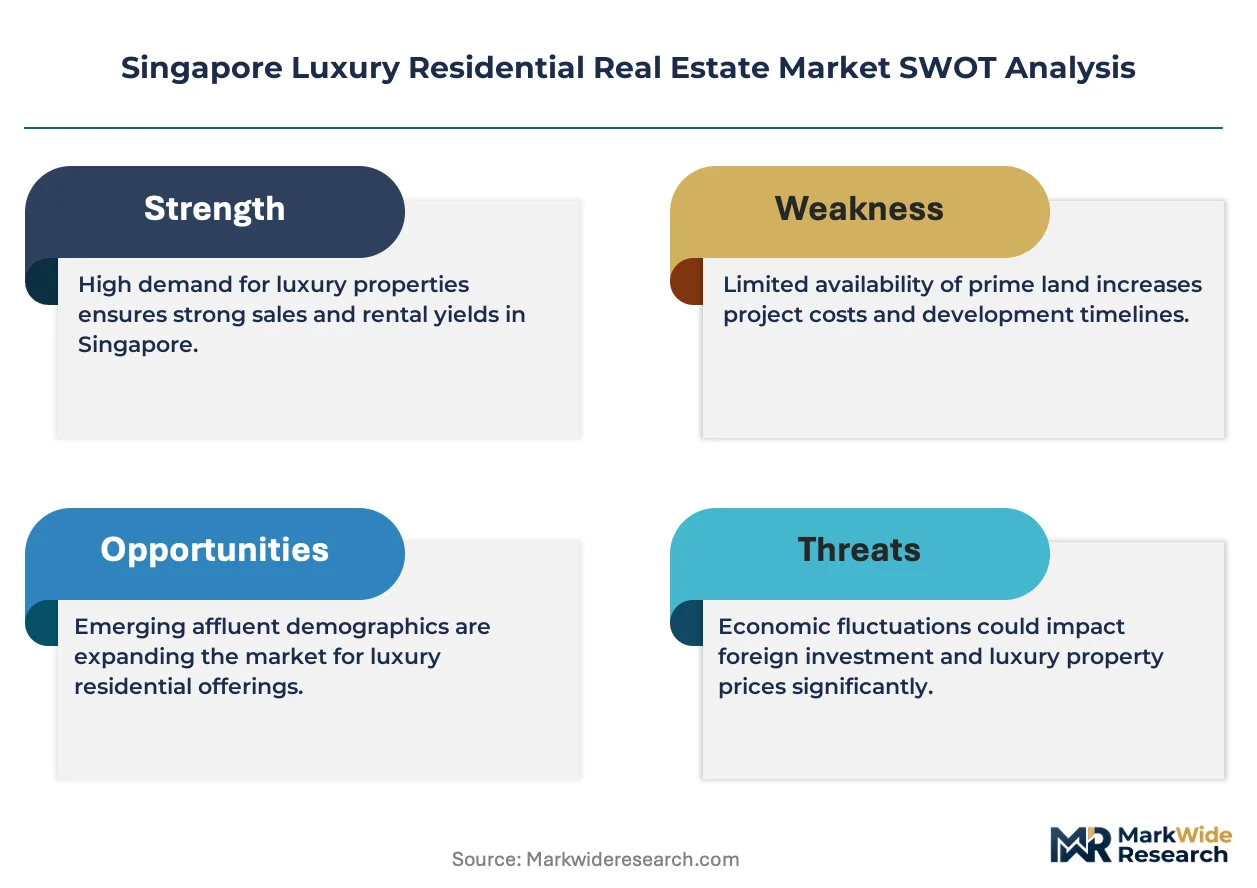
The Urban Redevelopment Authority's Additional Buyer's Stamp Duty recalibrations constitute the dominant structural force, fragmenting foreign purchaser eligibility and bifurcating developer strategies between domestic wealth preservation products and corporate-structured leasehold offerings.
Growth Catalysts
- Ultra-high-net-worth family office expansion:Southeast Asian capital holders are accelerating Singapore property allocations as regional wealth concentration intensifies. The Monetary Authority of Singapore's wealth management licensing framework facilitates this capital migration.
- Conservation guidelines:The Urban Redevelopment Authority's heritage protection mandates restrict prime district supply elasticity. Bungalow stock in Districts 9, 10, and 11 remains tightly held, sustaining scarcity premiums.
- Residency-by-investment pathways:The Global Investor Programme administered by Economic Development Board channels qualified foreign capital into qualifying residential assets. This end-use driver concentrates demand in Core Central Region condominiums.
Market Restraints
- ABSD tier escalation:The Inland Revenue Authority of Singapore's stamp duty framework imposes progressive levies on foreign and corporate purchasers. Corporate structuring costs now absorb 5-8% of acquisition capital.
- Landed stock concentration:Good Class Bungalow supply concentrates among multi-generational Singaporean families with minimal turnover velocity. Foreign ownership restrictions prevent market clearing at marginal price points.
- Total debt servicing ratio caps:The Monetary Authority of Singapore's leverage limits filter speculative participation from end-user demand. Financing accessibility compresses for non-resident buyers without local income documentation.
Strategic Opportunities
- Tanjong Pagar corridor densification:The Greater Southern Waterfront transformation unlocks ultra-luxury tower development sites with harbour views. GuocoLand and comparable developers compete on design pedigree and sky villa scarcity.
- Shophouse conservation conversion:The Urban Redevelopment Authority's heritage incentives support boutique residential adaptation of protected stock. CDL and specialized operators capture premium margins in this constrained sub-segment.
- Integrated mixed-use schemes:Frasers Property Singapore's hospitality-retail playbook anchors luxury residential within activated precincts. This product configuration attracts family office capital seeking operational yield components.
Industry Challenges
- Beneficial ownership interpretation:The Inland Revenue Authority of Singapore's evolving trust structure scrutiny creates compliance uncertainty. Legal advisors face expanding due diligence obligations for nominee arrangements.
- Construction cost volatility:Specialized interior specifications and smart building infrastructure require imported materials and skilled trades. Supply chain reconfiguration extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Luxury Residential Real Estate Market |
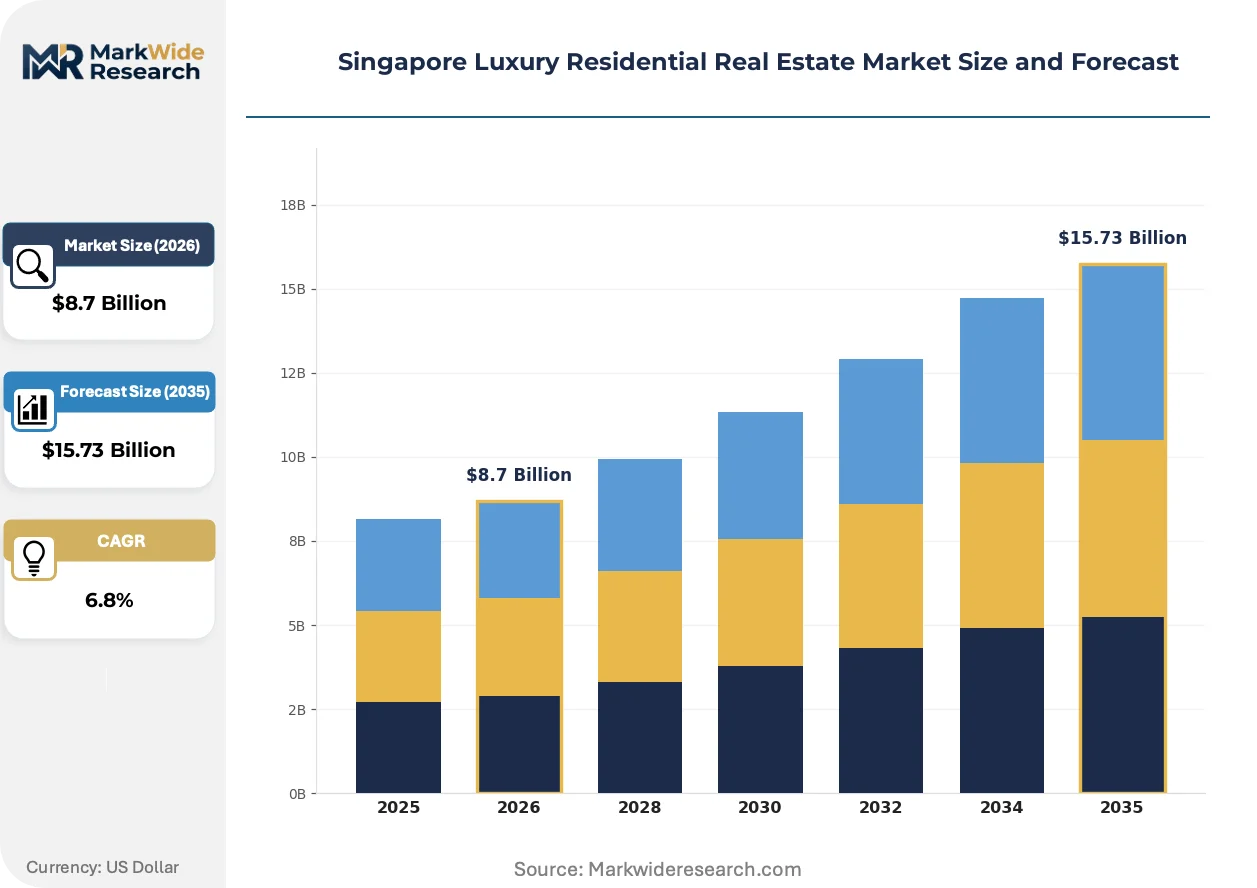
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Condominiums, Villas, Penthouses, Bungalows Buyer Profile: High-Net-Worth Individuals, Foreign Investors, Expats, Corporates Amenities: Swimming Pools, Fitness Centers, Concierge Services, Private Gardens Investment Purpose: Primary Residence, Rental Income, Capital Appreciation, Vacation Home |
| Companies Covered | Allgreen Properties Limited, Frasers Property Singapore, City Developments Limited (CDL), GuocoLand Limited, Keppel Land Limited, CapitaLand Limited, IOI Properties Group, Bukit Sembawang Estates Limited, UOL Group Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Luxury Residential Real Estate Market Evolving Landscape
Digital twin technology and predictive maintenance systems are actively reshaping how developers design and operate luxury residential assets. These innovations compress operational cost structures while elevating service delivery benchmarks.
Building information modeling integrated with IoT sensor networks is decomposing traditional facilities management into predictive, automated workflows. Ultra-luxury tower developers deploy these systems to differentiate concierge infrastructure. The structural consequence is margin compression for conventional property management operators unable to digitize service delivery.
The Urban Redevelopment Authority's 2023 Master Plan intensification guidelines are reshaping permissible gross floor area ratios in prime districts. Developers respond by optimizing unit mix toward larger floorplates with fewer total apartments. The Core Central Region sees accelerated en-bloc activity as ageing stock becomes eligible for density bonuses.
Family office principals increasingly direct acquisitions through single-family investment vehicles rather than personal name purchases. This behavioral shift responds to Inland Revenue Authority of Singapore scrutiny on beneficial ownership disclosure. The leasehold condominium segment absorbs this demand rotation as corporate structuring manages stamp duty exposure.
Singapore Luxury Residential Real Estate Market Segmentation
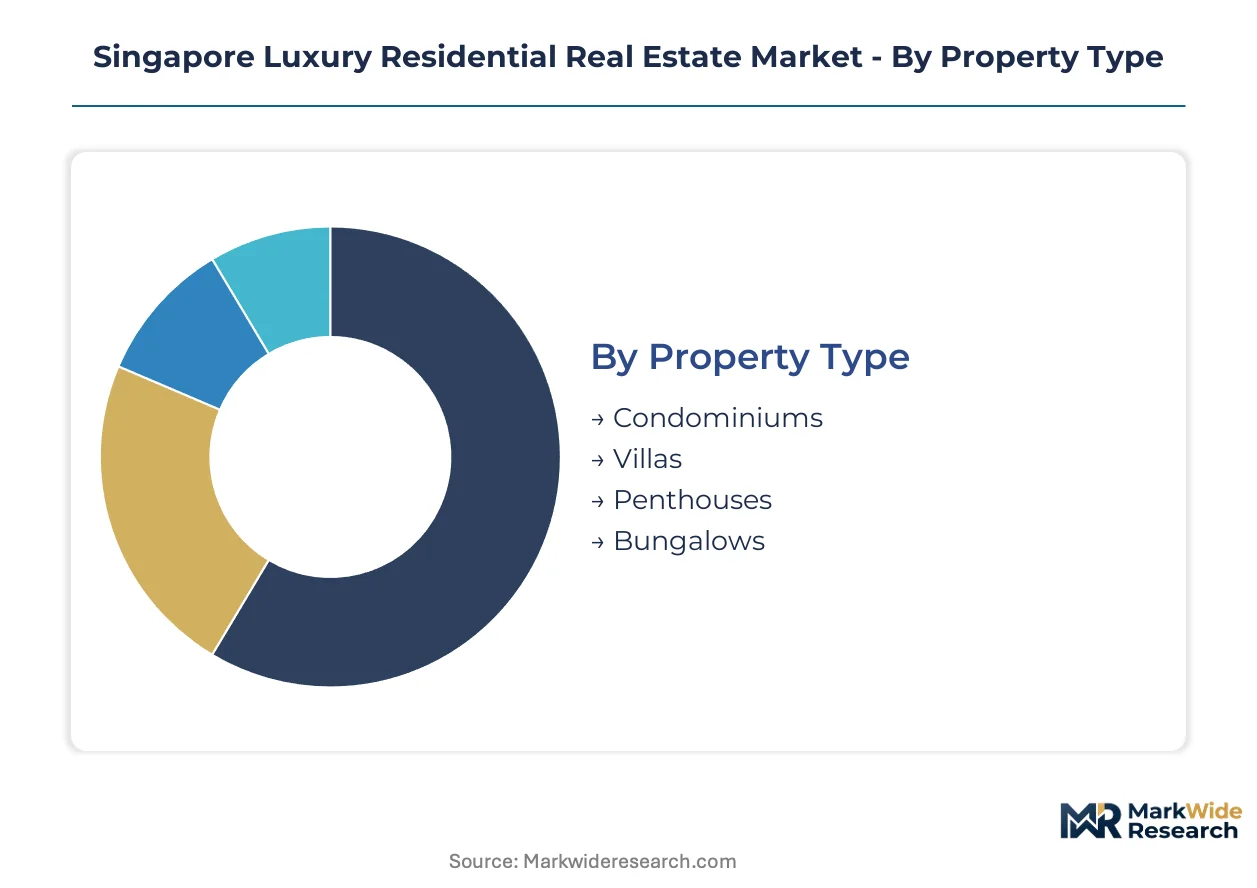
Singapore's luxury residential market fragments across four distinct dimensions that determine pricing power, transaction velocity, and regulatory exposure. Each segmentation axis carries specific margin implications shaped by the Urban Redevelopment Authority's land use frameworks and the Inland Revenue Authority of Singapore's stamp duty tiers.
Property Type:
Margin pools concentrate in landed stock where supply inelasticity sustains scarcity premiums, while leasehold towers absorb volume-driven foreign capital flows.
- Condominiums:High-rise leasehold and freehold apartments dominate transaction volume across the Core Central Region. Foreign investors concentrate here through corporate structures that manage Additional Buyer's Stamp Duty exposure, particularly in Districts 9, 10, and 11.
- Bungalows:Good Class Bungalows and detached houses command the deepest per-square-foot margins due to restricted land release and foreign ownership prohibitions. Multi-generational Singaporean families hold this stock with minimal turnover velocity, sustaining price premiums through supply constraint.
- Villas:Cluster housing and semi-detached configurations occupy a mid-tier position between condominiums and bungalows. These assets attract domestic upgraders seeking landed living without full bungalow capital commitment.
- Penthouses:Sky villa inventory within ultra-luxury towers attracts family office principals seeking trophy assets. Developers ration this product category, creating artificial scarcity that compresses cap rates.
The dominant share belongs to Condominiums, while Penthouses are closing the gap fastest.
Buyer Profile:
Regulatory eligibility tiers fragment purchaser access, with residency status determining feasible property categories and structuring complexity.
- High-Net-Worth Individuals:Singapore citizens and permanent residents leverage favorable Additional Buyer's Stamp Duty rates to acquire freehold landed stock. This cohort drives Good Class Bungalow transactions and heritage shophouse conversions.
- Foreign Investors:Non-resident capital holders face elevated stamp duty tiers but concentrate in leasehold condominiums through corporate vehicles. The Global Investor Programme channels qualified foreign capital into qualifying residential assets.
- Expats:Long-term employment pass holders seek Core Central Region rentals and leasehold purchases with exit liquidity. Their demand concentrates in districts proximate to central business district employment clusters.
- Corporates:Single-family investment vehicles and trust structures acquire residential assets for wealth preservation and generational transfer. The Inland Revenue Authority of Singapore's beneficial ownership scrutiny is reshaping this segment's compliance architecture.
High-Net-Worth Individuals retain the largest transaction value share, though Corporate structures are expanding most quickly.
Amenities:
Service infrastructure intensity separates ultra-luxury product from commodity premium offerings, with operational technology becoming a margin differentiator.
- Swimming Pools:Infinity-edge and temperature-controlled pools anchor wellness positioning in tower developments. Developers compete on pool deck design and harbor view alignment.
- Fitness Centers:Specialized training facilities with imported equipment and personal training services attract health-conscious principals. These amenities support rental yield premiums in investor-targeted product.
- Concierge Services:Full-building concierge infrastructure differentiates ultra-luxury towers, with digital twin technology enabling predictive service delivery. GuocoLand and comparable developers compete on service automation sophistication.
- Private Gardens:Landscaped outdoor space concentrates in landed stock and ground-floor villa units. This amenity commands scarcity premiums in dense urban districts.
Concierge Services command the highest capital allocation per square foot, while Fitness Centers are gaining share fastest as wellness positioning intensifies.
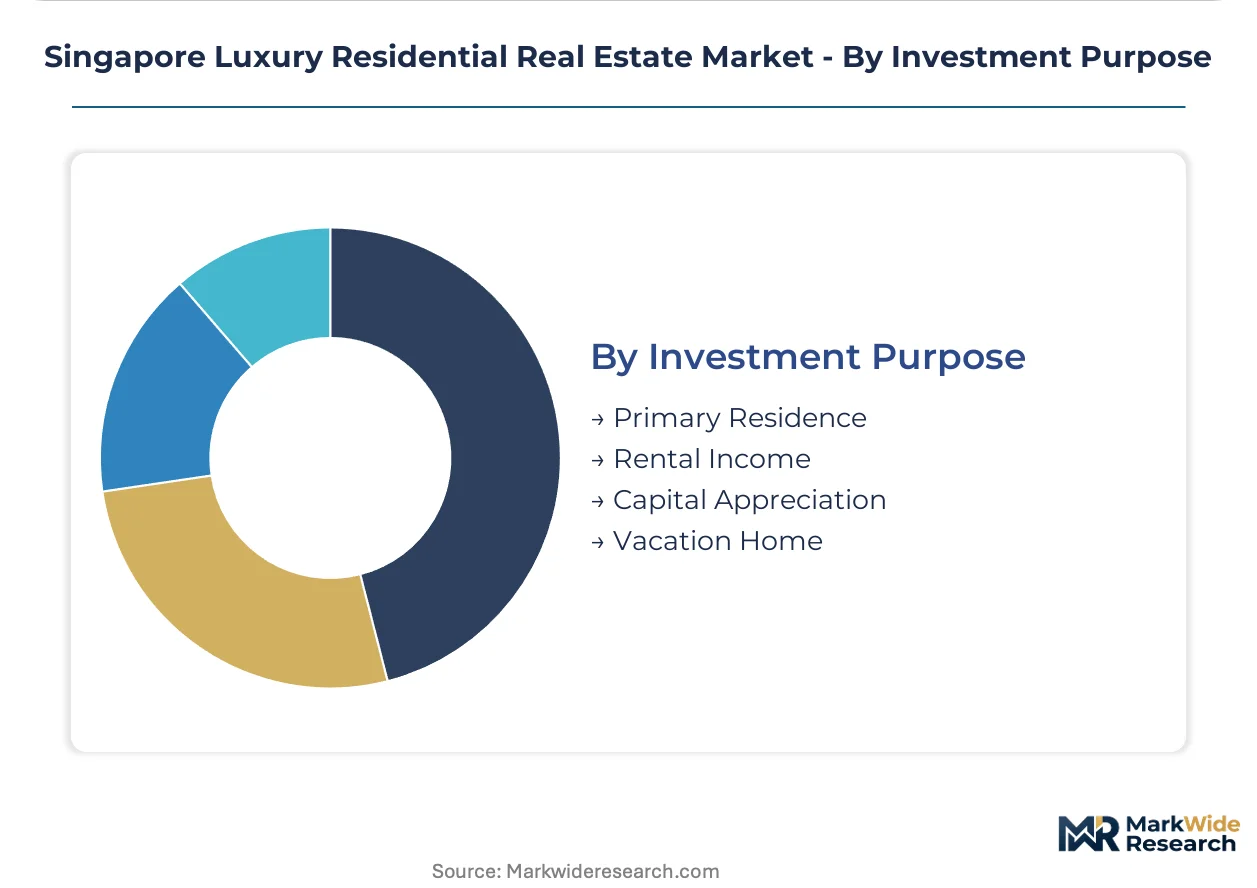
Investment Purpose:
End-use motivation determines holding period, financing structure, and sensitivity to regulatory recalibration.
- Primary Residence:Owner-occupier demand concentrates in freehold landed stock and large-format condominiums. This segment exhibits lowest price elasticity and longest holding periods.
- Rental Income:Yield-focused investors target Core Central Region leasehold units with expat tenant exposure. Total debt servicing ratio caps constrain leverage for non-resident buyers without local income documentation.
- Capital Appreciation:Wealth preservation objectives drive acquisition of scarcity assets with constrained supply elasticity. Bungalows and heritage shophouses serve this purpose for domestic capital.
- Vacation Home:Secondary residence demand from regional ultra-high-net-worth families concentrates in integrated mixed-use schemes. Frasers Property Singapore's hospitality-retail playbook targets this segment.
Primary Residence holds the dominant position, though Capital Appreciation is climbing the fastest as regional wealth concentration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ultra-high-net-worth family offices from Indonesia, Malaysia, and Thailand concentrate capital deployment in Singapore's Core Central Region. These buyers prioritize residency-by-investment pathways and wealth preservation vehicles. The Monetary Authority of Singapore's wealth management licensing framework channels this regional capital migration into qualifying residential assets.
Indonesia
Jakarta-based conglomerate principals drive demand for leasehold condominiums in Districts 9 and 10. The Economic Development Board's Global Investor Programme provides qualifying pathways for capital holders meeting investment thresholds. Surabaya and Medan family offices increasingly favor corporate-structured acquisitions through Singapore-registered vehicles.
Malaysia
Kuala Lumpur banking dynasties and Penang manufacturing families expand property allocations amid regional currency volatility. The Inland Revenue Authority of Singapore's trust structure scrutiny shapes how Malaysian capital holders arrange beneficial ownership. Iskandar Malaysia-linked investors concentrate activity in Tanjong Pagar corridor mixed-use schemes.
Thailand
Bangkok agribusiness and energy sector fortunes seek Singapore freehold stock for generational asset transfer. The Urban Redevelopment Authority's conservation guidelines limit heritage shophouse availability, intensifying competition among Thai buyers. Phuket and Chiang Mai-based principals favor penthouses with harbor views in ultra-luxury towers.
China
Mainland capital holders pivot toward Singapore following domestic property sector recalibration. The Additional Buyer's Stamp Duty framework imposes tiered levies that corporate structuring partially mitigates. Shenzhen and Guangzhou technology principals concentrate demand in new launch leasehold inventory with digital concierge infrastructure.
India
Mumbai financial services families and Bangalore technology founders accelerate Singapore allocations. The Monetary Authority of Singapore's total debt servicing ratio caps filter speculative participation from end-user demand. Delhi-NCR industrialists concentrate acquisitions in bungalows and large-format condominiums for primary residence use.
Singapore Luxury Residential Real Estate Market Competitive Landscape
Player mix skews toward integrated property conglomerates with hospitality and retail operating capabilities. Market structure concentrates around developers with land banking capacity in prime districts and heritage conservation expertise. Three archetypes dominate: ultra-luxury tower specialists, heritage conversion operators, and mixed-use scheme integrators. Competitive moves center on en-bloc site acquisition and density optimization under Urban Redevelopment Authority intensification guidelines.
Within the integrated conglomerate tier, Frasers Property Singapore and CapitaLand Limited exemplify hospitality-retail anchored development models. CDL occupies a position among heritage conservation specialists converting protected shophouse stock. GuocoLand Limited anchors the ultra-luxury tower segment competing on design pedigree in the Tanjong Pagar corridor. Keppel Land Limited and UOL Group Limited sit within the diversified developer archetype spanning multiple product categories.
| Leading Market Players |
|---|
| Allgreen Properties Limited |
| Frasers Property Singapore |
| City Developments Limited (CDL) |
| GuocoLand Limited |
| Keppel Land Limited |
| CapitaLand Limited |
| IOI Properties Group |
| Bukit Sembawang Estates Limited |
| UOL Group Limited |
| Others |
Value Network & Pricing Analysis
Long-term development management contracts with progressive payment indexation to construction cost indices lock in supply access for prime district land parcels while anchoring price visibility for ultra-luxury tower completions. These arrangements tether developer margins to the Urban Redevelopment Authority's land release calendar and the Monetary Authority of Singapore's leverage environment.
Pricing Analysis
Cost-plus contracts with Singapore Construction Price Index escalation clauses dominate developer-procurement relationships for specialized interior fit-outs and smart building infrastructure. Price differentiation separates freehold landed stock in Districts 9, 10, and 11 from leasehold tower inventory, with scarcity premiums widening as foreign ownership restrictions constrain bungalow turnover. Pricing pressure stems from imported materials cost volatility and skilled trade shortages extending project timelines. Family office principals exhibit lowest price sensitivity, while yield-focused expat investors concentrate in mid-tier leasehold condominiums with highest elasticity.
Supply Chain Analysis
Italy and Spain anchor marble and natural stone finishing materials for ultra-luxury specifications, while Germany and Japan supply precision-engineered smart building systems. Construction inputs draw from regional Southeast Asian fabrication for structural steel and concrete, with specialized glass curtain wall systems sourced from South Korea. Single-source vulnerability concentrates in heritage conservation materials where the Urban Redevelopment Authority mandates specific restoration techniques. Distribution runs through developer-direct procurement channels with appointed interior design houses managing final-mile specification delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among ultra-high-net-worth family offices deploying through single-family investment vehicles, fragmenting traditional individual purchaser segments and reshaping developer go-to-market architectures.
For Market Incumbents: Secure en-bloc site pipelines in the Tanjong Pagar corridor ahead of Greater Southern Waterfront densification, while deepening heritage conservation capabilities to capture shophouse conversion premiums threatened by CDL's specialized positioning. Vertical integration into hospitality-retail operations, following Frasers Property Singapore's playbook, defends margin pools against pure-play residential developers. For New Entrants and Emerging Players: Digital concierge service layers where incumbents under-serve present immediate white-space opportunity, particularly predictive maintenance systems and IoT-integrated facilities management for ageing ultra-luxury stock. Boutique heritage shophouse conversion specialists can penetrate Districts 9 and 10 where conservation guidelines constrain supply elasticity. A partnership-led go-to-market angle with established family office advisors accelerates capital access. For Investors and Strategic Acquirers: Land banking specialists with prime district holdings and active development entitlements represent the highest-conviction acquisition archetype for exposure to Singapore's luxury residential scarcity premium. Long-term viability hinges on sustained regional wealth concentration and the Urban Redevelopment Authority's restraint on Core Central Region supply expansion. The signal to watch is Inland Revenue Authority of Singapore recalibration of beneficial ownership disclosure requirements for trust-structured acquisitions.| Strategic Initiative | Industry Significance |
|---|---|
| En-bloc Site Acquisition | Captures density bonuses under Urban Redevelopment Authority intensification guidelines before competitor land banking. |
| Heritage Conservation Conversion | Unlocks premium margins in protected shophouse stock where supply constraints intensify competition. |
| Integrated Mixed-use Development | Attracts family office capital seeking operational yield components alongside residential appreciation. |
| Digital Twin Technology Deployment | Compresses operational cost structures while elevating concierge service delivery benchmarks against conventional operators. |
| Corporate Structuring Capability Buildout | Enables foreign purchaser access under Additional Buyer's Stamp Duty frameworks through Singapore-registered vehicles. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Urban Redevelopment Authority transaction records, Monetary Authority of Singapore regulatory circulars, and developer disclosure filings. Primary interviews engaged property development executives, family office investment principals, heritage conservation architects, and real estate legal advisors specializing in trust structures. Secondary sources included the Inland Revenue Authority of Singapore stamp duty guidance, Economic Development Board Global Investor Programme documentation, and Core Central Region en-bloc transaction databases. Bottom-up unit economics triangulate against top-down market sizing across property type, buyer profile, and investment purpose dimensions.
Segmentation dimensions modeled span property type, buyer profile, amenities intensity, and investment purpose across the projection horizon. CAGRs derive from regression analysis of historical transaction velocity, supply pipeline visibility, and regulatory elasticity assumptions. Forecast inputs incorporate the Urban Redevelopment Authority's Master Plan intensification guidelines and the Monetary Authority of Singapore's total debt servicing ratio calibration trajectory.
Material uncertainties — Additional Buyer's Stamp Duty tier recalibration, beneficial ownership interpretation shifts, and construction cost volatility — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained regional wealth concentration and conservation guideline stability. Recalibration cycles align with material shifts in stamp duty frameworks and land release policy announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Residential Real Estate Market
North America Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Sweden Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
United States Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Belgium Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
South Korea Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Residential Real Estate Market
Luxury Residential Real Estate Market
Japan Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Switzerland Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Bahrain Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
India Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Canada Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Australia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Luxury-Minded Retirement Residences Market
Luxury Residential Real Estate Market
Italy Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Europe Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Saudi Arabia Luxury Residential Real Estate Market