
 Czech Republic Facility Management Market | 2026-2036
Czech Republic Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Czech Republic Facility Management Market Outlook
Central Bohemia's industrial corridor is rewriting procurement patterns for integrated facility services. ISS Facility Services leverages its multi-site contracts across automotive and electronics campuses to sustain recurring revenue depth. CBRE Group Inc. anchors premium office management in Prague's CBD, while Sodexo competes through specialized food and workplace services embedded in manufacturing environments. ECOSERVIS differentiates via localized responsiveness in secondary Czech cities where multinational footprints remain lighter.
Facility management encompasses the professional coordination of building operations, maintenance, and support services through structured service-level agreements that specify response times, uptime thresholds, and energy performance benchmarks. Its primary commercial purpose is to reduce total cost of occupancy while ensuring regulatory compliance and workforce productivity across complex physical environments. Cleaning and maintenance services dominate current contract value given their non-discretionary nature and labor intensity, while IoT solutions and energy management technology represent the fastest-expanding margin pools as building owners face escalating utility costs and carbon reporting obligations. The hybrid management level is gaining traction as organizations retain strategic oversight while outsourcing technical execution.
The Czech Ministry of Industry and Trade enforces national energy efficiency obligations that directly shape building modernization budgets and FM contract scopes. BSI Czech Republic certifies quality and environmental management systems that determine vendor eligibility for public institution tenders. EU taxonomy alignment requirements and the F-Gas Regulation are forcing refrigeration and HVAC service providers to retool capabilities. Stakeholders must monitor how rapidly Czech industrial tenants shift from cost-based FM procurement to outcome-based contracts tied to measurable productivity and sustainability metrics.
Market Dynamics
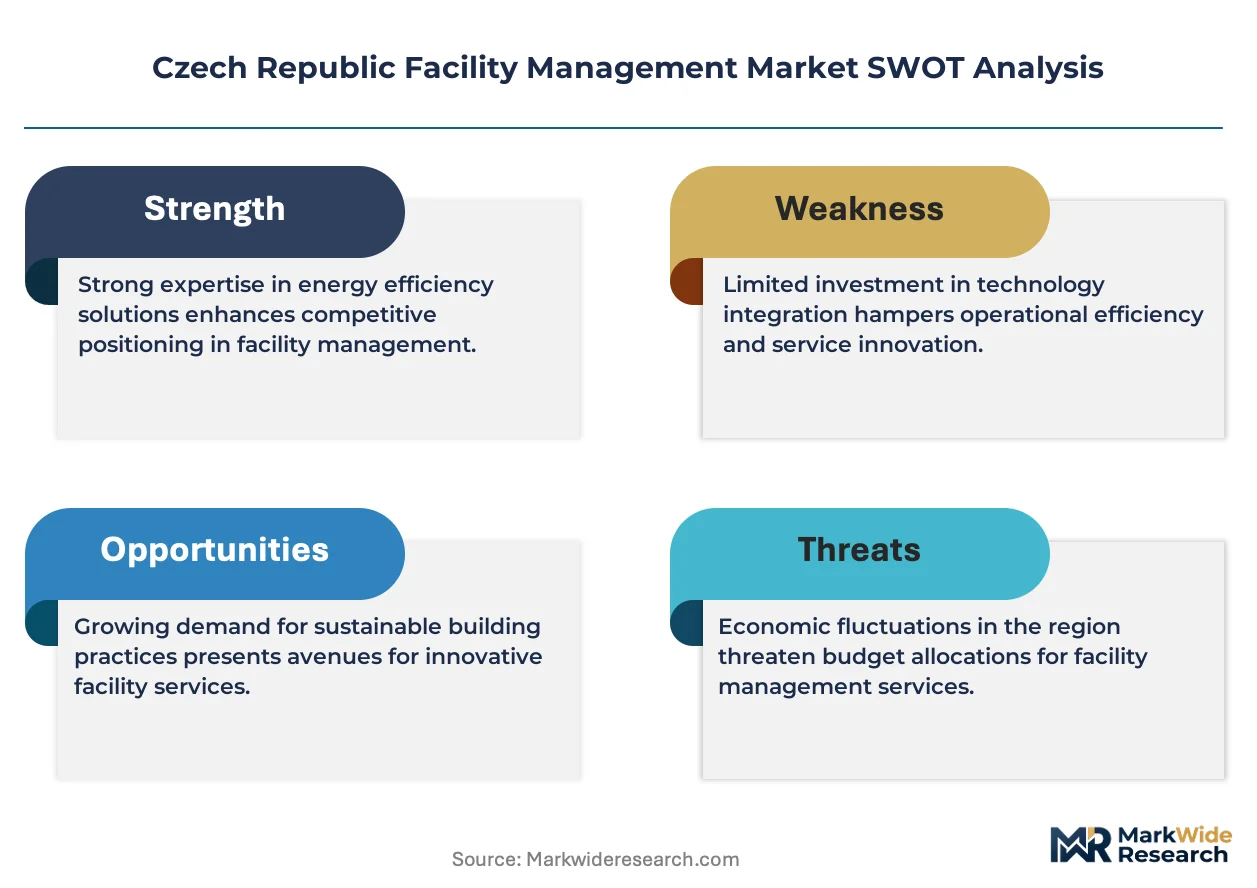
The EU Energy Performance of Buildings Directive is compressing contract timelines for Czech facility management providers, forcing simultaneous upgrades to HVAC infrastructure and digital monitoring systems across Prague's commercial stock and industrial zones.
Growth Catalysts
- EU Green Deal implementation:The directive mandates deep energy retrofits across public and private building stock, expanding integrated FM contract scopes to include carbon reporting and renewable energy integration.
- Pharmaceutical manufacturing expansion:Sterile production facilities across Plzeň and Brno corridors require specialized cleanroom maintenance and validated environmental monitoring services.
- Smart building sensor deployment:IoT-enabled predictive maintenance systems are reducing unplanned downtime for automotive and electronics campuses in Central Bohemia.
Market Restraints
- Skilled technician scarcity:Refrigeration and HVAC specialists face F-Gas Regulation certification requirements that constrain service capacity expansion.
- Energy price volatility:Natural gas and electricity input costs are compressing fixed-price FM contract margins.
- Supplier concentration in Prague:Premium technical services cluster in the capital, leaving secondary cities dependent on fragmented local providers.
Strategic Opportunities
- Ústí nad Labem industrial zone:Heavy manufacturing tenants there are consolidating multi-site FM contracts under single providers.
- Hybrid management adoption:Organizations are retaining strategic oversight while outsourcing technical execution, creating advisory service revenue streams.
- CSRD alignment services:The EU Corporate Sustainability Reporting Directive is generating demand for verified building performance data and ESG documentation.
Industry Challenges
- BMS integration complexity:Legacy building management systems in Prague's 1990s office stock resist seamless connection to cloud-based analytics platforms.
- Multi-certification timelines:ISO 14001, ISO 45001, and BSI quality standards require sequential auditing that delays vendor qualification for public tenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Czech Republic Facility Management Market |
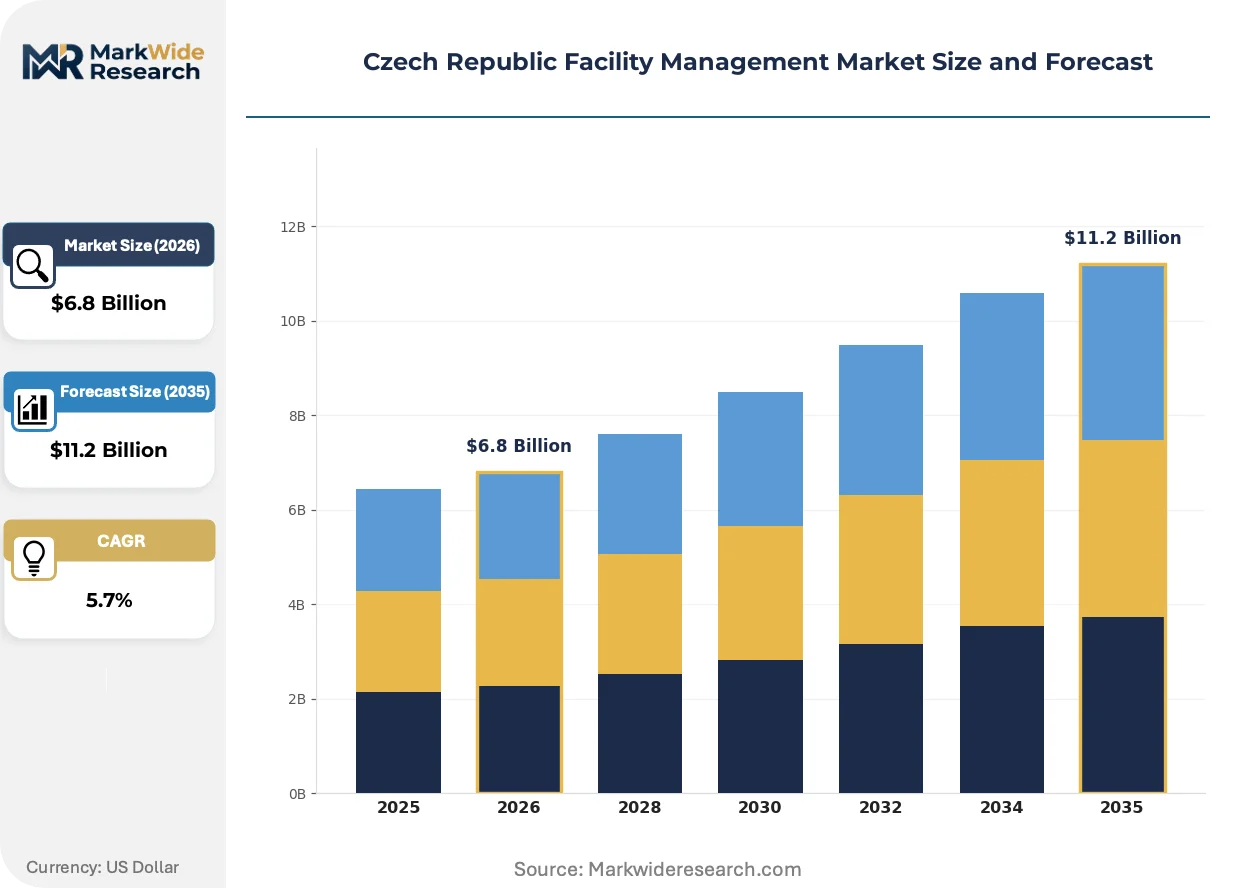
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Security, Maintenance, Landscaping Facility Type: Commercial Buildings, Residential Complexes, Industrial Facilities, Public Institutions Management Level: Outsource, In-house, Hybrid, Contracted Technology: Automation, Mobile Applications, IoT Solutions, Energy Management |
| Companies Covered | ISS Facility Services, CBRE Group Inc., JLL, Sodexo, Cushman & Wakefield, ENGIE Services, Johnson Controls, ECOSERVIS, Skanska a.s., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Czech Republic Facility Management Market Strategic Shifts
Digital infrastructure is compressing traditional service boundaries across the Czech FM sector, merging physical maintenance with real-time energy optimization and automated compliance reporting.
Digital twin technology is collapsing the information gap between building design specifications and operational performance. Facility managers in Prague's premium office segment are deploying virtual replicas to simulate HVAC load scenarios before physical intervention. This capability is collapsing response times for thermal comfort complaints and enabling precise capital planning for mechanical upgrades.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants with stringent quota reductions through 2030. Czech HVAC service providers must retool technician certifications and equipment inventories to handle alternative refrigerants like R-32 and CO2 systems. Industrial refrigeration users in food processing and pharmaceutical cold chains face the steepest compliance costs and shortest adaptation windows.
Integrated service bundling is replacing siloed cleaning, security, and maintenance contracts. Manufacturing tenants across the Brno electronics corridor are consolidating vendor relationships under single accountability frameworks with unified KPI dashboards. This pattern is most visible among German-owned automotive suppliers seeking operational symmetry with their parent facility management standards.
Czech Republic Facility Management Market Segmentation
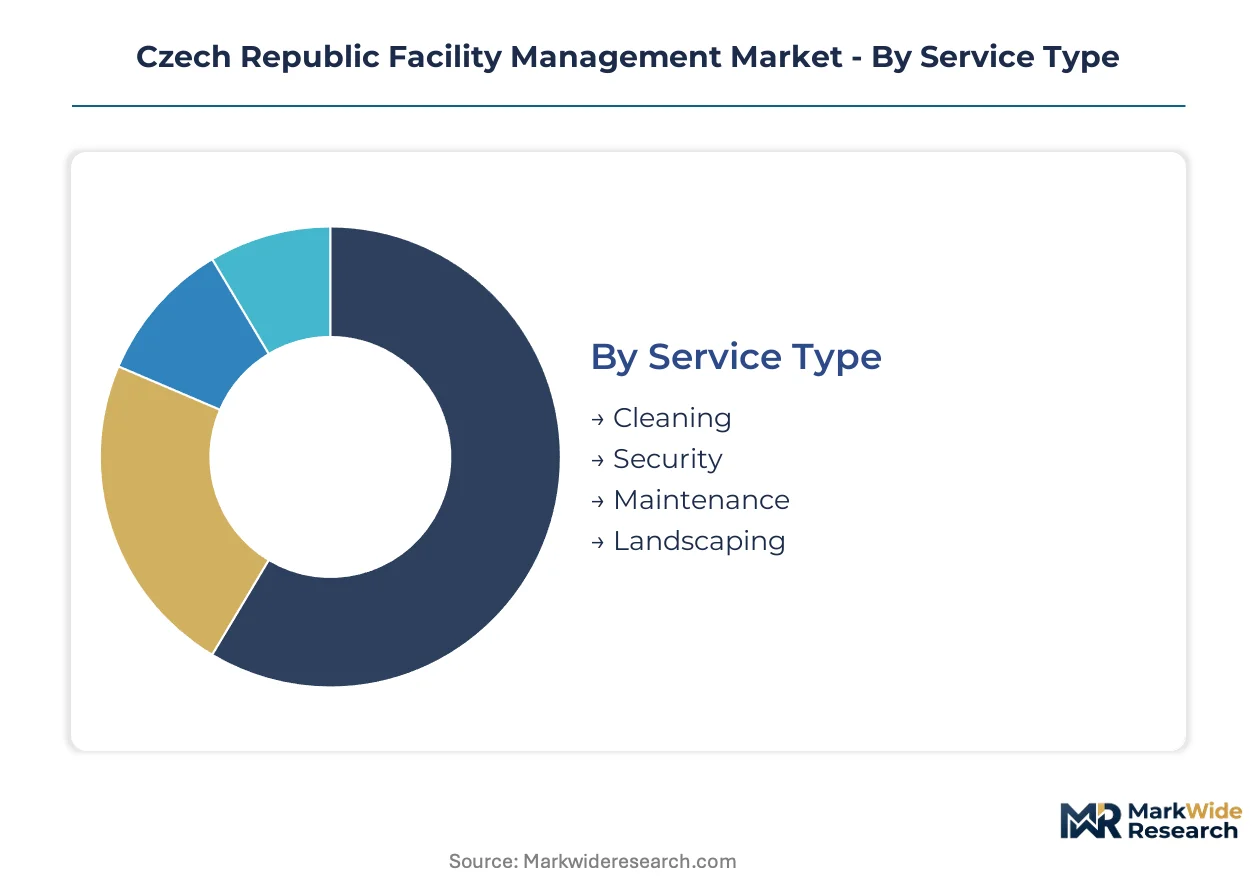
Segmentation in the Czech FM sector exposes how service intensity, asset complexity, and regulatory exposure fragment procurement patterns. Each dimension reveals distinct margin structures and vendor capability requirements.
Service Type:
After-sales service intensity varies dramatically across service categories, with technical maintenance demanding specialized technician retention while cleaning operates on volume-based labor arbitrage.
- Maintenance:Encompasses HVAC, electrical, and mechanical systems requiring certified technician deployment and regulatory compliance documentation. Demand concentrates in Plzeň pharmaceutical corridors where validated equipment uptime underpins sterile production continuity and EU GMP audit readiness.
- Cleaning:Covers routine janitorial, specialized disinfection, and cleanroom protocols. Prague's premium office segment drives contract value through bundled daytime cleaning and sustainability-certified service delivery.
- Security:Includes manned guarding, access control, and surveillance system monitoring. Industrial zones in Ústí nad Labem generate demand for integrated perimeter protection tied to insurance risk assessments.
- Landscaping:Encompasses grounds maintenance, seasonal planting, and snow removal for commercial campuses. Municipal contracts in Brno's technology parks emphasize biodiversity compliance under local green space ordinances.
Maintenance holds the largest share; momentum sits with cleaning as ESG reporting requirements expand scope.
Facility Type:
Cost tier differentiation separates premium technical services for complex industrial assets from standardized offerings in residential portfolios.
- Industrial Facilities:Encompass manufacturing plants, warehouses, and distribution centers requiring specialized environmental controls and heavy equipment maintenance. Central Bohemia's automotive campuses drive integrated FM contract consolidation under single-provider accountability frameworks.
- Commercial Buildings:Covers office towers, retail centers, and mixed-use developments. Prague CBD assets command premium pricing through smart building integration and tenant experience services.
- Public Institutions:Includes government offices, healthcare facilities, and educational campuses subject to public procurement rules. BSI certification requirements constrain vendor pools for hospital maintenance tenders.
- Residential Complexes:Encompass multi-unit housing developments and gated communities. Secondary Czech cities show fragmented provider landscapes with localized pricing pressure.
Industrial facilities command premium contract values; commercial buildings show steepest expansion trajectory through smart retrofit mandates.
Management Level:
Customer type segmentation reveals how strategic control preferences reshape vendor relationships and contract architecture.
- Outsource:Full delegation of facility operations to third-party providers with defined SLA frameworks. German-owned automotive suppliers in the Brno corridor favor this model for operational symmetry with parent company standards.
- Hybrid:Retains strategic oversight and vendor management in-house while outsourcing technical execution. Mid-sized Czech manufacturers adopt this structure to balance control with capability access.
- In-house:Direct employment of maintenance and operations staff. Large pharmaceutical complexes in Plzeň maintain captive teams for validated cleanroom environments.
- Contracted:Project-based engagement for specific capital works or seasonal demand spikes. Energy retrofit projects under EU Green Deal implementation drive short-term technical contracting.
Outsource arrangements dominate current contract volume; hybrid models are gaining share fastest as organizations seek advisory service integration.
Technology:
Application focus separates operational efficiency tools from compliance and sustainability enablers in technology adoption patterns.
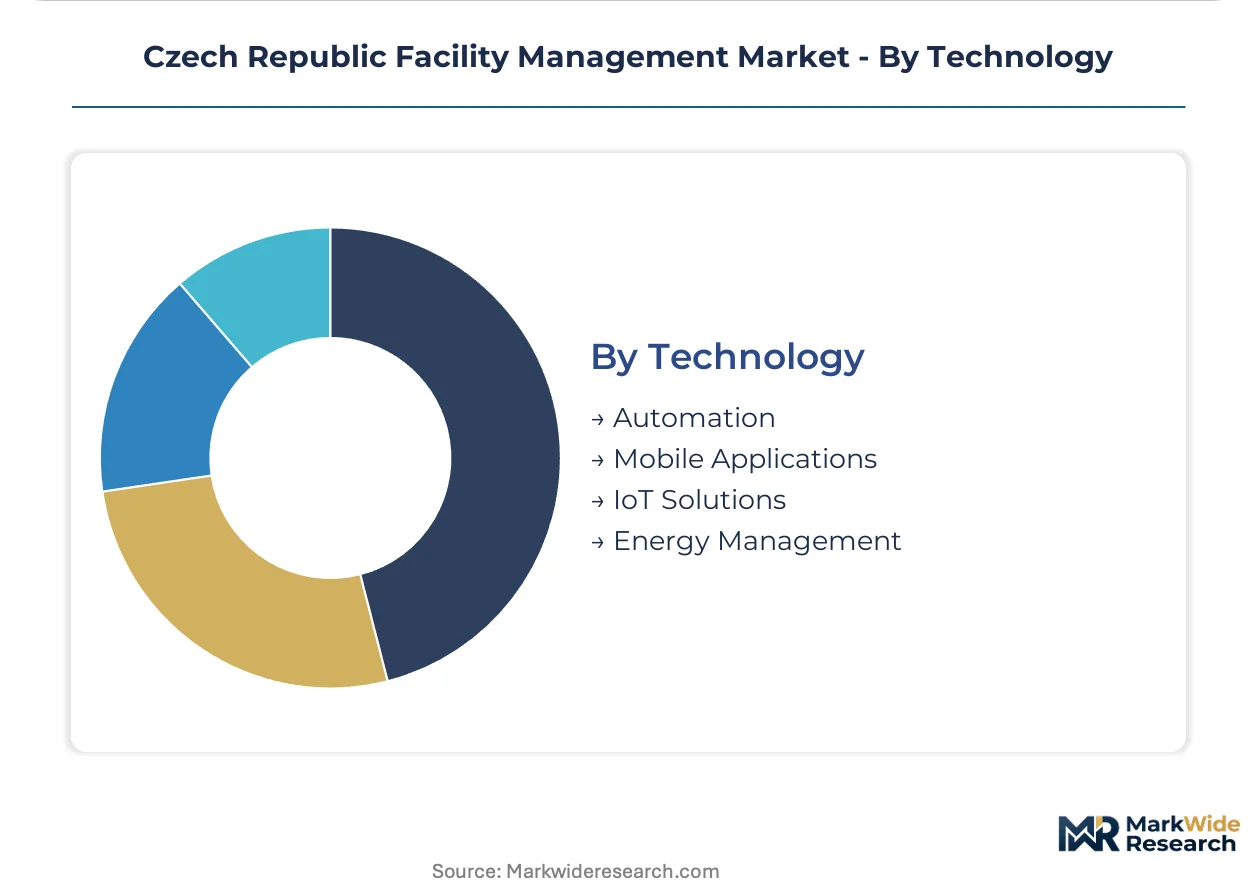
- IoT Solutions:Sensor networks enabling predictive maintenance, occupancy monitoring, and environmental tracking. Prague's 1990s office stock presents integration challenges with legacy BMS infrastructure.
- Energy Management:Systems for consumption optimization, renewable integration, and carbon reporting. EU Energy Performance of Buildings Directive compliance expands contract scopes to include verified performance data.
- Automation:Robotic cleaning systems, automated access control, and drone-based inspection tools. High labor cost environments in premium commercial segments drive pilot deployments.
- Mobile Applications:Workforce dispatch platforms, tenant service portals, and real-time reporting dashboards. Field technician efficiency gains support margin recovery in fixed-price contracts.
Energy management captures largest technology investment; IoT solutions are climbing the fastest as F-Gas Regulation compliance drives sensor deployment for refrigeration monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technical service capacity clusters disproportionately in Prague, leaving secondary Czech regions dependent on fragmented local networks. This spatial imbalance shapes contract pricing and vendor selection patterns across the national market.
Prague
Premium office towers and mixed-use developments drive demand for smart building integration and tenant experience services. The EU Energy Performance of Buildings Directive mandates deep retrofits across the capital's 1990s commercial stock. Prague's CBD anchors the national market for integrated facility management contracts with unified KPI frameworks.
Central Bohemia
Automotive and electronics campuses generate concentrated demand for predictive maintenance and multi-site service consolidation. The Czech Ministry of Industry and Trade enforces national energy efficiency obligations that shape modernization budgets. German-owned suppliers across the industrial corridor favor outsourced models aligned with parent company facility management standards.
Plzeň
Pharmaceutical manufacturing complexes require specialized cleanroom maintenance and validated environmental monitoring. EU GMP audit readiness underpins sterile production continuity requirements. The region's sterile facilities drive premium contract values for technical maintenance with certified technician deployment.
Brno
Electronics manufacturing and technology parks generate demand for integrated service bundling under single accountability frameworks. Local green space ordinances shape municipal landscaping contracts with biodiversity compliance requirements. The city's manufacturing tenants are consolidating vendor relationships to match operational symmetry with German parent standards.
Ústí nad Labem
Heavy manufacturing tenants drive demand for consolidated multi-site FM contracts under single providers. Industrial zones generate requirements for integrated perimeter protection tied to insurance risk assessments. The region shows pricing pressure from supplier concentration gaps relative to Prague's technical service density.
Czech Republic Facility Management Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in technical niches. The Czech facility management market structures around three distinct player tiers: multinational service platforms with multi-site contract capabilities, regional specialists with localized responsiveness, and captive in-house operations retained by pharmaceutical and industrial complexes. Consolidation pressures favor integrated service bundling over siloed contracts. Competitive moves center on hybrid management advisory services and CSRD-aligned building performance data offerings.
Among multinational platforms, ISS Facility Services exemplifies the multi-site automotive and electronics campus model, while CBRE Group Inc. occupies a position in premium Prague CBD office management. Sodexo represents the specialized workplace services archetype embedded in manufacturing environments. ECOSERVIS anchors the regional specialist tier with localized responsiveness in secondary Czech cities where multinational footprints remain lighter. These three archetypes—ISS Facility Services, CBRE Group Inc., and ECOSERVIS—collectively illustrate how vendor selection maps to asset complexity and geographic concentration.
| Leading Market Players |
|---|
| ISS Facility Services |
| CBRE Group Inc. |
| JLL |
| Sodexo |
| Cushman & Wakefield |
| ENGIE Services |
| Johnson Controls |
| ECOSERVIS |
| Skanska a.s. |
| Others |
Value Chain & Pricing Dynamics
Prague's technical service density anchors national pricing power for premium facility management contracts, while supplier fragmentation in Ústí nad Labem and secondary Czech cities forces cost absorption by local providers unable to pass input volatility downstream.
Pricing Analysis
The EU Energy Performance of Buildings Directive dictates the pricing tier structure across Czech facility management, separating premium smart-building-integrated contracts from standardized maintenance agreements. Pricing stratifies across certified energy performance tiers, with ISO 14001 and BSI quality certification commanding material premiums in public institution tenders. Cost compression in fixed-price HVAC and refrigeration contracts is intensifying because natural gas and electricity input volatility erodes margins before escalation clauses activate. Mid-sized Czech manufacturers adopting hybrid management models show highest price sensitivity, while pharmaceutical complexes in Plzeň prioritize validated uptime over unit cost.
Supply Chain Analysis
ISS Facility Services, CBRE Group Inc., and Sodexo hold concentrated contract-manufacturing capacity for multi-site integrated facility services across the Czech Republic's automotive and pharmaceutical corridors. Geographic supply concentration clusters in Prague for premium technical talent, with secondary capacity distributed across Brno and Plzeň for specialized cleanroom and electronics manufacturing support. Raw material dependencies center on HVAC equipment imports from Germany, IoT sensor hardware from Chinese manufacturers, and refrigerants subject to EU F-Gas Regulation quota restrictions. Single-source vulnerability runs through F-Gas-certified technician pools constrained by sequential certification timelines. Distribution runs through direct vendor-client relationships for enterprise accounts, with regional specialists serving fragmented municipal and residential contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating across the Czech facility management market as German-owned automotive suppliers and pharmaceutical complexes consolidate multi-site contracts under single-provider accountability frameworks, compressing vendor margins while demanding outcome-based performance guarantees.
For Market Incumbents: Harden defensible positions by embedding CSRD-aligned building performance data services into existing contracts before competitors capture advisory revenue streams. Acquire F-Gas-certified technician capacity in Plzeň and Brno corridors to preempt service gaps as refrigerant phase-down accelerates. Deepen backward integration into energy management technology partnerships to offset margin compression from fixed-price maintenance agreements. For New Entrants and Emerging Players: Secondary Czech cities outside Prague's technical service cluster represent the most penetrable entry point, where localized responsiveness can displace fragmented providers serving municipal and residential contracts. Specialized cleanroom maintenance capabilities for pharmaceutical manufacturing in the Ústí nad Labem industrial zone offer white-space access with lower competitive density than Prague's saturated premium office segment. A certification-first go-to-market approach targeting BSI quality and environmental management credentials unlocks public institution tenders where incumbent qualification delays create temporary vendor pool gaps. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors regional specialists with established F-Gas compliance infrastructure and hybrid management advisory capabilities that can scale across EU Energy Performance of Buildings Directive retrofit cycles. Long-term viability hinges on exposure to outcome-based contract structures rather than commoditized cleaning and security volumes. The signal to watch is the pace of Czech industrial tenant migration from cost-based procurement to productivity-linked performance guarantees, which would revalue service provider multiples toward technology-enabled platforms.| Strategic Initiative | Industry Significance |
|---|---|
| CSRD Alignment Service Development | EU Corporate Sustainability Reporting Directive compliance creates verified building performance data revenue streams for advisory-capable providers. |
| F-Gas Certification Capacity Expansion | Technician credentialing for R-32 and CO2 refrigeration systems secures service continuity as EU quota reductions phase down hydrofluorocarbon alternatives. |
| Hybrid Management Advisory Integration | Strategic oversight retention by clients generates recurring advisory fees alongside outsourced technical execution margins. |
| Multi-Site Contract Consolidation | Single-provider accountability frameworks reduce vendor management overhead for German-owned automotive suppliers seeking parent-company operational symmetry. |
| Digital Twin Technology Deployment | Virtual building replicas enable predictive HVAC load simulation that collapses response times for thermal comfort complaints in Prague's premium office stock. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with facility management directors at pharmaceutical manufacturing complexes, procurement leads for German-owned automotive suppliers, BSI Czech Republic certification auditors, and Czech Ministry of Industry and Trade energy efficiency officers. Secondary validation drew from EU Energy Performance of Buildings Directive implementation tracking, F-Gas Regulation compliance databases, public procurement tender records, and SEC filings of listed multinational service platforms. Bottom-up contract value estimates were triangulated against top-down market sizing derived from building stock modernization budgets and outsourced service penetration rates.
Calibration against historical contract award patterns and regulatory implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass service type intensity, facility complexity tiers, management level control preferences, and technology adoption maturity. CAGRs were derived from fitted growth curves anchored to EU Green Deal retrofit mandates and pharmaceutical manufacturing expansion trajectories. Forecast inputs incorporated technician certification pipeline constraints and smart building sensor deployment rates in Prague's 1990s commercial stock.
Practitioners should monitor EU taxonomy alignment enforcement pace and F-Gas Regulation quota reduction schedules for early signals of contract scope expansion or service capacity constraints. Forecasts reflect assumptions regarding regulatory implementation continuity and industrial tenant outsourcing propensity. Cross-checking against Czech Statistical Office construction and modernization investment data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
North America Facilities Management Market
Facility Management
Poland Facility Management Market
Facility Management
Middle East and Africa Facility Management Market
Facility Management
Saudi Arabia Soft Facility Management Market
Facility Management
Africa Facility Management Market
Facility Management
Moldova Facility Management Market
Facility Management
Greece Facility Management Market
Facility Management
Germany Facility Management Market
Facility Management
Austria Facility Management Market
Facility Management
Warehouse Management Service Market
Facility Management
India Integrated Facility Management Market
Facility Management
Central and Eastern Europe (CEE) Facility Management Market
Facility Management
Qatar Facility Management Market
Facility Management
Nigeria Facility Management Services Market
Facility Management
Finland Facility Management Market
Facility Management
Albania Facility Management Market