
 Spain Residential Real Estate Market | 2026-2036
Spain Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Residential Real Estate Market Analytics
Energy-efficient certification upgrades is reorganizing buyer priorities across Spain's new-build segment. Metrovacesa leverages its land bank in Madrid to sustain premium positioning in the mid-range tier. Neinor Homes anchors its pipeline through in-house construction management, while AEDAS Homes differentiates via build-to-rent specialization in Barcelona and Valencia.
Spain residential real estate encompasses completed dwelling units—ranging from reinforced concrete-framed apartments to timber-structure detached houses—traded for owner occupation or rental income generation, with floor-area ratios and thermal envelope ratings now critical to mortgage eligibility and resale liquidity. Apartments dominate transaction volumes in Madrid and Barcelona, though villas command disproportionate margin pools along the Mediterranean coast. First-time buyers face structural constraint from deposit requirements, pushing investor participation upward in the affordable tier.
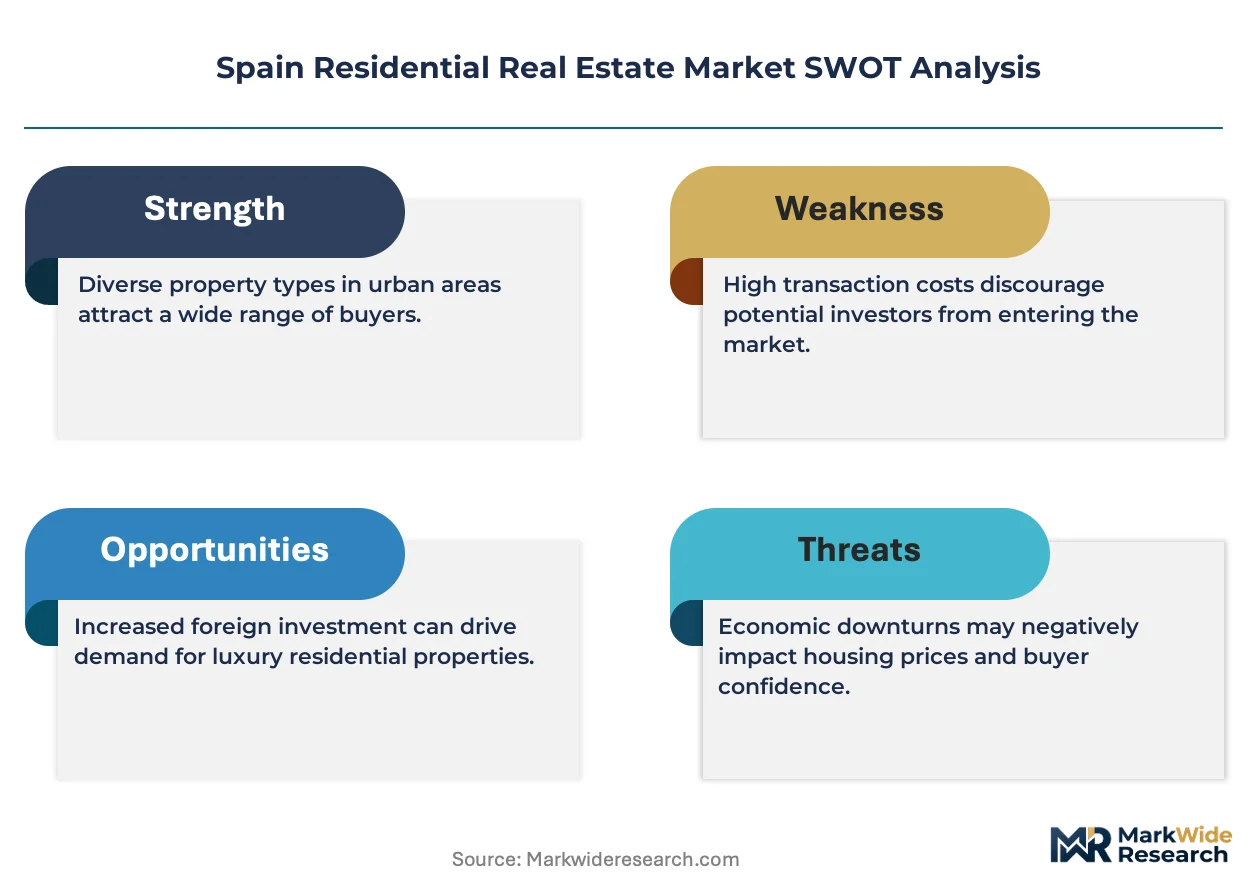
Spain's Ministry of Transport and Housing enforces the Technical Building Code, while the Bank of Spain supervises mortgage lending standards; both frameworks tighten capital allocation toward compliant, energy-efficient stock. Regional urban planning laws in Andalusia and Catalonia add further layers of zoning complexity that developers must navigate before project approval. Stakeholders should monitor how interest rate trajectories interact with these regulatory filters to determine which price tiers clear financing thresholds.
Market Dynamics
Spain's updated Technical Building Code is compressing development timelines while elevating capital requirements, forcing developers to front-load energy efficiency investments before securing mortgage-linked buyer financing.
Growth Catalysts
- Foreign retiree inflows:Northern European buyers concentrate property searches along the Costa del Sol, creating sustained demand for coastal villas and serviced apartments.
- Bank of Spain mortgage standards:Thermal envelope ratings now factor directly into loan eligibility, channeling capital toward compliant new-build stock.
- Build-to-rent specialization:Institutional capital targets Barcelona and Valencia for long-hold rental portfolios, absorbing construction risk from traditional developers.
Market Restraints
- Deposit requirements:First-time buyers face structural savings gaps that exclude them from owner-occupation tiers, capping demand elasticity.
- Regional zoning fragmentation:Andalusia and Catalonia maintain divergent urban planning laws that extend project approval timelines by 18-24 months.
- Construction input volatility:Reinforced concrete and glazing supply concentrates among Iberian producers exposed to energy cost pass-through.
Strategic Opportunities
- Madrid's northern corridor:Underdeveloped land parcels in Pozuelo and Las Rozas offer premium positioning for mid-range family housing.
- Energy certification arbitrage:Retrofit demand for existing stock lags new-build compliance, creating margin pools for renovation specialists.
- Timber-structure detached housing:Cross-laminated timber convergence with passive house standards opens coastal markets to lower-carbon alternatives.
Industry Challenges
- Project management talent scarcity:In-house construction capability gaps limit developer throughput despite land bank availability.
- Legacy system integration:Digital twin adoption for energy modeling conflicts with existing CAD workflows, delaying design finalization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Residential Real Estate Market |
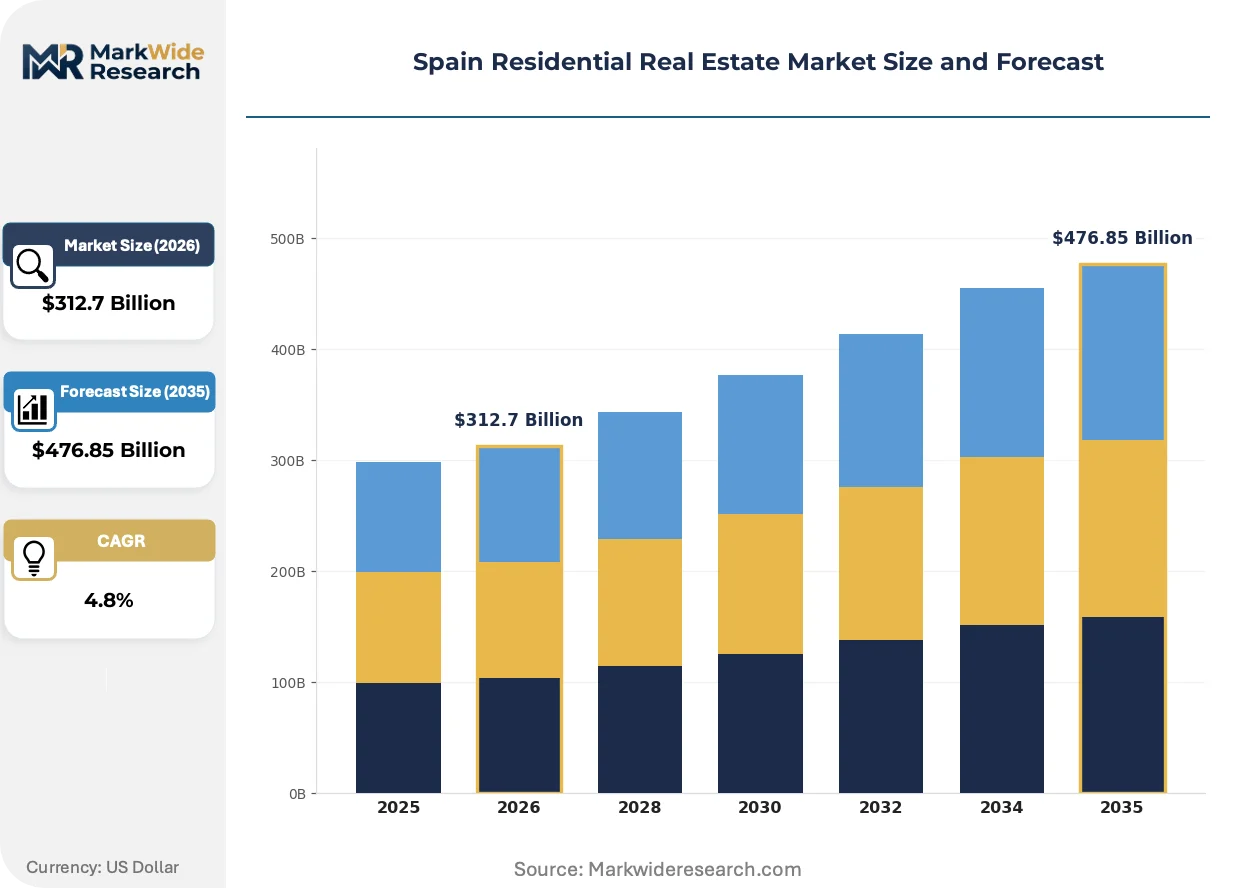
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $476.85 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Detached Houses, Townhouses, Apartments, Villas Price Tier: Luxury, Mid-range, Affordable, Budget Customer Type: First-time Buyers, Investors, Expats, Retirees Sales Channel: Online Platforms, Real Estate Agents, Auctions, Direct Sales |
| Companies Covered | Vía Célere, Realia Business, Neinor Homes, Culmia, Habitat Inmobiliaria, AEDAS Homes, Kronos Homes, Grupo Lar, Metrovacesa, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Residential Real Estate Market Evolving Landscape
Digital tools and regulatory mandates are compressing traditional development cycles while segmenting buyer access based on energy performance credentials rather than location alone.
Cross-laminated timber framing is decomposing the reinforced concrete monopoly in detached coastal construction. Passive house-certified buyers in Alicante and Málaga provinces are specifying timber structures for second homes. This material shift is decomposing margin structures for conventional concrete suppliers while enabling faster assembly timelines.
Spain's Technical Building Code mandates near-zero energy building standards for all new permits issued from 2026. Developers must integrate photovoltaic generation and heat recovery ventilation into standard specifications. Madrid and Barcelona metropolitan projects face the steepest compliance ramps, accelerating pre-permit land preparation.
Mortgage eligibility now hinges on energy performance certificates rather than solely loan-to-value ratios. Spanish banks are channeling preferential rates toward A-rated properties, compressing financing access for aging stock. This behavioral pivot concentrates buyer attention on new-build segments in Valencia and Seville.
Spain Residential Real Estate Market Segmentation
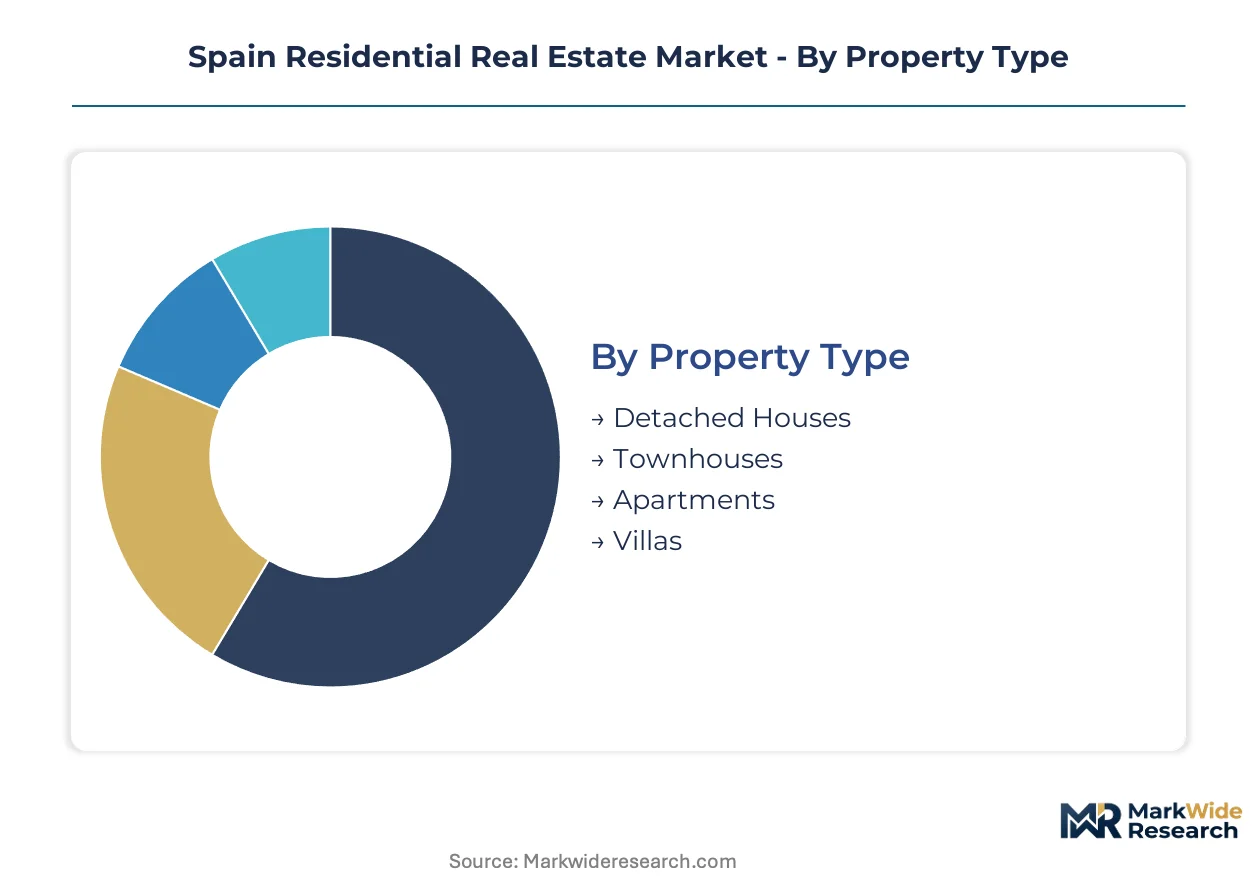
Spain's residential market fragments across property types and price tiers that respond differently to the Technical Building Code's energy mandates. Regulatory filters now determine financing access, resale velocity, and construction viability within each segment cluster.
Property Type:
Spain's Technical Building Code applies differentiated thermal envelope standards to structural typologies, with reinforced concrete apartments facing steeper retrofit obligations than timber-framed detached alternatives.
- Apartments:Reinforced concrete-framed units dominate transaction volumes in Madrid and Barcelona metropolitan rings. Bank of Spain mortgage standards channel preferential rates toward new-build apartments with A-rated energy certificates, compressing financing access for aging stock in central districts.
- Villas:Mediterranean coastal construction commands disproportionate margin pools along the Costa del Sol. Northern European retirees concentrate property searches in Málaga and Alicante provinces, sustaining premium pricing for detached units with passive house certification.
- Detached Houses:Timber-structure alternatives gain traction in Pozuelo and Las Rozas land parcels. Cross-laminated timber assembly enables faster construction timelines while meeting near-zero energy building standards.
- Townhouses:Mid-density typologies bridge urban accessibility with family-oriented floor plates in Barcelona's metropolitan ring.
Established volume favors apartments; emerging adoption favors villas.
Price Tier:
Deposit requirements and mortgage eligibility criteria stratify buyer access across cost bands, with energy performance ratings now determining financing tier rather than location alone.
- Mid-range:Family housing in Madrid's northern corridor concentrates Metrovacesa's land bank deployment. Thermal envelope compliance costs elevate capital requirements, squeezing developer margins while sustaining premium positioning.
- Affordable:First-time buyers face structural savings gaps that exclude owner-occupation tiers. Investor participation absorbs construction risk from traditional developers in Valencia and Seville build-to-rent pipelines.
- Luxury:Coastal villas in Andalusia attract institutional capital for long-hold rental portfolios.
- Budget:Aging stock in peripheral urban zones faces compressed resale liquidity under tightening energy certificate standards.
Mid-range supply dominates construction permits; affordable tier absorbs institutional capital flows.
Customer Type:
Buyer motivation and financing capacity diverge sharply across demographic segments, with regulatory frameworks favoring investor and expatriate profiles over domestic first-time purchasers.
- Investors:Institutional capital targets Barcelona and Valencia for build-to-rent specialization. Long-hold rental portfolios absorb construction risk while capturing yield compression from energy-efficient new stock.
- Retirees:Northern European buyers accelerate property purchases along the Costa del Sol. Serviced apartment demand concentrates in Málaga province, sustaining premium pricing for compliant new-build inventory.
- Expats:Non-resident purchasers navigate regional zoning fragmentation in Catalonia and Andalusia.
- First-time Buyers:Structural deposit requirements cap demand elasticity in Madrid and Barcelona metropolitan markets.
Investor capital dominates new-build absorption; retiree inflows sustain coastal premium tiers.
Sales Channel:
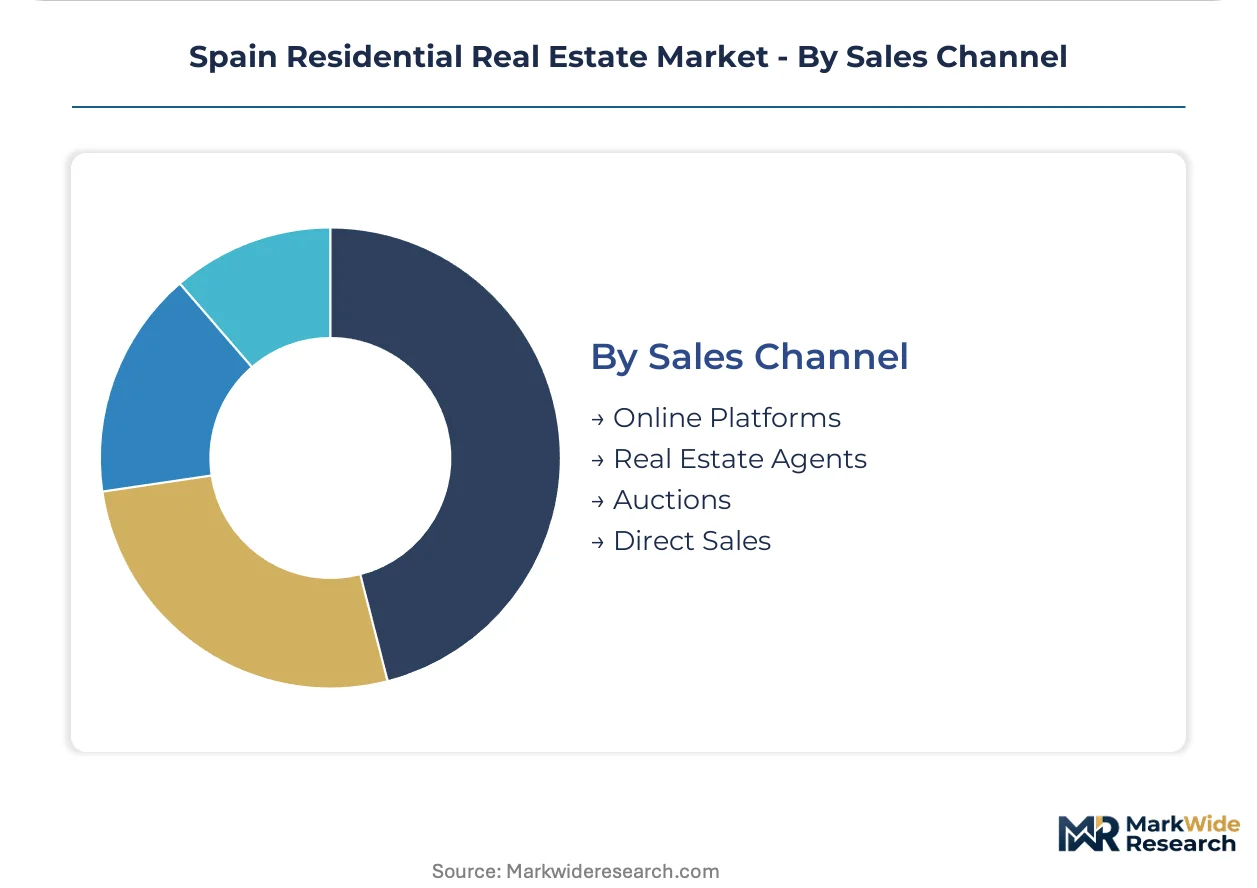
Digital platform adoption and regulatory disclosure requirements reshape transaction economics, with energy certificate transparency accelerating online platform penetration.
- Online Platforms:Digital marketplaces integrate energy performance data into search filters. Mortgage-linked buyer financing now hinges on certificate visibility, compressing discovery timelines for A-rated properties.
- Real Estate Agents:Traditional intermediaries navigate regional urban planning law complexity in Andalusia and Catalonia. Project approval timeline extensions of 18-24 months elevate advisory value for developer relationships.
- Direct Sales:Developer-owned channels capture margin from energy certification arbitrage in Madrid's northern corridor.
- Auctions:Distressed stock liquidation concentrates aging inventory with suboptimal thermal envelope ratings.
Online platforms gain share fastest in new-build segments; agent networks retain zoning complexity advisory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's residential real estate market exhibits pronounced regional asymmetries in capital flows, with coastal provinces attracting foreign currency inflows while interior metropolitan zones depend on domestic mortgage origination. Export-import dynamics manifest through Northern European retiree property purchases that function effectively as service exports, offsetting construction material import dependencies.
Madrid
Spain's capital concentrates institutional investment and corporate relocation demand in its northern corridor municipalities. The Technical Building Code enforcement by Spain's Ministry of Transport and Housing accelerates near-zero energy building permits in Pozuelo and Las Rozas, where Metrovacesa deploys land bank reserves for mid-range family housing.
Catalonia
Barcelona's metropolitan ring absorbs build-to-rent institutional capital targeting long-hold rental portfolios. Regional urban planning laws extend project approval timelines, yet AEDAS Homes specializes in compliant new-build pipelines across Barcelona and Valencia metropolitan zones.
Andalusia
Costa del Sol municipalities capture sustained Northern European retiree property searches in Málaga province. Passive house-certified villas command premium pricing pools, while serviced apartment demand concentrates in coastal sub-markets with thermal envelope compliance.
Valencia
Spain's eastern seaboard attracts yield-focused institutional capital for energy-efficient rental stock. The Bank of Spain's mortgage standards channel preferential rates toward A-rated new-build apartments, compressing financing access for aging inventory in peripheral urban zones.
Basque Country
Industrial employment density sustains owner-occupation demand in Bilbao and San Sebastián metropolitan areas. Timber-structure detached housing alternatives gain limited traction here compared to coastal markets, with reinforced concrete framing maintaining construction dominance.
Spain Residential Real Estate Market Competitive Landscape
Concentration sits with diversified developers holding integrated land banks and in-house construction management capabilities. Spain's residential development sector fragments across regional specialists and national platforms with varying exposure to energy compliance costs. Two strategic archetypes dominate: land-bank-heavy developers front-loading regulatory capital requirements, and build-to-rent operators absorbing construction risk through institutional partnerships. Competitive moves center on land bank accumulation in Madrid's northern corridor and vertical integration into construction management to compress development timelines.
Among Spain-based developers, Metrovacesa, Neinor Homes, and AEDAS Homes exemplify contrasting strategic positions. Metrovacesa occupies the land-bank-driven archetype with concentrated exposure to Madrid's premium mid-range tier. Neinor Homes represents the in-house construction management model, leveraging direct project control to navigate Technical Building Code compliance ramps. AEDAS Homes anchors the build-to-rent specialization vector, targeting Barcelona and Valencia for institutional rental portfolio absorption.
| Leading Market Players |
|---|
| Vía Célere |
| Realia Business |
| Neinor Homes |
| Culmia |
| Habitat Inmobiliaria |
| AEDAS Homes |
| Kronos Homes |
| Grupo Lar |
| Metrovacesa |
| Others |
Value Network & Pricing Analysis
Eighteen-to-twenty-four month project approval timelines in Andalusia and Catalonia compress developer working capital cycles while elevating carrying costs, concentrating pricing power with land-bank-heavy developers who can front-load regulatory capital requirements.
Pricing Analysis
Foreign retirees from Northern Europe anchor premium pricing for Costa del Sol villas with passive house certification. Pricing stratifies across A-rated new-build apartments, compliant mid-range family housing, and aging peripheral stock facing compressed resale liquidity. Cost compression in the budget tier is intensifying because mortgage eligibility now hinges on energy performance certificates rather than solely location. First-time buyers exhibit highest price sensitivity due to structural deposit requirements, while institutional investors in build-to-rent pipelines demonstrate lowest sensitivity.
Supply Chain Analysis
Reinforced concrete and glazing inventory concentrates among Iberian producers exposed to energy cost pass-through, with cross-laminated timber alternatives emerging from Austrian and Scandinavian suppliers. Construction input volatility draws from concrete supply concentration, glazing energy intensity, and timber import dependencies. Single-source vulnerability sits with domestic concrete producers facing electricity price spikes. Distribution runs through developer-owned direct sales channels in Madrid's northern corridor and real estate agent networks navigating regional zoning complexity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Property management and energy certification advisory services expand faster than dwelling unit sales, creating service-attach opportunities for developers repositioning around recurring revenue streams.
For Market Incumbents: Shield land bank value through accelerated permitting in Madrid's northern corridor municipalities. Prioritize in-house construction management capability to compress eighteen-to-twenty-four month approval timelines. Defensive consolidation should target renovation specialists capturing margin pools from energy certification arbitrage in aging stock.
For New Entrants and Emerging Players: Passive house certification fast-tracks entry into Málaga and Alicante province coastal markets where Northern European retirees concentrate property searches. White-space targets include timber-structure detached housing in Pozuelo and Las Rozas, plus retrofit demand for existing stock in peripheral urban zones. Go-to-market positioning should emphasize mortgage-linked financing partnerships with Spanish banks channeling preferential rates toward A-rated properties.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified conglomerates with non-core residential development assets in Barcelona and Valencia metropolitan rings. Long-term viability favors build-to-rent operators with institutional capital partnerships absorbing construction risk. Monitor Bank of Spain mortgage standard adjustments as the inflection indicator for capital flow redirection between new-build and aging stock tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Land Bank Accumulation | Metrovacesa deploys Pozuelo and Las Rozas reserves to sustain premium mid-range positioning. |
| In-House Construction Management | Neinor Homes leverages direct project control to navigate Technical Building Code compliance ramps. |
| Build-to-Rent Specialization | AEDAS Homes targets Barcelona and Valencia for institutional rental portfolio absorption. |
| Energy Certification Arbitrage | Retrofit specialists capture margin pools from thermal envelope upgrade demand in aging stock. |
| Timber Structure Adoption | Cross-laminated timber enables faster assembly timelines while meeting near-zero energy building standards. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary validation across regulatory and transaction databases. Primary interviews encompassed land acquisition directors at Madrid-based developers, construction project managers navigating Technical Building Code compliance, mortgage lending officers at Spanish banks, and regional urban planning officials in Andalusia and Catalonia. Secondary sources included Bank of Spain mortgage origination reports, Spain's Ministry of Transport and Housing permitting databases, property transaction registries, and energy certificate issuance records. Bottom-up project pipeline enumeration triangulated against top-down metropolitan market sizing.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmented demand decomposition. Segmentation dimensions encompassed property type, price tier, customer motivation, and sales channel, with energy performance rating integration as a cross-cutting filter. CAGRs were derived from permit issuance velocity, foreign transaction share trends, and mortgage origination patterns. Industry-specific inputs included Northern European retiree inflow projections and Technical Building Code implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained foreign capital inflows or interest rate stability would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and construction input cost trajectories. Specific risks that could revise projections include abrupt mortgage standard tightening, regional zoning law fragmentation escalation, or energy cost volatility disrupting material supply. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
Residential Real Estate Market
Residential Real Estate Market
France Manufactured Homes Market
Residential Real Estate Market
Germany Manufactured Homes Market
Residential Real Estate Market
United States Residential Real Estate Market
Residential Real Estate Market
Armenia Real Estate Market
Residential Real Estate Market
Japan Manufactured Homes Market
Residential Real Estate Market
India Residential Construction Market
Residential Real Estate Market
Online Home Rental Market
Residential Real Estate Market
Europe Residential Real Estate Market
Residential Real Estate Market
Global Manufactured Housing Market
Residential Real Estate Market
United States Real Estate Brokerage Market
Residential Real Estate Market
US E-House Market
Residential Real Estate Market
Real Estate Market
Residential Real Estate Market
North America Tiny Homes Market
Residential Real Estate Market
Latin America Residential Real Estate Market
Residential Real Estate Market
Indonesia Real Estate Market