
 United Arab Emirates Real Estate Services Market | 2026-2036
United Arab Emirates Real Estate Services Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Real Estate Services Market Analytics
The off-plan sales channel is narrowing as RERA-imposed escrow requirements and completion-risk assessments filter speculative capital toward established developers. Emaar Properties leverages its integrated master-developer model to control land banks and construction timelines across Dubai's premium districts. Aldar Properties anchors Abu Dhabi's supply pipeline through government-linked land allocations and large-scale community planning. DAMAC Properties competes on design-led positioning in the luxury segment, differentiating through branded residential partnerships and golf course adjacencies.
Real estate services in the United Arab Emirates encompass property management, brokerage, valuation, and facilities management delivered across residential, commercial, industrial, and mixed-use assets. These services coordinate transaction execution, asset oversight, and regulatory compliance within a market where freehold ownership rights apply to designated zones and lease structures vary by emirate. Property management and facilities management command the most stable fee streams as recurring service contracts outlast transaction cycles. Brokerage services face margin compression where digital listing platforms disintermediate traditional agent roles in standard residential leasing. Mixed-use developments generate cross-service bundling opportunities as single assets require simultaneous management of retail, hospitality, and residential components.
RERA Dubai and the Abu Dhabi Department of Municipalities and Transport enforce escrow mandates, completion guarantees, and broker licensing standards that elevate barriers for undercapitalized operators. MOHAP and local municipality building codes shape material specifications, sustainability thresholds, and safety protocols for new construction and retrofits. Stakeholders must monitor escrow regulation tightening and green building mandate expansion as these frameworks determine which developers and service providers retain market access.
Market Dynamics
Escrow mandate tightening under RERA Dubai is compressing speculative capital flows and concentrating transaction volumes toward established master-developers with proven completion track records.
Growth Catalysts
- Ultra-high-net-worth capital inflows:Luxury residential developments in prime waterfront and golf course communities attract sustained international investment as supply tightens in established precincts.
- RERA escrow account frameworks:Updated regulations elevate developer accountability and reshape buyer confidence through enforced completion guarantees and fund segregation protocols.
- Integrated mixed-use asset expansion:Single developments combining retail, hospitality, and residential components generate bundled service contracts spanning property management, facilities management, and brokerage.
Market Restraints
- Escrow compliance capital intensity:RERA-mandated fund segregation and completion guarantees require substantial liquidity reserves that strain undercapitalized developers.
- Brokerage margin compression:Digital listing platforms disintermediate traditional agent roles in standard residential leasing, eroding fee structures.
- Supply concentration in prime districts:Land bank control by integrated master-developers limits market entry for independent operators seeking premium positioning.
Strategic Opportunities
- Facilities management contract expansion:Recurring service agreements for mixed-use assets outlast transaction cycles and stabilize revenue streams across market volatility.
- Green building mandate alignment:MOHAP and local municipality sustainability thresholds create differentiation pathways for service providers with certified retrofit capabilities.
- Valuation services digitization:Automated assessment tools integrated with property management platforms compress turnaround times for institutional portfolio reviews.
Industry Challenges
- Licensed broker talent scarcity:RERA licensing standards elevate qualification barriers while demand for compliant transaction execution outpaces certified professional supply.
- Cross-service integration complexity:Coordinating simultaneous retail, hospitality, and residential management within single mixed-use assets strains legacy operational frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Real Estate Services Market |
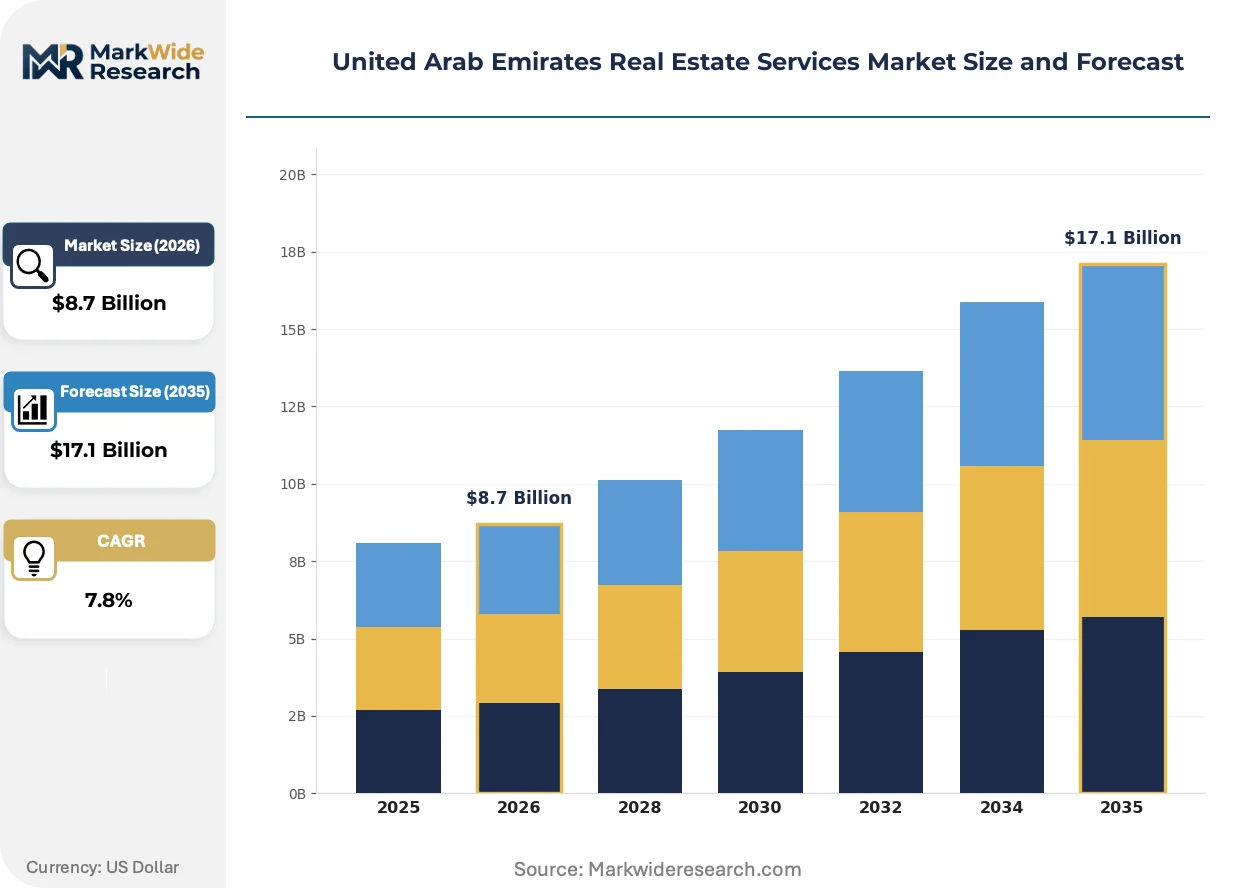
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Property Management, Brokerage Services, Valuation Services, Facilities Management Client Type: Individuals, Corporates, Investors, Government Entities Property Type: Residential, Commercial, Industrial, Mixed-Use Transaction Type: Sales, Leasing, Rentals, Investment |
| Companies Covered | Emaar Properties, Aldar Properties, DAMAC Properties, Nakheel, Dubai Properties, Meraas, Sobha Realty, CBRE Group Inc., Jones Lang LaSalle Incorporated (JLL), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Real Estate Services Market Evolving Landscape
Digital platforms and regulatory digitization are restructuring how property services are delivered, priced, and consumed across the Emirates.
Blockchain-enabled transaction registries are collapsing the due diligence timeline for off-plan purchases. Institutional buyers and sovereign wealth vehicles now demand immutable title verification before escrow release. This compression is eliminating intermediary layers that previously managed document authentication and fund flow coordination.
MOHAP building codes and local municipality green certification mandates are accelerating retrofit specifications for existing commercial stock. Property managers must coordinate material upgrades, energy monitoring installation, and compliance documentation across aging assets. Service providers with integrated sustainability auditing capabilities capture premium positioning in government-linked portfolios.
Institutional landlords are unbundling property management from facilities management to optimize cost allocation across asset classes. Separate contracting for mechanical systems oversight, tenant relations, and capital planning replaces bundled agreements. This segmentation is most visible in Dubai's commercial office and industrial warehouse segments where REIT structures demand granular expense visibility.
United Arab Emirates Real Estate Services Market Segmentation
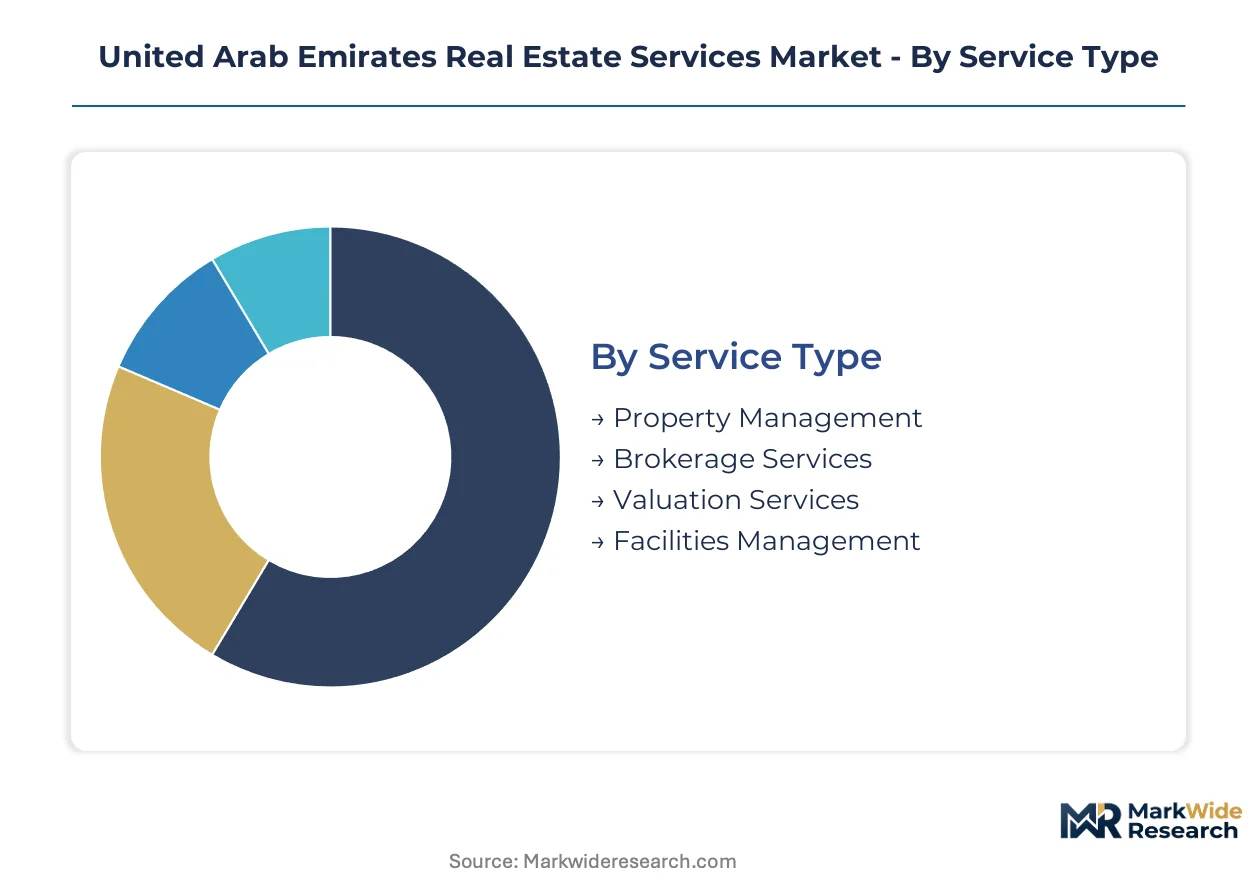
Segmentation in the UAE real estate services market reveals distinct operational rhythms and margin structures. Service type determines contract duration and revenue predictability. Client type shapes fee sensitivity and relationship complexity. Property type and transaction type dictate regulatory exposure and capital intensity.
Service Type:
Cycle times vary dramatically across service categories, with recurring contracts outlasting transactional engagements by multiples.
- Property Management:Long-term asset oversight contracts spanning residential, commercial, and mixed-use portfolios. Demand concentrates in Dubai's master-planned communities where Emaar and Nakheel retain captive property management arms, though third-party operators penetrate aging stock in older precincts.
- Facilities Management:Mechanical, electrical, and building systems maintenance delivered through multi-year service agreements. Abu Dhabi's government-linked portfolios and Dubai's REIT-structured commercial assets drive procurement standardization, with green retrofit mandates accelerating technical specialization requirements.
- Brokerage Services:Transaction facilitation for sales and leasing across residential and commercial segments. Digital platform penetration compresses margins in standard residential leasing while off-plan sales and ultra-luxury transactions preserve fee premiums.
- Valuation Services:Asset appraisal for financing, investment, and regulatory compliance. Institutional portfolio reviews and RERA-mandated escrow assessments sustain demand despite automation pressure on routine residential valuations.
Property management anchors the volume base while facilities management gains share at the steepest rate.
Client Type:
Fee structures and contract terms diverge sharply based on procurement sophistication and scale.
- Corporates:Multi-asset service agreements with standardized SLAs and centralized procurement. Dubai International Financial Centre and Abu Dhabi Global Market tenants drive bundled property and facilities management contracts with granular reporting requirements.
- Investors:Sovereign wealth vehicles, family offices, and institutional funds requiring portfolio-level oversight. Cross-border capital deployment into prime Dubai waterfront assets generates demand for integrated valuation, management, and transaction execution.
- Government Entities:Abu Dhabi Department of Municipalities and Transport and Dubai Land Department-linked portfolios with mandated sustainability compliance. Green building retrofit specifications and escrow oversight requirements elevate technical qualification barriers.
- Individuals:Fragmented demand for residential leasing, sales, and single-asset management. Digital disintermediation reduces fee capture in standard transactions while high-net-worth individuals in prime districts sustain premium brokerage margins.
Corporates dominate contract value while government entities are expanding most quickly under mandate-driven procurement.
Property Type:
Asset complexity determines service bundling requirements and margin profiles across the Emirates.
- Mixed-Use:Integrated retail, hospitality, and residential components requiring simultaneous management of divergent operational rhythms. Dubai's Downtown and Bluewaters Island developments generate cross-service contracts spanning property management, facilities oversight, and retail leasing coordination.
- Commercial:Office and retail assets with REIT-driven expense visibility demands. Dubai's commercial office segment sees unbundling of property management from facilities management as institutional landlords optimize cost allocation.
- Residential:Freehold apartments and villas across Dubai's designated zones and Abu Dhabi's investment areas. Prime waterfront and golf course communities concentrate ultra-high-net-worth demand as supply tightens in established precincts.
- Industrial:Warehousing and logistics facilities serving trade and e-commerce flows. Jebel Ali and KIZAD anchor industrial service demand with specialized facilities management for temperature-controlled and hazardous material storage.
Residential commands the widest service provider footprint while mixed-use climbs the fastest on development pipeline expansion.
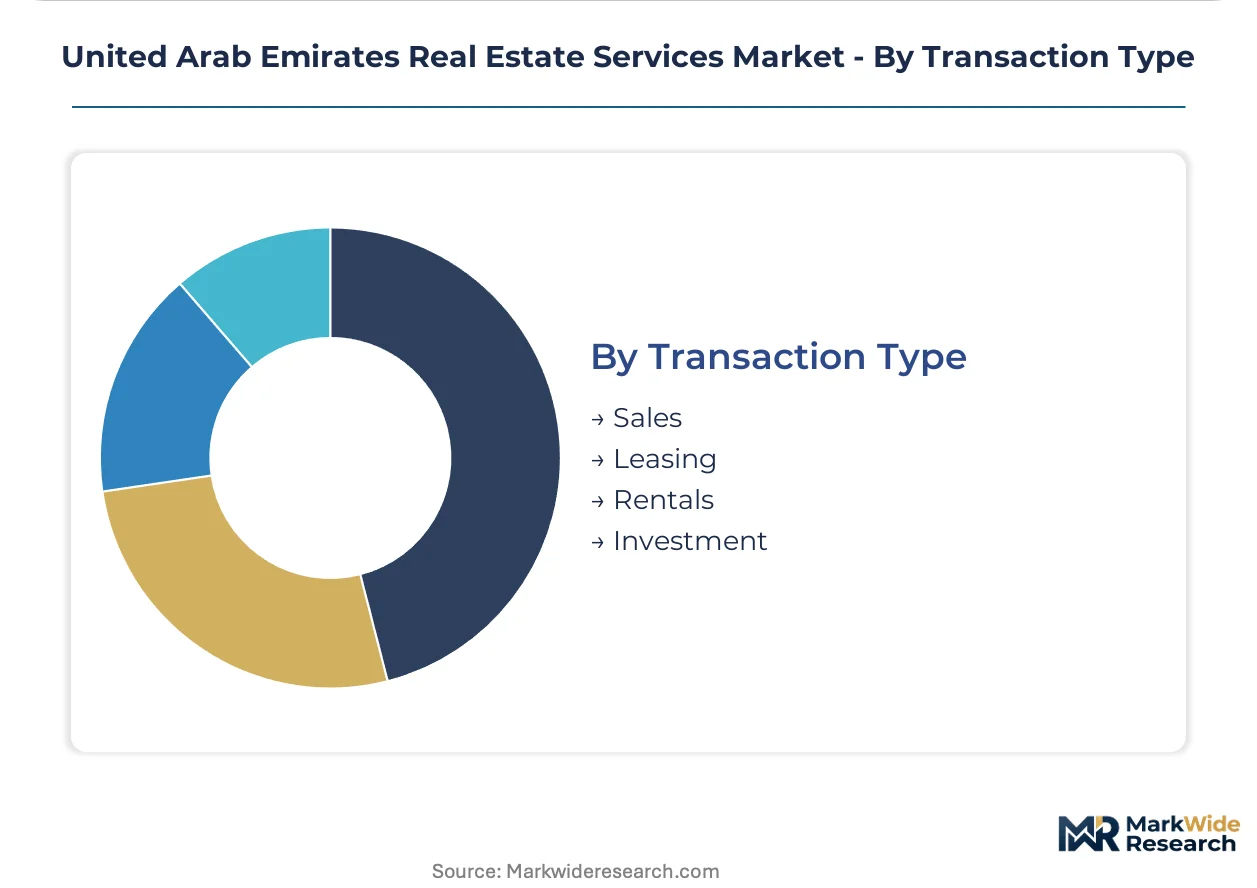
Transaction Type:
Regulatory intensity and capital commitment duration vary across transaction modalities.
- Sales:Freehold transfers and off-plan purchases subject to RERA escrow mandates and completion guarantees. Dubai's updated escrow regulations filter speculative capital toward established developers with proven track records.
- Leasing:Commercial and residential tenancy agreements with regulatory registration requirements. Standard residential leasing faces digital platform disintermediation while commercial leases retain broker involvement for complex term negotiations.
- Rentals:Short-term and holiday home lettings governed by Dubai Tourism and Abu Dhabi Department of Culture and Tourism licensing. Regulatory tightening on unlicensed operators concentrates volume toward compliant property management platforms.
- Investment:Portfolio acquisitions, development financing, and structured real estate vehicles. Valuation and due diligence services cluster around institutional capital deployment into income-generating commercial assets.
Leasing sustains the highest transaction frequency while investment transactions show the steepest fee expansion on institutional capital inflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai commands premium pricing power through waterfront scarcity and master-developer concentration, while Abu Dhabi's government-linked allocations sustain volume pipelines at compressed margins. Sharjah and the Northern Emirates compete on affordability thresholds, drawing mid-market residential demand from cost-sensitive segments. Pricing asymmetry between emirates reflects divergent land release policies and foreign ownership frameworks.
Dubai
Prime waterfront and golf course communities attract sustained ultra-high-net-worth capital as supply tightens in established precincts. RERA Dubai enforces escrow account mandates and completion guarantees that filter speculative capital toward Emaar Properties and Nakheel. Downtown Dubai and Bluewaters Island anchor mixed-use development pipelines generating bundled property management and facilities management contracts.
Abu Dhabi
Government-linked land allocations through Aldar Properties sustain large-scale community planning across Yas Island and Saadiyat Island. The Department of Municipalities and Transport mandates green building retrofit specifications for aging commercial stock. Al Reem Island and Al Maryah Island concentrate institutional-grade office assets demanding unbundled property and facilities management procurement.
Sharjah
Affordable freehold zones in Aljada and Tilal City draw mid-market residential demand from Dubai spillover. The Sharjah Real Estate Registration Directorate maintains stricter ownership eligibility criteria than RERA Dubai. Industrial zones around Hamriyah Free Zone generate specialized facilities management demand for warehousing and logistics assets.
Northern Emirates
Ras Al Khaimah's hospitality-led developments around Al Marjan Island attract second-home buyers seeking beachfront accessibility at discount-to-Dubai pricing. Ajman and Umm Al Quwain compete on transaction cost minimization with lower registration fees and service charges. Fujairah's port-linked industrial corridor sustains niche demand for temperature-controlled storage facilities management.
United Arab Emirates Real Estate Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fragmented niches. The UAE real estate services market structures around integrated master-developers controlling land banks and construction timelines, with third-party service providers competing for outsourcing contracts on aging stock. Two strategic archetypes dominate: captive service arms of major developers, and independent operators with certified retrofit capabilities. Competitive moves concentrate on facilities management contract consolidation and green building mandate alignment.
Within the integrated master-developer tier, Emaar Properties and Aldar Properties exemplify platform control through land bank dominance and captive service integration. DAMAC Properties occupies a design-led positioning archetype, differentiating through branded residential partnerships. Among third-party service providers, CBRE Group Inc. and Jones Lang LaSalle Incorporated anchor the institutional advisory segment, competing for portfolio-level mandates from sovereign wealth vehicles and cross-border capital deployers.
| Leading Market Players |
|---|
| Emaar Properties |
| Aldar Properties |
| DAMAC Properties |
| Nakheel |
| Dubai Properties |
| Meraas |
| Sobha Realty |
| CBRE Group Inc. |
| Jones Lang LaSalle Incorporated (JLL) |
| Others |
Value Network & Pricing Analysis
Master-developer land bank concentration in Dubai and Abu Dhabi funnels margin pools toward captive service arms, compressing third-party operator pricing power in prime precincts while elevating fee premiums for certified retrofit specialists in aging commercial stock.
Pricing Analysis
Configured-to-order pricing for integrated mixed-use management contracts commands substantial premiums over standardized residential brokerage fees. Three-tier pricing structure across premium, standard, and economy levels separates Emaar-captive master community management from independent operator bids on older Dubai precincts and Sharjah mid-market assets. Pricing pressure stems from digital platform disintermediation in standard residential leasing, eroding traditional agent margins. Institutional landlords in Dubai International Financial Centre exhibit lowest price sensitivity due to REIT-mandated service level requirements, while individual investors in Northern Emirates show highest sensitivity to transaction cost differentials.
Supply Chain Analysis
Extended payment terms from government-linked portfolios in Abu Dhabi and supply-chain finance facilities through Dubai REIT structures shape working capital requirements for service providers. Skilled facilities management labor draws from India, Philippines, and Pakistan, while specialized green building certification expertise rests on European and Australian training pipelines. Raw material dependencies include HVAC equipment from China, building automation systems from Germany and USA, and sustainable retrofit materials from regional GCC manufacturers. Single-source vulnerability concentrates in advanced energy monitoring hardware. Distribution runs through master-developer captive networks in prime Dubai districts and third-party procurement consortia in commercial office segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
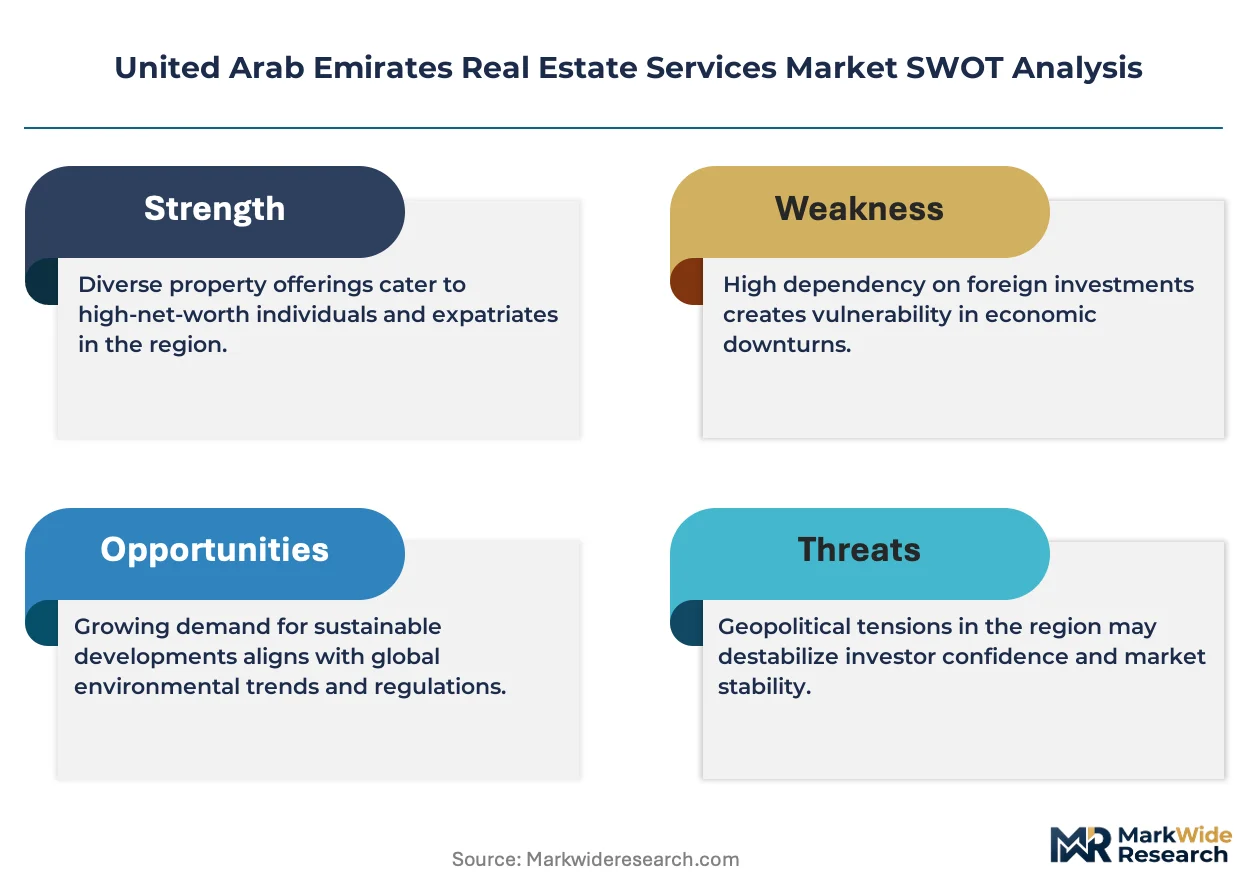
RERA-licensed broker scarcity and green building retrofit technical gaps create asymmetric returns for operators bridging qualification barriers, while digital platform proliferation threatens traditional fee structures in commoditized segments.
For Market Incumbents: Insulate recurring revenue streams through multi-year facilities management contract extensions with Abu Dhabi government portfolios and Dubai REIT-structured assets. Deepen captive service integration into master-developer land bank pipelines to preempt third-party penetration. Certification investment in MOHAP-mandated sustainability auditing capabilities defends margin position against specialized retrofit entrants. For New Entrants and Emerging Players: Mid-market commercial buildings in Sharjah and aging residential stock in Dubai's older precincts represent the most penetrable entry point for third-party property management operators. Specialized green retrofit coordination for government-mandated compliance deadlines offers immediate contract visibility. Direct procurement relationships with Dubai Land Department-registered valuation panels provide go-to-market credibility without master-developer affiliation. For Investors and Strategic Acquirers: Capital is best deployed toward certified facilities management specialists with MOHAP sustainability credentials and established government contract track records. Long-term viability across the analysis window favors operators with recurring revenue concentration over transaction-dependent brokerage exposure. The signal to watch is RERA escrow regulation expansion into secondary emirates, which would replicate Dubai's developer consolidation dynamics and elevate compliant service provider valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Green Building Certification Investment | MOHAP-mandated retrofit deadlines in Abu Dhabi create premium positioning for certified operators. |
| RERA Licensing Scale-Up | Broker qualification barriers filter speculative entrants and protect compliant transaction volumes. |
| Mixed-Use Service Bundling | Downtown Dubai and Bluewaters Island developments demand simultaneous retail, hospitality, and residential coordination. |
| Digital Platform Integration | Blockchain-enabled transaction registries collapse due diligence timelines for institutional off-plan buyers. |
| Government Contract Procurement | Department of Municipalities and Transport-linked portfolios sustain volume pipelines through mandate-driven procurement. |
Research Methodology
Desk research of RERA regulatory filings, Dubai Land Department transaction records, and MOHAP building code specifications preceded structured interviews with property management directors, facilities management procurement leads, RERA-licensed brokers, and institutional landlord portfolio managers. Primary fieldwork combined with secondary validation against Abu Dhabi Department of Municipalities and Transport procurement databases, escrow account regulatory frameworks, and master-developer annual disclosures. Bottom-up service provider revenue estimates triangulated against top-down market size calculations derived from transaction volume and fee structure analysis.
Assumption sets held RERA regulatory enforcement intensity and MOHAP green building mandate timelines fixed across the projection horizon, while varying ultra-high-net-worth capital flow estimates and digital platform penetration rates. Segmentation dimensions modeled include service type, client procurement sophistication, property complexity tier, and emirate-level regulatory framework. CAGRs derived from historical transaction volume trajectories and service fee evolution patterns, incorporating mixed-use development pipeline schedules and government land release policies as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in oil price volatility, regional geopolitical stability, or interest rate trajectories would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and capital flow sustainability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
Home Warranty Service Market
Real Estate Services
US Home Service Market
Real Estate Services
Thailand Real Estate Market
Real Estate Services
Warehousing and Storage Services Market
Real Estate Services
Public Warehousing Market
Real Estate Services
Asia-Pacific Real Estate Brokerage Market
Real Estate Services
Co-Working Space Services Market
Real Estate Services
United States Self Storage Market
Real Estate Services
US Real Estate and Hospitality Market
Real Estate Services
Relocation Management Service Market
Real Estate Services
Property Tax Services Market
Real Estate Services
Warehousing Services Market
Real Estate Services
Latin America Coworking Spaces Market
Real Estate Services
Switzerland Self-Storage Market
Real Estate Services
Second-Hand Housing Trading Platform Market
Real Estate Services
Canada Real Estate Services Market