
 Indonesia Commercial Real Estate Market | 2026-2036
Indonesia Commercial Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Commercial Real Estate Market Foresight
Modular lease packaging with built-in fit-out and facility management bundles is restructuring tenant decision-making in Indonesian commercial property. Ciputra Group leverages its township development expertise to anchor mixed-use portfolios across secondary cities. Sinar Mas Land competes through integrated logistics park designs that combine warehousing with cold-chain infrastructure. Pakuwon Jati specializes in retail-led mixed-use complexes that dominate Surabaya's commercial landscape.
Indonesia commercial real estate comprises income-generating properties including office towers, retail centers, industrial estates, and hospitality assets, typically structured through strata titles, long-term leases (HGB), or build-to-suit arrangements with floor plates exceeding 2,000 square meters for modern logistics facilities. Office and logistics segments lead transaction velocity as institutional capital pursues yield compression in Jakarta's CBD fringe and Bekasi-Cikarang industrial corridors. Retail maintains defensive cash flow in tier-one malls but faces margin pressure from e-commerce penetration, while hospitality recovery tracks international visitor return patterns to Bali and Jakarta.
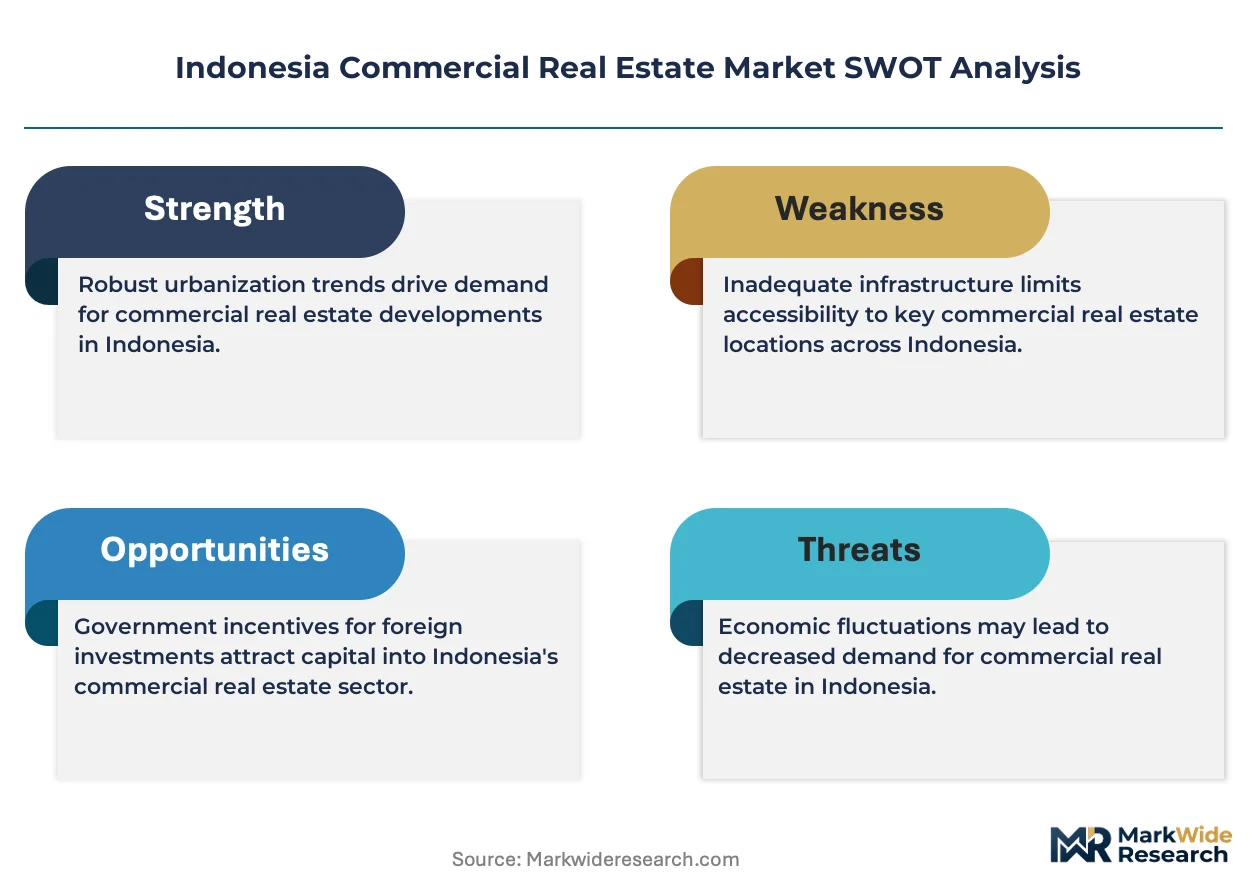
Indonesia's Omnibus Law on Job Creation, administered by the Ministry of Agrarian Affairs and Spatial Planning, accelerated land-use conversion permits for industrial zones. BSI (Indonesian National Standard) building codes and regional spatial plans (RTRW) enforced by provincial governments dictate density bonuses and green building thresholds that shape development feasibility. Stakeholders must monitor regulatory enforcement consistency across provincial boundaries and assess how upcoming tax incentive revisions for REIT structures alter capital formation channels.
Market Dynamics
E-commerce fulfillment networks are compressing warehouse absorption timelines across Java's logistics corridors, forcing developers to accelerate speculative construction ahead of tenant commitment.
Growth Catalysts
- Omnibus Law on Job Creation:The Ministry of Agrarian Affairs streamlined land-use conversion permits for industrial zones, cutting approval timelines for Bekasi-Cikarang corridor projects.
- Cold-chain infrastructure:Food and pharmaceutical distributors are driving demand for temperature-controlled warehousing in Greater Jakarta's peripheral districts.
- Surabaya industrial zones:Manufacturing relocation from saturated Java markets is accelerating absorption in East Java's emerging logistics parks.
Market Restraints
- Land banking concentration:Five developer groups control prime industrial land parcels in Jakarta's buffer zones, limiting entry for new institutional investors.
- Building material volatility:Steel rebar and cement price fluctuations compress development margins on fixed-price construction contracts.
- Spatial plan misalignment:Provincial RTRW regulations in Banten and West Java create permitting friction for cross-border logistics corridor development.
Strategic Opportunities
- Secondary city expansion:Makassar and Medan offer undeveloped industrial land at 40% below Jakarta fringe valuations for regional distribution centers.
- REIT structure optimization:Pending tax incentive revisions for real estate investment trusts could unlock institutional capital formation channels.
- Green building certification:BSI building codes mandating energy efficiency thresholds create first-mover advantages for LEED-equivalent warehouse stock.
Industry Challenges
- Construction talent scarcity:Qualified project managers with industrial facility expertise command premium wages that inflate development overhead.
- Legacy title fragmentation:HGB leasehold conversions from inherited agricultural parcels require costly notarial reconciliation before financing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Commercial Real Estate Market |
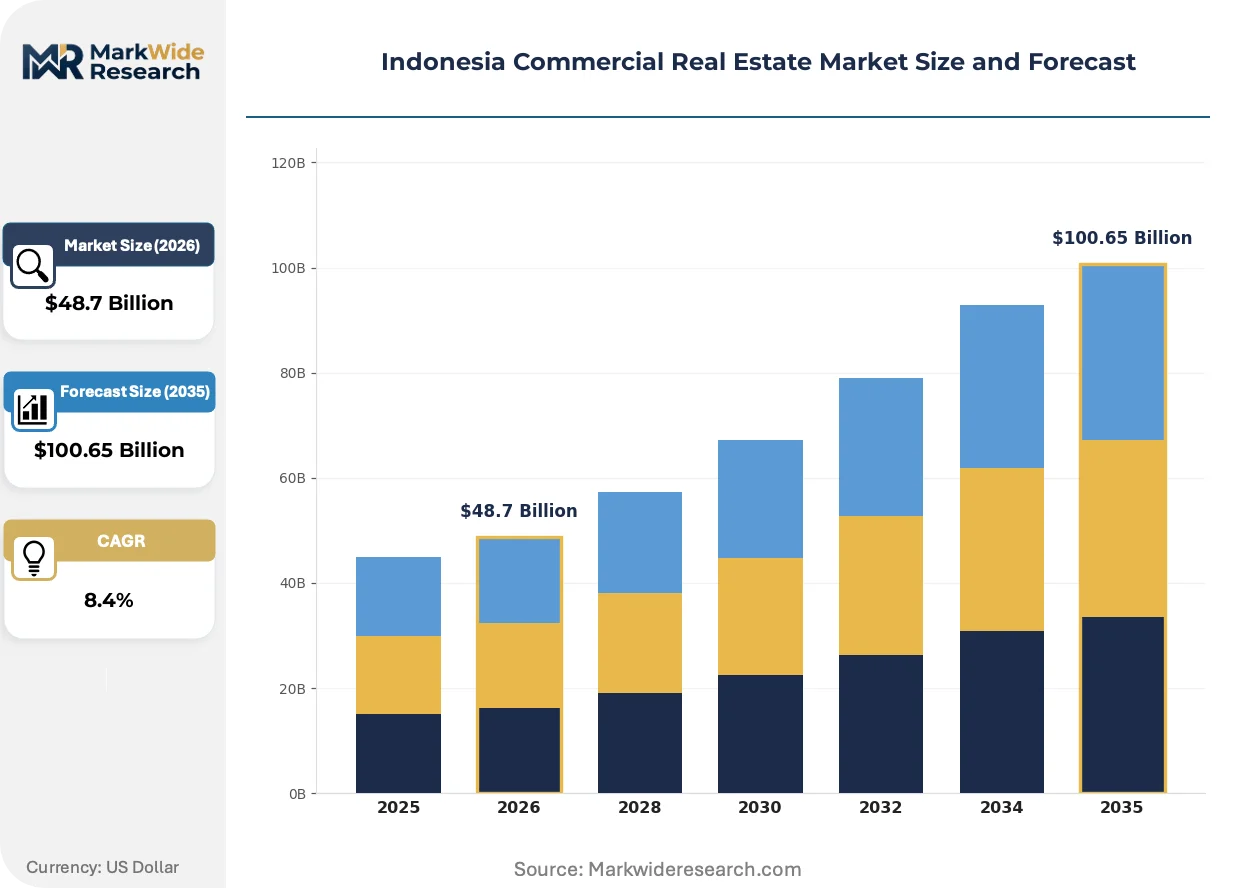
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Office, Retail, Industrial, Hospitality Investment Strategy: Core, Value-add, Opportunistic, Development Client Type: Institutional Investors, High-net-worth Individuals, REITs, Foreign Investors Market Sector: Commercial, Mixed-use, Co-working, Logistics |
| Companies Covered | Agung Podomoro Land, Ciputra Group, Lippo Group, Sinar Mas Land, RDTX Group, PP Properti, Summarecon Agung, Alam Sutera Realty, Pakuwon Jati, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Commercial Real Estate Market Shifts & Advancements
Built-to-suit development models are displacing speculative construction as tenant requirements for specialized configurations tighten. Three forces are compressing traditional development cycles.
Prefabricated steel frame systems are modularizing warehouse construction timelines. Third-party logistics operators in the pharmaceutical cold-chain segment are specifying these systems for rapid deployment. The technology is modularizing developer risk profiles by compressing pre-lease commitment windows from eighteen to six months.
Indonesia's Omnibus Law on Job Creation introduced centralized environmental permitting through the Ministry of Environment and Forestry. Industrial estate developers now face consolidated impact assessments rather than fragmented provincial approvals. The policy shift most affects greenfield logistics parks in Central Java, where developers are front-loading biodiversity offset commitments to accelerate groundbreaking.
Tenant decision-making is consolidating around integrated facility management bundles. Retail-led mixed-use operators in Surabaya are displacing standalone lease negotiations with packaged fit-out and maintenance contracts. This bundling pattern concentrates most visibly in Surabaya's commercial districts, where Pakuwon Jati anchors tenant retention through captive service provision.
Indonesia Commercial Real Estate Market Segmentation
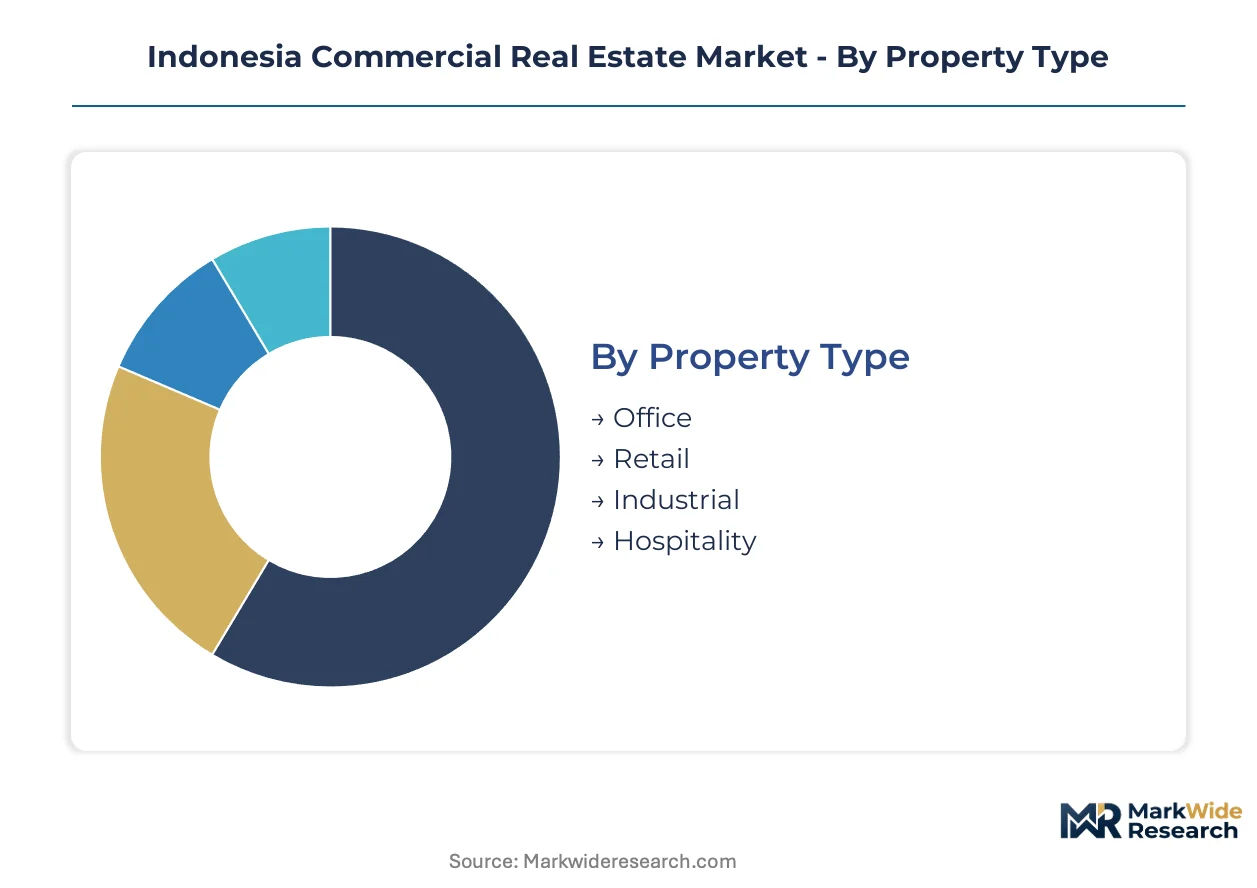
Segmentation in Indonesian commercial real estate reveals how capital formation channels, tenant requirements, and regulatory frameworks diverge across asset classes. Investment strategy and client type distinctions determine which projects secure financing and which face prolonged capital deployment timelines.
Property Type:
Capital intensity varies dramatically across these four asset classes, with industrial and hospitality requiring the heaviest upfront infrastructure investment while office and retail balance initial outlay against recurring income stability.
- Office:Modern office stock in Jakarta's CBD fringe emphasizes floor plate efficiency above 2,000 square meters and Grade A specifications. Demand concentrates in Sudirman-Thamrin corridor and emerging BSD City fringe as financial services and technology tenants seek proximity to talent pools. Yield compression in core assets is forcing investors toward value-add repositioning of aging 1990s stock.
- Industrial:Logistics facilities dominate absorption in Bekasi-Cikarang corridor with speculative construction accelerating ahead of tenant commitment. Cold-chain specifications are driving capital costs higher as pharmaceutical and food distributors require temperature-controlled warehousing in Greater Jakarta's peripheral districts. Land banking concentration among five developer groups limits entry for new institutional capital.
- Retail:Tier-one malls in Jakarta and Surabaya maintain defensive cash flow against e-commerce penetration, though margin pressure is intensifying in secondary city schemes. Community retail and neighborhood centers anchored by grocery operators show relative resilience compared to discretionary shopping formats.
- Hospitality:Recovery tracks international visitor return patterns to Bali and Jakarta with resort assets lagging urban business hotels in occupancy stabilization. Development timelines extend due to specialized MEP systems and operator selection processes that precede construction financing.
Most installed capacity flows through Industrial. Expansion is steepest in Hospitality as international visitation normalizes.
Investment Strategy:
Risk-return profiles separate these four approaches, with core strategies commanding the lowest yields and development plays requiring the longest capital lock-up periods.
- Core:Stabilized assets in established Jakarta submarkets with long-lease tenants and minimal capex requirements. Institutional capital concentrates here for yield compression in Sudirman-Thamrin corridor office towers and prime retail malls with defensive tenancy.
- Value-add:Repositioning of aging office stock through lobby upgrades, MEP modernization, and tenant mix reconfiguration. Execution risk centers on lease rollover timing and construction cost volatility in steel rebar and cement markets.
- Opportunistic:Distressed acquisition or complex title resolution plays requiring specialized local knowledge. Returns depend on notarial reconciliation of inherited agricultural parcels before HGB leasehold conversion and financing.
- Development:Ground-up construction of industrial estates and mixed-use townships in secondary cities. Ciputra Group leverages township development expertise to anchor portfolios across Makassar and Medan where industrial land trades at 40% below Jakarta fringe valuations.
Capital deployment is deepest in Core. Value-add is climbing fastest as yield compression eliminates core acquisition opportunities.
Client Type:
Regulatory access and capital scale differentiate these four investor categories, with foreign capital facing structural constraints that domestic institutional pools navigate more fluidly.
- Institutional Investors:Pension funds and insurance companies with long-duration liabilities matching commercial real estate cash flow profiles. Deployment concentrates in Jakarta CBD office and prime retail with strict investment grade tenant covenants.
- High-net-worth Individuals:Family office capital seeking diversification through direct property acquisition or developer joint ventures. Investment horizons align with generational wealth transfer timelines rather than quarterly reporting cycles.
- REITs:Pending tax incentive revisions for real estate investment trust structures could unlock institutional capital formation channels. Current regulatory framework limits REIT scale compared to Singapore and Malaysia listed vehicles.
- Foreign Investors:Subject to HGB leasehold restrictions and local partner requirements for direct land ownership. Capital concentrates in build-to-suit industrial facilities with single-tenant credit backing rather than speculative development.
Deal flow concentrates with Institutional Investors. Regulatory optimization is advancing fastest for REITs.
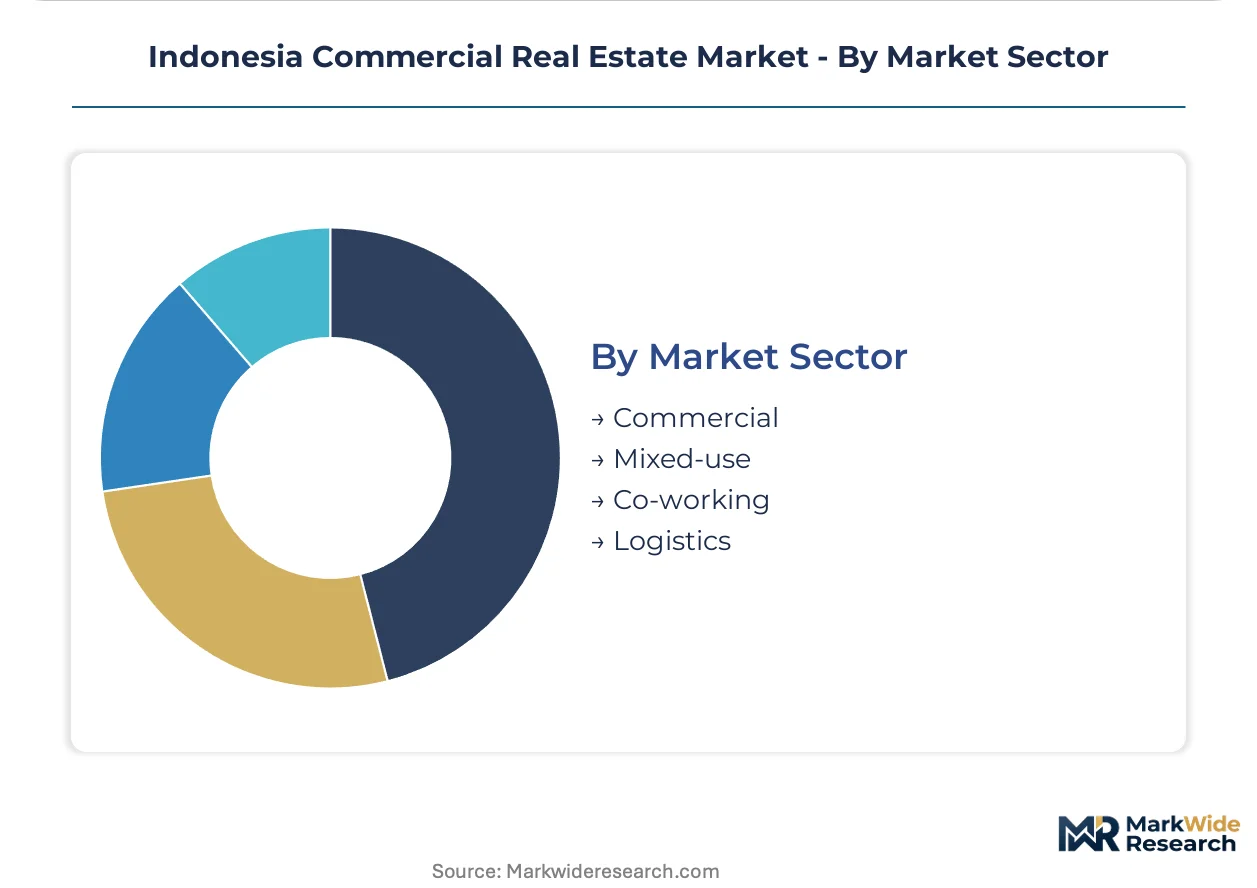
Market Sector:
Functional use patterns and tenant operational requirements distinguish these four sectors, with logistics and co-working representing structural growth against traditional commercial formats.
- Commercial:Conventional income-generating properties including office towers and retail centers with standard lease structures. Tenant decision-making is consolidating around integrated facility management bundles rather than standalone lease negotiations.
- Mixed-use:Retail-led complexes dominating Surabaya's commercial landscape through Pakuwon Jati's township developments. Vertical integration of residential, hospitality, and retail components spreads development risk across income streams.
- Co-working:Flexible workspace operators compressing traditional office lease terms and expanding beyond Jakarta into Bandung and Yogyakarta. Demand correlates with startup ecosystem density and remote work policy adoption among multinational employers.
- Logistics:E-commerce fulfillment networks compressing warehouse absorption timelines across Java's logistics corridors. Sinar Mas Land competes through integrated logistics park designs combining warehousing with cold-chain infrastructure.
Transaction velocity is highest in Commercial. Structural transformation is most pronounced in Logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial real estate development in Indonesia traces its modern lineage to the 1970s New Order-era township programs that established Ciputra Group's foundational mixed-use models in Jakarta. These early satellite city experiments created the institutional template for contemporary master-planned developments across the archipelago.
Greater Jakarta
Financial services consolidation and technology sector expansion drive absorption in Sudirman-Thamrin corridor office towers. The Ministry of Agrarian Affairs and Spatial Planning enforces regional spatial plans (RTRW) that dictate density bonuses for transit-oriented developments. Bekasi-Cikarang industrial corridor concentrates logistics facility construction as e-commerce fulfillment networks compress pre-lease commitment windows.
Surabaya and East Java
Manufacturing relocation from saturated western Java markets accelerates demand for industrial land in Gresik and Sidoarjo regencies. Provincial governments administer BSI building codes that mandate green building thresholds for new commercial stock. Pakuwon Jati anchors retail-led mixed-use complexes that dominate Surabaya's commercial landscape through integrated facility management bundles.
Bandung and West Java Highlands
Co-working operators and creative industry tenants expand flexible workspace demand beyond Jakarta into Bandung's technology corridor. Regional spatial plans in West Java create permitting friction for cross-border logistics corridor development with Banten province. Lembang and Dago districts concentrate hospitality and lifestyle commercial assets targeting domestic tourism flows.
Makassar and South Sulawesi
Regional distribution center demand from eastern Indonesia trade routes drives industrial land absorption at valuations 40% below Jakarta fringe levels. The Omnibus Law on Job Creation streamlined land-use conversion permits for industrial zones in secondary cities. Tanjung Bunga and industrial zones in Maros regency concentrate emerging logistics park development.
Medan and North Sumatra
Palm oil processing and rubber manufacturing supply chains generate demand for warehousing and light industrial facilities. Provincial RTRW regulations govern density and land-use conversion for commercial expansion in Deli Serdang regency. Ciputra Group leverages township development expertise to anchor mixed-use portfolios in this underpenetrated northern market.
Indonesia Commercial Real Estate Market Competitive Landscape
Premium-margin players sit above commodity-margin players across land banking quality and tenant covenant strength. Five developer groups control prime industrial land parcels in Jakarta's buffer zones, limiting entry for new institutional investors. The competitive terrain separates into township master-planners, integrated logistics park specialists, and retail-led mixed-use operators. Dominant competitive moves include portfolio diversification into secondary cities and backward integration into captive facility management services.
Within the township master-planner tier, Ciputra Group exemplifies geographic diversification into secondary cities, while Sinar Mas Land occupies a position representing integrated logistics park design. Pakuwon Jati anchors the retail-led mixed-use archetype through Surabaya market concentration. These three developers represent the strategic archetypes restructuring tenant decision-making across Indonesian commercial property.
| Leading Market Players |
|---|
| Agung Podomoro Land |
| Ciputra Group |
| Lippo Group |
| Sinar Mas Land |
| RDTX Group |
| PP Properti |
| Summarecon Agung |
| Alam Sutera Realty |
| Pakuwon Jati |
| Others |
Supply & Pricing Matrix
Prefabricated steel frame systems are compressing construction timelines for industrial facilities while simultaneously concentrating procurement leverage among three integrated developer groups. This modularization dynamic tightens margins for speculative warehouse builders in Bekasi-Cikarang corridor even as it accelerates tenant commitment velocity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments Jakarta CBD fringe office assets from secondary city stock and aging 1990s repositioning plays. Price differentiation rests on BSI green building certification thresholds and captive facility management bundling rather than base rent alone. Cost compression in standard-tier logistics facilities is intensifying because steel rebar and cement price volatility erodes fixed-price contract margins. E-commerce fulfillment operators show least price sensitivity due to speed-to-market imperatives, while regional distribution center tenants in Makassar and Medan negotiate hardest on base rates.
Supply Chain Analysis
Reverse-logistics flows for warehouse refurbishment and MEP system upgrades are creating secondary material markets in Greater Jakarta's industrial buffer zones. Construction inputs draw from China, South Korea, and domestic Indonesian steel producers, with cement supply anchored in Java-based clinker operations. Single-source vulnerability concentrates in specialized cold-chain refrigeration equipment imported from Japan and Germany. Distribution runs through developer-captive procurement networks controlled by Ciputra Group, Sinar Mas Land, and Pakuwon Jati, limiting third-party contractor access to bulk pricing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia commercial real estate has entered a late-cycle quality phase where Grade A specifications and integrated service bundling command rent premiums. Tenant demand is migrating toward LEED-equivalent warehouse stock and mixed-use complexes with captive facility management.
For Market Incumbents: To counter margin compression in speculative industrial construction, accelerate backward integration into prefabricated steel frame production and lock in multi-year cement supply agreements with Semen Indonesia. Prioritize HGB leasehold consolidation in Jakarta buffer zones before Omnibus Law permitting windows narrow for new entrants. For New Entrants and Emerging Players: Begin with cold-chain logistics specialization in Surabaya's Gresik-Sidoarjo corridor where pharmaceutical distributor demand outpaces supply. Target regional distribution center development in Makassar and Medan where industrial land trades at steep discounts to Java valuations. Lead with build-to-suit development models that eliminate speculative construction risk. For Investors and Strategic Acquirers: Valuations sit cheapest among opportunistic title-resolution plays requiring notarial reconciliation of inherited agricultural parcels. Long-term viability favors developers with township master-planning capabilities spanning multiple Indonesian cities. Monitor Omnibus Law enforcement consistency across provincial boundaries as the signal for institutional capital deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Green Building Certification Program | BSI-mandated energy efficiency thresholds create first-mover rent premiums for compliant warehouse stock. |
| Integrated Logistics Park Development | Combining warehousing with cold-chain infrastructure captures pharmaceutical distributor commitment velocity. |
| Secondary City Township Expansion | Ciputra Group's Makassar and Medan deployments validate 40% land cost arbitrage against Jakarta fringe. |
| Captive Facility Management Bundling | Pakuwon Jati's Surabaya retail complexes demonstrate tenant retention through packaged fit-out contracts. |
| HGB Leasehold Portfolio Consolidation | Notarial reconciliation of fragmented agricultural titles unlocks financing for repositioning plays. |
Research Methodology
Bottom-up tenant demand modeling reconciled against top-down land supply tracking forms the analytical core of this study. Primary interviews with industrial estate developers, third-party logistics operators, provincial planning officials, and institutional investment officers were cross-validated against Ministry of Agrarian Affairs permitting databases, BSI building code filings, and regional spatial plan (RTRW) documentation. Secondary sources include Omnibus Law regulatory circulars, provincial government construction statistics, and listed developer annual disclosures.
Input-output matrices mapped warehouse absorption velocity against speculative construction timelines across Bekasi-Cikarang, Surabaya, and secondary city corridors. Segmentation dimensions encompass property type, investment strategy, client type, and market sector with geographic granularity at provincial level. CAGRs were derived from trend extrapolation of transaction velocity and land price appreciation across the projection horizon, incorporating e-commerce fulfillment network expansion rates and cold-chain infrastructure investment flows as sector-specific demand drivers.
Several conditions sit outside the modeled scope, including expropriation risk for agricultural land conversion, currency volatility effects on imported construction materials, and sudden regulatory reversals to Omnibus Law permitting provisions. Forecasts reflect documented assumptions regarding sustained e-commerce growth and international visitor return patterns to Bali and Jakarta. Practitioners should monitor provincial RTRW enforcement divergence and REIT tax incentive legislative progress for early signals of capital formation channel shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Real Estate
Global Shared Office Spaces Market
Commercial Real Estate
Canada Hospitality Real Estate Sector Market
Commercial Real Estate
UAE Commercial Real Estate Market
Commercial Real Estate
UK Commercial Real Estate Market
Commercial Real Estate
Spain Commercial Real Estate Market
Commercial Real Estate
Hospitality Real Estate Sector Market
Commercial Real Estate
Saudi Arabia Commercial Real Estate Market
Commercial Real Estate
Thailand Commercial Real Estate Market
Commercial Real Estate
Egypt Commercial Real Estate Market
Commercial Real Estate
Canada Commercial Real Estate Market
Commercial Real Estate
Oman Commercial Real Estate Market
Commercial Real Estate
Vietnam Commercial Real Estate Market
Commercial Real Estate
Latin America Commercial Real Estate Market
Commercial Real Estate
United Arab Emirates Co-Working Space Market
Commercial Real Estate
Brazil Commercial Real Estate Market
Commercial Real Estate
United States Commercial Real Estate Market