
 Singapore Self-Storage Market | 2026-2036
Singapore Self-Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Self-Storage Market Analytics
Market Context
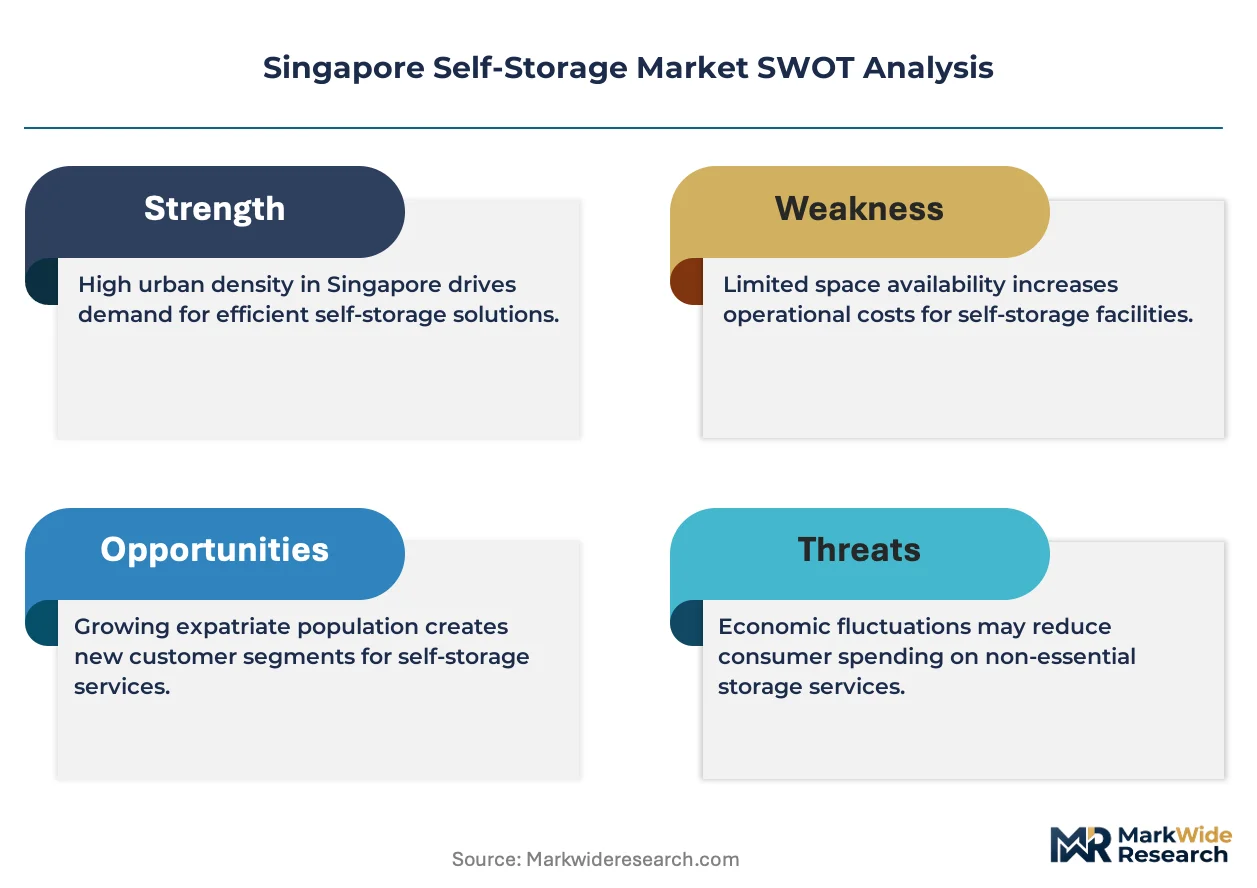
E-commerce fulfillment is restructuring Singapore self-storage demand as online retailers seek flexible inventory staging. Extra Space Asia leverages its network density across industrial zones to capture this shift. StorHub Self Storage anchors its position through climate-controlled infrastructure near port logistics corridors. Beam Storage differentiates via technology leadership in automated access and digital inventory management.
Technical Definition and Segment Structure
Singapore self-storage comprises leased enclosed units ranging from 25 to 300 square feet, constructed with reinforced concrete, steel partitioning, and humidity control systems for asset preservation. The primary commercial purpose is to provide flexible, short-to-medium duration space for household overflow, business inventory, and transitional logistics. Climate-controlled storage commands premium positioning due to Singapore's tropical humidity and electronics concentration. Business customers represent the fastest-expanding customer type as SMEs outsource warehousing. Small units dominate volume transactions while large units capture disproportionate margin pools from commercial clients.
Regulatory Framework and Outlook
Singapore's Urban Redevelopment Authority governs facility zoning through industrial and commercial land-use classifications, while the Singapore Civil Defence Force enforces fire safety and hazardous materials standards. The Building and Construction Authority mandates structural integrity certifications that shape facility design costs and operational compliance burdens. Stakeholders must monitor upcoming land-use plan revisions and sustainability requirements that could reshape facility economics and permissible locations.
Market Dynamics
Land scarcity under the Urban Redevelopment Authority's industrial zoning framework is compressing facility development timelines and pushing operators toward vertical expansion and automated density solutions.
Growth Catalysts
- E-commerce fulfillment surge:Online retailers require flexible inventory staging near port logistics corridors, creating sustained demand for climate-controlled units with rapid access protocols.
- SME warehousing outsourcing:Small and medium enterprises are abandoning fixed commercial leases in favor of scalable self-storage for document archives and seasonal inventory cycles.
- Urban Redevelopment Authority zoning flexibility:Recent amendments to industrial land-use classifications permit self-storage in more locations, expanding addressable supply nodes across the Central Region.
Market Restraints
- Land cost escalation:Industrial plot premiums in Singapore have compressed facility development margins to levels that deter new market entrants without established capital reserves.
- Construction input volatility:Reinforced concrete and steel partitioning costs fluctuate with regional commodity markets, creating unpredictable capex cycles for expansion projects.
- Fire safety compliance burden:Singapore Civil Defence Force hazardous materials standards impose extensive sprinkler system and compartmentalization requirements that extend build-out timelines.
Strategic Opportunities
- Jurong Lake District corridor:Planned commercial and residential density in this western growth area will concentrate household overflow demand within underserved industrial adjacencies.
- Building and Construction Authority green certification:Sustainability mandates for new industrial buildings create first-mover advantage for operators deploying solar-integrated climate control and rainwater harvesting systems.
- Mobile access convergence:Integration of biometric entry with inventory management apps is electrifying customer retention through reduced friction in unit access and payment workflows.
Industry Challenges
- Automation engineering scarcity:Facility operators struggle to recruit technicians capable of maintaining robotic retrieval systems and IoT sensor networks at scale.
- Legacy system integration friction:Established operators face complex data migration when retrofitting digital inventory platforms onto concrete structures built before smart infrastructure standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Self-Storage Market |
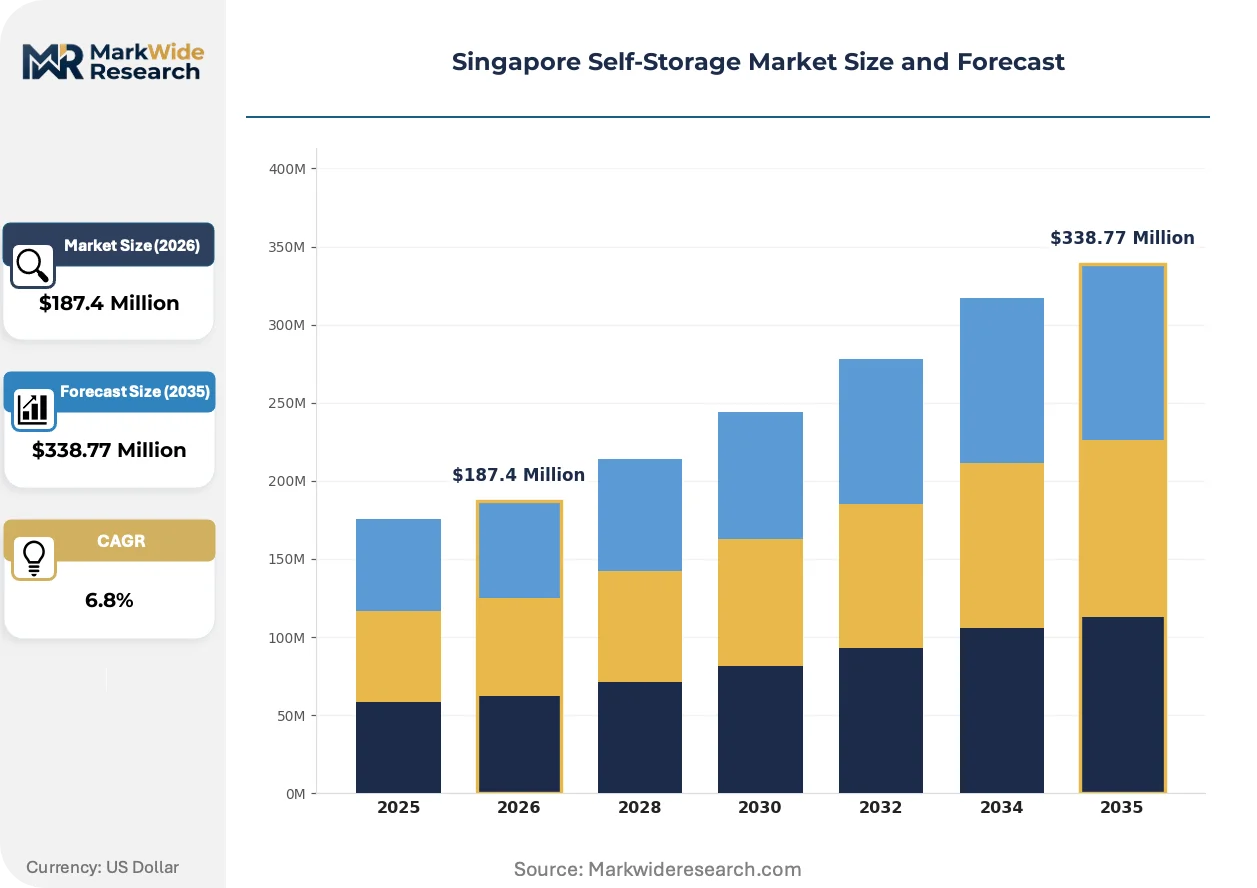
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard Storage, Climate-Controlled Storage, Vehicle Storage, Personal Storage Customer Type: Residential Customers, Business Customers, Student Customers, Military Personnel Storage Size: Small Units, Medium Units, Large Units, Extra-Large Units Access Type: 24/7 Access, Keypad Access, Drive-Up Access, Managed Access |
| Companies Covered | Extra Space Asia, Work Plus Store, StorHub Self Storage, Mandarin Self Storage, General Storage Company, Store Friendly Management, Store Room, Beam Storage, Spaceship Singapore, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Self-Storage Market Evolving Landscape
Digital infrastructure is restructuring how operators capture and retain commercial customers, with automation and sustainability credentials becoming primary competitive differentiators rather than ancillary features.
Automated storage and retrieval systems are electrifying facility economics by compressing labor requirements and enabling 24-hour unmanned operations. E-commerce fulfillment teams now specify robotic access as a procurement criterion, prioritizing providers with vertical racking and conveyor-fed loading bays. This technology shift is enabling operators to justify premium positioning on throughput speed rather than square footage alone.
Singapore Civil Defence Force fire safety codes are tightening compartmentalization standards for facilities storing electronics and lithium batteries. The Building and Construction Authority has synchronized structural integrity certifications with these requirements, extending approval timelines for new developments. Climate-controlled operators serving the electronics trade are responding by pre-certifying units for hazardous material subclasses, converting compliance burden into segment-specific lock-in.
Subscription-based capacity contracts are displacing traditional fixed-term leases among SME customers seeking inventory elasticity. Channel partners including commercial property brokers and logistics consultants now bundle storage with freight forwarding, unbundling the direct operator relationship. This pattern concentrates in the Central Region where business customers prioritize location flexibility over unit ownership.
Singapore Self-Storage Market Segmentation
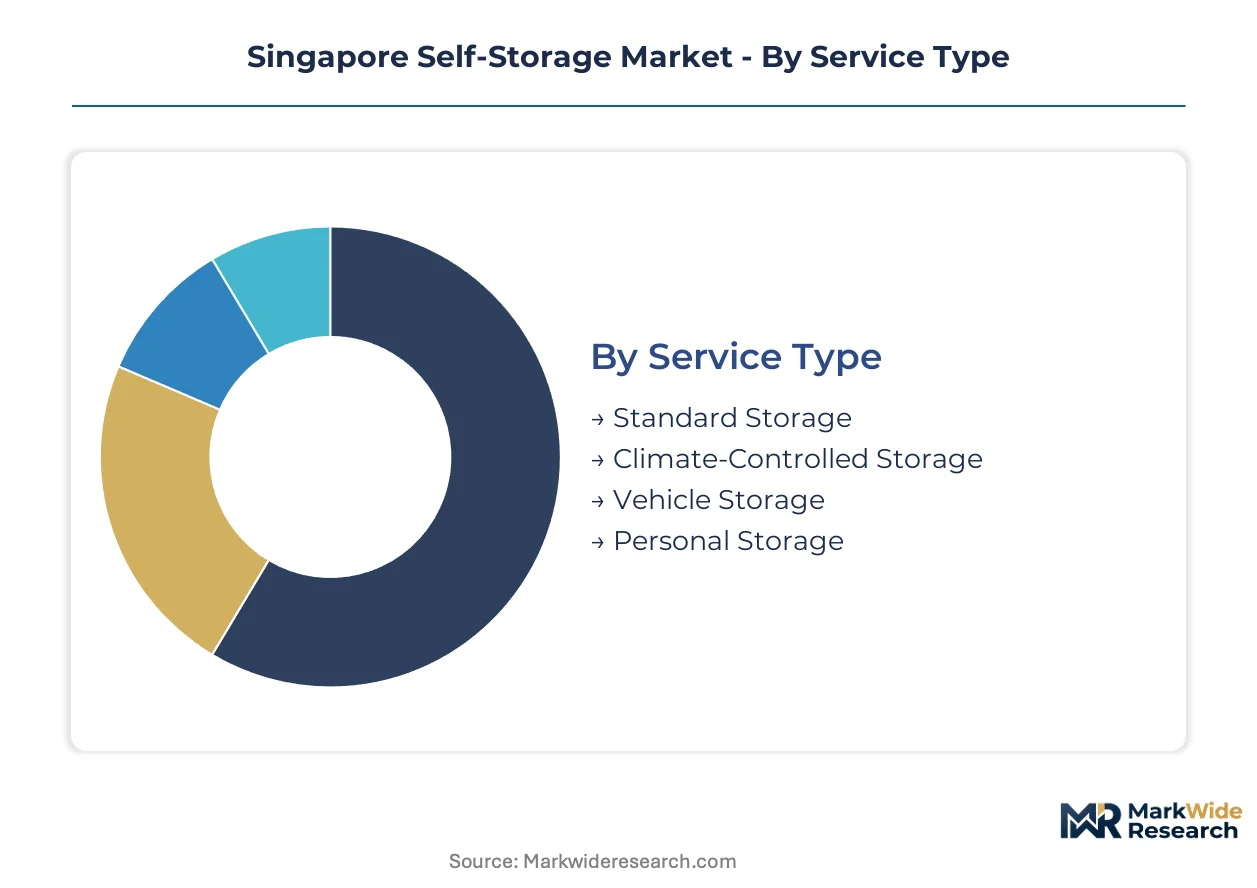
Segmentation in Singapore's self-storage market reveals how capital deployment, regulatory compliance, and customer workflow requirements fragment operational economics. Understanding these divisions exposes where facility operators earn premium returns versus where commoditization pressures concentrate.
Service Type:
Climate-controlled infrastructure demands the heaviest upfront capital outlay due to humidity management systems and reinforced concrete specifications required by the Building and Construction Authority.
- Climate-Controlled Storage:Units maintain 50-55% relative humidity through industrial dehumidification and HVAC systems. Electronics traders and pharmaceutical distributors in the Central Region specify this tier to protect inventory from Singapore's tropical moisture degradation.
- Standard Storage:Basic concrete units with passive ventilation serve household overflow and document archiving. SME clusters in Jurong and Tampines industrial estates absorb volume here, prioritizing cost over environmental precision.
- Vehicle Storage:Secured bays accommodate motorcycles and commercial vans with reinforced flooring and fire suppression systems mandated by the Singapore Civil Defence Force.
- Personal Storage:Locker-scale units for seasonal items and travel belongings concentrate near residential corridors in Bedok and Woodlands.
Standard storage absorbs the bulk of installed capacity; climate-controlled storage is expanding most quickly.
Customer Type:
Business procurement patterns concentrate margin pools differently than individual consumers, with contract duration and unit scale determining customer lifetime value calculations.
- Business Customers:SMEs and e-commerce fulfillment teams lease multiple units on rolling contracts. Port-proximate facilities in Tuas and Pasir Panjang capture this demand as inventory staging replaces fixed warehousing.
- Residential Customers:Households in transition—renovation, relocation, downsizing—drive seasonal demand spikes. HDB corridor proximity determines facility selection more than price sensitivity.
- Student Customers:International students at NUS and NTU require short-term storage during term breaks. University-adjacent operators in Clementi and Jurong West seasonally adjust pricing.
- Military Personnel:SAF members on overseas deployment represent a narrow but predictable segment with standardized insurance requirements.
Residential customers dominate transaction volume; business customers command the steepest expansion trajectory as outsourcing accelerates.
Storage Size:
Unit dimensions dictate construction economics, with vertical stacking efficiency and floor loading capacity varying substantially across the size spectrum.
- Small Units:25-50 square foot lockers optimize revenue per square meter through dense racking. Urban Redevelopment Authority zoning constraints in the Central Region favor this footprint for maximum yield.
- Large Units:150-300 square foot spaces accommodate palletized inventory and equipment. E-commerce fulfillment teams in Changi Business Park specify these for receiving and dispatch workflows.
- Medium Units:75-100 square foot configurations balance accessibility with density, serving residential overflow and small business archives.
- Extra-Large Units:300+ square foot warehouse-scale spaces attract commercial tenants requiring vehicle maneuvering room and loading dock proximity.
Small units generate the highest revenue per square meter; large units are gaining share fastest as business demand scales.
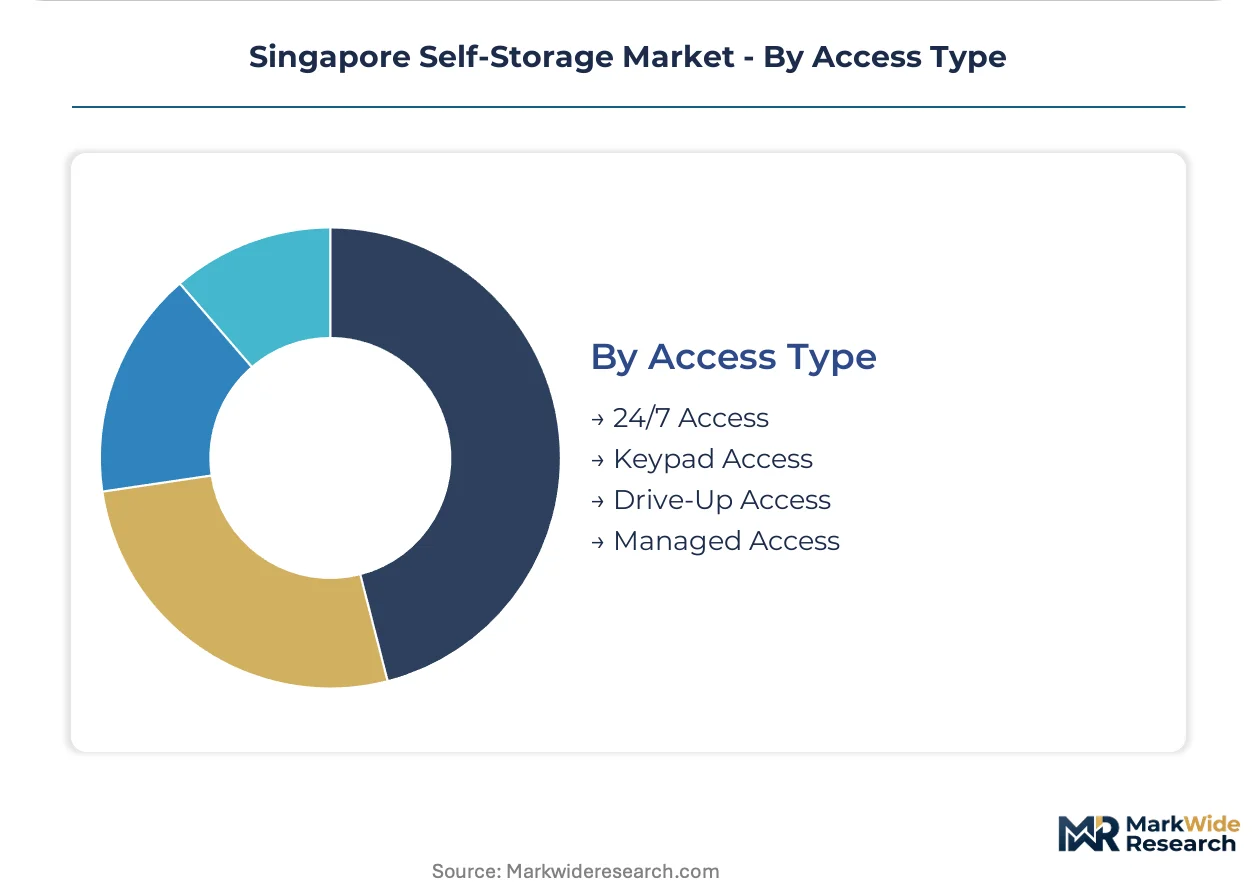
Access Type:
Technology integration levels separate premium positioning from commodity competition, with automation capex recovering through labor reduction and extended operating hours.
- 24/7 Access:Biometric entry systems and unmanned reception enable round-the-clock retrieval. E-commerce fulfillment teams in Alexandra and Tiong Bahru industrial zones treat this as a procurement requirement.
- Managed Access:Staffed reception with appointment scheduling serves corporate document archives requiring chain-of-custody protocols. Financial services firms in the CBD fringe specify this tier.
- Keypad Access:PIN-based entry without biometric verification offers mid-tier convenience for residential customers prioritizing cost over technology.
- Drive-Up Access:Ground-floor units with vehicle loading bays suit heavy equipment and frequent inventory turnover in Tuas logistics corridors.
Keypad access retains the largest installed base; 24/7 biometric systems are climbing the fastest as automation economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility supply concentrates in industrial corridors while demand radiates from residential zones and logistics hubs. The Urban Redevelopment Authority's zoning decisions determine where operators can build, compressing development into approved nodes.
Central Region
E-commerce fulfillment teams and SME inventory staging drive demand in Alexandra, Tiong Bahru, and Kallang industrial estates. The Urban Redevelopment Authority permits self-storage under B2 industrial zoning, enabling vertical facilities near the CBD fringe. Climate-controlled units command premium positioning in this corridor due to electronics concentration.
Jurong Lake District
Planned commercial and residential density expansion is concentrating household overflow demand in western industrial adjacencies. The Urban Redevelopment Authority designates this as a growth area with flexible industrial land-use classifications. Clementi and Jurong West facilities capture student storage cycles from NUS and NTU.
Tuas and Pasir Panjang
Port-proximate logistics corridors attract business customers replacing fixed warehousing with scalable inventory staging. The Singapore Civil Defence Force enforces stringent fire safety standards for facilities storing electronics and lithium batteries. Changi Business Park spillover demand extends to this western logistics belt.
Bedok and Tampines
Eastern residential corridors generate household overflow and renovation-driven storage needs. HDB estate proximity determines facility selection more than price sensitivity. Industrial estates in this zone absorb standard storage volume from cost-conscious SME clusters.
Woodlands and Northern Corridor
Cross-border logistics activity and residential density create hybrid demand for personal and small-business storage. The Urban Redevelopment Authority's industrial zoning in this area permits lower-density facilities with drive-up access configurations. SAF personnel on overseas deployment represent a predictable narrow segment here.
Singapore Self-Storage Market Competitive Landscape
Top-tier vendors anchor premium positioning through climate-controlled infrastructure and automation, while mid-tier operators compete on location density and price accessibility. The market structure reflects tiered differentiation rather than consolidation. Three archetypes dominate: network-scale incumbents with industrial zone coverage, technology-forward specialists deploying automated access systems, and location-focused operators serving residential corridors. Competitive moves center on vertical expansion to overcome land scarcity and strategic partnerships with logistics brokers to capture e-commerce fulfillment demand.
Among Singapore-based operators, Extra Space Asia, StorHub Self Storage, and Beam Storage exemplify the three competitive archetypes. Extra Space Asia occupies a position representing network-scale coverage across industrial zones. StorHub Self Storage anchors the climate-controlled infrastructure tier with port-proximate facilities. Beam Storage sits within the technology-forward segment through automated access and digital inventory management capabilities. Work Plus Store, Mandarin Self Storage, and Store Friendly Management represent additional incorporated entities competing in this market.
| Leading Market Players |
|---|
| Extra Space Asia |
| Work Plus Store |
| StorHub Self Storage |
| Mandarin Self Storage |
| General Storage Company |
| Store Friendly Management |
| Store Room |
| Beam Storage |
| Spaceship Singapore |
| Others |
Value Network & Pricing Analysis
E-commerce fulfillment teams concentrate procurement power in Singapore's Central Region, anchoring a contract-based pricing model where rolling subscriptions displace fixed-term leases and location flexibility commands premium positioning over square footage metrics.
Pricing Analysis
Margin tightening in climate-controlled tiers reflects Building and Construction Authority certification costs and humidity management system maintenance. Pricing stratifies across climate-controlled, standard, and vehicle storage tiers, with certification grade and proximity to port logistics corridors serving as primary differentiation drivers. Cost compression accelerates in standard storage as SME clusters prioritize unit accessibility over environmental precision. Residential customers in HDB corridors exhibit highest price sensitivity; e-commerce fulfillment teams demonstrate lowest sensitivity due to inventory staging requirements.
Supply Chain Analysis
Technician scarcity in Singapore, Malaysia, and South Korea constrains deployment of automated storage and retrieval systems at scale. Facility construction draws from regional reinforced concrete, steel partitioning, and industrial HVAC equipment suppliers. Single-source vulnerability concentrates in automated retrieval system components imported from Japanese and German manufacturers. Distribution runs through direct operator relationships and logistics broker channel partnerships bundling storage with freight forwarding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's self-storage market functions as a vertical-integration race where facility operators pursue backward integration into automated system maintenance capabilities to reduce technician dependency and extend unmanned operating hours.
For Market Incumbents: Cement network density in Jurong Lake District and Tuas corridors ahead of planned commercial density expansion. Acquire automated system engineering talent pools to preempt technician scarcity bottlenecks. Channel control through direct logistics broker partnerships defends against subscription-based capacity contract disintermediation. For New Entrants and Emerging Players: Capture white-space in Woodlands and Northern Corridor where cross-border logistics activity meets underserved residential density. The Jurong West student storage segment remains penetrable through university-adjacent micro-facility formats. A sustainability-first go-to-market angle leveraging Building and Construction Authority green certification creates differentiation against established climate-controlled infrastructure. For Investors and Strategic Acquirers: The window for entry favors technology-forward operators with deployed automated access systems and digital inventory platforms. Long-term viability hinges on vertical expansion economics overcoming Singapore's land scarcity constraints. Monitor Urban Redevelopment Authority industrial zoning amendments as inflection indicators for addressable supply node expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Vertical Facility Expansion | Maximizes yield per square meter under Urban Redevelopment Authority industrial zoning constraints. |
| Automated Access Integration | Reduces labor requirements and enables 24-hour unmanned operations for e-commerce fulfillment teams. |
| Climate Control Certification | Converts Building and Construction Authority compliance burden into segment-specific lock-in for electronics traders. |
| Logistics Broker Partnership | Captures SME demand through bundled storage and freight forwarding channel relationships. |
| Sustainability Retrofit Program | Preempts green certification mandates with solar-integrated climate control and rainwater harvesting systems. |
Research Methodology
Multi-period observation of facility development timelines, zoning amendment patterns, and customer procurement shifts anchored the trend analysis, supplemented by interviews with self-storage facility operators, logistics consultants, commercial property brokers, and Urban Redevelopment Authority planning officers. Secondary validation drew from Urban Redevelopment Authority land-use plans, Building and Construction Authority structural integrity filings, Singapore Civil Defence Force fire safety compliance records, and industrial real estate transaction databases. Bottom-up unit economics modeling triangulated against top-down market sizing from sector revenue aggregates.
Segment-weighting across service type, customer type, storage size, and access type dimensions informed value distribution across the projection horizon. CAGRs derived from fitted growth curves applied to base-year market estimates, with sensitivity testing against e-commerce fulfillment penetration rates and SME warehousing outsourcing velocity. Climate-controlled capacity expansion timelines and automated system deployment rates served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Urban Redevelopment Authority zoning revisions, construction input commodity volatility, and automation engineering labor market tightness. Material deviation in e-commerce fulfillment demand trajectories or industrial land-use policy direction warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
United States Self Storage Market
Real Estate Services
US Landscaping Services Market
Real Estate Services
Global Self Storage Market
Real Estate Services
Thailand Real Estate Market
Real Estate Services
Vietnam Self-Storage Market
Real Estate Services
GCC Interior Design Services Market
Real Estate Services
Singapore Customs Brokerage Market
Real Estate Services
Warehousing Services Market
Real Estate Services
Europe Coworking Spaces Market
Real Estate Services
Switzerland Self-Storage Market
Real Estate Services
US Home Service Market
Real Estate Services
US Real Estate and Hospitality Market
Real Estate Services
Property Tax Services Market
Real Estate Services
Home Warranty Service Market
Real Estate Services
IBC Rental Business Market
Real Estate Services
Coworking Spaces Market