
 Property Tax Services Market | 2026-2036
Property Tax Services Market Size, Share, and Industry Trends Forecast 2026-2036
Property Tax Services Market Outlook
Subscription-based appeal management is realigning how property tax services generate recurring revenue. Ryan, LLC leverages its proprietary technology platform to sustain long-term client relationships across multiple jurisdictions. Deloitte anchors its practice through deep integration with corporate real estate departments, while KPMG competes by embedding data analytics into every engagement phase.
Property tax services encompass valuation review, liability minimization, and compliance management delivered through certified assessors, tax attorneys, and automated workflow platforms. These functions reduce effective tax rates on commercial and residential real property by identifying assessment errors, filing administrative appeals, and negotiating settlements with taxing authorities. Consulting engagements command premium pricing due to specialized expertise in complex valuation disputes, while cloud-based solutions expand addressable markets by lowering deployment costs for mid-sized property owners. Data analytics capabilities represent the fastest-growing technology segment as firms compete on predictive assessment modeling.
The US Internal Revenue Service and state-level departments of revenue shape compliance frameworks, while local assessor boards establish valuation standards that determine service demand intensity. Municipal digitization mandates accelerate GIS system adoption, forcing service providers to integrate geospatial data into appeal strategies. Stakeholders must monitor how artificial intelligence tools reshape assessor accuracy and the corresponding need for specialized human intervention.
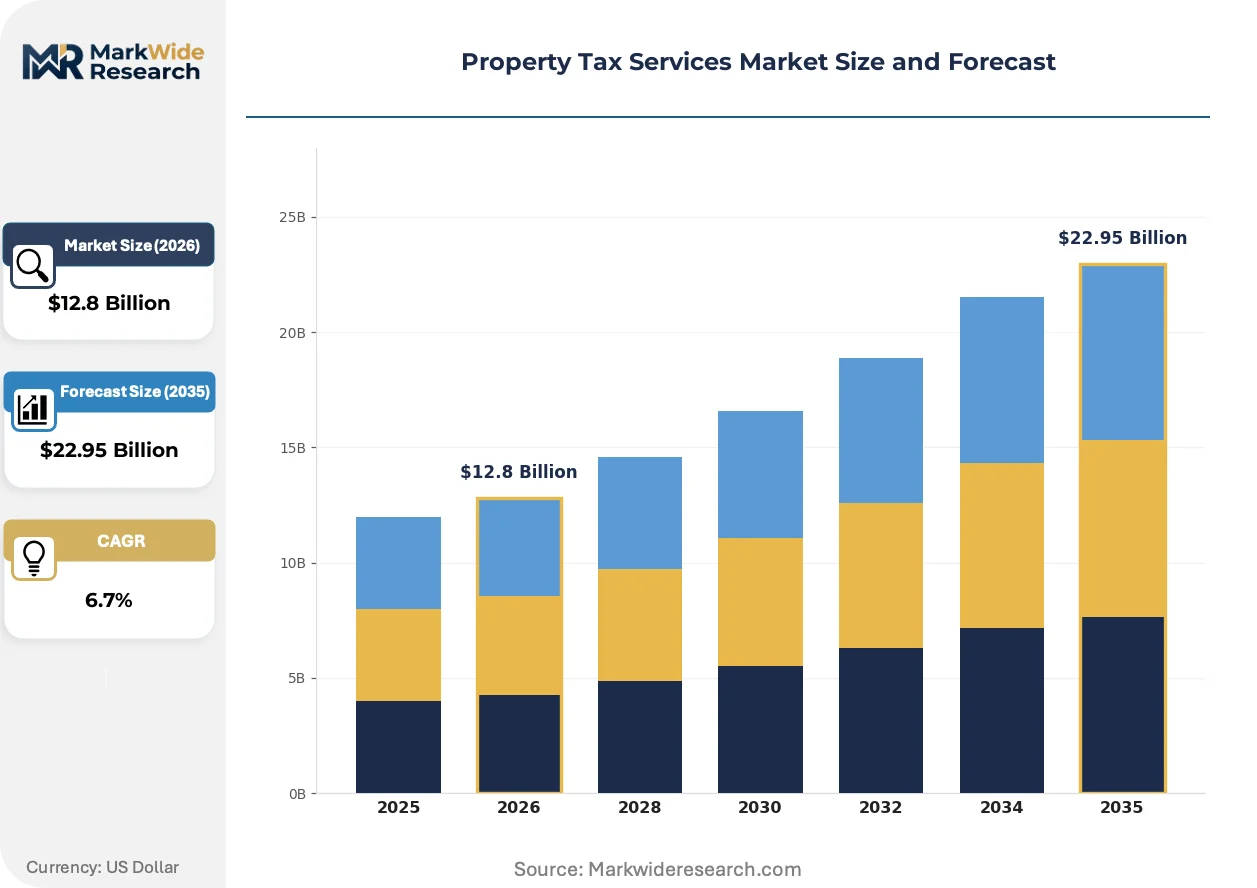
Market Dynamics
Municipal digitization mandates across the United States are forcing assessor offices to modernize valuation infrastructure, creating sustained demand for technology-integrated appeal services that bridge legacy assessment systems with automated compliance workflows.
Growth Catalysts
- Mass Appraisal Modernization:County assessor offices in Texas, Florida, and California are deploying computer-assisted mass appraisal systems that generate assessment errors, directly expanding the addressable market for professional appeal services.
- Commercial Portfolio Complexity:Multi-state property owners face divergent valuation methodologies across jurisdictions, necessitating centralized tax management platforms that standardize compliance across fragmented regulatory environments.
- Proprietary Analytics Platforms:Machine learning tools that predict assessment outcomes before filing are shortening appeal cycles and improving success rates, embedding technology vendors deeper into client workflows.
Market Restraints
- Assessor Resource Constraints:Understaffed municipal valuation departments in mid-sized US counties are extending appeal resolution timelines, compressing service provider revenue recognition cycles.
- Data Standardization Gaps:Inconsistent property characteristic databases across Texas appraisal districts force providers to maintain jurisdiction-specific data cleansing operations, elevating delivery costs.
- Alternative Dispute Resolution:Binding arbitration clauses in commercial lease agreements are diverting some tax disputes away from formal administrative appeals, constraining traditional service volumes.
Strategic Opportunities
- Mid-Market Penetration:Property owners with portfolios between 10 and 50 assets in Ohio, Illinois, and Georgia remain underserved by high-touch consulting models, creating white space for automated self-service platforms.
- ESG-Linked Valuation Appeals:Green building certifications and energy efficiency upgrades are generating new appeal categories as assessors struggle to value sustainability improvements, opening specialized advisory practices.
- Interstate Compliance Bundling:Providers that integrate sales tax, use tax, and property tax workflows into unified dashboards can capture cross-functional spend from corporate real estate departments.
Industry Challenges
- Certified Assessor Shortage:The pipeline of professionals holding both MAI designations and state-level tax appeal certifications is narrowing, constraining firm expansion capacity.
- Legacy System Integration:Enterprise clients require API connections into Yardi, MRI Software, and CoStar platforms, demanding substantial upfront development investment before revenue materializes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Property Tax Services Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Assessment, Consulting, Appeal, Management Client Type: Residential Owners, Commercial Property Owners, Local Governments, Investors Engagement Model: Retainer, Fee-for-Service, Contingency, Project-Based Technology: Cloud-Based Solutions, Software, GIS Systems, Data Analytics |
| Companies Covered | Ryan, LLC, Deloitte, KPMG, PwC, Kroll, LLC, Moss Adams LLP, Cherry Bekaert, Baker Tilly, CBRE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Property Tax Services Market Strategic Shifts
Artificial intelligence is penetrating property tax workflows at the assessment prediction and document generation layers, compressing the traditional appeal preparation timeline while elevating the strategic role of human judgment in complex disputes.
Robotic process automation is automating the extraction of property characteristics from county GIS databases and assessor records. Mid-sized commercial owners in Arizona and Nevada are adopting these tools fastest, cutting preliminary research hours by half. The technology is automating routine data gathering so that senior consultants can redirect expertise toward valuation methodology challenges and settlement negotiations.
The Internal Revenue Service has intensified scrutiny of real estate valuation practices used in conservation easement transactions, creating downstream compliance requirements that property tax advisors must now address. This enforcement posture is elevating documentation standards across all commercial property appeals. Corporate real estate departments in California and New York are responding by embedding tax attorneys earlier in the engagement lifecycle.
Subscription pricing for appeal management is displacing contingency-based fee structures among institutional property owners. Pension funds and REITs are negotiating annual retainers that cover proactive assessment monitoring and rapid-response filing capabilities. This shift is most pronounced in Texas, where biennial reassessment cycles create predictable workflow spikes that favor predictable cost structures.
Property Tax Services Market Segmentation
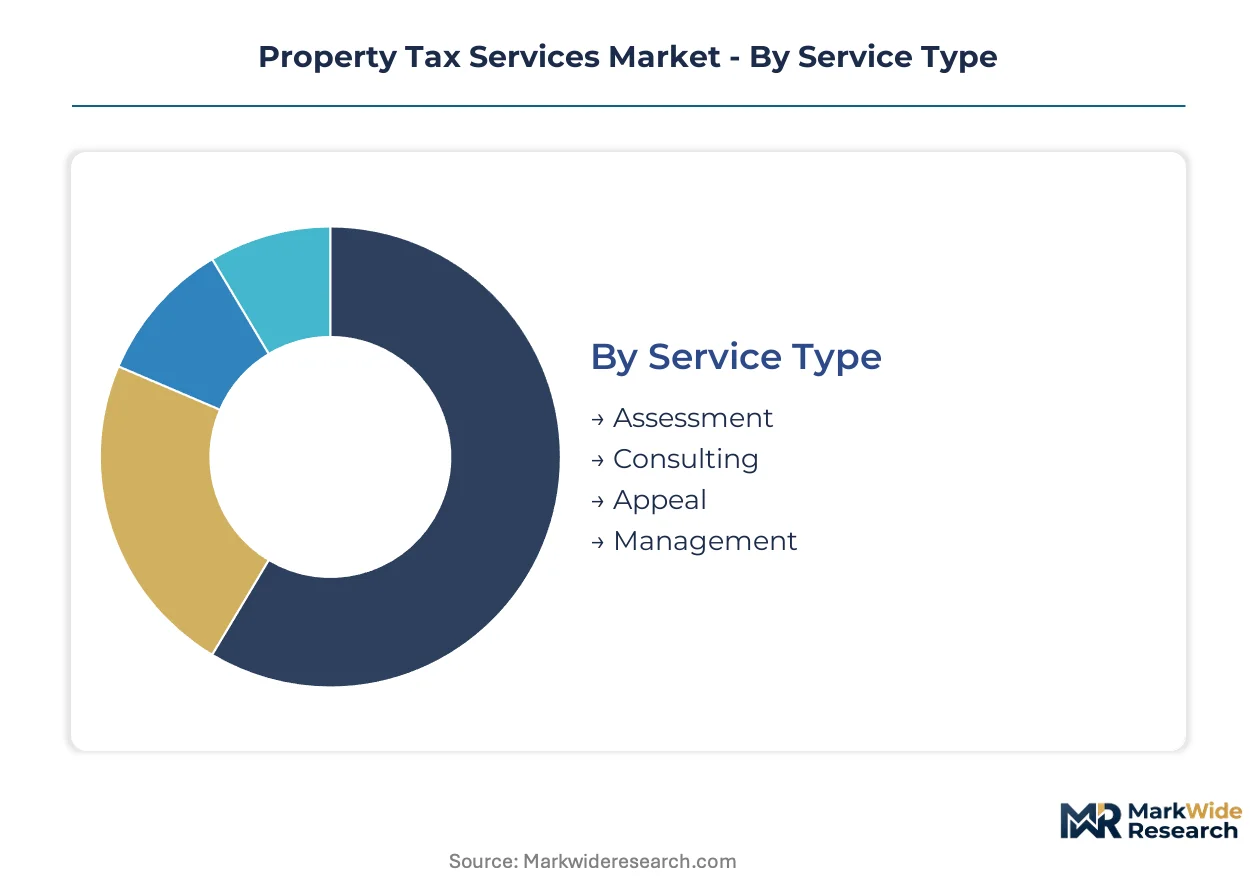
Property tax services fragment across four distinct dimensions that shape how providers configure delivery teams and price engagements. Service type determines staffing ratios of assessors to attorneys, while engagement model governs revenue predictability and client retention mechanics.
Service Type:
Supply concentrates in assessment and consulting functions where certified professionals maintain scarcity premiums.
- Assessment:Valuation review and property characteristic verification performed by state-licensed assessors. Demand clusters in Texas, Florida, and California where mass appraisal modernization generates systematic errors requiring professional challenge.
- Consulting:Strategic advisory on portfolio-wide tax minimization delivered through tax attorneys and MAI-designated appraisers. Commercial property owners in multistate portfolios drive adoption as jurisdictional methodology divergence escalates compliance complexity.
- Appeal:Administrative protest filing and hearing representation before local assessment review boards.
- Management:Ongoing compliance monitoring and deadline orchestration across distributed property portfolios.
Assessment absorbs the bulk of installed capacity; Consulting is expanding most quickly.
Client Type:
Cost tier stratification separates high-touch institutional relationships from automated self-service deployments.
- Commercial Property Owners:Multistate portfolios, REITs, and pension funds commanding dedicated account teams and proprietary analytics platforms. Portfolio complexity above 50 assets necessitates centralized tax management systems that standardize compliance across fragmented regulatory environments.
- Investors:Private equity real estate funds and opportunity zone participants requiring transaction-related valuation opinions and due diligence support. Acquisition timelines compress engagement windows, favoring retainer relationships over project-based procurement.
- Residential Owners:Individual homeowners pursuing single-property assessment challenges.
- Local Governments:Municipal assessor offices outsourcing mass appraisal system implementation and staff training.
Commercial Property Owners dominate current revenue contribution; Investors are climbing the fastest as transaction velocity accelerates.
Engagement Model:
Margin structure varies dramatically across pricing architectures that align incentives differently between client and provider.
- Retainer:Annual fixed-fee arrangements covering proactive monitoring and rapid-response filing capabilities. Pension funds and institutional owners in Texas favor this structure where biennial reassessment cycles create predictable workflow spikes.
- Contingency:Success-based fees calculated as percentage of tax savings achieved through appeal resolution. Commercial owners with disputed valuations above threshold levels prefer this model to align provider incentives with outcome magnitude.
- Fee-for-Service:Hourly billing for discrete valuation opinions and compliance filings.
- Project-Based:Fixed-scope engagements for portfolio acquisitions, dispositions, or appeals with defined timelines.
Retainer arrangements capture the greatest share of enterprise relationships; Contingency maintains strongest presence among mid-market owners seeking performance-aligned pricing.
Technology:
Application maturity separates legacy infrastructure from emerging capabilities that compress appeal preparation timelines.
- Data Analytics:Machine learning platforms predicting assessment outcomes before filing, shortening appeal cycles and improving success rates. Mid-sized commercial owners in Arizona and Nevada deploy these tools fastest, cutting preliminary research hours by half.
- Cloud-Based Solutions:Subscription platforms enabling distributed portfolio management without enterprise IT investment. Providers leverage these deployments to penetrate the 10-50 asset owner segment in Ohio, Illinois, and Georgia that high-touch consulting models underserve.
- GIS Systems:Geospatial data integration supporting comparable property analysis and valuation methodology challenges.
- Software:On-premise legacy systems requiring substantial implementation investment before revenue materialization.
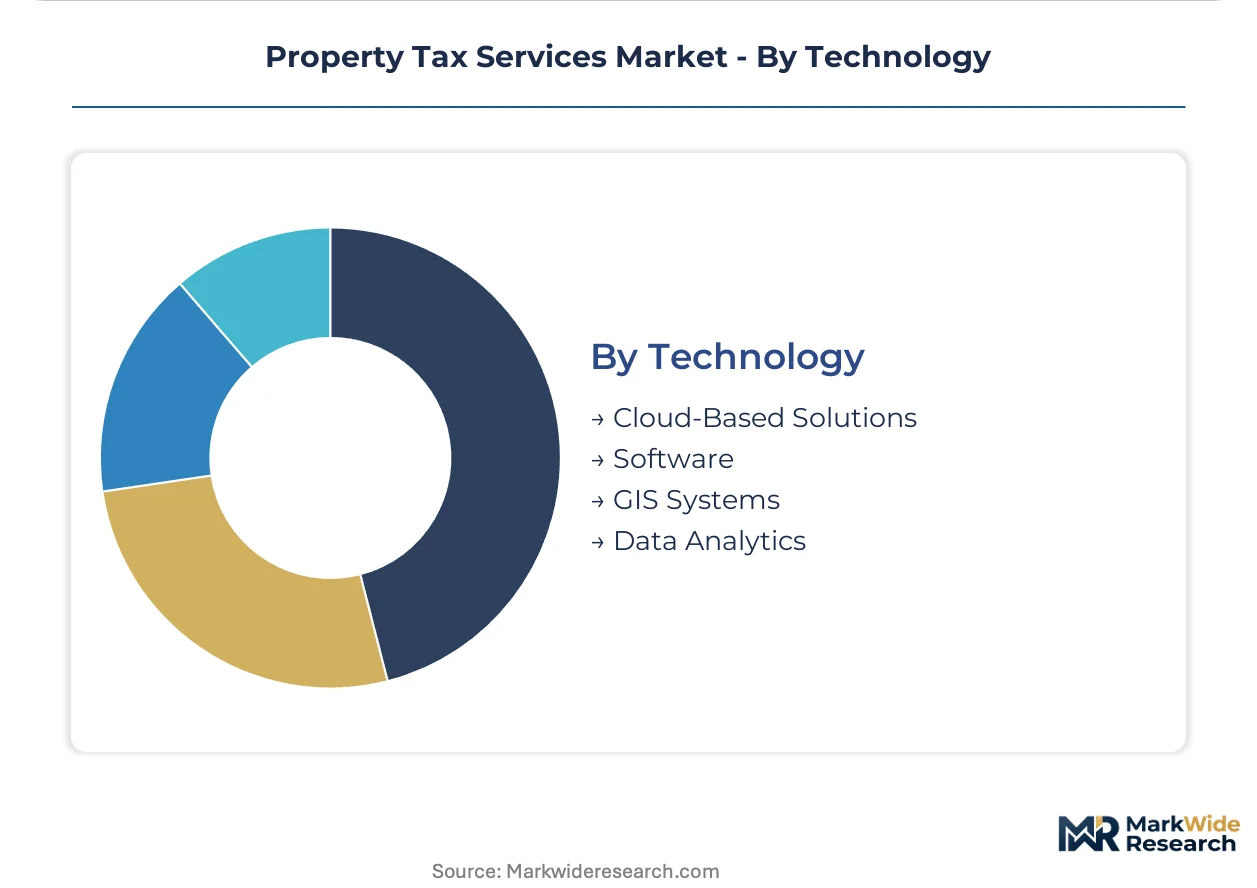
Data Analytics is gaining share fastest as competitive differentiation shifts toward predictive capability; Cloud-Based Solutions hold the broadest addressable market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the bulk of property tax services capacity, while Canada and Australia develop specialized niches. Service production concentrates in jurisdictions with complex assessment regimes and active appeal cultures.
United States
Texas, Florida, and California drive demand through biennial reassessment cycles and mass appraisal modernization. The Internal Revenue Service intensifies scrutiny of conservation easement valuations, elevating documentation standards. Dallas-Fort Worth and Houston anchor the largest commercial property appeal volumes.
Canada
Ontario and British Columbia property owners navigate municipal reassessment harmonization and valuation standard updates. Provincial assessment authorities mandate digitized comparable data submissions. Toronto and Vancouver concentrate advisory capacity for multi-provincial portfolio management.
United Kingdom
Commercial ratepayers in England and Wales respond to 2023 revaluation cycles and transitional relief complexity. The Valuation Office Agency's rating list updates create sustained compliance demand. London and Manchester host specialized practices serving institutional real estate investors.
Germany
The 2022 property tax reform triggered reassessment activity across federal states with divergent implementation timelines. Municipalities deploy computer-assisted valuation models requiring professional challenge. Berlin and Munich concentrate advisory services for cross-border portfolio holders.
Australia
New South Wales and Victoria property owners manage land tax threshold changes and foreign investor surcharge regimes. State revenue offices accelerate digital assessment platform rollouts. Sydney and Melbourne anchor specialist practices for commercial and industrial appeals.
Property Tax Services Market Competitive Environment
Top-tier vendors anchor enterprise relationships, while mid-market specialists compete on technology-enabled efficiency. The market exhibits tiered concentration with Big Four accounting firms and dedicated tax consultancies sharing institutional accounts. Three archetypes dominate: integrated professional services networks, specialized property tax boutiques, and technology-enabled managed service providers. Competitive moves center on proprietary analytics platform development and subscription pricing model migration.
Within the integrated network tier, Deloitte and KPMG exemplify structures combining tax advisory with corporate real estate department embedding. Ryan, LLC occupies a position representing the specialized boutique archetype with technology platform differentiation. These three entities anchor competitive dynamics through divergent client acquisition and retention mechanics.
| Leading Market Players |
|---|
| Ryan, LLC |
| Deloitte |
| KPMG |
| PwC |
| Kroll, LLC |
| Moss Adams LLP |
| Cherry Bekaert |
| Baker Tilly |
| CBRE |
| Others |
Value Chain & Pricing Dynamics
Certification-tier divergence between MAI-designated appraisers and state-licensed assessors bifurcates both pricing power and talent acquisition costs across the property tax services value chain. Premium engagements draw from the shallow pool of dual-credentialed professionals while automated platforms compress margins in standardized appeal workflows.
Pricing Analysis
Margin tightening in technology-enabled tiers reflects subscription pricing migration displacing contingency-based structures. Three-tier pricing structure across premium advisory, mid-market managed services, and self-service automation separates fee structures by client sophistication and portfolio scale. Cost-down pressure on cloud-based solutions accelerates because assessor offices in Texas and Florida are extending resolution timelines. Institutional owners with multistate portfolios demonstrate lowest price sensitivity; mid-market owners in Ohio and Illinois exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with the concentrated pipeline of professionals holding both MAI designations and state-level tax appeal certifications. Talent supply concentrates in the United States, Canada, and the United Kingdom where credentialing bodies maintain rigorous standards. Raw material dependencies include proprietary analytics platforms, geospatial data licenses, and API connections into Yardi, MRI Software, and CoStar systems. Regulatory restriction risk emanates from municipal digitization mandates forcing legacy system integration investments. Distribution runs through direct enterprise sales teams, channel partnerships with commercial real estate brokerages, and self-service platform deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The property tax services market operates as a supply-constrained environment where certified assessor scarcity props pricing power across premium advisory tiers.
For Market Incumbents: Anchor enterprise relationships through proprietary analytics platform development and deeper API integration into corporate real estate management systems. Defend against technology-enabled entrants by embedding tax attorneys earlier in engagement lifecycles as IRS scrutiny of conservation easement valuations intensifies. Prioritize certification pipeline investments to expand MAI-designated capacity in Texas and California. For New Entrants and Emerging Players: Municipal digitization mandates in mid-sized US counties open a window for automated self-service platforms targeting the 10-50 asset owner segment in Ohio, Illinois, and Georgia. ESG-linked valuation appeals present a penetrable white-space category as assessors struggle to value sustainability improvements. Pursue channel partnerships with regional commercial real estate brokerages as the primary go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by Big Four accounting firms seeking property tax vertical capabilities. Long-term viability hinges on technology platform differentiation rather than pure professional services scaling. Target acquisition archetypes feature specialized boutiques with machine learning appeal prediction tools. Monitor artificial intelligence adoption by municipal assessor offices as the critical inflection signal for human-intervention service demand.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Analytics Platform Development | Machine learning tools predicting assessment outcomes compress appeal cycles and improve success rates for Texas and Florida clients. |
| API Integration with CRE Management Systems | Seamless data exchange with Yardi, MRI Software, and CoStar platforms embeds providers deeper into enterprise client workflows. |
| Certification Pipeline Investment | Expanded MAI-designated capacity addresses the narrowing talent pool constraining firm expansion in high-demand jurisdictions. |
| ESG-Linked Valuation Advisory Practice | Green building certification expertise captures new appeal categories as assessors struggle to value energy efficiency upgrades. |
| Mid-Market Self-Service Platform Launch | Automated solutions penetrate the underserved 10-50 asset owner segment across Ohio, Illinois, and Georgia. |
Study Parameters
Independent corroboration across primary interviews with property tax directors, certified assessors, municipal valuation officers, and commercial real estate executives, combined with secondary validation from SEC 10-K filings, state department of revenue assessment manuals, and county appraisal district records, underwrites the qualitative findings. Bottom-up triangulation against top-down market sizing ensures consistency across volume and value estimates.
Rate-of-change decomposition separates volume effects from price-mix shifts across the projection horizon. The analytical framework models segmentation dimensions including service type, client portfolio scale, engagement pricing structure, and technology deployment maturity. CAGRs derive from historical trajectory analysis adjusted for regulatory catalysts and technology adoption curves. Forecast inputs incorporate municipal digitization mandate timelines and mass appraisal system deployment schedules.
The model assumes a particular technology adoption path; alternative pathways for artificial intelligence in assessor offices would alter the outlook. Forecasts reflect assumptions regarding certified professional pipeline expansion and cloud platform penetration rates. Specific risk factors include assessor resource constraints extending resolution timelines and data standardization gaps elevating delivery costs. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
Canada Real Estate Services Market
Real Estate Services
Green Lease Market
Real Estate Services
GCC Interior Design Services Market
Real Estate Services
Germany Real Estate Services Market
Real Estate Services
United States Real Estate Services Market
Real Estate Services
Latin America Coworking Spaces Market
Real Estate Services
Europe Real Estate Brokerage Market
Real Estate Services
Asia-Pacific Self Storage Market
Real Estate Services
United Arab Emirates Real Estate Services Market
Real Estate Services
United States Self Storage Market
Real Estate Services
US Home Service Market
Real Estate Services
Public Warehousing Market
Real Estate Services
Vietnam Self-Storage Market
Real Estate Services
Thailand Real Estate Market
Real Estate Services
Europe Coworking Spaces Market
Real Estate Services
Warehousing and Storage Services Market