
 Global Manufactured Housing Market | 2026-2036
Global Manufactured Housing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Manufactured Housing Market Outlook
The southeastern United States is reshaping competitive dynamics in manufactured housing production. Clayton Homes leverages its vertically integrated supply chain to control material costs and accelerate build times across its factory network. Skyline Champion sustains market presence through geographic diversification and brand portfolio breadth spanning multiple price tiers. Cavco Industries anchors its strategy in specialized retail financing and community ownership models that differentiate its customer capture approach.
Manufactured housing refers to residential structures built entirely in factory-controlled environments under federal or state building codes, then transported to permanent or semi-permanent sites for installation. These units typically employ steel chassis frames, vinyl or wood siding, and insulation systems rated for regional climate zones, with HUD Code compliance mandating specific wind load and thermal performance thresholds. Modular Homes command premium positioning due to their local-code compliance and conventional financing eligibility, while Tiny Homes attract margin-diluted but volume-expanding interest from minimalist lifestyle adopters. The First-time Buyers segment presents structural growth potential as conventional homeownership barriers intensify in high-cost metropolitan areas.
The U.S. Department of Housing and Urban Development enforces the HUD Code, which preempts local building standards and streamlines interstate shipment but creates compliance complexity for manufacturers targeting modular-code jurisdictions. The Consumer Financial Protection Bureau oversees lending practices under the Truth in Lending Act and SAFE Act, directly influencing buyer qualification rates and dealer inventory turnover. Stakeholders must monitor evolving zoning liberalization in California and Texas municipalities, where accessory dwelling unit ordinances and density bonus programs are altering site placement economics for factory-built units.
Market Dynamics
The manufactured housing sector is pivoting around the tension between federal standardization through the HUD Code and mounting pressure for climate-adaptive construction methods that exceed baseline thermal performance requirements.
Growth Catalysts
- HUD Code modernization:The U.S. Department of Housing and Urban Development's updated energy efficiency mandates are compelling factory retooling that reduces long-term operating costs for residents.
- Retiree demographic concentration:Aging populations across Florida, Arizona, and Texas are driving community-oriented living demand that manufactured housing uniquely satisfies through integrated amenity packages.
- Steel framing advances:Cold-formed steel chassis manufacturing is enabling larger module dimensions and improved structural integrity for multi-section units.
Market Restraints
- Lumber and OSB volatility:Input cost swings for engineered wood products compress margin predictability for producers without captive timber operations.
- Transportation radius limits:The economics of oversized load permitting restrict effective distribution to approximately 500-mile radii from assembly plants.
- Zoning fragmentation:Municipal ordinances in high-demand metropolitan counties continue to exclude manufactured housing through minimum square footage requirements and aesthetic design standards.
Strategic Opportunities
- ADU regulatory liberalization:California's accessory dwelling unit ordinances and density bonus programs are opening backyard placement channels previously inaccessible to factory-built units.
- Cross-laminated timber integration:The convergence of mass timber engineering with modular assembly methods offers carbon-sequestering alternatives to conventional stick-frame construction.
- Rural broadband infrastructure:USDA ReConnect program investments are enabling remote-work-capable manufactured communities in historically disconnected counties.
Industry Challenges
- Skilled installer scarcity:Certified setup contractor pipelines in Texas and the Carolinas cannot match community development timelines, creating site-readiness bottlenecks.
- Financing system bifurcation:The persistence of chattel lending alongside conventional mortgage availability creates consumer confusion and qualification friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Manufactured Housing Market |
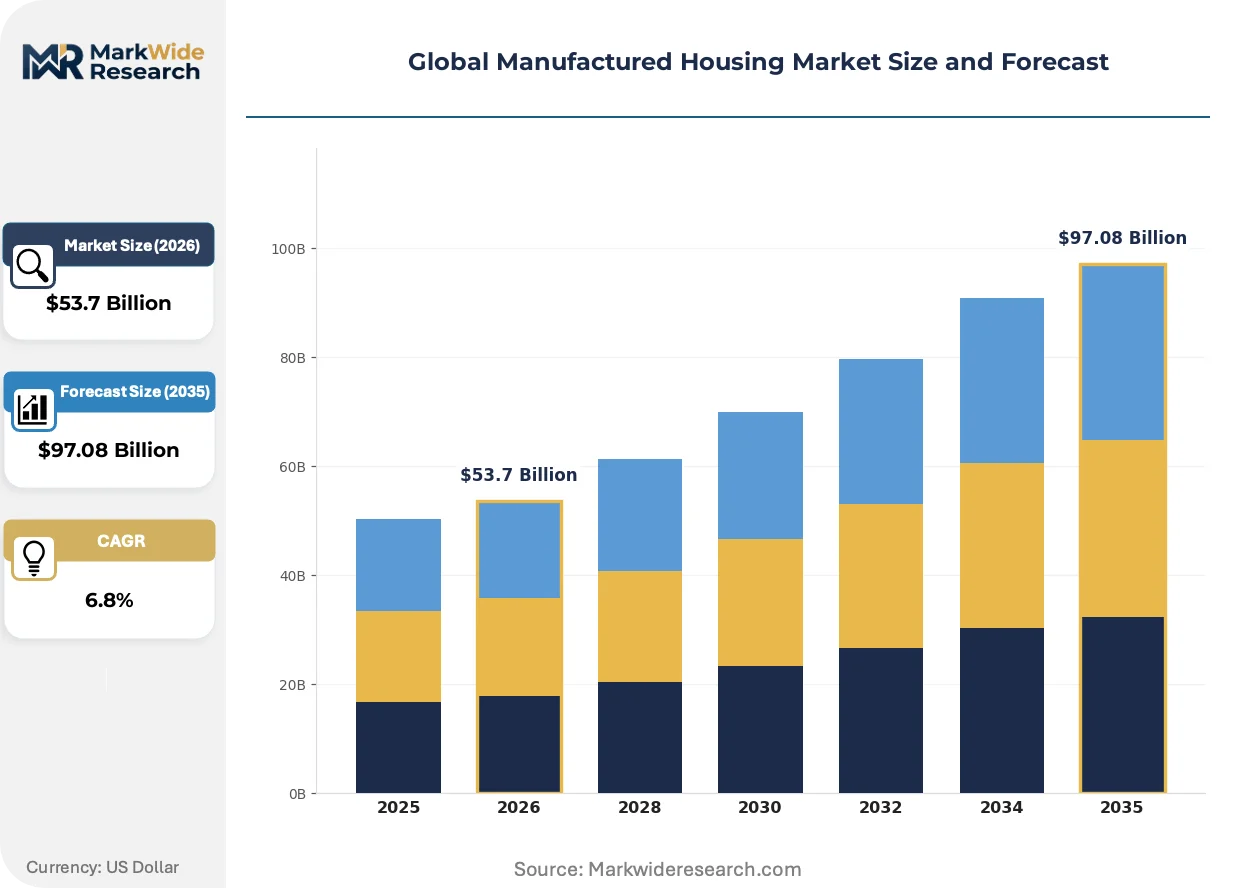
| Market Size in 2026 | $53.7 Billion |
| Market Size in 2035 | $97.08 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Homes, Prefabricated Homes, Mobile Homes, Tiny Homes End User: First-time Buyers, Investors, Retirees, Families Distribution Channel: Online Sales, Direct Sales, Retail Outlets, Brokers Price Tier: Budget, Mid-range, Luxury, Custom |
| Companies Covered | Clayton Homes, Skyline Champion, Cavco Industries, Champion Home Builders, Legacy Housing, American Home Star, Adventure Homes, Live Oak Homes, Berkshire Hathaway, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Manufactured Housing Market Strategic Shifts
Factory construction methods are undergoing material and process reinvention as energy performance targets tighten and buyer expectations for customization expand beyond traditional configuration limits.
Solar-integrated roofing systems are migrating from aftermarket installation to factory-integrated standard offerings. First-time buyers in high-insolation states like Arizona and New Mexico are specifying photovoltaic-ready electrical panels at rates that outpace national averages. This technology migration is compressing the installed cost gap between site-built and manufactured homes while complicating transportation logistics for oversize roof modules.
The EU Green Deal's building performance standards are pressuring modular exporters to certify products under dual compliance regimes. Manufacturers serving both North American and European markets must maintain parallel quality documentation systems. The modular home segment bears the heaviest documentation burden, as these units must satisfy local building codes rather than preemptive federal standards.
Community developers are consolidating land acquisition and retail financing functions under single ownership structures. This channel integration displaces the traditional dealer-network model in Florida and Georgia retirement corridors. The shift is most visible in age-restricted communities where developers capture margin from both unit sale and ongoing site lease revenue streams.
Global Manufactured Housing Market Segmentation
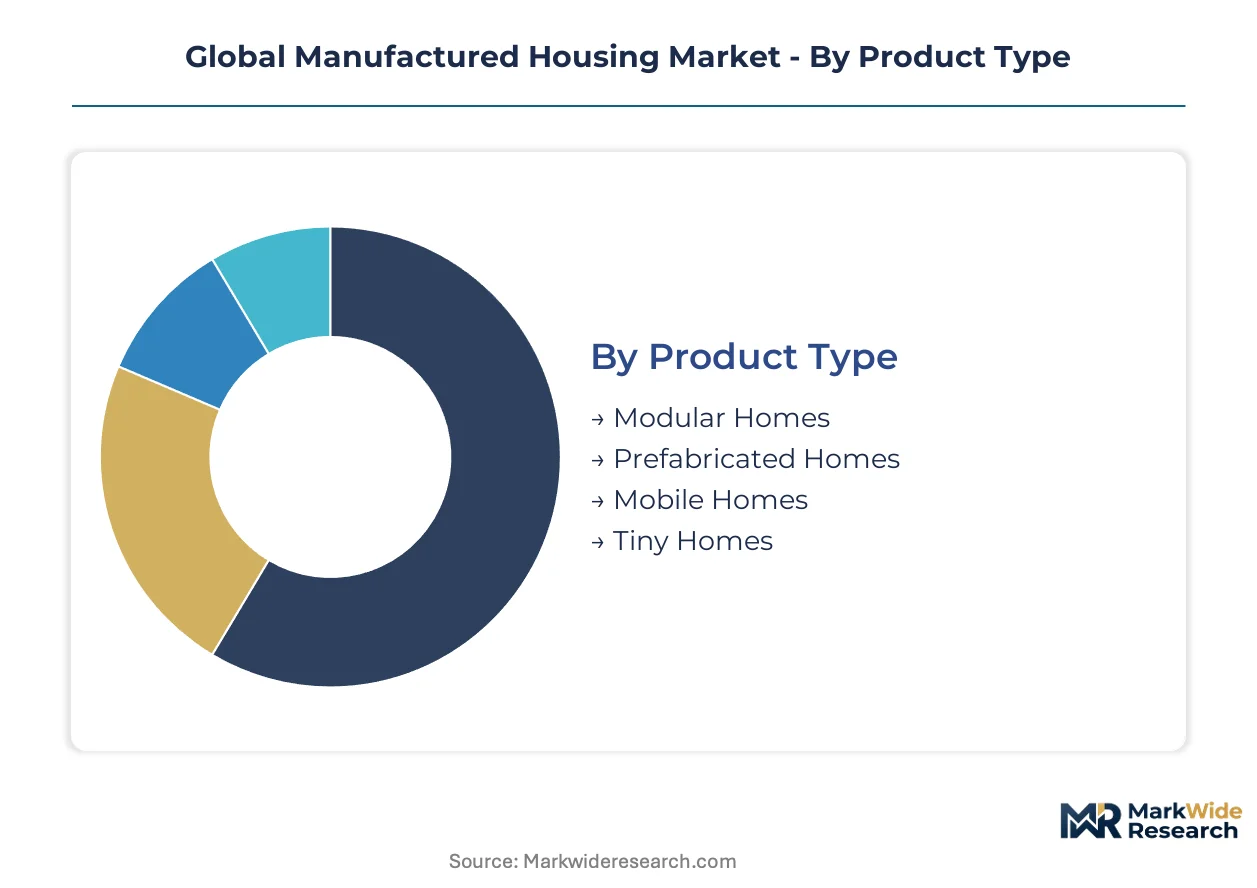
Segmentation in manufactured housing reveals how construction methods, buyer economics, and channel structures create distinct competitive battlegrounds. Each dimension carries unique margin profiles and regulatory exposure that shape capital allocation decisions across factory networks.
Product Type:
Construction methodology defines cost structures, code compliance pathways, and transportation logistics across factory-built residential categories.
- Modular Homes:Built to local building codes rather than federal HUD standards, enabling conventional mortgage financing and placement in jurisdictions with restrictive zoning. Demand concentrates in California and New York municipalities where accessory dwelling unit ordinances require code-compliant structures that blend with existing neighborhoods.
- Prefabricated Homes:Encompass panelized and pre-cut systems assembled on-site, offering customization flexibility between modular precision and site-built adaptability. Florida retirement corridors show accelerating adoption as developers seek faster envelope closure to compress community construction timelines.
- Mobile Homes:Traditional HUD Code-compliant units on permanent chassis, dominating rural and semi-rural placement in Texas and the Carolinas where land costs support large-lot configurations.
- Tiny Homes:Compact sub-400 square foot units targeting minimalist lifestyle adopters and backyard ADU placement, with Oregon and Colorado municipalities leading regulatory accommodation for reduced footprint dwellings.
Modular Homes command the established base. The steepest expansion runs through Tiny Homes.
End User:
Buyer demographics determine financing instrument selection, community amenity requirements, and unit specification complexity.
- First-time Buyers:Price-sensitive entrants priced out of conventional homeownership in high-cost metropolitan areas like Los Angeles and Seattle. These buyers concentrate in southeastern states where land availability and regulatory familiarity support entry-level community development with integrated financing packages.
- Retirees:Aging populations seeking affordable, community-oriented living arrangements with integrated healthcare access and recreational amenities. Arizona and Florida age-restricted communities capture disproportionate demand from this cohort.
- Investors:Institutional and individual buyers acquiring units for rental income streams, particularly active in Texas and Georgia where community ownership models generate recurring site lease revenue.
- Families:Multi-generational households requiring larger multi-section configurations with dedicated bedroom separation and expanded living space.
Retirees anchor volume concentration. First-time Buyers are gaining share fastest.
Distribution Channel:
Channel structure dictates customer acquisition costs, financing integration depth, and post-sale service responsibility allocation.
- Direct Sales:Factory-owned retail operations capturing margin from both manufacturing and distribution, prevalent in vertically integrated producer networks across the southeastern United States.
- Retail Outlets:Independent dealer networks providing localized market knowledge and customer financing facilitation, maintaining strong presence in Texas and Florida.
- Brokers:Intermediary arrangements connecting buyers with multiple manufacturer product lines, concentrated in markets with fragmented producer presence.
- Online Sales:Digital configuration and ordering platforms emerging for standardized product lines, with California and Washington state buyers showing highest digital engagement rates.
Retail Outlets maintain channel dominance. Online Sales show the steepest trajectory.
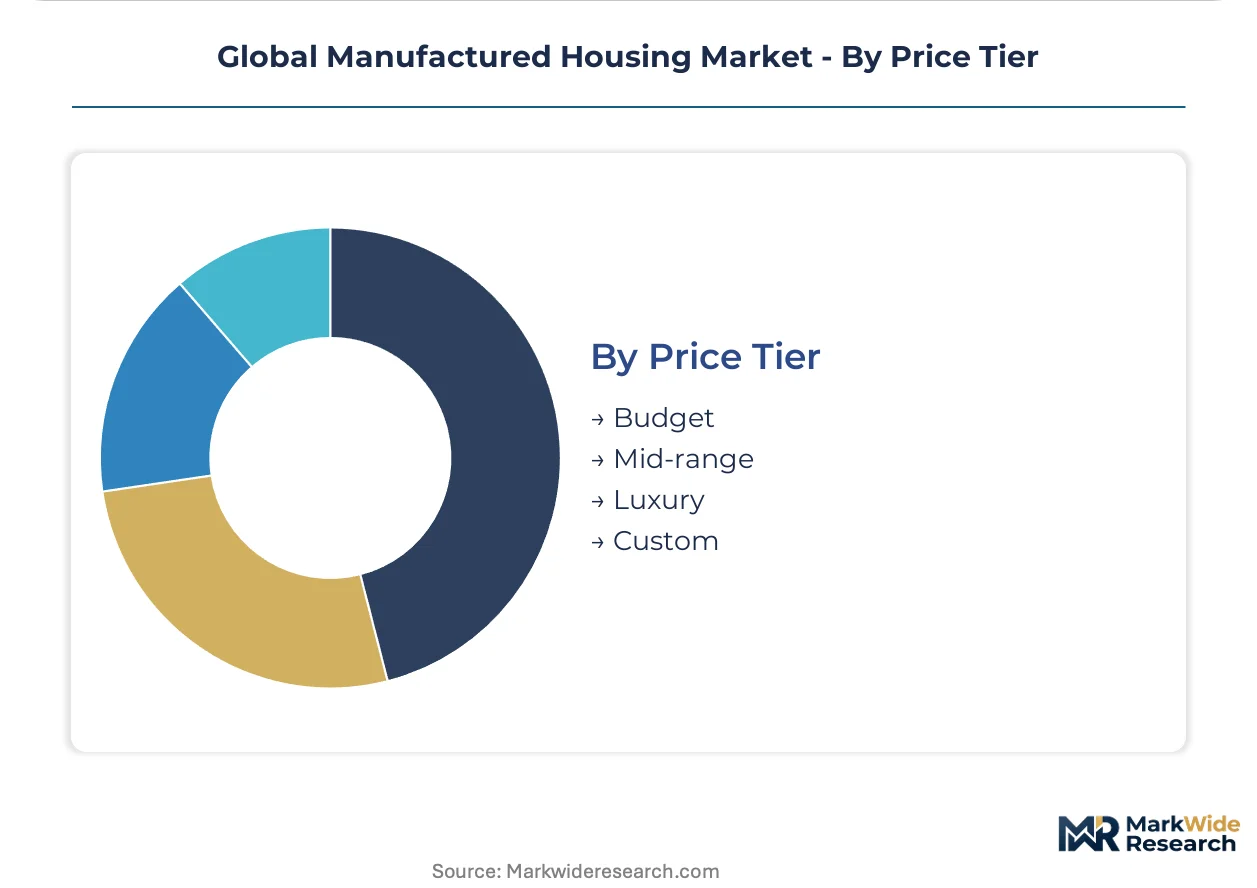
Price Tier:
Price positioning determines material specification, customization latitude, and financing instrument eligibility.
- Mid-range:Standard HUD Code-compliant units with upgraded insulation and finish packages, representing the volume core in Texas and Florida community developments where buyers prioritize value optimization over premium features.
- Luxury:High-end modular and manufactured configurations with site-built aesthetic integration, gourmet kitchen specifications, and smart home infrastructure. California and Colorado mountain markets show concentrated demand for elevated finish tiers.
- Budget:Entry-level single-section units minimizing cost per square foot through standardized specifications and high-volume production runs.
- Custom:Architect-designed modular systems with non-standard dimensions and premium material selections, serving distinctive site conditions and aesthetic requirements in high-value land markets.
Mid-range products anchor manufacturer volume. Luxury tier shows the steepest climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Factory networks cluster in jurisdictions where regulatory clarity and land availability intersect. The United States dominates production capacity, while Canada, Germany, Australia, and Japan develop distinct regulatory pathways for factory-built residential deployment.
United States
Retiree demand concentrates in Florida and Arizona age-restricted communities. The Department of Housing and Urban Development enforces the HUD Code, preempting local building standards for interstate shipment. Texas and the Carolinas host the densest manufacturing plant networks, where steel chassis fabrication and vinyl siding production integrate under single ownership structures.
Canada
Remote-work migration to smaller municipalities accelerates modular home orders in British Columbia and Ontario. Health Canada and the PMRA oversee material safety standards for residential construction inputs. Quebec's factory builders specialize in cold-climate insulation packages that exceed baseline thermal performance requirements for northern latitudes.
Germany
Energy retrofit mandates drive demand for high-efficiency modular units in Bavaria and North Rhine-Westphalia. The KBA regulates transport dimensions for oversized loads moving factory-built modules. Stuttgart's industrial corridor hosts engineering firms developing cross-laminated timber integration with modular assembly methods.
Australia
Housing affordability pressures in Sydney and Melbourne expand manufactured housing acceptance in New South Wales and Victoria. The TGA oversees material compliance, though state-level building codes govern final installation standards. Queensland's factory network specializes in cyclone-rated structural systems for coastal deployment.
Japan
Aging demographics and rural depopulation create demand for compact factory-built units in prefectures outside Tokyo-Osaka corridors. METI promotes prefabricated construction through industrial standardization programs. Nagoya's manufacturing belt concentrates precision timber-frame modular production for seismic-resistant applications.
Global Manufactured Housing Market Competitive Environment
Vertically integrated holding companies and specialized regional fabricators split the market into distinct operational models. The vendor base concentrates around three strategic archetypes: national-scale producers with captive retail financing, regional specialists optimizing transportation radius economics, and community developers integrating land acquisition with unit placement. Dominant competitive moves include backward integration into steel chassis manufacturing and geographic expansion through dealer network acquisition.
Among U.S.-based holding company structures, Clayton Homes and Cavco Industries exemplify vertically integrated archetypes combining factory production with retail distribution and financing origination. Skyline Champion occupies a position emphasizing geographic diversification across multiple factory locations. These three entities anchor the competitive structure, representing distinct approaches to customer capture through either financing integration, manufacturing scale, or brand portfolio breadth.
| Leading Market Players |
|---|
| Clayton Homes |
| Skyline Champion |
| Cavco Industries |
| Champion Home Builders |
| Legacy Housing |
| American Home Star |
| Adventure Homes |
| Live Oak Homes |
| Berkshire Hathaway |
| Others |
Value Chain & Pricing Dynamics
Steel chassis fabrication concentration in Texas and the Carolinas anchors margin capture for producers with captive metal-forming operations, while vinyl siding and engineered wood sourcing from dispersed regional mills creates cost volatility for non-integrated assemblers.
Pricing Analysis
The HUD Code dictates the pricing tier structure across factory-built residential categories, separating modular homes eligible for conventional mortgage financing from HUD-compliant units subject to chattel lending terms. Price differentiation rests on certification grade—local-code modular units command premiums over federal-standard manufactured products—and geographic delivery cost from plant to placement site. Cost compression in entry-level single-section units is intensifying because lumber and OSB input volatility compresses margin predictability for producers without captive timber operations. First-time buyers in southeastern states exhibit highest price sensitivity, while luxury modular purchasers in California mountain markets demonstrate lowest elasticity.
Supply Chain Analysis
Extended payment terms from engineered wood suppliers and supply-chain finance facilities from steel service centers enable working capital management across factory networks. Geographic supply concentration draws from the United States for steel chassis and vinyl siding, Canada for softwood lumber, and Mexico for appliance assemblies. Raw material dependencies rest on cold-formed steel, oriented strand board, and insulation batts rated for climate zones. Single-source vulnerability runs through specialized HUD-certified window manufacturers concentrated in Alabama and Georgia. Distribution runs through vertically integrated retail operations in the southeastern United States and independent dealer networks in Texas and Florida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward community developers consolidating land acquisition with retail financing functions, displacing traditional dealer networks and concentrating volume negotiation leverage among fewer large-scale purchasers.
For Market Incumbents: Insulate margin pools by deepening captive supply of steel chassis fabrication and accelerating factory retooling for solar-integrated roofing systems. The emergence of cross-laminated timber modular competitors threatens structural differentiation advantages. Channel control through community ownership models in Florida and Arizona retirement corridors provides defensive positioning against dealer-network displacement. For New Entrants and Emerging Players: California's accessory dwelling unit regulatory liberalization offers the most penetrable white-space for modular code-compliant units targeting backyard placement. Oregon and Colorado municipalities accommodating sub-400 square foot dwellings present secondary entry points for tiny home specialists. A direct-to-consumer digital configuration platform targeting high-insolation states can bypass established dealer infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated holding companies combining factory production with captive retail financing origination. Long-term viability favors entities controlling both unit manufacturing and recurring site lease revenue streams in age-restricted community developments. The signal to monitor is zoning ordinance liberalization in high-cost metropolitan counties, which would inflect placement economics for factory-built units.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Chassis Manufacturing | Captive metal-forming operations insulate margin from commodity volatility and accelerate build times. |
| Community Ownership Model Expansion | Integrated land acquisition and site lease revenue displace traditional dealer-network economics in retirement corridors. |
| Solar-Integrated Roofing Standardization | Factory-installed photovoltaic readiness compresses installed cost gap with site-built residential competitors. |
| Cross-Laminated Timber Modular Certification | Carbon-sequestering alternatives open premium positioning in jurisdictions with green building mandates. |
| Digital Configuration Platform Launch | Direct-to-consumer ordering reduces customer acquisition costs in California and Washington state markets. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of HUD Code regulatory filings, manufactured housing community development permits, and steel chassis production records. Primary interviews engaged factory operations directors, community developer acquisition leads, retail financing originators, and municipal zoning officers across Texas, Florida, California, and the Carolinas. Secondary validation drew from U.S. Census Bureau manufactured housing shipment data, Consumer Financial Protection Bureau lending practice disclosures, and state-level accessory dwelling unit ordinance databases. Bottom-up unit shipment tallies triangulate against top-down construction spending allocations.
Forecast inputs include HUD Code compliance cost trajectories, retiree demographic migration patterns, and zoning liberalization timelines across the analysis window. Segmentation modeling spans product type, end user demographic, distribution channel structure, and price tier positioning. CAGRs derive from regression analysis of historical shipment volumes against macroeconomic drivers including mortgage rate spreads and conventional home price indices. Industry-specific inputs incorporate steel price volatility indices and transportation radius economics from plant location data.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cross-laminated timber modular entrants or municipal zoning coalitions would shift outcomes. Macroeconomic deviation in interest rate environments, regulatory acceleration in energy efficiency mandates, or technological breakthroughs in factory automation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
Germany Residential Real Estate Market
Residential Real Estate Market
Egypt Manufactured Homes Market
Residential Real Estate Market
Indonesia Residential Real Estate Market
Residential Real Estate Market
France Condominiums and Apartments Market
Residential Real Estate Market
France Manufactured Homes Market
Residential Real Estate Market
Egypt Residential Real Estate Market
Residential Real Estate Market
Malaysia Real Estate Market
Residential Real Estate Market
Europe Residential Real Estate Market
Residential Real Estate Market
Mexico Residential Real Estate Market
Residential Real Estate Market
Asia Pacific Manufactured Homes Market
Residential Real Estate Market
Myanmar Residential Real Estate Market
Residential Real Estate Market
Real Estate Market
Residential Real Estate Market
Indonesia Real Estate Market
Residential Real Estate Market
North America Tiny Homes Market
Residential Real Estate Market
India Manufactured Homes Market
Residential Real Estate Market
Online Home Rental Market