
 Shellfish Extract Market | 2026-2036
Shellfish Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Shellfish Extract Market Analysis
Ingredient value-added processing is reconfiguring margin pools away from raw commodity trading toward refined bioactive concentrates. Aker BioMarine leverages Antarctic krill harvesting operations to secure vertical control over omega-3 phospholipid supply chains. Kerry Group anchors its position through enzymatic hydrolysis expertise that transforms shellfish biomass into standardized nutraceutical inputs. Symrise AG competes in flavor and fragrance applications, diverting extract volumes toward premium savory taste modulation.
Shellfish extract comprises concentrated bioactive compounds—principally chitin, chitosan, astaxanthin, and marine peptides—recovered through enzymatic hydrolysis, solvent extraction, or mechanical pressing of crustacean and mollusk biomass, serving functional food, cosmetic, and pharmaceutical formulation needs. Hydrolysates command the highest value per kilogram due to their bioavailability in sports nutrition and clinical dietary supplements, while powders dominate volume throughput for ingredient blending efficiency. Crustacean-sourced extracts lead revenue contribution because shrimp and crab processing waste streams offer the most scalable raw material base for industrial recovery operations.
FDA dietary supplement GMPs and EFSA novel food authorization pathways govern market access for new shellfish-derived ingredients in North America and Europe, compelling manufacturers to maintain batch-level traceability and allergen labeling compliance. BIS food safety standards and FSSAI ingredient approval processes in India add parallel certification burdens for exporters targeting emerging nutraceutical demand. Stakeholders must monitor evolving marine resource quotas and extraction effluent regulations that could restrict supply elasticity faster than formulation demand expands.
Market Dynamics
EU Green Deal sustainable sourcing mandates are compressing extraction facility certification timelines across coastal processing zones, forcing operators to revalidate waste-stream recovery protocols or forfeit market access in premium nutraceutical channels.
Growth Catalysts
- EFSA Novel Food Pathways:Standardized authorization frameworks in Europe accelerate ingredient commercialization timelines for chitosan and marine peptide concentrates, reducing regulatory uncertainty for functional food entrants.
- Sports Nutrition Formulation:Hydrolysate bioavailability advantages command premium positioning in clinical dietary supplements and athletic recovery products, pulling volume from commodity-grade powder alternatives.
- Norwegian Arctic Aquaculture Corridor:Cold-water species processing infrastructure concentrates premium chitin and astaxanthin recovery capacity, anchoring supply security for high-value concentrate manufacturers.
Market Restraints
- Crustacean Waste Stream Volatility:Shrimp and crab processing byproduct availability fluctuates with seasonal fishing quotas and aquaculture harvest cycles, constraining raw material planning horizons for continuous extraction operations.
- Allergen Labeling Burden:FDA dietary supplement GMPs and parallel FSSAI requirements in India mandate batch-level traceability systems that elevate compliance overhead for multi-destination exporters.
- Plant-Derived Chitosan Substitution:Fungal and insect-sourced chitin extraction technologies mature at competitive cost structures, threatening crustacean-derived product differentiation in cosmetic and pharmaceutical applications.
Strategic Opportunities
- Indian Nutraceutical Demand:BIS food safety standard alignment and FSSAI ingredient approval process maturation open formulation partnerships with domestic supplement manufacturers serving expanding middle-class wellness consumption.
- Cosmeceutical Peptide Convergence:Marine bioactive hydrolysates integrate with microbiome-targeted skincare science, creating white space in dermatological brand ingredient portfolios beyond traditional antioxidant positioning.
- EU Green Deal Certification Tailwinds:Sustainable sourcing mandate compliance differentiates European extraction facilities in procurement decisions by multinational functional food corporations with net-zero supply chain commitments.
Industry Challenges
- Enzymatic Hydrolysis Expertise Scarcity:Specialized biocatalysis talent for optimizing peptide yield and molecular weight distribution remains concentrated in limited academic and industrial research clusters, constraining process scale-up velocity.
- Multi-Jurisdiction Certification Timelines:Simultaneous pursuit of FDA, EFSA, and FSSAI approvals fragments regulatory affairs bandwidth and extends time-to-revenue for novel shellfish-derived ingredient launches.
- Legacy Cold-Chain Integration:Temperature-sensitive astaxanthin concentrate logistics require reconfiguration of existing seafood distribution infrastructure originally designed for frozen commodity products rather than high-value bioactive preservation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shellfish Extract Market |
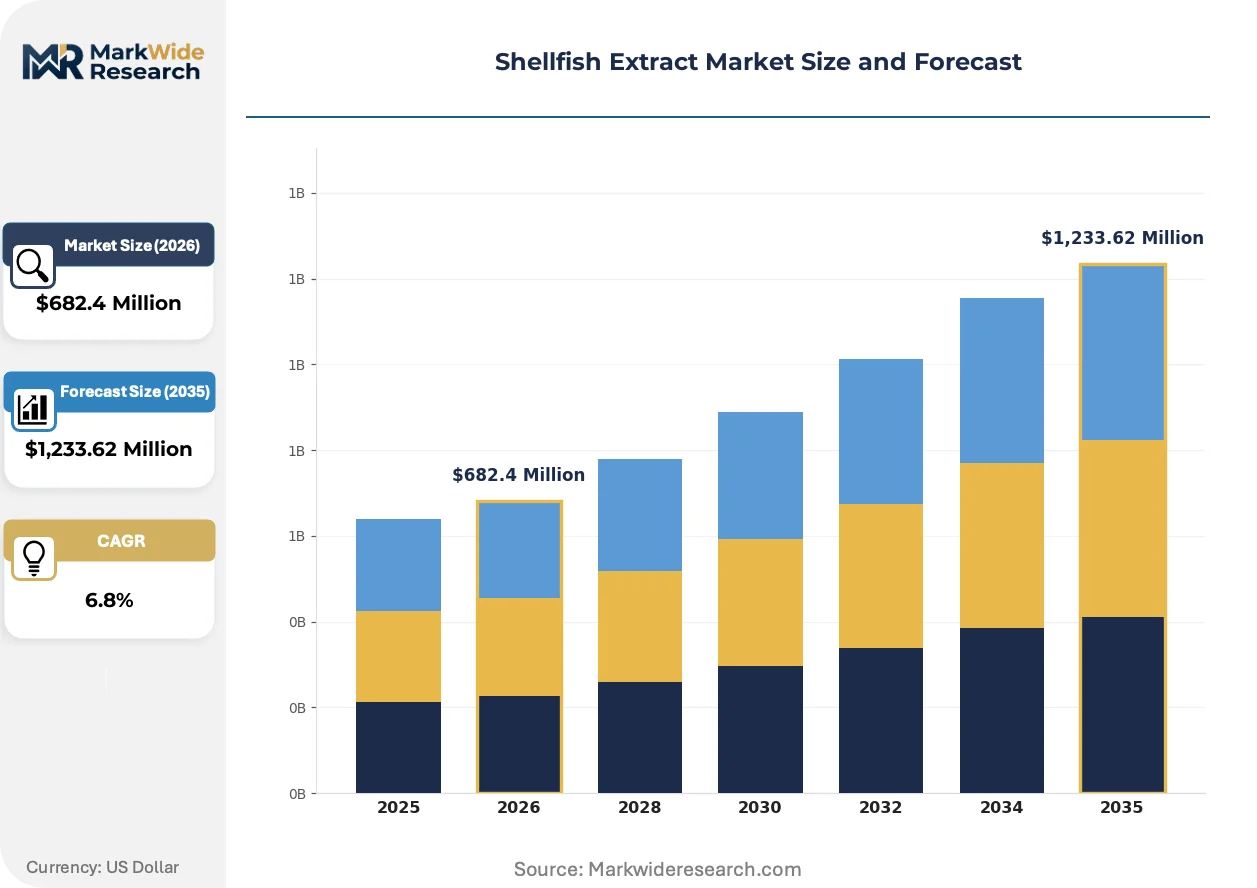
| Market Size in 2026 | $682.4 Million |
| Market Size in 2035 | $1,233.62 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolysates, Powders, Liquids, Extracts Application: Nutraceuticals, Food & Beverage, Cosmetics, Pharmaceuticals Source: Crustaceans, Mollusks, Marine Species, Others End User: Manufacturers, Retailers, Distributors, Research Institutions |
| Companies Covered | Nikken Foods, Aker BioMarine, Kakusan Foods Co., Azantis Inc., Norwegian Fish Oil AS, Kerry Group, Givaudan, Symrise AG, Brisan Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shellfish Extract Market Emerging Trajectories
Extraction technology convergence with precision fermentation and enzymatic engineering is redefining yield economics and molecular specificity in shellfish biomass recovery, compressing the viable scale threshold for industrial operations.
Supercritical carbon dioxide extraction systems for astaxanthin recovery from crustacean shell waste is rendering obsolete traditional solvent-based methods dependent on hexane and acetone chemistries. Cosmetic formulators in South Korea and Japan adopt these systems to meet clean-label certification requirements from retailers such as Sephora and Shiseido. The technology is rendering obsolete mid-scale extraction facilities unable to amortize capital intensity through premium concentrate output.
REACH authorization requirements for solvent residues in cosmetic and food-contact applications tighten acceptable thresholds for residual hexane in chitin-derived products, compelling extraction operators to validate alternative processing chemistries or exit European personal care supply chains. The regulation compresses margin structures for facilities lacking in-house analytical testing capabilities. German and French cosmetic ingredient distributors now require third-party REACH compliance documentation as a procurement gate.
Direct procurement relationships between nutraceutical brand houses and Antarctic krill harvesting operators displace traditional trader intermediaries in omega-3 phospholipid supply chains. Sports nutrition and clinical supplement manufacturers in Australia and the United States negotiate multi-year offtake agreements securing volume priority and origin traceability. This channel restructuring concentrates purchasing power among vertically integrated end-users while marginalizing speculative commodity traders lacking processing asset backing.
Shellfish Extract Market Segmentation
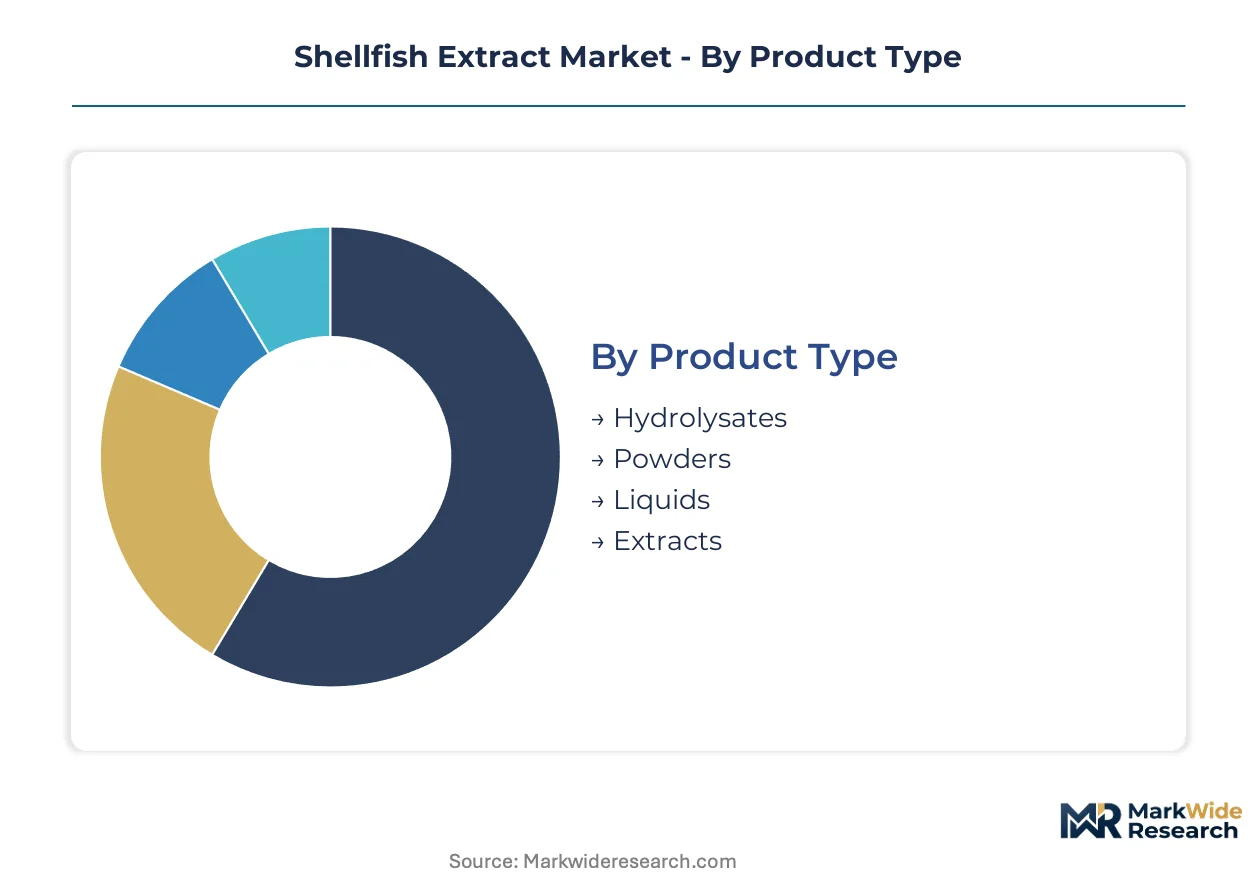
Shellfish extract value chains fragment across four intersecting dimensions that determine pricing power and margin capture. Product form dictates bioavailability economics, while application end-use governs regulatory pathway complexity and certification overhead.
Product Type:
Cost tier differentiation separates commodity-grade inputs from premium bioactive concentrates, with enzymatic processing intensity determining value realization.
- Hydrolysates:Enzymatically hydrolyzed marine peptides with molecular weights optimized for rapid absorption in sports nutrition and clinical dietary formulations. Demand concentrates in Norwegian Arctic processing corridors where cold-water species yield superior astaxanthin co-recovery, though enzymatic hydrolysis expertise scarcity constrains batch-to-batch consistency at scale.
- Powders:Spray-dried or freeze-dried concentrates standardized for ingredient blending efficiency in functional food manufacturing. Volume throughput dominates this segment, with procurement shifting toward automated dosing systems that require precise particle size distribution and moisture specifications.
- Liquids:Aqueous suspensions and oil-based concentrates serving flavor modulation and direct formulation applications. Symrise AG diverts significant volumes toward savory taste solutions where clean-label positioning commands procurement preference.
- Extracts:Solvent-recovered or supercritical CO2-derived isolates targeting pharmaceutical and cosmeceutical purity requirements. REACH authorization thresholds for residual solvents are compressing margin structures for facilities lacking in-house analytical validation.
Powders command the established base. The steepest expansion runs through hydrolysates.
Application:
End-use regulatory maturity determines market access velocity, with novel food authorization pathways creating divergence between established and emerging formulation channels.
- Nutraceuticals:Dietary supplements and functional foods leveraging chitosan, marine peptides, and omega-3 phospholipids for metabolic and cognitive health positioning. EFSA novel food standardization accelerates ingredient commercialization timelines, reducing uncertainty for entrants targeting sports nutrition and clinical supplement segments.
- Food & Beverage:Clean-label flavor enhancement and texture modification in premium savory and seafood analog products. South Korean and Japanese cosmetic formulators increasingly specify supercritical CO2-derived inputs to meet Sephora and Shiseido certification requirements.
- Cosmetics:Microbiome-targeted skincare integrating marine bioactive hydrolysates beyond traditional antioxidant positioning. Dermatological brand portfolios are expanding peptide convergence with cold-water species concentrates.
- Pharmaceuticals:Chitosan-based drug delivery systems and wound healing applications requiring GMP-compliant extraction and batch-level traceability. FDA dietary supplement GMPs and parallel FSSAI mandates in India elevate compliance overhead for multi-destination exporters.
Nutraceuticals anchor volume absorption. Cosmetics is climbing the fastest as peptide science converges with dermatological formulation.
Source:
Raw material availability follows coastal processing infrastructure and seasonal harvest cycles, with waste-stream recovery economics determining competitive positioning.
- Crustaceans:Shrimp and crab processing byproducts offer the most scalable industrial recovery base, anchoring revenue concentration across extraction operations. Norwegian Arctic aquaculture corridors concentrate premium chitin and astaxanthin capacity.
- Mollusks:Oyster and mussel biomass yields distinct peptide profiles and glycosaminoglycan fractions for specialized nutraceutical applications. Seasonal availability fluctuates with aquaculture harvest cycles.
- Marine Species:Antarctic krill harvesting secures vertical control over omega-3 phospholipid supply chains through direct procurement relationships displacing trader intermediaries.
- Others:Emerging cephalopod and echinoderm sources for niche bioactive applications in research-stage pharmaceutical development.
Crustaceans dominate supply security. Marine species is gaining share fastest through krill phospholipid offtake consolidation.
End User:
Customer type determines procurement sophistication, with specification requirements scaling from commodity trading to co-development partnerships.
- Manufacturers:Functional food, supplement, and cosmetic formulators requiring standardized inputs with certificate of analysis documentation and origin traceability. Kerry Group anchors position through enzymatic hydrolysis expertise transforming biomass into validated nutraceutical inputs.
- Retailers:Private-label supplement and wellness product channels with growing clean-label and sustainable sourcing specification requirements. EU Green Deal compliance differentiates European facilities in procurement decisions.
- Distributors:Ingredient traders and regional wholesalers facing margin compression as vertically integrated end-users negotiate direct offtake agreements.
- Research Institutions:Academic and clinical trial sponsors driving peptide characterization and novel application discovery, though volumes remain limited to pilot-scale procurement.
Manufacturers command specification authority. Retailers are expanding most quickly as private-label wellness portfolios deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Arctic processing corridors in Norway concentrate premium chitin and astaxanthin recovery capacity. Coastal extraction facilities cluster where cold-water species waste streams meet enzymatic hydrolysis infrastructure. Regulatory divergence across jurisdictions fragments certification timelines for multi-destination exporters.
Norway
Nutraceutical manufacturers source hydrolysates from Arctic aquaculture corridors for sports nutrition formulations. The EU Green Deal mandates sustainable sourcing certification for coastal processing facilities. Tromsø and Bergen anchor extraction operations where krill and cold-water shrimp byproducts yield premium bioactive concentrates.
United States
Sports nutrition brands negotiate direct procurement relationships with Antarctic krill harvesting operators for omega-3 phospholipid security. FDA dietary supplement GMPs enforce batch-level traceability and allergen labeling compliance. Massachusetts and California concentrate formulation partnerships between supplement manufacturers and extraction technology providers.
Germany
Cosmetic ingredient distributors require third-party REACH compliance documentation as a procurement gate for chitin-derived products. ECHA authorization thresholds for residual hexane tighten acceptable solvent residue limits. Hamburg and Bremen host analytical testing facilities validating alternative processing chemistries for personal care supply chains.
India
Domestic supplement manufacturers expand middle-class wellness portfolios driving crustacean-derived ingredient demand. FSSAI ingredient approval processes and BIS food safety standards add parallel certification burdens for importers. Maharashtra and Gujarat concentrate formulation partnerships between nutraceutical brands and coastal processing waste-stream recovery operations.
Japan
Cosmetic formulators adopt supercritical carbon dioxide extraction systems to meet clean-label certification requirements from premium retailers. METI standards govern novel food authorization for marine peptide concentrates. Osaka and Tokyo anchor peptide characterization research clusters linking academic institutions to dermatological brand development pipelines.
Shellfish Extract Market Vendor Landscape
Vertically integrated harvesters and specialized enzymatic processors split the market into distinct capability tiers. Three archetypes dominate: Antarctic krill operators controlling upstream phospholipid supply, enzymatic hydrolysis specialists transforming biomass into standardized inputs, and flavor houses diverting extract volumes toward taste modulation applications. Competitive moves concentrate on direct offtake agreements displacing trader intermediaries and supercritical extraction technology licensing for clean-label certification compliance.
Among vertically integrated marine operators, Aker BioMarine anchors the Antarctic harvesting tier through captive supply of krill-derived inputs. Kerry Group exemplifies the enzymatic processing archetype, leveraging hydrolysis expertise to convert crustacean biomass into validated nutraceutical-grade concentrates. Symrise AG occupies a position within the flavor and fragrance vector, redirecting shellfish extract volumes toward premium savory applications where clean-label positioning commands procurement preference.
| Leading Market Players |
|---|
| Nikken Foods |
| Aker BioMarine |
| Kakusan Foods Co. |
| Azantis Inc. |
| Norwegian Fish Oil AS |
| Kerry Group |
| Givaudan |
| Symrise AG |
| Brisan Group |
| Others |
Supply Flow & Price Mechanics
Norwegian Arctic aquaculture corridors concentrate premium chitin and astaxanthin recovery capacity, anchoring upstream supply scarcity that funnels margin capture toward enzymatic hydrolysis specialists and direct offtake negotiators rather than commodity traders.
Pricing Analysis
EU Green Deal sustainable sourcing mandates dictate the pricing tier structure across extraction facilities, separating REACH-compliant supercritical CO2-derived concentrates from solvent-based commodity grades. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, enzymatic processing intensity, and cold-chain logistics requirements. Pricing pressure stems from fungal and insect-sourced chitosan substitution technologies maturing at competitive cost structures. Contract manufacturers exhibit highest price sensitivity due to thin margin absorption of compliance overhead, while cosmetic formulators in South Korea and Japan demonstrate lowest sensitivity for clean-label certified inputs.
Supply Chain Analysis
Extended payment terms from Antarctic krill harvesting operators to sports nutrition brands are compressing working capital cycles for intermediary traders lacking processing asset backing. Raw material supply draws from Norway, India, and the United States, with crustacean waste stream availability fluctuating with seasonal fishing quotas and aquaculture harvest cycles. Enzymatic hydrolysis expertise scarcity and multi-jurisdiction certification timelines constitute single-source vulnerability for novel ingredient commercialization. Distribution runs through direct procurement relationships displacing speculative commodity channels, with vertically integrated end-users securing volume priority through multi-year offtake agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic hydrolysis expertise scarcity constrains batch-to-batch consistency at scale, creating asymmetric returns for operators that secure specialized biocatalysis talent clusters or licensing arrangements with academic research institutions.
For Market Incumbents: Entrench market position through captive supply arrangements with Antarctic krill harvesting operations and in-house analytical testing capabilities validating REACH-compliant alternative processing chemistries. Invest in enzymatic hydrolysis R&D partnerships with Norwegian Arctic processing corridors to defend against plant-derived chitosan substitution threats. Prioritize EU Green Deal certification investment to differentiate in procurement decisions by multinational functional food corporations.
For New Entrants and Emerging Players: Mid-scale extraction facilities in India serving domestic nutraceutical manufacturers represent the most penetrable entry point, given FSSAI process maturation and expanding middle-class wellness consumption. Cosmeceutical peptide convergence with microbiome-targeted skincare science offers white-space formulation partnerships beyond traditional antioxidant positioning. Pursue supercritical CO2 extraction technology licensing to meet Sephora and Shiseido clean-label certification requirements.
For Investors and Strategic Acquirers: Capital is best deployed toward enzymatic hydrolysis specialists with established EFSA novel food authorization track records and scalable peptide yield optimization capabilities. Long-term viability hinges on backward integration into cold-water species waste-stream recovery infrastructure rather than trader intermediary models. Monitor plant-derived chitosan cost parity achievements as inflection indicator for crustacean-derived product differentiation erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Licensing | Enables REACH compliance for cosmetic ingredient distributors in Hamburg and Bremen. |
| Direct Krill Offtake Agreements | Secures omega-3 phospholipid supply chains for Australian and US sports nutrition brands. |
| Enzymatic Hydrolysis R&D Partnerships | Addresses peptide yield optimization constraints in Norwegian Arctic processing corridors. |
| FSSAI Certification Investment | Opens formulation partnerships with Maharashtra and Gujarat supplement manufacturers. |
| Cold-Chain Infrastructure Reconfiguration | Preserves astaxanthin concentrate bioactivity through temperature-controlled logistics. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with enzymatic hydrolysis specialists, nutraceutical formulation scientists, cosmetic ingredient procurement managers, Antarctic krill harvesting operation executives, and regulatory affairs leads navigating EFSA novel food pathways. Secondary validation drew from EFSA novel food authorization databases, FDA dietary supplement GMP guidance documents, REACH authorization thresholds published by ECHA, BIS food safety standard notifications, and FSSAI ingredient approval registers. Bottom-up volume modeling across extraction facility capacity and top-down demand segmentation by application end-use were triangulated for consistency.
Calibration against historical authorization timelines and commercialization velocity informed projection reliability across the analysis window. Segmentation dimensions modeled include product form, application end-use, raw material source, and customer procurement sophistication tier. CAGRs were derived from slope analysis of normalized growth trajectories adjusted for regulatory pathway complexity and waste-stream recovery economics. Industry-specific forecast inputs incorporated seasonal crustacean processing byproduct availability patterns and enzymatic hydrolysis batch yield distributions.
Practitioners should monitor EU Green Deal certification mandate expansion, fungal chitosan extraction cost curves, and Antarctic krill harvest quota adjustments for early signals of supply elasticity constraints. Forecasts reflect documented assumptions regarding regulatory pathway standardization and enzymatic processing scale-up velocity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Japan Lobster Market
Seafood
North America Tuna Market
Seafood
Global Seafood Market
Seafood
Canned Salmon Market
Seafood
Smoked Whiting Market
Seafood
Asia-Pacific Seafood Market
Seafood
Japan Frozen Seafood Market
Seafood
United States Seafood Market
Seafood
Latin America Salmon Market
Seafood
Mussel Oil Market
Seafood
Edible Seaweed Market
Seafood
Dry-Packaged Scallops Market
Seafood
Fish Nutrition Market
Seafood
Fresh Fish Market
Seafood
Toothfish Market
Seafood
Canned Anchovy Market