
 Edible Seaweed Market | 2026-2036
Edible Seaweed Market Size, Share, and Industry Trends Forecast 2026-2036
Edible Seaweed Market Foresight
South Korea is narrowing the gap between artisanal harvest volumes and industrial food-grade demand through automated offshore farm expansion. Cargill Incorporated leverages its global ingredient distribution network to supply hydrocolloid extracts to multinational food processors. Acadian Seaplants anchors North American supply with land-based cultivation systems that sustain year-round output consistency. DuPont competes in the premium hydrocolloid segment with specialized alginate and carrageenan portfolios for pharmaceutical and food binding applications.
Edible seaweed comprises macroalgae biomass harvested from marine environments, containing bioactive polysaccharides such as alginates, carrageenans, and agars that function as gelling, thickening, and stabilizing agents across food and industrial formulations. The primary commercial purpose centers on delivering functional hydrocolloids and nutrient-dense whole foods to manufacturers seeking plant-based alternatives to synthetic additives. Nori dominates volume in direct-to-consumer food applications, while extracts command the widest margin pools through pharmaceutical and cosmetic ingredient supply. Dried form products sustain the largest revenue base across supermarkets and health food stores, though powder and extract forms are gaining traction in functional food and nutraceutical channels.
The EU Novel Food Regulation and EFSA safety assessments govern species authorization and labeling claims for seaweed products entering European food and supplement markets. South Korea's Ministry of Oceans and Fisheries enforces aquaculture licensing and heavy metal testing protocols that shape export eligibility for domestic producers. The US FDA oversees GRAS determinations for new seaweed-derived food ingredients under the Federal Food, Drug, and Cosmetic Act. Stakeholders must monitor evolving novel food approval timelines and traceability mandates as regulatory divergence between major consuming regions intensifies supply chain complexity.
Market Dynamics
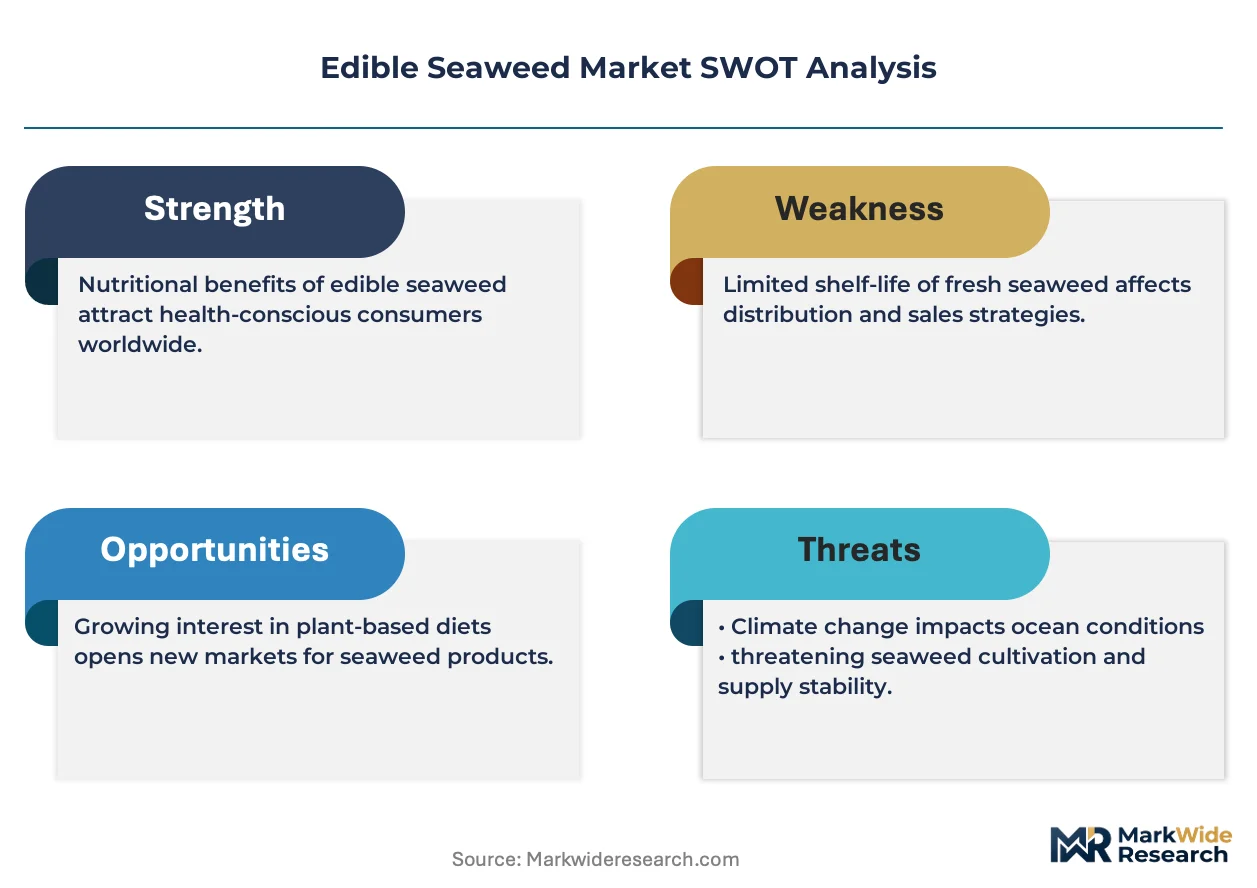
Automated offshore cultivation systems are compressing the artisanal-industrial supply gap while EU Novel Food Regulation compliance timelines fragment European market entry pathways for new species approvals.
Growth Catalysts
- Plant-based protein substitution:Food manufacturers in Germany and the Netherlands are expanding certified organic seaweed procurement as dairy and meat alternatives absorb hydrocolloid gelling agents for texture replication.
- EU Novel Food Regulation streamlining:EFSA safety assessment harmonization is accelerating species authorization for red and brown algae biomass entering supplement and functional food channels.
- Jeolla cultivation cluster expertise:South Korea's southwestern coastal region concentrates multi-generational nori farming knowledge that feeds automated farm scaling for export-grade production.
Market Restraints
- Heavy metal bioaccumulation:Arsenic and iodine uptake variability in wild harvests forces costly batch testing under South Korea's Ministry of Oceans and Fisheries export protocols.
- Input cost volatility:Synthetic rope and flotation equipment prices swing with petrochemical indices, squeezing margins for open-water farm operators dependent on polymer-based infrastructure.
- Species substitution threat:Fermentation-derived cellulose and microbial gums are displacing alginate and carrageenan in cost-sensitive food binding applications.
Strategic Opportunities
- Underpenetrated US functional food channel:GRAS determination pathways for novel seaweed-derived ingredients remain underutilized by domestic processors seeking clean-label positioning.
- Regenerative aquaculture incentives:EU Green Deal carbon sequestration crediting for ocean-based biomass production creates subsidy tailwinds for integrated multi-trophic farm expansion.
- Pharmaceutical-grade extract demand:Biopharma contract manufacturers are sourcing sulfated polysaccharides for drug delivery matrices, opening margin pools beyond food-grade hydrocolloid supply.
Industry Challenges
- Phycology talent scarcity:Commercial-scale macroalgae cultivation expertise concentrates in aging farming communities, constraining technical workforce expansion for automated system operation.
- Novel food approval timelines:EFSA dossier preparation and safety study completion cycles extend 18-36 months, freezing capital deployment for species diversification strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edible Seaweed Market |
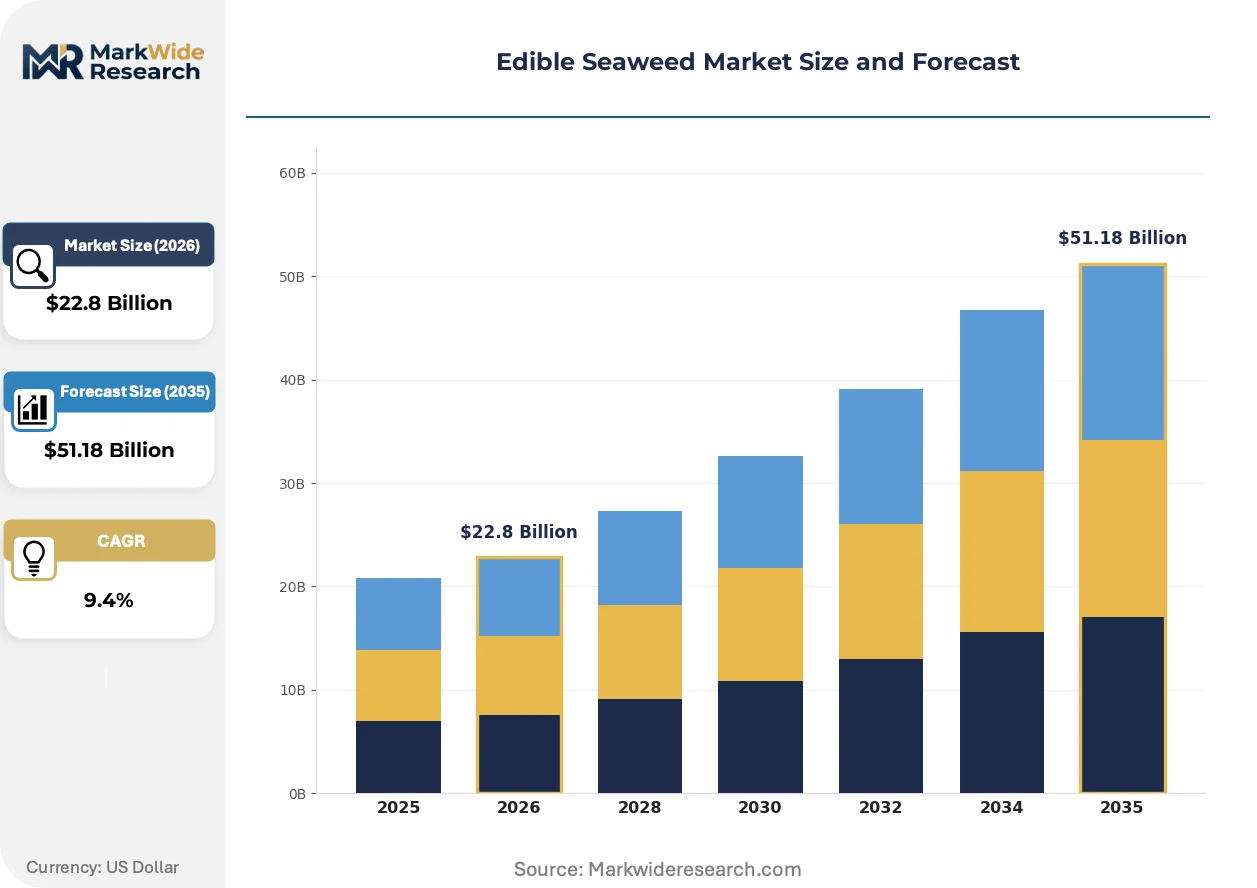
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $51.18 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nori, Kombu, Wakame, Dulse End Use: Food, Cosmetics, Pharmaceuticals, Animal Feed Distribution Channel: Online Sales, Supermarkets, Health Food Stores, Restaurants Form: Fresh, Dried, Powder, Extracts |
| Companies Covered | Cargill Incorporated, Acadian Seaplants, DuPont, Gelymar, Seaweed & Co., Algaia, Green Rise Agro Industries, Ocean Rainforest, Tate & Lyle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edible Seaweed Market Shifts & Advancements
Digital twin technology is compressing cultivation cycle optimization timelines while regulatory divergence between major consuming regions is fragmenting compliance architecture.
Sensor-integrated offshore monitoring platforms are virtualizing real-time biomass density and nutrient uptake tracking for floating farm arrays. Norwegian and Scottish operators are deploying these systems at pilot scale. The technology is virtualizing historical reliance on manual dive inspection and seasonal harvest estimation, compressing working capital cycles.
EFSA novel food safety assessment consolidation is standardizing heavy metal and allergen testing protocols for algae biomass entering European food and supplement markets. Industrial consequence includes dossier preparation cost reduction for multi-specification exporters. Brown algae-derived ingredients for hydrocolloid extraction face the steepest compliance burden under tightened iodine exposure limits.
Direct procurement relationships between food manufacturers and cultivation cooperatives are displacing layered trader intermediaries in dried nori and wakame supply. German and Dutch plant-based protein processors are establishing annual offtake agreements with Jeolla region farming associations. This channel compression is most visible in organic-certified biomass streams where traceability documentation requirements exceed commodity-grade tolerance.
Edible Seaweed Market Segmentation
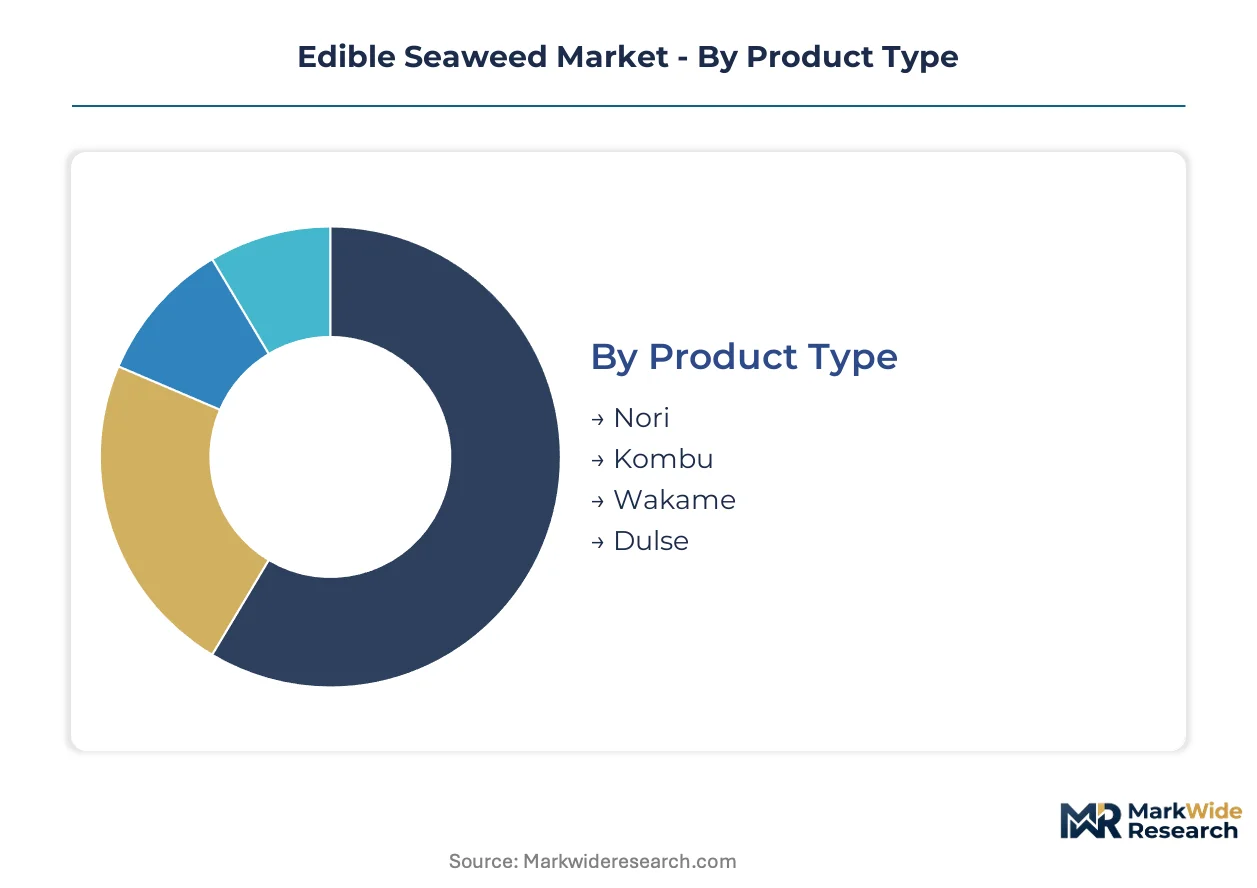
Segmentation in edible seaweed reveals how functional properties and supply chain economics split procurement strategies across food manufacturers, cosmetic formulators, and pharmaceutical extractors. Each dimension carries distinct margin profiles and regulatory compliance burdens that reshape competitive positioning.
Product Type:
Volume concentration and margin differentiation across species reflect cultivation scalability and extraction complexity.
- Nori:Thin-sheet red algae biomass dominates direct-to-consumer food applications with standardized drying and toasting protocols. Japanese and South Korean restaurant supply chains absorb the highest throughput volumes, though Jeolla region automated farm expansion is compressing seasonal supply gaps.
- Kombu:Thick-leaf brown algae delivers the highest natural glutamate concentration for umami extraction and dashi stock production. Premium Japanese culinary channels sustain pricing power, while industrial hydrocolloid processors extract alginates for food binding matrices.
- Wakame:Tender green-brown fronds serve prepared salad and instant soup applications with shorter rehydration cycles.
- Dulse:Red algae flakes target specialty health food positioning with elevated mineral density profiles.
Nori commands the established base. The steepest expansion runs through Kombu as alginate demand climbs in plant-based protein texturization.
End Use:
Application-driven demand splits between commodity food-grade throughput and premium extract value capture.
- Food:Hydrocolloid gelling, thickening, and stabilizing functions absorb the widest species range across processed meat alternatives, dairy substitutes, and instant noodle seasoning. German and Dutch plant-based manufacturers are expanding certified organic procurement from Jeolla cultivation cooperatives.
- Pharmaceuticals:Sulfated polysaccharide extraction for drug delivery matrices and wound dressing applications commands the highest purity premiums. EFSA novel food dossier requirements and FDA GRAS pathways create divergent compliance architectures for entrants.
- Cosmetics:Marine bioactive incorporation into moisturizing and anti-aging formulations relies on polysaccharide film-forming properties.
- Animal Feed:Iodine-rich supplements for aquaculture and livestock rations compete on mineral density specifications against synthetic alternatives.
Food absorbs the volume concentration. Pharmaceuticals deliver the margin expansion trajectory.
Distribution Channel:
Channel selection determines traceability documentation depth and price realization.
- Supermarkets:Packaged dried nori and wakame sustain the largest retail revenue base with standardized shelf-stable formats. Multi-national grocery chains in Germany and the Netherlands are tightening organic certification requirements for own-label seaweed products.
- Online Sales:Direct-to-consumer powder and extract formats bypass layered distributor margins, though cold-chain constraints limit fresh biomass penetration. Subscription models for functional food ingredients are gaining traction among nutraceutical buyers.
- Health Food Stores:Premium positioning for dulse flakes and specialty kombu variants depends on staff education and sampling investment.
- Restaurants:Bulk dried sheet procurement for sushi and Korean cuisine operators concentrates in ethnic supply wholesalers.
Supermarkets anchor the revenue base. Online sales are climbing the fastest as powder and extract formats bypass traditional distribution layers.
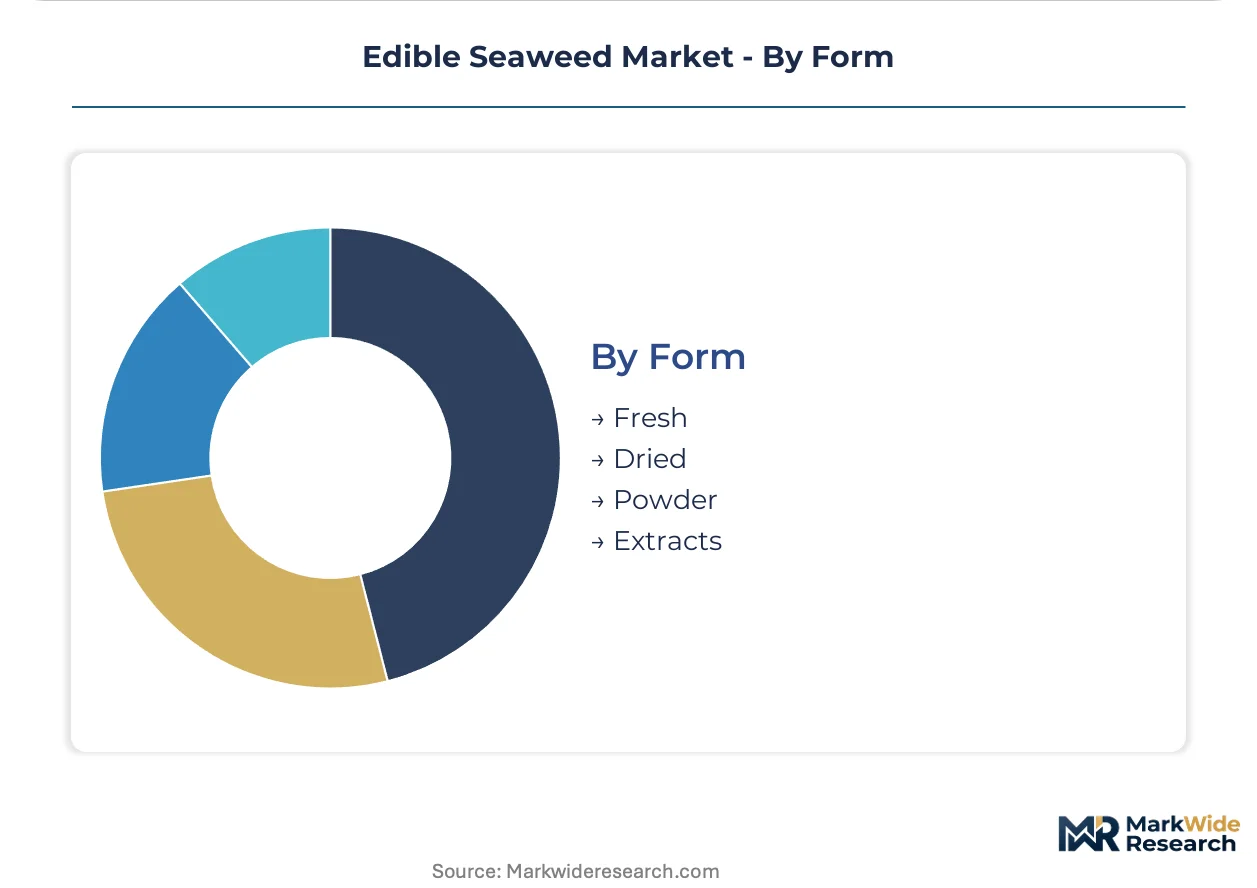
Form:
Processing intensity separates commodity throughput from value-added extraction economics.
- Dried:Shelf-stable whole-leaf and sheet formats sustain the largest installed production base with minimal processing infrastructure. South Korean Ministry of Oceans and Fisheries heavy metal testing protocols shape export eligibility for batch-labeled products.
- Extracts:Refined alginate, carrageenan, and agar hydrocolloids command the widest margin pools through pharmaceutical and industrial applications. DuPont and Cargill distribution networks concentrate supply to multinational food processors.
- Powder:Milled biomass for functional food and nutraceutical incorporation requires grinding and packaging investment with shorter working capital cycles.
- Fresh:Perishable whole algae serves niche restaurant and direct consumption channels with geographic radius constraints.
Dried forms hold the volume concentration. Extracts are expanding most quickly as biopharma contract manufacturers source sulfated polysaccharides for drug delivery matrices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automated offshore cultivation clusters in South Korea and Japan concentrate the artisanal-industrial transition, while European novel food compliance and North American functional food underpenetration create divergent entry economics for biomass exporters.
South Korea
Jeolla region farming cooperatives supply automated nori farms scaling for export-grade sheet production to German and Dutch plant-based manufacturers. The Ministry of Oceans and Fisheries enforces heavy metal testing protocols that shape batch-labeled export eligibility. Gwangju-Honam processing hubs integrate sensor-integrated monitoring platforms for real-time biomass density tracking.
Japan
Premium culinary channels sustain kombu pricing power through traditional dashi stock and umami extraction demand. METI oversees aquaculture licensing frameworks that govern offshore farm expansion in coastal prefectures. Hokkaido cultivation zones concentrate multi-generational kelp farming expertise feeding industrial alginate supply to pharmaceutical extractors.
Germany
Plant-based protein processors expand certified organic seaweed procurement for dairy and meat alternative texturization. EFSA novel food safety assessments standardize heavy metal and allergen testing protocols under EU regulatory harmonization. Hamburg and Bremen port logistics clusters handle bulk dried nori imports from Jeolla region cooperatives.
United States
Functional food and nutraceutical channels remain underpenetrated for novel seaweed-derived ingredients seeking GRAS determination pathways. The FDA oversees food additive safety assessments that create compliance architecture divergence from European novel food frameworks. Pacific Northwest coastal operations pilot land-based cultivation systems for year-round output consistency.
Norway
Offshore kelp farm operators deploy digital twin technology for cultivation cycle optimization at commercial scale. The Norwegian Food Safety Authority aligns with EFSA protocols for algae biomass entering European supplement markets. Trøndelag and Nordland county cultivation zones concentrate macroalgae biomass production for hydrocolloid extraction.
Edible Seaweed Market Competitive Landscape
Ingredient distributors and cultivation specialists split the market into divergent margin pools, with hydrocolloid extractors commanding premium pricing through pharmaceutical-grade purity tiers while farm operators compete on biomass throughput scale. Three archetypes dominate: multinational ingredient distributors with global logistics networks, regional cultivation cooperatives with automated farm assets, and specialized extractors with refined alginate and carrageenan portfolios. Competitive moves concentrate on direct procurement relationship formation with food manufacturers and capacity expansion into land-based controlled-environment systems.
Within the multinational distributor tier, Cargill Incorporated anchors supply chain positioning through global ingredient distribution infrastructure. DuPont occupies a position in specialized hydrocolloid extraction for pharmaceutical and food binding applications. Acadian Seaplants exemplifies regional cultivation specialization with land-based systems sustaining North American supply consistency. These three entities represent the archetype spectrum from logistics-scale distribution through premium extract refinement to integrated farm-to-ingredient production.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Acadian Seaplants |
| DuPont |
| Gelymar |
| Seaweed & Co. |
| Algaia |
| Green Rise Agro Industries |
| Ocean Rainforest |
| Tate & Lyle |
| Others |
Supply & Pricing Matrix
Busan-Rotterdam container freight corridors transmit petrochemical-index volatility from synthetic rope and flotation equipment through to open-water farm operators, compressing margins for biomass exporters while creating tiered price separation between artisanal harvest cooperatives and automated offshore producers serving German plant-based manufacturers.
Pricing Analysis
EU Novel Food Regulation dictates the pricing tier structure across European edible seaweed procurement. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade extract purity from food-grade hydrocolloid specifications and commodity dried biomass. Cost compression in standard-tier food-grade supply is intensifying because fermentation-derived cellulose substitutes displace alginate and carrageenan in cost-sensitive binding applications. German and Dutch plant-based protein processors exhibit the least price sensitivity for organic-certified biomass with full traceability documentation, while Asian restaurant supply wholesalers absorb economy-tier dried nori with minimal certification requirements.
Supply Chain Analysis
Wild macroalgae biomass and cultivated nori fronds anchor upstream feedstock sourcing for downstream hydrocolloid extraction. Supply concentrates in South Korea's Jeolla region, Japan's Hokkaido cultivation zones, and Norway's Trøndelag county kelp farms. Synthetic rope, flotation equipment, and sensor-integrated monitoring platforms constitute critical input dependencies tethered to petrochemical supply chains. Single-source vulnerability runs through South Korean Ministry of Oceans and Fisheries heavy metal testing protocols that gate export eligibility for batch-labeled products. Distribution runs through direct procurement relationships between Jeolla farming cooperatives and German plant-based manufacturers, displacing layered trader intermediaries in organic-certified biomass streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edible seaweed markets present a service-attach opportunity as subscription-based traceability documentation and certification renewal revenues expand faster than raw biomass throughput. Recurring revenue from automated farm monitoring-as-a-service layers outpaces commodity sheet sales growth.
For Market Incumbents: Entrench defensive positioning through backward integration into land-based controlled-environment cultivation systems that sustain year-round output consistency beyond seasonal wild harvest limitations. Cargill Incorporated and DuPont should deepen captive supply of pharmaceutical-grade alginate and carrageenan portfolios to offset fermentation-derived cellulose substitution threats in food binding applications. Certification investment in EU Novel Food Regulation dossier preparation creates switching costs for German and Dutch plant-based manufacturers.
For New Entrants and Emerging Players: Pursue underpenetrated US functional food channels where FDA GRAS determination pathways for novel seaweed-derived ingredients remain underutilized by domestic processors seeking clean-label positioning. The most penetrable segment lies in pharmaceutical-grade sulfated polysaccharide extraction for biopharma contract manufacturers, where purity premiums exceed food-grade hydrocolloid margins. A go-to-market angle anchored in regenerative aquaculture carbon sequestration crediting under EU Green Deal frameworks differentiates offerings for sustainability-focused European buyers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with non-core hydrocolloid extraction assets lacking pharmaceutical-grade purity tier focus. Long-term viability across the analysis window hinges on exposure to pharmaceutical and biopharma contract manufacturing demand rather than commodity food-grade supply. The signal to watch is EFSA novel food approval timeline compression for red and brown algae species, which would unlock capital deployment for species diversification strategies and validate premium positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Offshore Farm Expansion | South Korea's Jeolla region deploys sensor-integrated platforms to compress artisanal-industrial supply gaps for export-grade nori. |
| Land-Based Controlled-Environment Cultivation | Acadian Seaplants anchors North American supply consistency through year-round biomass production independent of seasonal wild harvest cycles. |
| Pharmaceutical-Grade Extract Refinement | DuPont captures premium margin pools through specialized alginate portfolios for drug delivery matrices and wound dressing applications. |
| Direct Procurement Relationship Formation | German plant-based manufacturers displace layered trader intermediaries through annual offtake agreements with Jeolla farming cooperatives. |
| EU Novel Food Regulation Dossier Investment | EFSA safety assessment harmonization accelerates species authorization for algae biomass entering European supplement and functional food channels. |
Research Methodology
A standing panel of aquaculture farm operators, hydrocolloid extraction plant managers, regulatory affairs specialists at EFSA and FDA, procurement leads at German plant-based food manufacturers, and pharmaceutical contract manufacturing executives provided ongoing calibration. Primary interviews with these stakeholders combined with secondary validation from EU Novel Food Regulation filings, South Korean Ministry of Oceans and Fisheries export protocol documentation, FDA GRAS determination databases, and customs trade data. Bottom-up biomass production estimates and top-down hydrocolloid demand triangulation anchored market sizing across the analysis window.
Scenario-bracketing around regulatory approval timeline variance and petrochemical input cost volatility shaped the analytical framework. Segmentation dimensions modeled include product type, end-use application, distribution channel, and form across the projection horizon. CAGRs derived from installed cultivation capacity expansion trajectories, EFSA dossier approval velocity assumptions, and pharmaceutical-grade extract demand elasticity. Industry-specific forecast inputs incorporated Jeolla region automated farm deployment schedules and EU Green Deal carbon sequestration crediting implementation progress.
Macroeconomic conditions sit as an overlay; deviation in container freight rates, petrochemical indices, and euro-dollar exchange rates would shift the trajectory for export-dependent biomass suppliers. Forecasts reflect assumptions about regulatory harmonization progress and substitution technology penetration that could revise outlooks if EFSA timelines extend or fermentation-derived hydrocolloids accelerate displacement. Cross-checking against UN Comtrade seaweed export statistics and Cefic hydrocolloid consumption surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Sea Bass Market
Seafood
Canned Seafood Market
Seafood
Canned Salmon Market
Seafood
Dried Scallop Market
Seafood
Organic Seafood Market
Seafood
Mussels Market
Seafood
United States Salmon Market
Seafood
United States Frozen and Canned Seafood Market
Seafood
Seafood Flavors Market
Seafood
Toothfish Market
Seafood
Asian Sea Bass Market
Seafood
United Arab Emirates Seafood Market
Seafood
United States Plant-Based Seafood Market
Seafood
China Crustaceans Market
Seafood
Molluscs Market
Seafood
Fish Protein Hydrolysate Market