
 Smoked Whiting Market | 2026-2036
Smoked Whiting Market Size, Share, and Industry Trends Forecast 2026-2036
Smoked Whiting Market Analytics
Artisanal fish-smoking expertise is rotating toward industrial scale as European processors struggle to replicate traditional curing knowledge at volume. Leroy Seafood Group leverages its Nordic cold-chain infrastructure to sustain consistent supply of cold-smoked fillets across Northern Europe. Acme Smoked Fish Corp. anchors its position through specialized hot-smoked production lines serving food-service distributors. High Liner Foods competes by controlling frozen raw-material flows that stabilize input costs for processors.
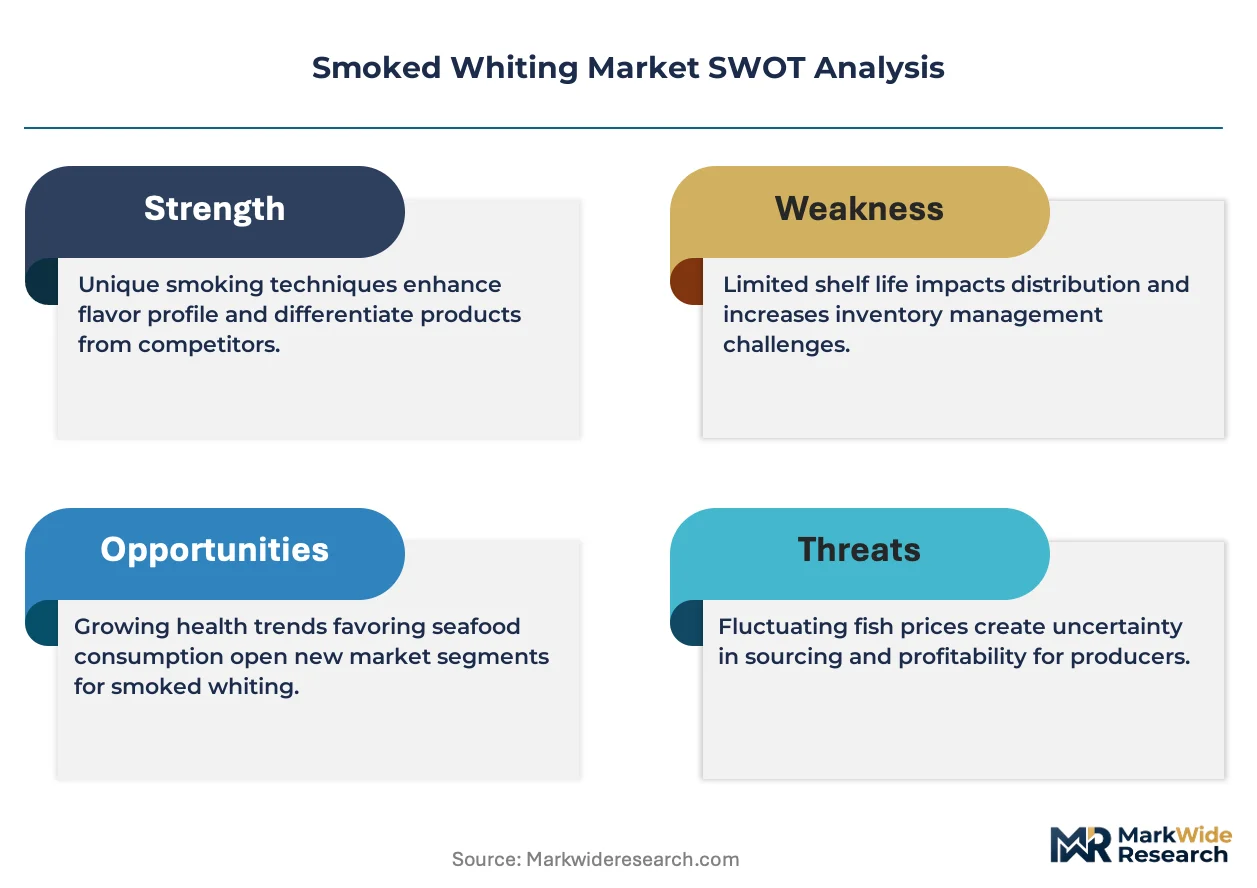
Smoked whiting denotes whiting fish (Merlangius merlangus) cured through controlled exposure to hardwood smoke at temperatures between 20°C and 80°C, yielding shelf-stable protein with moisture content below 70 percent and characteristic phenolic compounds from beech or oak combustion. The product serves retail and food-service channels as a ready-to-eat seafood item requiring no further preparation before consumption. Cold-smoked fillets occupy the premium tier where vacuum-sealed packaging extends chilled shelf life and commands higher margins than hot-smoked alternatives. Supermarkets and specialty stores dominate distribution volume, though online retail channels are capturing faster growth as direct-to-consumer seafood platforms expand refrigerated logistics coverage.
EU food safety frameworks including EFSA guidelines and national regulators such as BfR in Germany enforce strict limits on polycyclic aromatic hydrocarbons and microbiological contaminants in smoked fish products. REACH-compliant packaging materials and CE-marked processing equipment shape capital investment decisions for smokehouse operators. Stakeholders must monitor evolving cold-chain traceability requirements and alternative protein competition when allocating capacity between traditional curing methods and automated smoking systems.
Market Dynamics
Artisanal cold-smoking expertise faces industrialization pressure as European processors scale traditional curing methods. Smokehouse operators balance heritage protocols against automated throughput demands while EFSA polycyclic aromatic hydrocarbon limits tighten quality thresholds.
Growth Catalysts
- EU Food Safety Frameworks:EFSA guidelines and BfR enforcement in Germany elevate quality benchmarks that premium smoked whiting commands. Retailers favor certified suppliers.
- Food Service Channel Expansion:European restaurant operators add smoked whitefish as a premium protein alternative. Menu placement drives volume through specialized distributors.
- Beech and Oak Smoke Chemistry:Controlled hardwood combustion at 20°C to 80°C yields characteristic phenolic compounds. Consumer preference for authentic flavor profiles sustains premium pricing.
Market Restraints
- Raw Material Cost Volatility:Frozen whiting supply fluctuations destabilize processor margins. High Liner Foods controls frozen flows but spot market exposure persists for smaller smokehouses.
- Supply Concentration in North Sea Fisheries:Merlangius merlangus landings concentrate around Scottish and Norwegian waters. Climate-driven stock shifts threaten input security.
- Polycyclic Aromatic Hydrocarbon Limits:EFSA maximum residue levels restrict traditional smoking intensity. Compliance requires costly equipment upgrades or extended curing cycles.
Strategic Opportunities
- Direct-to-Consumer Refrigerated Logistics:Online seafood platforms expand cold-chain coverage. Smoked whiting reaches households bypassing supermarket slotting fees.
- REACH-Compliant Packaging Innovation:Vacuum-sealed barrier films extend chilled shelf life. Premium positioning justifies packaging investment against hot-smoked alternatives.
- German and UK Premium Positioning:Traditional fish-smoking heritage in Hamburg and Grimsby supports artisanal brand narratives. Regional identity commands price premiums.
Industry Challenges
- Curing Knowledge Transfer Gap:Master smokers retire faster than apprentices acquire sensory judgment. Automated systems replicate temperature curves but not organoleptic quality assessment.
- CE-Marked Equipment Capital Intensity:Smokehouse operators face six-figure investments for compliant processing lines. Smaller facilities delay modernization and risk regulatory exclusion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smoked Whiting Market |
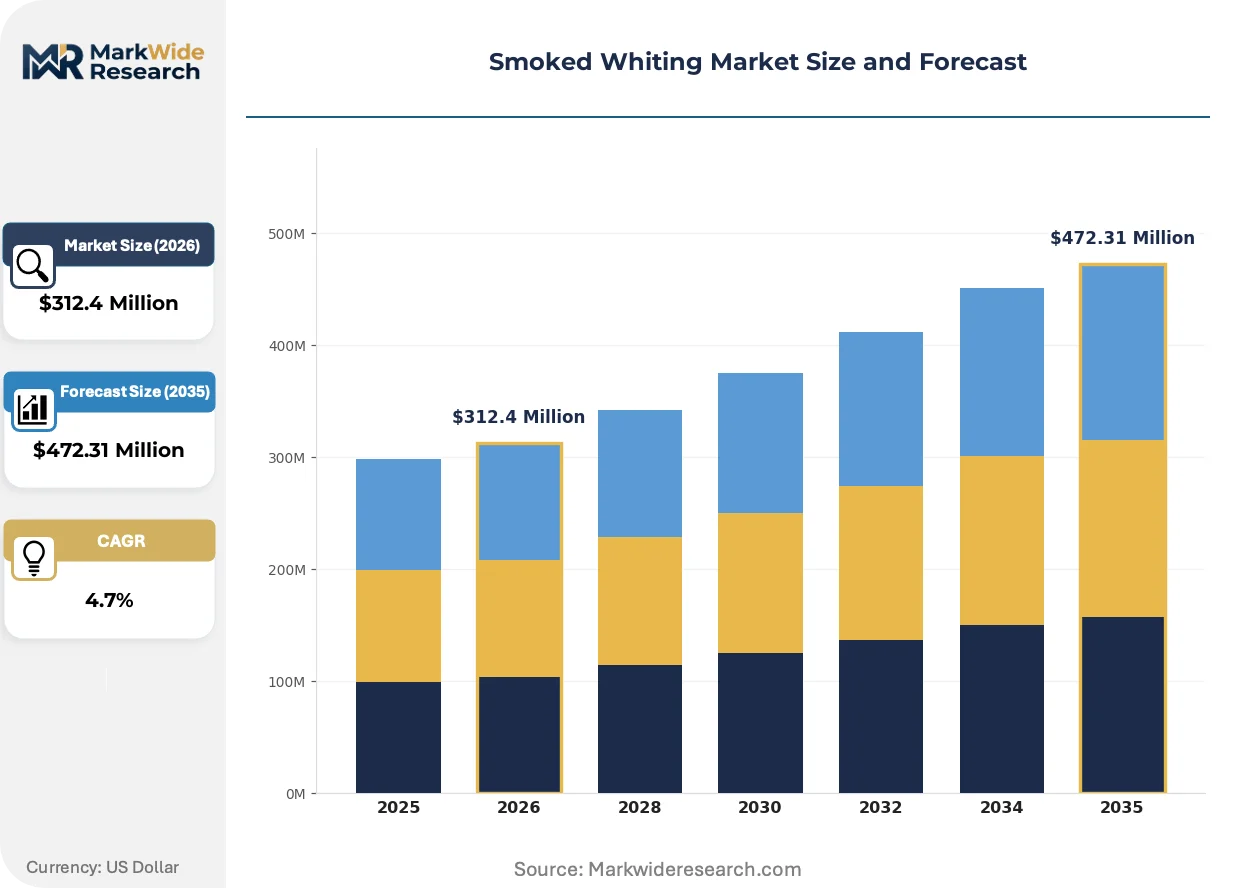
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot-Smoked, Cold-Smoked, Whole Fish, Fillets Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Fish Markets Packaging Type: Vacuum-Sealed, Modified Atmosphere, Canned, Plastic Containers Customer Type: Restaurants, Retailers, Food Service, Individuals |
| Companies Covered | Kraft Heinz, Leroy Seafood Group, Marine Harvest, Unilever, ConAgra, High Liner Foods, Nestle, 2 Sisters Food Group, Acme Smoked Fish Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smoked Whiting Market Evolving Landscape
Smokehouse automation is fragmenting traditional craft boundaries while regulatory chemistry limits and direct-to-consumer channels reconfigure value capture. Three developments dominate this transition.
Electrostatic precipitation technology for smoke particle filtration is decomposing conventional smokehouse ventilation economics. German processors in Hamburg and Bremen adopt these systems to meet BfR air emission standards without sacrificing throughput. The technology compresses facility upgrade timelines from years to months while preserving phenolic compound profiles.
REACH compliance deadlines for food-contact materials are accelerating packaging supplier consolidation. Vacuum-sealed barrier film specifications now require full substance disclosure through SCIP database registration. Smoked whiting processors sourcing from Northern Europe face material switching costs as legacy laminates phase out.
Refrigerated last-mile networks are enabling subscription seafood boxes that bypass traditional retail gatekeepers. British consumers in London and Edinburgh receive direct shipments of cold-smoked fillets within temperature-controlled packaging. Food service distributors in these cities observe volume leakage as households experiment with home consumption.
Smoked Whiting Market Segmentation
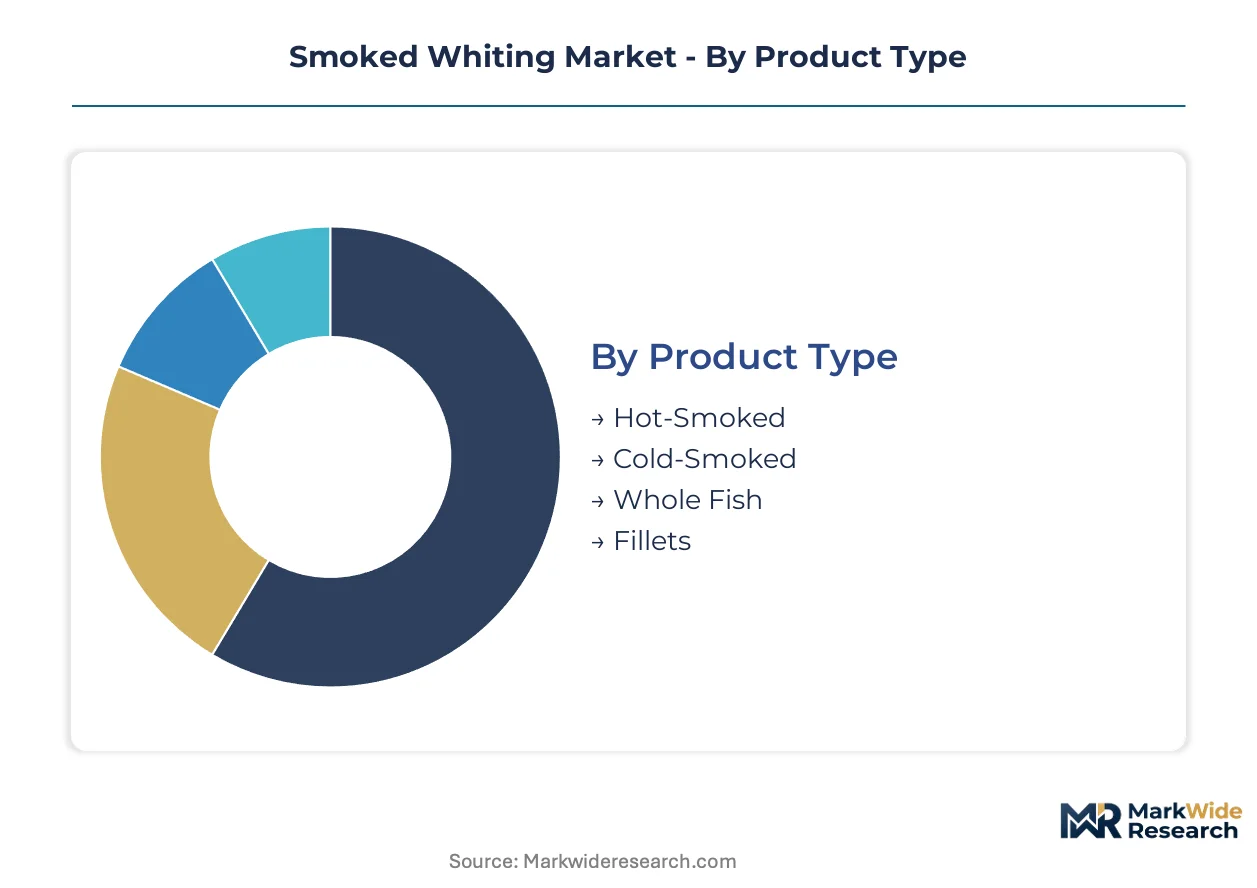
Channel-mix dynamics in smoked whiting hinge on temperature protocols and shelf-life requirements. Cold-smoked fillets command premium placement in refrigerated retail cases, while hot-smoked variants penetrate food-service channels through lower price points and broader temperature tolerance.
Product Type:
Channel-mix patterns diverge sharply by curing temperature, with cold-smoked products dominating supermarket chilled sections and hot-smoked alternatives flowing through food-service distributors.
- Cold-Smoked:Cured at 20°C to 30°C over extended cycles, yielding dense texture and pronounced phenolic surface compounds from beech or oak smoke. German retailers in Hamburg and Bremen stock vacuum-sealed cold-smoked fillets as flagship deli items, driven by BfR-certified production standards that validate premium positioning.
- Fillets:Portioned cuts with standardized weights enable portion-control economics for restaurant operators. United Kingdom food-service distributors in London and Edinburgh prioritize fillet formats for menu consistency, constrained by EFSA polycyclic aromatic hydrocarbon limits that favor controlled industrial smoking over artisanal batch methods.
- Hot-Smoked:Cooked through at 70°C to 80°C during smoke exposure, producing flaky texture and shorter shelf life. Ready-to-eat positioning suits casual dining channels.
- Whole Fish:Intact Merlangius merlangus presentation for traditional retail formats and ethnic food-service accounts. Visual authenticity commands niche premiums.
By volume, fillets lead. By growth pace, cold-smoked variants are expanding most quickly.
Distribution Channel:
Cost-tier stratification separates mass-market supermarket placements from premium specialty and direct channels, with online retail capturing margin through subscription economics.
- Supermarkets:Refrigerated deli counters and pre-packaged sections in Tesco, Sainsbury's, and Edeka chains drive baseline volume. Standardized barcoding and EFSA traceability requirements favor scaled processors with compliant cold-chain documentation.
- Online Retail:Direct-to-consumer platforms bypass slotting fees and capture household experimentation with subscription seafood boxes. British consumers in London receive temperature-controlled shipments within 24 hours, though last-mile refrigeration capex constrains geographic expansion.
- Specialty Stores:Curated selections emphasizing provenance and artisanal credentials. Higher labor intensity limits footprint.
- Fish Markets:Traditional wet-market and municipal hall formats with limited cold-chain investment. Price competition from fresh alternatives pressures smoked positioning.
Supermarkets dominate absolute volume. Online retail shows the steepest expansion trajectory.
Packaging Type:
Margin structures align with barrier performance, where vacuum and modified atmosphere technologies justify price premiums against commodity canned formats.
- Vacuum-Sealed:Multi-layer barrier films with oxygen transmission rates below 1 cc/m²/day extend chilled shelf life to 21 days. REACH-compliant laminates from Northern European suppliers satisfy SCIP database disclosure requirements, though material switching costs burden smaller smokehouses.
- Modified Atmosphere:Gas-flushed headspaces with elevated carbon dioxide suppress microbial growth without freezing. German processors favor this format for retail-ready cold-smoked fillets, balancing shelf-life extension against visible purge accumulation that degrades presentation.
- Canned:Retort-processed ambient stability for export markets and emergency stockpiling. Hot-fill protocols compromise texture quality.
- Plastic Containers:Rigid tubs for food-service bulk portions. Lower unit costs attract institutional buyers.
Vacuum-sealed formats capture the highest margin per kilogram. Modified atmosphere packaging is gaining share fastest among premium-positioned products.
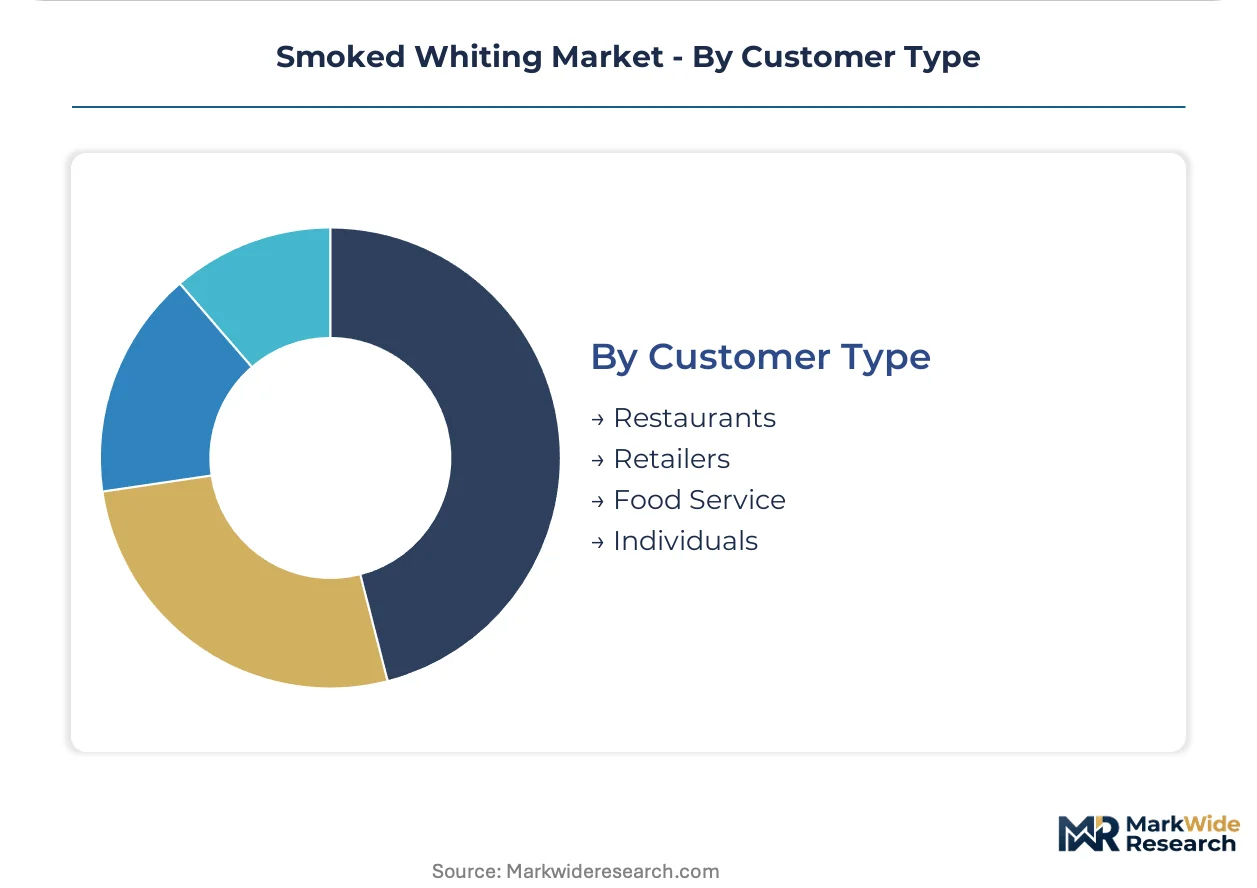
Customer Type:
Application requirements segment procurement patterns, with restaurants demanding consistent portioning and retailers prioritizing shelf-life visibility.
- Restaurants:Fine-dining and casual operators in Edinburgh and Hamburg specify cold-smoked fillets for appetizer and salad applications. Menu placement contracts with annual volume commitments stabilize processor throughput, though spot-market exposure persists for uncontracted supply.
- Food Service:Broadline distributors serving institutional accounts and chain restaurants. Consolidated procurement favors standardized hot-smoked products with extended frozen holding capacity.
- Retailers:Supermarket and specialty store buyers negotiating slotting fees and promotional calendars. Chilled distribution requirements filter supplier pools.
- Individuals:Direct purchasers through farmers markets and subscription platforms. Small batch sizes elevate per-unit logistics costs.
Food service leads by volume. Restaurants command the fastest growth in cold-smoked premium tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United Kingdom consume smoked whiting through divergent channels. German households favor vacuum-sealed retail formats for home preparation, while British demand concentrates in food-service applications where restaurants specify cold-smoked fillets for menu integration.
Germany
Retail deli counters at Edeka and REWE chains drive household penetration of cold-smoked fillets. BfR enforces polycyclic aromatic hydrocarbon limits that filter supplier pools to certified smokehouses. Hamburg processors leverage port proximity to secure fresh Merlangius merlangus landings for same-day curing cycles.
United Kingdom
London restaurants and Edinburgh fine-dining operators contract annual volumes for appetizer applications. Food Standards Agency traceability mandates require batch-level documentation through chilled distribution networks. Grimsby smokehouses maintain heritage curing methods while installing electrostatic precipitation systems for BfR-equivalent emission compliance.
France
Specialty retailers in Paris and Lyon curate artisanal provenance narratives for premium positioning. EFSA guidelines on microbiological contaminants shape import acceptance criteria for Norwegian-supplied fillets. Boulogne-sur-Mer processors experiment with modified atmosphere packaging for extended shelf-life export to Belgian retail chains.
Norway
Integrated trawler-smokehouse operations control raw material flows from North Sea catch to finished product. Leroy Seafood Group's cold-chain infrastructure sustains consistent supply across Northern European markets. Bergen facilities specialize in cold-smoked formats that command price premiums in German and British retail channels.
Netherlands
Rotterdam port logistics enable re-export of processed fillets to inland European markets. REACH-compliant packaging material switching costs burden smaller smokehouses sourcing barrier films. Amsterdam-based distributors consolidate procurement for Belgian and German retail chains seeking standardized product specifications.
Smoked Whiting Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in smoked whiting supply. Vertically integrated seafood conglomerates control frozen raw-material flows and cold-chain distribution, while regional smokehouses compete on artisanal credentials and heritage curing protocols. Strategic archetypes include Nordic cold-chain integrators, North American hot-smoked specialists, and European heritage smokehouses. Competitive moves center on backward integration into fishing quotas and forward integration into direct-to-consumer refrigerated logistics.
Among Nordic cold-chain integrators, Leroy Seafood Group exemplifies vertical control from catch to retail shelf. High Liner Foods anchors the North American specialist tier through frozen supply chain management. Acme Smoked Fish Corp. occupies a position within the hot-smoked production segment serving food-service distributors. These three entities represent distinct strategic postures: geographic integration, supply stabilization, and channel specialization respectively.
| Leading Market Players |
|---|
| Kraft Heinz |
| Leroy Seafood Group |
| Marine Harvest |
| Unilever |
| ConAgra |
| High Liner Foods |
| Nestle |
| 2 Sisters Food Group |
| Acme Smoked Fish Corp. |
| Others |
Value Network & Pricing Analysis
EFSA polycyclic aromatic hydrocarbon limits and BfR certification standards in Germany gate supplier qualification while simultaneously enabling price premiums for compliant smokehouses. These regulatory thresholds concentrate procurement power among certified processors who command higher margins from retailers seeking liability protection.
Pricing Analysis
Long-term offtake contracts between Hamburg smokehouses and Edeka retail chains stabilize volume commitments against spot-market volatility in frozen whiting supply. Three-tier pricing structure across premium cold-smoked, standard hot-smoked, and economy canned levels reflects certification grade and shelf-life performance. Cost compression in the economy tier is intensifying because REACH-compliant packaging material switching costs burden smaller processors without scale. Quick-service restaurant distributors exhibit highest price sensitivity, while fine-dining operators in Edinburgh absorb premiums for BfR-certified cold-smoked fillets.
Supply Chain Analysis
North Sea landing ports at Grimsby and Bergen constitute a chokepoint where Scottish and Norwegian trawler access determines raw material flow security for European processors. Merlangius merlangus landings, beech hardwood supply, and REACH-compliant barrier films anchor production feasibility. Single-source vulnerability concentrates in Norwegian integrated trawler-smokehouse operations controlling frozen inventory. Distribution runs through refrigerated broadline distributors serving food-service channels, with direct-to-consumer platforms emerging as an alternative route.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around EFSA contamination limits and BfR certification requirements creates defensive moats for incumbent smokehouses. Network effects concentrate among processors with established cold-chain partnerships and retail slotting relationships.
For Market Incumbents: Secure backward integration into North Sea fishing quotas to insulate margins from spot-market volatility in Merlangius merlangus supply. Invest in electrostatic precipitation systems to preempt BfR air emission enforcement while maintaining phenolic compound profiles that differentiate premium positioning.
For New Entrants and Emerging Players: Anchor in direct-to-consumer subscription channels where refrigerated last-mile networks bypass supermarket slotting fee barriers. Target British household experimentation in London and Edinburgh with temperature-controlled seafood boxes as the most penetrable entry vector.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated smoking system deployment as CE-marked equipment requirements escalate. Mid-scale smokehouses with established BfR certification and underutilized capacity present viable acquisition targets. Watch electrostatic precipitation adoption rates as an inflection indicator for regulatory compliance investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fishing Quotas | Captive supply of Merlangius merlangus insulates processors from North Sea landing volatility. |
| Electrostatic Precipitation System Deployment | German processors in Hamburg meet BfR emission standards without sacrificing smoke chemistry throughput. |
| Direct-to-Consumer Refrigerated Logistics | British subscription platforms bypass Tesco and Sainsbury's slotting fees while capturing household experimentation. |
| REACH-Compliant Packaging Transition | Vacuum-sealed barrier films with SCIP database registration satisfy EFSA traceability mandates for retail placement. |
| Cold-Smoked Production Line Expansion | Extended curing cycles at 20°C to 30°C yield premium phenolic profiles commanding higher margins than hot-smoked alternatives. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, EFSA contaminant monitoring reports, and smokehouse operator SEC filings where available. Smokehouse master smokers, Edeka category buyers, food-service distributors in London, and BfR regulatory affairs specialists contributed interview perspectives. Bottom-up volume modeling from processor capacity utilization triangulates against top-down consumption estimates derived from retail audit data.
Segmentation dimensions modeled include curing temperature protocol, packaging barrier technology, distribution channel format, and customer application requirements across the projection horizon. CAGRs derive from weighted average growth assumptions applied to volume and value baselines. Forecast inputs incorporate EFSA maximum residue level enforcement trajectories and REACH compliance deadline phasing for food-contact materials.
Material uncertainties — North Sea stock shifts, hardwood smoke chemistry regulatory revisions, and alternative protein substitution rates — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as cold-chain traceability requirements and direct-to-consumer platform economics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Global Commercial Fishing Market
Seafood
Global Seafood Market
Seafood
Fish Maw Market
Seafood
Europe Lobster Market
Seafood
Europe Seafood Market
Seafood
Carp Market
Seafood
Salmon Fish Market
Seafood
Asia-Pacific Seafood Market
Seafood
Sea Bream Market
Seafood
COD Market
Seafood
US Crustacean Market
Seafood
Fish Meal Market
Seafood
Smoked Salmon Market
Seafood
Organic Salmon Market
Seafood
Dried Scallop Market
Seafood
North America Frozen and Canned Seafood Market