
 Oyster Meal Market | 2026-2036
Oyster Meal Market Size, Share, and Industry Trends Forecast 2026-2036
Oyster Meal Market Analytics
Premium-grade protein specification is rotating toward higher digestibility thresholds and lower heavy-metal certification, compelling processors to invest in cold-chain washing and traceability systems. Mere Point Oyster Company leverages its vertical integration from farm to dryer to sustain consistent batch quality across seasonal harvest fluctuations. Pangea Shellfish & Seafood Company anchors its position through specialized relationships with East Coast aquaculture cooperatives. White Stone Oyster Company differentiates via controlled-temperature processing that preserves heat-labile amino acid profiles.
Oyster meal denotes dried, milled oyster tissue and shell biomass processed to specified particle sizes, typically containing 40-60% crude protein alongside calcium carbonate fractions, and serves primarily as a nutritional supplement in aquaculture feeds and high-value animal rations. The powder segment dominates current volume due to its ease of incorporation into pelleted aquafeeds and homogenous nutrient distribution. Granules are gaining share in specialized ornamental fish applications where slow-release feeding behavior commands price premiums. The fertilizer application remains mature with stable demand from organic viticulture and berry operations seeking calcium-rich soil amendments.
USDA and FDA oversight of aquafeed safety under the Food Safety Modernization Act shapes product standards for oyster meal destined for domestic aquaculture, while EU REACH and EFSA guidelines govern heavy-metal thresholds for imports into European feed supply chains. China's SAMR enforces GB standards for feed-grade marine products that constrain market access for non-compliant foreign suppliers. Stakeholders must monitor evolving maximum residue limits for cadmium and lead, as regulatory divergence between jurisdictions threatens to fragment sourcing strategies and testing protocols.
Market Dynamics
Integrated shellfish processing clusters in coastal China are compressing procurement timelines and forcing mid-scale processors to consolidate or exit, as traceability mandates from EU REACH and China's SAMR raise capital barriers.
Growth Catalysts
- Aquaculture hatchery expansion:Vietnam and Indonesia are scaling oyster meal inclusion in larval diets for shrimp and finfish, creating pull-through demand for certified marine protein.
- EU Animal Feed Regulation 767/2009:Tightened traceability requirements for marine-derived feed ingredients are rewarding compliant suppliers with preferential channel access across European aquafeed networks.
- Organic viticulture amendment demand:Calcium-rich soil amendment applications in berry and wine operations are stabilizing offtake volumes outside aquaculture cyclicality.
Market Restraints
- Heavy-metal input cost volatility:Cold-chain washing and traceability system investments required to meet cadmium and lead thresholds are elevating fixed costs for non-integrated processors.
- Supply concentration risk:Coastal Chinese provinces dominate raw material sourcing, exposing buyers to regional harvest fluctuations and logistics bottlenecks.
- Regulatory fragmentation:Divergent maximum residue limits between EU EFSA, US FDA, and China's GB standards force redundant testing protocols that erode margin.
Strategic Opportunities
- Ornamental fish slow-release formulations:Granule formats for specialized aquarium applications command price premiums through differentiated feeding behavior.
- East Coast aquaculture cooperative anchoring:Direct supply relationships with regional hatcheries bypass commodity channel compression.
- Controlled-temperature processing:Heat-labile amino acid preservation technology opens premium positioning in high-value animal rations beyond standard aquafeed.
Industry Challenges
- Batch consistency across seasonal harvests:Farm-to-dryer integration is required to sustain protein specification compliance amid raw material variability.
- Certification timeline compression:EU REACH and SAMR documentation requirements are extending qualification cycles for new supplier entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oyster Meal Market |
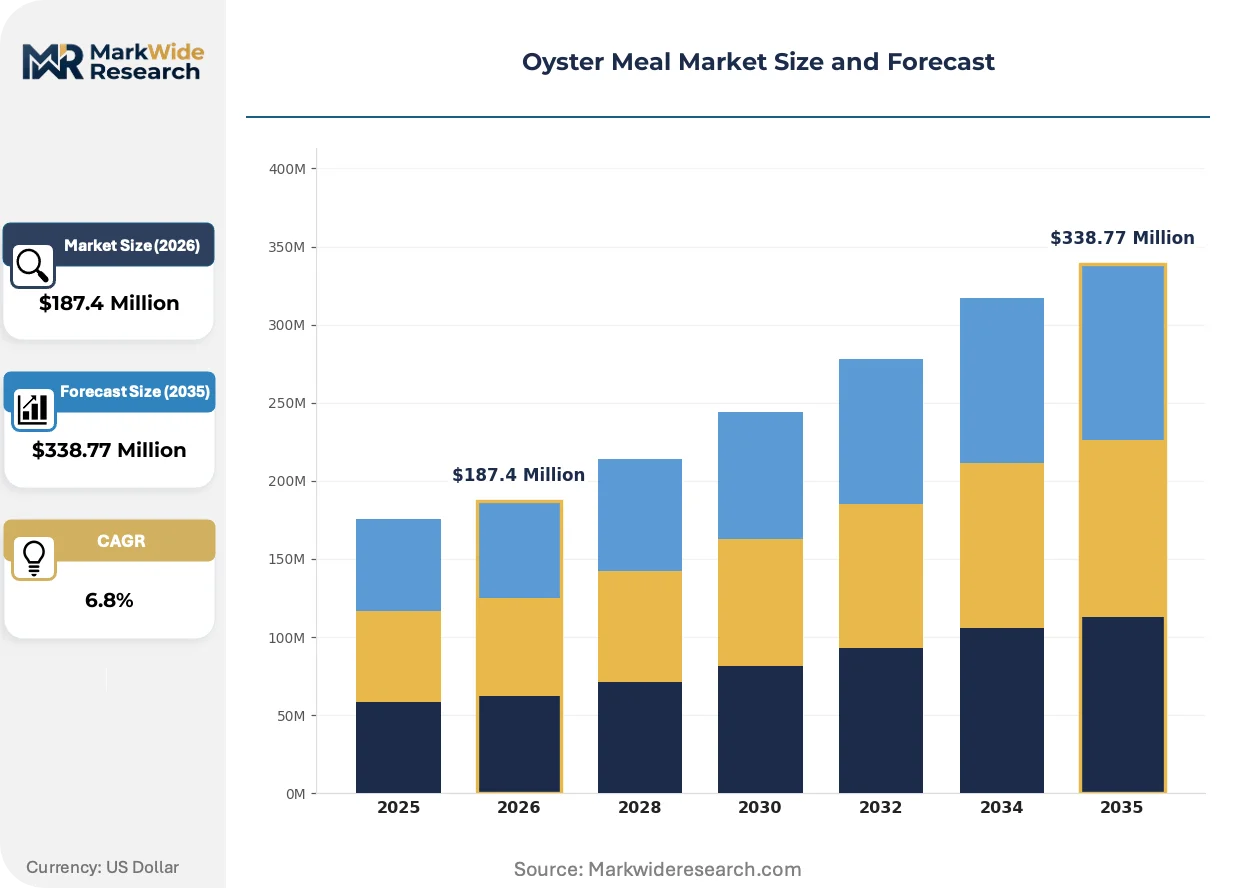
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Flakes, Pellets Application: Aquaculture, Food Supplement, Animal Feed, Fertilizer Formulation: Organic, Non-Organic, Fortified, Standard Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Mere Point Oyster Company, Pangea Shellfish & Seafood Company, Chatham Shellfish Company, La Belle Oyster Co., White Stone Oyster Company, Hog Island Oyster Company, Morro Bay Oyster Company, Shelley Farms Louisiana Premium Oysters Co., Hoopers Island Oyster Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oyster Meal Market Evolving Landscape
Cold-chain infrastructure and particle-size engineering are reshaping how oyster meal processors capture value, separating premium-grade from commodity-grade supply tiers.
Flash-drying with nitrogen blanketing is bifurcating the equipment landscape. Large-scale Vietnamese hatcheries are adopting these systems to preserve lysine and methionine integrity. The technology is bifurcating supplier tiers into heat-labile-certified versus standard-protein camps, compressing mid-tier processor margins.
REACH authorization sequences for marine-derived feed additives are tightening heavy-metal documentation requirements. ECHA's evolving substance evaluation protocols are forcing importers to establish in-house testing laboratories. European compound feed manufacturers are responding by consolidating supplier lists to pre-qualified cold-chain operators.
Direct contracting between hatcheries and integrated farm-dryer operations is displacing spot-market purchasing. Vietnamese shrimp hatcheries are locking in multi-year supply agreements with traceability-verified processors. This pattern is most visible in Mekong Delta aquaculture zones where feed cost volatility has compressed working capital tolerance.
Oyster Meal Market Segmentation
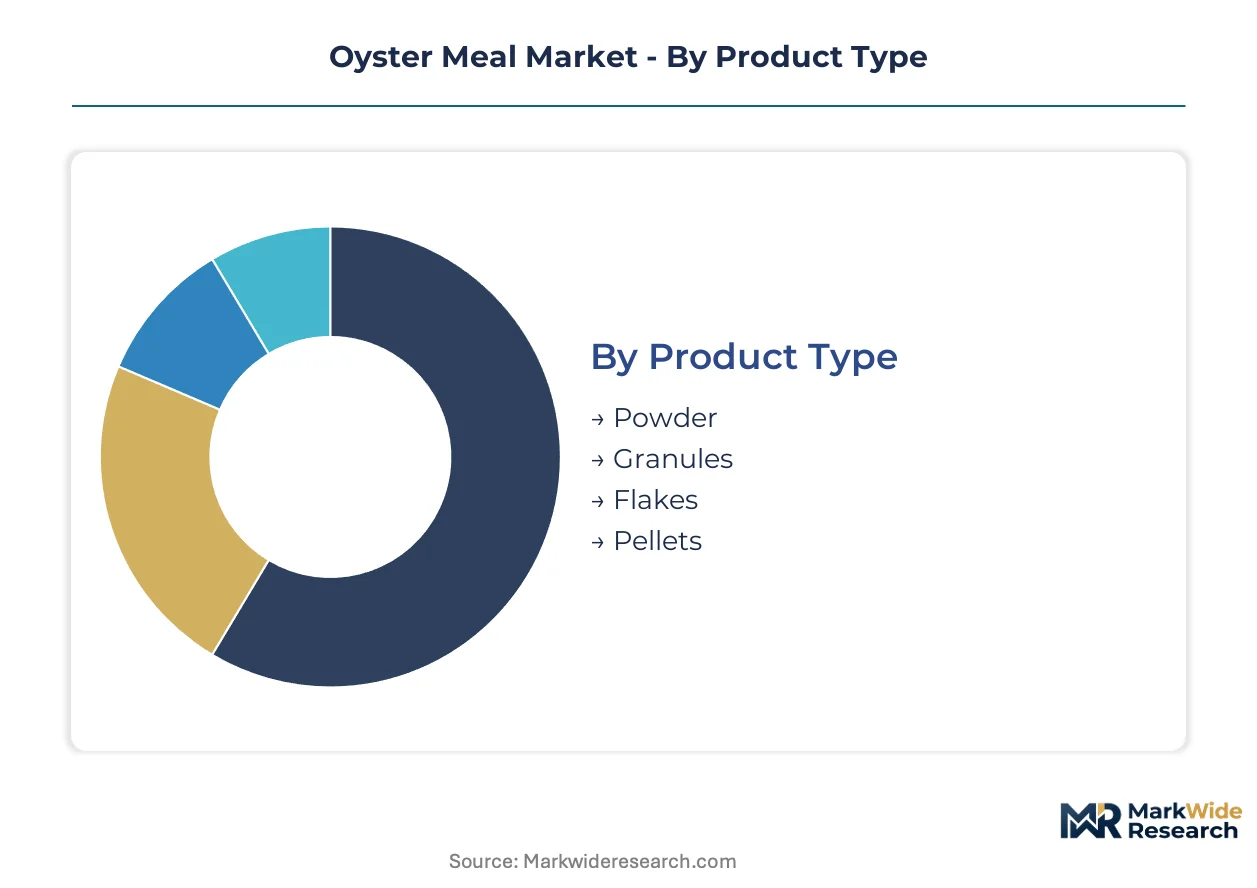
Oyster meal segmentation reflects divergent regulatory thresholds across feed-grade versus food-grade applications. Powder and granule formats face distinct certification requirements under EU REACH and China's GB standards. Distribution channel selection directly constrains which customer segments processors can legally serve.
Product Type:
EU REACH authorization sequences and China's SAMR feed-grade certifications bifurcate acceptable particle specifications for cross-border trade.
- Powder:Fine-milled particles below 250 microns enable homogeneous nutrient distribution in pelleted aquafeeds. Vietnamese shrimp hatcheries in the Mekong Delta concentrate procurement here, driven by automated feed system compatibility and lysine preservation requirements under flash-drying protocols.
- Granules:Slow-release particles sized 500-2000 microns command price premiums in ornamental fish applications. Specialized aquarium operations in Indonesia favor this format for controlled feeding behavior that reduces water quality degradation.
- Flakes:Thin, heat-processed sheets serve niche ornamental applications requiring surface-floating feed behavior.
- Pellets:Compressed extrusions target large-scale finfish operations with automated feeding infrastructure.
Established volume favors powder; emerging adoption favors granules.
Application:
Cost tier separation between commodity feed inputs and premium nutritional supplements dictates processing investment and margin structure.
- Aquaculture:Larval diets for shrimp and finfish demand 40-60% crude protein with cadmium thresholds below EU EFSA limits. Vietnam and Indonesia hatcheries are scaling certified marine protein inclusion, creating pull-through demand for cold-chain traceability systems.
- Animal Feed:High-value rations for poultry and swine require heat-labile amino acid preservation through controlled-temperature processing. Premium positioning here depends on methionine integrity certification.
- Food Supplement:Human-grade specifications face stricter heavy-metal documentation under FDA and EFSA guidelines than feed applications.
- Fertilizer:Calcium-rich soil amendments for organic viticulture and berry operations exhibit stable demand cyclicality outside aquaculture seasonality.
Aquaculture commands the steepest expansion trajectory; fertilizer maintains the most predictable offtake.
Formulation:
Customer type stratification separates certified organic operations from conventional feed compounders with divergent documentation burdens.
- Organic:EU Organic Regulation compliance and USDA National Organic Program certification enable access to premium viticulture and specialty aquaculture channels. Traceability from farm to dryer is mandatory.
- Fortified:Lysine and methionine supplementation targets high-value animal rations where amino acid profiles determine pricing tiers.
- Non-Organic:Standard feed-grade specifications serve cost-sensitive aquaculture operations in Southeast Asia with less stringent residue documentation.
- Standard:Baseline protein and calcium carbonate fractions compete primarily on volume pricing in commodity channels.
Organic formulation captures the widest margin expansion; non-organic retains the largest volume base.
Distribution Channel:
Supply concentration in coastal Chinese provinces shapes logistics economics and customer reach for each channel archetype.
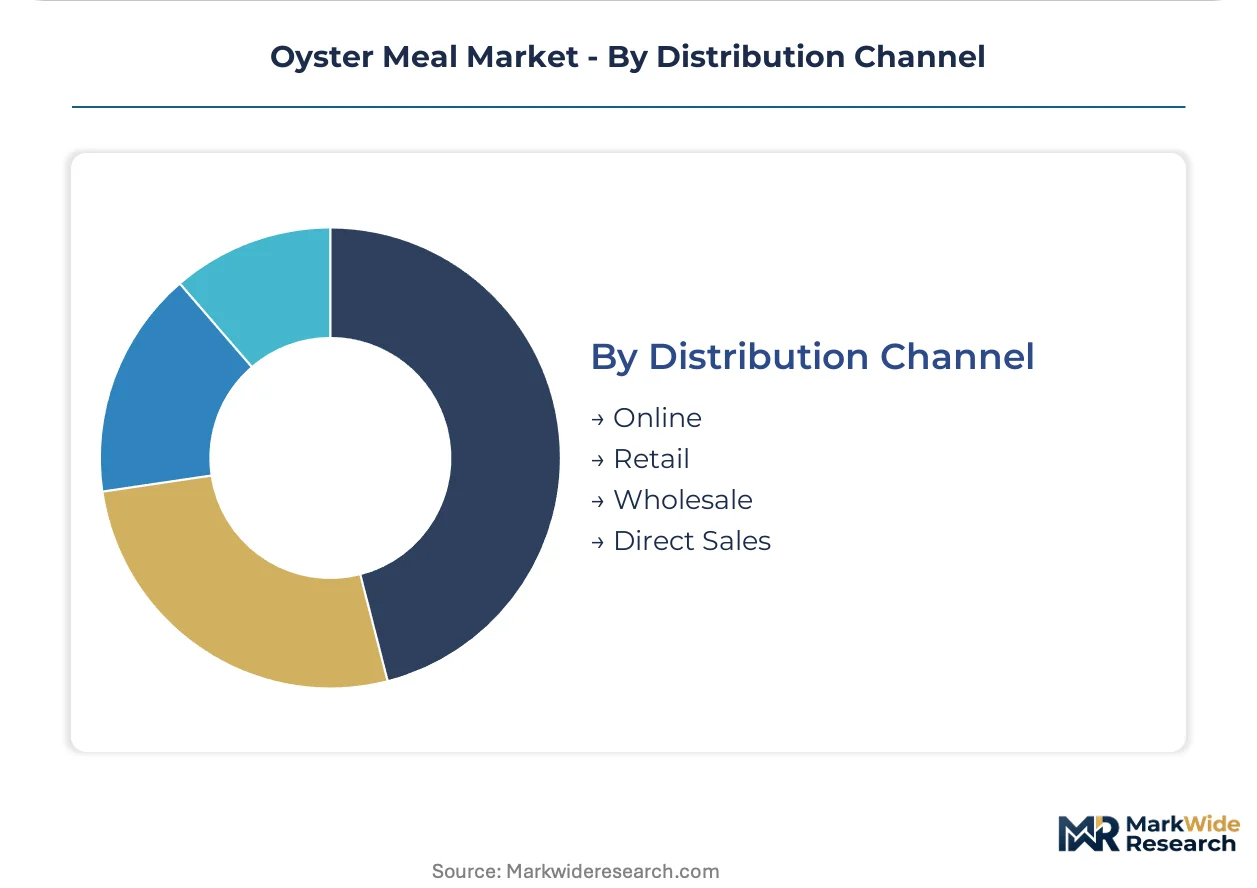
- Direct Sales:Multi-year contracting between integrated farm-dryer operations and Vietnamese shrimp hatcheries is displacing spot-market purchasing. This pattern concentrates in Mekong Delta zones where feed cost volatility has compressed working capital tolerance.
- Wholesale:Commodity volume flows through regional distributors serving mid-scale aquafeed compounders with less stringent traceability requirements.
- Online:Specialized ornamental fish suppliers and small-scale organic farmers procure certified product through platform-based channels with documentation transparency.
- Retail:Garden center and agricultural supply stores serve hobbyist aquarium keepers and home viticulture operations with smaller pack sizes.
Direct sales are gaining share fastest; wholesale retains dominant volume position.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Raw material sourcing concentrates in coastal provinces of China, where integrated shellfish processing clusters compress procurement timelines and force mid-scale processors to consolidate. Vietnam and Indonesia are scaling aquaculture hatchery demand for certified marine protein. Regulatory divergence between EU REACH, US FDA, and China's SAMR standards fragments testing protocols across trade corridors.
China
Shandong and Fujian provinces anchor domestic supply through vertically integrated farm-to-dryer operations that sustain batch consistency across seasonal harvest fluctuations. SAMR enforces GB standards for feed-grade marine products that constrain market access for non-compliant foreign suppliers. Qingdao processing clusters are consolidating under traceability mandates that raise capital barriers for mid-scale entrants.
Vietnam
Mekong Delta shrimp hatcheries are locking in multi-year supply agreements with traceability-verified processors, displacing spot-market purchasing patterns. The country's national feed safety regulator aligns with ASEAN harmonization efforts while maintaining cadmium thresholds below EU EFSA limits. Can Tho and Ben Tre aquaculture zones concentrate demand for flash-dried powder formats compatible with automated larval feeding systems.
United States
East Coast aquaculture cooperatives in Maine and Massachusetts anchor specialized supply relationships that bypass commodity channel compression. USDA and FDA oversight under the Food Safety Modernization Act shapes product standards for domestic aquaculture applications. Chesapeake Bay and Damariscotta River clusters are investing in cold-chain washing infrastructure to meet heavy-metal certification thresholds.
Indonesia
Java and Sulawesi hatcheries are scaling oyster meal inclusion in ornamental fish and shrimp larval diets, creating pull-through demand for granule formats. The national food and drug regulator enforces residue documentation that diverges from EU REACH sequences, extending qualification cycles for new supplier entry. Bali and Lombok aquarium specialists command price premiums for slow-release feeding behavior in high-value ornamental applications.
Germany
Compound feed manufacturers are consolidating supplier lists to pre-qualified cold-chain operators in response to ECHA's evolving substance evaluation protocols. REACH authorization sequences for marine-derived feed additives tighten heavy-metal documentation requirements beyond baseline EU thresholds. Hamburg and Bremerhaven import gateways are establishing in-house testing laboratories to manage regulatory divergence from Asian supply origins.
Oyster Meal Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with flash-drying nitrogen blanketing systems separating premium-grade from commodity-grade supply tiers. The vendor base clusters around three strategic positions: integrated farm-dryer operations with captive raw material supply, specialized hatchery contractors with multi-year direct sales relationships, and regional wholesalers serving cost-sensitive compounders. Dominant competitive moves include backward integration into hatchery supply agreements and geographic anchoring within aquaculture cooperative networks.
Among US-based integrated producers, Mere Point Oyster Company and White Stone Oyster Company exemplify the farm-to-dryer archetype that sustains protein specification compliance amid raw material variability. Pangea Shellfish & Seafood Company occupies a position within the specialized contractor tier, anchoring relationships with East Coast aquaculture cooperatives that bypass commodity channel compression. These three represent divergent strategic bets on vertical control versus partnership-based market access.
| Leading Market Players |
|---|
| Mere Point Oyster Company |
| Pangea Shellfish & Seafood Company |
| Chatham Shellfish Company |
| La Belle Oyster Co. |
| White Stone Oyster Company |
| Hog Island Oyster Company |
| Morro Bay Oyster Company |
| Shelley Farms Louisiana Premium Oysters Co. |
| Hoopers Island Oyster Company |
| Others |
Value Network & Pricing Analysis
Multi-year offtake agreements between Vietnamese shrimp hatcheries and traceability-verified processors lock in both raw material access and price visibility across seasonal harvest fluctuations, compressing spot-market liquidity and elevating contract premiums for cold-chain certified supply.
Pricing Analysis
EU Animal Feed Regulation 767/2009 dictates the pricing tier structure by mandating heavy-metal documentation that separates REACH-authorized suppliers from commodity-grade competitors. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with organic formulation commanding the widest margin expansion. Cost compression in the standard tier is intensifying because mid-scale processors face redundant testing protocols across EU EFSA, US FDA, and China's SAMR standards. Commodity aquafeed compounders in Southeast Asia exhibit the highest price sensitivity, while ornamental fish specialists and organic viticulture operations demonstrate the lowest.
Supply Chain Analysis
Qingdao processing cluster concentration in Shandong Province underwrites regional procurement timelines and logistics economics for global oyster meal distribution. Raw material sourcing draws from coastal Chinese provinces, Vietnamese Mekong Delta aquaculture zones, and Indonesian Java hatcheries, with flash-drying equipment and nitrogen blanketing systems as critical processing inputs. Single-source vulnerability concentrates in Shandong and Fujian farm-to-dryer operations where SAMR traceability mandates have forced mid-scale processor consolidation. Distribution runs through direct sales channels for certified hatchery supply, wholesale networks for commodity compounders, and platform-based online channels for specialized ornamental applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct contracting platforms between hatcheries and integrated processors signal a platform-economics inflection, with interoperability of traceability data systems enabling multi-year supply agreement standardization across previously fragmented procurement relationships.
For Market Incumbents: Fortify batch consistency through backward integration into captive farm supply, insulating protein specification compliance from seasonal harvest variability that threatens EU REACH certification renewal. Expand cold-chain washing infrastructure in Chesapeake Bay and Damariscotta River clusters to preempt FDA heavy-metal threshold tightening. Channel control through exclusive East Coast aquaculture cooperative anchoring defends margin position against commodity channel compression. For New Entrants and Emerging Players: SAMR fast-track certification for GB standards compliance unlocks white-space access to mid-scale Vietnamese shrimp hatcheries seeking second-source supply security. Target ornamental fish granule applications in Indonesian Bali and Lombok markets where slow-release feeding behavior commands price premiums and incumbent presence remains thin. Go-to-market leverage rests on platform-based documentation transparency that displaces opaque wholesale channels. For Investors and Strategic Acquirers: Integrated farm-dryer operations with multi-year hatchery contracts and in-house testing laboratories represent the priority acquisition archetype, capturing structural margin expansion as regulatory divergence extends qualification cycles for new supplier entry. Long-term viability over the five-to-ten year horizon hinges on traceability technology deployment that satisfies evolving ECHA substance evaluation protocols. Watch for flash-drying nitrogen blanketing system adoption rates as the inflection signal separating premium-grade from commodity-grade supply tier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farm Supply | Captive raw material sourcing sustains protein specification compliance across seasonal harvest fluctuations in Shandong. |
| Cold-Chain Infrastructure Investment | Flash-drying with nitrogen blanketing preserves lysine integrity for EU REACH certification and premium positioning. |
| Multi-Year Hatchery Contracting | Direct sales relationships with Vietnamese Mekong Delta operations displace spot-market purchasing and compress working capital tolerance. |
| In-House Testing Laboratory Establishment | ECHA substance evaluation protocols and SAMR GB standards divergence force redundant certification documentation control. |
| Granule Format Development | Slow-release particle engineering captures ornamental fish price premiums in Indonesian aquarium specialist channels. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU REACH authorization sequences, SAMR GB standards filings, and ASEAN feed safety harmonization documentation, combining interviews with hatchery procurement managers, aquafeed compounder technical directors, and cold-chain equipment suppliers with customs trade data and ECHA substance evaluation protocols. Bottom-up volume modeling from processor capacity utilization and top-down demand estimation from aquaculture hatchery expansion trajectories enable cross-validation.
Segmentation dimensions modeled span powder-granule-flake-pellet product types, aquaculture-animal feed-fertilizer applications, organic-fortified-standard formulations, and direct-wholesale-online-retail distribution channels across the projection horizon. CAGRs derive from regression analysis of historical protein specification premium trends and regulatory timeline compression effects, with flash-drying adoption rates and heavy-metal threshold evolution as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained EU-China regulatory divergence and Vietnamese-Indonesian hatchery expansion; material deviation in SAMR enforcement intensity or ECHA authorization sequencing would warrant model refresh. Practitioners should keep alternative scenarios live as cold-chain infrastructure investment cycles and ornamental fish demand trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Global Commercial Fishing Market
Seafood
Fresh Fish Market
Seafood
Tuna Fish Market
Seafood
Organic Salmon Market
Seafood
South America Canned Seafood Market
Seafood
Sea Bass Market
Seafood
COD Market
Seafood
Mussel Oil Market
Seafood
Fish Protein Concentrate Market
Seafood
Fish Meal and Fish Oil Market
Seafood
Middle East Seafood Market
Seafood
Fish Hydrolysate Market
Seafood
Asia-Pacific Seafood Market
Seafood
Alaskan Salmon Market
Seafood
Oyster Market
Seafood
Fish Processing Market