
 Shellfish Market | 2026-2036
Shellfish Market Size, Share, and Industry Trends Forecast 2026-2036
Shellfish Market Analysis
The EU Green Deal's sustainable food system targets is decoupling European shellfish procurement from unverified distant-water sources. Maruha Nichiro leverages integrated cold-chain logistics to sustain premium positioning in Japanese retail. Thai Union Frozen Products anchors volume contracts with North American foodservice distributors through certified aquaculture programs. Dong Won Fisheries differentiates via deepwater crab specialization and Korean domestic channel control.
Shellfish comprise aquatic invertebrates with exoskeletons—primarily crustaceans such as shrimp, crab, and lobster, plus bivalve mollusks including clams—harvested through wild catch or aquaculture and processed for human consumption at protein contents typically exceeding eighteen percent by weight. Their commercial purpose centers on supplying high-protein, low-fat nutrition to foodservice and retail channels with strict cold-chain requirements from harvest to plate. Shrimp dominates product type volumes due to farming scalability across tropical coastlines, while lobster commands concentrated margin pools in premium restaurant and direct sales channels. Clams represent a mature, price-stable category tied to regional wholesale networks in the Atlantic geological origin zone.
The EU's EFSA and EMA frameworks enforce maximum residue limits for shellfish toxins and veterinary pharmaceuticals, directly conditioning market access for non-European exporters. In the United States, FDA HACCP regulations and NOAA fisheries certification shape import inspection intensity and retail labeling requirements. China's SAMR and GB standards govern domestic aquaculture chemical use and cross-border e-commerce shellfish sales. Stakeholders must monitor divergence between EU and Asian traceability protocols to avoid customs detention and qualify for premium supermarket placement.
Market Dynamics
The EU's Common Fisheries Policy reform is tightening traceability mandates for imported mollusks while Southeast Asian restaurant chains accelerate raw bar menu expansion, creating a structural squeeze between regulatory compliance costs and foodservice demand pull.
Growth Catalysts
- EU Green Deal procurement standards:European supermarket buyers now require verified distant-water source documentation, rewarding certified aquaculture operations with shelf placement premiums.
- Integrated cold-chain logistics:Advanced temperature monitoring from harvest to retail reduces spoilage losses and extends premium product reach into inland distribution networks.
- Vietnam's Mekong Delta processing clusters:Concentrated peeling and freezing infrastructure achieves economies of scale that lower unit costs for North American foodservice contracts.
Market Restraints
- Wild catch quota compression:NOAA fisheries certification limits on Atlantic lobster harvest volumes constrain supply elasticity for premium restaurant channels.
- Input cost volatility in aquaculture feed:Fishmeal and soybean price swings directly compress farming margins across Thai and Vietnamese shrimp operations.
- Regulatory friction from EFSA toxin limits:Maximum residue thresholds for paralytic shellfish poisoning toxins block non-European exporters without expensive testing protocols.
Strategic Opportunities
- Underpenetrated Indian retail frozen seafood:Cold-chain infrastructure gaps in tier-two cities create first-mover advantages for branded shellfish distribution.
- Cell-cultured crustacean convergence:Bioreactor technology paired with precision fermentation offers path to decoupled protein supply for allergen-sensitive consumer segments.
- China cross-border e-commerce channels:SAMR's streamlined import documentation for frozen bivalves opens direct-to-consumer sales bypassing traditional wholesale layers.
Industry Challenges
- HACCP certification timeline compression:FDA inspection backlogs for new processing facilities delay market entry by quarters, freezing capital deployment.
- Traceability system integration:Divergent EU and Asian electronic logging standards force exporters to maintain parallel documentation systems.
- Deepwater crab harvesting skill scarcity:Specialized pot-setting and handling expertise shortages limit fleet expansion in Korean and Japanese waters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shellfish Market |
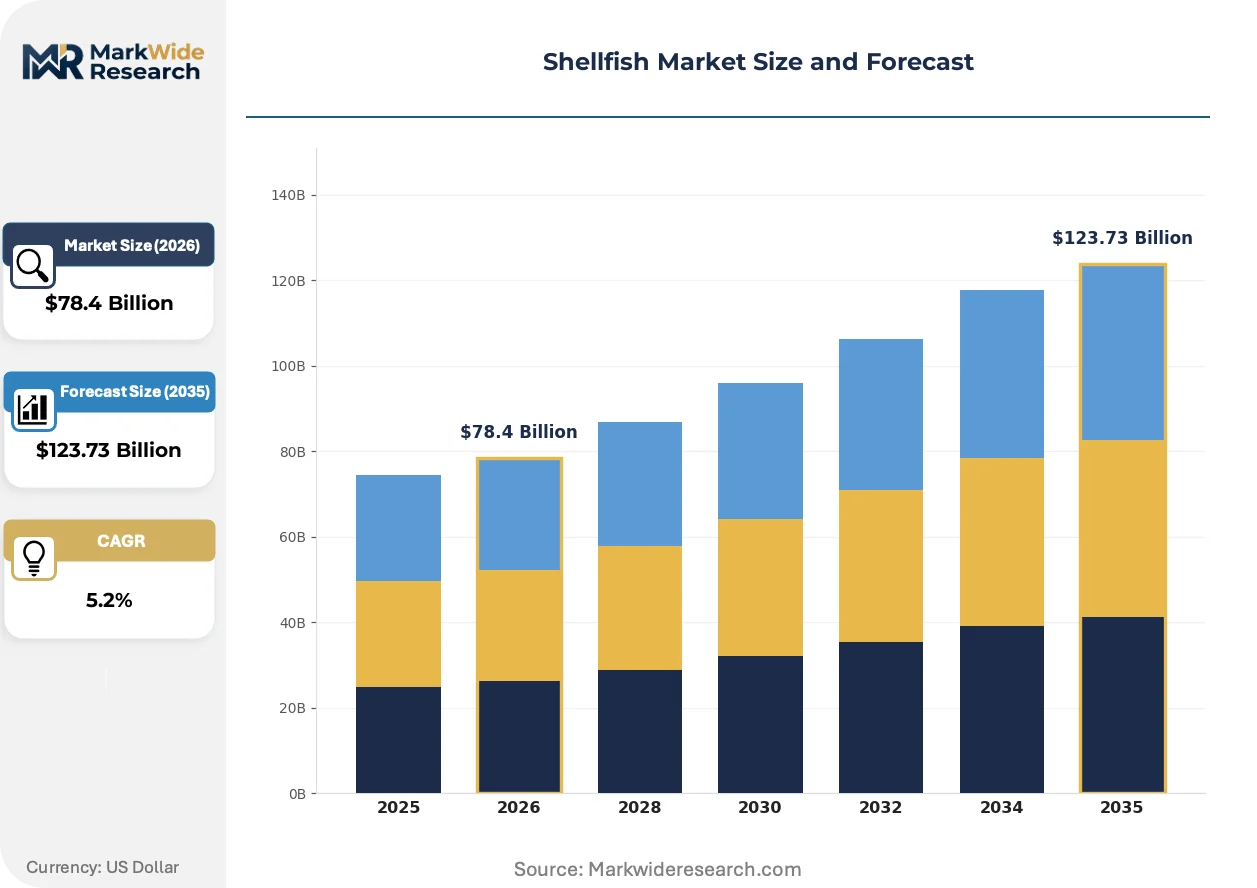
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $123.73 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shrimp, Crab, Lobster, Clams End User: Restaurants, Retailers, Food Service, Exporters Distribution Channel: Direct Sales, Online Sales, Wholesalers, Supermarkets Geological Origin: Atlantic, Pacific, Gulf, Others |
| Companies Covered | Surapon Foods, Beijing Princess Seafood International, Thai Union Frozen Products, High Liner Foods, Princes Group, Dong Won Fisheries, Hansung Enterprise, Sajo Industries, Maruha Nichiro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shellfish Market Emerging Trajectories
Shellfish supply chains are digitizing rapidly as blockchain-enabled provenance tracking meets pressure from retail buyers for transparent sourcing narratives that justify premium positioning.
Blockchain-based catch documentation is consolidating supply chain transparency into unified digital ledgers. Major North American foodservice distributors now mandate lot-level traceability from vessel to delivery. This technology is consolidating fragmented paper-based systems into interoperable platforms that reduce recall scope and insurance costs.
REACH chemical registration requirements are expanding to cover biocides used in aquaculture equipment and processing facilities. European processors face reformulation deadlines for cleaning agents and antifouling coatings. Smaller Vietnamese exporters without technical compliance teams are ceding shelf space to integrated operators with in-house regulatory affairs capacity.
Direct sourcing contracts between restaurant groups and certified farms are displacing traditional auction-house procurement in premium segments. Tokyo and Singapore-based raw bar operators now contract directly with Hokkaido crab cooperatives and Tasmanian oyster leases. This pattern is most visible in high-turnover metropolitan dining markets where provenance storytelling commands menu price premiums.
Shellfish Market Segmentation
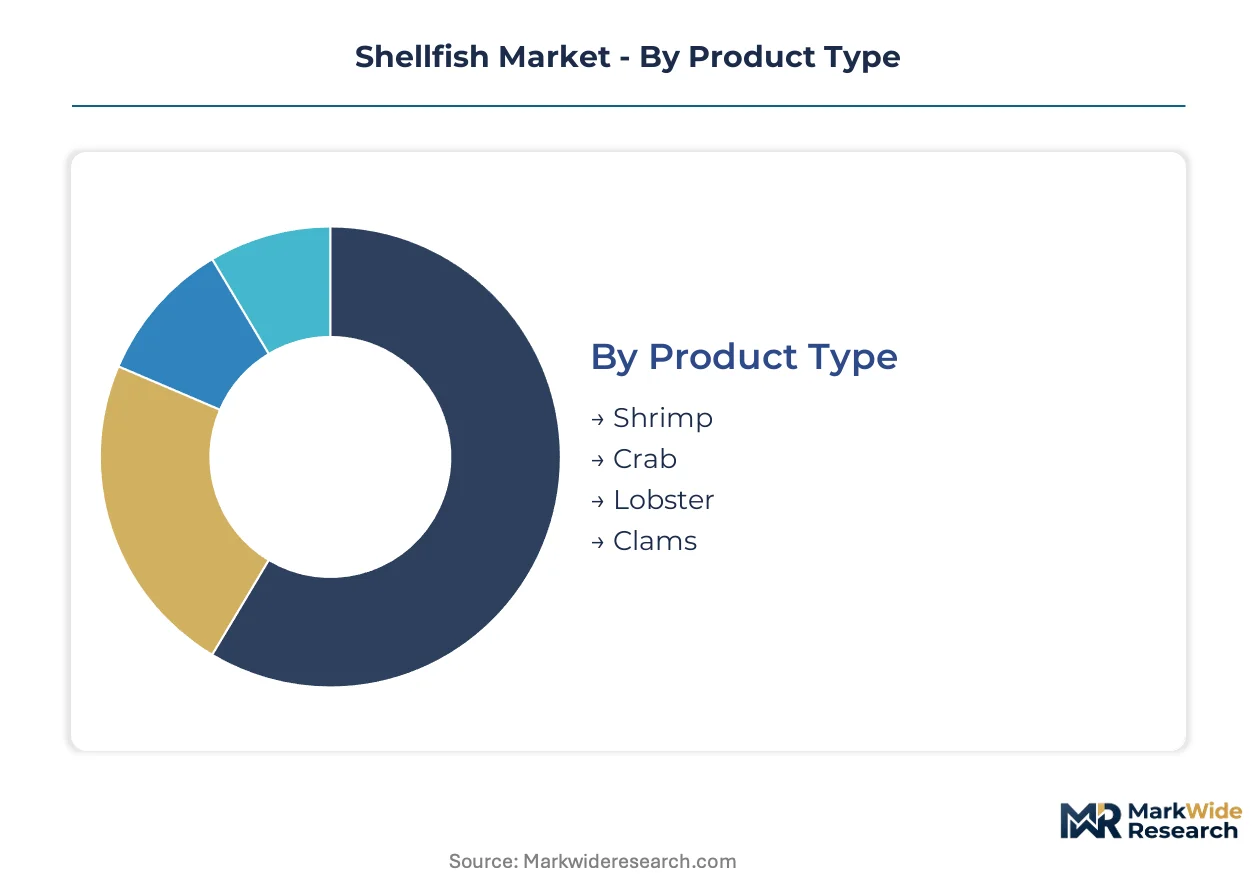
Shellfish procurement patterns diverge sharply between commodity volume plays and premium-positioned categories. Segmentation reveals where cold-chain investment, certification premiums, and channel control concentrate returns across crustacean and mollusk value chains.
Product Type:
Volume scale separates farming-dependent species from wild-catch premiums, with protein content and perishability dictating channel strategy.
- Shrimp:Aquaculture dominance across tropical coastlines delivers eighteen percent protein content with farming scalability unmatched by wild alternatives. Vietnamese Mekong Delta peeling clusters supply North American foodservice contracts through integrated freezing infrastructure, though fishmeal input volatility compresses farming margins.
- Crab:Deepwater pot-harvesting demands specialized vessel expertise with Korean and Japanese fleets commanding domestic channel control. Dong Won Fisheries anchors this segment through vertical integration from catch to retail, limiting expansion due to crew skill scarcity.
- Lobster:Atlantic geological stocks face NOAA quota compression, constraining supply elasticity for premium restaurant channels. Homarus americanus commands concentrated margin pools in direct sales and white-tablecloth segments.
- Clams:Mature bivalve category tied to regional wholesale networks with stable pricing and lower cold-chain intensity. Atlantic hard-shell varieties dominate U.S. east coast distributor contracts.
Today's leader: Shrimp. Tomorrow's challenger: Crab.
End User:
Channel power determines traceability burden and pricing leverage, with certification requirements escalating from foodservice through retail.
- Restaurants:Raw bar expansion across Southeast Asian chains drives live-tank and fresh-chilled procurement, with Tokyo and Singapore operators contracting directly with Hokkaido cooperatives for provenance storytelling.
- Retailers:EU supermarket buyers now mandate blockchain-enabled lot-level traceability, rewarding certified aquaculture with shelf placement premiums under Green Deal procurement standards.
- Food Service:North American distributors anchor volume through Thai Union certified aquaculture programs, with HACCP compliance timelines freezing capital deployment for new processing entrants.
- Exporters:Cross-border specialists navigate divergent EFSA and Asian electronic logging standards, maintaining parallel documentation systems to avoid customs detention.
Channel control concentrates with retailers. Fastest volume expansion: food service.
Distribution Channel:
Cold-chain maturity and customer proximity define which intermediaries capture margin between harvest and plate.
- Direct Sales:Restaurant group contracts with certified farms displace auction-house procurement in premium segments, eliminating wholesale layers for high-turnover metropolitan dining markets.
- Online Sales:China cross-border e-commerce channels leverage SAMR streamlined import documentation for frozen bivalves, opening direct-to-consumer paths bypassing traditional wholesale tiers.
- Wholesalers:Regional networks dominate Atlantic-origin clam distribution with price-stable, mature logistics and lower technology adoption barriers.
- Supermarkets:Integrated cold-chain logistics from Maruha Nichiro sustain Japanese retail premium positioning through harvest-to-shelf temperature monitoring.
Intermediary power: wholesalers hold volume. Disruption vector: online sales.
Geological Origin:
Stock health and regulatory jurisdiction shape supply security and market access conditions.
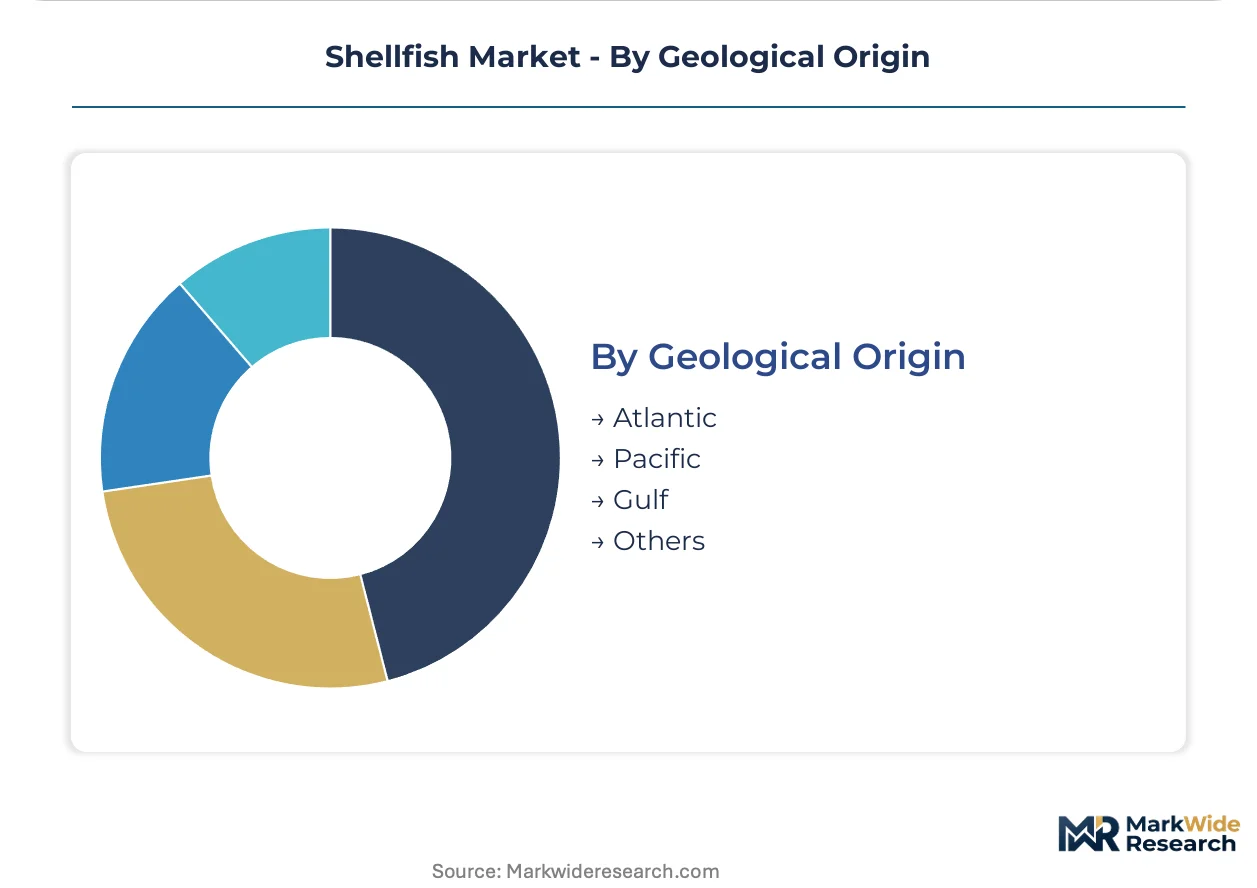
- Atlantic:Lobster and hard-shell clam stocks face NOAA certification limits and EFSA toxin threshold scrutiny, with wild catch quota compression constraining premium restaurant supply elasticity.
- Pacific:Tasmanian oyster leases and Hokkaido crab grounds anchor direct-sourcing contracts with Asian raw bar operators, leveraging cold-water growth conditions for flavor premium.
- Gulf:Shrimp aquaculture concentration along Vietnamese and Thai coastlines achieves economies of scale for North American foodservice, though climate vulnerability and feed cost volatility persist.
- Others:Indian tier-two city cold-chain gaps create first-mover opportunities for branded frozen distribution, while cell-cultured alternatives emerge as decoupled protein supply options.
Supply security: Pacific leads on direct contracts. Expansion frontier: Others.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shellfish aquaculture scaled from Japanese coastal villages in the early twentieth century, then migrated to Southeast Asian estuaries and North Atlantic inlets as cold-chain infrastructure matured. Processing gravity now concentrates in Vietnamese delta clusters and Korean deepwater ports.
Vietnam
Mekong Delta peeling houses supply North American foodservice contracts through integrated freezing infrastructure. SAMR's streamlined import documentation enables cross-border e-commerce sales of frozen bivalves. Ho Chi Minh City logistics hubs coordinate containerized shipments to EU and US markets.
United States
Atlantic lobster stocks face NOAA certification limits constraining premium restaurant supply elasticity. FDA HACCP regulations shape import inspection intensity for processed crustaceans. Boston and Portland maintain auction-house procurement networks for Homarus americanus distribution.
Japan
Maruha Nichiro leverages integrated cold-chain logistics to sustain premium positioning in domestic retail. METI standards govern domestic aquaculture chemical use and processing facility hygiene. Hokkaido crab cooperatives anchor direct-sourcing contracts with Tokyo raw bar operators.
South Korea
Dong Won Fisheries differentiates via deepwater crab specialization and captive domestic channel control. MFDS enforces maximum residue limits for shellfish toxins in retail distribution. Busan processing ports concentrate pot-harvesting fleet operations for regional export.
Thailand
Thai Union Frozen Products anchors volume contracts with North American foodservice distributors through certified aquaculture programs. Fishmeal input volatility compresses farming margins across coastal shrimp operations. Samut Sakhon processing clusters achieve economies of scale for frozen export volumes.
Shellfish Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the shellfish value chain. Integrated aquaculture-to-retail operators hold margin advantages against commodity traders dependent on spot procurement. Three archetypes dominate: vertically integrated Asian seafood conglomerates, North American frozen food distributors, and specialized deepwater harvesters. Capacity expansion and certification premiums constitute the dominant competitive vectors.
Within the integrated conglomerate tier, Maruha Nichiro and Thai Union Frozen Products exemplify cold-chain mastery and volume contract anchoring. Dong Won Fisheries occupies a specialist position in deepwater crab harvesting. Beijing Princess Seafood International represents Chinese coastal processing scale. Surapon Foods anchors Thai shrimp aquaculture certification programs for export compliance.
| Leading Market Players |
|---|
| Surapon Foods |
| Beijing Princess Seafood International |
| Thai Union Frozen Products |
| High Liner Foods |
| Princes Group |
| Dong Won Fisheries |
| Hansung Enterprise |
| Sajo Industries |
| Maruha Nichiro |
| Others |
Supply Flow & Price Mechanics
Captive cold-chain infrastructure from Vietnamese Mekong Delta processors anchors both supply security and pricing power for North American foodservice contracts, while EU Green Deal procurement standards reward certified aquaculture operations with shelf placement premiums that widen margin spreads against commodity traders.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates HACCP-certified export grades from domestic wholesale and unverified spot lots. Price differentiation hinges on traceability documentation depth and cold-chain integrity guarantees. Cost compression in economy tiers is intensifying because fishmeal input volatility compresses farming margins across Thai and Vietnamese shrimp operations. Retail buyers demonstrate lowest price sensitivity for Pacific-origin direct-sourced crab and lobster, while foodservice distributors remain most elastic on undifferentiated frozen shrimp blocks.
Supply Chain Analysis
Certification gating through FDA HACCP and EU EFSA toxin thresholds concentrates supply access among integrated operators with in-house regulatory affairs capacity. Production clusters in Vietnam, Thailand, and South Korea dominate processing gravity, drawing from wild Atlantic lobster stocks, Gulf shrimp aquaculture, and Pacific deepwater crab grounds. Supply chain risk centers on single-source vulnerability for specialized pot-harvesting expertise in Korean and Japanese waters. Distribution runs through containerized cold-chain logistics from Ho Chi Minh City and Busan to North American and European retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shellfish market represents a late-cycle quality story as EU supermarket buyers shift procurement toward verified distant-water sources with blockchain-enabled traceability, rewarding certified operations with sustained margin premiums over commodity traders.
For Market Incumbents: Anchor volume contracts through backward integration into Mekong Delta peeling infrastructure to defend against Thai Union's certified aquaculture scale advantages. Invest in parallel EU-Asian electronic logging systems to preempt customs detention risks from divergent traceability mandates. Prioritize Hokkaido crab cooperative direct-sourcing relationships to secure provenance storytelling rights for Tokyo raw bar channels. For New Entrants and Emerging Players: Tier-two Indian city retailers represent an underserved buyer archetype with cold-chain infrastructure gaps creating first-mover advantages for branded frozen distribution. Cell-cultured crustacean technology offers white-space entry for allergen-sensitive consumer segments without wild-catch quota constraints. Pursue SAMR streamlined import documentation pathways for China cross-border e-commerce direct-to-consumer sales. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap Vietnamese processors because fragmented peeling house operations lack integrated freezing infrastructure and regulatory compliance teams. Long-term viability favors targets with captive aquaculture certification and EU supermarket shelf placement. Watch for FDA inspection backlog resolution as inflection indicator for new processing facility capital deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | HACCP and EFSA compliance unlocks EU and North American premium channel access for Mekong Delta processors. |
| Backward Integration | Captive shrimp farming operations in Thai and Vietnamese coastal zones reduce fishmeal cost volatility exposure. |
| Direct Sourcing Contracts | Tokyo and Singapore raw bar operators now bypass auction houses for Hokkaido crab and Tasmanian oyster leases. |
| Cold-Chain Infrastructure | Ho Chi Minh City logistics hubs enable containerized temperature-controlled shipments to inland North American markets. |
| Blockchain Traceability | Lot-level digital ledgers reduce recall scope and insurance costs for Maruha Nichiro's Japanese retail network. |
Methodological Framework
Direct dialogue with seafood processing executives, EU supermarket procurement directors, North American foodservice distributors, and Vietnamese aquaculture farm operators grounded qualitative insights in operational realities. Secondary validation drew from FDA import refusal data, EFSA rapid alert system notifications, NOAA fisheries landings statistics, and Thai Ministry of Commerce export records. Bottom-up volume modeling across peeling house capacity and top-down value triangulation against foodservice contract values ensured cross-verified outputs.
Segment-level projections across crustacean and mollusk product types, restaurant-retail-foodservice-exporter end users, and Atlantic-Pacific-Gulf geological origins were generated through the analysis window. CAGRs were derived from elasticity-adjusted demand curves incorporating cold-chain penetration rates and certification adoption timelines. Forecast inputs included fishmeal price volatility indices, EU quota compression schedules, and SAMR import documentation streamlining progress.
Inputs from FDA inspection databases and EU rapid alert archives were available through the study window; gaps in real-time Vietnamese processing facility capacity utilization introduce uncertainty bands around Mekong Delta supply forecasts. Model outputs reflect documented assumptions on certification timeline compression and climate vulnerability in Gulf aquaculture zones. A model refresh is warranted upon material change in EU Green Deal procurement enforcement intensity or breakthroughs in cell-cultured crustacean bioreactor economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Mussel Extract Market
Seafood
Food Clamshells Market
Seafood
Asian Sea Bass Market
Seafood
South America Canned Seafood Market
Seafood
North America Frozen and Canned Seafood Market
Seafood
US Crustacean Market
Seafood
Striped Bass Market
Seafood
Crayfish Market
Seafood
Global Frozen and Canned Seafood Market
Seafood
Canned Tuna Market
Seafood
Surimi Market
Seafood
Sea Bream Market
Seafood
Seafood Flavors Market
Seafood
Octopus Market
Seafood
Fish Protein Concentrate Market
Seafood
Canned Sardines Market