
 Japan Frozen Seafood Market | 2026-2036
Japan Frozen Seafood Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Frozen Seafood Market Intelligence
A capital-intensity divergence between blast-freeze infrastructure owners and rental-dependent processors is redrawing competitive tiers in Japan's frozen seafood sector. Maruha Nichiro Corporation leverages integrated trawler-to-retail operations across Hokkaido and Kyushu. Kyokuyo Corporation anchors its position through deepwater fleet ownership and Tsukiji-adjacent cold storage assets. Nichirei Corporation dominates the household channel through controlled distribution into supermarket freezer sections nationwide.
Japan frozen seafood comprises marine and aquaculture products preserved at temperatures below minus eighteen degrees Celsius through plate freezing, blast freezing, or cryogenic methods to arrest microbial activity and maintain protein integrity for extended commercial distribution. The fish segment sustains volume leadership through pollock, mackerel, and salmon consumption in retail and foodservice channels, while shrimp commands premium margin pools driven by sushi and tempura demand. Foodservice end users concentrate procurement of individually quick frozen portions to manage labor costs and yield consistency across restaurant chains. Supermarket distribution channels occupy the structural center of value capture, though online platforms are gaining traction among urban households seeking direct-to-door frozen delivery.
METI enforces cold chain efficiency standards under the Act on Rationalization of Energy Use, while the Ministry of Health, Labour and Welfare applies Food Sanitation Act requirements to frozen seafood importers and domestic processors. JIS standards for frozen fish product labeling and quality grading shape market access for both domestic producers and foreign suppliers. Stakeholders must monitor evolving F-Gas Regulation alignment discussions and carbon accounting pressures on refrigerated logistics to anticipate compliance cost shifts and infrastructure investment timing.
Market Dynamics
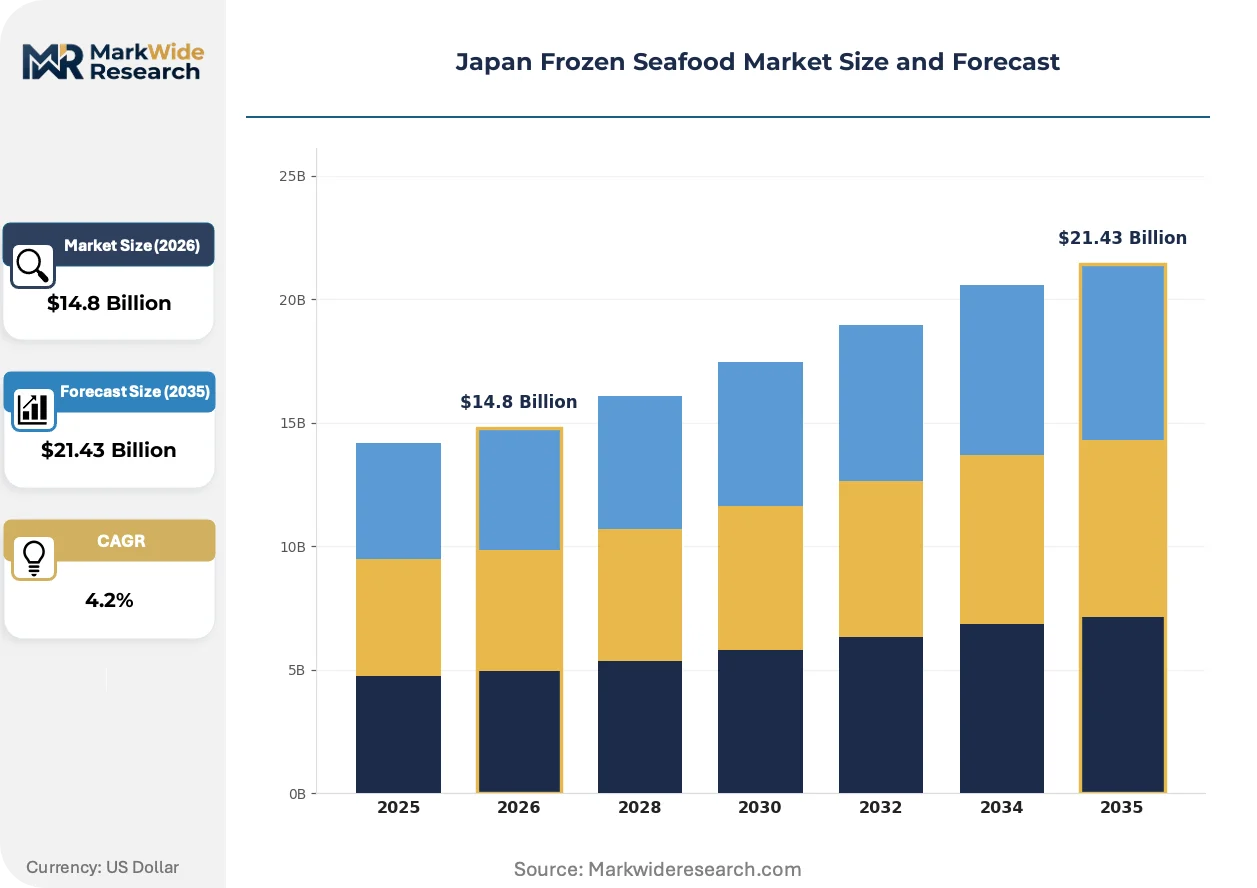
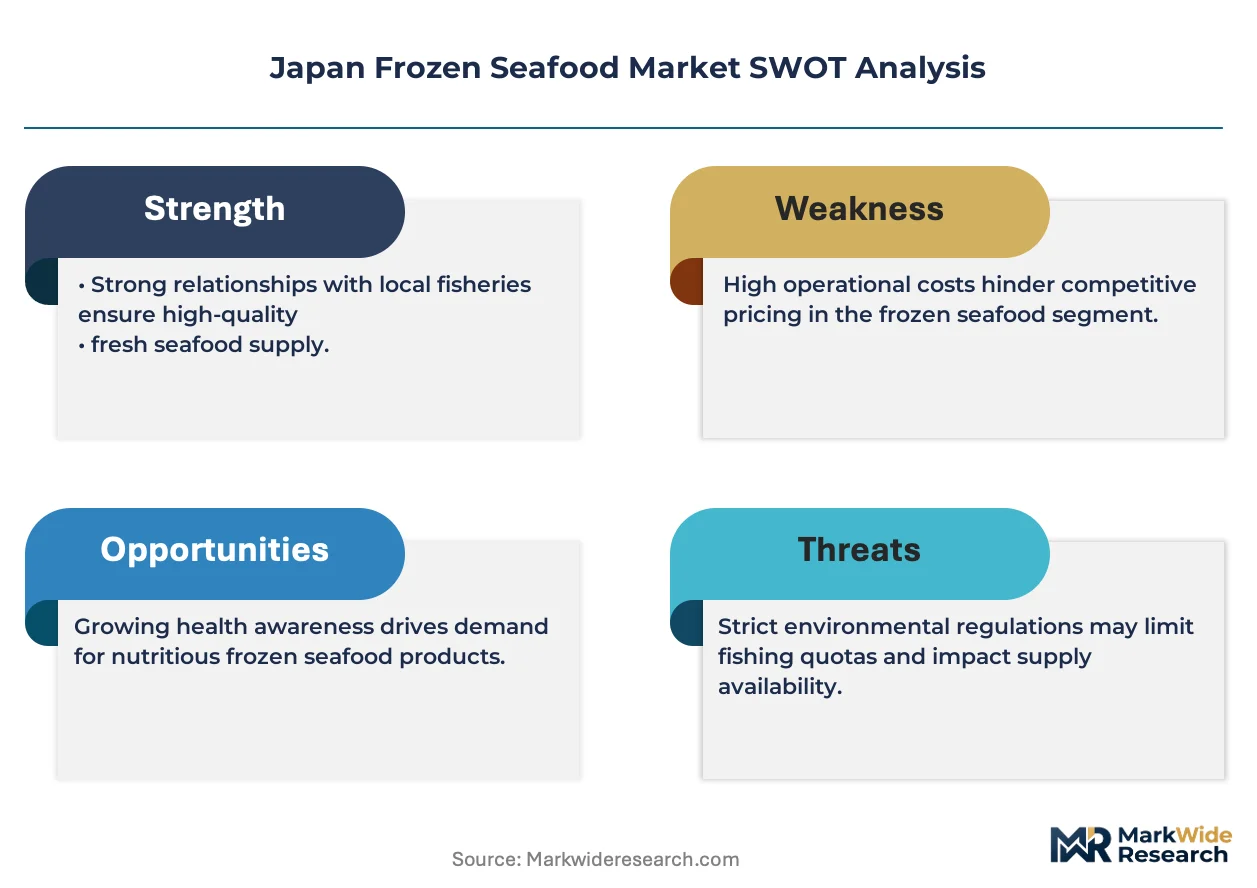
Blast-freeze infrastructure ownership is concentrating competitive advantage among capital-deploying processors, while rental-dependent operators face margin compression from METI energy efficiency mandates and rising F-gas compliance costs.
Growth Catalysts
- Foodservice Labor Arbitrage:Restaurant chains are accelerating adoption of individually quick frozen fillets to reduce skilled knife-work dependency and standardize portion yields across outlet networks.
- METI Cold Chain Mandates:The Act on Rationalization of Energy Use is forcing efficiency upgrades that favor scale operators with capital to deploy advanced plate-freezing systems.
- Hotel Banquet Expansion:Premium hospitality operators in Tokyo and Osaka are expanding frozen seafood procurement for large-format catering with consistent quality requirements.
Market Restraints
- Fuel Price Volatility:Deepwater trawler operations face input cost instability from marine diesel fluctuations that compress fleet operating margins.
- Cold Storage Concentration:Tsukiji-adjacent and Kanto corridor freezer capacity is controlled by a limited asset base, creating bottleneck risk for non-integrated processors.
- Fresh Sushi Substitution:High-end omakase establishments maintain preference for same-day landed fish, limiting frozen penetration in the premium tier.
Strategic Opportunities
- Kyushu Port Clusters:Underdeveloped cold storage infrastructure in southern Japan offers first-mover advantage for blast-freeze facility investment.
- Direct-to-Door Platforms:Urban household segments in Yokohama and Nagoya are adopting online frozen seafood delivery with subscription mechanics.
- JIS Grade Certification:Export-oriented processors can capture premium positioning through quality grading alignment with supermarket private label requirements.
Industry Challenges
- Refrigeration Technician Scarcity:Cold chain maintenance expertise is concentrating among aging workforce cohorts with limited apprenticeship pipeline.
- HACCP Timeline Compression:Ministry of Health, Labour and Welfare protocol revisions are extending compliance certification cycles for frozen food handlers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Frozen Seafood Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $21.43 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish, Shrimp, Squid, Shellfish End User: Retailers, Foodservice, Households, Restaurants Distribution Channel: Supermarkets, Online, Wholesalers, Specialty Stores Packaging Type: Vacuum Sealed, Ice Pack, Bulk, Tray |
| Companies Covered | Kyokuyo Corporation, Thai Union Group, Maruha Nichiro Corporation, Cooke Inc., Charoen Pokphand Foods Group, Nippon Suisan Kaisha (Nissui), Mowi ASA, Dongwon Group, Nichirei Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Frozen Seafood Market Strategic Shifts & Innovations
Cryogenic freezing methods and smart logistics platforms are redrawing operational boundaries between catch landing and retail shelf, while regulatory pressure on refrigerant chemistry forces equipment replacement cycles.
Blast-freezing technology is fragmenting the processor landscape by enabling smaller-scale operators to achieve protein integrity previously reserved for industrial plate-freezing installations. Mid-tier seafood processors in Hokkaido are adopting compact nitrogen-based systems to bypass centralized cold storage dependency. This diffusion is compressing the historical advantage of integrated trawler-to-freezer conglomerates.
METI's alignment discussions with EU F-Gas Regulation are accelerating hydrofluorocarbon phase-out timelines for refrigerated transport fleets. Fleet operators face compressed replacement windows for cooling units across the Kanto distribution corridor. Cold logistics providers are responding with ammonia-CO2 cascade system pilots in Yokohama port zones.
Urban household purchasing is migrating from supermarket freezer aisles toward platform-coordinated direct delivery with temperature-verified packaging. Younger demographic segments in Tokyo's 23 wards are subscribing to frozen seafood boxes with recipe-matched portioning. This channel rotation is most visible among dual-income households seeking convenience without quality compromise.
Japan Frozen Seafood Market Segmentation
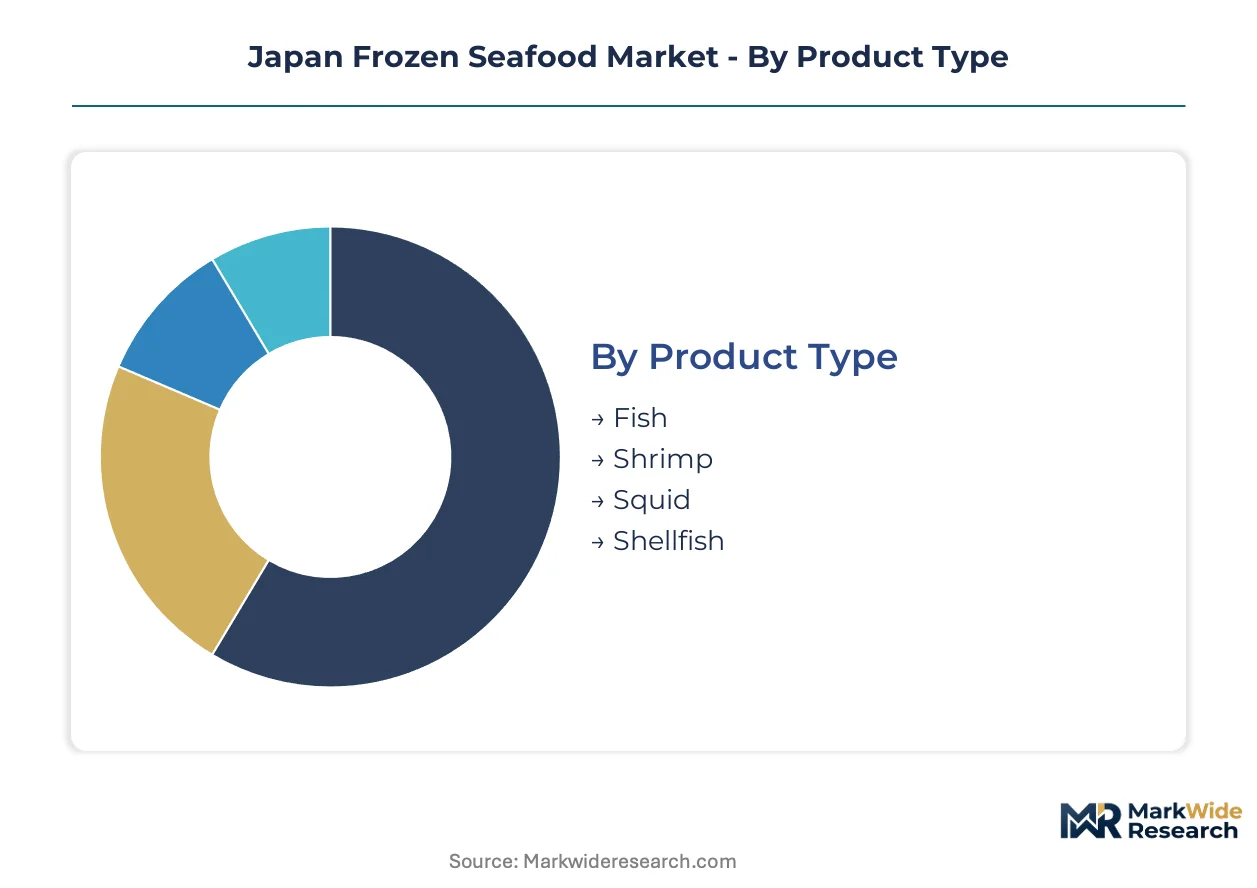
Japan's frozen seafood sector fragments across four critical dimensions that determine margin capture and channel access. Product type dictates freezing technology requirements, while distribution channel ownership separates integrated conglomerates from rental-dependent processors.
Product Type:
Fish commands the highest throughput across Tsukiji-adjacent cold storage networks, with pollock and mackerel flowing through supermarket freezer sections and foodservice procurement channels. Shrimp and squid concentrate in premium hospitality supply chains, while shellfish routes through specialty retail and direct-to-door platforms.
- Fish:Pollock, mackerel, and salmon preserved through plate freezing or blast freezing retain protein integrity for extended distribution. Tokyo's central wholesale markets and Kanto corridor cold storage clusters concentrate procurement from retail and foodservice channels seeking standardized portion yields. METI cold chain mandates favor scale operators with capital to deploy advanced freezing infrastructure.
- Shrimp:Individually quick frozen portions command premium positioning driven by sushi and tempura demand in restaurant chains and hotel banquet operations. Sushi-grade specifications require cryogenic or nitrogen-based freezing systems that compress the advantage of smaller-scale Hokkaido processors bypassing centralized cold storage dependency.
- Squid:Processed for izakaya chains and prepared food manufacturers with texture-sensitive freezing protocols.
- Shellfish:Routes through specialty stores and online platforms serving urban households seeking direct-to-door delivery.
Fish dominates installed base. Shrimp is where expansion concentrates.
End User:
Cost tier separation distinguishes labor-arbitrage-seeking foodservice operators from quality-focused retail channels. Restaurants and foodservice chains prioritize individually quick frozen fillets to reduce skilled knife-work dependency, while households and retailers emphasize convenience and portion consistency.
- Retailers:Supermarket chains and specialty stores control the structural center of value capture through controlled distribution into freezer sections nationwide. Private label requirements and JIS grade certification standards shape procurement from export-oriented processors seeking premium positioning.
- Foodservice:Restaurant chains and institutional catering operations accelerate adoption of standardized frozen portions to manage labor costs and yield consistency across outlet networks. Premium bento chains and hotel banquet operations in Tokyo and Osaka expand procurement of individually quick frozen fillets.
- Households:Dual-income segments in Tokyo's 23 wards and Yokohama subscribe to platform-coordinated frozen seafood boxes with recipe-matched portioning.
- Restaurants:High-end omakase establishments maintain preference for same-day landed fish, limiting frozen penetration in the premium tier.
Foodservice dominates installed base. Households represent the steepest expansion trajectory.
Distribution Channel:
Channel ownership determines cold chain control and margin retention, with supermarket networks offering scale access and online platforms enabling direct customer relationships. Wholesalers and specialty stores serve niche segments with specific quality or provenance requirements.
- Supermarkets:Controlled distribution into freezer sections nationwide occupies the structural center of value capture, with Nichirei Corporation and integrated conglomerates dominating shelf access. METI energy efficiency mandates and rising F-gas compliance costs favor scale operators with capital for infrastructure deployment.
- Online:Direct-to-door platforms gain traction among urban households in Yokohama and Nagoya seeking temperature-verified packaging and subscription mechanics. Younger demographic segments migrate from supermarket freezer aisles toward platform-coordinated delivery.
- Wholesalers:Tsukiji-adjacent and Kanto corridor operators control bottleneck capacity for non-integrated processors.
- Specialty Stores:Serve premium segments with JIS grade-certified products and regional provenance specifications.
Supermarkets dominate installed base. Online is where expansion concentrates.
Packaging Type:
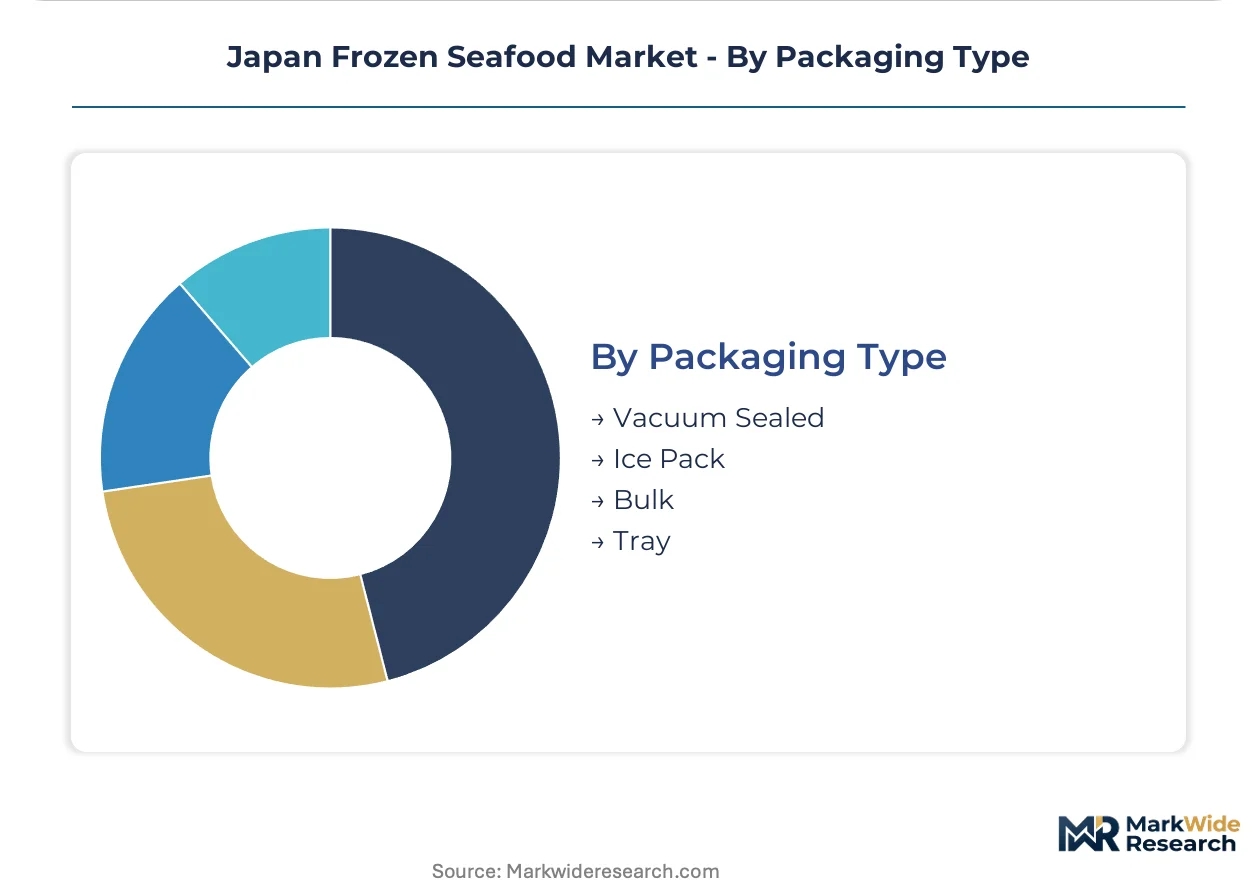
Packaging technology aligns with distribution distance and quality preservation requirements, with vacuum sealing and ice packs serving premium channels and bulk formats addressing cost-sensitive foodservice procurement.
- Vacuum Sealed:Extends shelf life for retail and export channels requiring extended distribution timelines. Premium supermarket private labels and direct-to-door platforms specify vacuum sealing to maintain protein integrity through temperature-verified logistics.
- Ice Pack:Enables shorter-distance distribution for specialty stores and online platforms with rapid fulfillment capabilities.
- Bulk:Foodservice chains and restaurant procurement favor bulk formats for portion control and labor cost reduction.
- Tray:Retail-ready presentation for supermarket freezer sections with standardized portion sizing.
Vacuum sealed dominates installed base. Tray formats are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Japan diverge sharply between the Kanto corridor's institutional foodservice dominance and Kyushu's emerging retail-direct channels. Urban density and cold storage infrastructure concentration drive these regional distinctions.
Kanto/Tokyo
Tokyo's central wholesale markets and Tsukiji-adjacent cold storage clusters command national distribution leverage. METI enforces cold chain efficiency standards under the Act on Rationalization of Energy Use that favor scale operators with capital for advanced plate-freezing systems. Premium bento chains and hotel banquet operations in the capital accelerate procurement of individually quick frozen fillets to manage labor costs.
Kansai/Osaka
Osaka's hospitality sector mirrors Tokyo's banquet expansion but with stronger izakaya chain penetration driving squid and prepared seafood demand. The Ministry of Health, Labour and Welfare applies Food Sanitation Act requirements to frozen food handlers with particular scrutiny on cross-border imports through Kansai International Airport. Cold storage capacity concentrates in Osaka Bay port zones with limited expansion land.
Hokkaido
Marine catch landing volumes sustain blast-freeze infrastructure investment across northern processing zones. Mid-tier seafood processors adopt compact nitrogen-based systems to bypass centralized cold storage dependency. Pollock and salmon flow through Sapporo-coordinated distribution into supermarket freezer sections nationwide.
Kyushu
Underdeveloped cold storage infrastructure in southern Japan offers first-mover advantage for blast-freeze facility investment. Fukuoka and Nagasaki port clusters see accelerating direct-to-door platform adoption among urban households. Younger demographic segments subscribe to frozen seafood boxes with recipe-matched portioning.
Chubu/Nagoya
Manufacturing belt logistics networks integrate frozen seafood into industrial catering supply chains. Toyota-adjacent foodservice operations prioritize individually quick frozen portions for standardized yield across outlet networks. JIS standards for frozen fish product labeling shape procurement from regional processors seeking supermarket private label placement.
Japan Frozen Seafood Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with capital ownership of trawler fleets and cold storage assets determining competitive position. Blast-freeze infrastructure concentration favors conglomerates with upstream catch control, while rental-dependent processors face margin compression from METI energy mandates. Three archetypes dominate: integrated trawler-to-retail operators, fleet-owning deepwater specialists, and household-channel distributors with controlled supermarket access. Competitive moves center on cold storage capacity expansion and direct-to-door platform partnerships.
Among Japan-based integrated conglomerates, Maruha Nichiro Corporation and Kyokuyo Corporation exemplify the fleet-ownership archetype with Hokkaido and Kyushu operational footprints. Nichirei Corporation anchors the household-channel tier through controlled distribution into supermarket freezer sections. Thai Union Group represents the Southeast Asian processing specialist position with supply relationships into Japanese foodservice channels. These three occupy distinct vertical positions rather than direct overlapping competition.
| Leading Market Players |
|---|
| Kyokuyo Corporation |
| Thai Union Group |
| Maruha Nichiro Corporation |
| Cooke Inc. |
| Charoen Pokphand Foods Group |
| Nippon Suisan Kaisha (Nissui) |
| Mowi ASA |
| Dongwon Group |
| Nichirei Corporation |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between blast-freeze infrastructure owners and Kanto corridor supermarket chains lock in both cold storage access and price visibility across volatile marine diesel cycles. These contracts insulate scale operators from spot market fluctuations while compressing margin buffers for rental-dependent processors facing METI energy efficiency mandates.
Pricing Analysis
Contract-based long-term offtake dominates procurement between integrated trawler-to-retail conglomerates and foodservice chains seeking yield consistency. Price differentiation rests on JIS grade certification and volume scale, with premium sushi-grade specifications commanding substantial uplifts over standard retail tiers. Pricing pressure stems from F-gas compliance costs and cold storage rental inflation, which squeeze mid-tier processors disproportionately. Foodservice chains exhibit highest price sensitivity due to labor arbitrage mandates, while hotel banquet operations absorb premium positioning with less elasticity.
Supply Chain Analysis
Port congestion in Tokyo Bay and container availability fluctuations on trans-Pacific trade lanes elevate inbound logistics costs for Russian pollock and Vietnamese shrimp shipments. Supply concentration draws from Russia, Vietnam, and domestic Hokkaido catch zones, with raw material flows resting on marine diesel, refrigerant chemistry, and blast-freeze equipment inputs. Single-source vulnerability concentrates in Tsukiji-adjacent cold storage assets controlled by limited operators. Distribution runs through supermarket freezer sections nationwide, with direct-to-door platforms emerging as secondary channel infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as direct-to-door platform adoption accelerates among urban households seeking temperature-verified delivery without supermarket intermediary markup.
For Market Incumbents: Fortify cold storage ownership positions in Kyushu port clusters before competitor capital deployment captures first-mover advantage in underdeveloped southern infrastructure. Deepen backward integration into compact nitrogen-based freezing systems to bypass centralized dependency. METI refrigerant phase-out timelines threaten rental-dependent processors with stranded asset risk; captive blast-freeze capacity defends margin position against this regulatory compression. For New Entrants and Emerging Players: Lead with subscription mechanics targeting dual-income households in Yokohama and Nagoya corridor zones where platform coordination penetration remains below Kanto saturation levels. Kyushu cold storage infrastructure offers the most penetrable geographic white space. Position around JIS grade certification alignment with supermarket private label procurement specifications to secure channel access without legacy shelf relationships. For Investors and Strategic Acquirers: Fleet-owning deepwater specialists with Hokkaido operational footprints represent the priority acquisition archetype for long-term viability across the analysis window. These assets combine upstream catch control with blast-freeze infrastructure ownership that rental-dependent competitors cannot replicate. Monitor METI-EU F-Gas Regulation alignment discussions as the critical inflection signal for compliance cost acceleration and equipment replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Kyushu Cold Storage Capacity Expansion | Captures first-mover advantage in underdeveloped southern Japan infrastructure ahead of competitor deployment. |
| Direct-to-Door Platform Partnership | Secures customer relationship ownership bypassing supermarket intermediary control held by Nichirei. |
| JIS Grade Certification Investment | Unlocks premium supermarket private label placement and export-oriented positioning against uncertified rivals. |
| Nitrogen-Based Freezing System Adoption | Enables smaller-scale Hokkaido processors to bypass Tsukiji-adjacent cold storage bottleneck dependency. |
| Ammonia-CO2 Cascade Pilot Deployment | Anticipates METI-EU F-Gas alignment with zero-hydrofluorocarbon refrigeration for Kanto corridor fleet compliance. |
Research Approach
Initial hypotheses were tested against primary input from blast-freeze facility operators, supermarket category buyers, foodservice procurement directors, and cold logistics fleet managers and refined through secondary validation across METI regulatory filings, Ministry of Health Labour and Welfare HACCP protocol revisions, JIS standards documentation, and customs trade data on marine product flows. Bottom-up volume modeling triangulated with top-down value reconciliation anchored the sizing framework.
Variance decomposition across product type, end user tier, distribution channel ownership, and regional cold storage infrastructure concentration shaped analytical segmentation. CAGRs were derived from installed base penetration curves and adoption trajectory analysis across the projection horizon. Forecast inputs incorporated METI energy efficiency mandate implementation timelines and F-gas refrigerant phase-out schedule assumptions.
The analysis sits within stated boundaries; outcomes outside sustained cold chain infrastructure investment and stable marine diesel cost environments would require recalibration. Forecasts reflect documented assumptions on platform adoption velocity and regulatory alignment timing. Practitioners should keep alternative scenarios live as METI-EU F-Gas negotiation positions and urban household delivery preference shifts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
United States Plant-Based Seafood Market
Seafood
Fish Processing Market
Seafood
South America Canned Seafood Market
Seafood
Tuna Market
Seafood
North America Tuna Market
Seafood
Fried Dace with Salted Black Beans Market
Seafood
Sardine and Anchovy Umami Concentrate Systems Market
Seafood
Canned Mackerel Market
Seafood
Processed Seafood and Seafood Processing Equipment Market
Seafood
Fish Meal Market
Seafood
Mussels Market
Seafood
Asia-Pacific Seafood Market
Seafood
Striped Bass Market
Seafood
Seafood Extracts Market
Seafood
Europe Lobster Market
Seafood
Fish Powder Market