
 Canned Anchovy Market | 2026-2036
Canned Anchovy Market Size, Share, and Industry Trends Forecast 2026-2036
Canned Anchovy Market Insights
Asset-light contract processing and third-party canning leases are reshaping competitive entry in the canned anchovy sector. Calvo Group leverages vertical integration from fleet to shelf to sustain margin control across Spanish retail channels. Thai Union Group competes through scale advantages in Southeast Asian raw material sourcing. Ortiz Conservas differentiates via artisan positioning and glass jar premiumization in specialty food stores.
Canned anchovies are small pelagic fish preserved through steam-cooking or brine-curing, then packed in oil, salt, or sauce within hermetically sealed metal or glass containers with shelf stability exceeding 24 months at ambient temperatures. The product serves as a concentrated umami ingredient for food manufacturers, pizza operators, and household pantries seeking long-duration protein storage. Fillet anchovies command premium placement in gourmet shops and restaurants due to labor-intensive manual cleaning and higher oil-grade packing standards. Metal can packaging dominates volume throughput in supermarkets and wholesale distributors, while vacuum sealed packs are gaining traction among catering services seeking portion control and reduced waste. Distribution through food service providers remains the most margin-sensitive channel, with pricing power concentrated among operators offering certified sustainable catch documentation.
EU Green Deal fisheries protocols and EFSA contaminant thresholds for histamine and heavy metals are elevating testing costs and disqualifying smaller Moroccan and Peruvian processors from premium European market access. FDA seafood HACCP requirements and EPA fish consumption advisories shape US import acceptance criteria and retail labeling obligations for canned anchovy offerings. Stakeholders must monitor evolving maximum residue limits for cadmium and mercury, as regulatory tightening in multiple jurisdictions will determine which processing regions retain market access and which face exclusion from high-value retail and food service contracts.
Market Dynamics
EU Green Deal fisheries protocols are compressing market access for non-compliant processors while concentrating supply authority within Mediterranean coastal clusters that control certified sustainable catch documentation.
Growth Catalysts
- EFSA traceability mandates:Small pelagic supply chain digitization requirements are forcing processor upgrades that favor established Galician and Sicilian operators with existing compliance infrastructure.
- Food service umami demand:Pizza operators and sauce manufacturers are standardizing anchovy fillets as concentrated flavor inputs, creating volume pull through wholesale distribution channels.
- Glass jar premiumization:Marinated fillet lines in hermetic glass containers are capturing shelf space expansion in Italian and Spanish gourmet retail formats.
Market Restraints
- Histamine testing cost inflation:EFSA contaminant threshold enforcement is elevating laboratory certification expenses that disqualify smaller Moroccan processors from premium European contracts.
- Peruvian supply concentration:Raw material dependence on Southeast Asian and Eastern Pacific fishing grounds exposes processors to El Niño-driven catch volatility and quota restrictions.
- Metal can substitution pressure:Vacuum-sealed flexible packaging alternatives are eroding volume share in catering services seeking portion-control efficiency.
Strategic Opportunities
- US retail penetration:FDA seafood HACCP compliance gaps among incumbent suppliers create entry space for certified Mediterranean processors targeting specialty food distributors.
- Carbon labeling alignment:EU Green Deal product footprint disclosure requirements favor operators with fleet-to-shelf emissions tracking already operational.
- Direct-to-chef platforms:E-commerce channels connecting Sicilian canneries to restaurant kitchens are bypassing traditional wholesale markups.
Industry Challenges
- Manual filleting labor scarcity:Artisan cleaning skills required for premium oil-grade packing are concentrating in aging workforce pools around Cádiz and Palermo.
- Dual certification timelines:Simultaneous EFSA heavy metal documentation and Marine Stewardship Council chain-of-custody audits are extending product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canned Anchovy Market |
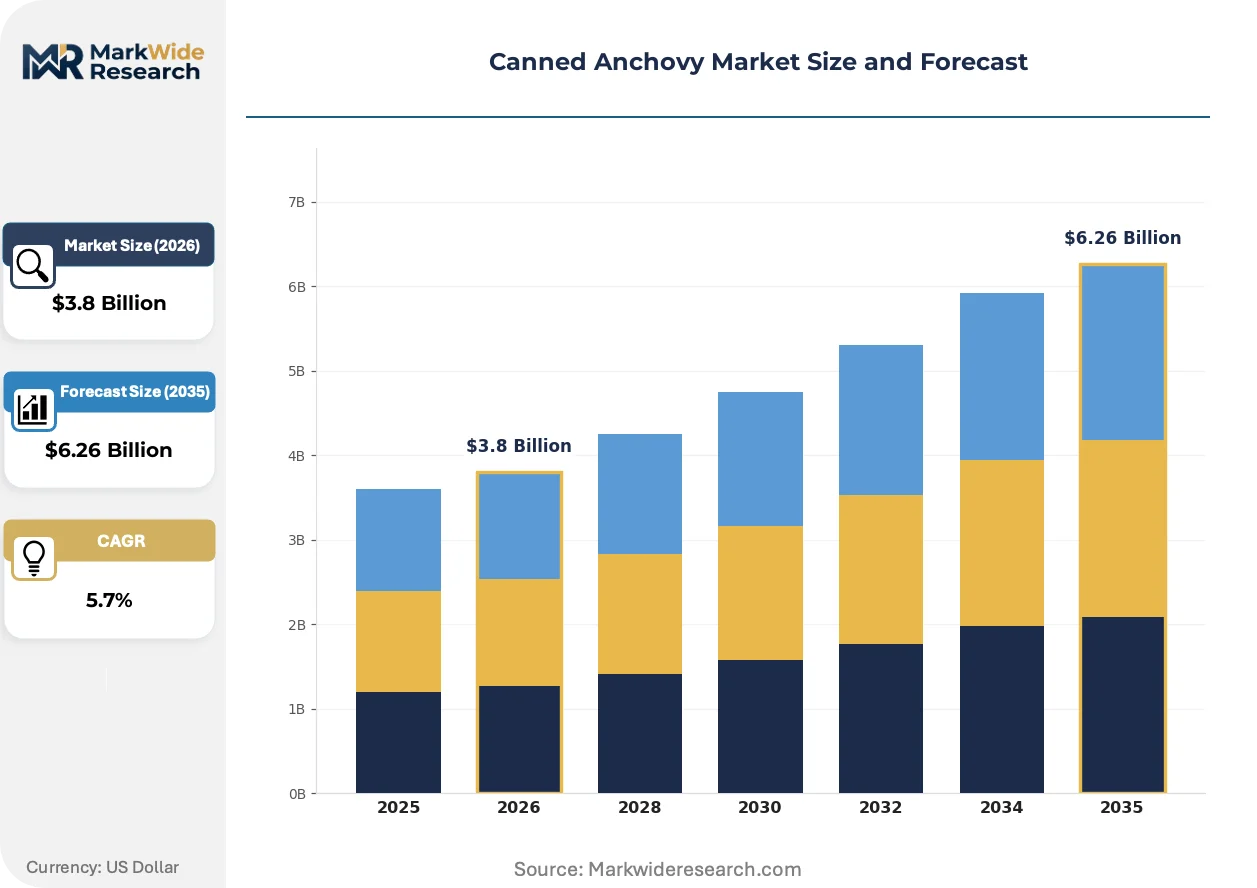
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Anchovies, Fillet Anchovies, Paste, Spiced Anchovies, Marinated Anchovies Packaging Type: Metal Can, Glass Jar, Plastic Container, Pouch Packaging, Vacuum Sealed Pack Distribution Channel: Supermarkets, Specialty Food Stores, Online Retail, Wholesale Distributors, Food Service Providers End User: Food Manufacturers, Restaurants, Catering Services, Household Consumers, Gourmet Shops |
| Companies Covered | Calvo Group, Grupo Consorcio, Ortiz Conservas, Delicius Rizzoli, Agromar, Bolton Group, Thai Union Group, Dongwon Industries, Maruha Nichiro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canned Anchovy Market Trends and Innovations
Automation in fillet processing and packaging line digitization are compressing labor dependencies while regulatory transparency tools are redefining competitive differentiation in premium segments.
High-speed optical sorting systems paired with AI-driven defect detection are replacing manual quality control stations in Galician canneries. Mid-scale processors are adopting these systems to maintain EFSA compliance without expanding headcount. This technological shift is rendering obsolete the traditional artisan-labor cost advantage that previously sustained smaller competitors.
EU Green Deal extended producer responsibility frameworks are mandating metal can recycling participation rates and supply chain carbon disclosure. Spanish and Italian processors face binding reporting thresholds that favor vertically integrated operators with captive fleet emissions data. Fillet-grade product lines bear the heaviest documentation burden due to higher per-unit environmental footprint exposure.
Restaurant procurement teams are consolidating supplier relationships around certified sustainable catch documentation rather than price-per-kilogram metrics. Food service distributors in France and Germany are responding by bundling anchovy SKUs with traceability dashboards. This buyer behavior shift is most pronounced in Northern European markets where Ecolabel recognition drives menu planning decisions.
Canned Anchovy Market Segmentation
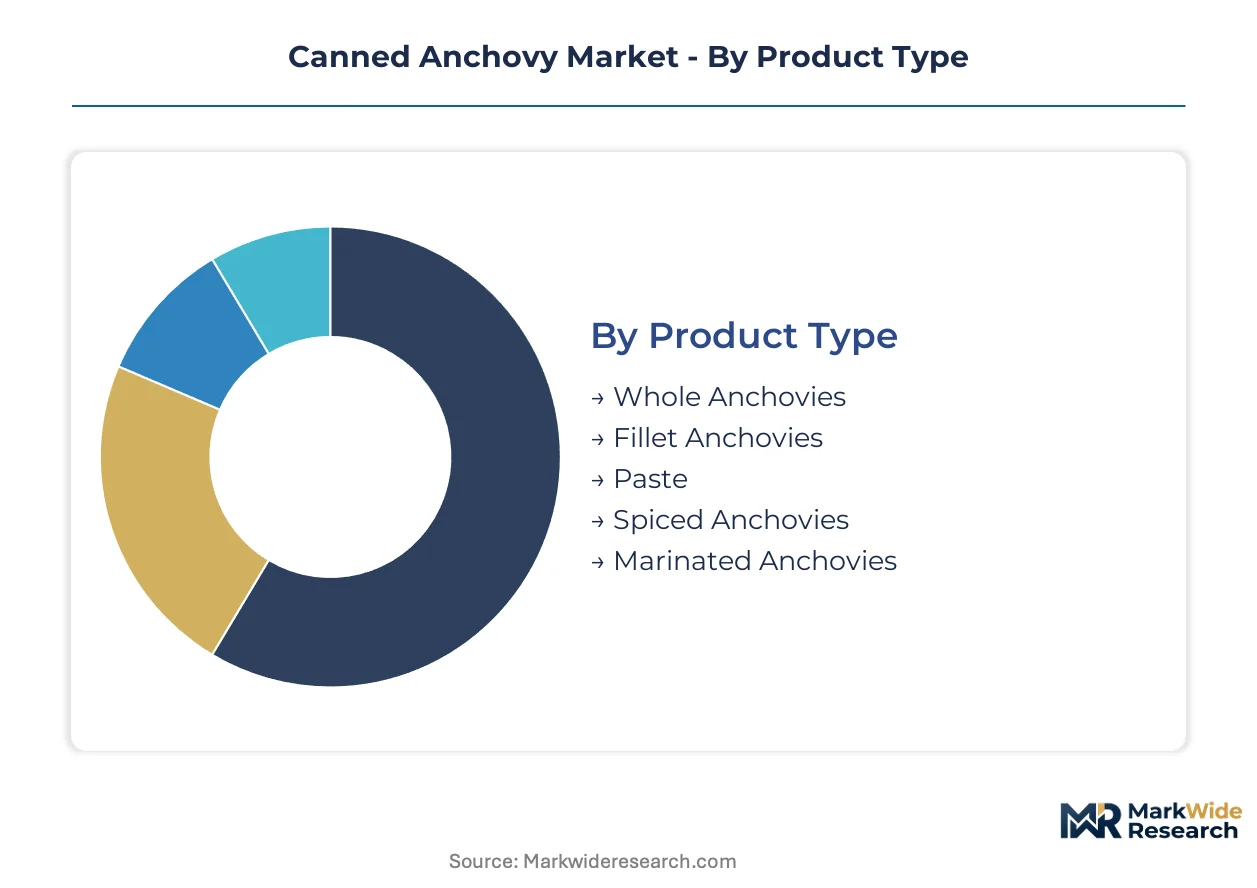
Canned anchovy segmentation reveals distinct margin architectures across preparation grades and channel access tiers. Product type and packaging format decisions cascade through distribution economics and end-user procurement specifications.
Product Type:
Mature formats dominate volume throughput while emerging value-added lines reshape margin capture.
- Fillet Anchovies:Labor-intensive manual cleaning produces boneless oil-grade fillets meeting EFSA contaminant thresholds. Demand concentrates in Italian and Spanish gourmet shops where glass jar premiumization commands shelf space expansion. Ecolabel recognition drives menu planning decisions among Northern European restaurant procurement teams.
- Marinated Anchovies:Vinegar-cured fillets in hermetic glass containers serve as concentrated umami ingredients for pizza operators and sauce manufacturers. Galician and Sicilian processors control certified sustainable catch documentation required by food service distributors in France and Germany.
- Whole Anchovies:Steam-cooked or brine-cured small pelagics packed in salt or oil for wholesale distribution and household pantry storage.
- Paste:Pulverized anchovy concentrate used as flavor base in manufactured sauces and processed foods.
- Spiced Anchovies:Chili, garlic, or herb-infused variants targeting specialty retail formats in Mediterranean markets.
Fillet Anchovies handles the majority of throughput; Marinated Anchovies is the fastest mover on share.
Packaging Type:
Cost tier stratification separates commodity metal can volumes from premium glass jar positioning.
- Metal Can:Hermetically sealed cylindrical containers dominate supermarket and wholesale distributor volume throughput. Thai Union Group and Calvo Group leverage scale advantages in Southeast Asian raw material sourcing and Spanish retail channel control respectively. Shelf stability exceeding 24 months at ambient temperatures serves food manufacturers and household consumers seeking long-duration protein storage.
- Glass Jar:Hermetic sealing preserves marinated fillet lines for Italian and Spanish gourmet retail formats. EU Green Deal extended producer responsibility frameworks mandate recycling participation rates that favor vertically integrated operators with captive fleet emissions data.
- Vacuum Sealed Pack:Portion-control efficiency gains traction among catering services seeking reduced waste.
- Pouch Packaging:Flexible alternatives eroding volume share in food service channels.
- Plastic Container:Lower-cost option for mass-market retail placements.
Metal Can captures the bulk of unit economics; Glass Jar is climbing the fastest on value contribution.
Distribution Channel:
Customer type fragmentation splits procurement between price-sensitive wholesale and traceability-demanding specialty routes.
- Food Service Providers:Pizza operators and sauce manufacturers standardize anchovy fillets as concentrated flavor inputs. Pricing power concentrates among operators offering certified sustainable catch documentation. Margin sensitivity peaks in this channel where EFSA heavy metal documentation and Marine Stewardship Council chain-of-custody audits extend product launch cycles.
- Specialty Food Stores:Gourmet shops across Italy and Spain are expanding shelf space for premium fillet and marinated lines. E-commerce channels connecting Sicilian canneries to restaurant kitchens bypass traditional wholesale markups.
- Supermarkets:Volume throughput anchor for metal can formats.
- Wholesale Distributors:Bundling anchovy SKUs with traceability dashboards in response to buyer consolidation.
- Online Retail:Direct-to-chef platforms emerging from Mediterranean coastal processing clusters.
Food Service Providers manage the deepest volume pipelines; Specialty Food Stores are expanding most quickly on margin capture.
End User:
Application concentration varies between industrial ingredient demand and artisan consumption rituals.
- Restaurants:Procurement teams consolidate supplier relationships around certified sustainable catch documentation rather than price-per-kilogram metrics. Ecolabel recognition drives menu planning decisions in Northern European markets where EFSA traceability mandates force processor upgrades.
- Gourmet Shops:Artisan positioning and glass jar premiumization differentiate Ortiz Conservas in specialty food stores. Manual filleting labor scarcity concentrates in aging workforce pools around Cádiz and Palermo.
- Food Manufacturers:Standardized anchovy inputs for sauce and processed food production.
- Catering Services:Vacuum-sealed flexible packaging alternatives address portion-control efficiency requirements.
- Household Consumers:Pantry storage demand for long-duration protein.
Restaurants anchor procurement volume; Gourmet Shops show the steepest expansion trajectory on per-unit value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reshape competitive positioning across the canned anchovy sector. Mediterranean processors dominate premium fillet shipments to Northern Europe while Southeast Asian operators feed commodity volume into wholesale channels. Regulatory divergence between EFSA jurisdictions and FDA enforcement zones fragments market access protocols.
Spain
Gourmet retail expansion in Madrid and Barcelona drives glass jar premiumization for marinated fillet lines. EU Green Deal extended producer responsibility frameworks mandate metal can recycling participation rates that favor vertically integrated Galician operators. The Cádiz processing cluster concentrates artisan cleaning skills for oil-grade packing standards demanded by French and German distributors.
Italy
Restaurant procurement teams in Milan and Rome consolidate supplier relationships around Ecolabel recognition rather than price metrics. EFSA traceability mandates for small pelagic supply chains force processor upgrades that favor established Sicilian canneries with existing compliance infrastructure. The Palermo coastal cluster anchors manual filleting expertise for premium product lines.
United States
Pizza operators and sauce manufacturers standardize anchovy inputs as concentrated umami flavor bases. FDA seafood HACCP requirements and EPA fish consumption advisories shape import acceptance criteria and retail labeling obligations for Mediterranean processors. Specialty food distributors in New York and California create entry space for certified European suppliers with documentation gaps among incumbent sources.
Thailand
Scale advantages in Southeast Asian raw material sourcing support volume throughput for metal can formats. Thai Union Group leverages procurement networks across Eastern Pacific fishing grounds exposed to El Niño-driven catch volatility. Bangkok-based processing infrastructure serves wholesale distribution channels across Asia-Pacific markets with reduced regulatory documentation burdens compared to EU destinations.
Peru
Raw material concentration in Eastern Pacific fishing grounds exposes processors to quota restrictions and marine ecosystem fluctuations. National fisheries regulators enforce catch documentation schemes that determine access to premium European contracts. The Callao processing cluster manages commodity-grade whole anchovy production for bulk salt and oil packing destined for food manufacturers.
Canned Anchovy Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fragmented supply positions. The vendor base distributes across vertically integrated fleet operators, contract canning leaseholders, and artisan positioning specialists. Three archetypes dominate: Mediterranean coastal clusters with captive fleet emissions data, Southeast Asian scale players with raw material procurement networks, and premium-tier glass jar specialists with gourmet retail channel control. Capacity consolidation and certification infrastructure investments constitute the dominant competitive moves as EFSA compliance timelines extend product launch cycles.
Within the Mediterranean archetype tier, Calvo Group and Ortiz Conservas exemplify divergent strategic positioning. Calvo Group anchors vertically integrated Spanish retail channel control from fleet through shelf. Ortiz Conservas occupies the artisan specialist position with glass jar premiumization in specialty food stores. Thai Union Group represents the Southeast Asian scale-driven model with procurement advantages across Pacific fishing grounds.
| Leading Market Players |
|---|
| Calvo Group |
| Grupo Consorcio |
| Ortiz Conservas |
| Delicius Rizzoli |
| Agromar |
| Bolton Group |
| Thai Union Group |
| Dongwon Industries |
| Maruha Nichiro |
| Others |
Pricing and Supply Chain Analysis
The Galician coastal processing cluster concentrates certified sustainable catch documentation that underpins pricing power for Mediterranean fillet-grade exports to Northern European distributors. EFSA contaminant threshold enforcement compresses market access for non-compliant Moroccan operators, elevating premium tier scarcity value.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the canned anchovy sector. Pricing stratifies across EFSA heavy metal documentation tiers, with Marine Stewardship Council chain-of-custody certification commanding material premiums over baseline compliance. Cost compression in economy-grade metal can formats is intensifying because Thai Union Group and Calvo Group leverage Southeast Asian raw material procurement scale. Food service providers exhibit the highest price sensitivity due to standardized umami input specifications, while Italian gourmet shops demonstrate the lowest sensitivity given artisan positioning and glass jar premiumization.
Supply Chain Analysis
Tariff exposure between Morocco and the European Union dominates supply chain risk assessment for canned anchovy processors seeking premium market access. Raw material sourcing draws from Eastern Pacific fishing grounds around Peru, Southeast Asian waters, and Mediterranean coastal zones. Supply chain vulnerability rests on El Niño-driven catch volatility and quota restrictions that disrupt Peruvian anchovy landings. Distribution runs through Mediterranean coastal clusters with captive fleet emissions data, then channels through French and German food service distributors bundling traceability dashboards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The canned anchovy market is recovering from cyclical trough conditions as El Niño patterns normalize and Eastern Pacific fishing grounds stabilize. Procurement consolidation around certified sustainable catch documentation creates asymmetric returns for compliance-ready operators.
For Market Incumbents: Entrench EFSA traceability infrastructure investments to disqualify smaller Moroccan competitors from premium European contracts. Expand glass jar premiumization capacity in Sicilian and Galician processing clusters to capture gourmet retail shelf space expansion. Certification investment represents the critical defensive lever against Southeast Asian scale players eroding commodity tier margins. For New Entrants and Emerging Players: FDA seafood HACCP compliance gaps among incumbent US suppliers represent the most penetrable entry point for certified Mediterranean processors. Direct-to-chef e-commerce platforms connecting Palermo canneries to restaurant kitchens offer a defensible go-to-market angle bypassing traditional wholesale markups. Specialty food distributors in New York and California provide channel access with reduced incumbent saturation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated operators with captive fleet emissions data already operational under EU Green Deal frameworks. Long-term viability across the five-to-ten year window hinges on carbon labeling alignment and extended producer responsibility compliance infrastructure. The signal to watch is EFSA maximum residue limit tightening for cadmium and mercury, which will determine which processing regions retain premium market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fleet Operations | Captive supply of raw anchovy landings secures EFSA traceability documentation for premium fillet lines. |
| Glass Jar Premiumization Launch | Hermetic container formats capture shelf space expansion in Italian and Spanish gourmet retail channels. |
| AI-Driven Optical Sorting Deployment | High-speed defect detection systems compress labor dependencies while maintaining EFSA contaminant compliance. |
| Direct-to-Chef E-Commerce Platform | Sicilian canneries bypass wholesale markups by connecting directly to restaurant procurement teams. |
| Carbon Labeling Certification Program | Fleet-to-shelf emissions tracking satisfies EU Green Deal product footprint disclosure requirements. |
Research Methodology
Cross-validation between processor production records and customs trade data anchors the qualitative findings in this study. Primary interviews with cannery operations directors, food service procurement managers at pizza chains, gourmet retail category buyers, and EFSA regulatory affairs specialists combined with secondary validation from EU fisheries landing statistics, EFSA contaminant monitoring reports, and Marine Stewardship Council chain-of-custody databases. Bottom-up volume modeling and top-down value reconciliation triangulate market size estimates.
Calibration against historical price series and volume throughput patterns informs the analytical framework across the projection horizon. Segmentation dimensions modeled include product preparation grade, packaging format, distribution channel tier, and end-user application concentration. CAGRs were derived from trend extrapolation adjusted for regulatory compliance cost inflation and El Niño cycle impacts on raw material availability. Industry-specific forecast inputs incorporate EFSA maximum residue limit revision schedules and EU Green Deal extended producer responsibility phase-in timelines.
Practitioners should monitor EFSA heavy metal threshold tightening and El Niño Southern Oscillation indices for early signals of forecast revision. Forecasts reflect assumptions regarding regulatory enforcement consistency and fishing quota stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
United States Plant-Based Seafood Market
Seafood
Fish Protein Hydrolysate Market
Seafood
Oyster Meal Market
Seafood
Global Seafood Market
Seafood
Groundfish Market
Seafood
Frozen Seafood Market
Seafood
Tuna Market
Seafood
COD Market
Seafood
Fish Powder Market
Seafood
Crayfish Market
Seafood
Latin America Salmon Market
Seafood
Salmon Fish Market
Seafood
Mussel Extract Market
Seafood
Canned Mackerel Market
Seafood
Salmon Market
Seafood
Haddock Market