
 Canned Salmon Market | 2026-2036
Canned Salmon Market Size, Share, and Industry Trends Forecast 2026-2036
Canned Salmon Market Analysis
Retort pouch sterilization is rewriting how salmon processors preserve flavor texture and shelf stability without traditional tin-can infrastructure. Trident Seafoods leverages its Alaska-based vertical harvesting to control raw material quality from catch to can. Thai Union Group anchors its volume leadership through Thai and European processing hubs that serve private-label retail contracts. Maruha Nichiro competes via Japanese cold-chain expertise that extends premium fillet freshness into ambient retail formats.
Canned salmon consists of cooked salmon flesh preserved in hermetically sealed containers through thermal processing, typically achieving commercial sterility at F0 values exceeding three minutes while retaining omega-3 fatty acid profiles above two grams per hundred-gram serving for nutritional labeling claims. Its primary commercial purpose is to deliver shelf-stable protein to retail and foodservice buyers independent of refrigerated distribution. Chunk product dominates unit volume due to lower raw-material selectivity and broader price accessibility across mass-market channels. Pouch packaging represents the fastest-expanding format as retailers reduce shelf weight and consumers prioritize convenience opening. Smoked variants command premium positioning in specialty stores where flavor differentiation supports margin pools that offset slower inventory turns.
The FDA enforces low-acid canned food regulations under CFR 113 requiring scheduled thermal processes and container integrity testing for all salmon entering US interstate commerce. The EU EFSA sets maximum residue limits for heavy metals and contaminants under EC 1881/2006 that directly determine which harvest lots gain European market access. Food service buyers must monitor how tightening Marine Stewardship Council chain-of-custody requirements reshape supplier qualification timelines and procurement flexibility.
Market Dynamics
Retort pouch sterilization is virtualizing traditional canning infrastructure across salmon processing, collapsing the capital barrier between ambient-stable packaging and cold-chain-dependent fresh fillet operations. This technology shift redistributes competitive advantage toward flexible-format contract manufacturers and away from legacy tin-can asset bases.
Growth Catalysts
- EU EFSA contaminant standards:Maximum residue limits under EC 1881/2006 are filtering harvest lots and concentrating demand around certified clean-water sources, tightening supplier qualification but securing premium channel access for compliant processors.
- Meal-kit protein sourcing:European ready-to-eat subscription services are pulling shelf-stable salmon into portion-controlled recipe boxes, creating pull-through demand that bypasses traditional retail shelf competition.
- Bergen processing corridor concentration:Norway's aquaculture infrastructure cluster near Bergen is capturing economies of scale in filleting, thermal processing, and logistics that lower unit costs for ambient-format exports.
Market Restraints
- Wild-catch supply volatility:Marine Stewardship Council certification timelines and tightening sustainability quotas are constraining raw material availability from Alaskan and Pacific Northwest fisheries, compressing wild-sourced product margins.
- Tin-plate input cost exposure:Traditional metal can formats remain exposed to steel tariff fluctuations and coating material chemistry regulations, disadvantaging processors without pouch-format flexibility.
- Frozen fillet substitution:Blast-frozen Atlantic salmon portions with extended refrigerated shelf life are capturing price-sensitive foodservice accounts that previously stocked canned alternatives.
Strategic Opportunities
- Private-label pouch contracts:Mass-market retailers are outsourcing ambient salmon development to co-manufacturers with retort expertise, opening white-space for processors without owned-brand heritage.
- Smoked variant premiumization:Specialty grocers are allocating shelf space to flavor-differentiated SKUs that command margin pools unavailable to standard chunk or flaked formats.
- Omega-3 retention marketing:Nutritional labeling claims above two grams per hundred-gram serving are creating regulatory-compliant differentiation that supports price positioning against lower-cost protein alternatives.
Industry Challenges
- Scheduled process validation:FDA low-acid canned food regulations under CFR 113 require thermal process filing and container integrity testing that extends new product launch timelines and consumes technical staff capacity.
- Cold-chain to ambient format transition:Japanese and Nordic processors with frozen-fillet heritage face equipment reconfiguration costs and sterility-culture gaps when entering retort pouch production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canned Salmon Market |
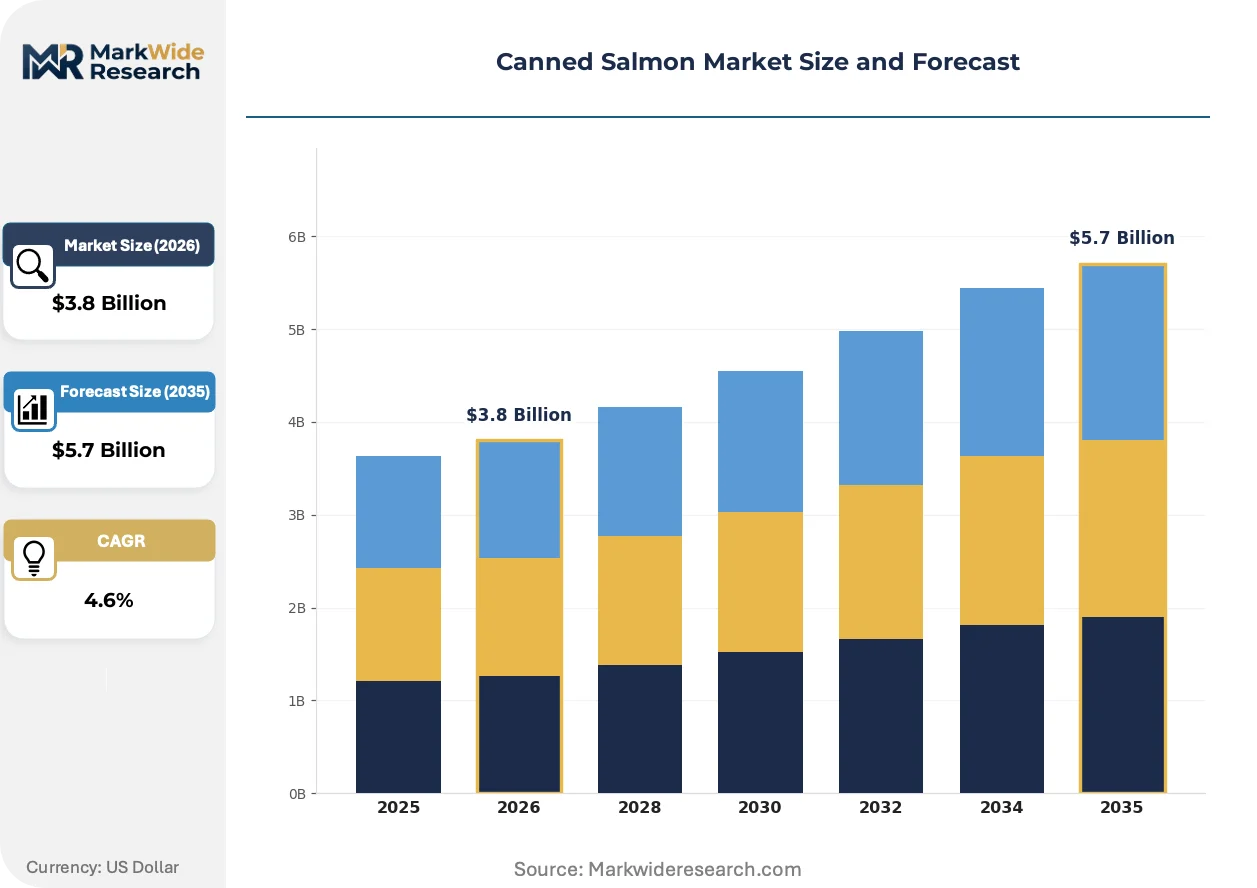
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chunk, Fillet, Smoked, Skinless Packaging Type: Tin, Glass Jar, Pouch, Can Distribution Channel: Supermarket, Online Retailer, Specialty Store, Wholesale End User: Household, Food Service, Retailer, Restaurant |
| Companies Covered | Trident Seafoods, Thai Union Group, Starkist, Bumble Bee Foods, Maruha Nichiro, Wild Planet Foods, Crown Prince, John West, Dongwon Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canned Salmon Market Emerging Trajectories
Digital traceability systems and alternative thermal processing methods are compressing the gap between artisanal freshness claims and mass-market shelf stability. These shifts reward processors who can verify provenance while maintaining ambient distribution economics.
Retort pouch laminates with high-barrier aluminum oxide coatings are virtualizing the protective function of traditional tin-plate cans while eliminating weight and opening-force disadvantages. European meal-kit assemblers and Nordic convenience retailers are adopting these formats for home-delivery protein inclusion. The technology is virtualizing the boundary between canned goods and fresh-food merchandising, forcing legacy canners to defend shelf space against flexible-format entrants.
EU EFSA is tightening maximum residue limits for heavy metals under EC 1881/2006, forcing harvest-lot segregation and testing protocols that extend supplier qualification timelines. Norwegian and Scottish farmed salmon operations are investing in feed-source traceability to preempt disqualification. Premium private-label contracts are concentrating among processors with documented chain-of-custody systems that satisfy tightening European market access rules.
Foodservice procurement is consolidating around direct-processor relationships that bypass traditional wholesale distribution. Nordic contract caterers and British institutional buyers are negotiating annual volume commitments with thermal processors in exchange for SKU customization and just-in-time delivery. This pattern is most visible in the United Kingdom and Netherlands, where foodservice cost pressures are eliminating distributor markups from ambient protein sourcing.
Canned Salmon Market Segmentation
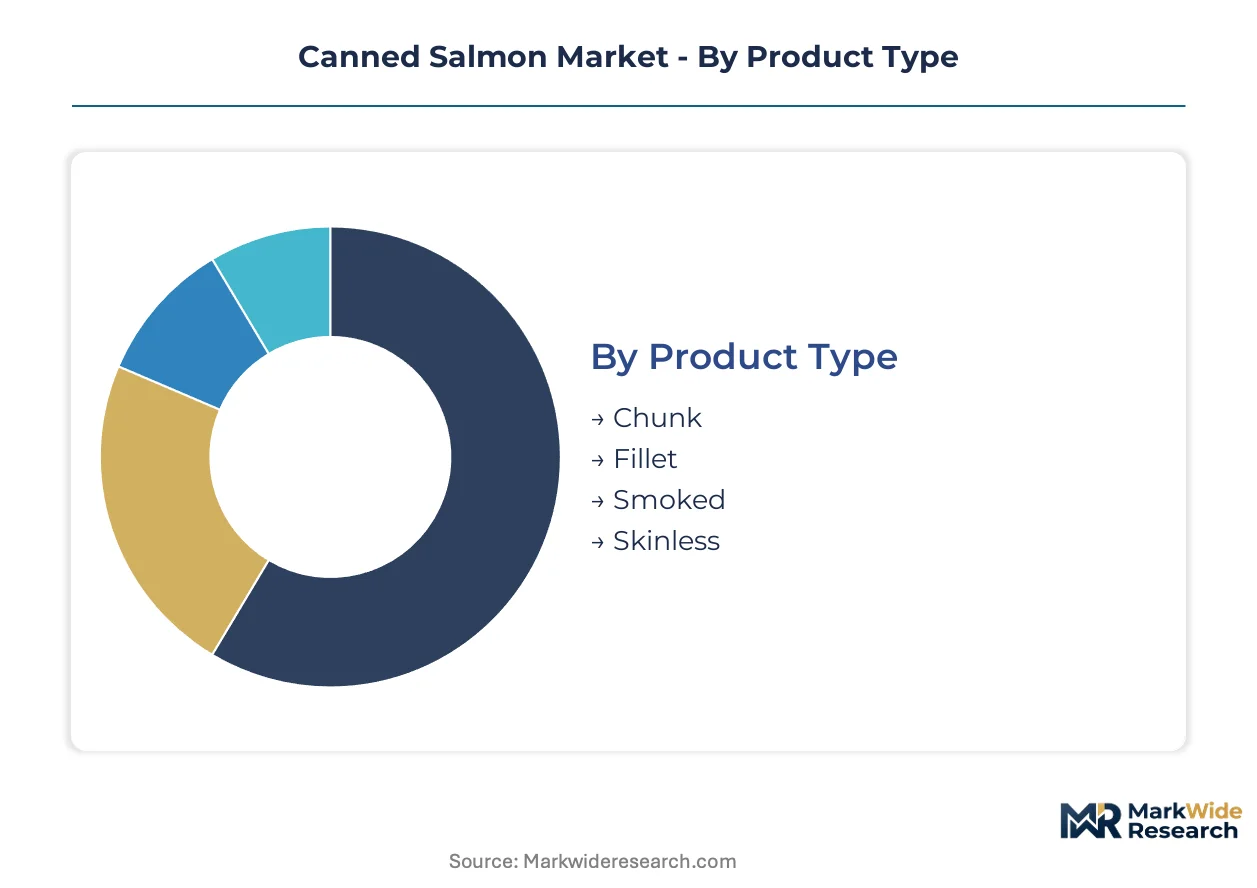
Canned salmon processors configure product portfolios around four intersecting dimensions that determine margin structure and channel access. Product format and packaging technology together define production economics, while distribution pathways and end-user specifications dictate pricing power and volume scalability.
Product Type:
Mature formats dominate shelf presence while emerging variants capture premium positioning through functional differentiation.
- Chunk:Irregular cooked flesh pieces processed from lower-grade raw material with minimal sorting requirements. Mass-market retailers in Germany and France concentrate procurement here for private-label economy tiers where price accessibility drives basket attachment.
- Fillet:Intact longitudinal sections preserving muscle fiber orientation and visual plate presentation. Norwegian meal-kit assemblers and British institutional foodservice buyers are concentrating demand around this format for portion-controlled recipe inclusion that justifies per-unit premiums.
- Smoked:Cold-smoked variants commanding specialty channel placement through flavor differentiation.
- Skinless:Labor-intensive preparation targeting convenience-oriented household segments.
Chunk retains volume leadership; Fillet holds the steepest expansion curve.
Packaging Type:
Cost tier stratification separates legacy metal infrastructure from flexible-format investments that reduce logistics burden.
- Tin:Traditional three-piece steel construction with internal lacquer coatings achieving F0 sterility thresholds. Alaskan and Pacific Northwest processors maintain captive canning lines here, though steel tariff exposure and coating chemistry regulations under EPA and FDA guidance compress margin flexibility.
- Pouch:Retortable multilayer laminates with aluminum oxide barrier coatings eliminating shelf weight and opening-force disadvantages. Thai and Vietnamese contract manufacturers are scaling capacity fastest to serve European retailer private-label contracts demanding ambient-stable protein with fresh-food merchandising aesthetics.
- Glass Jar:Premium positioning format for specialty smoked variants with visual product inspection.
- Can:Two-piece aluminum or steel drawn construction for standard chunk presentations.
Tin retains installed base dominance; Pouch is climbing the fastest on capital inflow.
Distribution Channel:
Customer type fragmentation is forcing processors to maintain parallel qualification systems for retail and foodservice procurement.
- Supermarket:Mass-market retail chains controlling shelf-stable seafood category management through annual listing negotiations. British and Dutch supermarket buyers are consolidating supplier bases around processors with documented Marine Stewardship Council chain-of-custody systems that satisfy tightening EFSA market access rules.
- Online Retailer:Direct-to-consumer platforms and meal-kit subscription services bypassing traditional wholesale distribution. Nordic convenience retailers and German recipe-box assemblers are pulling ambient salmon into home-delivery protein inclusion, creating demand that prioritizes pouch-format convenience over traditional can aesthetics.
- Specialty Store:Premium grocers allocating space to smoked and artisanal variants.
- Wholesale:Distributor-mediated supply to independent foodservice accounts.
Supermarket holds volume concentration; Online Retailer shows the steepest demand trajectory.
End User:
Application requirements diverge sharply between ambient pantry stocking and operational kitchen deployment.
- Household:Consumer pantry stocking for recipe ingredient and ready-to-eat protein occasions. Japanese and South Korean household buyers are concentrating demand around omega-3 nutritional labeling claims above two grams per hundred-gram serving, creating regulatory-compliant differentiation that supports price positioning against lower-cost protein alternatives.
- Food Service:Institutional and contract catering procurement negotiating annual volume commitments for SKU customization. British and Netherlands institutional buyers are eliminating distributor markups through direct-processor relationships that specify thermal process parameters and just-in-time delivery windows.
- Retailer:Private-label brand owners outsourcing product development to co-manufacturers.
- Restaurant:Independent foodservice operators with sporadic, specification-light purchasing patterns.
Household maintains consumption base; Food Service is gaining share fastest on procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in canned salmon tilt heavily toward processing hubs that convert raw harvest into shelf-stable formats for retail and foodservice buyers. Norway, Thailand, the United States, Japan, and the United Kingdom anchor the trade matrix through distinct supply-chain specializations.
Norway
European meal-kit services pull Norwegian-origin salmon into portion-controlled recipe boxes, bypassing traditional retail shelf competition. EFSA maximum residue limits under EC 1881/2006 filter harvest lots and concentrate demand around certified clean-water sources. The Bergen aquaculture processing corridor captures economies of scale in filleting, thermal processing, and logistics that lower unit costs for ambient-format exports.
Thailand
Private-label retail contracts from European mass-market chains drive volume through Thai processing hubs that serve as contract manufacturing centers. The country's national food safety regulator enforces thermal process standards aligned with Codex guidelines for low-acid canned foods. Bangkok-based co-manufacturers with retort pouch expertise are scaling fastest to meet retailer demand for ambient-stable protein with fresh-food merchandising aesthetics.
United States
Alaskan wild-catch operations supply raw material to domestic canneries, though Marine Stewardship Council certification timelines constrain availability from Pacific Northwest fisheries. FDA low-acid canned food regulations under CFR 113 require scheduled thermal processes and container integrity testing that extends new product launch timelines. Seattle-area processors maintain captive canning lines while facing pressure from pouch-format flexibility.
Japan
Household buyers concentrate demand around omega-3 nutritional labeling claims above two grams per hundred-gram serving, creating regulatory-compliant differentiation against lower-cost protein alternatives. METI oversees food labeling standards that govern shelf-stable seafood claims. Tokyo-Osaka corridor processors with frozen-fillet heritage face equipment reconfiguration costs when entering retort pouch production.
United Kingdom
Institutional and contract catering procurement negotiates annual volume commitments for SKU customization, eliminating distributor markups through direct-processor relationships. Food Standards Agency regulations implement EU-derived contaminant limits post-Brexit. British and Netherlands foodservice buyers are consolidating supplier bases around processors with documented Marine Stewardship Council chain-of-custody systems.
Canned Salmon Market Vendor Landscape
On the supply side, the industry is consolidating around processors with dual capabilities in traditional metal canning and retort pouch flexibility. Tiered competitive positioning separates vertically integrated harvest-to-can operators from contract manufacturers serving private-label retail. Three archetypes dominate: Alaska-based wild-catch specialists controlling raw material quality from source, Asian contract manufacturers scaling retort capacity for European retail, and Japanese cold-chain experts extending premium freshness into ambient formats. Dominant competitive moves include backward integration into harvesting assets and technology licensing for barrier-coating laminates.
Within the vertically integrated tier, Trident Seafoods represents harvest-to-can control over Alaskan sourcing. Thai Union Group anchors volume leadership through Asian and European processing hubs serving private-label contracts. Maruha Nichiro occupies a position bridging Japanese cold-chain heritage with ambient format adaptation. These three exemplify how geographic specialization and format flexibility determine competitive positioning.
| Leading Market Players |
|---|
| Trident Seafoods |
| Thai Union Group |
| Starkist |
| Bumble Bee Foods |
| Maruha Nichiro |
| Wild Planet Foods |
| Crown Prince |
| John West |
| Dongwon Industries |
| Others |
Supply Flow & Price Mechanics
Norway's Bergen aquaculture processing corridor concentrates raw material conversion capacity, anchoring margin pools in private-label pouch contracts and smoked variant premium tiers where format flexibility commands price premiums over legacy tin-can output.
Pricing Analysis
Foodservice procurement directors anchor contract-based long-term offtake pricing through annual volume commitments for SKU customization. Price differentiation rests on Marine Stewardship Council certification tier and retort pouch format premium against standard chunk tin presentations. Pricing pressure stems from frozen fillet substitution in price-sensitive institutional accounts. Mass-market retailers exhibit highest price sensitivity; specialty grocers purchasing smoked variants show lowest.
Supply Chain Analysis
Bangkok-based co-manufacturers with retort expertise hold expanding contract-manufacturing capacity for European private-label contracts. Supply concentrates in Norway, Thailand, and Alaska, drawing from farmed Atlantic salmon, wild-catch Pacific harvests, and imported raw material lots. Steel tariff exposure on tin-plate inputs and single-source vulnerability to MSC-certified wild-catch quotas constitute structural risks. Distribution runs through direct-processor relationships that bypass traditional wholesale markups in British and Dutch foodservice channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is cycling through a retort-format substitution wave as meal-kit services and convenience retailers pull ambient salmon into home-delivery channels, justifying capacity reconfiguration investments.
For Market Incumbents: Build regulatory compliance moats through documented chain-of-custody systems satisfying tightening EFSA maximum residue limits under EC 1881/2006. Incumbents should deepen backward integration into Bergen aquaculture assets to secure feed-source traceability, while adding pouch-format capacity to defend against Thai and Vietnamese contract manufacturers capturing European retail contracts. For New Entrants and Emerging Players: Build out white-space presence in smoked variant premium tiers where flavor differentiation supports margin pools unavailable to standard chunk formats. The most penetrable segment sits with Nordic convenience retailers and German recipe-box assemblers prioritizing pouch-format convenience; entrants should pursue co-manufacturing partnerships with established retort operators rather than greenfield asset builds. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Asian contract manufacturers scaling retort capacity for European private-label retail. Long-term viability favors processors with dual metal-can and pouch flexibility across the analysis window. The signal to watch is MSC certification timeline compression, which would disqualify wild-catch dependent operators and concentrate value in farmed-source processors with preemptive feed-source traceability investments.| Strategic Initiative | Industry Significance |
|---|---|
| Retort Pouch Capacity Expansion | Captures European retailer demand for ambient-stable protein with fresh-food merchandising aesthetics. |
| Backward Integration into Aquaculture Assets | Secures feed-source traceability to preempt EFSA disqualification under tightening EC 1881/2006 limits. |
| Marine Stewardship Council Certification Investment | Unlocks premium channel access as sustainability quotas constrain wild-catch competitor availability. |
| Direct Foodservice Procurement Relationships | Eliminates distributor markups through annual volume commitments with British and Dutch institutional buyers. |
| Omega-3 Retention Process Development | Supports regulatory-compliant nutritional labeling claims above two grams per hundred-gram serving. |
Methodological Framework
Desk research of customs trade databases, FDA scheduled process filings, and Marine Stewardship Council chain-of-custody registries preceded structured interviews with salmon processing plant managers, European retail category buyers, foodservice procurement directors, and thermal process engineering consultants. Primary fieldwork combined with secondary validation from EFSA contaminant limit documentation and Norwegian aquaculture production statistics. Bottom-up volume modeling and top-down value triangulation anchored forecast outputs.
Assumptions held fixed include EFSA maximum residue limit enforcement intensity, retort pouch laminate cost trajectories, and meal-kit subscription growth rates across the projection horizon. Modeled segmentation dimensions spanned product format, packaging technology, distribution channel, and end-user application. CAGRs were derived from slope analysis of historical volume trends adjusted for technology substitution effects. Industry-specific forecast inputs incorporated MSC certification timeline projections and steel tariff exposure scenarios.
Stress conditions across wild-catch quota volatility, retort equipment lead times, and European retail private-label contract renewal rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of MSC certification backlog indicators and EFSA heavy metal testing protocol amendments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Fish Maw Market
Seafood
North America Tuna Market
Seafood
Asia Pacific Canned Seafood Market
Seafood
Fish Processing Market
Seafood
Frozen Seafood Market
Seafood
Asian Sea Bass Market
Seafood
Seafood Takeout Market
Seafood
Carp Market
Seafood
Crayfish Market
Seafood
Processed Seafood and Seafood Processing Equipment Market
Seafood
Dried Scallop Market
Seafood
Fish Hydrolysate Market
Seafood
China Crustaceans Market
Seafood
Canned Mackerel Market
Seafood
Canned Sardines Market
Seafood
Global Shrimp Market