
 US Legionella Testing Market | 2026-2036
US Legionella Testing Market Size, Share, and Industry Trends Forecast 2026-2036
US Legionella Testing Market Insights
A move from reactive single-source contracting to multi-source validation partnerships is shifting how institutional buyers structure their testing programs. QuidelOrtho Corporation leverages its molecular diagnostics platform to compete in PCR-based detection workflows. Bio-Rad Laboratories anchors its position through specialized reagent supply chains that sustain high-throughput laboratory throughput. Phigenics differentiates by occupying the facility management advisory niche, combining field sampling with compliance documentation services.
US Legionella testing encompasses analytical methods for detecting viable and non-viable Legionella pneumophila and related species in environmental and clinical matrices, with PCR protocols typically targeting the mip gene at sensitivity thresholds of one to ten genome equivalents per reaction. The primary purpose centers on outbreak investigation, proactive building water system surveillance, and regulatory compliance verification in high-occupancy facilities. Culture testing retains dominance in regulatory submission pathways where infectivity confirmation remains mandatory, while PCR testing captures the fastest expansion as turnaround-time pressures intensify in healthcare-associated infection control. Application demand stratifies sharply, with cooling towers and healthcare facilities representing the deepest margin pools due to litigation exposure and Joint Commission accreditation requirements.
FDA oversight shapes clinical diagnostic assay validation requirements, while EPA methods such as EPA 1605 establish culture-based benchmarks for environmental monitoring that constrain method substitution. ASHRAE Standard 188 and the CDC's Water Management Program toolkit create compliance-driven demand floors that municipal agencies and property management firms must satisfy through documented testing cadences. Stakeholders must monitor whether CMS conditions of participation for hospitals tighten to mandate specific test method categories, as this would restructure procurement specifications across the environmental testing lab vendor base.
Market Dynamics
ASHRAE Standard 188 compliance mandates and CDC Water Management Program requirements are restructuring procurement specifications across US healthcare facilities, cooling tower operators, and property management firms toward documented, recurring testing cadences rather than reactive outbreak response.
Growth Catalysts
- CDC Water Management Program toolkit:Federal guidance expansion drives mandatory surveillance protocols in hospitals and long-term care facilities, creating baseline demand for environmental testing services.
- Cooling tower density in Sun Belt states:Florida, Texas, and Arizona harbor elevated Legionella exposure risk from aging municipal infrastructure combined with high-temperature operating conditions.
- PCR-based detection workflows:Molecular diagnostics compress turnaround times from days to hours, satisfying Joint Commission accreditation pressures for rapid healthcare-associated infection control response.
Market Restraints
- Culture-based EPA Method 1605:Regulatory submission pathways mandate infectivity confirmation that PCR cannot satisfy, forcing laboratories to maintain dual-method capabilities and specialized biosafety infrastructure.
- Reagent supply concentration:Specialized PCR reagents for mip gene targeting flow through limited qualified suppliers, exposing testing programs to batch-to-batch variability and customs clearance friction.
- Technical limitation in viable-but-non-culturable detection:Standard culture methods miss dormant Legionella cells that resuscitate under favorable conditions, creating false-negative risk in proactive surveillance.
Strategic Opportunities
- Underpenetrated municipal building stock:K-12 schools, correctional facilities, and municipal office buildings lack mandated testing programs, representing white space for compliance-as-a-service offerings.
- CMS Conditions of Participation tightening:Prospective federal mandate expansion into specific test method categories would restructure procurement specifications across the environmental testing lab vendor base.
- IoT sensor convergence with molecular diagnostics:Continuous temperature and disinfectant monitoring integrated with automated sampling triggers creates subscription revenue models beyond transactional testing.
Industry Challenges
- Biosafety Level 2 containment shortage:Legionella culture work demands specialized facilities that smaller environmental laboratories cannot economically justify, concentrating service capacity in regional hubs.
- ASHRAE 188 documentation complexity:Water management plan validation requires interdisciplinary coordination between facilities engineers, infection control officers, and external testing vendors that stretches organizational bandwidth.
- PCR inhibition in environmental matrices:Cooling tower biocides and plumbing corrosion byproducts interfere with nucleic acid amplification, demanding costly sample preprocessing protocols that erode margin on rapid-turnaround contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Legionella Testing Market |
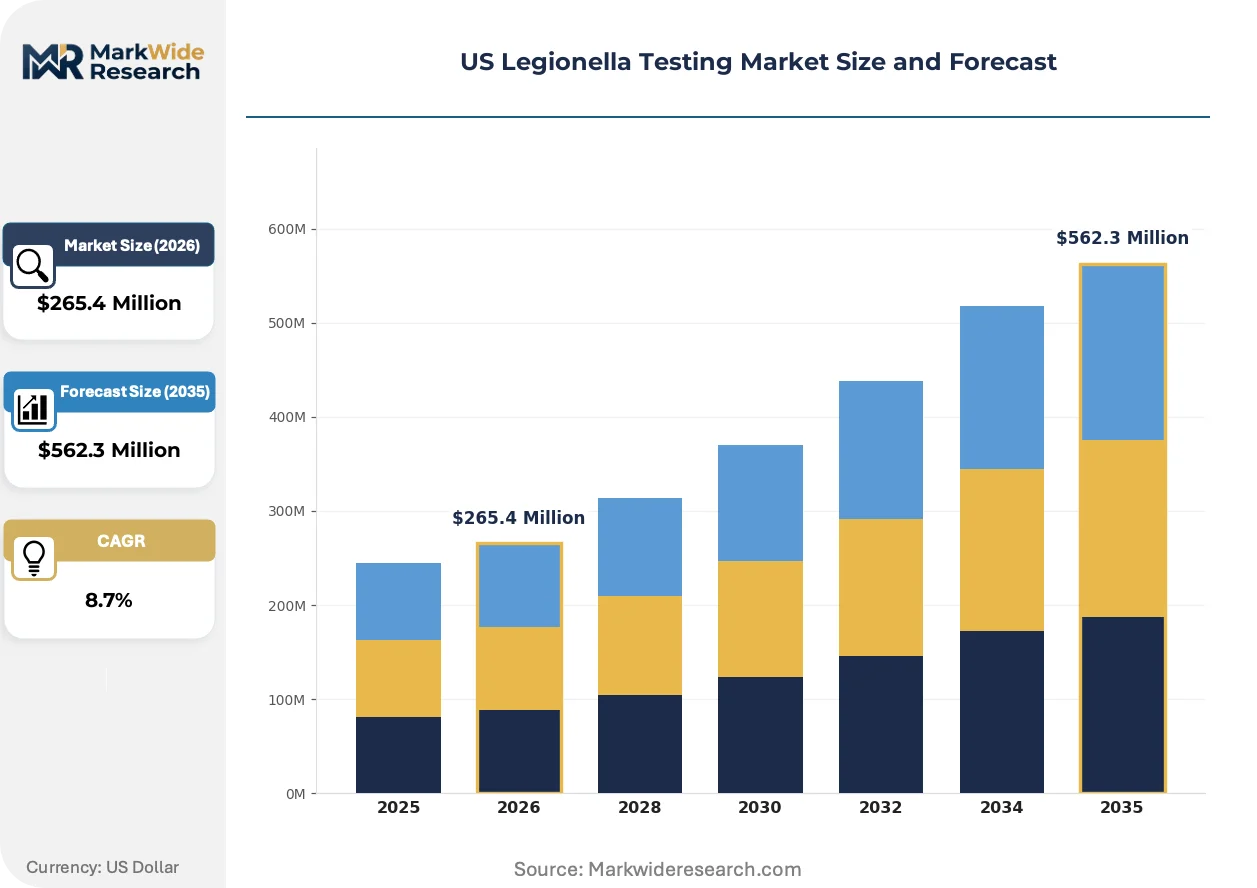
| Market Size in 2026 | $265.4 Million |
| Market Size in 2035 | $562.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Method: Culture Testing, PCR Testing, Immunofluorescence, Rapid Diagnostic Kits, Serological Tests Sample Type: Water, Air, Biofilm, Soil, Surface Swabs Application: Cooling Towers, Healthcare Facilities, Commercial Buildings, Hospitality Industry, Public Water Systems End User: Environmental Testing Labs, Municipal Agencies, Industrial Safety Departments, Healthcare Institutions, Property Management Firms |
| Companies Covered | QuidelOrtho Corporation, Abbott Laboratories, Bio-Rad Laboratories, IDEXX Corporation, Thermo Fisher Scientific, bioMérieux, Becton Dickinson and Company, Merck KGaA, Phigenics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Legionella Testing Market Trends and Innovations
Digital water management platforms are integrating field sampling logistics with real-time compliance dashboards, compressing the interval between detection and remediation response in high-occupancy facilities.
Digital PCR technology is electrifying quantitative Legionella enumeration by partitioning reactions into thousands of micro-reactions, eliminating standard curve dependency and improving reproducibility at low target concentrations. Reference laboratories in California and New York are adopting these platforms for litigation-support testing where measurement uncertainty carries financial exposure. The technology is electrifying competitive positioning among high-complexity laboratories by enabling ISO 17025-accredited quantification with defensible uncertainty budgets.
EPA Method 1605 harmonization with ISO 11731 culture standards is creating transatlantic method equivalence that simplifies multinational facility operator compliance documentation. The convergence reduces redundant sampling for US-based corporations operating European subsidiaries. Pharmaceutical manufacturing facilities with dual FDA-EMA oversight are driving adoption of harmonized protocols to streamline batch release water testing.
Subscription-based monitoring contracts are displacing transactional per-sample pricing in hospital systems seeking predictable operating expenditure structures. Large integrated delivery networks in Texas and Florida are consolidating vendor relationships under multi-year agreements bundling sampling, analysis, and regulatory filing services. The shift concentrates purchasing power among fewer buyers while raising switching costs for incumbent testing providers.
US Legionella Testing Market Segmentation
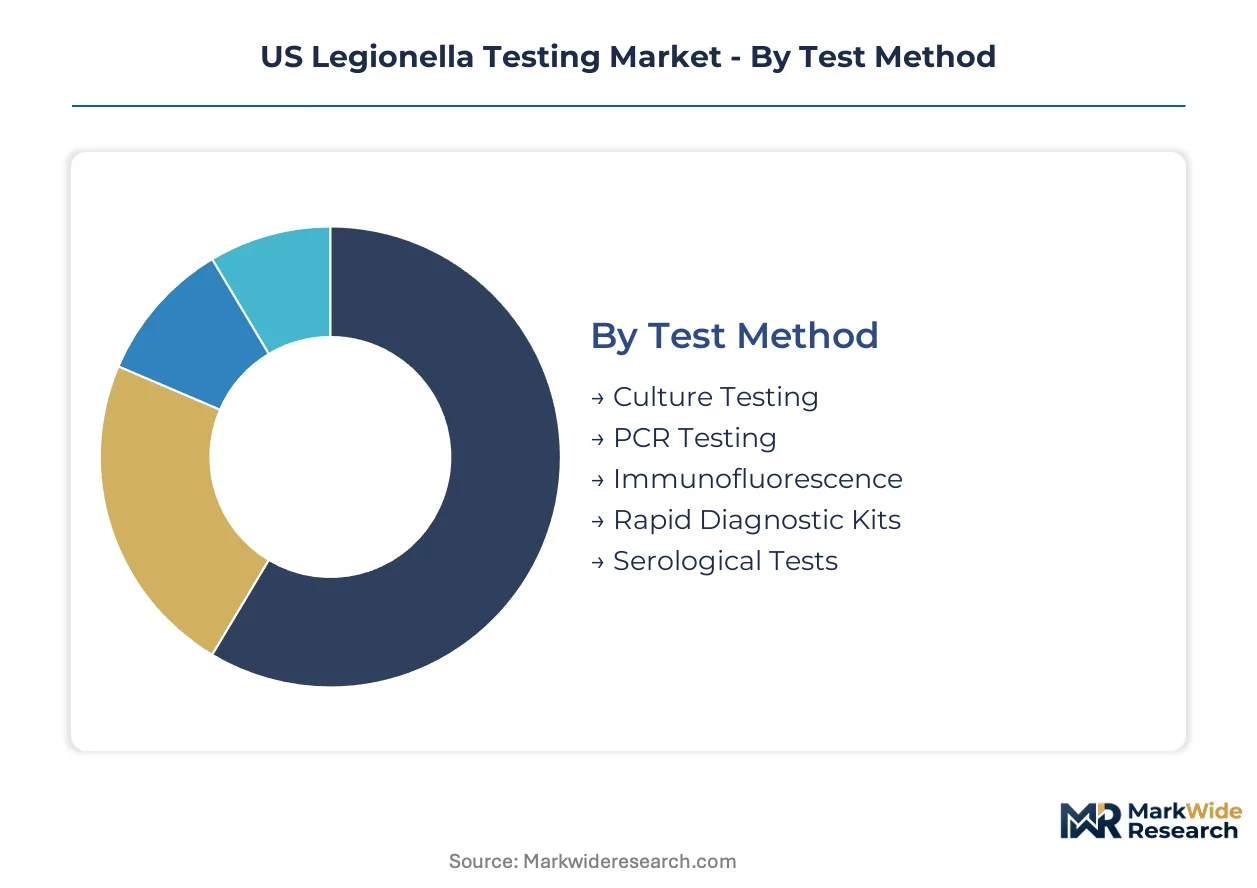
Testing program design in the US Legionella market hinges on matching analytical rigor to regulatory submission pathways. Procurement specifications diverge sharply across method categories, sample matrices, and end-user compliance obligations.
Test Method:
Standardization pressure from EPA Method 1605 contrasts with customization demand for rapid-turnaround PCR workflows in hospital infection control.
- Culture Testing:EPA Method 1605 mandates this approach for regulatory submissions requiring infectivity confirmation. Biosafety Level 2 infrastructure requirements concentrate service capacity in regional reference laboratories serving multiple states.
- PCR Testing:mip gene targeting delivers results within hours versus days, satisfying Joint Commission pressures for rapid healthcare-associated infection response. Sun Belt hospital systems in Florida and Texas are expanding molecular diagnostics contracts fastest.
- Immunofluorescence:Direct fluorescent antibody staining retains niche utility in reference laboratory confirmation workflows.
- Rapid Diagnostic Kits:Lateral flow formats serve preliminary field screening where immediate presence-absence determination guides emergency remediation.
- Serological Tests:Antibody detection supports retrospective outbreak investigation in clinical diagnostic settings.
Most installed capacity flows through Culture Testing. Expansion is steepest in PCR Testing.
Sample Type:
Collection logistics and matrix interference patterns create distinct margin profiles across environmental and clinical specimen categories.
- Water:Cooling tower bulk samples and potable water draws constitute the highest-volume testing category. Municipal building operators in aging Sun Belt infrastructure zones drive recurring surveillance demand.
- Biofilm:Plumbing system deposits harbor dormant Legionella populations that standard water sampling misses. Healthcare facilities pursuing proactive ASHRAE 188 compliance are expanding biofilm analysis contracts fastest.
- Air:Aerosol sampling supports outbreak investigation in HVAC-associated transmission events.
- Soil:Excavation and construction site monitoring addresses disturbed municipal infrastructure exposure risk.
- Surface Swabs:Faucet and showerhead sampling complements water testing in high-acuity patient care environments.
Water samples dominate transaction volume. Biofilm analysis is gaining share fastest among premium-priced surveillance contracts.
Application:
Litigation exposure and accreditation mandates stratify willingness-to-pay across facility categories.
- Healthcare Facilities:Joint Commission accreditation and CMS Conditions of Participation create non-negotiable testing cadences. Long-term care operators in Florida face combined state and federal compliance layering.
- Cooling Towers:High-density installations in Texas and Arizona generate recurring environmental monitoring demand tied to state registration programs and liability risk management.
- Commercial Buildings:Class A office properties in Sun Belt metros are adopting voluntary surveillance ahead of anticipated municipal mandate expansion.
- Hospitality Industry:Resort and hotel operators in Florida address guest exposure liability through documented water management plans.
- Public Water Systems:Municipal distribution system monitoring concentrates in aging infrastructure districts with documented Legionella colonization history.
Healthcare Facilities anchor current revenue concentration. Cooling Towers are expanding most quickly as state registration programs proliferate.
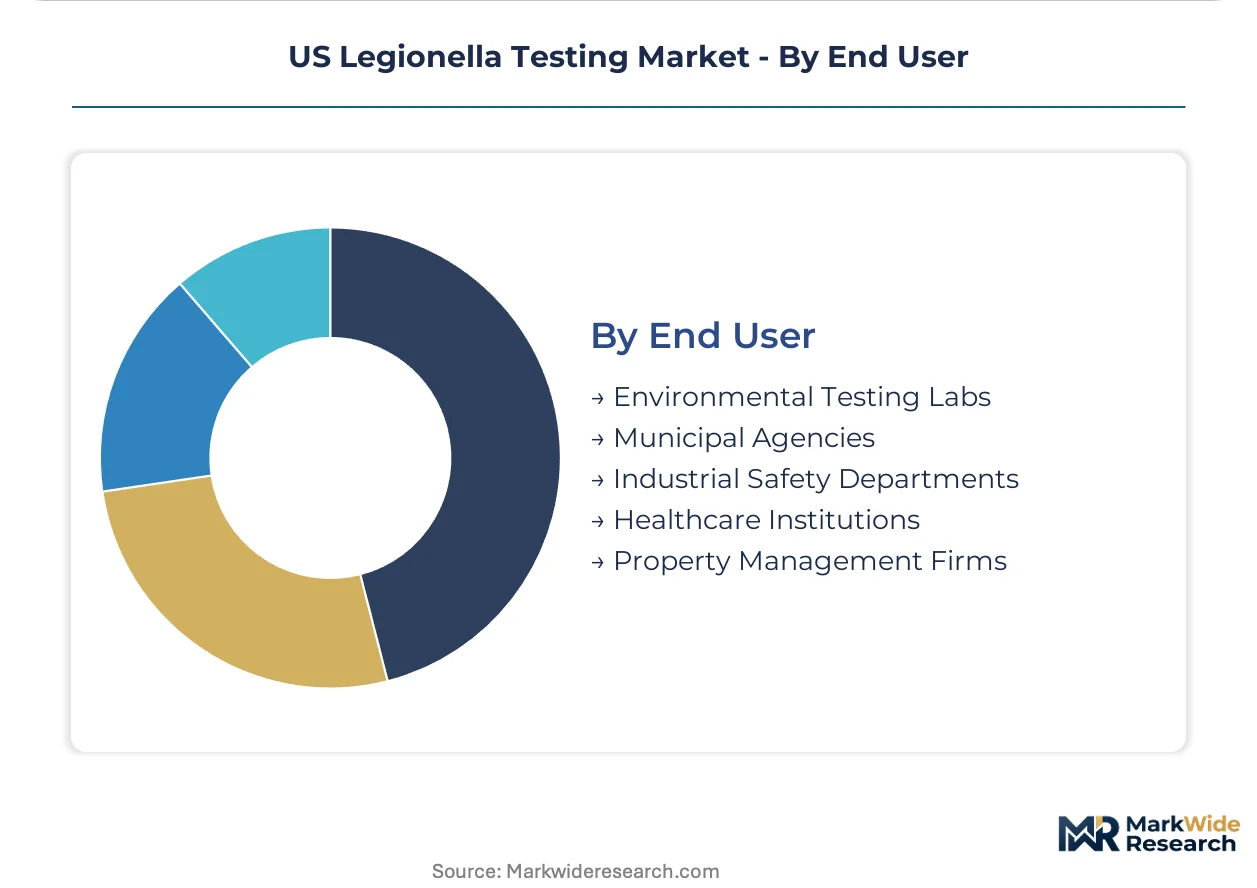
End User:
Technical capability and compliance documentation requirements segment the customer base into outsourced versus in-house testing strategies.
- Environmental Testing Labs:High-complexity reference laboratories in California and New York capture litigation-support and pharmaceutical manufacturing validation work requiring ISO 17025 accreditation.
- Healthcare Institutions:Large integrated delivery networks in Texas are consolidating vendor relationships under multi-year subscription contracts bundling sampling, analysis, and regulatory filing.
- Municipal Agencies:Building code enforcement and public health departments specify testing protocols without direct laboratory operation.
- Industrial Safety Departments:Petrochemical and power generation facilities maintain in-house sampling capacity with external laboratory partnerships for confirmatory analysis.
- Property Management Firms:Multi-site operators seek compliance-as-a-service offerings covering ASHRAE 188 documentation and testing cadence management.
Environmental Testing Labs process the highest sample volumes. Healthcare Institutions are driving procurement consolidation fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Sun Belt corridor dominates US Legionella testing demand, with Florida, Texas, and Arizona harboring the nation's densest concentrations of cooling towers and aging water infrastructure.
Florida
Resort hospitality chains and long-term care facilities drive recurring surveillance contracts across the Orlando and Miami metropolitan zones. The Florida Department of Health mandates cooling tower registration and routine monitoring for properties exceeding specific occupancy thresholds. Tampa Bay healthcare systems are consolidating vendor relationships under multi-year agreements bundling sampling, PCR analysis, and ASHRAE 188 documentation services.
Texas
Petrochemical complexes and power generation facilities in the Houston-Gulf Coast corridor maintain intensive cooling tower monitoring programs tied to state environmental permits. The Texas Commission on Environmental Quality enforces discharge monitoring requirements that intersect with Legionella surveillance protocols. Dallas-Fort Worth hospital systems are expanding molecular diagnostics contracts fastest, driven by Joint Commission accreditation pressures and litigation risk management.
Arizona
Desert climate conditions accelerate cooling tower biofilm formation, elevating baseline exposure risk in Phoenix and Tucson commercial building stock. The Arizona Department of Environmental Quality coordinates with county health departments on outbreak investigation protocols. Scottsdale and Paradise Valley resort properties are adopting voluntary surveillance programs ahead of anticipated municipal mandate expansion.
New York
Post-2015 cooling tower regulations following the South Bronx outbreak maintain stringent testing cadences across New York City metropolitan facilities. The New York State Department of Health enforces quarterly monitoring requirements for all registered cooling towers. Manhattan and Brooklyn healthcare institutions anchor litigation-support testing demand, with reference laboratories capturing high-complexity ISO 17025-accredited quantification work.
California
Pharmaceutical manufacturing facilities with dual FDA-EMA oversight drive harmonized protocol adoption for batch release water testing in the San Francisco Bay Area. The California Department of Public Health coordinates environmental monitoring with local water districts managing aging distribution infrastructure. San Diego and Los Angeles hospital systems are piloting IoT-integrated monitoring platforms that combine continuous sensor data with automated sampling triggers.
US Legionella Testing Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital water management advisory services and IoT-integrated monitoring platforms. The vendor base stratifies across three capability clusters: molecular diagnostics platforms, specialized reagent supply chains, and facility management compliance services. Strategic differentiation concentrates on turnaround-time compression, biosafety infrastructure scale, and documentation automation. Consolidation pressures favor multi-year subscription contracts over transactional per-sample pricing.
Among diagnostics-focused corporations, QuidelOrtho Corporation and Abbott Laboratories exemplify the molecular platform archetype, leveraging PCR-based detection workflows to serve hospital infection control demands. Bio-Rad Laboratories occupies a specialized position in reagent supply chains that sustain high-throughput laboratory throughput. Phigenics represents the facility management advisory tier, combining field sampling with compliance documentation services for property management firms navigating ASHRAE 188 complexity.
| Leading Market Players |
|---|
| QuidelOrtho Corporation |
| Abbott Laboratories |
| Bio-Rad Laboratories |
| IDEXX Corporation |
| Thermo Fisher Scientific |
| bioMérieux |
| Becton Dickinson and Company |
| Merck KGaA |
| Phigenics |
| Others |
Pricing and Supply Chain Analysis
Specialized PCR reagent costs flow from limited qualified suppliers through to testing laboratories, compressing margins on rapid-turnaround contracts while subscription-based hospital agreements stabilize revenue predictability for multi-service vendors.
Pricing Analysis
Input-cost pass-through from biosafety infrastructure and reagent supply concentration shapes tiered pricing separating ISO 17025-accredited reference laboratories from regional environmental testing providers. Certification level and turnaround-time urgency drive price differentiation, with litigation-support quantification commanding premiums over routine surveillance. Pricing pressure stems from hospital procurement consolidation under multi-year subscription contracts. Municipal agencies and smaller property management firms exhibit highest price sensitivity, while healthcare institutions facing Joint Commission accreditation deadlines show lowest elasticity.
Supply Chain Analysis
Reverse-logistics flows for temperature-controlled specimen transport and culture plate incubation cycles create specialized cold-chain dependencies that concentrate service capacity in regional hub laboratories. Reagent manufacturing concentrates in the United States, Germany, and Japan, with specialized mip gene primers and culture media drawing from pharmaceutical-grade chemical feedstocks. Single-source vulnerability in qualified PCR reagent suppliers exposes testing programs to batch-to-batch variability. Distribution runs through direct laboratory partnerships and group purchasing organizations serving integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Legionella testing market functions as a regulatory compounder where ASHRAE Standard 188 compliance mandates create recurring revenue floors that deepen with each CDC guidance expansion.
For Market Incumbents: Hedge against PCR commoditization by embedding IoT sensor platforms into subscription contracts that automate sampling triggers and compress detection-to-remediation intervals. Fortify biosafety infrastructure scale in Sun Belt regional hubs to capture cooling tower registration program volumes as state mandates proliferate. Defensive patent positioning around digital PCR quantification methods protects litigation-support pricing tiers. For New Entrants and Emerging Players: Begin with compliance-as-a-service offerings targeting underpenetrated municipal building stock in K-12 schools and correctional facilities where documented water management plans remain voluntary. Arizona and Florida resort properties adopting surveillance ahead of mandate expansion represent the most penetrable white space. A field-sampling-plus-documentation bundling angle bypasses capital-intensive laboratory infrastructure requirements. For Investors and Strategic Acquirers: Consolidation pressure builds where subscription contract concentration among large integrated delivery networks raises switching costs and squeezes regional environmental laboratory margins. Long-term viability favors platform players combining molecular diagnostics with digital water management advisory services. The signal to watch is CMS Conditions of Participation tightening that would mandate specific test method categories and restructure procurement specifications across the vendor base.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Sensor Platform Integration | Continuous temperature monitoring from Phigenics triggers automated sampling that locks hospitals into multi-year subscription contracts. |
| ISO 17025 Accreditation Investment | Defensible measurement uncertainty budgets from Bio-Rad Laboratories enable litigation-support pricing tiers in California and New York. |
| Digital PCR Technology Adoption | Partitioned reaction quantification from Thermo Fisher Scientific eliminates standard curve dependency for pharmaceutical batch release testing. |
| ASHRAE 188 Documentation Automation | Compliance dashboard integration reduces facilities engineer coordination burden that stretches organizational bandwidth in hospital systems. |
| Multi-Year Subscription Contracting | Predictable operating expenditure structures from QuidelOrtho Corporation displace transactional per-sample pricing in Texas and Florida. |
Research Methodology
Direct dialogue with laboratory directors, infection control officers, facilities engineers, and group purchasing organization contract managers grounded qualitative findings, validated against EPA method documentation, CDC surveillance data, ASHRAE technical standards, and state cooling tower registration databases. Bottom-up and top-down triangulation cross-checked sample volume estimates against laboratory capacity disclosures and procurement contract values.
Bottom-up modeling segmented the market by test method, sample matrix, application, and end-user technical capability across the projection horizon. CAGR derivation incorporated regulatory mandate adoption curves, cooling tower density by climate zone, and hospital accreditation pressure indices. Industry-specific inputs included Joint Commission citation frequency data and state environmental permit enforcement patterns.
Several conditions sit outside the modeled scope, including hypothetical CMS mandate expansion timing, novel biocide formulations that alter PCR inhibition profiles, and viable-but-non-culturable detection technology breakthroughs. Forecasts reflect assumptions about regulatory enforcement continuity and reagent supply chain stability. Practitioners should monitor CDC guidance revision cycles and state cooling tower registration program expansions for early demand inflection signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Meat Speciation Testing Service Market
Food Safety Testing
Food and Beverages Disinfection Market
Food Safety Testing
UAE Product Testing Lab Services Market
Food Safety Testing
Food and Beverage Protective Cultures Market
Food Safety Testing
Global Bacteriological Testing Market
Food Safety Testing
Genetically Modified Food Safety Testing Market
Food Safety Testing
Amylase Testing Market
Food Safety Testing
Xylose Absorption Tests Market
Food Safety Testing
Salt Meter Market
Food Safety Testing
Salmonella Testing Market
Food Safety Testing
Inline Beverage Gas and Microbial Load Monitoring Test Systems Market
Food Safety Testing
Food Testing, Inspection, and Certification Market
Food Safety Testing
Chromatography Food Testing Market
Food Safety Testing
Food Allergen Testing Market
Food Safety Testing
Water Activity Meter Market
Food Safety Testing
Global Inline Metal Detector Market