
 Global Seafood Market | 2026-2036
Global Seafood Market Size, Share, and Industry Trends Forecast 2026-2036
Global Seafood Market Outlook
EU IUU Regulation enforcement is shifting the cost-of-entry calculus for exporters lacking traceability infrastructure. Mowi ASA leverages its integrated salmon farming operations to sustain full-chain documentation. Thai Union Group anchors its competitive stance through vertically controlled tuna supply networks. Trident Seafoods Corporation dominates Alaskan pollock harvesting with shore-based processing control.
Seafood encompasses finfish, crustaceans, mollusks, and other aquatic organisms harvested from marine or freshwater environments, typically preserved through freezing, canning, drying, or chilled distribution to retain nutritional protein content and extend shelf stability for commercial trade. The primary commercial purpose centers on supplying protein-rich food products to households, foodservice operators, and retail channels across diverse geographies. Frozen processing occupies the largest volume position due to its suitability for long-distance trade, while fresh distribution commands premium pricing in urban markets with developed cold-chain logistics. Online retail represents the fastest-expanding channel as direct-to-consumer platforms reduce intermediary layers.
FDA seafood HACCP requirements in the United States, EU hygiene regulations enforced by EFSA, and China's GB standards administered by SAMR collectively elevate safety compliance as a non-negotiable market access condition. These frameworks intensify testing and traceability investments across export-oriented supply chains. Stakeholders must monitor regulatory divergence between major import jurisdictions to anticipate certification burdens and reposition sourcing strategies accordingly.
Market Dynamics
EU IUU Regulation enforcement is forcing distant-water fleets to rebuild documentation infrastructure or exit European import channels entirely. Traceability investments now separate compliant exporters from stranded inventory.
Growth Catalysts
- China's cold-chain buildout:Live-seafood retail in coastal provinces now reaches inland cities previously limited to frozen product, unlocking premium crustacean demand.
- EU catch documentation mandate:The IUU Regulation's phased enforcement creates first-mover advantage for fleets with blockchain-anchored traceability systems.
- Recirculating aquaculture systems:Land-based RAS technology is electrifying salmon production in jurisdictions with limited marine lease availability.
Market Restraints
- Fuel cost volatility:Diesel price swings directly compress margins for wild-catch operators running long-haul distant-water fleets.
- Processing concentration in Thailand:Tuna cannery capacity clustering creates single-point vulnerability for brands dependent on Southeast Asian supply.
- Substitute protein competition:Plant-based seafood analogs from Impossible Foods and others capture trial purchases in North American foodservice.
Strategic Opportunities
- Direct-to-consumer platforms:Online retail channels bypass wholesale layers, enabling aquaculture producers to capture margin previously lost to distributors.
- Vietnamese pangasius expansion:Underpenetrated EU retail frozen whitefish segments offer volume growth as Vietnamese exporters invest in ASC certification.
- US offshore aquaculture permitting:NOAA's advancing aquaculture opportunity areas in Gulf of Mexico waters could unlock domestic finfish production.
Industry Challenges
- HACCP implementation timeline:FDA seafood safety compliance requires 12-18 month facility certification cycles that delay market entry for new processors.
- Veterinary drug residue testing:Export certification demands multi-laboratory confirmation workflows that strain quality control staffing in developing-country hatcheries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Seafood Market |
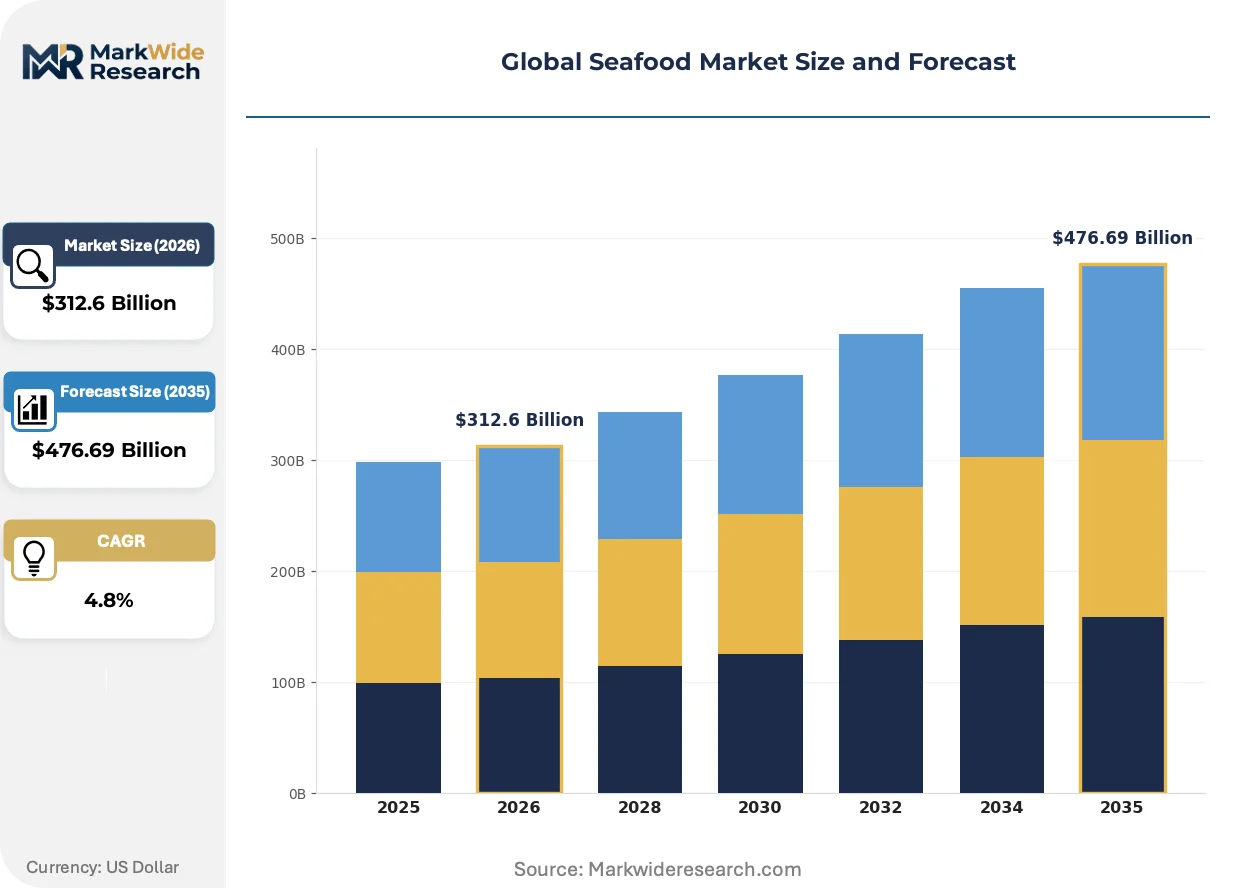
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $476.69 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish, Crustaceans, Mollusks, Other Aquatic Products Processing Method: Frozen, Canned, Dried, Fresh Distribution Channel: Supermarkets, Restaurants, Online Retail, Fish Markets End User: Households, Foodservice Industry, Retailers, Exporters |
| Companies Covered | Nippon Suisan Kaisha, Charoen Pokphand Foods, Mowi ASA, Austevoll Seafood ASA, Leroy Seafood Group, Maruha Nichiro Corporation, Trident Seafoods Corporation, Cooke Inc., Thai Union Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Seafood Market Strategic Shifts
Digital traceability and alternative proteins are compressing traditional supply chain architectures while regenerative aquaculture practices reshape production geography.
Blockchain-enabled catch documentation is electrifying supply chain transparency from vessel to retail shelf. Norwegian salmon exporters now deploy interoperable traceability platforms satisfying both EU IUU requirements and downstream retailer audit demands. This technology compression is collapsing documentation costs for integrated producers while marginalizing fragmented wild-catch operators lacking capital for system investment.
EFSA hygiene regulations are tightening cold-chain validation standards for imported chilled seafood. European border inspection posts now reject shipments lacking continuous temperature logging, forcing Asian exporters to retrofit container fleets with IoT monitoring. Small-scale Indonesian tuna suppliers face particular displacement as compliance costs exceed their per-shipment margins.
Foodservice procurement is consolidating around certified sustainable sourcing mandates. Major North American restaurant chains now require Marine Stewardship Council or Aquaculture Stewardship Council labeling for menu-listed seafood, displacing uncertified alternatives from approved vendor lists. This preference compression is most visible in California and Pacific Northwest markets where consumer awareness of fishery sustainability ranks highest.
Global Seafood Market Segmentation
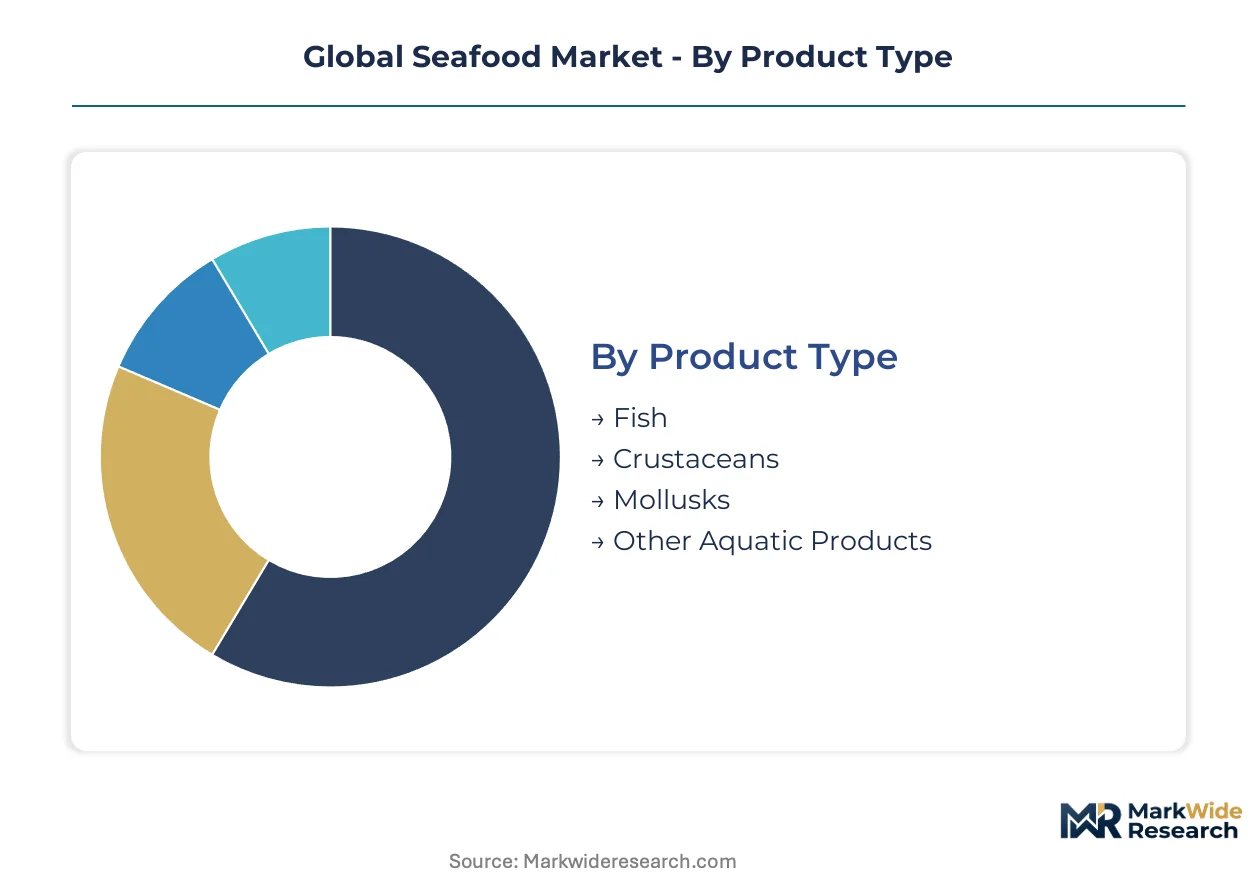
Seafood market segmentation reveals how processing technology and channel control determine margin capture. Producers with integrated cold-chain infrastructure command premium positioning across multiple categories simultaneously.
Product Type:
Fish dominates standalone commodity trade, while crustaceans and mollusks increasingly embed into controlled supply networks with direct retail partnerships.
- Fish:Finfish species including salmon, tuna, cod, and pollock constitute the volume foundation of commercial seafood trade. Norwegian and Chilean salmon farms supply EU and US retail through frozen fillet and fresh chilled channels. Wild-catch tuna fleets from the Western Pacific feed Thailand's cannery concentration.
- Crustaceans:Shrimp, crab, and lobster command price multiples over finfish due to live-holding logistics complexity. China's coastal cold-chain buildout now extends live-lobster distribution from Dalian and Qingdao ports to inland tier-2 cities previously limited to frozen alternatives.
- Mollusks:Oysters, mussels, and scallops filter-feed in coastal aquaculture zones with lower input costs than finfish farming. French and Irish producers dominate EU mussel supply through suspended rope culture in Brittany and Galway Bay.
- Other Aquatic Products:Seaweed, sea cucumber, and jellyfish serve regional specialty markets with limited cross-border standardization. South Korean and Japanese processors extract alginate and carrageenan for food additive applications.
Fish leads volumes today; crustaceans are gaining share fastest.
Processing Method:
Cost tier separation runs from premium fresh-chilled through economy canned products, with frozen occupying the intermediate value band.
- Frozen:Blast-freezing at sea or shore plants locks protein quality for intercontinental shipment. Alaskan pollock and Russian cod fleets dominate frozen whitefish blocks supplying EU and Asian reprocessing industries. This method sustains the longest supply chains with acceptable sensory degradation.
- Fresh:Chilled distribution from harvest to retail within 72 hours preserves texture and flavor for premium positioning. Live tanks in Shanghai and Singapore seafood markets command 40-60% price premiums over frozen equivalents for identical species.
- Canned:Thermal processing in Thailand, Ecuador, and Spain extends shelf stability for pantry-stocking consumers. Skipjack and yellowfin tuna dominate cannery intake, with Thai Union and Bumble Bee controlling brand shelf space in North American grocery.
- Dried:Traditional dehydration for cod, squid, and shrimp serves East Asian culinary traditions with minimal infrastructure requirements. Norwegian stockfish air-drying and Chinese squid jerky production represent distinct regional specialization.
Frozen processing anchors volume; fresh distribution shows the steepest expansion trajectory.
Distribution Channel:
Customer type stratification separates institutional procurement from household purchasing, with online platforms collapsing traditional wholesale layers.
- Supermarkets:Multinational retail chains consolidate seafood sourcing through approved vendor lists with MSC or ASC certification mandates. Carrefour and Tesco frozen seafood cases in France and Britain now exclude uncertified wild-catch alternatives.
- Restaurants:Foodservice operators in Southeast Asia expand premium crustacean menus as Chinese tourist flows recover. Singapore's seafood restaurant sector sources live crab and lobster through dedicated importers with tank-holding facilities at Jurong Port.
- Online Retail:Direct-to-consumer platforms enable aquaculture producers to bypass distributor margins and capture end-user data. Vietnamese pangasius farms now ship frozen fillets direct to EU households through Amazon and specialized seafood portals.
- Fish Markets:Traditional wet markets persist in developing Asia as price-discovery mechanisms and social shopping venues. Jakarta's Muara Angke and Mumbai's Sassoon Docks maintain wholesale auction functions alongside retail counters.
Supermarkets retain volume leadership; online retail climbs the fastest.
End User:
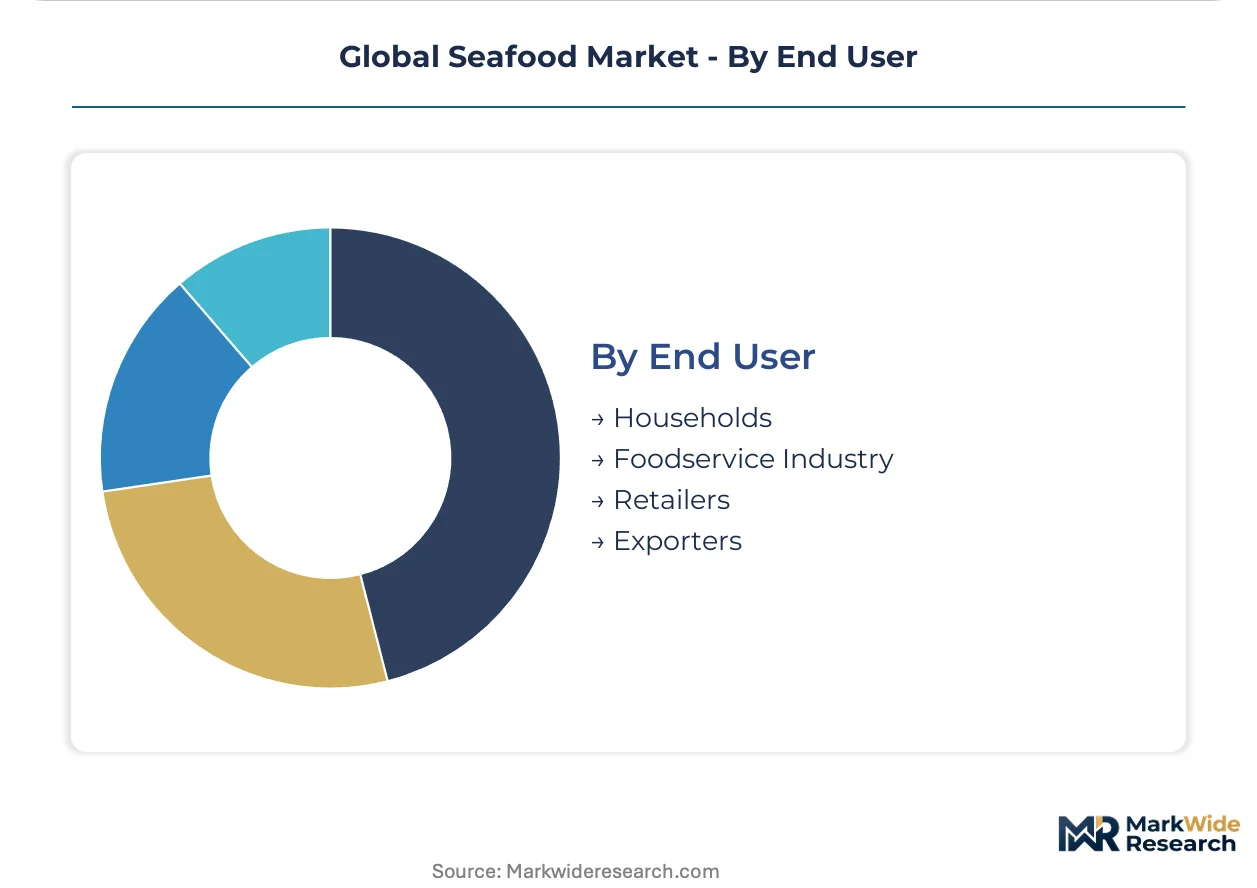
Application concentration varies from commodity protein sourcing to experience-driven consumption, with exporters facing the most stringent documentation burdens.
- Households:Retail purchasing decisions increasingly weight sustainability certification and origin labeling. German and Dutch consumers show willingness-to-pay premiums for pole-and-line caught tuna over purse-seine alternatives.
- Foodservice Industry:Restaurant and catering procurement prioritizes portion consistency and supply reliability over species provenance. North American chain operators specify individually quick-frozen shrimp counts rather than catch method.
- Retailers:Supermarket and hypermarket buyers negotiate annual contracts with volume commitments and quality penalties. French retail consolidation around Carrefour, E.Leclerc, and Intermarché concentrates supplier bargaining power.
- Exporters:Re-export traders face compound compliance requirements from origin country, transit port, and destination jurisdiction. Nigerian and Ghanaian re-processors of EU-imported frozen fish must satisfy both EFSA hygiene rules and domestic standards.
Household consumption leads volumes today; foodservice demand is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial seafood production first industrialized in Norway's fjords during the 1970s salmon farming boom, then replicated across Chilean Patagonia and Southeast Asian processing zones. Contemporary trade flows reflect this heritage, with four nations commanding disproportionate influence over volume, value, and regulatory standard-setting.
China
Coastal provinces from Shandong to Guangdong host the world's largest aquaculture output, with live-seafood retail now penetrating inland tier-2 cities via cold-chain investments. SAMR enforces GB standards for veterinary drug residues that exceed EU detection thresholds in several categories. Qingdao and Dalian ports function as consolidation nodes for Russian and North Korean catch re-export.
Norway
Atlantic salmon farming generates the highest per-kilogram export value of any seafood origin, with Bergen and Trondheim anchoring genetics and feed technology clusters. The Norwegian Food Safety Authority coordinates with EFSA on hygiene rule equivalency, preempting border inspection friction. Fjord-based producers now deploy blockchain traceability satisfying EU IUU documentation mandates.
Thailand
Samut Sakhon province concentrates global tuna canning capacity, processing skipjack and yellowfin from Western Pacific distant-water fleets. FDA HACCP compliance requirements for US-bound product have driven consolidation among smaller processors since 2022. Bangkok-based traders face rising documentation costs under EU IUU phased enforcement.
United States
Alaskan pollock harvesting dominates whitefish block production for global reprocessing industries, with shore-based plants in Dutch Harbor and Kodiak controlling primary processing. NOAA's advancing aquaculture opportunity areas in Gulf of Mexico waters could unlock domestic finfish farming permits. Seattle anchors North American seafood trading and logistics headquarters functions.
Vietnam
Mekong Delta pangasius farming supplies frozen whitefish fillets to EU retail through ASC-certified operations expanding into underpenetrated market segments. The country's national food safety regulator enforces export certification protocols aligned with EFSA hygiene standards. Can Tho and An Giang provinces concentrate hatchery and processing infrastructure.
Global Seafood Market Competitive Environment
The competitive structure tilts toward vertically integrated aquaculture operators with captive feed supply and distribution control. Wild-catch processors and distant-water fleet operators occupy a subordinate tier, squeezed between fuel cost volatility and documentation compliance burdens. Two strategic archetypes dominate: integrated salmon farmers with full-chain traceability, and diversified seafood conglomerates with multi-species processing networks. Competitive moves concentrate on M&A for cold-chain assets and strategic partnerships with retail chains for certified sustainable sourcing.
Among Norwegian integrated producers, Mowi ASA exemplifies the salmon-farming archetype with controlled genetics, feed, and distribution. Thai Union Group anchors the diversified conglomerate model with multi-species processing across tuna, shrimp, and value-added categories. Trident Seafoods Corporation represents the wild-catch processor segment with Alaskan pollock harvesting and shore-based processing concentration.
| Leading Market Players |
|---|
| Nippon Suisan Kaisha |
| Charoen Pokphand Foods |
| Mowi ASA |
| Austevoll Seafood ASA |
| Leroy Seafood Group |
| Maruha Nichiro Corporation |
| Trident Seafoods Corporation |
| Cooke Inc. |
| Thai Union Group |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap Norwegian salmon farmers anchor supply discipline through generational ownership horizons that resist short-term price-cutting, while their integrated feed-to-retail control sustains premium positioning against distant-water fleet competitors facing fuel volatility and documentation compliance costs.
Pricing Analysis
Contract-based long-term offtake with annual volume commitments dominates procurement between integrated aquaculture operators and European retail chains. Price differentiation separates ASC-certified premium fillets from standard frozen blocks and economy-grade canned tuna. Cost compression in the distant-water wild-catch tier is intensifying because diesel price swings and EU IUU documentation burdens strain operator margins. Foodservice buyers in North America show highest price sensitivity, while live-seafood retailers in China's coastal provinces absorb premium multiples for supply reliability.
Supply Chain Analysis
Dual-sourcing requirements now mandate that major EU retailers qualify minimum two ASC-certified pangasius suppliers alongside incumbent whitefish providers, fragmenting procurement concentration. Geographic supply concentrates in Norway, Chile, and Vietnam for farmed species, with Thailand and China dominating processing stages. Raw material flows draw from Peruvian fishmeal, Brazilian soy protein concentrate, and marine omega-3 oil inputs. Single-source vulnerability clusters in Thai tuna cannery capacity. Distribution runs through Rotterdam and Hamburg cold-chain hubs for European retail, with Shanghai and Singapore anchoring Asia-Pacific live-seafood logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in premium-tier certified aquaculture as cold-chain infrastructure cost curves flatten and retail sustainability mandates displace uncertified alternatives from approved vendor lists.
For Market Incumbents: Cement supply security through backward integration into genetics and feed manufacturing, locking out distant-water fleet competitors facing EU IUU documentation barriers. Expand ASC-certified pangasius capacity in Vietnam's Mekong Delta to capture underpenetrated EU frozen whitefish segments before Thai Union consolidates processing control. For New Entrants and Emerging Players: Begin with direct-to-consumer online platforms targeting German and Dutch households willing to pay traceability premiums for pole-and-line caught tuna. Partner with Vietnamese pangasius farms holding existing ASC certification rather than building processing greenfield, accelerating time-to-revenue while avoiding FDA HACCP facility certification delays. For Investors and Strategic Acquirers: Valuations sit cheapest among distant-water fleet operators stranded by EU IUU enforcement, presenting distressed acquisition opportunities for private equity with capital to deploy blockchain traceability infrastructure. Watch EU border inspection post rejection rates for Asian chilled seafood shipments as the inflection indicator for compliance-cost driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Deployment | Norwegian salmon exporters now satisfy EU IUU mandates and retailer audit demands simultaneously through interoperable platforms. |
| Land-Based RAS Capacity Buildout | Electrified salmon production in jurisdictions with limited marine lease availability reduces biological risk exposure. |
| Direct-to-Consumer Channel Launch | Vietnamese pangasius farms bypass distributor margins and capture end-user data through Amazon and specialized seafood portals. |
| ASC Certification Investment | EU retail frozen seafood cases at Carrefour and Tesco now exclude uncertified wild-catch alternatives from approved vendor lists. |
| Cold-Chain Infrastructure Partnership | Live-lobster distribution from Dalian and Qingdao ports now reaches inland tier-2 cities previously limited to frozen product. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with salmon farm operations directors, EU retail category buyers, Thai cannery quality managers, and Vietnamese pangasius export certification officers with secondary validation against customs trade data, EFSA border inspection post reports, FDA seafood HACCP facility listings, and ASC certification databases. Bottom-up volume modeling from species-level production data triangulated against top-down trade flow analysis.
Comparable historical periods anchored the projection horizon to capture cyclical patterns in fuel cost volatility and regulatory enforcement phases. Segmentation dimensions modeled include product type, processing method, distribution channel, and end-user application across farmed versus wild-catch sourcing origins. CAGRs derived from trend extrapolation adjusted for cold-chain infrastructure deployment timelines and EU IUU phased enforcement milestones. Industry-specific inputs incorporated fishmeal price indices and diesel futures curves.
Caveats apply where fuel cost spikes, EU IUU documentation rejection rate escalations, or plant-based seafood analog adoption acceleration could materially shift the outlook. Deviation in Chinese cold-chain investment pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Middle East and Africa Canned Seafood Market
Seafood
Canned Sardines Market
Seafood
Tinned Fish Market
Seafood
Fish Protein Hydrolysate Market
Seafood
Middle East Seafood Market
Seafood
Seafood Powders Market
Seafood
South America Canned Seafood Market
Seafood
North America Salmon Market
Seafood
Herring Market
Seafood
Mussels Market
Seafood
United Arab Emirates Seafood Market
Seafood
Milkfish Market
Seafood
Smoked Whiting Market
Seafood
Global Shrimp Market
Seafood
Canned Salmon Market
Seafood
Processed Seafood Market