
 Toothfish Market | 2026-2036
Toothfish Market Size, Share, and Industry Trends Forecast 2026-2036
Toothfish Market Insights
Antarctic longline fleets is repositioning harvest quotas toward higher-value fillet grades. Austral Fisheries leverages chain-of-custody certification to command premium positioning in Asian wholesale channels. Talley's Group anchors New Zealand supply through vertically integrated processing at its Nelson facility. Newsan competes via direct Argentine landings into Barcelona and Madrid food-service markets.
Toothfish comprise large-bodied, slow-growing Nototheniidae species harvested primarily from sub-Antarctic and Antarctic waters, with flesh prized for high fat content, firm texture, and mild flavor profile suited to premium culinary applications. Chilean Sea Bass dominates landed value across the product type split, while vacuum-sealed packaging captures the margin pool by extending shelf life for air-freight distribution to distant importers. The online distribution channel represents the fastest-growing access route, though direct sales still control volume flows between licensed operators and established exporters.
CCAMLR catch documentation schemes and the Marine Stewardship Council certification framework shape market access for toothfish, with non-compliant product barred from major importing jurisdictions. The U.S. FDA seafood hazard controls and EU IUU regulation enforcement both require verifiable vessel-level traceability for legal entry. Stakeholders must monitor quota allocation battles among Convention members and the pace of Marine Protected Area expansions that could displace historic fishing grounds.
Market Dynamics
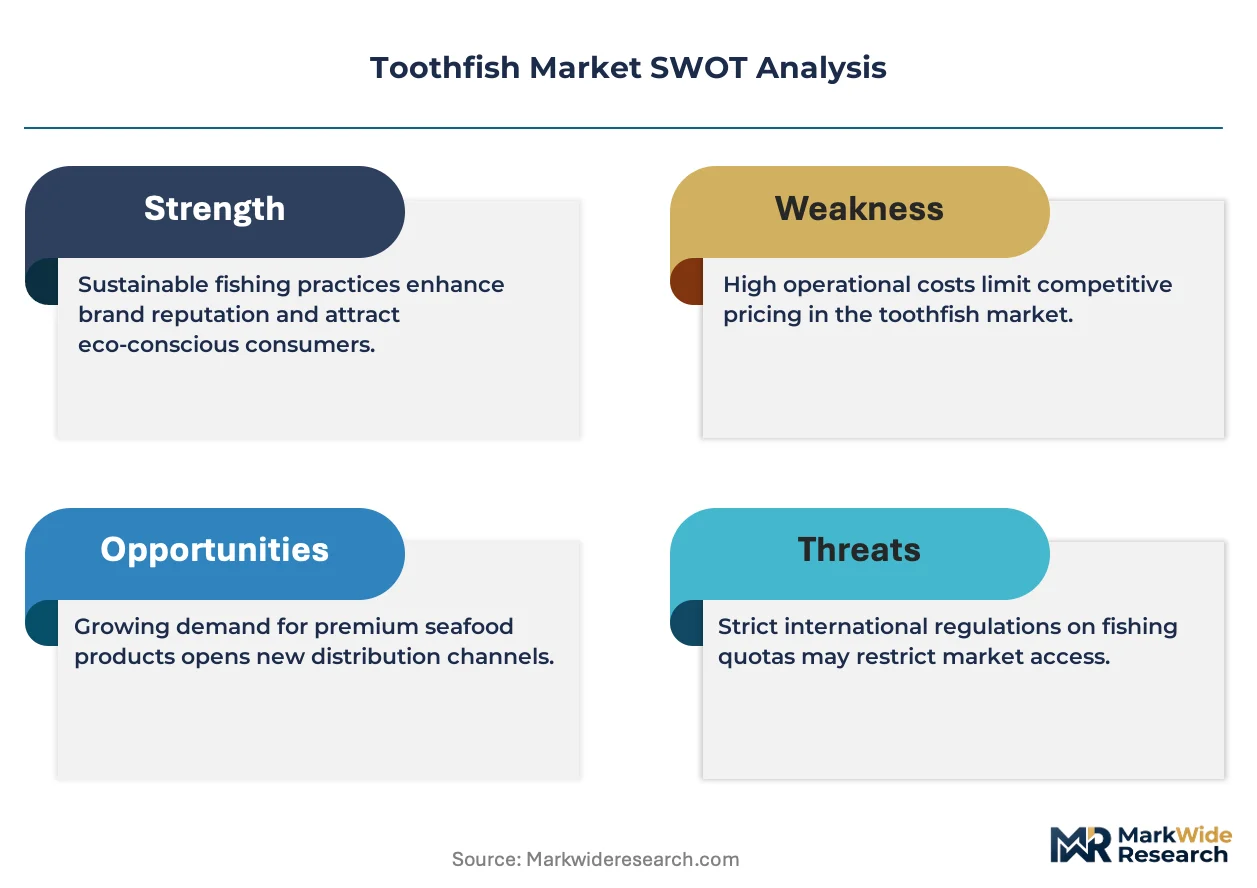
CCAMLR's tightening catch documentation rules and Marine Protected Area expansions are restructuring harvest access, forcing licensed operators to consolidate chain-of-custody investments or exit premium supply channels entirely.
Growth Catalysts
- East Asian premium dining expansion:High-end restaurant chains in Japan's kaiseki and sushi sectors are expanding certified sustainable toothfish placements, creating pull-through demand for MSC-certified supply.
- Air-freight shelf-life extension:Vacuum-sealed packaging technologies are enabling longer distribution windows to distant importers, reducing spoilage losses on trans-Pacific and trans-Atlantic routes.
- EU IUU regulation enforcement:The European Union's illegal, unreported, and unregulated fishing framework is barring non-compliant product from major entry points, concentrating demand among verified operators.
Market Restraints
- Sub-Antarctic quota concentration:Harvest rights cluster among Convention members with historic allocations, limiting new entrant access to certified catch.
- Fuel and logistics cost volatility:Antarctic longline operations depend on bunker fuel and ice-class vessel availability, exposing margins to energy price swings.
- Whitefish substitution pressure:Farmed halibut and black cod from Alaska and British Columbia compete for premium white-tablecloth placements at lower price points.
Strategic Opportunities
- Online direct-to-chef channels:Digital platforms connecting licensed exporters directly to restaurant procurement teams are bypassing traditional wholesale tiers in Seoul and Singapore.
- Marine Stewardship Council certification expansion:Fisheries lacking MSC status can capture margin premiums by completing assessment pathways for previously uncertified stocks.
- Chinese cold-chain infrastructure:Investment in refrigerated warehousing at Shanghai and Guangzhou ports enables fresh fillet positioning for mainland premium hospitality.
Industry Challenges
- Vessel-level traceability system integration:Operators must retrofit legacy catch documentation workflows to meet real-time electronic reporting requirements under CCAMLR schemes.
- At-sea observer coverage gaps:Shortages of trained monitors for longline fleets create compliance bottlenecks during peak harvest windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toothfish Market |
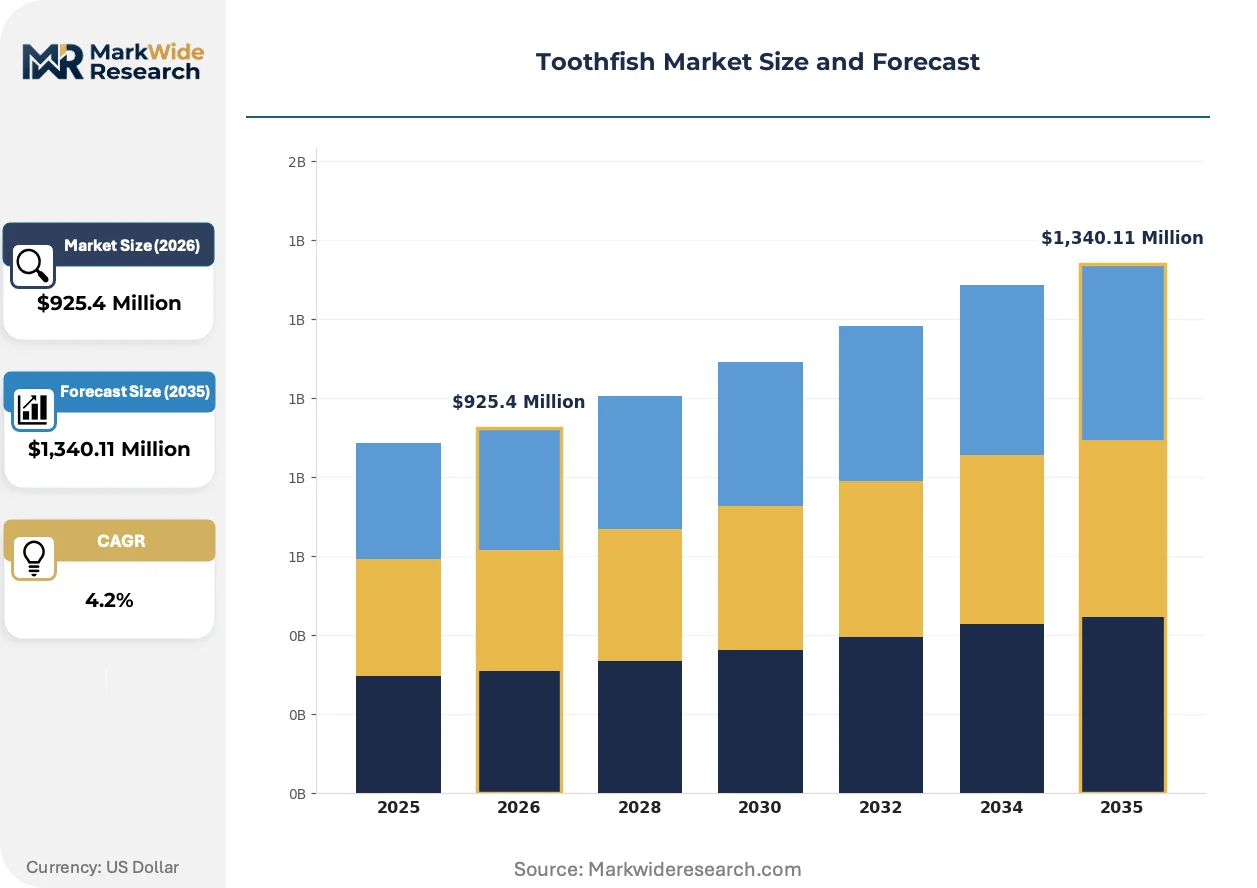
| Market Size in 2026 | $925.4 Million |
| Market Size in 2035 | $1,340.11 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chilean Sea Bass, Antarctic Toothfish, Black Cod, Other Species Distribution Channel: Direct Sales, Wholesale, Retail, Online End User: Restaurants, Supermarkets, Food Service, Exporters Packaging Type: Vacuum Sealed, Can Pack, Bulk Packaging, Pre-Portioned |
| Companies Covered | Newsan, Cap Bourbon, Consolidated Fisheries Ltd, Pesentar, Talley's Group, Austral Fisheries, Fortuna, Ocean Fish, Profand, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toothfish Market Trends and Innovations
Digital traceability platforms and shifting procurement behaviors are compressing traditional supply tiers, while regulatory enforcement tightens documentation standards across major importing jurisdictions.
Blockchain-enabled chain-of-custody systems are unifying vessel catch data, processing records, and retail packaging codes into single-source verification. Asian wholesale buyers are adopting these platforms fastest, demanding instant provenance confirmation for high-value fillet lots. This unifying architecture is compressing the time between harvest and restaurant plate while reducing documentation disputes at customs checkpoints.
REACH-style chemical disclosure requirements in the European Union are extending to seafood packaging materials, forcing exporters to certify that vacuum films and insulated containers meet substance restrictions. Processors serving Barcelona and Madrid food-service markets are reformulating packaging specifications to preempt entry denials. The compliance burden falls heaviest on smaller Argentine operators lacking in-house regulatory affairs capacity.
Certification-driven purchasing mandates among Japanese institutional buyers are displacing spot-market procurement with long-term offtake agreements tied to MSC status. Major hotel chains in Tokyo and Osaka now require documented sustainability credentials for all whitefish categories, including toothfish. This shift concentrates volume among pre-qualified suppliers while marginalizing uncertified landings.
Toothfish Market Segmentation
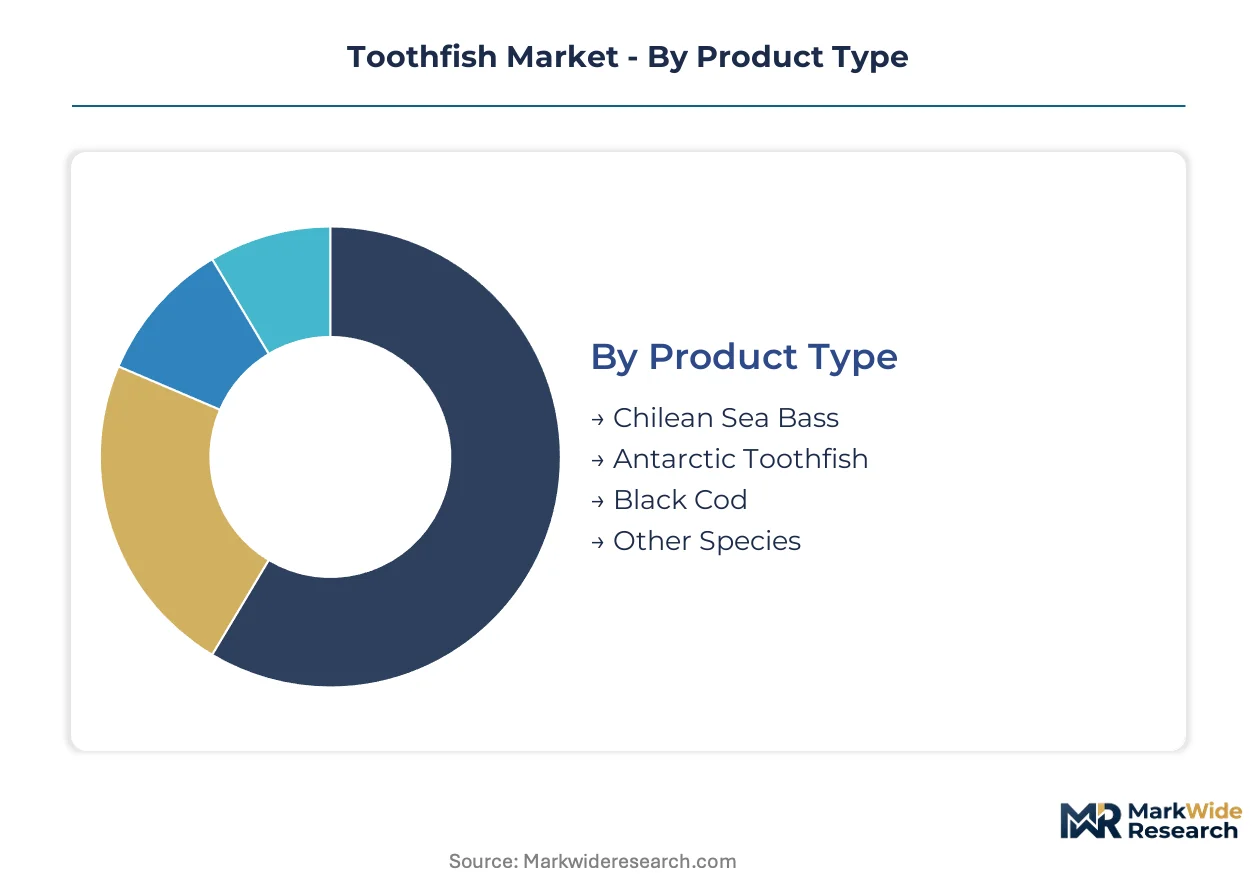
Toothfish market segmentation reveals how capital deployment, regulatory compliance costs, and cold-chain infrastructure requirements vary sharply across product grades and distribution pathways. Understanding these structural divides helps operators allocate vessel quotas, processing investments, and certification resources toward the highest-margin access routes.
Product Type:
Capital intensity concentrates in longline vessel fleets and onshore blast-freezing infrastructure, with species-specific handling protocols driving differential investment thresholds.
- Chilean Sea Bass:Patagonian toothfish (Dissostichus eleginoides) harvested from sub-Antarctic waters carries the highest landed value per kilogram. Japanese kaiseki and premium sushi establishments in Tokyo and Osaka drive demand for MSC-certified fillets with verified chain-of-custody documentation.
- Antarctic Toothfish:D. mawsoni from higher-latitude CCAMLR management areas requires ice-class vessel capability and extended at-sea endurance. The species commands positioning in Seoul and Singapore high-end restaurant chains seeking differentiated provenance narratives for white-tablecloth menus.
- Black Cod:Anoplopoma fimbria from North Pacific fisheries competes as a substitute in lower price tiers.
- Other Species:Minor nototheniid landings fill commodity processing channels.
Most installed capacity flows through Chilean Sea Bass. Expansion is steepest in Antarctic Toothfish.
Distribution Channel:
Channel selection dictates working capital cycles, with direct sales locking up receivables longest and online platforms compressing cash conversion through prepayment structures.
- Direct Sales:Licensed operators transact bilateral contracts with established exporters, bypassing intermediary margins. These arrangements dominate volume flows between Austral Fisheries and Asian wholesale buyers, though they require dedicated regulatory affairs staff to manage CCAMLR documentation and EU IUU compliance.
- Wholesale:Barcelona and Madrid food-service markets source through consolidated importers demanding real-time traceability. Newsan leverages direct Argentine landings into these channels, competing on freshness metrics against frozen inventory from distant water fleets.
- Retail:Supermarket placement requires retail-ready packaging and sustained promotional support.
- Online:Digital platforms connecting licensed exporters to restaurant procurement teams are gaining share fastest in Seoul and Singapore, bypassing traditional wholesale tiers entirely.
Direct Sales anchors volume throughput. Online channels are climbing the fastest.
End User:
End-user concentration shapes quota allocation strategies, with institutional buyers commanding long-term offtake agreements and spot-market players absorbing seasonal surplus.
- Restaurants:High-end Japanese dining establishments require documented sustainability credentials under procurement mandates from Tokyo and Osaka hotel chains. Certification-driven purchasing displaces spot-market sourcing, concentrating volume among pre-qualified MSC suppliers.
- Supermarkets:Retail placement depends on consumer-facing packaging and cold-chain reliability.
- Food Service:Barcelona and Madrid operators prioritize freshness and portion consistency for white-tablecloth applications.
- Exporters:Licensed re-export hubs in New Zealand and Argentina manage documentation workflows for secondary markets.
Restaurants command the premium tier. Food Service is gaining share fastest in Southern European channels.
Packaging Type:
Packaging technology investments determine shelf-life extension capabilities and air-freight economics for distant importers.
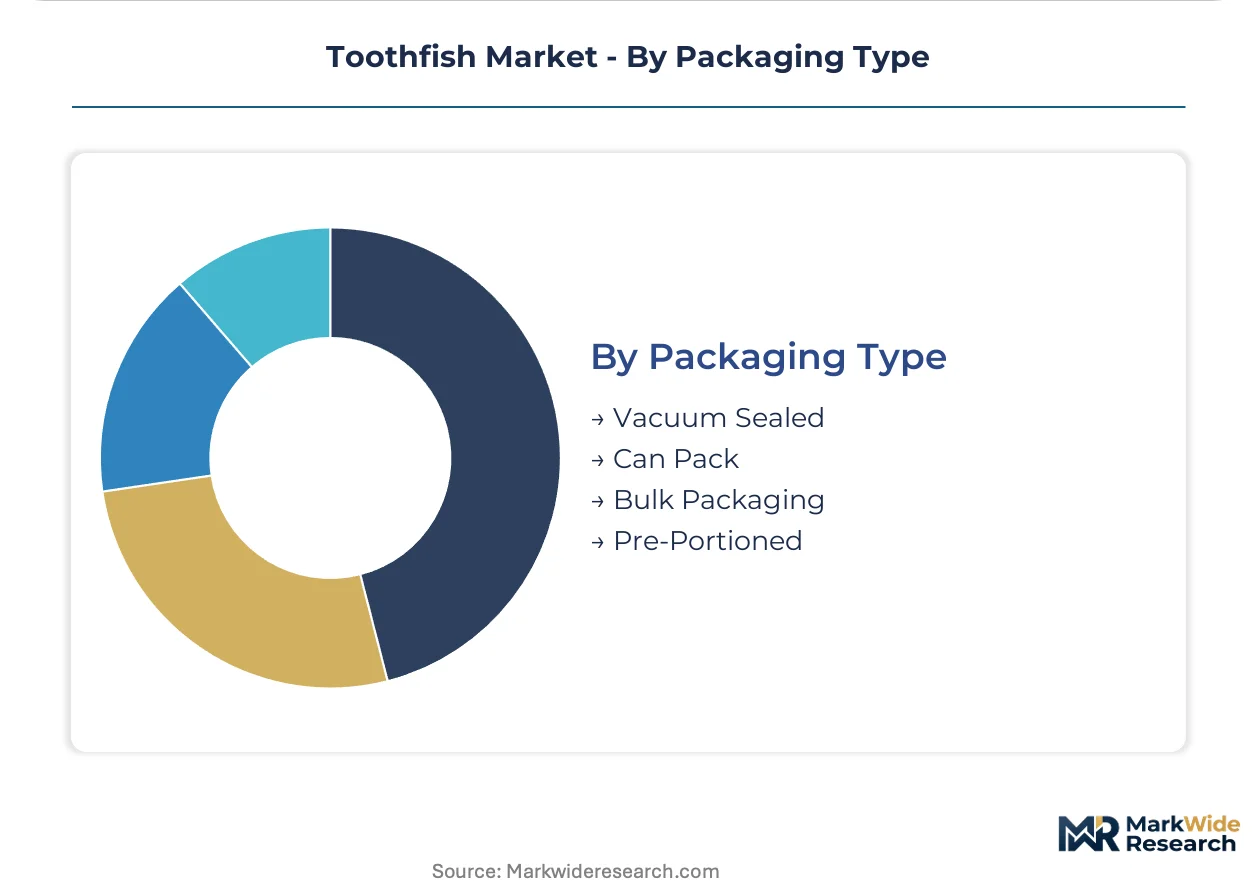
- Vacuum Sealed:Modified-atmosphere films extend distribution windows for trans-Pacific and trans-Atlantic routes, reducing spoilage losses. REACH-style chemical disclosure requirements in the European Union force exporters to certify film compositions, burdening smaller Argentine operators lacking in-house compliance capacity.
- Can Pack:Shelf-stable formats serve commodity segments with lower margin profiles.
- Bulk Packaging:Industrial processors at Talley's Nelson facility utilize bulk formats for secondary processing and re-export.
- Pre-Portioned:Cut-to-specification fillets reduce kitchen labor for restaurant end-users.
Vacuum Sealed dominates air-freight premium flows. Pre-Portioned formats are expanding most quickly in direct-to-chef channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing toothfish processing capacity toward jurisdictions with streamlined catch documentation and lower compliance overhead, particularly as CCAMLR enforcement tightens in traditional harvesting zones.
Japan
Tokyo and Osaka hotel chains now mandate MSC certification for all whitefish procurement, concentrating demand among pre-qualified suppliers. Japan's Ministry of Agriculture, Forestry and Fisheries enforces strict import documentation aligned with CCAMLR schemes. Kaiseki and premium sushi establishments in Ginza and Roppongi drive the highest per-kilogram pricing for Patagonian toothfish fillets.
Spain
Barcelona and Madrid food-service markets prioritize freshness metrics and real-time traceability for white-tablecloth applications. EU IUU regulation enforcement through the European Fisheries Control Agency bars non-compliant product from Spanish ports. Basque Country processors are reformulating packaging specifications to meet REACH-style chemical disclosure requirements for vacuum-sealed films.
China
Shanghai and Guangzhou cold-chain infrastructure investments enable fresh fillet positioning for mainland premium hospitality. The General Administration of Customs China enforces vessel-level traceability documentation under import safety protocols. Yangtze River Delta refrigerated warehousing expansions are drawing Argentine direct landings away from traditional European re-export hubs.
South Korea
Seoul restaurant procurement teams are adopting digital platforms that bypass traditional wholesale tiers entirely. The Ministry of Oceans and Fisheries implements electronic catch documentation verification for Antarctic marine species. Gangnam district high-end dining chains are expanding certified sustainable toothfish placements on seasonal menus.
New Zealand
Nelson-based vertically integrated processing anchors supply chain control for Australasian export channels. The Ministry for Primary Industries administers chain-of-custody certification aligned with MSC frameworks. Canterbury region cold-storage expansions support air-freight distribution to East Asian markets with extended shelf-life packaging.
Toothfish Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-chef digital channels and MSC certification gaps. The vendor base clusters around three strategic archetypes: vertically integrated quota holders with processing assets, specialist longline operators selling into wholesale consolidation points, and direct-landing specialists serving Southern European food-service markets. Dominant competitive moves include chain-of-custody certification investments and geographic repositioning of harvest quotas toward higher-value fillet grades.
Among Southern Hemisphere quota holders, Austral Fisheries exemplifies the integrated archetype with end-to-end control from vessel to export documentation. Talley's Group anchors New Zealand supply through captive processing infrastructure. Newsan represents the direct-landing specialist model, competing on freshness metrics in Barcelona and Madrid markets through Argentine port access.
| Leading Market Players |
|---|
| Newsan |
| Cap Bourbon |
| Consolidated Fisheries Ltd |
| Pesentar |
| Talley's Group |
| Austral Fisheries |
| Fortuna |
| Ocean Fish |
| Profand |
| Others |
Pricing and Supply Chain Analysis
MSC certification gates both qualified supply and premium-tier pricing access, with Japanese hotel chains and Seoul restaurant procurement teams refusing uncertified product regardless of price discounting. This sustainability mandate compresses margins for non-compliant operators while concentrating pricing power among verified quota holders with chain-of-custody documentation.
Pricing Analysis
Wholesale margin layers dominate pricing architecture, with direct-to-chef channels capturing value through prepayment structures that bypass distributor markups. Pricing stratifies across MSC-certified premium, conventional standard, and uncertified economy tiers, with certification level and air-freight delivery cost as primary differentiation drivers. Cost compression in conventional tiers is intensifying because farmed halibut and black cod from Alaska and British Columbia compete for white-tablecloth placements. Food-service buyers in Barcelona and Madrid show highest price sensitivity; Tokyo kaiseki establishments show lowest.
Supply Chain Analysis
CCAMLR chain-of-custody certification gates market access, with electronic catch documentation requirements filtering out legacy operators lacking real-time vessel reporting capability. Supply concentrates in New Zealand, Argentina, and Australia, with raw material flows drawing from sub-Antarctic longline fleets and Nelson-based blast-freezing infrastructure. Single-source vulnerability runs through ice-class vessel availability and trained at-sea observer shortages. Distribution runs through bilateral contracts between licensed operators and established exporters, with online platforms emerging as alternative pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Toothfish market dynamics reward geographic arbitrage between Argentine direct-landing freshness plays and Asian cold-chain infrastructure investments, with regulatory compliance cost differentials of fifteen to twenty percentage points separating efficient operators from marginal exits.
For Market Incumbents: Anchor quota allocation toward higher-value fillet grades demanded by Tokyo and Osaka hotel chains, while deepening backward integration into vacuum-sealed packaging to preempt REACH-style chemical disclosure enforcement. Defend against whitefish substitution pressure by locking long-term offtake agreements with MSC-certified supply. Prioritize ice-class vessel renewal to maintain Antarctic Toothfish access as Marine Protected Area expansions displace historic grounds. For New Entrants and Emerging Players: Digital platform partnerships offer the fastest path around entrenched wholesale tiers in Seoul and Singapore, where restaurant procurement teams seek direct exporter relationships. Target the online distribution channel as the most penetrable access route, with pre-portioned fillet formats reducing kitchen labor for end-users. Pursue MSC certification for previously uncertified stocks to capture margin premiums in certification-driven purchasing mandates. For Investors and Strategic Acquirers: Roll-up economics work for vertically integrated quota holders with captive processing assets because chain-of-custody certification creates durable competitive moats that fragment supply concentration among compliant operators. Long-term viability hinges on five-to-ten year quota security under CCAMLR Convention membership. Watch Marine Protected Area expansion pace as the critical inflection signal for harvest access displacement.| Strategic Initiative | Industry Significance |
|---|---|
| MSC Certification Pathway Completion | Opens Tokyo and Osaka hotel chain procurement mandates to previously excluded suppliers. |
| Direct-to-Chef Digital Platform Launch | Bypasses wholesale margin layers in Seoul and Singapore restaurant procurement. |
| Vacuum-Sealed Packaging Reformulation | Ensures EU REACH compliance for Barcelona and Madrid food-service market entry. |
| Ice-Class Vessel Fleet Renewal | Maintains Antarctic Toothfish access as CCAMLR management areas shift. |
| Chain-of-Custody System Integration | Enables real-time electronic reporting required under tightened catch documentation rules. |
Research Methodology
Coverage spans East Asia, Southern Europe, and the South Pacific, with primary inputs from each region combining vessel operator interviews, seafood importer regulatory affairs leads, and restaurant procurement managers with secondary validation from CCAMLR catch documentation databases, EU IUU regulation enforcement records, customs trade data, and Marine Stewardship Council certification registries. Bottom-up quota allocation modeling triangulates against top-down market sizing from certified supply volumes.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon, with segmentation modeling across species type, distribution channel, end-user category, and packaging format. CAGRs derive from quota trajectory analysis, certification penetration curves, and cold-chain infrastructure investment pacing, with air-freight cost volatility and fuel price swings as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Marine Protected Area expansion decisions and Convention membership quota reallocation battles. Forecasts reflect documented assumptions regarding certification compliance rates and observer coverage availability. A model refresh is warranted upon material change in CCAMLR catch documentation enforcement stringency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Fried Dace with Salted Black Beans Market
Seafood
Canned Sardines Market
Seafood
Fresh Fish Market
Seafood
Mackerel Market
Seafood
Fish Meal Market
Seafood
Latin America Salmon Market
Seafood
Fish & Shrimp, Fish Feed & Shrimp Feed and Additives Market
Seafood
Seafood Powders Market
Seafood
Europe Salmon Market
Seafood
Seafood Takeout Market
Seafood
North America Salmon Market
Seafood
Asia-Pacific Shrimp Market
Seafood
Carp Market
Seafood
Asia Pacific Canned Seafood Market
Seafood
Fish Protein Concentrate Market
Seafood
Crustacean Market