
 Asia-Pacific Seafood Market | 2026-2036
Asia-Pacific Seafood Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Seafood Market Outlook
Food service operators are reorganizing procurement priorities toward traceable, cold-chain-verified seafood, while retail consumers shift toward vacuum-sealed and frozen formats for home preparation. Nippon Suisan Kaisha Ltd leverages vertical integration across Pacific tuna longlines to sustain supply security. Charoen Pokphand Foods PCL anchors its position through captive aquaculture feed operations in Thailand. Thai Union Group PCL dominates shelf-stable canned tuna exports into European and Middle Eastern channels.
Asia-Pacific seafood encompasses finfish, shellfish, mollusks, and crustaceans harvested from wild capture or aquaculture systems, typically processed through chilling, freezing, canning, or vacuum-sealing to preserve protein integrity and extend shelf life. The category serves protein substitution in retail meals, food service platters, and industrial further-processing applications. Fish products lead volume throughput due to established aquaculture infrastructure, while crustaceans command premium margin pools in restaurant and export segments. Frozen packaging formats are gaining fastest in online and supermarket channels as cold-chain reliability improves across Southeast Asian logistics networks.
China's SAMR enforces GB standards for aquatic product safety and labeling, while Japan's METI coordinates HACCP-aligned processing protocols that shape regional export eligibility. South Korea's MFDS maintains residue testing regimes that filter market access for imported shellfish and mollusks. Stakeholders must monitor regulatory divergence between national food safety regimes and align certification investments with the strictest destination-market requirements.
Market Dynamics
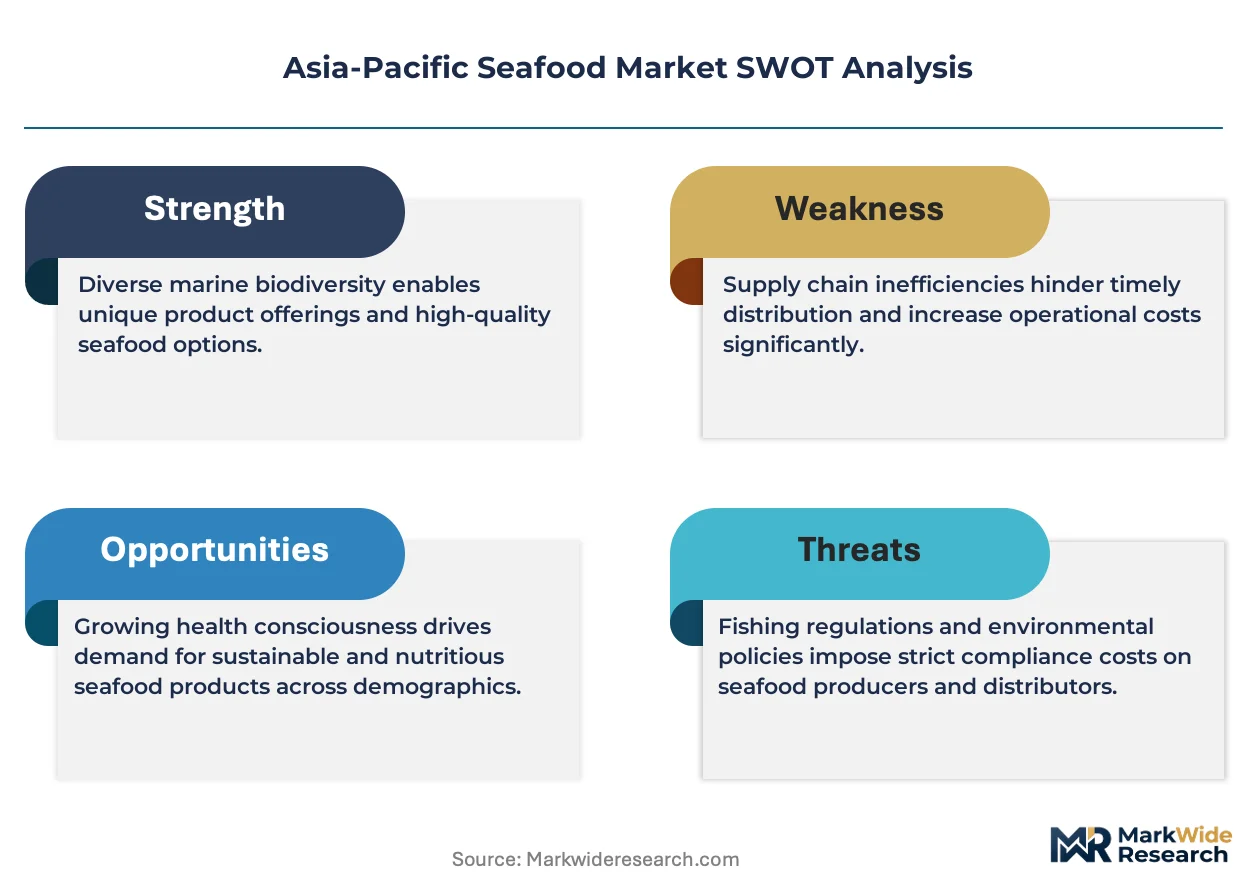
Traceable cold-chain verification is restructuring procurement hierarchies across Asia-Pacific seafood distribution, forcing processors to invest in temperature-logging infrastructure and digital certification layers that were previously optional.
Growth Catalysts
- GB Standards Compliance:China's SAMR enforcement of aquatic product safety protocols is mandating batch-level traceability systems that upgrade processing facility capabilities across Shandong and Fujian provinces.
- Food Service Reorganization:Restaurant chains and institutional caterers are rewriting supplier scorecards to prioritize HACCP-aligned cold-chain documentation, pulling premium volumes toward certified operators.
- Mekong Delta Concentration:Vietnam's processing clusters are capturing upstream aquaculture feed and downstream export logistics within single corridor infrastructure, compressing lead times for pangasius and shrimp value chains.
Market Restraints
- Input Cost Volatility:Fishmeal and soy-protein concentrate prices fluctuate with South American crop cycles and Peruvian anchovy harvest variability, squeezing aquaculture feed margins.
- Supply Concentration Risk:Indonesia's tuna export corridors depend on a narrow band of Bitung and Benoa landing sites vulnerable to port congestion and fuel access interruptions.
- Regulatory Friction:South Korea's MFDS residue testing regimes for imported shellfish create inspection backlogs that delay Japanese and Chinese mollusk shipments by 7-14 days.
Strategic Opportunities
- Underpenetrated Geographies:The Philippines' Mindanao aquaculture zones lack integrated cold-chain networks, opening first-mover positions for processors building captive logistics.
- Technology Convergence:Blockchain ledger systems merged with IoT temperature sensors are enabling real-time custody documentation that satisfies European retailer audit requirements.
- Channel Innovation:Direct-to-restaurant platforms in Bangkok and Ho Chi Minh City are bypassing traditional wet-market intermediaries, capturing margin and harvest-to-kitchen data streams.
Industry Challenges
- Capex Intensity:Blast-freezing and controlled-atmosphere storage installations require capital commitments that strain mid-tier processors in Indonesia and Malaysia.
- Certification Timeline Compression:HACCP re-audits and METI-aligned protocol updates demand dedicated compliance staff that smaller Vietnamese operators struggle to retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Seafood Market |
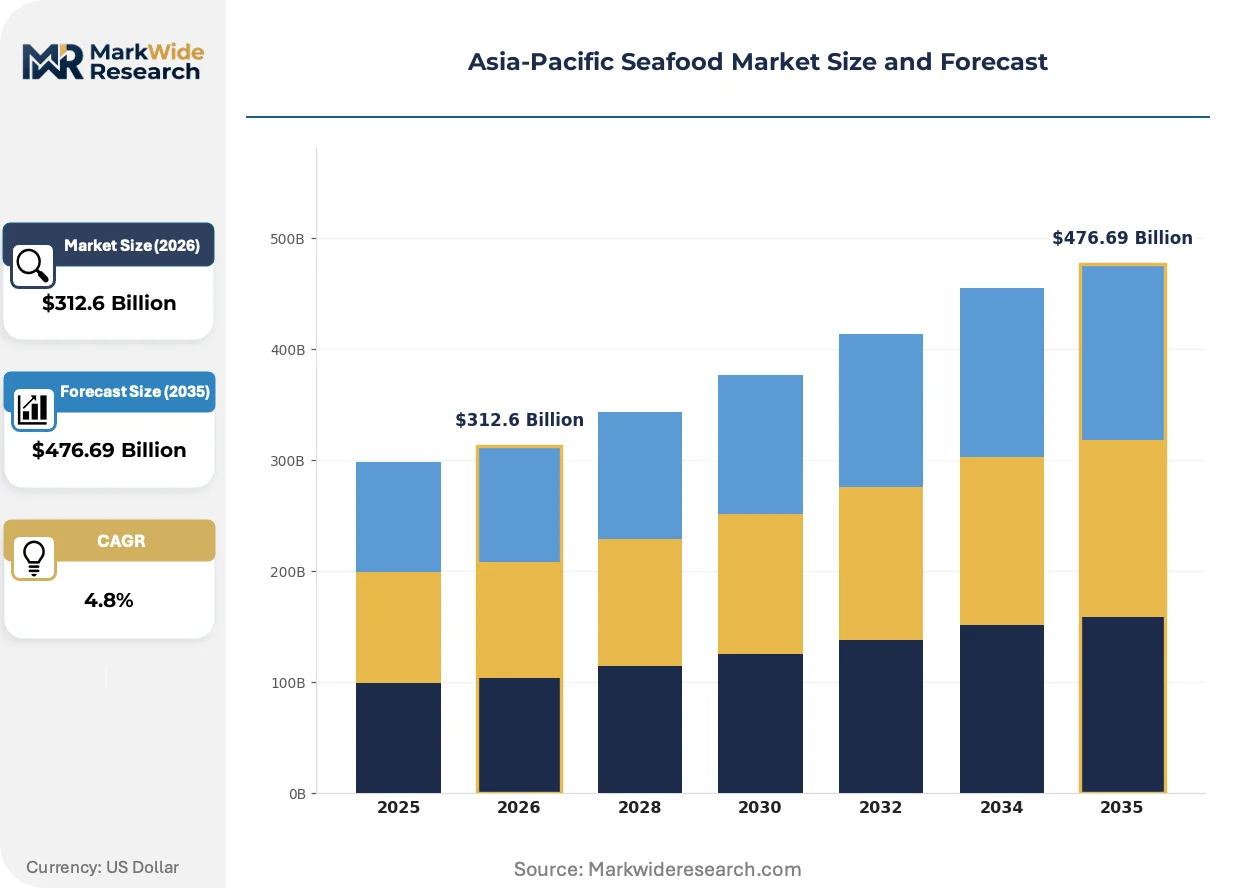
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $476.69 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish, Shellfish, Mollusks, Crustaceans Distribution Channel: Supermarkets, Online, Wholesale, Restaurants End User: Retail Consumers, Food Service, Processors, Exporters Packaging Type: Frozen, Canned, Fresh, Vacuum-Sealed |
| Companies Covered | Nippon Suisan Kaisha Ltd, Charoen Pokphand Foods PCL, Maruha Nichiro Corporation, Sajo Industries, Beijing Princess Seafood International, Thai Union Group PCL, Mowi ASA, Hansung Enterprise, Dongwon Industries Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Seafood Market Strategic Shifts
Digital traceability infrastructure and alternative protein positioning are rewriting competitive boundaries across Asia-Pacific seafood value chains, compressing traditional advantages held by scale incumbents.
Blockchain-enabled supply chain documentation is decomposing the information asymmetry that previously protected established traders. Japanese supermarket chains and Australian import houses are adopting distributed-ledger verification for tuna and salmon provenance within eighteen-month procurement cycles. This transparency architecture is collapsing the premium that undocumented catch commands in wholesale auctions.
METI's HACCP-aligned processing protocols are mandating hazard-control documentation that reshapes facility design standards. Japanese canneries and Thai Union Group's export-oriented plants must install metal-detection and temperature-monitoring checkpoints that add operational layers but unlock European retail shelf access. Vietnamese pangasius processors are responding by consolidating under shared certification umbrellas to spread compliance costs.
Retail buyer concentration toward vacuum-sealed and frozen formats is restructuring supermarket shelf allocations and e-commerce fulfillment priorities. Home-meal-preparation segments in Seoul, Singapore, and Sydney are displacing fresh-counter purchases with IQF shrimp and pre-portioned fish fillets. This channel rotation is most visible in Lazada and Shopee seafood categories, where frozen SKUs now dominate search rankings and promotional placement.
Asia-Pacific Seafood Market Segmentation
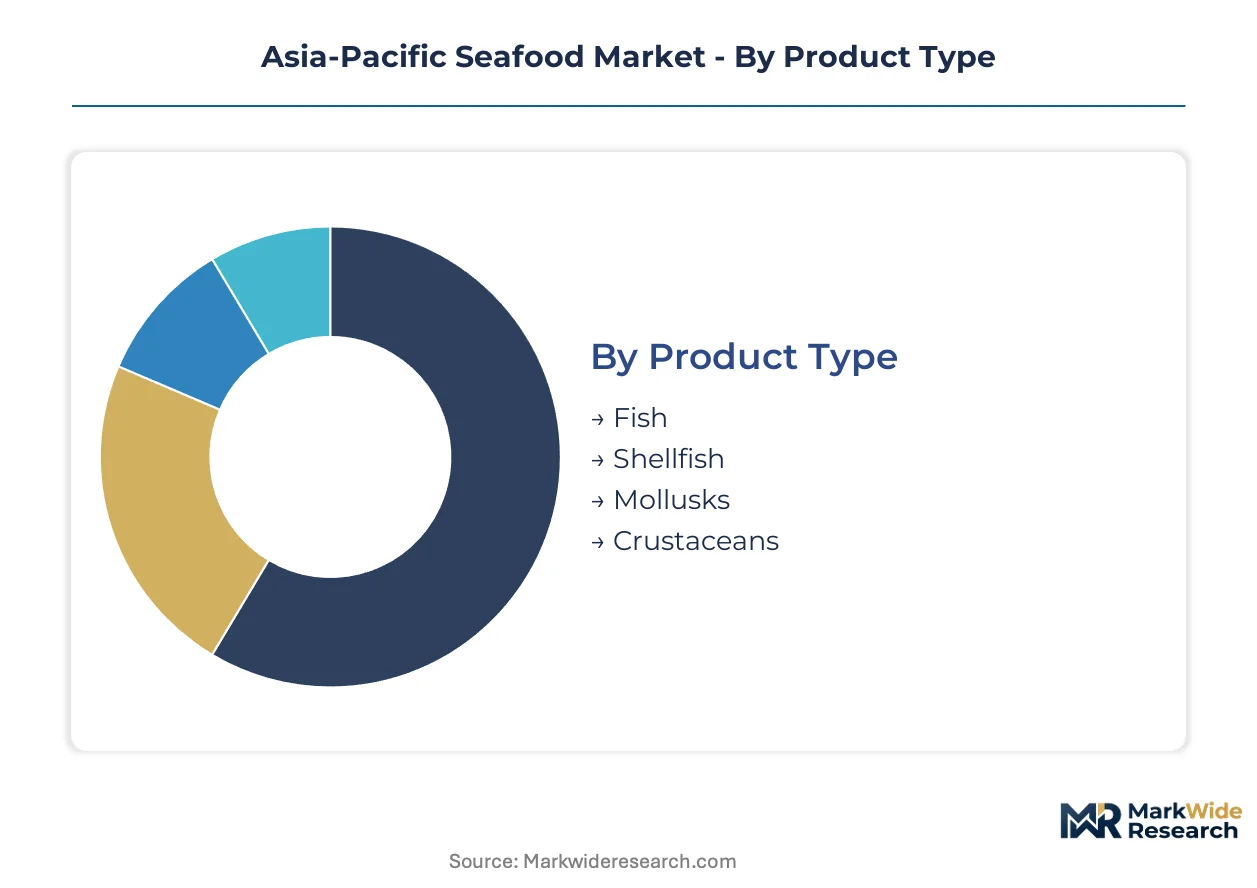
Channel specialization across Asia-Pacific seafood markets creates distinct margin and compliance requirements for each segment. Understanding how product categories map to distribution pathways enables targeted infrastructure investments and certification alignment.
Product Type:
Fish products flow predominantly through supermarket frozen counters and restaurant supply chains, while crustaceans and mollusks concentrate in premium wholesale channels and direct export corridors.
- Fish:Pangasius, tilapia, and tuna species dominate aquaculture and wild-capture volumes. Mekong Delta processors in Vietnam and Fujian-based operators in China supply IQF fillets to European retail and Southeast Asian food service networks. Demand concentrates where cold-chain reliability meets GB standards compliance for batch-level traceability.
- Shellfish:Oysters, clams, and scallops require rapid chilled distribution due to narrow shelf-life windows. South Korean import houses and Japanese sashimi distributors prioritize MFDS-aligned residue documentation when sourcing from Chinese and Japanese coastal farms.
- Mollusks:Squid and octopus categories serve dried-snack processors and frozen-tentacle exporters. Indonesia's Bitung landing sites and Thailand's Samut Sakhon freezing plants handle the bulk of regional throughput.
- Crustaceans:Shrimp and crab segments command premium pricing in restaurant and retail channels. Thai and Vietnamese black tiger shrimp farms supply value-added peeled products to Middle Eastern and Australian import markets.
Fish dominates installed base across production tonnage and processing facility count. Crustaceans represent where expansion concentrates due to margin premiums and export demand intensity.
Distribution Channel:
Channel selection determines temperature-control investment levels and documentation requirements, with digital platforms forcing traditional intermediaries to upgrade custody-verification capabilities.
- Supermarkets:Modern trade formats in Seoul, Singapore, and Sydney allocate expanding shelf space to vacuum-sealed and frozen SKUs. Retail buyers demand HACCP-aligned supplier scorecards that filter out wet-market-sourced products.
- Online:Lazada and Shopee seafood categories show frozen product dominance in search rankings and promotional placement. Direct-to-consumer fulfillment requires last-mile cold-chain partnerships that remain underdeveloped in Philippine and Indonesian secondary cities.
- Wholesale:Traditional auction houses and consolidated import terminals in Tokyo's Tsukiji successor market and Bangkok's Talad Thai handle volume aggregation for restaurant chains and institutional caterers. Temperature-logging documentation is becoming a mandatory entry ticket.
- Restaurants:Food service operators in Ho Chi Minh City and Bangkok are rewriting procurement hierarchies to prioritize traceable, cold-chain-verified suppliers. Direct sourcing platforms bypass traditional wet-market intermediaries.
Supermarkets anchor current volume throughput. Online channels are expanding most quickly as cold-chain logistics mature across Southeast Asian metropolitan corridors.
End User:
User-type segmentation reveals diverging quality thresholds and price sensitivity, with institutional buyers driving standardization while retail consumers fragment across convenience and freshness priorities.
- Retail Consumers:Home-meal-preparation segments in urban Australia, South Korea, and Japan displace fresh-counter purchases with pre-portioned frozen fillets and IQF shrimp. Convenience positioning competes with traditional wet-market freshness expectations.
- Food Service:Restaurant chains and institutional caterers impose HACCP-aligned documentation requirements that reshape supplier qualification processes. Thai and Vietnamese operators must install metal-detection and temperature-monitoring checkpoints to maintain contract eligibility.
- Processors:Further-processing facilities in Indonesia and Malaysia require consistent raw-material specifications for breaded, marinated, and ready-to-cook product lines. Input cost volatility in fishmeal and soy-protein concentrate squeezes margin predictability.
- Exporters:European and Middle Eastern destination markets enforce the strictest certification requirements. Japanese canneries and Thai Union Group's export-oriented plants align with METI protocols to unlock retail shelf access.
Food service dominates value extraction through contract concentration. Retail consumers represent where volume expansion concentrates as e-commerce penetration deepens.
Packaging Type:
Packaging selection directly links to shelf-life extension requirements and channel compatibility, with frozen and vacuum-sealed formats displacing traditional fresh distribution in premium segments.
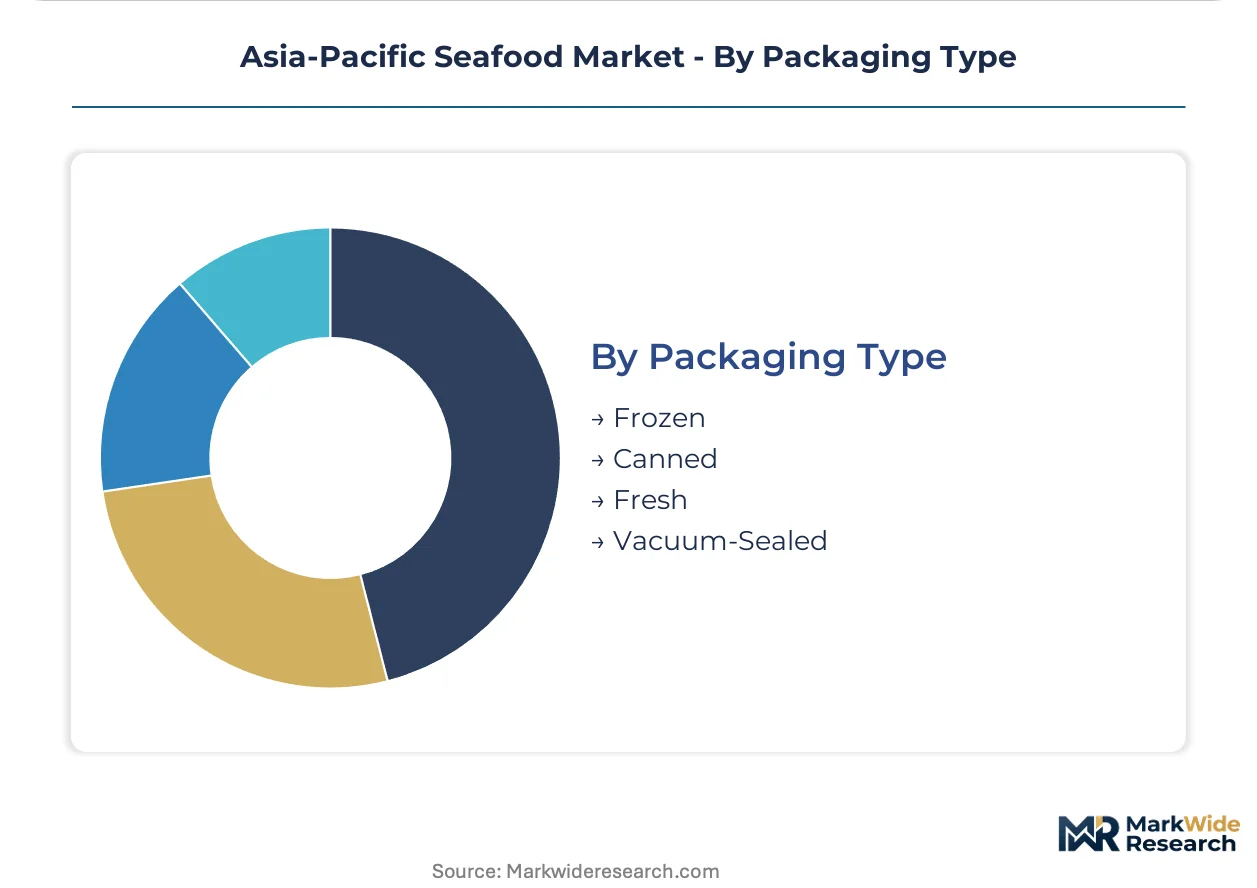
- Frozen:Individual quick-freezing and blast-freezing technologies preserve protein integrity for extended supply chains. Southeast Asian logistics networks are improving cold-chain reliability to support frozen SKU expansion in online and supermarket channels.
- Canned:Shelf-stable tuna and mackerel products serve emergency stockpiling, institutional feeding, and price-sensitive retail segments. Thai Union Group dominates European and Middle Eastern canned tuna export channels.
- Fresh:Chilled distribution maintains highest value for sashimi-grade tuna and live crustacean categories. Narrow shelf-life windows limit geographic reach to coastal metropolitan markets and same-day delivery zones.
- Vacuum-Sealed:Modified-atmosphere packaging extends retail shelf life while maintaining visual freshness cues. Australian and Japanese supermarket chains are expanding vacuum-sealed salmon and whitefish allocations.
Frozen formats dominate installed processing capacity and logistics infrastructure. Vacuum-sealed packaging is where technology investment concentrates as European retailer audit requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnamese pangasius exports to European retail channels and Indonesian tuna shipments to Middle Eastern processors define the dominant trade corridors reshaping procurement patterns across the region.
China
Shandong and Fujian processing clusters supply IQF fillets to Southeast Asian food service networks. SAMR enforces GB standards mandating batch-level traceability systems that upgrade facility capabilities. Qingdao-based operators are installing temperature-logging infrastructure to satisfy European retailer audit requirements.
Japan
Sashimi-grade tuna demand from Tokyo restaurant chains drives premium import volumes. METI coordinates HACCP-aligned processing protocols that reshape cannery design standards. Osaka and Nagoya freezing plants install metal-detection checkpoints to maintain export eligibility.
Vietnam
Mekong Delta pangasius and black tiger shrimp farms serve Middle Eastern and Australian import markets. Government aquaculture expansion programs consolidate feed and logistics within single corridor infrastructure. Can Tho processing clusters compress lead times through captive cold-chain networks.
Indonesia
Bitung and Benoa landing sites handle regional tuna throughput for cannery and fresh-export channels. Port congestion and fuel access interruptions create supply concentration vulnerabilities. Sulawesi-based operators face capex strain from blast-freezing installation requirements.
South Korea
Seoul supermarket chains displace fresh-counter purchases with vacuum-sealed salmon and whitefish. MFDS residue testing regimes filter market access for imported shellfish and mollusks. Busan import houses prioritize documentation-compliant Chinese and Japanese coastal farm suppliers.
Asia-Pacific Seafood Market Competitive Environment
Listed leaders compete with private specialists across cold-chain verification capabilities, creating a tiered structure where scale advantages clash with niche certification depth. The vendor base separates into three strategic archetypes: vertically integrated aquaculture operators, export-focused cannery conglomerates, and regional trading houses. Consolidation pressure concentrates in Vietnamese pangasius processing and Indonesian tuna logistics. Dominant competitive moves include backward integration into feed production and geographic expansion through direct-to-restaurant platform investments.
Among Japan-based marine products groups, Nippon Suisan Kaisha Ltd and Maruha Nichiro Corporation exemplify the vertically integrated archetype, anchoring positions through Pacific tuna longline control. Thai Union Group PCL occupies a scale-driven position within the export-oriented cannery tier, representing shelf-stable tuna specialists serving European and Middle Eastern channels. Charoen Pokphand Foods PCL anchors the aquaculture-integrated category, sitting within Thailand-based operators leveraging captive feed operations.
| Leading Market Players |
|---|
| Nippon Suisan Kaisha Ltd |
| Charoen Pokphand Foods PCL |
| Maruha Nichiro Corporation |
| Sajo Industries |
| Beijing Princess Seafood International |
| Thai Union Group PCL |
| Mowi ASA |
| Hansung Enterprise |
| Dongwon Industries Ltd |
| Others |
Value Chain & Pricing Dynamics
China's GB standards on aquatic product safety simultaneously gate supply qualification and stratify price tiers, forcing processors to absorb certification costs that separate documented cold-chain products from undocumented catch in wholesale auctions. This regulatory architecture compresses margins for non-compliant operators while rewarding HACCP-aligned facilities with premium channel access.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates Asia-Pacific seafood markets, with sashimi-grade tuna and live crustaceans commanding top positions while IQF fillets and canned products occupy volume tiers. Price differentiation rests on certification grade and cold-chain documentation completeness, with European retailer audit compliance adding margin premiums. Cost compression in economy-tier pangasius and tilapia is intensifying because Vietnamese processors face fishmeal price volatility and energy cost escalation. Food service buyers exhibit lowest price sensitivity due to contract concentration, while retail consumers in price-sensitive markets drive substitution toward frozen formats.
Supply Chain Analysis
Inventory cycles and lead-time compression vary dramatically across product categories, with fresh sashimi-grade tuna requiring same-day distribution while frozen IQF products tolerate multi-week logistics windows. Geographic supply concentration centers on Vietnam's Mekong Delta for pangasius and shrimp, Indonesia's Bitung-Benoa corridor for tuna, and China's Fujian-Shandong clusters for whitefish processing. Raw material dependencies draw from Peruvian anchovy harvests for fishmeal, South American soy for protein concentrate, and regional aquaculture feed formulations. Single-source vulnerability at Indonesian landing sites creates disruption exposure from port congestion. Distribution runs through consolidated import terminals in Tokyo, Bangkok, and Busan for restaurant and retail aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific seafood incumbents must defend against plant-based protein substitutes and cultivated seafood alternatives that are capturing premium positioning in European and Australian retail channels. Substitution threats intensify as consumer acceptance of non-animal proteins hardens in core export destinations.
For Market Incumbents: Consolidate processing capacity around captive cold-chain networks in Vietnam's Mekong Delta and Indonesia's Sulawesi corridor to achieve scale efficiencies that offset certification compliance costs. Backward integration into aquaculture feed production anchors margin control against fishmeal price volatility. METI-aligned HACCP investments unlock European retail shelf access that substitutes cannot yet match.
For New Entrants and Emerging Players: Anchor in the Philippines' Mindanao aquaculture zones where integrated cold-chain infrastructure remains underdeveloped and first-mover logistics partnerships can capture harvest-to-kitchen data streams. Direct-to-restaurant platforms in Ho Chi Minh City and Bangkok offer bypass opportunities around traditional wet-market intermediaries. Blockchain-enabled provenance documentation satisfies emerging buyer requirements faster than incumbent legacy systems can adapt.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across Vietnamese pangasius processing as blast-freezing and controlled-atmosphere storage requirements strain mid-tier operators. Long-term viability over the next decade favors processors with demonstrated European retailer audit compliance and captive feed supply chains. Acquisition targets should display METI certification completion and established Middle Eastern export relationships. The signal to watch is consolidation velocity among Vietnamese operators seeking shared certification umbrellas.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | Captive logistics networks in Vietnam and Indonesia compress lead times for pangasius and tuna value chains. |
| Backward Integration into Feed Production | Charoen Pokphand Foods PCL's captive aquaculture feed operations insulate margins from South American crop cycle volatility. |
| Blockchain Traceability Implementation | Japanese supermarket chains adopt distributed-ledger verification for tuna provenance within accelerated procurement cycles. |
| Shared Certification Umbrella Formation | Vietnamese pangasius processors consolidate compliance costs across facility networks to satisfy GB standards and METI protocols. |
| Direct-to-Restaurant Platform Launch | Bangkok and Ho Chi Minh City operators bypass wet-market intermediaries to capture margin and real-time demand data. |
Study Parameters
A spread of perspectives from aquaculture farm managers, cold-chain logistics operators, seafood procurement directors at restaurant chains, and export compliance officers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against customs records, GB standards documentation, METI processing protocols, and MFDS residue testing regimes. Bottom-up facility capacity assessments triangulated against top-down trade flow data from Vietnam, Indonesia, and China export terminals.
Segmentation dimensions modeled include product type, packaging format, distribution channel, and end-user category across the analysis window. The analytical framework derived CAGRs from production volume trajectories, processing capacity utilization rates, and channel penetration indices for frozen and vacuum-sealed formats. Industry-specific forecast inputs incorporated fishmeal price correlation models and cold-chain infrastructure investment pipelines in Southeast Asian logistics networks.
Decision-makers should treat outputs as directional under assumptions of sustained GB standards enforcement and stable Peruvian anchovy harvest cycles; material deviation in regulatory stringency or input cost volatility would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Global Frozen and Canned Seafood Market
Seafood
GCC Seafood Market
Seafood
Organic Shrimp Market
Seafood
Canned Fishery Product Market
Seafood
Seafood Flavors Market
Seafood
Canned Tuna Market
Seafood
Salmon Market
Seafood
Fish Meal and Fish Oil Market
Seafood
Krill Meal Market
Seafood
Sea Bass Market
Seafood
Europe Seafood Market
Seafood
Global Seafood Market
Seafood
Crustacean Market
Seafood
Toothfish Market
Seafood
Global White Shrimp Market
Seafood
Groundfish Market