
 Dry-Packaged Scallops Market | 2026-2036
Dry-Packaged Scallops Market Size, Share, and Industry Trends Forecast 2026-2036
Dry-Packaged Scallops Market Foresight
Automated vacuum-sealing with modified atmosphere technology is reconfiguring how scallops retain texture through distribution. Sea Watch International leverages integrated freezing and packaging lines to sustain year-round supply consistency. Clearwater Seafoods anchors its position through offshore harvesting and in-house processing control. Trident Seafoods Corporation differentiates via Alaska-origin sourcing and direct wholesale channel relationships.
Dry-packaged scallops denote bivalve mollusks preserved through dehydration, flash-freezing, or controlled smoking, then sealed in moisture-barrier packaging with sodium content typically below 3% for premium grades. These products serve commercial kitchens requiring stable protein inventory without live-shellfish logistics. Frozen product type leads volume due to extended holding periods in food service cold storage. Vacuum seal packaging captures margin concentration as processors pass through gas-flushing equipment costs. Wholesale distribution channels dominate tonnage flow, though online retail segments expand fastest among home cooks seeking restaurant-grade seafood delivery.
The FDA enforces seafood HACCP protocols that mandate time-temperature documentation from harvest through retail, while the USDA's FSIS overlapping jurisdiction on breaded scallop products creates dual compliance pathways for value-added processors. Japan's Food Sanitation Act and JIS packaging standards govern dried scallop imports, requiring moisture specification labeling that shapes product formulation for export-bound manufacturers. Stakeholders must monitor evolving cold-chain traceability mandates and shifting consumer preference between convenience-oriented pouches and bulk vacuum formats.
Market Dynamics
Flash-freezing technology paired with vacuum-barrier packaging is compressing cold-chain logistics costs while extending shelf-stable inventory windows for food service distributors.
Growth Catalysts
- Modified Atmosphere Packaging:Gas-flushing systems now replace nitrogen with argon blends to arrest enzymatic browning in premium scallop grades. High-end sushi chains in Tokyo specify this specification for raw preparations.
- FDA HACCP Mandates:Time-temperature documentation requirements from harvest through retail are pushing processors toward integrated sensor-enabled packaging that logs cold-chain integrity automatically.
- Food Service Cold Storage Expansion:Ghost kitchen operators and centralized commissaries require protein inventory that holds 180-plus days without quality degradation, favoring dry-packaged formats over live-shellfish logistics.
Market Restraints
- Atlantic Sea Scallop Quota Volatility:NOAA Fisheries sets annual catch limits that constrain raw material availability for New England processors, creating input cost spikes during quota-constrained seasons.
- Energy-Intensive Blast Freezing:Natural gas and electricity price swings directly compress margins at integrated freezing-packaging facilities, particularly for mid-scale operators without renewable power purchase agreements.
- Moisture Migration in Laminated Films:Current multi-layer barrier films exhibit oxygen transmission rate creep below minus 18 degrees Celsius, limiting shelf-life claims for ultra-premium export grades.
Strategic Opportunities
- Southeast Asia Direct-to-Consumer Channels:Singapore and Vietnam urban consumers now purchase vacuum-sealed scallops through seafood subscription platforms, bypassing traditional wet-market intermediaries entirely.
- USDA FSIS Value-Added Certification:Breaded and sauced scallop products fall under dual FDA-USDA jurisdiction, creating compliance complexity that specialized co-packers can monetize as a service offering.
- Blockchain Traceability Integration:Harvest-to-retail digital ledgers are converging with Internet-of-Things temperature loggers to create premium pricing tiers for verifiable cold-chain compliance.
Industry Challenges
- HACCP Plan Auditor Shortage:Qualified seafood safety plan reviewers are concentrated in coastal regulatory offices, creating 90-day backlog delays for new facility certifications.
- Legacy ERP Integration:Batch-oriented inventory systems at established processors struggle to accommodate real-time sensor data streams from smart packaging, requiring middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry-Packaged Scallops Market |
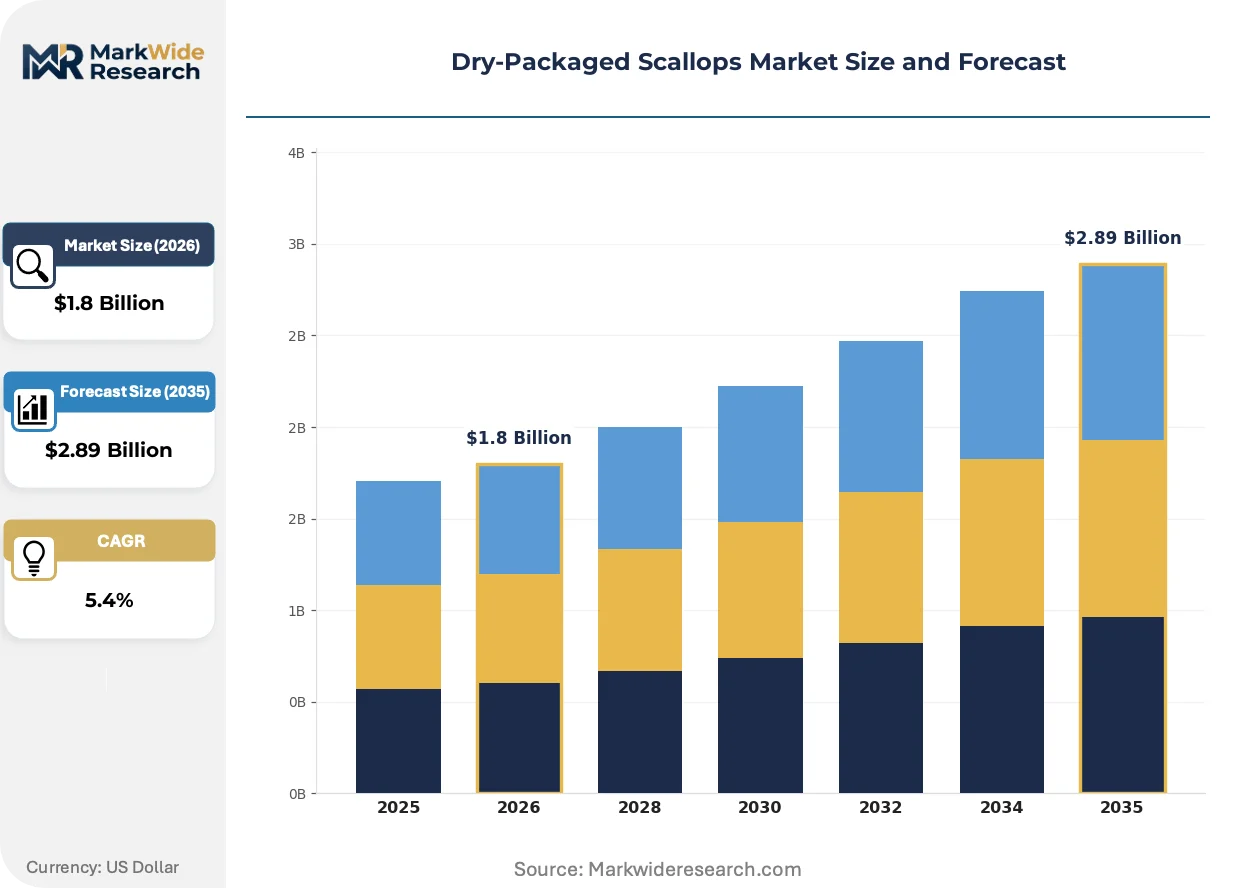
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.89 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen, Dried, Smoked, Breaded Packaging Type: Vacuum Seal, Resealable Bags, Cans, Pouches Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale End User: Restaurants, Home Cooks, Food Services, Catering |
| Companies Covered | Sea Watch International, Pacific Seafood Group, Clearwater Seafoods, High Liner Foods, Trident Seafoods Corporation, Maruha Nichiro Corporation, Blue Harvest Fisheries, Handy Seafood Incorporated, PanaPesca USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry-Packaged Scallops Market Shifts & Advancements
Processing automation and packaging material science are converging to redefine shelf-life benchmarks and traceability standards across the scallop supply chain.
Modified atmosphere packaging is migrating from nitrogen-dominant gas blends toward argon-carbon dioxide mixtures that better preserve texture in frozen bivalve tissue. Sushi-grade distributors in Osaka and Fukuoka now specify argon-flushed pouches for their high-turnover inventory. This migration from conventional gas blends is enabling 24-month shelf-life claims that command 15-20% price premiums in Asian wholesale markets.
Japan's Food Sanitation Act amendments now mandate moisture content labeling on all dried scallop imports, forcing export-oriented processors to reformulate dehydration protocols. The industrial consequence is accelerated adoption of controlled-environment drying rooms with precision humidity logging. Canadian and Alaskan processors targeting Japanese distribution channels are responding by installing in-house moisture analysis laboratories to preempt customs rejection.
Restaurant procurement departments are consolidating supplier relationships around vertically integrated harvest-process-distribute operations that guarantee year-round supply consistency. Independent brokers and spot-market buyers are losing share to long-term contractual arrangements with penalty clauses for temperature excursion events. This concentration is most visible in Tokyo's Tsukiji Outer Market, where large banquet hall operators now source exclusively from single-origin certified suppliers with full cold-chain documentation.
Dry-Packaged Scallops Market Segmentation
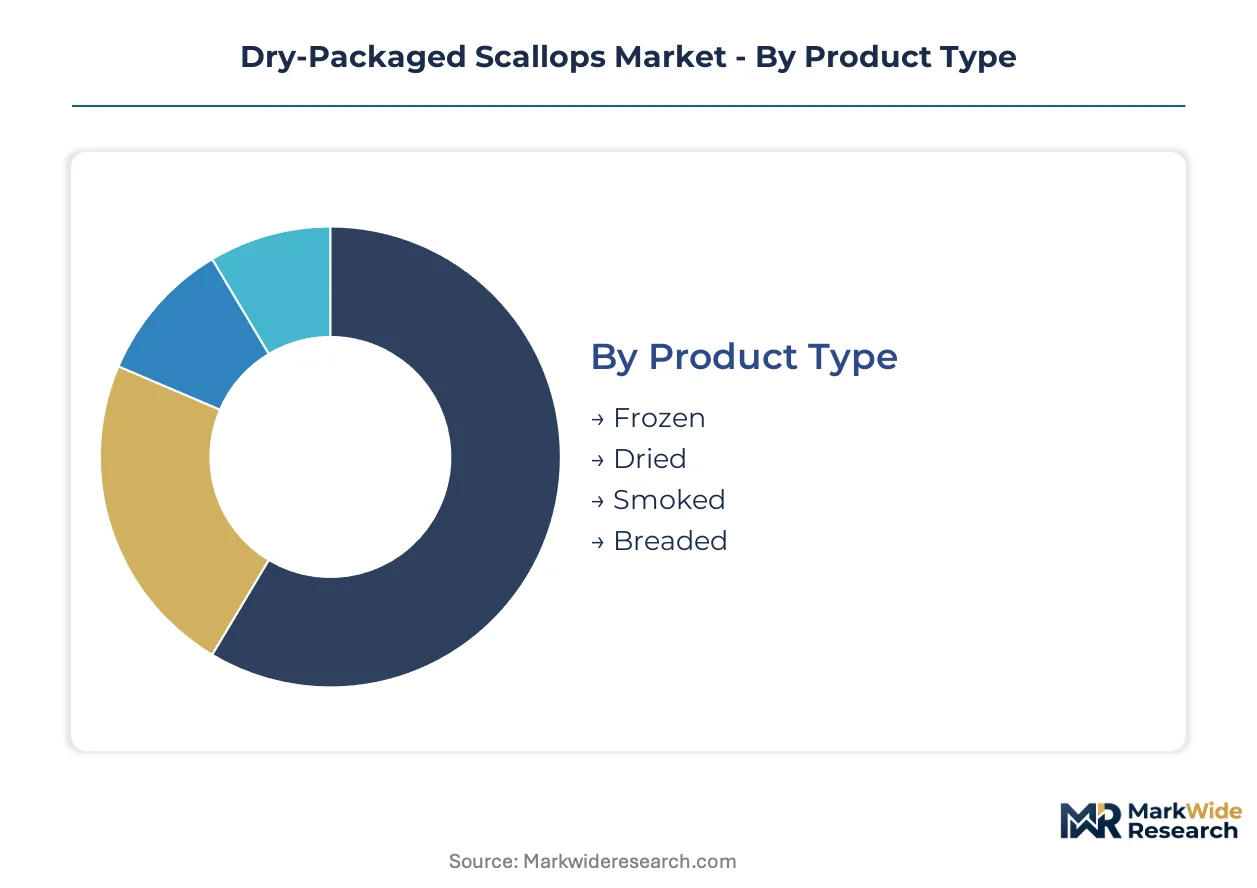
Dry-packaged scallops require distinct handling protocols across product formats, with frozen inventory demanding continuous cold-chain monitoring while dried variants need humidity-controlled storage. Packaging specifications directly determine shelf-life claims and regulatory compliance pathways. Distribution channel selection shapes margin capture, as food service bulk procurement operates on fundamentally different contract terms than direct-to-consumer retail.
Product Type:
After-sales service intensity varies sharply across preservation methods, with frozen products requiring temperature excursion investigations and dried formats needing moisture-content certification support for import clearance.
- Frozen:Flash-frozen at minus 40 degrees Celsius immediately post-harvest, these scallops retain cellular structure for raw preparations. Ghost kitchen operators in Singapore and centralized US commissaries specify 180-day minimum holding periods for inventory stability. Cold-chain documentation from blast freezer to final delivery dominates operational overhead.
- Dried:Controlled dehydration reduces moisture below 15 percent for traditional Japanese broth applications. Tokyo banquet halls and Osaka sushi chains drive specification tightening around moisture content labeling mandated by Japan's Food Sanitation Act amendments. Precision humidity logging during processing prevents customs rejection at Japanese ports.
- Smoked:Cold-smoked variants carry artisanal positioning for specialty retail channels in France and Spain.
- Breaded:Value-added formats trigger dual FDA-USDA jurisdiction compliance complexity for US processors.
Frozen holds the largest share; momentum sits with dried formats climbing the fastest on Japanese import demand.
Packaging Type:
Cost tier stratification separates premium gas-flushed barrier films from commodity formats, with equipment amortization driving per-unit economics at different production scales.
- Vacuum Seal:Modified atmosphere systems using argon-carbon dioxide blends arrest enzymatic browning in premium grades. High-turnover sushi distributors in Fukuoka now specify this specification for 24-month shelf-life claims commanding price premiums. Gas-flushing equipment costs pass through to wholesale pricing.
- Resealable Bags:Zip-lock closures target home cooks seeking portion control without dedicated vacuum equipment. Direct-to-consumer subscription platforms in Vietnam and Singapore favor this format for last-mile delivery convenience. Consumer preference for resealability drives format selection over barrier performance alone.
- Cans:Metal packaging persists in institutional procurement for extended ambient storage.
- Pouches:Flexible formats reduce shipping cube for export-bound containers from Alaskan processors.
Vacuum seal captures margin concentration; pouches gain share fastest on logistics efficiency.
Distribution Channel:
Volume concentration centers on contractual wholesale arrangements with penalty clauses for temperature excursions, while customer type fragmentation creates divergent service requirements.
- Wholesale:Food service distributors consolidate supplier relationships around vertically integrated harvest-process-distribute operations. Large banquet hall operators at Tokyo's Tsukiji Outer Market now source exclusively from single-origin certified suppliers. Long-term contracts displace spot-market procurement for supply consistency.
- Online Retail:Seafood subscription platforms in Singapore and Vietnam urban centers bypass traditional wet-market intermediaries entirely. Home cooks seeking restaurant-grade delivery drive steepest expansion trajectory among all channels. Last-mile cold-chain integrity remains the operational constraint.
- Supermarkets:Mass retail requires case-ready packaging with consumer-facing labeling compliance.
- Specialty Stores:Premium independent retailers emphasize provenance storytelling for high-margin positioning.
Wholesale dominates tonnage flow; online retail expands most quickly on subscription model adoption.
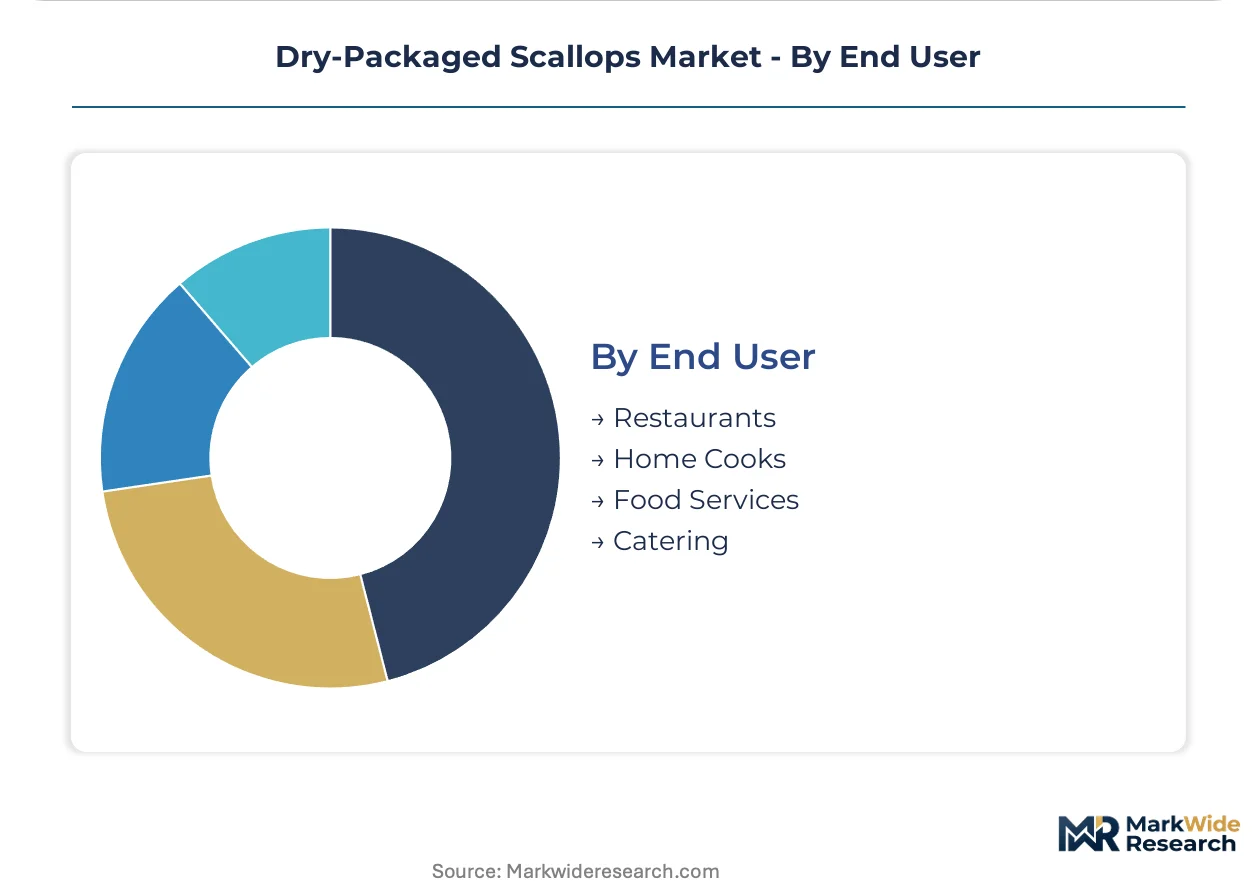
End User:
Application maturity separates established food service procurement from emerging home cook segments, with specification complexity varying by preparation method and volume scale.
- Restaurants:Commercial kitchens require stable protein inventory without live-shellfish logistics complexity. Sushi-grade distributors specify argon-flushed packaging for raw preparation integrity. Procurement departments consolidate around suppliers with full cold-chain documentation.
- Food Services:Institutional operators including hospitals and corporate cafeterias favor frozen formats for standardized portion control and extended holding periods. Centralized commissary models favor bulk vacuum formats over convenience-oriented pouches. HACCP plan compliance documentation is mandatory.
- Home Cooks:Direct purchasing through e-commerce channels expands as consumers seek restaurant-grade seafood delivery.
- Catering:Event-based demand creates volume spikes requiring flexible supplier responsiveness.
Restaurants anchor commercial demand; home cooks represent the fastest-climbing segment on delivery platform expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian and Alaskan processors dominate export flows to Japanese buyers, where dried scallop imports support traditional banquet preparation and high-end sushi service.
United States
Atlantic sea scallop quotas from NOAA Fisheries constrain raw material availability for New England processors, creating seasonal input cost volatility. FDA HACCP mandates require time-temperature documentation from harvest through retail. Boston-area distributors consolidate supplier relationships around vertically integrated operations with full cold-chain traceability.
Japan
Tokyo banquet halls and Osaka sushi chains drive specification tightening for dried scallop moisture content. METI-administered Food Sanitation Act amendments mandate precision labeling that shapes export-bound product formulation. Tsukiji Outer Market operators now source exclusively from single-origin certified suppliers with verifiable documentation.
Canada
Offshore harvesting and in-house processing control anchor supply consistency for Asian export channels. Canadian Food Inspection Agency seafood safety protocols align with Japanese import requirements. Nova Scotia and Newfoundland processing clusters install in-house moisture analysis laboratories to preempt customs rejection.
Singapore
Urban consumers purchase vacuum-sealed scallops through seafood subscription platforms, bypassing traditional wet-market intermediaries. Singapore Food Agency cold-chain regulations govern last-mile delivery integrity for direct-to-consumer channels. Centralized fulfillment hubs in Jurong and Tuas support rapid subscription model expansion.
Vietnam
Ho Chi Minh City home cooks seek restaurant-grade seafood delivery through e-commerce platforms. Vietnam Food Administration packaging standards shape import requirements for vacuum-sealed formats. Da Nang and Hai Phong processing zones emerge as consolidation points for re-export to Southeast Asian markets.
Dry-Packaged Scallops Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base separates into vertically integrated harvest-process-distribute operations, mid-scale freezing-packaging specialists, and value-added co-packers navigating dual FDA-USDA jurisdiction. Strategic moves concentrate on backward integration into offshore harvesting assets and geographic expansion into Southeast Asian direct-to-consumer channels.
Among North American vertically integrated operators, Sea Watch International and Clearwater Seafoods occupy positions defined by year-round supply consistency and cold-chain control. Trident Seafoods Corporation represents Alaska-origin sourcing archetypes with wholesale channel relationships. These three exemplify how scale-driven players anchor market structure through contractual arrangements with penalty clauses for temperature excursion events.
| Leading Market Players |
|---|
| Sea Watch International |
| Pacific Seafood Group |
| Clearwater Seafoods |
| High Liner Foods |
| Trident Seafoods Corporation |
| Maruha Nichiro Corporation |
| Blue Harvest Fisheries |
| Handy Seafood Incorporated |
| PanaPesca USA |
| Others |
Supply & Pricing Matrix
NOAA Fisheries quota volatility for Atlantic sea scallops compresses both margin buffers for New England processors and procurement flexibility for food service distributors, forcing pricing stratification across frozen, dried, and value-added formats while reshaping sourcing networks toward Alaskan and Canadian supply anchors.
Pricing Analysis
Gas-flushing equipment costs separate argon-modified atmosphere packaging from legacy nitrogen systems, with premium grades commanding sustained markups in Tokyo sushi supply chains while commodity frozen formats face cost compression from energy-intensive blast freezing operations. Price differentiation hinges on JIS-compliant moisture certification for Japanese export grades and HACCP documentation depth for food service contracts. Pricing pressure stems from natural gas price swings at integrated freezing facilities. Ghost kitchen operators exhibit highest price sensitivity; Tsukiji Outer Market banquet halls show lowest elasticity for single-origin certified supply.
Supply Chain Analysis
Extended payment terms from Japanese import distributors now reach 90-120 days, straining working capital for mid-scale Nova Scotia processors without supply-chain finance facilities. Raw material flows concentrate in United States Atlantic waters, Canadian offshore banks, and Alaskan Bering Sea harvesting zones. Blast freezing capacity, argon gas supply contracts, and multi-layer barrier film stockpiles constitute critical input dependencies. Single-source vulnerability sits with NOAA quota decisions that constrain New England landings. Distribution runs through vertically integrated harvest-process-distribute operations with cold-chain documentation mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified HACCP plan auditors concentrated in coastal regulatory offices create 90-day certification backlogs that throttle facility expansion timelines and reward processors with in-house compliance expertise.
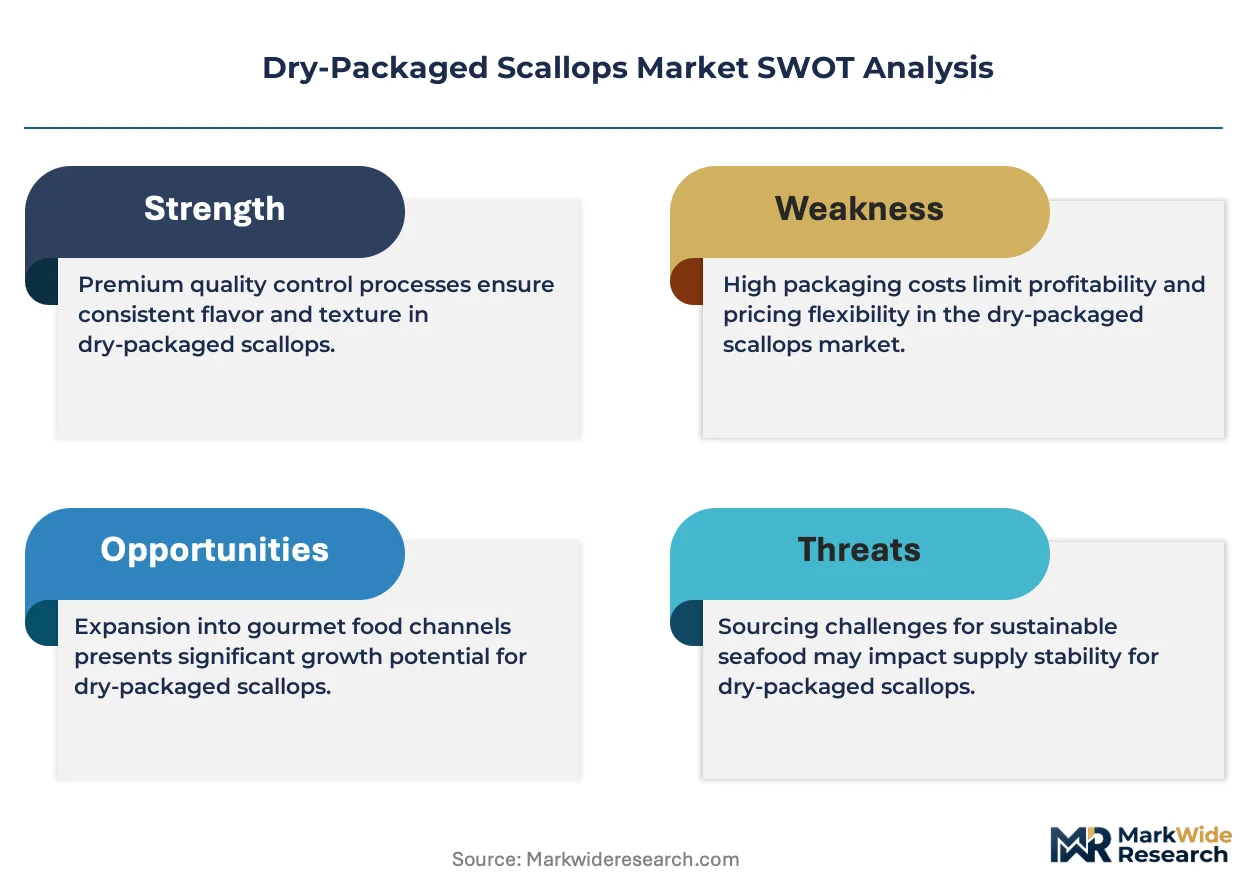
For Market Incumbents: Harden cold-chain documentation capabilities through sensor-enabled packaging integration and in-house moisture analysis laboratories to preempt Japanese customs rejection. Anchor procurement relationships with long-term contractual arrangements featuring temperature excursion penalty clauses that independent brokers cannot match. Threat substitution from blockchain-traceability entrants demands defensive certification investment. For New Entrants and Emerging Players: Southeast Asian direct-to-consumer subscription channels in Singapore and Vietnam represent the most penetrable entry point, bypassing entrenched wet-market intermediaries and traditional wholesale distribution chokepoints. Smoked and artisanal-positioned formats for European specialty retail offer secondary white-space with lower capital requirements than frozen infrastructure. Go-to-market execution should prioritize last-mile cold-chain partnerships with Jurong and Tuas fulfillment hub operators. For Investors and Strategic Acquirers: Mid-scale freezing-packaging specialists with dormant Alaskan harvesting permits but underutilized argon-flushing capacity present asymmetric upside if Southeast Asian subscription demand sustains expansion. Long-term viability rests on backward integration into offshore harvesting assets that insulate against NOAA quota volatility. Watch for Japanese Food Sanitation Act enforcement intensity at Osaka and Fukuoka entry points as inflection signal for compliance-cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Argon-Modified Atmosphere Packaging Deployment | Tokyo sushi chains now specify argon-flushed pouches for 24-month shelf-life claims commanding price premiums. |
| In-House Moisture Analysis Laboratory Investment | Canadian and Alaskan processors preempt Japanese customs rejection through precision humidity logging capabilities. |
| Blockchain Traceability Integration | Harvest-to-retail digital ledgers with IoT temperature loggers create premium pricing tiers for verifiable cold-chain compliance. |
| Southeast Asian Direct-to-Consumer Channel Expansion | Singapore and Vietnam subscription platforms bypass traditional wet-market intermediaries entirely for urban home cooks. |
| Backward Integration into Offshore Harvesting Assets | Year-round supply consistency guarantees displace spot-market procurement for Tsukiji Outer Market banquet hall operators. |
Research Methodology
Desk research of FDA HACCP guidance documents, NOAA Fisheries catch statistics, and Japanese Food Sanitation Act regulatory filings preceded structured interviews with seafood processing plant managers, cold-chain logistics coordinators, Tokyo-based import distributors, and food service procurement directors at centralized commissary operators. Secondary validation drew from customs trade data, CFIA seafood safety protocols, and Singapore Food Agency cold-chain regulations. Bottom-up volume modeling across frozen, dried, smoked, and breaded product formats triangulated against top-down market sizing from export flow analysis.
Assumption sets held Japanese import demand growth and FDA enforcement intensity constant while varying Atlantic sea scallop quota levels, natural gas price trajectories, and Southeast Asian e-commerce penetration rates across the analysis window. Segmentation dimensions included preservation method, packaging technology tier, distribution channel structure, and end-user application maturity. CAGRs derived from historical volume trajectories adjusted for structural shifts in ghost kitchen procurement patterns and subscription platform adoption curves. Forecast inputs incorporated blast freezing capacity utilization rates and argon gas supply contract pricing trends.
Practitioners should monitor NOAA Fisheries quota announcement timing, Japanese customs enforcement intensity at Osaka and Fukuoka ports, and Singapore Food Agency cold-chain regulation amendments for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Smoked Salmon Market
Seafood
Vietnam Pangasius (Basa) Market
Seafood
Global Seafood Market
Seafood
Organic Seafood Market
Seafood
Tinned Fish Market
Seafood
Canned Seafood Market
Seafood
Canned Tuna Market
Seafood
Fish Hydrolysate Market
Seafood
Fried Dace with Salted Black Beans Market
Seafood
Rainbow Trout Market
Seafood
Alaskan Salmon Market
Seafood
North America Frozen Seafood Market
Seafood
Herring Market
Seafood
Halibut Market
Seafood
Mussels Market
Seafood
Fish Protein Hydrolysate Market