
 United States Seafood Market | 2026-2036
United States Seafood Market Size, Share, and Industry Trends Forecast 2026-2036
United States Seafood Market Analytics
NOAA Fisheries traceability mandates and the Marine Mammal Protection Act import rules is consolidating compliance burdens across the import-dependent supply chain. Trident Seafoods leverages its Alaska-based vertical processing network to control documentation from harvest to distribution. Pacific Seafood Group sustains its West Coast dominance through integrated cold-chain logistics spanning Oregon and Washington ports. Thai Union, operating the Chicken of the Sea brand, competes on retail shelf stability while navigating stricter federal catch-certification protocols.
United States Seafood encompasses finfish, shellfish, and mollusks harvested from marine, freshwater, and aquaculture sources, processed to specifications ranging from whole-round fresh product to individually quick-frozen fillets with protein content typically exceeding 18 percent by weight. The category serves commercial foodservice, retail grocery, and industrial ingredient channels requiring HACCP-compliant handling throughout temperature-controlled distribution. Fish and shrimp together anchor volume throughput across Gulf and Alaskan landing points, while frozen form commands the largest share of retail and foodservice procurement due to extended shelf life and reduced spoilage risk. Online distribution channels represent the fastest-growing access point, though foodservice institutions still capture the highest per-transaction value and margin concentration.
FDA seafood HACCP regulations, NOAA Fisheries trade monitoring programs, and the Lacey Act enforcement framework collectively determine market access for both domestic harvesters and import suppliers. These standards elevate compliance costs for smaller distributors while advantaging scaled operators with dedicated quality-assurance infrastructure. Stakeholders must weigh capital allocation between traceability technology upgrades and geographic diversification of sourcing regions as federal enforcement intensifies.
Market Dynamics
NOAA Fisheries traceability mandates are compressing documentation timelines across import-dependent supply chains, forcing distributors to reallocate capital from inventory holding to compliance infrastructure before the next enforcement phase takes effect.
Growth Catalysts
- Marine Mammal Protection Act import rules:Buyers now demand pre-certified supply chains, accelerating consolidation among Alaska-based harvesters who control documentation from catch to customs.
- Foodservice menu expansion:Restaurant chains in the Gulf Coast corridor are adding traceable finfish and shellfish lines, pulling volume through Louisiana and Florida processing ports.
- Cold-chain logistics integration:Refrigerated warehousing networks spanning Oregon and Washington ports now handle frozen fillet throughput at scale, reducing spoilage loss below fresh-only alternatives.
Market Restraints
- Fuel cost volatility:Diesel prices for Gulf and Alaskan fishing vessel operations swing unpredictably, compressing margins for independent harvesters without fuel-hedging programs.
- Import concentration risk:Shrimp supply chains remain heavily dependent on Southeast Asian processing hubs, exposing distributors to customs delays when NOAA documentation audits intensify.
- HACCP compliance friction:FDA seafood safety protocols require continuous temperature monitoring infrastructure that smaller distributors cannot finance, accelerating exit rates among sub-scale operators.
Strategic Opportunities
- Direct-to-consumer channels:Online seafood subscription services bypass traditional retail markup structures, capturing margin that previously flowed to grocery intermediaries.
- IRA climate resilience grants:Federal funding streams support refrigerated infrastructure upgrades in hurricane-vulnerable Gulf Coast processing zones, lowering working capital requirements for facility modernization.
- Blockchain-traceability convergence:Distributed ledger systems interfacing with NOAA catch documentation are creating immutable supply chain records that command premium positioning in institutional procurement.
Industry Challenges
- HACCP auditor scarcity:FDA-qualified seafood safety specialists concentrate in coastal metropolitan areas, leaving inland distribution hubs underserved for compliance verification.
- Legacy ERP integration:Temperature-monitoring IoT sensors must interface with decades-old inventory management systems, creating data fragmentation that obscures real-time spoilage risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Seafood Market |
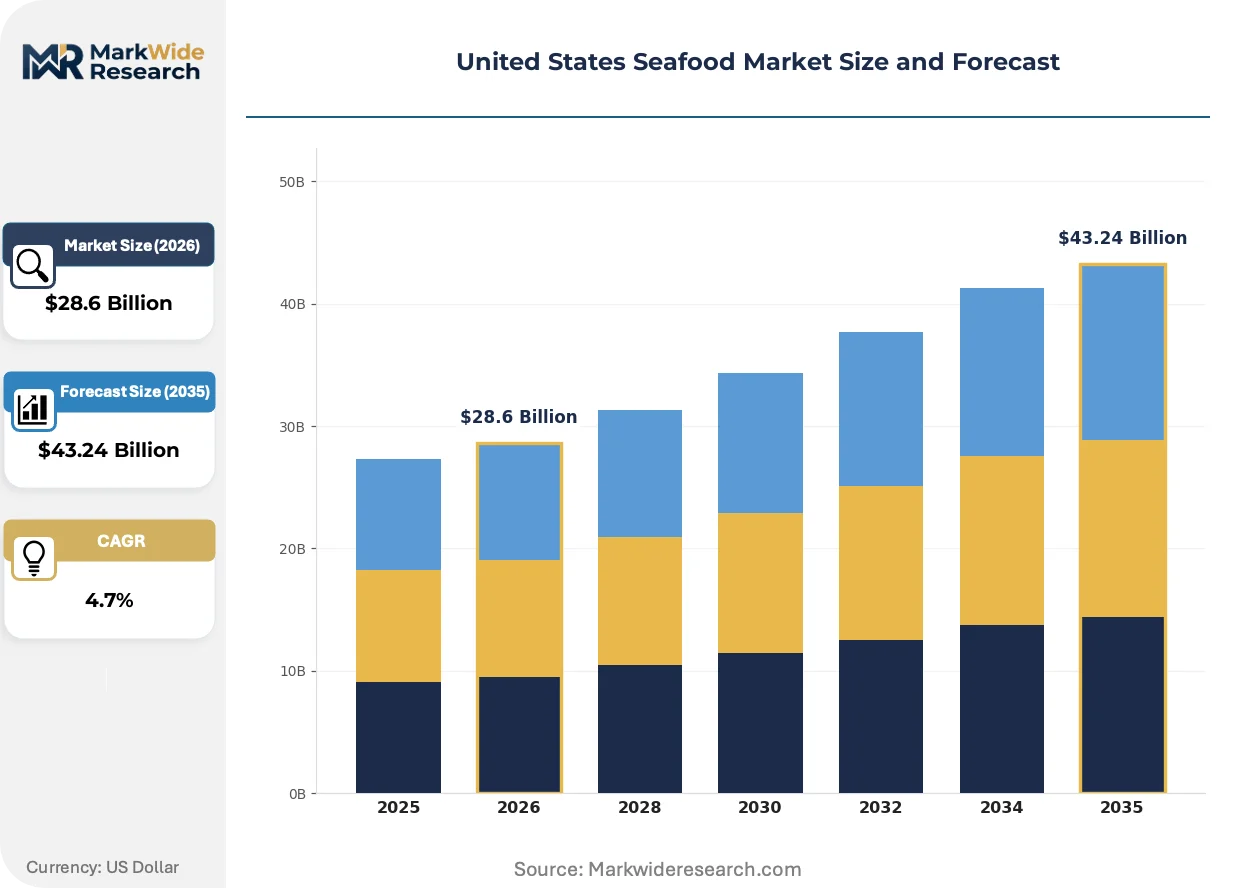
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
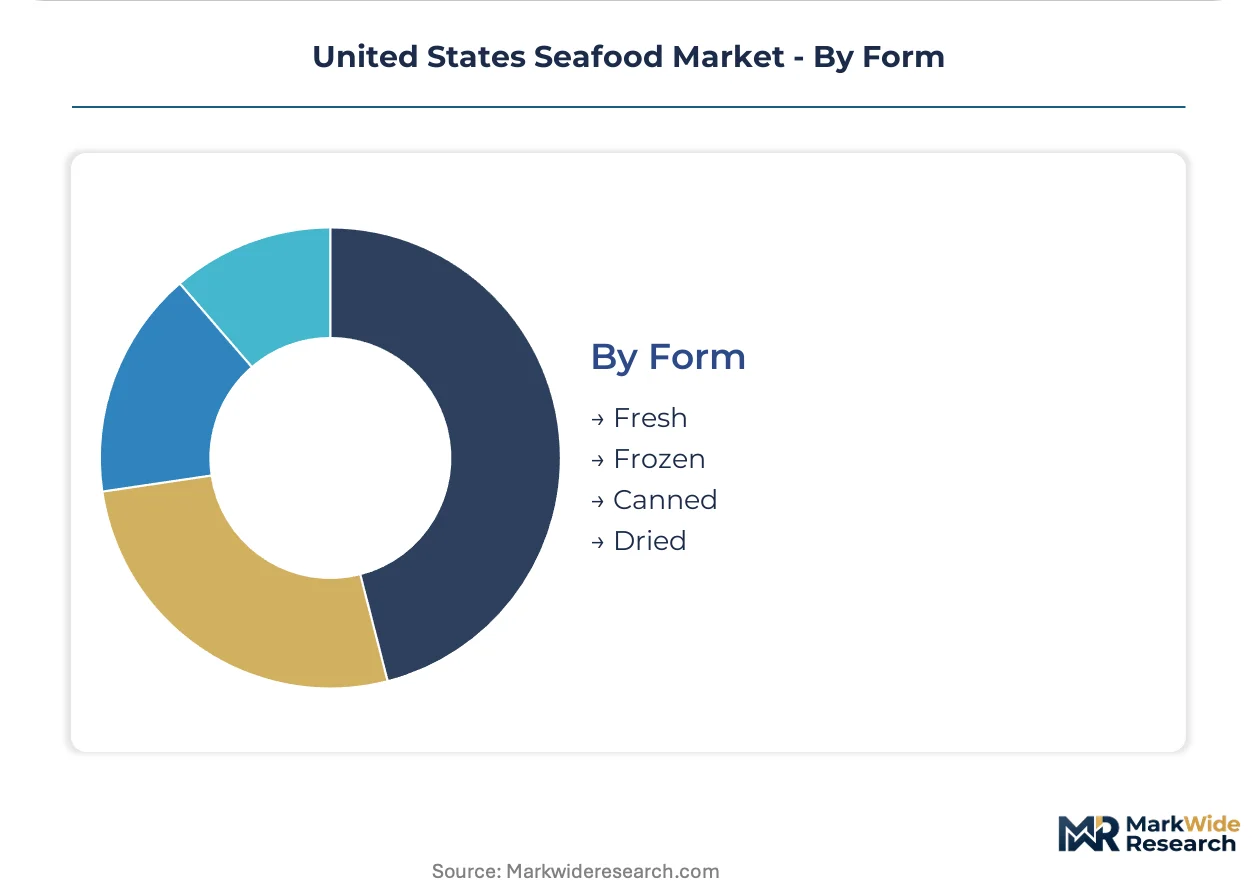
| Segmentation | Product Type: Fish, Shrimp, Crustaceans, Mollusks Distribution Channel: Retail, Wholesale, Online, Food Service End User: Restaurants, Households, Food Processors, Institutions Form: Fresh, Frozen, Canned, Dried |
| Companies Covered | Trident Seafoods, Pacific Seafood Group, Thai Union (Chicken of the Sea), Mowi USA, American Seafoods Group, New England Seafoods Group, High Liner Foods, Beaver Street Fisheries, Mazzetta Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Seafood Market Evolving Landscape
Digital traceability systems are compressing the time between harvest verification and retail shelf placement, eliminating information asymmetry that previously obscured origin claims and handling conditions.
Blockchain-based catch documentation is rewriting how institutional buyers validate supply chain integrity. Large foodservice contractors now require immutable ledger records as a condition of vendor qualification, compressing approval timelines from months to weeks. This technology is rewriting competitive access rules by disqualifying harvesters without digital infrastructure from premium contract pools.
FDA enforcement of seafood HACCP regulations is intensifying documentation requirements for foreign supplier verification. Importers must now maintain continuous temperature logs from processing plant to port of entry, elevating compliance costs for smaller trading houses. Alaskan vertically integrated operators are responding by marketing their domestic origin as a regulatory bypass advantage.
Foodservice procurement teams are consolidating vendor relationships around suppliers offering combined fresh-frozen-aquaculture portfolios. Large restaurant chains now demand single-source accountability across protein categories, displacing fragmented buying from specialized seafood-only distributors. This pattern is most visible in the Gulf Coast institutional corridor, where hospital and university buyers have reduced approved vendor lists by half since traceability mandates took effect.
United States Seafood Market Segmentation

Segmentation in United States seafood markets determines capital allocation across temperature-controlled infrastructure, processing equipment, and regulatory compliance systems. Each dimension carries distinct margin profiles and certification burdens that reshape competitive positioning.
Product Type:
Fish and shrimp segments demand the heaviest upfront investment in vessel fleets, onboard freezing systems, and dockside processing plants.
- Fish:Finfish categories including salmon, cod, and tuna require longline or trawl harvesting equipment with hold refrigeration capacity exceeding 50 tons. Alaska-based catcher-processor vessels dominate domestic supply, with Gulf Coast landings concentrating snapper and grouper through Louisiana ports. FDA HACCP protocols mandate continuous temperature logging from harvest through fillet fabrication.
- Shrimp:Wild-caught and farm-raised varieties move through separate supply chains, with warm-water species landing in Texas and Florida while cold-water imports clear through Pacific Northwest ports. NOAA import documentation rules impose traceability costs that disadvantage smaller distributors without dedicated compliance staff.
- Crustaceans:Crab and lobster operations require specialized pot gear and live-hold tanks with circulating seawater systems.
- Mollusks:Oyster and clam harvesting depends on state-leased bed rights and depuration facilities for post-harvest purification.
Most installed capacity flows through Fish. Expansion is steepest in Shrimp.
Distribution Channel:
Channel selection dictates working capital intensity, with inventory turns varying from daily in foodservice to seasonal in retail.
- Retail:Grocery chains and club stores demand case-ready packaging with barcode traceability and extended shelf-life dating. Frozen fillet SKUs dominate volume, with private-label programs compressing margins for branded suppliers. Refrigerated distribution centers in the Midwest and Southeast handle break-bulk consolidation.
- Food Service:Broadline distributors and specialty seafood purveyors service restaurants, hospitals, and universities with portion-controlled products and just-in-time delivery windows. Gulf Coast institutional buyers now require single-source documentation from harvest to plate.
- Wholesale:Terminal markets and cash-and-carry operations supply smaller retailers and ethnic foodservice operators with minimal packaging overhead.
- Online:Direct-to-consumer subscription models bypass traditional markup layers, capturing margin through temperature-controlled parcel shipping.
Food Service channels command the highest per-transaction value. Online distribution is gaining share fastest.
End User:
User category determines product specification complexity, from commodity portions for processors to live-tank delivery for premium restaurants.
- Restaurants:Full-service and quick-service operators specify exact weight ranges, skin-on or skin-off presentation, and certifiable origin for menu claims. Chain expansion in the Gulf Coast corridor drives volume through Louisiana and Florida processing hubs.
- Institutions:Hospital, university, and military buyers consolidate procurement around approved vendor lists with mandatory HACCP certification and allergen controls.
- Households:Consumer purchasing concentrates in retail frozen and canned categories with extended storage stability.
- Food Processors:Industrial buyers purchase block-frozen raw material for further processing into value-added products.
Restaurants absorb the largest volume share. Institutions are expanding procurement fastest.
Form:
Processing intensity varies dramatically, from minimal-handling fresh product to retort-sterilized shelf-stable formats.
- Frozen:Individually quick-frozen fillets and shell-on shrimp dominate commercial throughput, with blast-freezing operations concentrated in Alaska and Gulf Coast ports. Extended shelf life reduces spoilage risk and enables inventory positioning ahead of seasonal demand peaks.
- Fresh:Never-frozen product commands price premiums in white-tablecloth restaurants and specialty retail, requiring rapid turnover and cold-chain integrity through distribution. Pacific Seafood Group and similar integrated operators control freshness through captive logistics networks.
- Canned:Tuna and salmon retort processing delivers ambient stability for retail and emergency food programs.
- Dried:Salted and smoked varieties serve ethnic market niches with minimal refrigerated handling requirements.
Frozen form carries the greatest installed capacity. Fresh product is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alaska's fishing workforce and Gulf Coast processing labor pools anchor domestic seafood production capacity, with specialized vessel crews and dockside technicians concentrated in coastal corridors from Kodiak to Louisiana.
Alaska
Alaska's catcher-processor fleet supplies the majority of domestic wild-caught finfish, with pollock and salmon landings driving volume through Dutch Harbor and Kodiak ports. NOAA Fisheries catch share programs regulate harvest allocations through the North Pacific Fishery Management Council. Trident Seafoods operates integrated processing facilities in Ketchikan and Akutan, controlling documentation from harvest through cold-chain distribution to lower-48 markets.
Louisiana
Louisiana's Gulf Coast processing corridor handles shrimp, crab, and finfish landings from federal waters stretching from Texas to Florida. FDA HACCP enforcement mandates continuous temperature monitoring for all seafood entering interstate commerce. New Orleans and Houma serve as consolidation points for Gulf-caught product destined for institutional foodservice buyers throughout the Southeast.
Washington
Washington's Pacific Coast ports manage cold-chain logistics for both domestic Alaskan landings and Asian import volumes through Seattle-Tacoma terminals. The state's Department of Health enforces shellfish safety standards for farmed and wild bivalve harvests. Pacific Seafood Group maintains refrigerated warehousing networks spanning Puget Sound, enabling rapid distribution of fresh and frozen product to West Coast retail and foodservice accounts.
Florida
Florida's peninsula location positions the state as a transshipment hub for Caribbean and Latin American seafood imports entering Gulf and Atlantic distribution networks. Marine Mammal Protection Act import documentation requirements are enforced through Miami and Tampa customs districts. Tampa Bay processing facilities specialize in warm-water shrimp and spiny lobster distribution to restaurant chains throughout the Southeast.
Massachusetts
Massachusetts retains specialized capacity for Atlantic groundfish and scallop processing despite declining domestic fleet size. NOAA Northeast Fisheries Science Center stock assessments determine annual catch limits for cod and haddock under Magnuson-Stevens Act rebuilding mandates. New Bedford maintains the highest-value seafood landing port in the nation through scallop quota concentration and specialized auction infrastructure.
United States Seafood Market Competitive Landscape
Capital-heavy producers with captive vessel fleets and processing plants compete with asset-light distributors who source through contract arrangements and terminal market purchases. The market structure tilts toward consolidation at the harvest and primary processing tiers, while distribution remains fragmented among regional specialty purveyors and broadline foodservice operators. Two strategic archetypes dominate: vertically integrated harvester-processors controlling documentation from catch to customer, and logistics-focused distributors aggregating multiple species through cold-chain networks. Competitive positioning hinges on M&A activity consolidating quota holdings and strategic partnerships securing preferential access to institutional procurement channels.
Among Alaska-based integrated operators, Trident Seafoods and American Seafoods Group exemplify the harvester-processor archetype, while Pacific Seafood Group anchors West Coast distribution networks. Thai Union, operating the Chicken of the Sea brand, occupies a position bridging retail shelf-stable production with import sourcing compliance. These three companies represent contrasting responses to NOAA traceability mandates: domestic vertical integration versus import-dependent scale economies.
| Leading Market Players |
|---|
| Trident Seafoods |
| Pacific Seafood Group |
| Thai Union (Chicken of the Sea) |
| Mowi USA |
| American Seafoods Group |
| New England Seafoods Group |
| High Liner Foods |
| Beaver Street Fisheries |
| Mazzetta Company |
| Others |
Value Network & Pricing Analysis
Family-owned Gulf Coast processors anchor supply discipline through generational quota holdings, translating captive dockside access into pricing power over foodservice buyers who lack alternative sourcing for HACCP-certified domestic shrimp and finfish. This ownership pattern insulates harvesters from margin compression while forcing distributors to absorb compliance cost escalations from NOAA traceability mandates.
Pricing Analysis
Fresh-never-frozen product commands unbundled premiums from white-tablecloth restaurants, while frozen fillets sell through bundled contract structures with broadline distributors. Pricing stratifies across premium, standard, and economy tiers based on certification grade and geographic delivery cost. Cost compression in economy-tier imported shrimp is intensifying because Southeast Asian processors face escalating NOAA documentation audits. Institutional buyers exhibit the highest price sensitivity due to consolidated procurement mandates, while specialty retailers absorb premiums for traceable domestic origin.
Supply Chain Analysis
Direct-to-foodservice channels handle hyperscale institutional demand through just-in-time refrigerated distribution, while retail consolidation flows through break-bulk centers in the Midwest and Southeast. Supply concentrates in Alaska for domestic wild-caught finfish and in Thailand, Vietnam, and Ecuador for warm-water shrimp imports. Raw material flows draw from North Pacific pollock stocks, Gulf menhaden reduction fisheries, and Southeast Asian aquaculture ponds. Single-source vulnerability in Asian shrimp processing exposes distributors to customs clearance delays when Marine Mammal Protection Act documentation audits intensify.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Alaska's regulatory-certain domestic harvest and Southeast Asia's compliance-uncertain import channels, with cost differentials widening as NOAA enforcement phases tighten documentation timelines.
For Market Incumbents: Deploy backward integration into vessel quota holdings to lock harvest access before federal catch share allocations tighten. Consolidate around cold-chain infrastructure in hurricane-vulnerable Gulf zones using IRA climate resilience grants to defray modernization costs. Defensive positioning requires preemptive blockchain-traceability investment to disqualify smaller competitors from institutional procurement pools when immutable ledger records become mandatory qualification criteria. For New Entrants and Emerging Players: Ethnic foodservice operators in inland distribution hubs represent an underserved buyer archetype bypassed by coastal-focused incumbents. Direct-to-consumer subscription models capture margin from grocery intermediaries while bypassing HACCP auditor scarcity constraints that handicap smaller distributors. White-space penetration targets online channels and regional wholesale terminal markets with minimal packaging overhead requirements. For Investors and Strategic Acquirers: Broadline foodservice distributors is the most active acquirer in this space, consolidating fragmented regional seafood purveyors to secure single-source vendor status with hospital and university buyers. Long-term viability hinges on quota-concentrated harvester-processors with captive Alaskan or Gulf Coast infrastructure. Monitor FDA enforcement intensity around foreign supplier verification programs as the inflection signal for import-dependent distributor distress.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quota Holdings | Secures harvest access under NOAA catch share programs tightening allocation windows. |
| Blockchain-Traceability Deployment | Creates immutable ledger records qualifying suppliers for premium institutional contracts. |
| Direct-to-Consumer Channel Launch | Bypasses retail markup structures while capturing margin through temperature-controlled parcel shipping. |
| IRA-Funded Cold-Chain Modernization | Lowers working capital requirements for Gulf Coast facility upgrades in hurricane zones. |
| Institutional Procurement Consolidation | Reduces approved vendor lists by half while demanding single-source accountability across protein categories. |
Research Methodology
Direct dialogue with catcher-processor vessel operators, broadline distributor procurement directors, institutional foodservice buyers, and FDA HACCP compliance auditors grounded qualitative findings in operational reality. Secondary validation drew from NOAA Fisheries trade monitoring databases, FDA seafood import refusal records, customs clearance data through Seattle-Tacoma and Miami-Tampa ports, and refrigerated warehousing capacity reports. Bottom-up volume estimates from species-level landing data triangulated against top-down market sizing from foodservice procurement spend analysis.
Bottom-up modeling aggregated vessel-level harvest capacity, processing plant throughput, and cold-chain distribution reach across Alaska, Gulf Coast, and Pacific Northwest corridors. Top-down analysis calibrated against institutional foodservice procurement patterns, retail scanner data for frozen seafood SKUs, and online subscription service growth trajectories. Segmentation dimensions included product type, form, distribution channel, and end-user category. CAGR derivation incorporated historical landing volatility, regulatory phase-in schedules, and buyer consolidation trends throughout the projection horizon.
Underlying measurement precision varies by segment; frozen form and retail channel data carry tighter precision than fresh product and online distribution due to standardized reporting requirements. Forecasts reflect assumptions around NOAA enforcement intensity, fuel cost stability for vessel operations, and HACCP auditor availability in inland markets. Periodic stress-testing of base assumptions is recommended given regulatory uncertainty around Marine Mammal Protection Act implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Global Seafood Market
Seafood
Fried Dace with Salted Black Beans Market
Seafood
Oyster Market
Seafood
Sea Biscuits Market
Seafood
North America Tuna Market
Seafood
Fish Oil Market
Seafood
Fish Processing Market
Seafood
Fish Nutrition Market
Seafood
Dry-Packaged Scallops Market
Seafood
Mussel Oil Market
Seafood
Fish Protein Concentrate Market
Seafood
Striped Bass Market
Seafood
Krill Meal Market
Seafood
United States Salmon Market
Seafood
Tinned Fish Market
Seafood
Toothfish Market