
 North America Tuna Market | 2026-2036
North America Tuna Market Size, Share, and Industry Trends Forecast 2026-2036
North America Tuna Market Intelligence
Asset-light leasing arrangements for refrigerated processing vessels is rewriting competitive entry barriers in North American tuna supply. Bumble Bee Foods leverages its vertically integrated cold-chain infrastructure to sustain shelf-stable dominance. Wild Planet Foods differentiates through pole-and-line sourcing claims that anchor premium positioning in natural retail channels.
North America tuna comprises several commercially harvested Thunnus and Katsuwonus species valued for protein density, omega-3 fatty acid profiles, and sashimi-grade fat content measured by oil distribution and color scoring. Canned tuna occupies the largest volume position due to pantry-stocking patterns and extended shelf stability, while fresh tuna commands the highest per-unit margins through direct restaurant supply and specialty retail. Frozen tuna sustains export flows to Asian processing hubs, and smoked tuna extends value capture in delicates
FDA seafood HACCP regulations, NOAA fisheries management standards, and Mexico's national aquaculture and fisheries commission guidelines collectively shape permissible catch methods, species labeling, and interstate commerce protocols across the regional market. Stakeholders must monitor evolving traceability mandates and quota allocations that determine raw material access and product-origin verifiability.
Market Dynamics
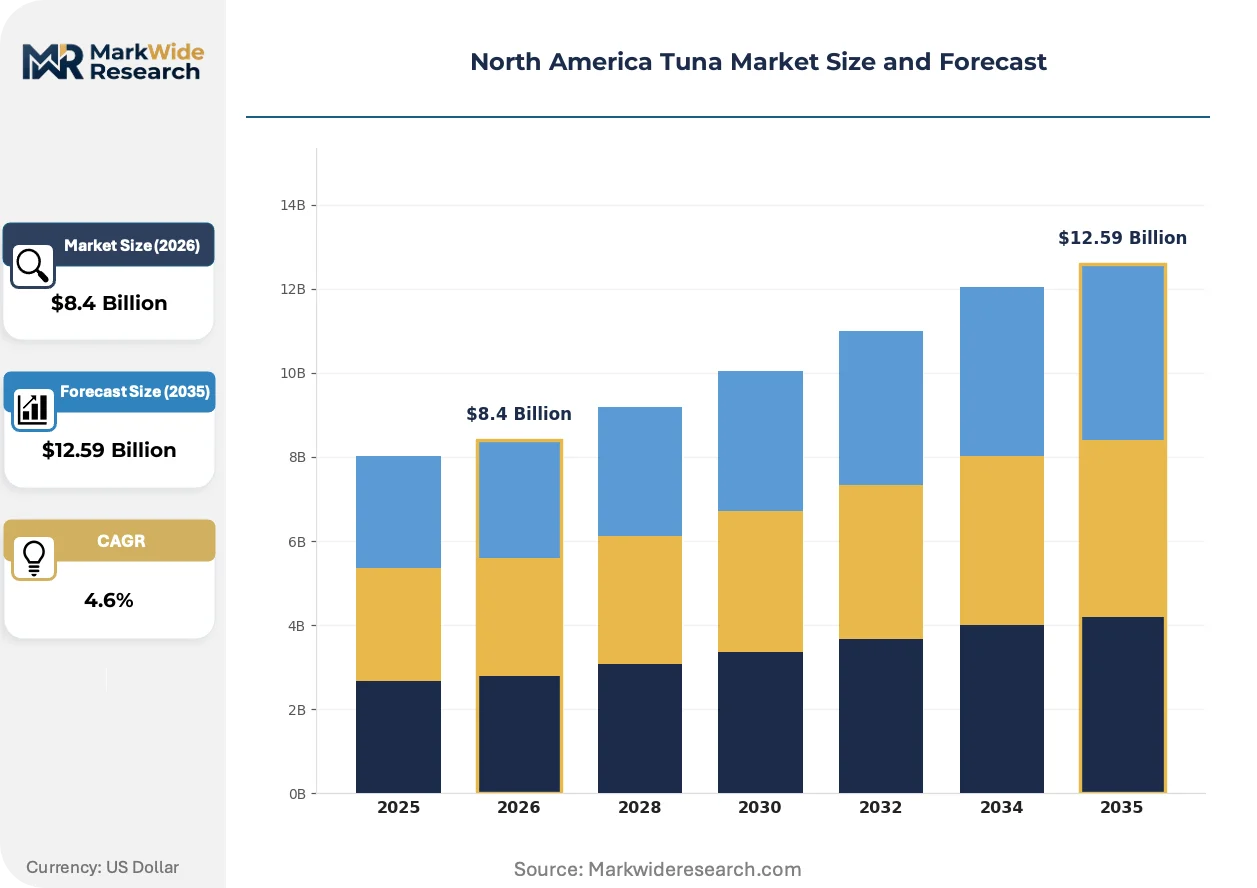
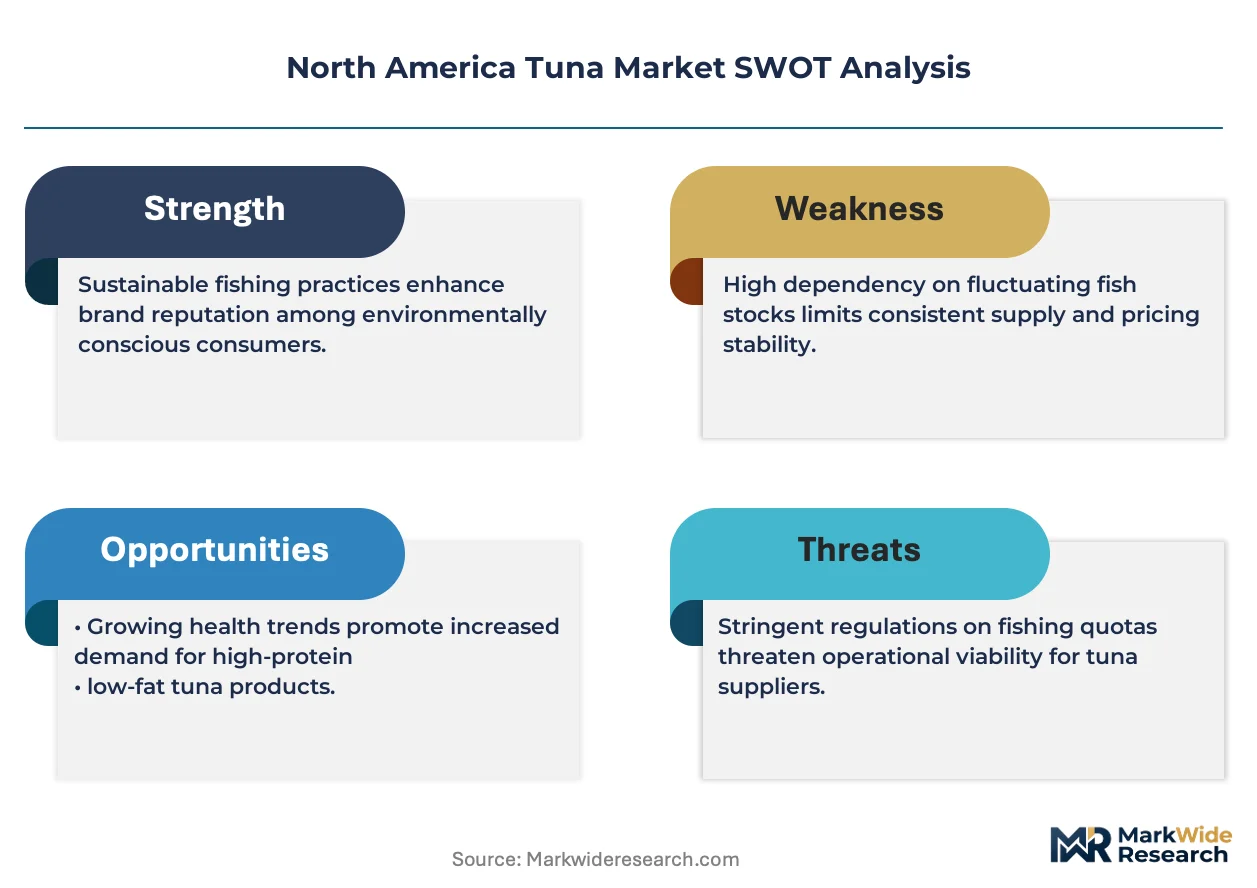
Asset-light vessel leasing is compressing capital barriers for new entrants while FDA traceability mandates force legacy operators into expensive cold-chain retrofits, creating asymmetric pressure across the North American tuna value chain.
Growth Catalysts
- Foodservice Premiumization:California's sushi and poke corridor drives sashimi-grade demand, pulling higher-margin product through direct restaurant supply channels.
- NOAA Fisheries Management Standards:Science-based quota allocations stabilize raw material access for domestic processors, reducing supply volatility versus unregulated waters.
- Omega-3 Positioning:Health-conscious retail buyers prioritize protein density and fatty acid profiles, expanding shelf space for premium canned and frozen formats.
Market Restraints
- Fuel Cost Volatility:Diesel price swings directly compress margins for distant-water purse-seine operators dependent on Pacific high-seas transit.
- Import Concentration Risk:Frozen loin supply from Southeast Asian processing hubs creates single-source vulnerability for US canneries.
- Technical Shelf-Life Limitations:Fresh tuna's narrow color-scoring window restricts distribution radius regardless of cold-chain investment.
Strategic Opportunities
- Mexico Underpenetration:Baja California's emerging aquaculture infrastructure offers nearshored grow-out capacity for US market access.
- Direct-to-Restaurant Platforms:Digital procurement portals bypass traditional seafood distributors, capturing margin for vertically integrated harvesters.
- IRA Clean Energy Incentives:Cold-chain refrigeration retrofits qualify for tax credits, offsetting FDA compliance costs for mid-sized processors.
Industry Challenges
- HACCP Specialist Scarcity:Qualified seafood safety auditors command premium wages, slowing facility certification timelines for new market entrants.
- Legacy Traceability Integration:Paper-based catch documentation systems resist digitization, creating audit gaps under FDA's updated fish and fishery products guidance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Tuna Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.59 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Tuna, Frozen Tuna, Canned Tuna, Smoked Tuna End User: Retail, Food Service, Exporters, Seafood Markets Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale Packaging Type: Glass Jar, Plastic Container, Vacuum Pack, Canned |
| Companies Covered | Chicken of the Sea, Wild Planet Foods, Thai Union Group PCL, Century Pacific Food, American Tuna, Bumble Bee Foods, Ocean Brands, Crown Prince Inc., StarKist Co., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Tuna Market Strategic Shifts & Innovations
Electronic monitoring systems and blockchain traceability protocols are converging to satisfy tightening provenance requirements while automation reshapes labor-intensive processing economics.
Blockchain-enabled supply chain verification is rendering obsolete paper-based catch documentation for high-value sashimi-grade tuna. West Coast specialty retailers and fast-casual poke chains are mandating digital provenance records as a procurement condition. This compression of verification timelines is rendering obsolete the multi-week documentation lags that previously delayed customs clearance for fresh imports.
Canada's PMRA residue monitoring protocols and the FDA's updated fish and fishery products guidance are tightening maximum allowable contaminant thresholds for imported species. Domestic canneries face reformulation costs to meet combined US-Canada standards for mercury and histamine limits. Smoked and value-added processors in the Pacific Northwest are responding by sourcing exclusively from pole-and-line fisheries with pre-certified testing documentation.
Restaurant procurement teams are consolidating supplier relationships around vertically integrated harvesters with captive cold-chain capacity. This concentration is displacing fragmented distributor networks that previously aggregated product from multiple sources. The shift is most visible in California's Los Angeles-San Francisco corridor, where direct vessel-to-restaurant contracts now govern premium yellowfin and bigeye supply.
North America Tuna Market Segmentation
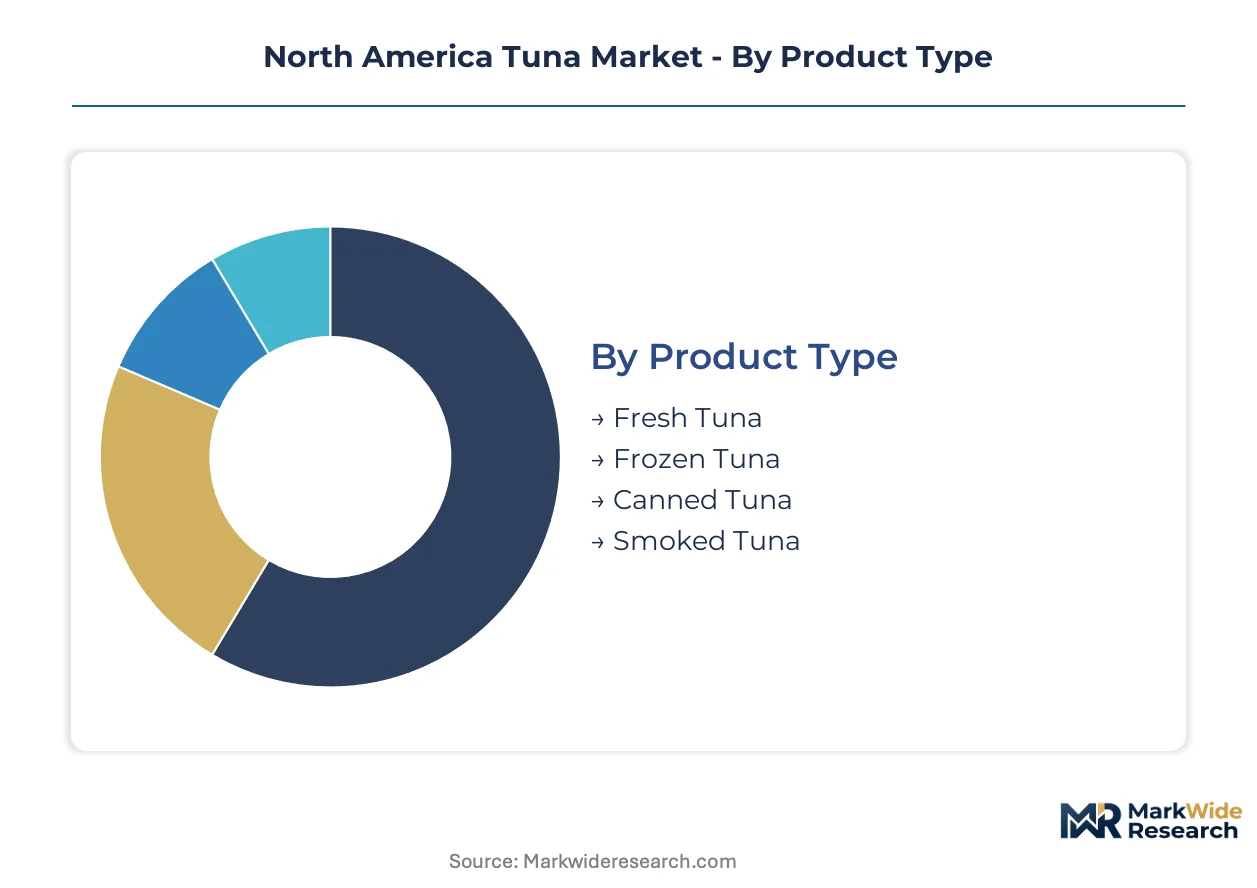
Segmentation in North American tuna reveals how product form dictates margin capture, regulatory exposure, and cold-chain investment intensity. Each dimension—product type, end user, distribution channel, and packaging—carries distinct velocity profiles and compliance burdens that reshape competitive positioning across the value chain.
Product Type:
Cycle times vary dramatically: fresh tuna turns in 48-72 hours from landing to plate, while canned inventory rotates over quarters. Frozen occupies the middle ground with monthly velocity, and smoked formats extend shelf life into years.
- Fresh Tuna:Sashimi-grade yellowfin and bigeye command premium pricing through direct vessel-to-restaurant contracts in California's Los Angeles-San Francisco corridor. Color-scoring windows measured in hours restrict distribution radius regardless of cold-chain investment, compressing margin recovery to high-density urban clusters.
- Canned Tuna:Shelf-stable skipjack and albacore sustain pantry-stocking patterns across mass retail, with Bumble Bee Foods leveraging vertically integrated cold-chain infrastructure to defend volume leadership. Extended stability enables inventory buffering against raw material price swings from Southeast Asian processing hubs.
- Frozen Tuna:Loin and whole-fish formats sustain export flows to Asian secondary processing facilities, with NOAA fisheries management standards stabilizing quota-based raw material access for domestic harvesters.
- Smoked Tuna:Value-added Pacific Northwest processors source exclusively from pole-and-line fisheries with pre-certified testing documentation to meet combined US-Canada contaminant thresholds.
Canned tuna dominates installed base. Fresh tuna is where expansion concentrates.
End User:
Margin tiers separate commodity absorption from premium extraction: retail moves volume at thin spreads, food service captures fat content premiums, exporters arbitrage currency and quota differentials, and seafood markets intermediate freshness claims.
- Food Service:California's sushi and poke restaurant corridor pulls sashimi-grade product through direct supply channels, with digital procurement portals displacing traditional seafood distributors. Menu premiumization across fast-casual chains is expanding placement of higher oil-content species.
- Retail:Natural channel buyers prioritize pole-and-line sourcing claims that anchor Wild Planet Foods' positioning, while conventional grocers rotate canned inventory on promotional calendars tied to pantry-stocking seasons.
- Exporters:Frozen loin shipments to Asian processing hubs create single-source vulnerability for US canneries, with customs clearance timelines compressing under blockchain-enabled verification mandates.
- Seafood Markets:Independent mongers in coastal cities intermediate freshness narratives through direct dock relationships, though HACCP specialist scarcity slows facility certification for new market entrants.
Retail commands volume leadership. Food service is climbing the fastest.
Distribution Channel:
Channel selection determines traceability burden and working capital intensity: wholesale aggregates fragmented supply, supermarkets demand SKU breadth, convenience stores prioritize shelf-stable formats, and online retail imposes last-mile cold-chain costs.
- Supermarkets:Multi-format placement spanning canned, frozen, and fresh cases requires compliance with FDA's updated fish and fishery products guidance across temperature zones, favoring operators with captive cold-chain capacity.
- Wholesale:Traditional distributor networks aggregate product from multiple sources, though restaurant procurement teams are consolidating around vertically integrated harvesters with direct vessel relationships.
- Online Retail:Direct-to-consumer frozen and shelf-stable shipments face last-mile refrigeration costs that erode margin on low-unit-value canned formats.
- Convenience Stores:Grab-and-go smoked and shelf-stable pouches align with immediate consumption patterns, though limited cold storage restricts fresh and frozen placement.
Supermarkets anchor channel volume. Online retail is gaining share fastest.
Packaging Type:
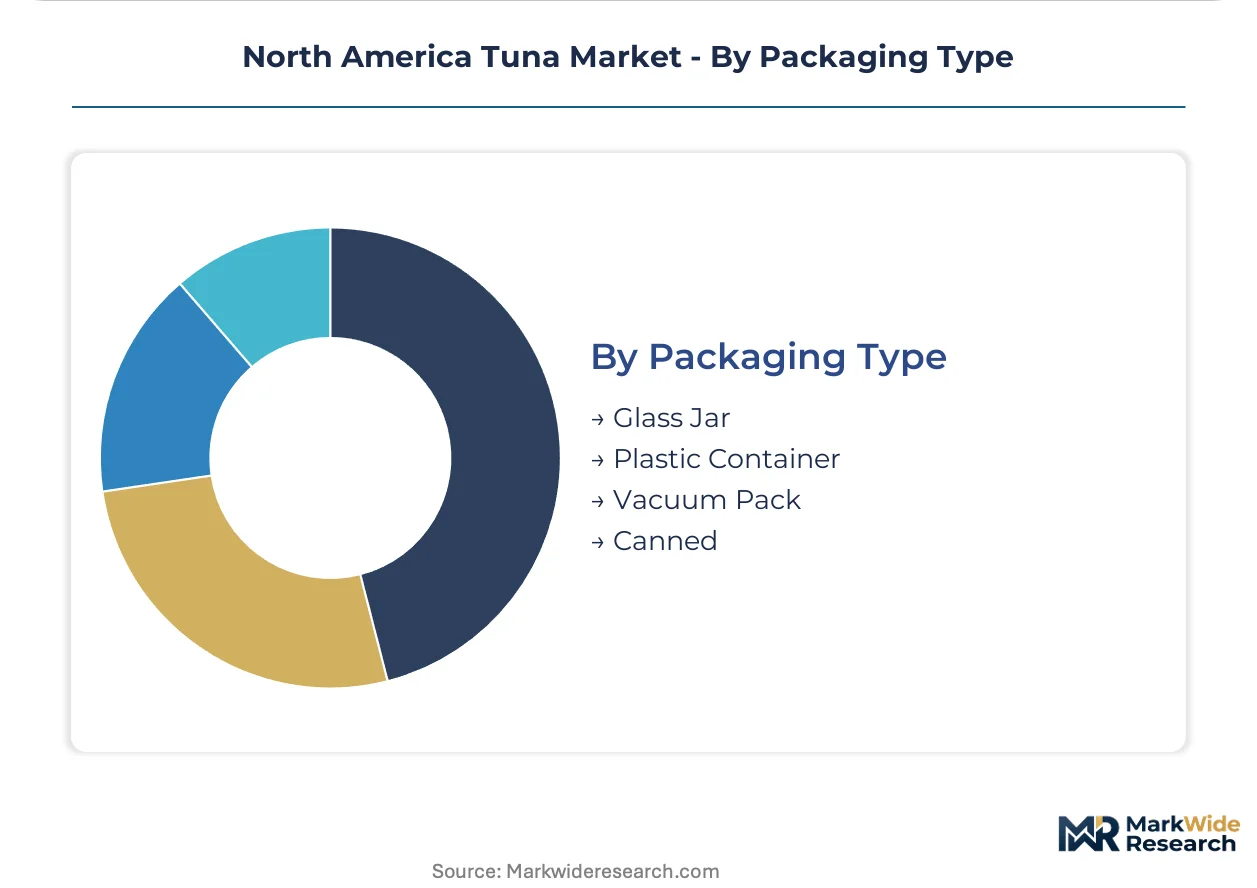
Material and seal technology dictate shelf-life extension and premium positioning: vacuum packs preserve color scoring, glass jars signal artisan smoking, plastic enables portion flexibility, and traditional cans defend cost efficiency.
- Vacuum Pack:Modified atmosphere sealing extends fresh tuna's color-scoring window from hours to days, enabling wider distribution radius for sashimi-grade product to inland markets.
- Canned:Double-seam steel construction sustains shelf stability across temperature excursions, supporting pantry-stocking patterns and disaster preparedness demand spikes.
- Glass Jar:Artisan smoked presentations in Pacific Northwest specialty retail command visual premium through transparency, though weight increases freight cost versus flexible alternatives.
- Plastic Container:Resealable pouches and trays enable portion-controlled fresh and smoked formats for single-person households, with recyclability pressures mounting under IRA clean energy incentive frameworks.
Canned packaging dominates installed base. Vacuum pack is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IRA clean energy incentives for cold-chain refrigeration retrofits are reshaping processor economics across the continent, while FDA traceability mandates compress customs clearance timelines for fresh imports. Regional demand concentrates in coastal urban corridors with direct dock-to-restaurant infrastructure.
United States
California's Los Angeles-San Francisco sushi and poke corridor pulls sashimi-grade yellowfin and bigeye through direct vessel-to-restaurant contracts. FDA's updated fish and fishery products guidance tightens documentation requirements for imported species, forcing legacy operators into expensive digitization. The Pacific Northwest hosts value-added smoked tuna processors sourcing exclusively from pole-and-line fisheries with pre-certified testing documentation.
Canada
Health Canada's PMRA residue monitoring protocols tighten maximum allowable contaminant thresholds for mercury and histamine, elevating sourcing standards for cross-border cannery supply. British Columbia's coastal processing facilities face HACCP specialist scarcity that slows facility certification timelines. Atlantic Canada sustains frozen loin export flows to Asian secondary processing hubs under NOAA fisheries management standards.
Mexico
Baja California's emerging aquaculture infrastructure offers nearshored grow-out capacity for US market access, reducing transit-dependent spoilage risk. Mexico's national aquaculture and fisheries commission guidelines shape permissible catch methods and species labeling for interstate commerce. The Yucatán Peninsula sustains traditional line-caught supply for premium US retail channels demanding pole-and-line sourcing claims.
Texas Gulf Coast
Houston's refrigerated logistics hub intermediates frozen tuna shipments from Southeast Asian processing centers to interior US markets. The state's energy sector workforce scarcity spills into cold-chain technician hiring, compressing facility expansion timelines. Corpus Christi vessel operators leverage asset-light leasing arrangements to reduce capital barriers for distant-water purse-seine deployment.
North America Tuna Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered margin positions in North American tuna supply. Consolidation pressure concentrates around vertically integrated cold-chain operators capable of satisfying FDA traceability mandates, while mid-sized processors face asymmetric compliance burdens. Three archetypes dominate: shelf-stable volume leaders, premium sourcing specialists, and Asian-integrated supply aggregators. Competitive moves center on backward integration into vessel capacity and geographic diversification of processing footprint.
Within the premium sourcing tier, Wild Planet Foods exemplifies pole-and-line positioning for natural retail channels, while Bumble Bee Foods anchors shelf-stable dominance through captive cold-chain infrastructure. Among Asian-integrated operators, Thai Union Group PCL occupies a position linking Southeast Asian processing hubs to North American distribution networks.
| Leading Market Players |
|---|
| Chicken of the Sea |
| Wild Planet Foods |
| Thai Union Group PCL |
| Century Pacific Food |
| American Tuna |
| Bumble Bee Foods |
| Ocean Brands |
| Crown Prince Inc. |
| StarKist Co. |
| Others |
Cost & Logistics Intelligence
Single-source dependency on Southeast Asian frozen loin supply creates asymmetric pricing power for integrated processors while forcing US canneries into long-term offtake contracts that lock in margin compression. This structural concentration simultaneously widens spreads between commodity canned tiers and premium fresh segments while reshaping cold-chain investment priorities across the value chain.
Pricing Analysis
Certification level under FDA's updated fish and fishery products guidance creates the primary spread between premium sashimi-grade and commodity canned tiers. Pole-and-line sourcing claims anchor Wild Planet Foods' three-tier pricing structure across premium, standard, and economy levels in natural retail channels. Cost compression in canned skipjack intensifies because Thai Union Group PCL's Asian-integrated supply aggregators leverage scale economies. Retail buyers show highest price sensitivity for shelf-stable formats, while California's sushi corridor absorbs fat-content premiums with minimal elasticity.
Supply Chain Analysis
Extended payment terms from Southeast Asian processing hubs to US distributors compress working capital cycles for mid-sized canneries. Raw material flows draw from Thailand, Vietnam, and Indonesia for frozen loin supply, while fresh yellowfin and bigeye rest on Pacific distant-water purse-seine landings. Single-source vulnerability for frozen loin imports creates tariff exposure at customs clearance chokepoints. Distribution runs through Houston's refrigerated logistics hub to interior markets, with direct vessel-to-restaurant contracts displacing traditional wholesale aggregation in coastal corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Restaurant procurement consolidation around vertically integrated harvesters has shifted buyer power toward foodservice operators with captive cold-chain capacity, fragmenting distributor influence across the value chain.
For Market Incumbents: Pre-empt FDA traceability mandate compliance gaps by digitizing paper-based catch documentation systems before audit penalties accumulate. Anchor defensive positioning through backward integration into Baja California aquaculture infrastructure, securing nearshored grow-out capacity that reduces transit-dependent spoilage risk from distant-water sourcing. For New Entrants and Emerging Players: Establish a beachhead in Mexico's underpenetrated Yucatán Peninsula line-caught supply corridor, where traditional catch methods align with premium US retail sourcing claims. Digital procurement portals offer the most penetrable go-to-market angle, bypassing fragmented distributor networks to capture margin through direct vessel relationships with California's fast-casual poke chains. For Investors and Strategic Acquirers: The market sits at a compliance-investment phase that favors vertically integrated cold-chain operators capable of satisfying tightening provenance requirements. Long-term viability hinges on asset-light vessel leasing models that compress capital barriers while maintaining traceability standards. Watch blockchain-enabled supply chain verification adoption rates as the inflection indicator for premium segment margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vessel Capacity | Captive supply of sashimi-grade yellowfin secures direct restaurant contracts in California's Los Angeles-San Francisco corridor. |
| FDA Traceability Digitization | Blockchain-enabled documentation satisfies updated fish and fishery products guidance while compressing customs clearance timelines. |
| Baja California Aquaculture Expansion | Nearshored grow-out infrastructure reduces spoilage risk and qualifies for IRA clean energy refrigeration retrofit credits. |
| Pole-and-Line Certification Investment | Pre-certified testing documentation meets combined US-Canada contaminant thresholds for premium natural channel placement. |
| Direct-to-Restaurant Platform Launch | Digital procurement portals displace traditional seafood distributors and capture margin for vertically integrated harvesters. |
Research Approach
Cross-validation between NOAA fisheries landings data and FDA import refusal records anchors the qualitative findings on supply concentration and regulatory exposure. Primary interviews with distant-water vessel operators, cold-chain logistics managers, HACCP compliance officers, and fast-casual restaurant procurement directors combined with secondary validation from customs trade databases, SEC 10-K filings, and fisheries management council quota reports. Bottom-up triangulation across product type velocity profiles and top-down cross-check against regional consumption estimates shaped final projections.
Calibration against historical price spreads between fresh and canned tiers informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product form, end-user channel, distribution pathway, and packaging technology, with species-specific fat-content grading as an additional seafood-industry dimension. CAGRs derived from quota allocation trajectories, menu premiumization trends, and cold-chain infrastructure investment cycles.
Sensitivities concentrate around fuel cost volatility, FDA enforcement intensity on traceability mandates, and Pacific high-seas quota reallocation decisions. Forecasts reflect documented assumptions on conservation policy continuity and restaurant demand recovery trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Krill Meal Market
Seafood
Europe Seafood Market
Seafood
Molluscs Market
Seafood
Sea Bream Market
Seafood
Oyster Market
Seafood
North America Seafood Market
Seafood
North America Salmon Market
Seafood
Seafood Processing Market
Seafood
Fish Oil Market
Seafood
Fish Fermentation Market
Seafood
Tinned Fish Market
Seafood
Canned Tuna Market
Seafood
Global Smoked Fish Market
Seafood
Middle East and Africa Canned Seafood Market
Seafood
Latin America Salmon Market
Seafood
Asia-Pacific Shrimp Market