
 Hemp Seed Peptide Market | 2026-2036
Hemp Seed Peptide Market Size, Share, and Industry Trends Forecast 2026-2036
Hemp Seed Peptide Market Analytics
Modular sachet-to-pouch bundling is pivoting how fitness centers and sports enthusiasts purchase hemp seed peptides, shifting volume from single-unit bottles to subscription-ready multi-packs. Victory Hemp Foods leverages its heartland processing footprint to anchor supply reliability for North American buyers. Manitoba Harvest Hemp Foods sustains brand recognition across mass retail channels. Nutraonly (Xi'an) Nutritions Inc competes on concentrated isolate output for B2B ingredient buyers.
Hemp seed peptides comprise short-chain amino acid sequences derived from enzymatic hydrolysis of Cannabis sativa seed protein, typically yielding fractions below 10 kDa molecular weight with documented antioxidant and antihypertensive bioactivity. Their primary commercial purpose centers on delivering functional protein fortification in formats that bypass the gritty texture and digestibility limitations of intact hemp protein. Hydrolyzed peptides command premium positioning in sports nutrition due to rapid absorption kinetics, while cosmeceuticals represent an emerging margin pool as peptide suppliers validate collagen-stimulating claims through dermatological testing. Isolate powder dominates ingredient trade volumes for contract manufacturers seeking standardized protein content above 90 percent.
The FDA exercises jurisdiction over hemp seed peptide labeling and health claim substantiation under the Dietary Supplement Health and Education Act, while the USDA oversees organic certification pathways for hemp cultivation inputs. Health Canada and the EFSA impose parallel novel food approval requirements that filter which peptide fractions enter respective national supply chains. Stakeholders must monitor how regulatory divergence across these jurisdictions fragments formulation standardization and forces region-specific product registration strategies.
Market Dynamics
Enzymatic hydrolysis advances are compressing production costs for sub-10 kDa peptide fractions, while FDA novel food guidance creates divergent compliance burdens across export destinations. Contract manufacturers now demand standardized isolate specifications above 90% protein content, forcing ingredient suppliers to synchronize analytical methods.
Growth Catalysts
- Clean-label CPG procurement:Mass retail buyers specify hemp-derived peptides for plant-based recovery formulations, replacing soy and whey isolates in sports nutrition SKUs.
- USDA organic certification:Certified organic hemp cultivation inputs command premium positioning in North American contract manufacturing channels.
- Cosmeceutical bioactivity validation:Dermatological testing of collagen-stimulating claims opens margin pools beyond traditional nutrition applications.
Market Restraints
- EFSA novel food approval timelines:European peptide fraction entry requires 18-24 month safety dossier reviews, filtering supplier participation.
- Hemp protein concentrate substitution:Intact protein isolates at 60-70% lower unit cost satisfy basic fortification needs in cost-sensitive formulations.
- Heartland processing concentration:North American enzymatic hydrolysis capacity clusters in Kentucky and Manitoba, creating single-source exposure for buyers.
Strategic Opportunities
- Japanese functional food channel:FOSHU and Foods with Function Claims frameworks permit peptide-specific hypertension reduction labeling, unlike US structure-function restrictions.
- Precision fermentation convergence:Microbial peptide production platforms threaten to bypass agricultural hemp supply chains entirely for high-value cosmetic actives.
- Direct-to-practitioner distribution:Sports dietitians and clinical nutritionists prescribe peptide protocols, bypassing retail markup structures.
Industry Challenges
- Peptide sequence IP fragmentation:Patent thickets around specific antihypertensive fractions complicate freedom-to-operate analysis for new entrants.
- Batch-to-batch bioactivity variance:Enzymatic hydrolysis parameter sensitivity requires analytical chemistry skill gaps that contract labs struggle to fill.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemp Seed Peptide Market |
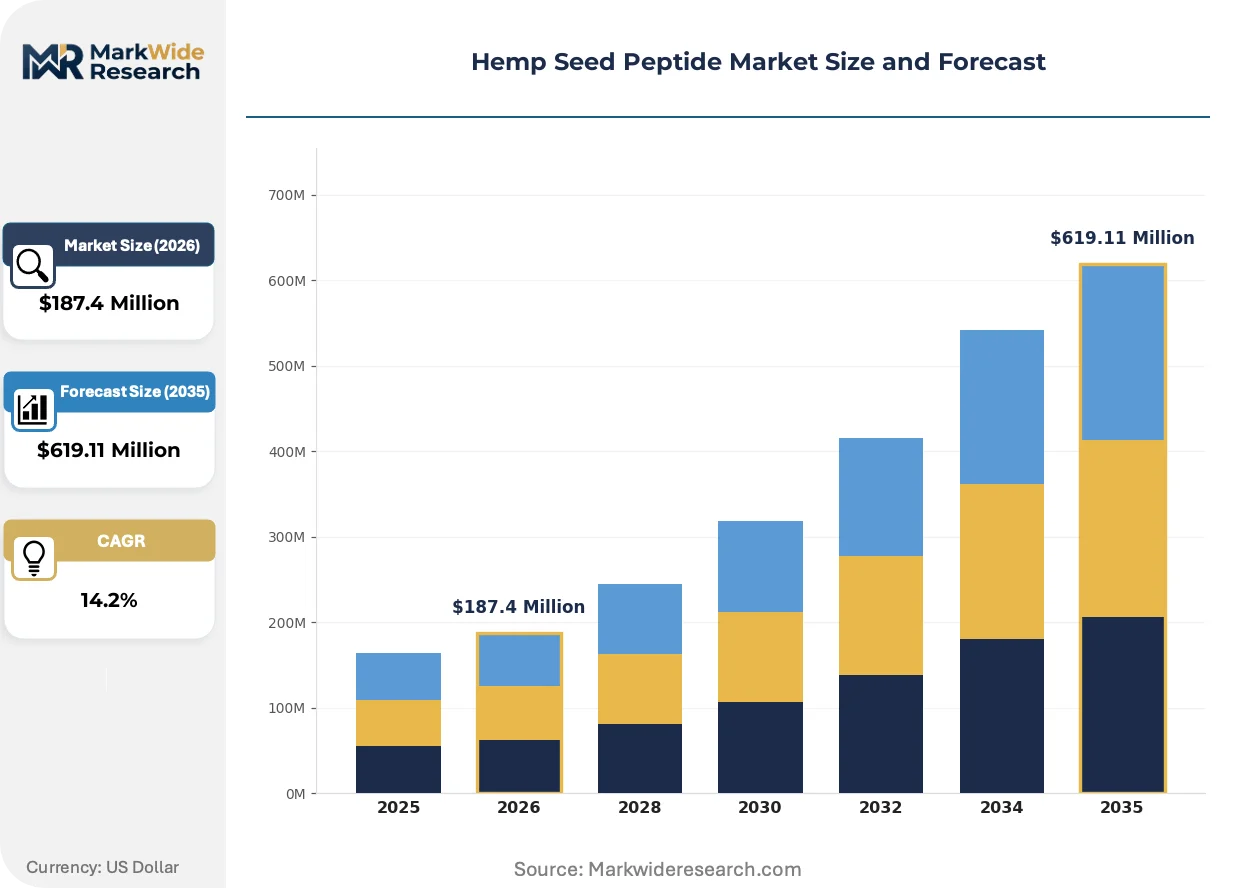
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Peptides, Isolate Powder, Concentrate Powder, Liquid Peptides Application: Nutritional Supplements, Functional Foods, Sports Nutrition, Cosmeceuticals End User: Healthcare, Sports Enthusiasts, Fitness Centers, Cosmetic Industry Packaging Type: Bottles, Pouches, Bulk Packaging, Sachets |
| Companies Covered | North American Hemp & Grain Co. Ltd, Victory Hemp Foods, Manitoba Harvest Hemp Foods, Navitas Organics, ETChem, Nutraonly (Xi'an) Nutritions Inc, Blue Sky Hemp Ventures, Axiom Foods Inc., Naturally Splendid Enterprises Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemp Seed Peptide Market Evolving Landscape
Peptide suppliers are reconfiguring around modular manufacturing footprints and regulatory science capabilities rather than commodity protein extraction. Three distinct vectors are compressing legacy business models.
Membrane filtration cascades with molecular weight cut-off specificity is modularizing how processors isolate sub-3 kDa antioxidant fractions from crude hydrolysates. Sports nutrition formulators adopt these standardized inputs at accelerating pace, enabling rapid SKU proliferation without reformulating base matrices. The technology is modularizing what previously required custom contract manufacturing relationships into catalog purchasing.
Health Canada's expanded novel food determination requirements for hemp-derived ingredients now mandate acute toxicity studies for peptide fractions above 5 kDa. This regulatory tightening forces exporters to maintain parallel dossier portfolios, fragmenting formulation standardization. Ingredient buyers serving Canadian CPG brands face extended qualification timelines that compress working capital efficiency.
Subscription bundling of sachet-to-pouch multi-packs is displacing single-unit bottle purchasing among fitness center operators and endurance sports clubs. This procurement model shift concentrates volume with direct-supply peptide processors capable of flexible batch sizing. The pattern is most visible in California and Colorado boutique gym chains that private-label recovery formulations.
Hemp Seed Peptide Market Segmentation
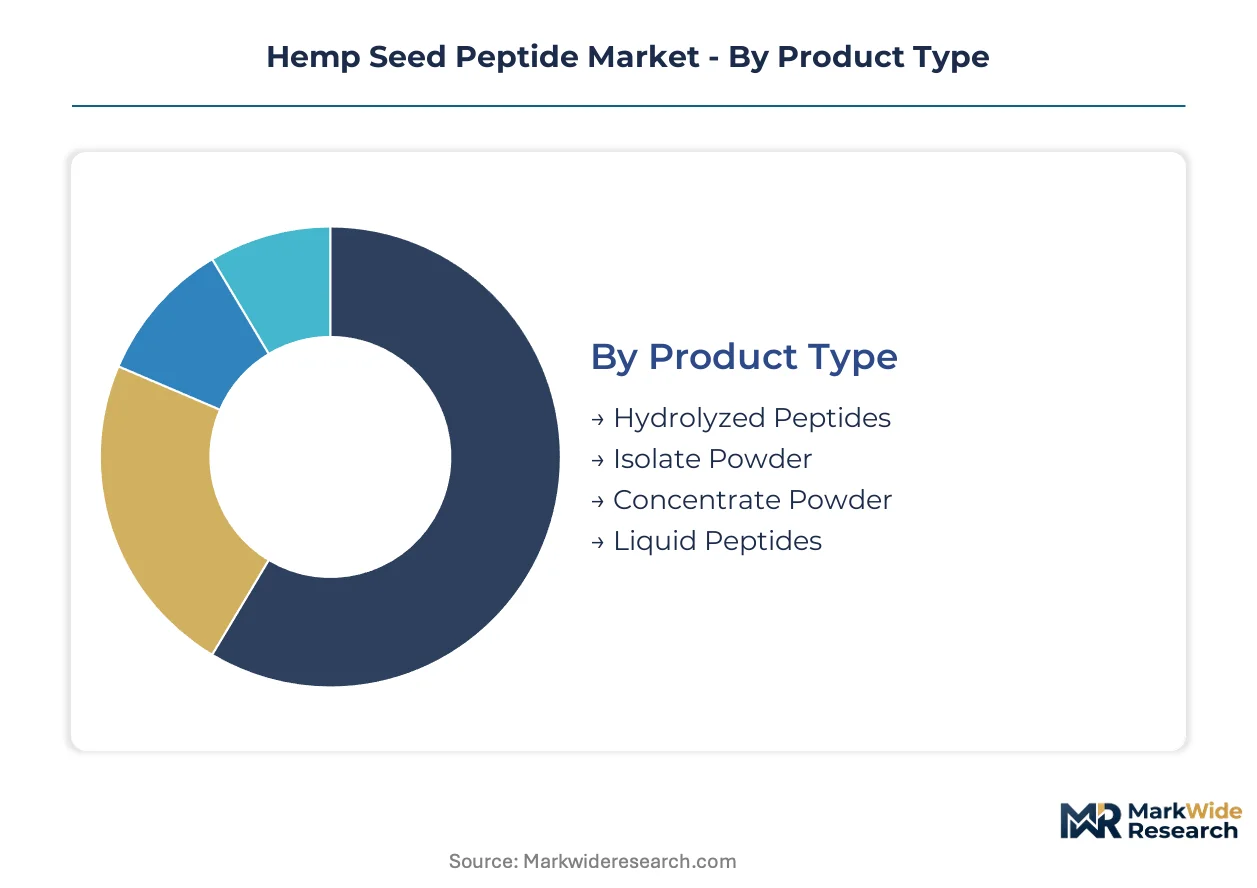
Hemp seed peptide suppliers configure product portfolios around enzymatic processing intensity and end-use bioactivity requirements. Segment boundaries reflect divergent margin pools across pharmaceutical-grade isolates and commodity fortification inputs.
Product Type:
Volume concentrates in standard-grade hydrolysates, while premium positioning attaches to isolate fractions with validated molecular weight specifications.
- Isolate Powder:Enzymatic hydrolysis yields fractions exceeding 90% protein content with sub-10 kDa molecular weight uniformity. Contract manufacturers in Kentucky and Manitoba specify these inputs for sports nutrition SKUs requiring rapid absorption claims.
- Hydrolyzed Peptides:Partial enzymatic processing retains broader molecular weight distribution, serving cost-sensitive functional food fortification. California CPG brands source these for clean-label protein bars where texture masking matters more than bioactivity precision.
- Concentrate Powder:Lower processing intensity yields 60-75% protein content suitable for bulk bakery and beverage applications.
- Liquid Peptides:Ready-to-dispense formats target beverage co-packing operations seeking minimal handling steps.
Mature deployment sits with Hydrolyzed Peptides. Newer deployment is concentrated in Isolate Powder.
Application:
Revenue allocation tracks regulatory claim permissiveness, with Japanese and North American channels enabling distinct positioning strategies.
- Sports Nutrition:Rapid absorption kinetics drive procurement by endurance athletes and boutique gym chains. FDA structure-function claim pathways permit recovery-focused labeling without clinical trial investment.
- Cosmeceuticals:Collagen-stimulating peptide validation through dermatological testing opens margin pools beyond traditional nutrition. South Korean and French cosmetic formulators lead peptide-specific efficacy substantiation.
- Nutritional Supplements:Capsule and tablet formats target aging demographics seeking plant-based protein alternatives.
- Functional Foods:Bakery, dairy alternative, and beverage fortification applications prioritize cost-efficient concentrate grades.
Contract manufacturing demand clusters around Sports Nutrition. Direct-to-consumer innovation is expanding fastest in Cosmeceuticals.
End User:
Procurement authority separates institutional buyers with formulation expertise from retail channels dependent on supplier technical support.
- Fitness Centers:Private-label recovery formulation programs concentrate volume with direct-supply peptide processors capable of flexible batch sizing. Colorado and California boutique chains drive sachet-to-pouch subscription bundling.
- Cosmetic Industry:Dermatological testing requirements and INCI nomenclature compliance filter supplier participation. South Korean beauty conglomerates specify peptide sequences with documented collagen synthesis activation.
- Sports Enthusiasts:Individual purchasing through e-commerce channels favors single-serve portability formats.
- Healthcare:Clinical nutrition protocols require batch documentation and bioactivity consistency that commodity suppliers struggle to provide.
Established relationships dominate Fitness Center procurement. Healthcare represents the steepest expansion trajectory pending clinical validation investment.
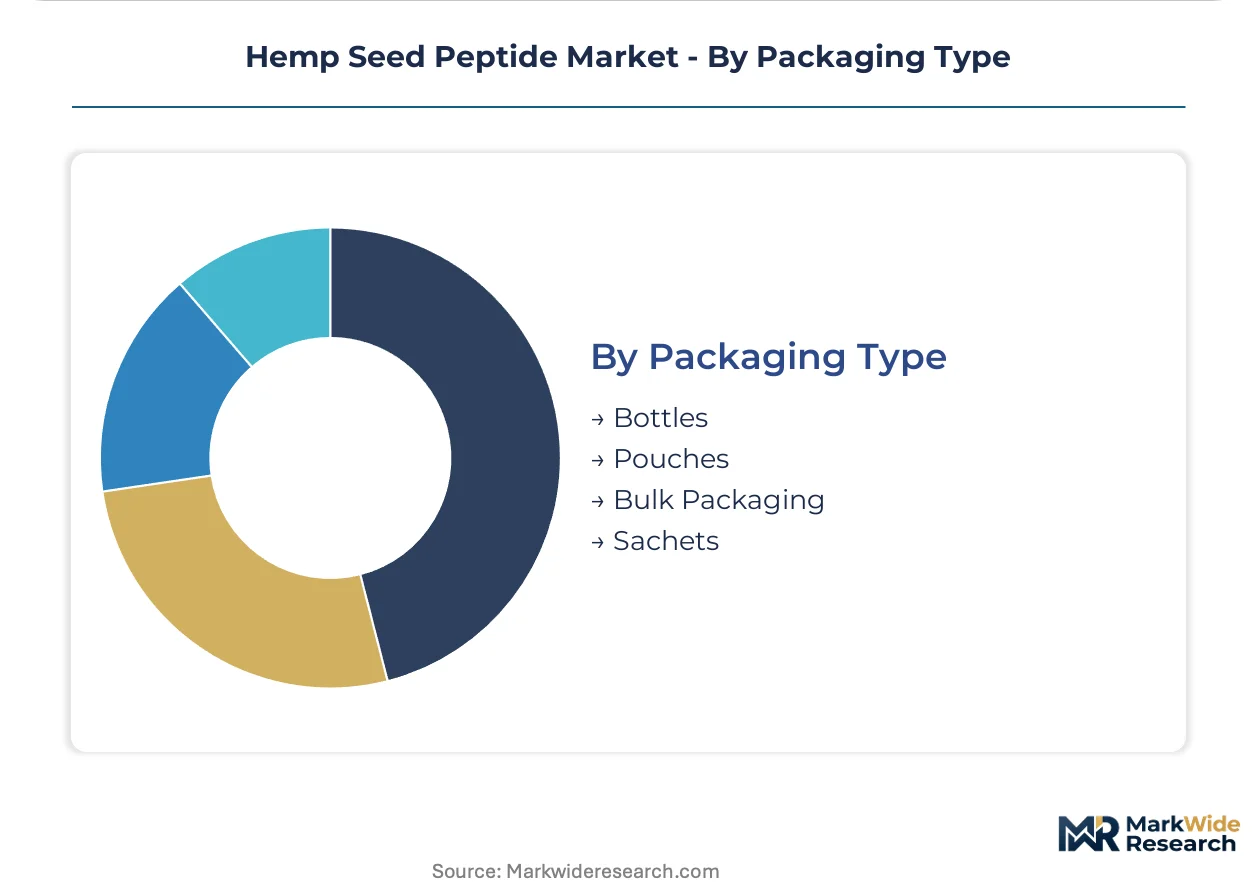
Packaging Type:
Format selection reflects distribution channel working capital constraints and consumption occasion fragmentation.
- Sachets:Single-serve precision dosing targets endurance sports events and travel occasions. Subscription bundling into multi-pouch configurations displaces bottle purchasing among fitness center operators.
- Pouches:Flexible format supports private-label recovery formulations with variable batch sizing. California co-packers favor stand-up pouch configurations for retail shelf differentiation.
- Bottles:Traditional format retains presence in mass retail supplement aisles where consumer familiarity reduces education burden.
- Bulk Packaging:25 kg drums and supersacks serve contract manufacturers with in-house blending and encapsulation capabilities.
Volume leadership remains with Bottles. Format innovation is concentrating in Sachets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processing capacity concentrates in North American heartland states while consumption pulls toward coastal fitness hubs and Asian functional food channels. Kentucky and Manitoba enzymatic hydrolysis facilities supply contract manufacturers serving clean-label CPG brands. Export demand fragments across regulatory jurisdictions with divergent novel food approval timelines.
United States
FDA structure-function claim pathways enable rapid sports nutrition SKU proliferation without clinical trial investment. The agency exercises jurisdiction over hemp seed peptide labeling under DSHEA while USDA oversees organic certification for cultivation inputs. Kentucky processing clusters anchor enzymatic hydrolysis capacity serving California boutique gym chains.
Canada
Health Canada's expanded novel food determination requirements mandate acute toxicity studies for peptide fractions above 5 kDa. The regulatory tightening forces exporters to maintain parallel dossier portfolios. Manitoba heartland facilities concentrate supply reliability for North American contract manufacturing hubs.
China
Xi'an-based ingredient processors compete on concentrated isolate output for B2B buyers. SAMR and NMPA frameworks govern novel food ingredient registration with dossier requirements that filter supplier participation. Shaanxi province enzymatic processing capacity serves domestic functional food fortification demand.
Japan
FOSHU and Foods with Function Claims frameworks permit peptide-specific hypertension reduction labeling unavailable under US restrictions. METI oversight coordinates functional food channel development. Tokyo-area sports nutrition distributors source North American isolate fractions for endurance athlete formulations.
Germany
EFSA novel food approval timelines of 18-24 months filter European peptide fraction entry. The REACH regulatory environment shapes ingredient compliance for cosmeceutical applications. Bavaria-based contract manufacturers specify standardized isolate specifications for clean-label bakery fortification.
Hemp Seed Peptide Market Competitive Landscape
The competitive structure tilts toward vertically integrated heartland processors with captive hemp cultivation supply. Tier differentiation separates premium isolate specialists from commodity hydrolysate suppliers. Three archetypes dominate: enzymatic processing technology licensors, organic-certified cultivation-to-peptide integrators, and B2B concentrate traders serving Asian ingredient markets. Capacity expansion and regulatory science capability acquisition represent the dominant competitive vectors as peptide suppliers reconfigure around modular manufacturing footprints.
Among North American heartland processors, Victory Hemp Foods and Manitoba Harvest Hemp Foods exemplify the cultivation-integrated archetype with supply reliability positioning. Nutraonly (Xi'an) Nutritions Inc occupies a position within the B2B concentrate tier competing on standardized isolate output. These three anchors illustrate how geographic processing concentration and regulatory jurisdiction mastery separate viable participants from commodity protein traders.
| Leading Market Players |
|---|
| North American Hemp & Grain Co. Ltd |
| Victory Hemp Foods |
| Manitoba Harvest Hemp Foods |
| Navitas Organics |
| ETChem |
| Nutraonly (Xi'an) Nutritions Inc |
| Blue Sky Hemp Ventures |
| Axiom Foods Inc. |
| Naturally Splendid Enterprises Ltd. |
| Others |
Value Network & Pricing Analysis
Contract manufacturer consolidation around 90% protein isolate specifications is forcing enzymatic hydrolysis facilities in Kentucky and Manitoba to synchronize analytical methods, compressing margin pools for suppliers lacking standardized certification. This procurement discipline is propagating cost-down pressure through upstream hemp cultivation contracts.
Pricing Analysis
Margin tightening in standard-grade hydrolysates reflects hemp protein concentrate substitution at 60-70% lower unit cost satisfying basic fortification needs. Three-tier pricing structure across pharmaceutical-grade isolates, certified-organic fractions, and commodity hydrolysates tracks enzymatic processing intensity and molecular weight uniformity. Cost compression accelerates in concentrate grades as California CPG brands prioritize texture masking over bioactivity precision. Boutique gym chains demonstrate lowest price sensitivity, while mass retail supplement buyers drive hardest bargain.
Supply Chain Analysis
Freight cost differentials between heartland processing clusters and coastal consumption hubs are widening procurement zone arbitrage for contract manufacturers. Enzymatic hydrolysis capacity concentrates in the United States, Canada, and China, with Shaanxi province serving domestic Asian demand. Raw material flows draw from certified organic hemp cultivation in Kentucky, Manitoba, and Shaanxi, resting on enzymatic substrate consistency and membrane filtration equipment availability. Single-source vulnerability concentrates in North American heartland hydrolysis facilities. Distribution runs through direct-supply relationships with contract manufacturers and B2B ingredient traders serving Asian cosmetic formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
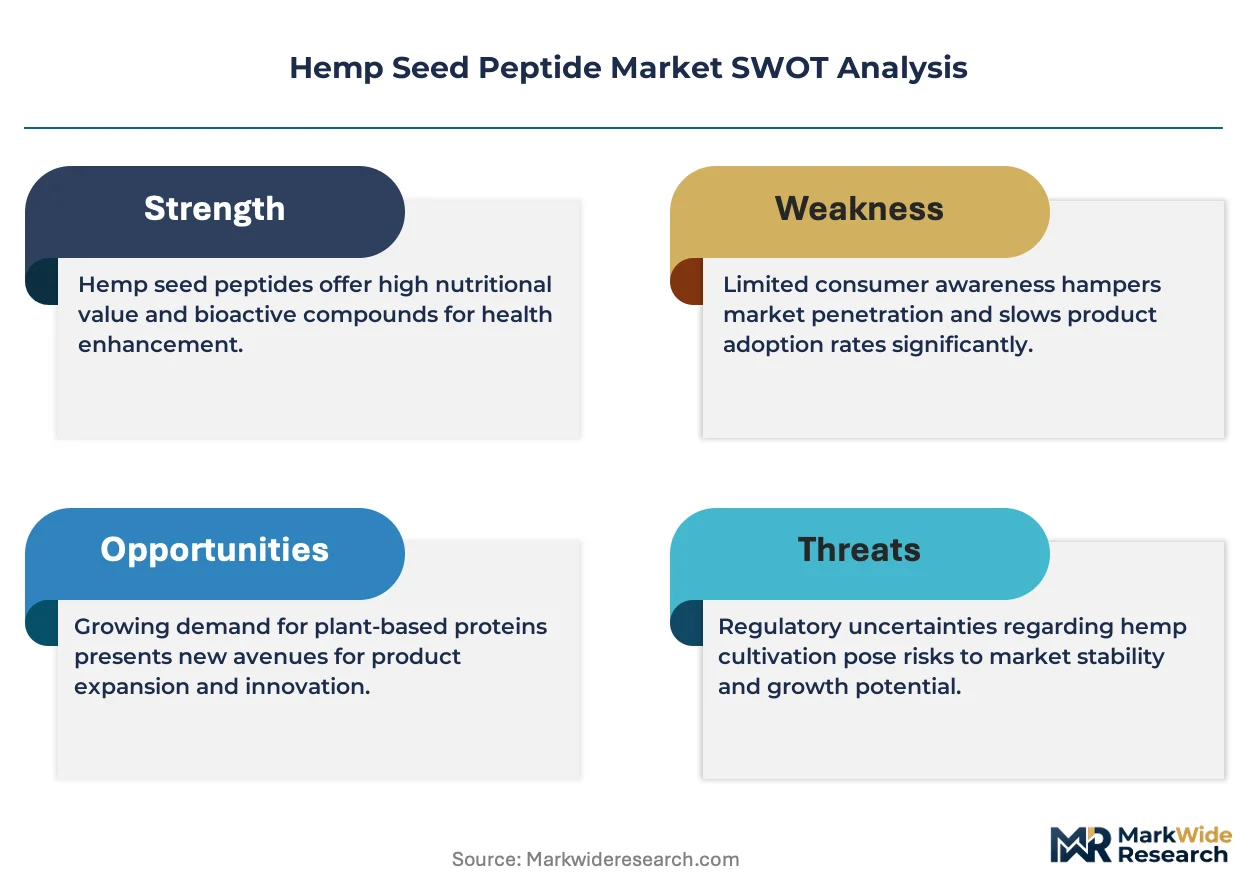
Heartland enzymatic hydrolysis capacity scarcity is propping isolate pricing premiums, creating asymmetric returns for processors with captive cultivation supply. Incumbents must anticipate competitive threats while new entrants exploit channel fragmentation.
For Market Incumbents: Anticipate precision fermentation platforms threatening to bypass agricultural hemp supply chains for high-value cosmetic actives. Defend position through backward integration into certified organic cultivation and membrane filtration technology licensing. Capacity addition in Manitoba and Kentucky anchors supply reliability commitments to North American contract manufacturers. For New Entrants and Emerging Players: Direct-to-practitioner distribution through sports dietitians and clinical nutritionists offers lowest competitive density. Target Japanese functional food channels where FOSHU frameworks permit hypertension reduction labeling unavailable under FDA structure-function restrictions. White-space exists in healthcare segment pending batch documentation and bioactivity consistency investment. For Investors and Strategic Acquirers: The window for entry favors enzymatic processing technology licensors with regulatory science capabilities spanning FDA, Health Canada, and EFSA dossier requirements. Long-term viability hinges on modular manufacturing footprints enabling flexible batch sizing for subscription bundling channels. Watch for precision fermentation cost parity as inflection signal threatening agricultural peptide economics.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Science Capability Acquisition | Parallel dossier portfolios for Health Canada and EFSA approval timelines reduce market access friction. |
| Membrane Filtration Technology Licensing | Sub-3 kDa antioxidant fraction modularization enables catalog purchasing replacing custom contract relationships. |
| Certified Organic Cultivation Integration | USDA organic certification commands premium positioning in North American contract manufacturing channels. |
| Direct-to-Practitioner Channel Development | Sports dietitian prescription protocols bypass retail markup structures and concentrate volume with processors. |
| Japanese FOSHU Registration Investment | Peptide-specific hypertension reduction labeling unlocks functional food positioning unavailable in US market. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with enzymatic processing plant managers, contract manufacturer procurement leads, sports nutrition brand formulators, and regulatory affairs directors at peptide suppliers were cross-validated against FDA DSHEA guidance documents, Health Canada novel food determinations, and EFSA safety dossier repositories. Bottom-up volume modeling triangulated with top-down market sizing from hemp cultivation throughput and enzymatic hydrolysis capacity estimates.
Reconciliation of production volume data, import-export flows, and channel shipment patterns informed analytical framework construction across the analysis window. Segmentation dimensions modeled include product type, application, end user, and packaging format, with regional regulatory cluster as additional industry-specific dimension. CAGRs derived from trend extrapolation of enzymatic processing cost compression curves and clean-label CPG procurement growth patterns, calibrated against peptide fraction bioactivity validation investment cycles.
Inputs from FDA, Health Canada, and EFSA regulatory databases were available through the study window; gaps in real-time contract manufacturer inventory positioning introduce uncertainty bands around short-term volume estimates. Forecasts reflect assumptions on enzymatic hydrolysis parameter standardization and precision fermentation platform development timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
South America Vegetable Oil Market
Ingredients
Sugared Egg Yolk Market
Ingredients
Prenatal Vitamin Ingredients Market
Ingredients
Wheat Protein Concentrates Market
Ingredients
North America Malt Ingredients Market
Ingredients
North America Bioactive Ingredients Market
Ingredients
Oat Grass Powder Market
Ingredients
Pulses Ingredients Market
Ingredients
Fermented Ingredients Market
Ingredients
Global Pulse Flours Market
Ingredients
China Gelatin Market
Ingredients
White Mulberry Leaves Extract Market
Ingredients
Cacao Extracts Market
Ingredients
Soy Protein Hydrolysate Market
Ingredients
Soluble Fibers Market
Ingredients
All Purpose Flour Market